
 High Temperature Alloys Market | 2026-2036
High Temperature Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Alloys Market Foresight
Modular component sourcing is decoupling traditional bundled supply contracts in the high temperature alloys sector, allowing aerospace and power generation buyers to procure wrought barstock, cast turbine blades, and additive-manufactured repair kits through separate vendor channels. Sandvik AB leverages its integrated powder metallurgy and wire production network to capture value across multiple product forms. Precision Castparts Corporation anchors the investment-casting tier for complex aerofoil geometries, while VDM Metals specializes in flat-rolled nickel alloy strip for industrial heat exchangers.
High temperature alloys are metallic systems—predominantly nickel, cobalt, and iron-nickel based—engineered to retain mechanical strength, creep resistance, and oxidation protection above 540°C, typically produced through vacuum induction melting followed by vacuum arc remelting or electroslag remelting to eliminate tramp elements and non-metallic inclusions. Nickel alloys dominate commercial volume due to their gamma-prime precipitation strengthening and established supply chains for turbine disk and combustor applications. Titanium alloys represent the fastest-growing product category as compressor section designers substitute lighter rotating components, while 3D printing technology concentrates margin pools in repair and legacy part obsolescence programs rather than original equipment supply.
FAA airworthiness directives and EPA New Source Performance Standards jointly constrain alloy chemistry tolerances and emissions profiles for domestic aerospace and stationary gas turbine operators. EASA certification requirements for engine critical parts extend these quality protocols across European manufacturing footprints. Stakeholders must monitor evolving MEE enforcement of dual carbon goals in China, where domestic superalloy producers face accelerating qualification timelines for indigenous aero-engine programs.
Market Dynamics
Modular sourcing is fragmenting traditional bundled supply contracts across aerospace and power generation, as buyers unbundle wrought barstock, cast turbine blades, and additive-manufactured repair kits into separate procurement channels. This structural shift concentrates margin pools in specialized tier suppliers while eroding full-line distributors.
Growth Catalysts
- EPA New Source Performance Standards:Tightening emissions thresholds for stationary gas turbines force upgrades to higher-grade nickel superalloys in combustor and transition section components.
- Additive manufacturing qualification:FAA airworthiness directives for powder-bed fusion repair kits accelerate adoption in legacy engine maintenance, bypassing traditional forging lead times.
- China's indigenous aero-engine programs:MEE enforcement of dual carbon goals compresses qualification timelines for domestic superalloy producers serving COMAC and military turbine platforms.
Market Restraints
- Cobalt supply concentration:Over 70% of mined cobalt originates from the Democratic Republic of Congo, exposing superalloy producers to geopolitical disruption and ethical sourcing audits.
- Triple-melt capacity scarcity:Vacuum induction melting plus vacuum arc remelting plus electroslag remelting infrastructure is concentrated among a handful of Western suppliers, constraining volume ramp.
- Titanium aluminide substitution:Gamma-TiAl intermetallics displace nickel alloys in low-pressure turbine blades above 650°C, threatening volume in the fastest-growing temperature segment.
Strategic Opportunities
- India defense modernization:The country's PLI scheme for aerospace and defense components creates first-mover advantage for superalloy producers qualifying under CDSCO and BIS standards.
- Hydrogen-fired turbine retrofits:EU F-Gas Regulation amendments incentivize hydrogen-adapted combustor alloys, opening replacement demand in existing gas turbine fleets.
- Digital twin integration:Convergence of physics-based alloy lifecycle models with IoT sensor feeds enables predictive maintenance contracts, shifting revenue from hardware to performance guarantees.
Industry Challenges
- Metallurgical talent scarcity:Vacuum melting operators and gamma-prime precipitation specialists command premium wages as experienced cohorts retire without sufficient pipeline replacement.
- Dual certification burden:Simultaneous FAA and EASA qualification for engine-critical parts extends timeline by 18-24 months, freezing working capital in pre-production inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Alloys Market |
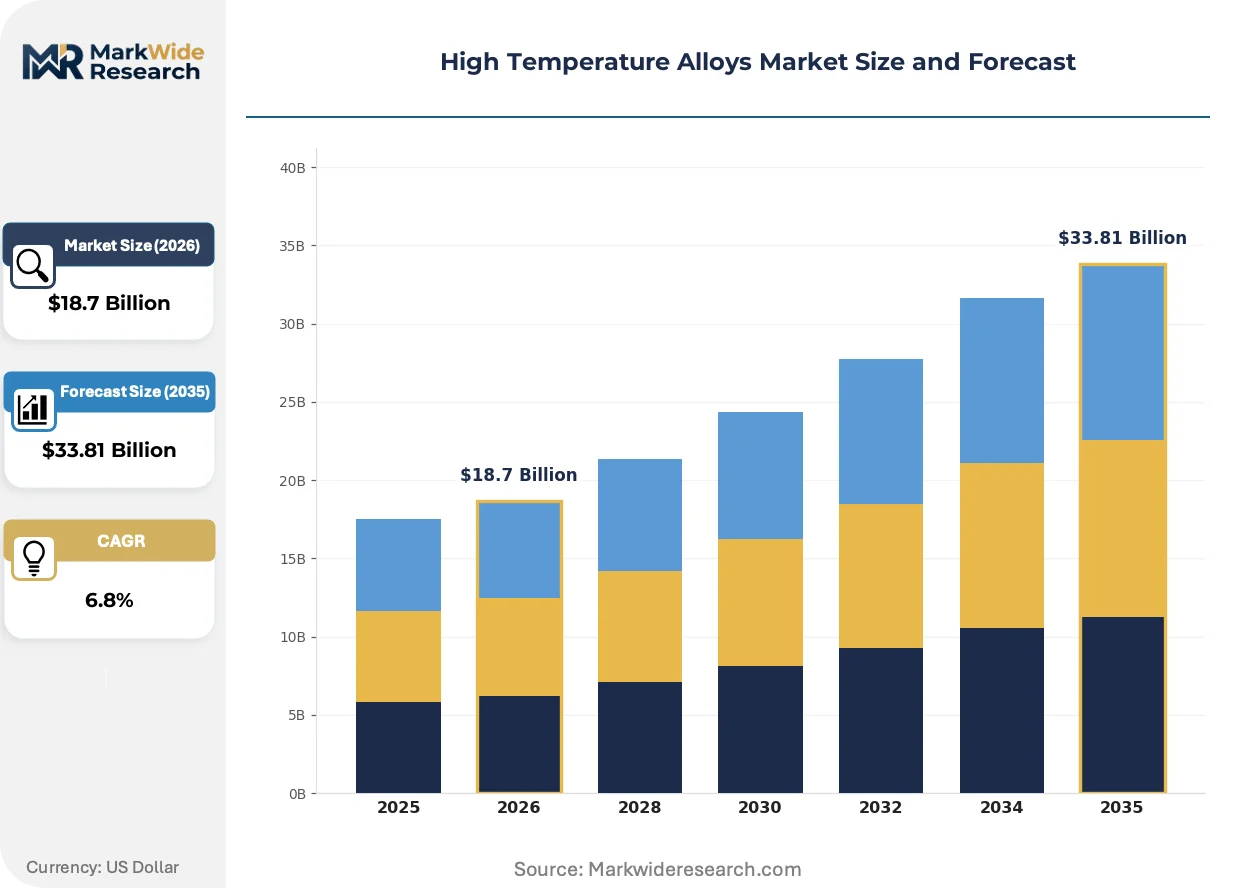
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel Alloys, Cobalt Alloys, Titanium Alloys, Stainless Steels Application: Aerospace, Energy Generation, Automotive, Chemical Processing End User: Aerospace Manufacturers, Power Plants, Automotive OEMs, Marine Industry Technology: Welding, Casting, 3D Printing, Machining |
| Companies Covered | Sandvik AB, Precision Castparts Corporation, Special Metals Corporation, VDM Metals, Aperam, Allegheny Technologies Incorporated, Haynes International, Hitachi Metals, Carpenter Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Alloys Market Shifts & Advancements
Process intensification and regulatory chemistry constraints are compressing traditional alloy development cycles while expanding the addressable market for non-traditional manufacturing routes. These shifts favor agile producers with captive powder metallurgy capabilities.
Directed energy deposition is converging with in-situ process monitoring to enable near-net-shape repair of single-crystal turbine blades. Maintenance, repair, and overhaul providers at Delta TechOps and Lufthansa Technik are qualifying these procedures under FAA delegated authority, compressing turnaround times from weeks to days while reducing material scrap rates.
The EU F-Gas Regulation is tightening allowable fluorinated greenhouse gas emissions from heat treatment and coating processes, forcing alloy producers to retrofit vacuum furnaces with closed-loop scrubbing systems. German and French superalloy foundries face the steepest compliance costs, accelerating migration of intermediate processing to Eastern European facilities with newer environmental infrastructure.
Long-term service agreements are displacing spot purchasing for aerospace turbine components, locking buyers into single-source relationships with certified suppliers. Rolls-Royce and GE Aviation are extending power-by-the-hour contracts to cover rotating hardware, concentrating procurement decisions at engine OEM headquarters rather than airline technical departments. This consolidation is most visible in the United States and United Kingdom, where fleet management outsourcing has reached mature penetration.
High Temperature Alloys Market Segmentation
High temperature alloys serve fundamentally different performance requirements across turbine stages, combustion environments, and thermal cycling regimes. Segmentation reveals where metallurgical complexity commands premium pricing versus where commoditized grades compete on scale.
Product Type:
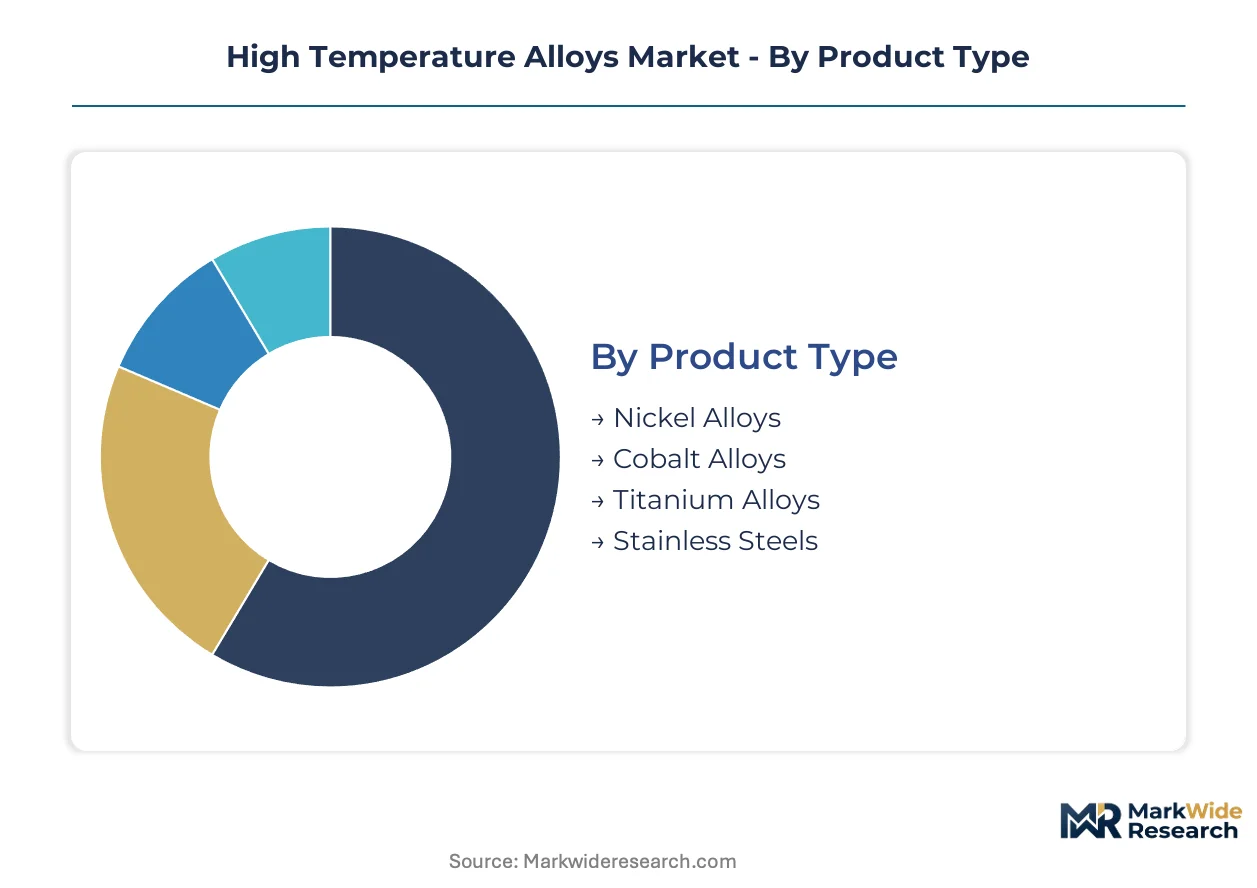
Nickel alloys dominate commercial volume through established gamma-prime strengthening mechanisms, while titanium alloys capture expanding share in weight-critical rotating components.
- Nickel Alloys:Gamma-prime precipitation-hardened systems retain creep resistance above 650°C through coherent Ni₃Al intermetallic phases. Demand concentrates in United States and Germany for turbine disks and combustor liners as FAA and EASA airworthiness directives tighten chemistry tolerances.
- Titanium Alloys:Alpha-beta and near-alpha compositions offer density advantages for compressor sections below 540°C. Aerospace manufacturers in China and Japan are substituting these for nickel alloys in low-pressure stages to reduce rotating mass.
- Cobalt Alloys:Solid-solution strengthened systems excel in sulfidation resistance for industrial gas turbines.
- Stainless Steels:Lower-cost austenitic and precipitation-hardened grades serve static hardware and heat exchanger applications.
Mature deployment sits with nickel alloys. Newer deployment is concentrated in titanium alloys.
Application:
Aerospace propulsion systems absorb the highest-value alloy tonnage, while energy generation provides volume scale through land-based turbine fleets.
- Aerospace:Turbine inlet temperatures exceeding 1100°C demand single-crystal nickel superalloys with platinum-modified aluminide coatings. OEMs in the United States and United Kingdom are extending power-by-the-hour contracts to cover rotating hardware, locking procurement at engine manufacturer headquarters.
- Energy Generation:Combined-cycle gas turbines require cobalt-modified nickel alloys for transition sections. EPA New Source Performance Standards and EU F-Gas Regulation are forcing upgrades to higher-grade materials in existing fleets.
- Automotive:Turbocharger turbines and exhaust valves utilize iron-nickel-based precipitation-hardened grades.
- Chemical Processing:Hydrogen reformer tubes and ethylene cracking furnaces consume wrought nickel alloy barstock.
Volume leadership belongs to energy generation. Margin concentration sits with aerospace.
End User:
Procurement authority is migrating from airline technical departments to engine OEM headquarters through long-term service agreements.
- Aerospace Manufacturers:Rolls-Royce and GE Aviation concentrate superalloy purchasing decisions through centralized supply chain functions. These entities qualify suppliers simultaneously under FAA and EASA protocols, extending qualification timelines.
- Power Plants:Utility operators in Germany and France face EU F-Gas Regulation compliance costs for heat treatment emissions, accelerating supplier migration to Eastern European processing facilities.
- Automotive OEMs:Turbocharger specialists source wrought barstock through modular channels separate from casting suppliers.
- Marine Industry:Naval propulsion programs in India and South Korea drive qualification of indigenous superalloy producers under defense procurement schemes.
Contract concentration is highest among aerospace manufacturers. Procurement fragmentation persists in power generation.
Technology:
Manufacturing route selection determines lead time, material utilization, and qualification burden for critical rotating hardware.
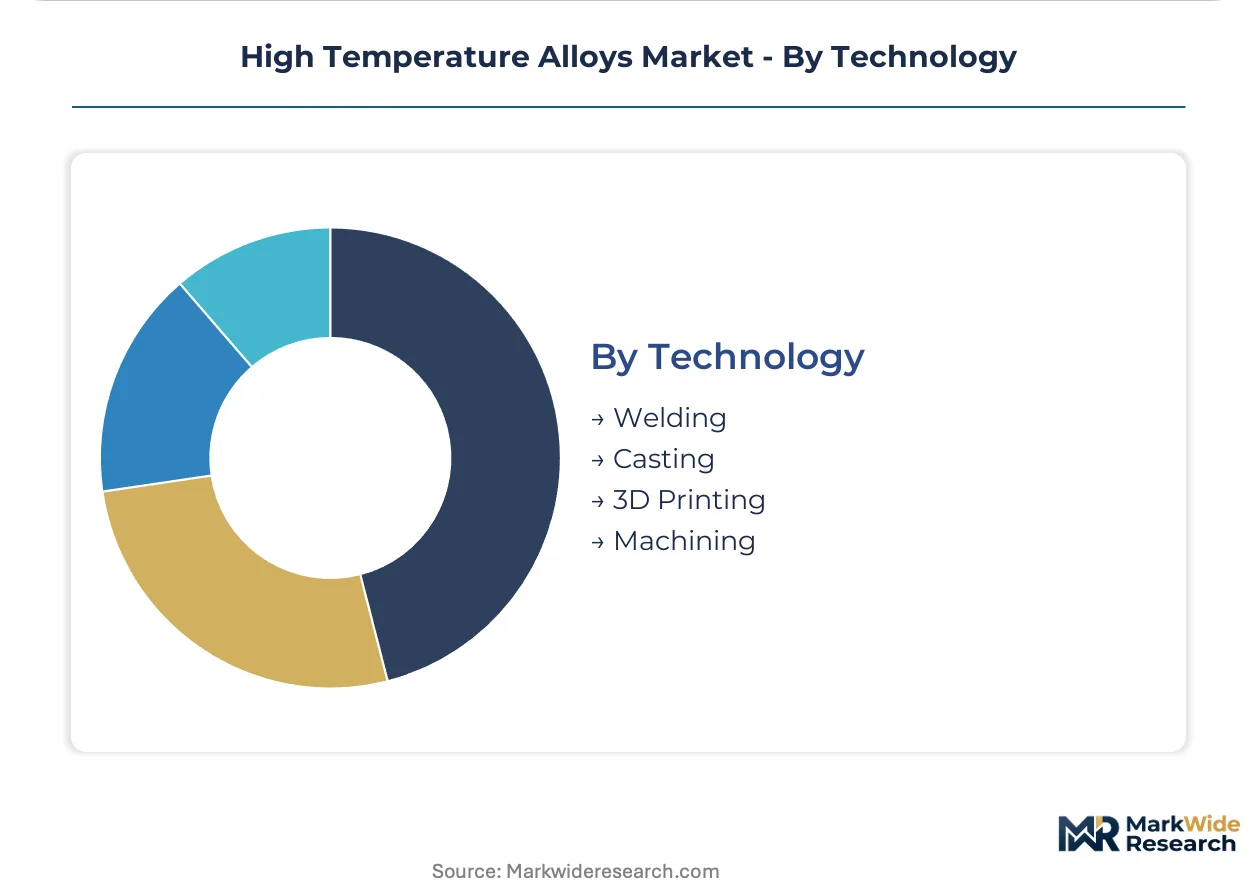
- Casting:Directional solidification and single-crystal processes produce complex aerofoil geometries for high-pressure turbine blades. Precision Castparts Corporation anchors this tier through vacuum induction melting plus vacuum arc remelting capacity.
- 3D Printing:Powder-bed fusion repair kits for legacy engine components are gaining FAA airworthiness directive approvals. Delta TechOps and Lufthansa Technik are qualifying directed energy deposition procedures under delegated authority.
- Welding:Automated gas tungsten arc and electron beam processes join wrought sections in combustor fabrications.
- Machining:Five-axis milling of nickel superalloys requires ceramic tooling and cryogenic cooling for single-crystal workpieces.
Established production sits with casting. Adoption velocity is steepest in 3D printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Western Europe and North America while consumption gravitates toward China's expanding aerospace and power generation sectors. Foundries in Germany and Sweden supply triple-melt barstock to turbine manufacturers worldwide. Assembly plants in the United States and China convert these inputs into finished rotating hardware.
United States
Defense procurement and commercial aerospace sustain demand for single-crystal nickel superalloys. FAA airworthiness directives govern powder-bed fusion repair kit qualifications across the domestic MRO network. GE Aviation and Pratt & Whitney concentrate turbine disk sourcing decisions in Cincinnati and Hartford engineering centers.
Germany
Land-based gas turbine retrofits and hydrogen adaptation programs drive alloy consumption in the Ruhr industrial corridor. EU F-Gas Regulation mandates closed-loop scrubbing systems for vacuum heat treatment furnaces. VDM Metals anchors flat-rolled nickel alloy production in Werdohl while foundries in Bavaria face steepest compliance migration costs.
China
COMAC indigenous aero-engine programs and military turbine platforms compress qualification timelines for domestic superalloy producers. MEE enforcement of dual carbon goals accelerates environmental audits at vacuum melting facilities. Shenyang and Xi'an host concentrated casting capacity serving AVIC and AECC supply chains.
India
Defense modernization under the PLI scheme creates first-mover openings for superalloy producers qualifying under CDSCO and BIS standards. Naval propulsion programs in Mumbai and Visakhapatnam drive indigenous producer qualification. Bengaluru aerospace clusters absorb imported barstock for gas turbine component machining.
Japan
Compressor section lightweighting programs substitute titanium alloys for nickel alloys in low-pressure turbine stages. METI industrial standards govern vacuum arc remelting quality protocols for aerospace suppliers. Nagoya and Tokyo metropolitan areas concentrate precision forging capacity serving IHI and Mitsubishi Heavy Industries turbine divisions.
High Temperature Alloys Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across melting, forming, and finishing tiers. The structure consolidates around triple-melt capacity holders while fragmenting in additive manufacturing repair services. Three archetypes dominate: integrated powder-to-part networks, investment casting specialists, and flat-rolled strip producers. Capacity expansion and qualification speed distinguish leaders from followers.
Among integrated metallurgy networks, Sandvik AB exemplifies diversification across powder, wire, and barstock forms. Precision Castparts Corporation anchors the investment-casting tier for complex aerofoil geometries. VDM Metals occupies a position within flat-rolled nickel alloy specialization for industrial heat exchanger applications.
| Leading Market Players |
|---|
| Sandvik AB |
| Precision Castparts Corporation |
| Special Metals Corporation |
| VDM Metals |
| Aperam |
| Allegheny Technologies Incorporated |
| Haynes International |
| Hitachi Metals |
| Carpenter Technology Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across Germany and Sweden anchor triple-melt capacity, translating concentrated ownership into disciplined contract pricing for aerospace turbine disk forgings while resisting spot-market volatility that erodes Western European foundry margins.
Pricing Analysis
Margin tightening in single-crystal blade supply traces to FAA and EASA dual-certification burdens that freeze working capital for eighteen to twenty-four months. Three-tier pricing structure across aerospace-certified, industrial-grade, and commodity nickel alloy levels separates qualification-intensive rotating hardware from heat-exchanger strip. Cost-down pressure on wrought barstock accelerates because power-generation buyers unbundle procurement from casting suppliers. Airline technical departments exhibit highest price sensitivity as procurement authority migrates to engine OEM headquarters under power-by-the-hour contracts.
Supply Chain Analysis
Dual-sourcing requirements mandated by Rolls-Royce and GE Aviation force qualified supplier rosters spanning Germany, Sweden, and the United States for vacuum arc remelted ingot. Raw material dependencies center on cobalt concentrates from the Democratic Republic of Congo, nickel cathode from Indonesia, and titanium sponge from Japan. Single-source vulnerability concentrates in electroslag remelting infrastructure held by a handful of Western suppliers. Distribution runs through long-term offtake agreements rather than spot channels, with foundries in Bavaria migrating intermediate processing to Eastern European facilities to evade EU F-Gas Regulation compliance costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powder-bed fusion repair kits are displacing traditional forging lead times in legacy engine maintenance, compressing the technology-transition window for incumbent metallurgy networks.
For Market Incumbents: Hedge gamma-TiAl substitution risk in low-pressure turbine stages by accelerating titanium aluminide qualification alongside nickel superalloy retention. Secure backward integration into captive powder metallurgy capacity before additive manufacturing margins pool with MRO providers. Defend triple-melt barstock pricing through exclusive long-term service agreements with AVIC and AECC supply chains in China. For New Entrants and Emerging Players: The premium-economy price-point gap in industrial heat-exchanger strip creates entry space below VDM Metals and Sandvik AB positioning. Target hydrogen-fired turbine retrofit demand in Germany's Ruhr corridor where EU F-Gas Regulation amendments force combustor alloy replacement. Qualify under India's PLI scheme for defense components before CDSCO and BIS standards harden for first-mover advantage. For Investors and Strategic Acquirers: Distressed-cycle entries favor additive manufacturing repair specialists with FAA delegated authority in the United States and Western Europe. Five-to-ten year viability hinges on powder-bed fusion qualification velocity outpacing traditional forging capacity expansion. Watch MEE enforcement timelines for dual carbon goals at Chinese vacuum melting facilities as inflection signal for domestic superalloy producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Melt Capacity Expansion | Alleviates electroslag remelting scarcity constraining single-crystal blade volume ramp. |
| Additive Manufacturing Qualification | FAA airworthiness directives for powder-bed fusion repair kits compress MRO turnaround times. |
| Hydrogen-Adapted Alloy Development | EU F-Gas Regulation amendments incentivize combustor material replacement in existing fleets. |
| India PLI Scheme Qualification | CDSCO and BIS certification creates first-mover defense procurement advantage. |
| Digital Twin Integration | Physics-based lifecycle models with IoT feeds enable predictive maintenance revenue shifts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of vacuum melting operators, gamma-prime precipitation specialists, turbine disk procurement leads at GE Aviation and Pratt & Whitney, and MRO technical directors at Delta TechOps and Lufthansa Technik. FAA airworthiness directive databases, EASA certification registries, EPA New Source Performance Standards filings, and EU F-Gas Regulation compliance disclosures supplied quantitative anchors. Bottom-up alloy consumption models triangulated against top-down turbine production forecasts.
Granularity-level modeling distinguished single-crystal versus equiaxed casting routes, gamma-prime versus solid-solution strengthening mechanisms, and aerospace versus power-generation end-use specifications across the projection horizon. CAGRs derived from segment-level volume build-ups incorporating indigenous aero-engine program timelines in China, hydrogen retrofit acceleration curves in Germany, and titanium aluminide substitution elasticities in low-pressure turbine stages. Cobalt supply concentration risk and triple-melt capacity constraints fed scenario-weighted outputs.
Underlying measurement precision varies by segment; aerospace-certified nickel superalloys carry tighter precision than commodity stainless grades given visible qualification pipelines. Forecasts assume continued MEE enforcement intensity in China and sustained EPA emissions threshold tightening in the United States. A model refresh is warranted upon material change in FAA additive manufacturing qualification velocity or DRC cobalt export policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Chromium Carbide Market