
 Multi-Metal Aluminum Sandwich Panels Market | 2026-2036
Multi-Metal Aluminum Sandwich Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Metal Aluminum Sandwich Panels Market Intelligence
Specialized distributor networks for architectural envelope systems is tilting toward direct manufacturer engagement on large commercial projects. Kingspan Group plc leverages its European fabrication footprint to sustain specification relationships with facade contractors across high-rise developments. ArcelorMittal S.A. anchors raw material supply through integrated flat-rolling capacity, while Metecno S.P.A. competes on project-specific thermal engineering and regional installation support.
Multi-metal aluminum sandwich panels consist of aluminum skins bonded to insulating cores such as polyurethane foam or mineral wool, typically achieving thermal transmittance values below 0.25 W/m²K for commercial building envelopes. Their primary purpose is to deliver structural rigidity, fire resistance, and thermal performance in a single lightweight module for exterior walls and roofing systems. Composite panels dominate volume in European facade retrofits where U-value compliance drives replacement cycles, while honeycomb configurations capture premium positioning in aerospace interior fit-outs where specific strength thresholds govern procurement. Steel-faced variants occupy cost-sensitive industrial roofing segments across emerging markets where coating durability rather than thermal performance determines selection criteria.
EMA's Construction Products Regulation and REACH chemical compliance frameworks govern core material formulations and surface coating chemistry across European supply chains, while BIS certification requirements and local fire-safety codes shape import eligibility for Indian infrastructure tenders. FAA airworthiness standards and ISO 9001 quality protocols further constrain aerospace-grade panel qualifications, effectively segmenting production lines by end-use certification tier. Stakeholders must track evolving carbon-emission disclosure obligations under CSRD and comparable frameworks, as embodied-carbon documentation becomes a gatekeeping criterion for public-sector construction procurement.
Market Dynamics
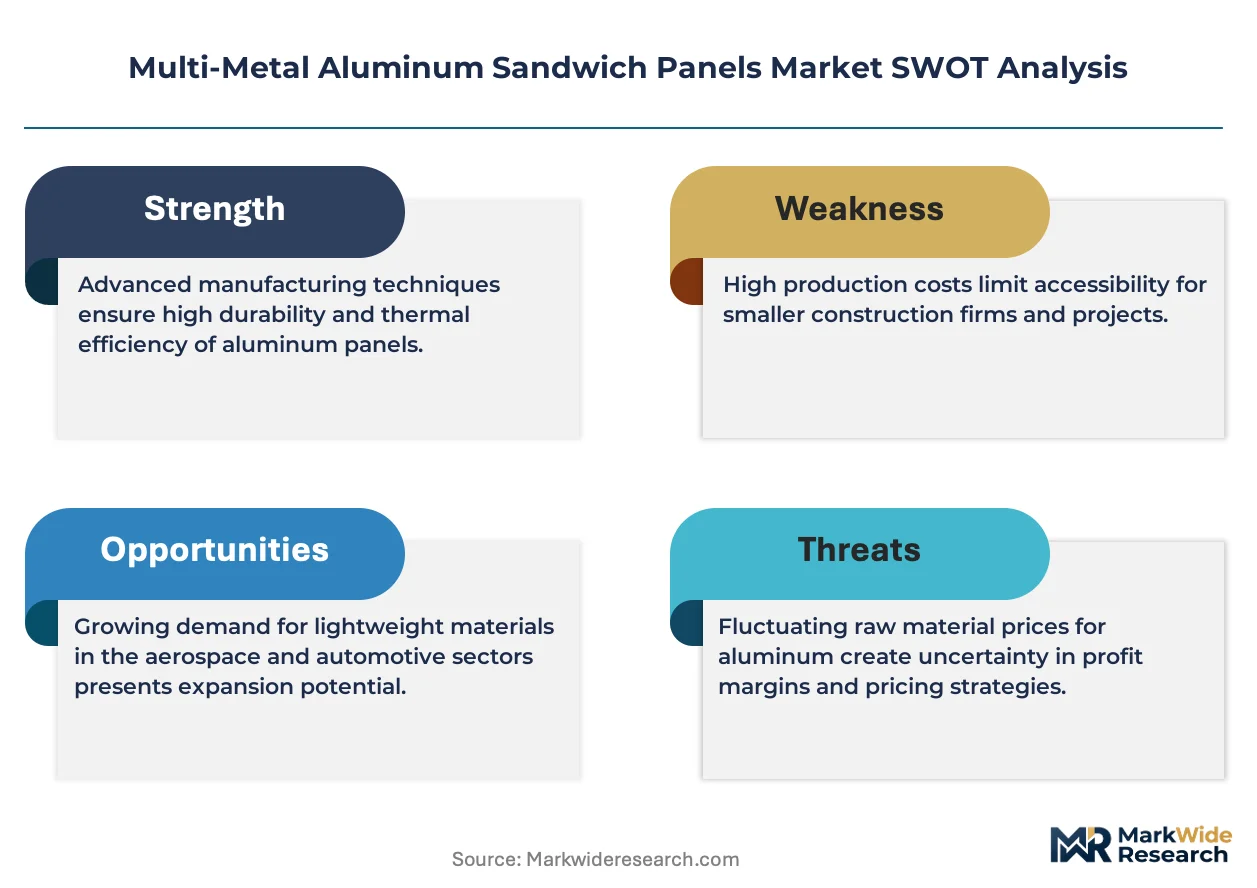
Fire-resistance certification tiers under the EU Construction Products Regulation are fragmenting procurement pools, as facade contractors now segregate project bids by EN 13501-1 reaction-to-fire class ratings rather than treating aluminum sandwich panels as a commodity category.
Growth Catalysts
- Green building mandates:Evolving energy codes in the United Arab Emirates and Saudi Arabia now require thermal transmittance below 0.20 W/m²K for commercial envelopes, accelerating specification of mineral wool-cored multi-metal assemblies over single-material alternatives.
- Logistics infrastructure buildout:Cold-chain warehouse construction across Germany and Japan is absorbing honeycomb-cored panels for temperature-stable roofing systems where structural dead-load limits constrain traditional steel decking.
- REACH compliance automation:Surface coating chemistry disclosure requirements are virtualizing supply chain documentation, enabling faster cross-border qualification of certified panel suppliers for Middle Eastern mega-projects.
Market Restraints
- Aluminum price volatility:LME aluminum futures swings above fifteen percent annually compress fabricator margins and destabilize fixed-price contracting models for tower developments with eighteen-month construction cycles.
- Core material supply concentration:Polyurethane foam precursor production clusters in Northeast China create geographic single-point vulnerability for European panel manufacturers reliant on just-in-time isocyanate delivery.
- Steel-faced substitution:Coated steel sandwich panels capture cost-sensitive industrial roofing in India and Southeast Asia where thermal performance ranks below capital expenditure minimization in buyer hierarchies.
Strategic Opportunities
- Retrofit acceleration zones:Germany's building stock renovation obligations under the EU Green Deal create concentrated demand for facade-overhaul panels that integrate with existing structural frames without demolition.
- Aerospace interior expansion:FAA airworthiness certification for thermoplastic-core honeycomb configurations opens cabin fit-out opportunities as aircraft OEMs seek weight reduction in premium seating modules.
- Carbon disclosure premiums:CSRD-mandated embodied-carbon reporting is virtualizing procurement scoring, positioning EPD-documented panel suppliers for preferred-vendor status in Dutch and French public infrastructure tenders.
Industry Challenges
- Fire-test certification bottlenecks:EN 13501-1 extended application assessments require twelve-to-eighteen-month validation cycles, delaying product launches and freezing specification relationships during competitive bidding windows.
- Installation labor scarcity:Specialized facade contractor capacity constraints in the Gulf Cooperation Council corridor limit project execution velocity despite available panel manufacturing throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Metal Aluminum Sandwich Panels Market |
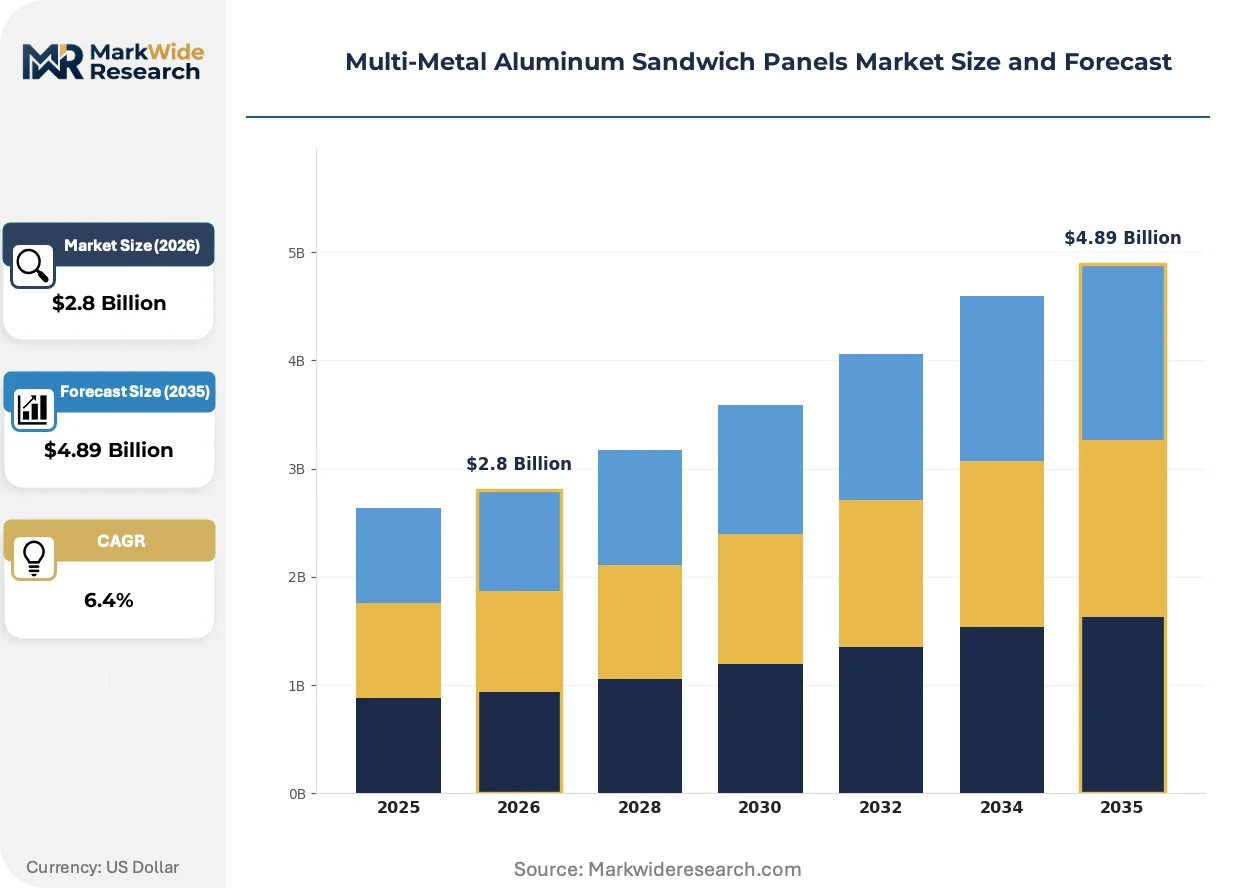
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honeycomb Panels, Composite Panels, Polyurethane Panels, Steel-Faced Panels End User: Construction, Transportation, Aerospace, Marine Application: Wall Cladding, Roofing, Interior Partitions, Facades Technology: Cold-Forming, CNC Machining, Thermal Insulation, Coating |
| Companies Covered | ArcelorMittal S.A., Isomec SRL, Kingspan Group plc, Jingxue Insulation Technology, Dana Group, Metecno S.P.A, Fischer Profil GmbH, Marcegaglia, Isopan Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Metal Aluminum Sandwich Panels Market Strategic Shifts & Innovations
Digital fabrication workflows and material traceability systems are compressing the gap between architectural specification and factory-floor production, enabling mass-customization of thermal-performance grades without sacrificing throughput economics.
Thermoplastic composite cores are virtualizing traditional honeycomb aluminum constructions in aerospace interior applications. Tier-one seating suppliers at Airbus and Boeing procurement programs now specify carbon-fiber-reinforced thermoplastic sandwiches for sidewall panels and overhead bins. This substitution is compressing part counts and assembly labor while maintaining specific strength thresholds mandated by FAA burn-through resistance protocols.
REACH chemical registration deadlines under ECHA's 2023-2027 substance evaluation roadmap are forcing reformulation of polyurethane foam blowing agents across European supply chains. Manufacturers face industrial consequence in core density consistency and lambda-value drift during the transition from HFC to hydro-olefin-based chemistries. German fabricators with captive foam-in-place operations are responding fastest, leveraging in-house R&D to stabilize thermal performance during the regulatory window.
Buyer concentration among European facade engineering consortiums is compressing distributor influence in commercial tower procurement. Direct manufacturer engagement now dominates projects above fifty thousand square meters of envelope area, displacing traditional merchant-distributor networks that previously handled specification support and logistics coordination. This channel consolidation is most visible in Frankfurt and Munich high-rise clusters, where D&B contractor panels now source through dedicated account engineering rather than regional stockists.
Multi-Metal Aluminum Sandwich Panels Market Segmentation
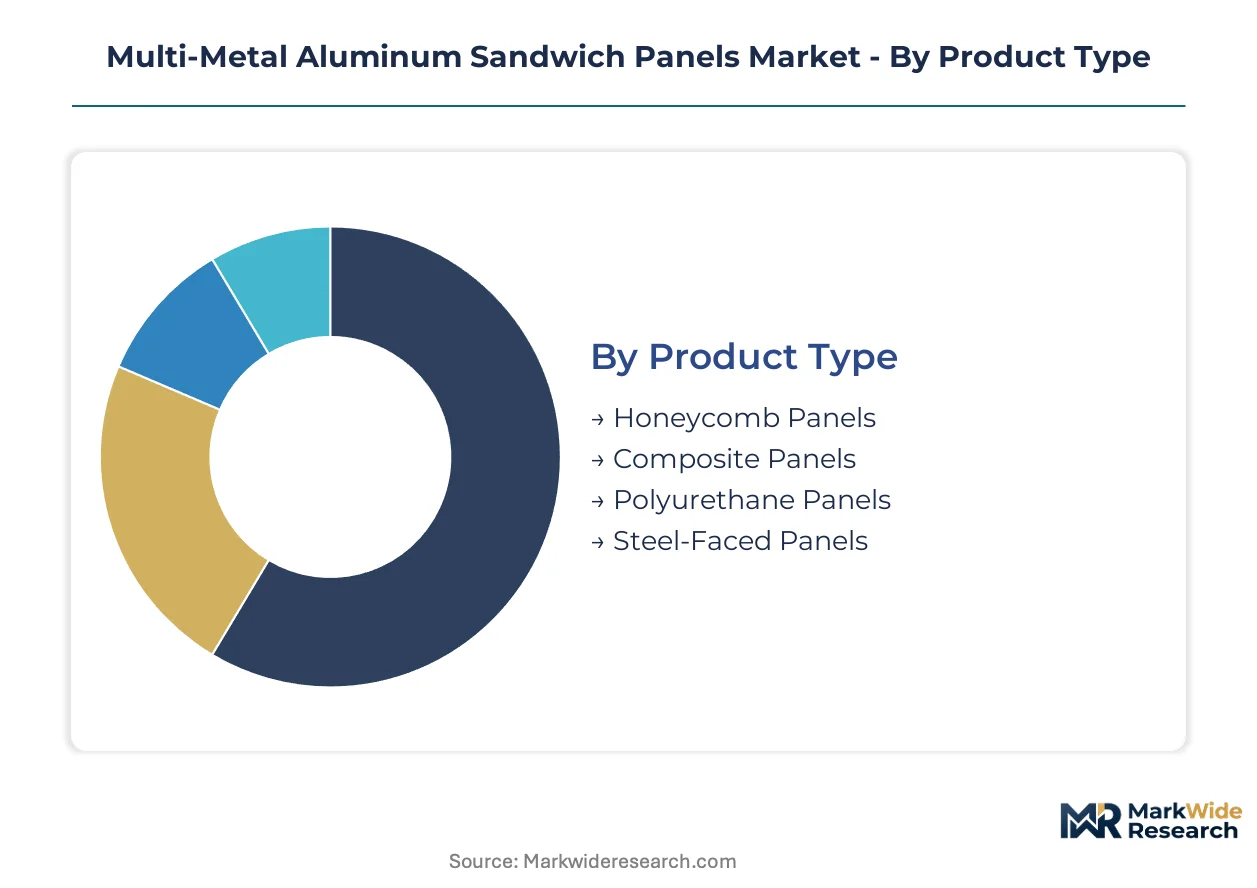
Specification engineers select multi-metal aluminum sandwich panels through four intersecting filters: structural performance grade, installation environment, thermal certification tier, and fabrication precision. Procurement decisions diverge sharply across these dimensions, with facade contractors prioritizing fire-class documentation while aerospace buyers weight specific strength thresholds above unit cost.
Product Type:
After-sales service intensity varies dramatically by panel architecture, with honeycomb configurations demanding specialized repair protocols and composite variants requiring thermal-performance recertification after field modifications.
- Composite Panels:Aluminum skins bonded to polyurethane or mineral wool cores achieve thermal transmittance below 0.25 W/m²K for commercial envelopes. Demand concentrates in German high-rise retrofits where EU Construction Products Regulation U-value compliance mandates replacement cycles.
- Honeycomb Panels:Hexagonal aluminum core structures deliver exceptional stiffness-to-weight ratios for aerospace interior fit-outs. Gulf Cooperation Council logistics infrastructure absorbs volume for temperature-stable roofing where structural dead-load limits constrain alternatives.
- Polyurethane Panels:Foam-in-place cores from captive German fabrication operations stabilize lambda values during REACH-mandated blowing-agent transitions.
- Steel-Faced Panels:Coated carbon steel skins compete on capital expenditure minimization for Indian industrial roofing where thermal performance ranks below durability.
By volume, composite panels lead. By growth pace, honeycomb configurations are ahead.
End User:
Cost tier stratification separates specification behavior, with aerospace procurement accepting 3-5x unit premiums for FAA airworthiness documentation against construction sector price-per-square-meter optimization.
- Construction:Facade contractors across Frankfurt and Munich high-rise clusters source through direct manufacturer account engineering for projects exceeding fifty thousand square meters of envelope area.
- Aerospace:Tier-one seating suppliers at Airbus and Boeing now specify carbon-fiber-reinforced thermoplastic sandwiches for sidewall panels, compressing part counts while maintaining FAA burn-through resistance thresholds.
- Transportation:Cold-chain warehouse builders in Japan deploy honeycomb-cored panels for roofing systems requiring temperature stability under structural load constraints.
- Marine:Salt-spray corrosion resistance drives coating chemistry selection for offshore platform accommodation modules.
Construction commands absolute volume. Aerospace delivers the steepest expansion trajectory.
Application:
Volume concentration tilts toward exterior envelope systems, yet interior fit-out applications command margin premiums through precision fabrication requirements and faster replacement cycles.
- Facades:Exterior wall systems integrate thermal insulation, fire resistance, and structural rigidity for commercial towers across the United Arab Emirates and Saudi Arabia.
- Roofing:Logistics infrastructure in Germany and Japan absorbs honeycomb-cored panels where dead-load limits constrain traditional steel decking alternatives.
- Wall Cladding:Retrofit acceleration zones under Germany's EU Green Deal obligations create concentrated demand for facade-overhaul panels integrating with existing structural frames.
- Interior Partitions:Aircraft cabin fit-outs specify thermoplastic-core honeycomb configurations as OEMs pursue weight reduction in premium seating modules.
Facade applications dominate current procurement. Interior partitions are climbing fastest.
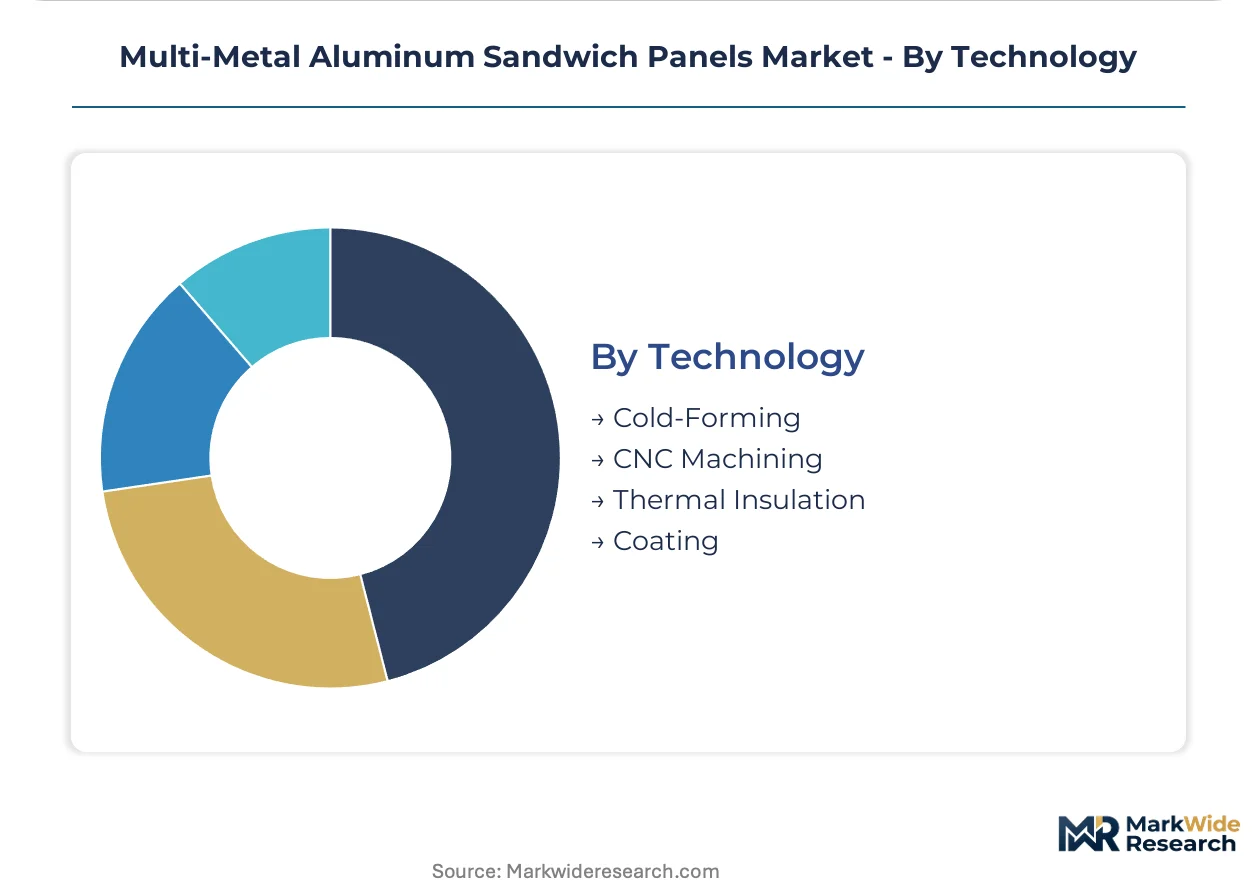
Technology:
Supply concentration in coating chemistry and thermal insulation creates procurement bottlenecks, while cold-forming and CNC machining capacity distributes more broadly across fabrication networks.
- Thermal Insulation:Core density consistency faces pressure during REACH-mandated transitions from HFC to hydro-olefin-based blowing agents, with German captive foam operations responding fastest.
- Coating:Surface chemistry disclosure requirements under ECHA's substance evaluation roadmap are virtualizing supply chain documentation for Middle Eastern mega-project qualification.
- Cold-Forming:Roll-forming lines produce standardized panel widths for cost-sensitive industrial roofing across emerging markets.
- CNC Machining:Digital fabrication workflows enable mass-customization of thermal-performance grades without sacrificing throughput economics for architectural envelope projects.
Thermal insulation technology anchors specification decisions. CNC machining is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German facade markets exceeds Gulf Cooperation Council corridors by 15-20 percent, reflecting tighter EU Green Deal compliance costs and premium thermal certification tiers. This asymmetry redirects capacity investments toward European captive fabrication while Middle Eastern mega-projects absorb volume through scale-driven procurement.
Germany
Frankfurt and Munich high-rise clusters drive facade retrofit demand under EU Green Deal building stock renovation obligations. The EU Construction Products Regulation mandates U-value compliance below 0.25 W/m²K, accelerating specification of mineral wool-cored assemblies. Bavarian fabricators with captive foam-in-place operations stabilize thermal performance during REACH-mandated blowing-agent transitions.
United Arab Emirates
Dubai and Abu Dhabi commercial towers absorb thermally efficient envelope solutions for mega-project pipelines exceeding fifty thousand square meters. MOHAP fire-safety codes and evolving green building codes redirect decisions toward certified multi-metal assemblies. Installation labor scarcity in the Gulf corridor constrains execution velocity despite manufacturing throughput availability.
Japan
Cold-chain warehouse construction across Kanto and Kansai regions deploys honeycomb-cored panels for temperature-stable roofing under structural dead-load limits. METI energy efficiency standards shape thermal transmittance requirements for logistics infrastructure. Osaka-based facade contractors source through direct manufacturer engagement on large commercial developments.
India
Industrial roofing procurement in Maharashtra and Gujarat favors steel-faced variants where capital expenditure minimization outweighs thermal performance. BIS certification requirements and local fire-safety codes shape import eligibility for infrastructure tenders. Cost-sensitive buyer hierarchies in emerging manufacturing clusters sustain coated steel substitution pressure.
Saudi Arabia
NEOM and Riyadh commercial developments require thermal transmittance below 0.20 W/m²K under evolving energy codes. SFDA and municipal building regulations accelerate specification of mineral wool-cored assemblies over single-material alternatives. Eastern Province logistics corridors absorb volume for temperature-stable envelope systems in warehouse buildouts.
Multi-Metal Aluminum Sandwich Panels Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in raw material and core formulation layers. The vendor base organizes around three archetypes: European fabrication networks with direct specification relationships, integrated steel-aluminum producers anchoring flat-rolled supply, and regional specialists competing on project-specific thermal engineering. Dominant competitive moves include backward integration into captive core production and channel consolidation toward direct manufacturer engagement on large commercial developments.
Among European-based fabricators, Kingspan Group plc and Metecno S.P.A. occupy positions within the platform integrator tier, exemplifying specification-driven business models. ArcelorMittal S.A. anchors the upstream material layer as an integrated steel-aluminum producer. These three entities represent the structural segmentation between system-level envelope providers and raw material supply concentration.
| Leading Market Players |
|---|
| ArcelorMittal S.A. |
| Isomec SRL |
| Kingspan Group plc |
| Jingxue Insulation Technology |
| Dana Group |
| Metecno S.P.A |
| Fischer Profil GmbH |
| Marcegaglia |
| Isopan Spa |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Jeddah container corridor transmits aluminum ingot cost volatility directly into German fabricator pricing, compressing margins on standard-grade panels while amplifying premiums for REACH-compliant configured-to-order assemblies.
Pricing Analysis
The customization-premium spread separates configured-to-order facade systems from standard-width roll-formed panels by certification tier and thermal performance grade. Project-based contracting dominates, with price differentiation anchored in EN 13501-1 fire-class documentation and volume scale. Pricing pressure stems from LME aluminum futures swings above fifteen percent annually, destabilizing fixed-price tower development contracts. Industrial roofing buyers in India exhibit highest price sensitivity, while aerospace procurement accepts substantial premiums for FAA airworthiness certification.
Supply Chain Analysis
Supplier-financing facilities from integrated flat-rollers extend payment terms to facade contractors, compressing distributor working capital positions. Supply concentrates in Germany, China, and the UAE for core fabrication, with polyurethane foam precursor production clustering in Northeast China. Raw material dependencies center on primary aluminum ingot, isocyanate chemicals, and mineral wool insulation. Single-source vulnerability in Chinese isocyanate supply creates geographic chokepoint risk. Distribution runs through direct manufacturer engagement on commercial developments exceeding fifty thousand square meters, displacing traditional stockist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized facade contractor capacity constraints in the Gulf Cooperation Council corridor outstrip available panel manufacturing throughput, creating a persistent execution bottleneck that rewards firms with captive installation partnerships or project-management capabilities.
For Market Incumbents: Harden specification relationships through backward integration into captive mineral wool core production, insulating margin positions from polyurethane precursor volatility. Secure EN 13501-1 extended application certifications ahead of competitive bidding windows to freeze distributor relationships. Prioritize direct account engineering investment in Frankfurt and Munich high-rise clusters where channel consolidation accelerates. For New Entrants and Emerging Players: Eastern Province logistics corridors in Saudi Arabia offer underpenetrated warehouse roofing demand where honeycomb-cored panel technical advantages outweigh established supplier relationships. Target cold-chain infrastructure builders seeking temperature-stable envelope systems under structural dead-load constraints. Lead with project-specific thermal engineering support rather than price competition. For Investors and Strategic Acquirers: Regional specialists with integrated fabrication and installation capabilities in the Gulf Cooperation Council corridor represent the most defensible acquisition profile. Long-term viability hinges on carbon disclosure infrastructure positioning ahead of CSRD-mandated embodied-carbon procurement scoring. Monitor ECHA substance evaluation roadmap deadlines for reformulation cost inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Production | Captive mineral wool operations stabilize lambda values during REACH-mandated blowing-agent transitions. |
| Fire-Test Certification Investment | EN 13501-1 extended application assessments freeze specification relationships during competitive bidding. |
| Direct Manufacturer Channel Expansion | Account engineering displaces distributor networks on Frankfurt and Munich high-rise developments. |
| Carbon Disclosure Infrastructure Buildout | EPD documentation positions suppliers for preferred-vendor status in Dutch and French public tenders. |
| Regional Installation Partnership Formation | Gulf Cooperation Council labor scarcity constrains execution velocity despite manufacturing availability. |
Research Approach
Cross-validation between facade contractor procurement data and ECHA regulatory filings anchors the qualitative findings. Primary interviews with envelope specification engineers, facade contractor project managers, aluminum flat-rolling procurement leads, and cold-chain warehouse developers combined with secondary validation from EU Construction Products Regulation documentation, REACH substance registration databases, customs trade records, and SEC filings from publicly traded fabricators. Bottom-up project pipeline tracking and top-down regional construction spend estimates provided triangulation.
Calibration against historical replacement cycles and thermal code adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include panel architecture, core material chemistry, fire-certification tier, end-use application, and regional regulatory cluster. CAGRs derived from installed base turnover rates and green building mandate phase-in schedules. Forecast inputs incorporated aluminum price elasticity coefficients and REACH compliance cost pass-through assumptions.
Practitioners should monitor ECHA substance evaluation roadmap deadlines and Gulf Cooperation Council labor mobility policies for early signals. Forecasts reflect assumptions on regulatory enforcement intensity and core material supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Tungsten Titanium Carbide Market