
 India Shape Memory Alloy Market | 2026-2036
India Shape Memory Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
India Shape Memory Alloy Market Foresight
Indian specialty alloy producers is broadening wire-drawing and vacuum-melting capacity to serve domestic medical device and aerospace programs. Mishra Dhatu Nigam Ltd (MIDHANI) anchors defense and space-grade superalloy supply with captive vacuum arc remelting infrastructure. SMA Wires India specializes in fine-gauge nitinol wire for catheter and stent OEMs. Johnson Matthey competes through precious metal coating competencies layered onto shape memory substrates for corrosion-critical applications.
Shape memory alloys are metallic materials—predominantly nickel-titanium intermetallics with near-equiatomic composition—that undergo thermoelastic martensitic transformation, enabling them to recover predetermined shapes upon heating above their austenite finish temperature; they are engineered for precise force delivery, superelastic strain recovery, and biocompatibility in constrained mechanical environments. Nitinol dominates product type revenue owing to its fatigue resistance and established vascular device approval pathways, while copper-based alloys occupy cost-sensitive actuator segments where thermal cycling bandwidth exceeds biocompatibility requirements. Aerospace end users drive specification intensity for sheet and tube forms, whereas medical device demand concentrates in wire and tube geometries for stent and guidewire platforms.
BIS material standards and CDSCO medical device rules govern alloy composition tolerances, surface finish thresholds, and implantable-grade traceability. The PLI scheme for specialty steel and advanced materials reduces capital cost burdens for domestic vacuum melting investments. Stakeholders must monitor CDSCO's evolving risk-based classification for nitinol implants and BIS harmonization with ISO 5832-11 surgical alloy norms to secure uninterrupted market access.
Market Dynamics
CDSCO's risk-based reclassification of nitinol implants is compressing certification timelines and forcing domestic manufacturers to accelerate vacuum-melting investments ahead of BIS harmonization with ISO 5832-11 surgical alloy norms.
Growth Catalysts
- PLI scheme for specialty steel:Capital cost subsidies for vacuum arc remelting furnaces are lowering entry barriers for domestic producers targeting aerospace and medical-grade nitinol.
- Maharashtra-Gujarat precision clusters:Concentrated metalworking infrastructure around Mumbai, Pune, and Ahmedabad reduces logistics costs for catheter and stent OEMs sourcing fine-gauge wire.
- Defense aerospace programs:Indigenous fighter jet and satellite initiatives are specifying nickel-titanium superelastic tubing for actuation and deployment mechanisms.
Market Restraints
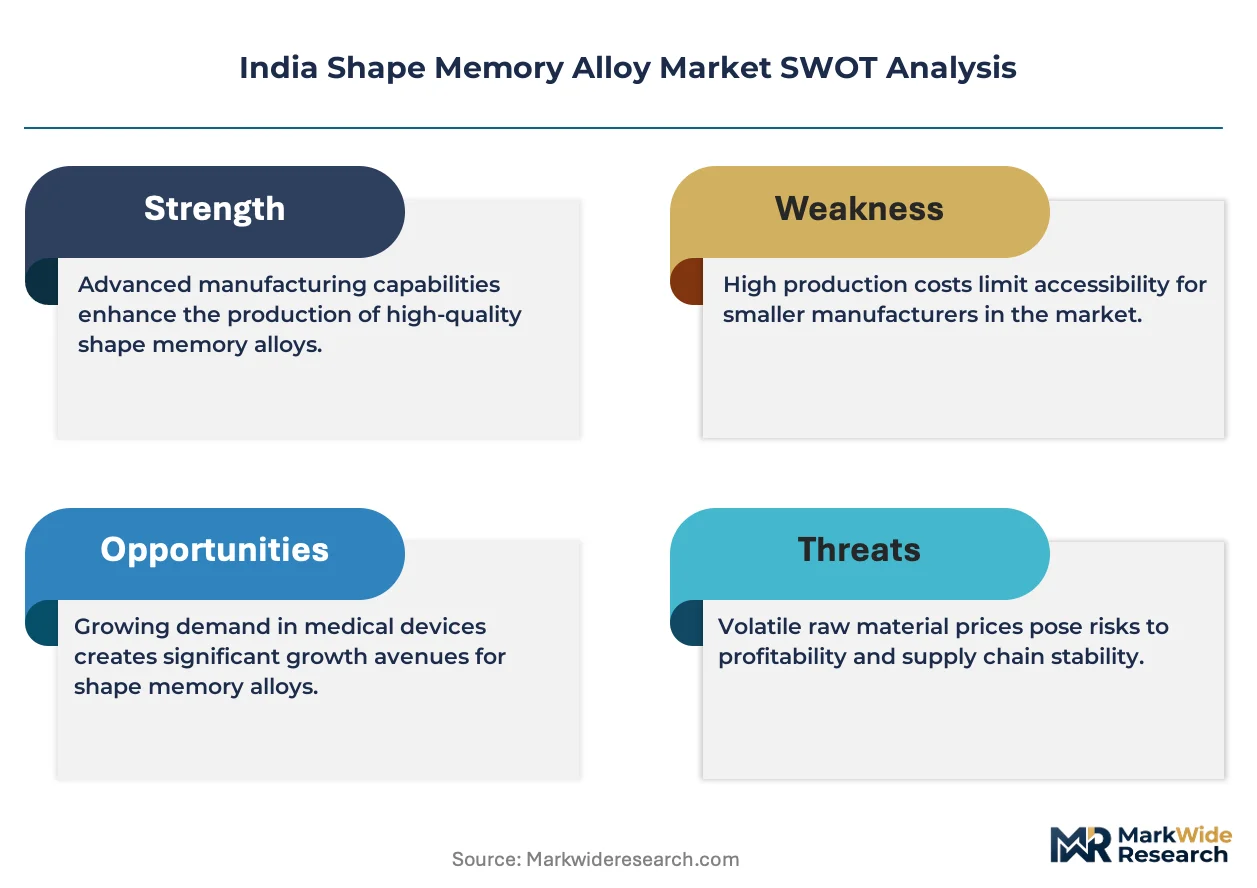
- Input nickel volatility:Nickel-titanium alloy pricing tracks London Metal Exchange nickel contracts, exposing domestic wire-drawers to margin compression during commodity spikes.
- Single-source vacuum melting:MIDHANI's captive VAR capacity dominates defense-grade supply, creating concentration risk for non-defense programs requiring equivalent traceability.
- Copper-aluminum substitution:Cost-sensitive thermal actuator applications in consumer electronics are migrating to copper-based SMA alternatives with lower transformation temperatures.
Strategic Opportunities
- Telangana-Karnataka expansion:Hyderabad and Bengaluru medical device parks offer untapped land and power subsidies for nitinol processors seeking alternatives to saturated western corridors.
- Robotic surgery instrumentation:Articulating graspers and needle drivers requiring superelastic force delivery are opening new wire-form specifications beyond traditional vascular platforms.
- CDSCO fast-track pathways:Priority review designations for domestically manufactured Class C and D implants are accelerating time-to-revenue for certified local producers.
Industry Challenges
- Vacuum metallurgy skill scarcity:Experienced VAR operators and melt chemists command premium wages, constraining capacity expansion timelines for new entrants.
- Dual certification burden:Simultaneous BIS alloy grade approval and CDSCO device licensing creates parallel documentation requirements that extend product launch cycles.
- Surface oxide control:Maintaining ASTM F2063-compliant passivation layers during fine-wire drawing requires capital-intensive in-line monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Shape Memory Alloy Market |
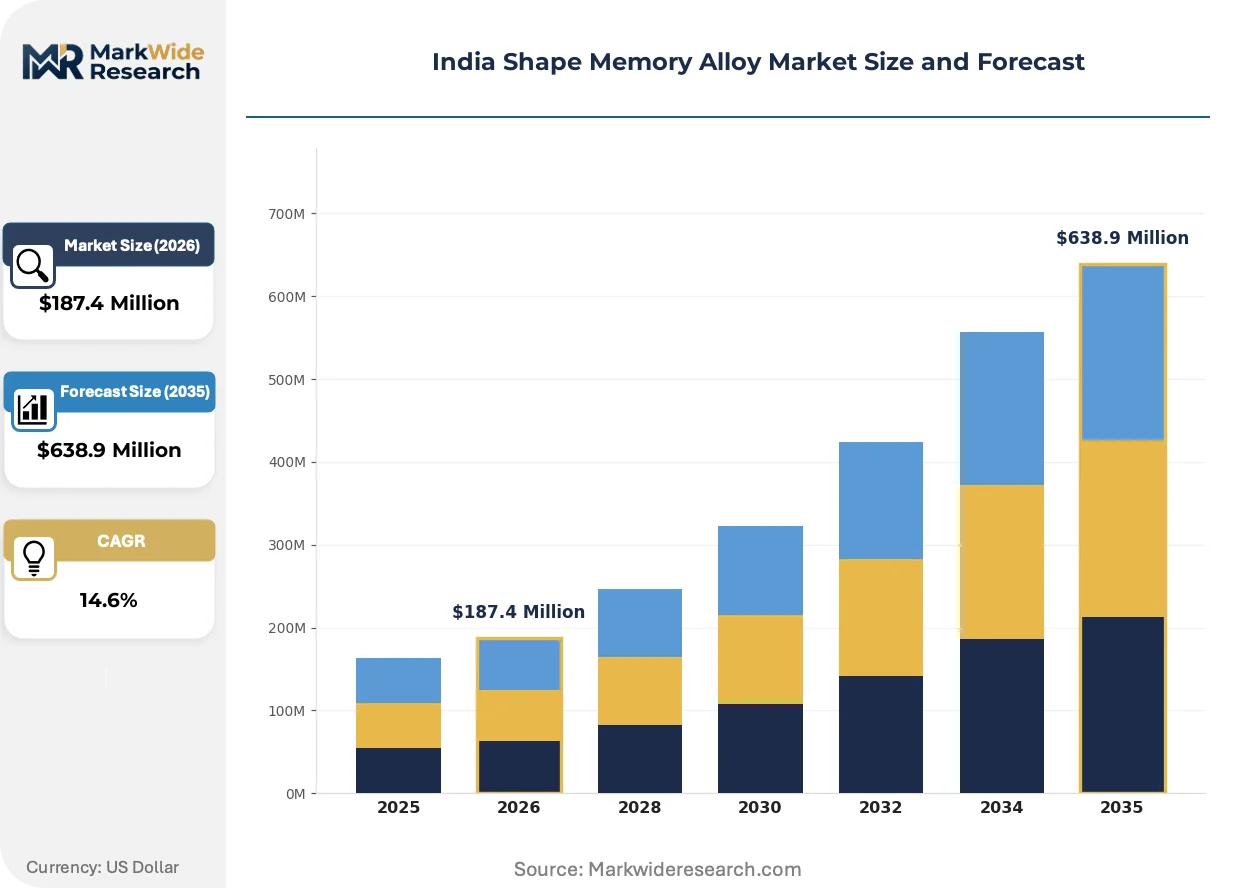
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitinol, Copper-based Alloys, Ceramic-based Alloys, Others End User: Aerospace, Medical Devices, Automotive, Robotics Application: Actuators, Stents, Fasteners, Sensors Form: Wires, Sheets, Tubes, Miscellaneous Shapes |
| Companies Covered | Mishra Dhatu Nigam Ltd (MIDHANI), SMA Wires India, Thermo Fisher Scientific India Private Limited, ATI Specialty Alloy & Components, SAES Getters, Furukawa Electric Co., Ltd., Nippon Steel & Sumitomo Metal, Johnson Matthey, Daido Steel Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Shape Memory Alloy Market Shifts & Advancements
Nitinol processing technology is fragmenting into specialized sub-systems as domestic producers seek alternatives to integrated foreign supply chains. Three developments are compressing competitive timelines.
Plasma-arc cold hearth melting is modularizing nitinol ingot production by separating titanium sponge refinement from nickel-alloying steps. Domestic aerospace contractors are piloting this approach to bypass traditional VAR bottlenecks. The technology is modularizing what was previously consolidated under single-furnace operations, enabling smaller batch sizes for prototype stent geometries.
BIS is accelerating adoption of ISO 5832-11 chemical composition tolerances for implantable nickel-titanium alloys, narrowing the gap between domestic and export-grade certification. Medical device manufacturers must now maintain dual-standard documentation during the transition period. Wire processors in Gujarat are responding by installing in-house spectrometry to verify carbon and oxygen thresholds in real time.
Catheter OEMs are consolidating supplier bases around vertically integrated nitinol processors capable of delivering finished guidewire geometries rather than raw wire. This specification compression favors domestic players with captive drawing and shape-setting operations. The shift is most visible in Maharashtra, where three stent manufacturers have shifted annual contracts from trading houses to integrated wire-to-device suppliers.
India Shape Memory Alloy Market Segmentation
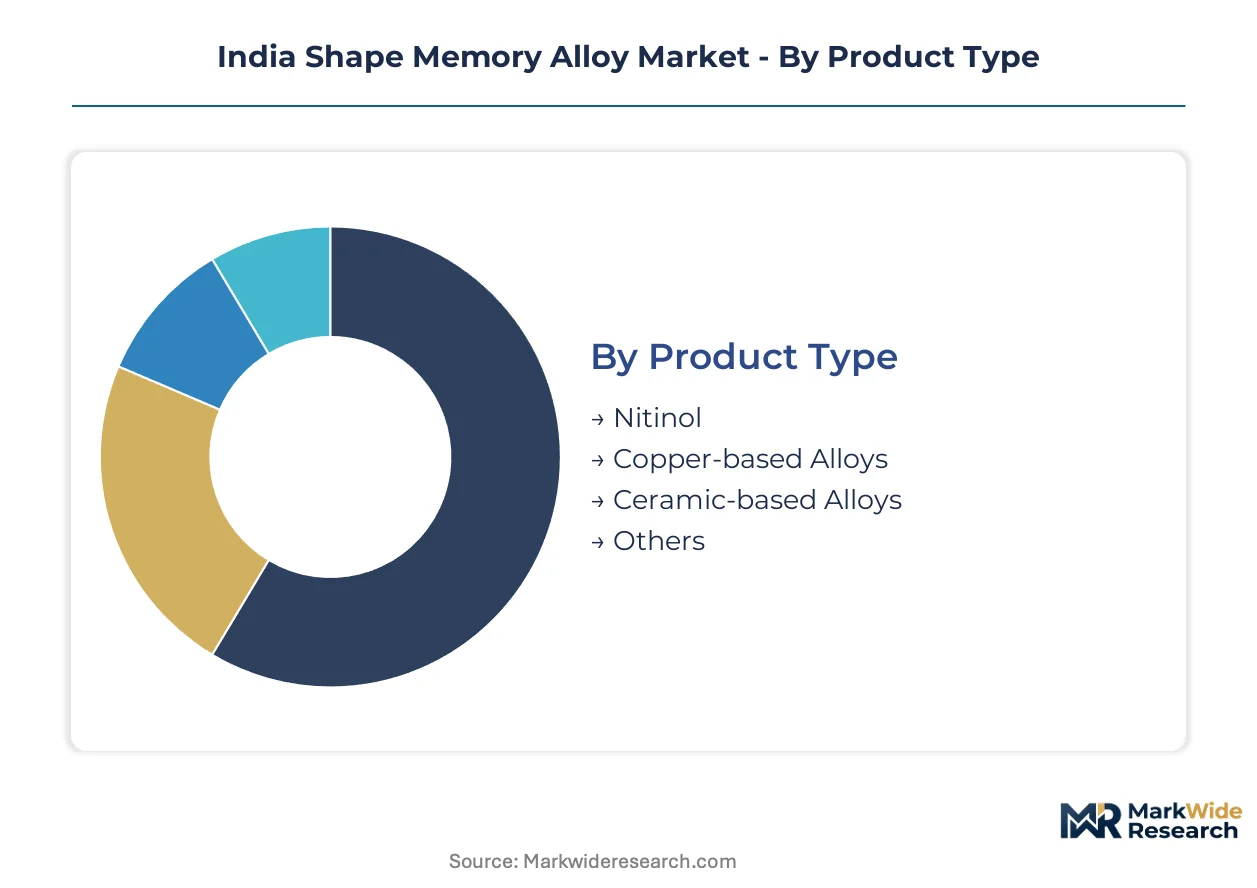
India's shape memory alloy market fragments along metallurgical composition, end-use criticality, and geometric form. Each dimension carries distinct certification burdens and margin profiles that determine supplier positioning.
Product Type:
Standalone nitinol commands premium pricing in implantable applications, while copper-based alternatives embed into cost-sensitive thermal actuators.
- Nitinol:Near-equiatomic nickel-titanium intermetallic delivering superelastic strain recovery and fatigue resistance above 8% strain. Maharashtra stent manufacturers and Gujarat guidewire processors specify this grade for CDSCO Class C and D implant pathways, with BIS harmonization to ISO 5832-11 tightening composition tolerances.
- Copper-based Alloys:Copper-aluminum-nickel and copper-zinc-aluminum formulations offering transformation temperatures below 100°C at substantially lower raw material cost. Automotive thermal management and consumer electronics actuator OEMs in Tamil Nadu favor this grade where biocompatibility is not required.
- Ceramic-based Alloys:Zirconia-toughened formulations for extreme temperature actuator environments.
- Others:Iron-manganese-silicon variants for experimental aerospace deployment mechanisms.
Nitinol leads volumes today; copper-based alloys are gaining share fastest in non-medical thermal actuator segments.
End User:
Medical device procurement concentrates in western India precision clusters, while aerospace demand distributes across defense contractor networks.
- Aerospace:Indigenous fighter jet and satellite programs specify nickel-titanium superelastic tubing for deployment mechanisms and morphing structures. MIDHANI's captive VAR capacity anchors defense-grade supply, with ISRO and DRDO laboratories driving specification intensity for vacuum-melted traceability.
- Medical Devices:Catheter OEMs, stent manufacturers, and guidewire processors in Mumbai, Pune, and Ahmedabad drive fine-gauge wire demand. CDSCO's risk-based reclassification of nitinol implants is compressing certification timelines and forcing vacuum-melting investments ahead of BIS harmonization.
- Automotive:Thermal valve actuators and adaptive intake systems in Chennai and Gurugram assembly plants.
- Robotics:Articulating surgical instruments and compliant mechanism research in Bengaluru and Hyderabad automation clusters.
Medical devices dominate revenue contribution; aerospace exhibits the steepest expansion trajectory as indigenous platform production scales.
Application:
Force-delivery applications command metallurgical precision, while sensing applications tolerate broader transformation temperature bands.
- Actuators:Thermal and electrical activation mechanisms converting heat or current into mechanical displacement. Aerospace deployment systems and automotive thermal valves specify this application, with copper-based alloys penetrating cost-sensitive consumer electronics in Noida and Bengaluru.
- Stents:Self-expanding vascular scaffolds requiring precise austenite finish temperature matching body temperature. Maharashtra and Gujarat catheter OEMs consolidate supplier bases around vertically integrated processors capable of finished guidewire geometries rather than raw wire.
- Fasteners:Shape-memory couplings and connectors for vibration-resistant aerospace assembly.
- Sensors:Temperature-responsive switches and position indicators with lower metallurgical stringency.
Stents anchor medical revenue; actuators are climbing the fastest as automotive thermal management specifications proliferate.
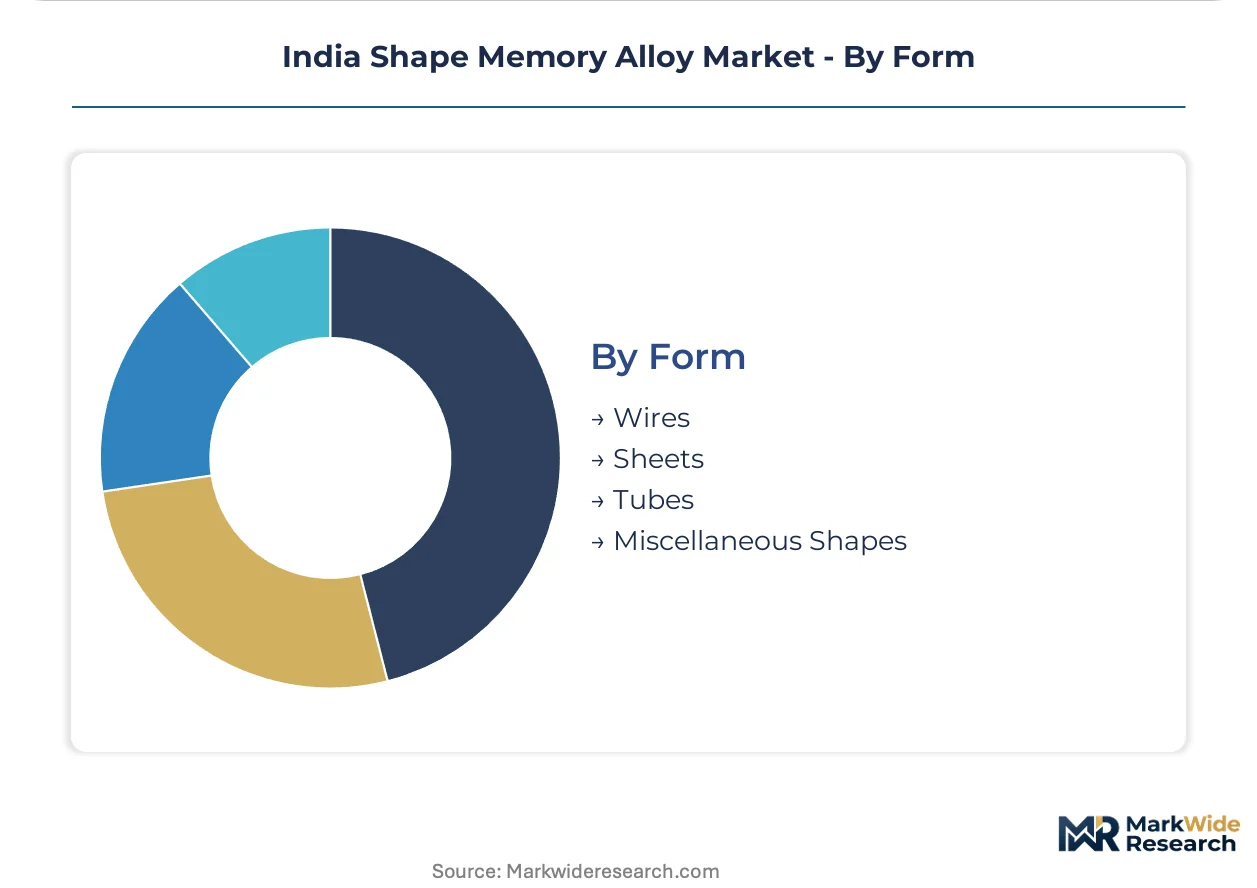
Form:
Wire geometries dominate medical procurement, while sheet and tube forms concentrate in aerospace actuator specifications.
- Wires:Fine-gauge diameters below 0.5mm for catheter and stent platforms requiring superelastic force delivery through tortuous vascular paths. SMA Wires India and Gujarat-based processors invest in in-line surface oxide monitoring to maintain ASTM F2063-compliant passivation during drawing.
- Tubes:Hollow cylindrical geometries for aerospace deployment mechanisms and hydraulic actuators. MIDHANI produces defense-grade superelastic tubing through captive vacuum arc remelting, with ISRO satellite programs specifying tight dimensional tolerances.
- Sheets:Flat-rolled plate for morphing aerostructures and thermal actuation surfaces.
- Miscellaneous Shapes:Custom-forged geometries for prototype robotic surgery instrumentation.
Wires lead current volumes; tubes are expanding most quickly as indigenous aerospace platform production accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's shape memory alloy demand outpaces Pakistan's nascent medical device sector by an order of magnitude, though Bangladesh's textile automation market is beginning to probe copper-based thermal actuator applications.
Maharashtra
Catheter OEMs and stent manufacturers in Mumbai and Pune drive procurement of fine-gauge nitinol wire for vascular device platforms. The CDSCO's risk-based reclassification of nitinol implants is compressing certification timelines for Class C and D devices. Metalworking clusters around Pune are installing in-line surface oxide monitoring systems to maintain ASTM F2063 compliance during wire drawing.
Gujarat
Guidewire processors in Ahmedabad concentrate demand for superelastic nitinol tubing with precise austenite finish temperature control. The BIS harmonization with ISO 5832-11 surgical alloy norms is tightening composition tolerances for implantable grades. Vacuum-melting investments are accelerating in the Sanand-Vadodara corridor as domestic producers seek captive VAR capacity.
Telangana
Hyderabad's medical device parks offer land and power subsidies attracting nitinol processors from saturated western corridors. The PLI scheme for specialty steel reduces capital cost burdens for vacuum arc remelting furnace installations. Robotic surgery instrumentation startups in Genome Valley are specifying novel wire-form geometries for articulating graspers.
Karnataka
Bengaluru's automation clusters probe copper-based SMA alternatives for compliant mechanism research in surgical robotics. The state's electronics manufacturing zones are piloting thermal actuator applications in consumer devices. Aerospace sub-assembly units near HAL headquarters are evaluating nickel-titanium superelastic tubing for satellite deployment mechanisms.
India Shape Memory Alloy Market Competitive Landscape
Western India producers anchor the domestic supply tier; Japanese and European specialists hold premium-grade import positions through established medical device certification pathways. The vendor base concentrates around three strategic archetypes: defense-anchored superalloy suppliers with captive VAR infrastructure, fine-gauge wire specialists serving catheter OEMs, and precious metal coaters layering corrosion protection onto shape memory substrates. Capacity expansion and backward integration into vacuum melting represent the dominant competitive moves as BIS certification requirements tighten.
Among domestic fabricators, Mishra Dhatu Nigam Ltd occupies the defense-grade superalloy tier with captive vacuum arc remelting infrastructure serving ISRO and DRDO programs. SMA Wires India exemplifies the fine-gauge wire specialist archetype targeting catheter and stent OEMs in Maharashtra and Gujarat. Johnson Matthey sits within the coating competency tier, layering precious metal protection onto shape memory substrates for corrosion-critical implantable applications.
| Leading Market Players |
|---|
| Mishra Dhatu Nigam Ltd (MIDHANI) |
| SMA Wires India |
| Thermo Fisher Scientific India Private Limited |
| ATI Specialty Alloy & Components |
| SAES Getters |
| Furukawa Electric Co., Ltd. |
| Nippon Steel & Sumitomo Metal |
| Johnson Matthey |
| Daido Steel Co., Ltd. |
| Others |
Supply & Pricing Matrix
Captive vacuum-melting investments by domestic nitinol producers anchor both supply security and pricing power against volatile London Metal Exchange nickel contracts. MIDHANI's integrated VAR infrastructure and SMA Wires India's backward integration into fine-gauge wire drawing compress margin exposure for implantable-grade material while forcing non-integrated competitors toward spot-market nickel procurement.
Pricing Analysis
Capacity additions in Gujarat and Telangana are reshaping price floors for implantable nitinol wire as domestic vacuum-arc remelting investments reduce import dependency. Contract-based long-term offtake dominates procurement between Maharashtra stent OEMs and certified wire processors, with price differentiation separating CDSCO Class D implant grades from industrial actuator specifications. Cost compression in copper-based alloy segments is intensifying because Tamil Nadu automotive thermal valve manufacturers are migrating from nitinol to lower-transformation-temperature alternatives. Medical device OEMs exhibit least price sensitivity due to regulatory lock-in, while consumer electronics actuator buyers drive hardest bargain negotiation.
Supply Chain Analysis
Single-source vulnerability sits with MIDHANI's captive defense-grade VAR capacity, which dominates traceable vacuum-melted supply for ISRO and DRDO programs. Raw material procurement draws from Indonesian and Philippine nickel laterite feeds, Australian titanium sponge, and domestic ferro-nickel intermediates. Commodity price volatility represents the structural risk, with nickel contract spikes transmitting directly to wire-drawer margins within 60-90 day lag. Distribution runs through vertically integrated processors delivering finished guidewire geometries rather than raw wire to Maharashtra and Gujarat catheter OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's shape memory alloy market functions as a geographic-arbitrage play where domestic vacuum-melting investments exploit the cost differential against European and Japanese import pricing while CDSCO regulatory localization accelerates certification timelines for locally manufactured implants.
For Market Incumbents: Deepen captive VAR capacity and in-line surface oxide monitoring to defend against emerging Telangana entrants with PLI-subsidized furnace installations. Accelerate BIS-ISO 5832-11 dual certification documentation ahead of harmonization deadlines to lock in stent OEM supplier consolidation. Prioritize robotic surgery instrumentation wire-form development as catheter OEMs expand beyond vascular platforms. For New Entrants and Emerging Players: Enter via Hyderabad and Bengaluru medical device parks where land and power subsidies undercut saturated Maharashtra-Gujarat corridor operating costs. Target copper-based SMA thermal actuator white space in Tamil Nadu automotive and Karnataka consumer electronics clusters. Pursue catheter OEM partnerships through finished guidewire geometry capabilities rather than commodity wire supply. For Investors and Strategic Acquirers: Roll-up economics work for fine-gauge wire specialists with captive shape-setting operations because catheter OEM supplier consolidation favors integrated processors over trading-house intermediaries. Five-to-ten year viability hinges on CDSCO fast-track pathway access and BIS certification velocity. Watch for PLI scheme expansion announcements as inflection signal for second-wave vacuum-melting investment feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Arc Remelting Capacity Expansion | Captive VAR infrastructure secures CDSCO traceability requirements for Class D implant supply. |
| BIS-ISO 5832-11 Dual Certification Investment | Harmonized alloy grade approval accelerates stent OEM procurement decisions ahead of competitors. |
| Robotic Surgery Instrument Partnership | Articulating grasper wire specifications open revenue streams beyond saturated vascular stent markets. |
| Backward Integration into Titanium Sponge | Plasma-arc cold hearth melting pilots bypass traditional VAR bottlenecks for prototype geometries. |
| Telangana-Karnataka Geographic Expansion | Hyderabad medical device park subsidies reduce landed cost against incumbent Maharashtra operations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with VAR melt chemists, catheter OEM procurement directors, CDSCO regulatory affairs specialists, and BIS certification auditors with secondary validation against CDSCO medical device registration databases, BIS alloy grade notifications, PLI scheme disbursement records, and London Metal Exchange nickel contract archives. Bottom-up triangulation across Maharashtra and Gujarat wire processor output estimates was cross-checked against top-down aerospace and medical device demand modeling.
Segment-weighting approaches distributed value and volume across nitinol versus copper-based alloy composition, medical device versus aerospace versus automotive end-use, and wire versus tube versus sheet geometric form, with additional dimensional layering for CDSCO risk-class certification tier. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of indigenous defense aerospace platform production schedules and stent market localization trajectories.
Inputs from CDSCO registration filings and BIS standards notifications were available through the study window; gaps in private wire-producer capacity utilization data introduce uncertainty bands around domestic supply-side expansion timelines. Forecasts reflect assumptions regarding PLI scheme continuity and nickel price regime stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Global Quartz Countertops Market