
 Metallurgical Rubber Roller Market | 2026-2036
Metallurgical Rubber Roller Market Size, Share, and Industry Trends Forecast 2026-2036
Metallurgical Rubber Roller Market Insights
Buyer concentration among steel and aluminum producers is consolidating as integrated mills prefer long-term service contracts over spot purchases of metallurgical rubber rollers. Menges Roller Company leverages its North American manufacturing footprint to serve this consolidated base. Nippon Steel & Sumikin Roll Co., Ltd. anchors supply relationships across Asian metallurgical complexes with specialized heat-resistant formulations. Suzhou Baosu Mining and Metallurgical Equipment Co. competes on cost-efficient compression-molded rollers for mid-tier mills.
A metallurgical rubber roller is a metal-cored cylinder bonded with elastomeric compounds, typically rated for surface temperatures exceeding 150°C and Shore hardness between 60A and 90A, designed to transport, press, or shape metal strip and slab in continuous casting and rolling operations. Synthetic rubber and silicone rubber segments lead in value terms due to superior thermal degradation resistance in hot-strip mill environments. Compression molding dominates technology selection for large-diameter rollers where void-free bonding to steel cores determines operational lifespan, while injection molding gains traction in precision coating applications requiring tighter dimensional tolerances.
EPA emissions standards and OSHA workplace safety rules shape rubber compound formulations and roller refurbishment practices in the United States. REACH restrictions on polycyclic aromatic hydrocarbons and EU Green Deal carbon-border adjustments push European suppliers toward bio-based curing agents and recycled rubber feedstocks. Stakeholders must monitor how China's MEE enforcement of dual carbon goals affects domestic roller pricing and export availability from Hebei and Jiangsu manufacturing bases.
Market Dynamics
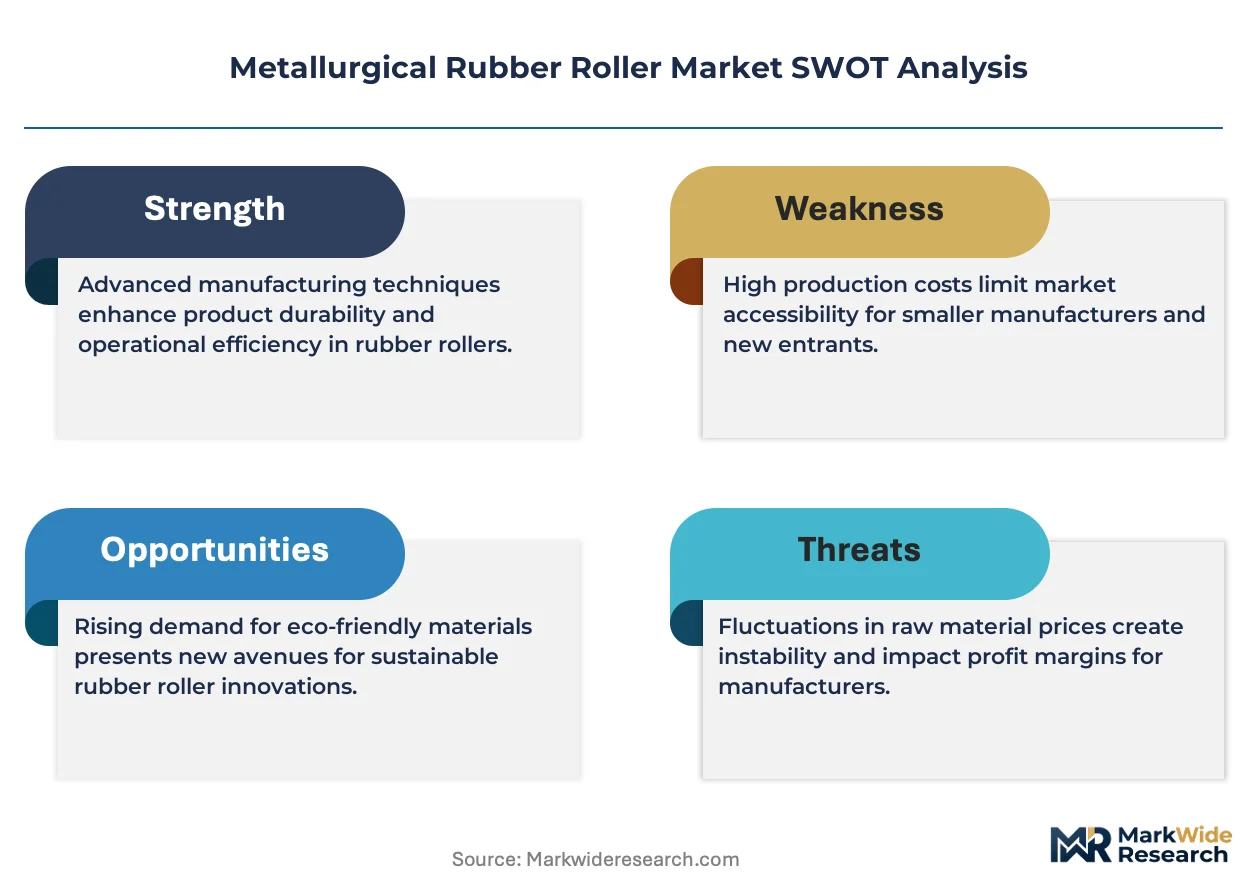
Steel mill consolidation into mega-complexes is compressing supplier bases and forcing roller manufacturers to absorb lifecycle risk through performance-guaranteed service contracts rather than unit sales.
Growth Catalysts
- Hot-strip mill expansion:Steel producers in China's Hebei province are commissioning wide-strip lines rated above 2,000mm, each requiring 40-60 heat-resistant rollers per casting section. This cluster density creates procurement economies that pull specialized compound formulations.
- REACH chemical restrictions:ECHA's tightening polycyclic aromatic hydrocarbon limits in rubber curing agents is accelerating reformulation investment among European suppliers, creating first-mover advantage for compliant producers.
- Continuous casting retrofits:Aluminum smelters are replacing batch slab handling with thin-strip casters that demand precision-bonded silicone rubber rollers for oxide-free surface transport.
Market Restraints
- Petrochemical feedstock volatility:Synthetic rubber compounds depend on styrene-butadiene and nitrile precursors tied to crude oil indices, compressing margin predictability for compounders serving price-locked annual contracts.
- Hebei manufacturing concentration:Over 60% of China's metallurgical roller capacity sits within 200km of Tangshan, exposing supply continuity to single-region environmental enforcement actions by MEE.
- Thermal degradation ceiling:Conventional nitrile rubber formulations harden and crack above 180°C surface temperature, limiting deployment in next-generation direct-strip-casting lines operating at 200°C+.
Strategic Opportunities
- India's PLI-scheme steel expansion:The country's production-linked incentive program for specialty steel is attracting greenfield mill investments in Odisha and Jharkhand, creating virgin demand for rollers without incumbent supplier relationships.
- Predictive maintenance integration:Roller-mounted temperature and vibration sensors streaming to cloud analytics platforms enable outcome-based pricing models where suppliers guarantee uptime rather than product life.
- Bio-based curing agents:EU Green Deal carbon-border adjustments incentivize rubber compounders to substitute petroleum-derived vulcanization accelerators with lignin-derived alternatives, opening premium positioning.
Industry Challenges
- Bonding technician scarcity:Void-free rubber-to-steel adhesion requires 10,000+ hour apprenticeship in compression molding, and retiring European and Japanese specialists are not being replaced at sufficient rates.
- Dual-carbon compliance timeline:China's MEE enforcement of provincial emissions caps is forcing Hebei roller plants to install regenerative thermal oxidizers on short deadlines, straining capex availability for compound R&D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallurgical Rubber Roller Market |
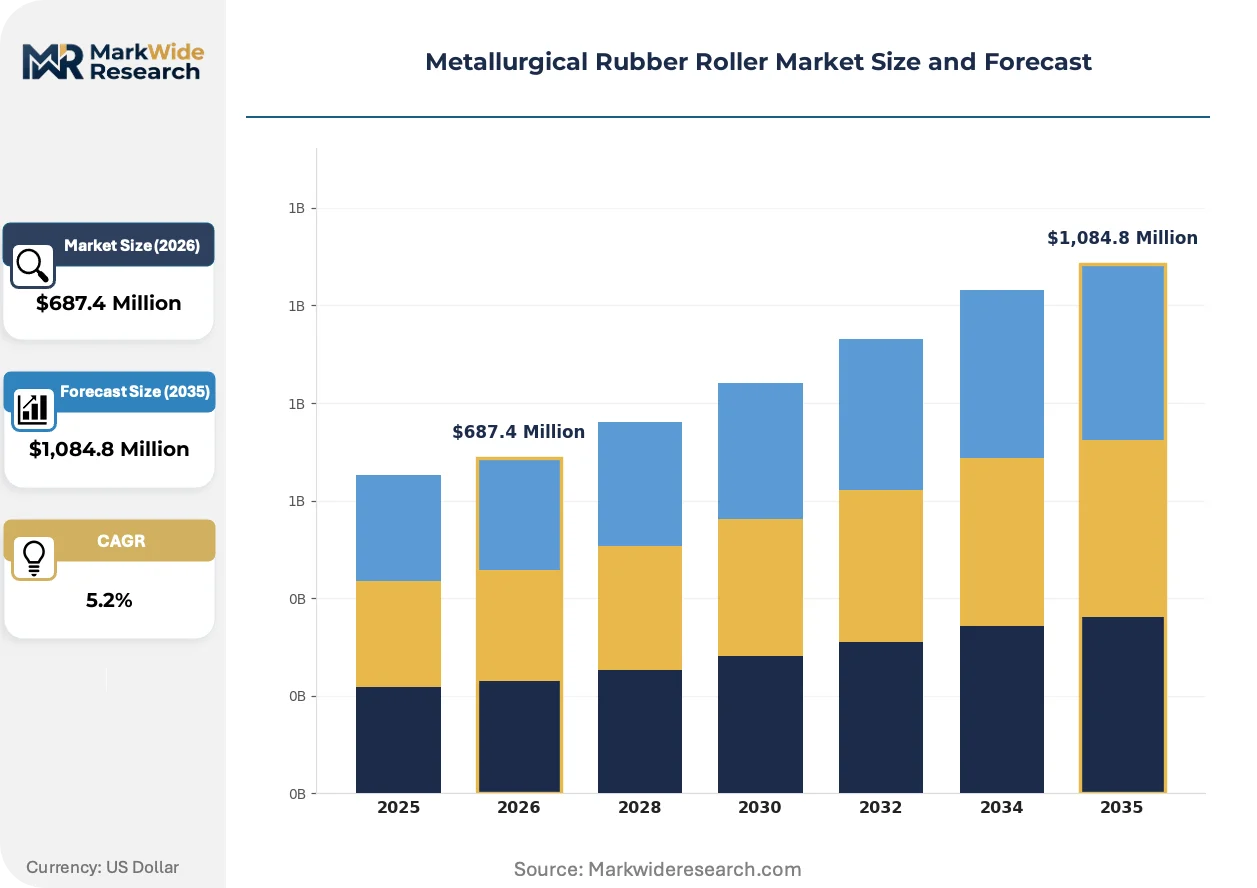
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,084.8 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Foam Rubber, Silicone Rubber Application: Printing, Coating, Textile, Packaging End User: Manufacturers, Contractors, Distributors, Service Providers Technology: Extrusion, Compression Molding, Injection Molding, Calendering |
| Companies Covered | Menges Roller Company, Western Roller Corporation, Mengxiang Rubber, REMCO Engineering, Suzhou Baosu Mining and Metallurgical Equipment Co., Jizhou Hengfeng Rubber Roll Co., Cangzhou Liwo Machinery Equipment Co., Nanjing Jin Sanli Rubber & Plastic Co., Nippon Steel & Sumikin Roll Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallurgical Rubber Roller Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are forcing simultaneous reformulation of rubber compounds and redesign of bonding architectures in metallurgical roller production.
Plasma surface preparation of steel cores is converging with conventional compression molding to eliminate mechanical roughening steps. Japanese integrated mills are piloting this hybrid process for thin-strip aluminum casters. The technology is converging with established molding infrastructure to compress bonding cycle times by 30% while improving shear strength at the rubber-metal interface.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber articles are forcing compounders to validate alternative curing accelerator packages. Industrial consequence includes 18-24 month requalification timelines for rollers in EU-serving export mills. German steel producers are most affected, demanding batch-traceable compound documentation that Chinese suppliers struggle to provide.
Integrated mills are unbundling roller supply from OEM equipment packages and awarding separate lifecycle service contracts to specialized compounders. This procurement model change disrupts traditional captive supply relationships between rolling mill builders and their affiliated roller divisions. The shift is most visible in North American steel restart projects, where private equity-owned mills prioritize operational expenditure flexibility over capital ownership.
Metallurgical Rubber Roller Market Segmentation
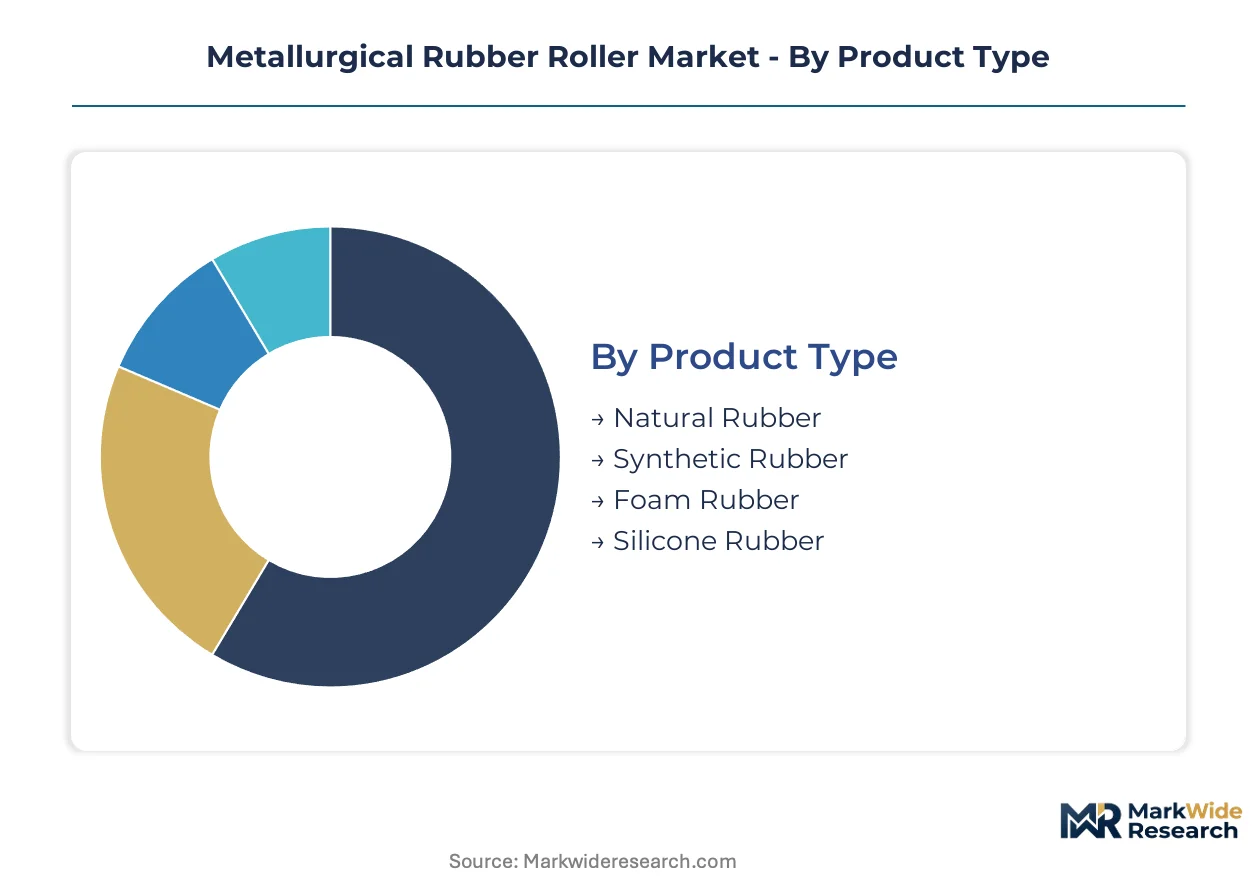
Segmentation in metallurgical rubber rollers reveals how thermal performance requirements and bonding precision dictate procurement patterns across steel and aluminum processing lines. Buyers select compounds and manufacturing technologies based on operating temperature bands, metal substrate sensitivity, and lifecycle cost structures rather than upfront unit pricing alone.
Product Type:
Steel mills and aluminum smelters differentiate compound selection primarily by surface temperature exposure and Shore hardness specifications for their casting and rolling operations.
- Synthetic Rubber:Styrene-butadiene and nitrile formulations dominate hot-strip mill installations rated for 150-180°C surface temperatures. Demand clusters in China's Hebei province steel complexes where wide-strip lines require heat-resistant rollers for oxide-free metal transport.
- Silicone Rubber:Premium elastomeric compounds withstand thermal degradation above 180°C in direct-strip-casting applications. Thin-strip aluminum casters in Japanese integrated mills specify silicone for precision-bonded rollers that prevent surface contamination during continuous casting.
- Natural Rubber:Lower-cost compounds serve ambient-temperature auxiliary conveying systems in batch slab handling operations.
- Foam Rubber:Lightweight cellular structures find limited deployment in cushioning applications for delicate metal finishing stages.
Synthetic rubber leads volumes today; silicone rubber is gaining share fastest.
Application:
End-use differentiation tracks how metal formability requirements and surface finish specifications determine roller hardness profiles and bonding architectures.
- Coating:Precision roller applications in continuous galvanizing lines require uniform elastomer thickness for zinc-aluminum alloy deposition. German steel producers under REACH Annex XVII compliance pressure demand batch-traceable compound documentation for coating rollers.
- Printing:Metallurgical marking and identification systems use rubber rollers for ink transfer onto hot metal surfaces in Chinese and Indian mill environments.
- Textile:Non-metallurgical crossover applications include fiber processing equipment with limited relevance to core steel and aluminum processing demand.
- Packaging:Peripheral material handling systems in finished coil dispatch areas utilize lower-specification rollers outside primary metallurgical value chains.
Coating applications anchor current procurement volumes; printing applications show steepest expansion trajectory.
End User:
Procurement authority concentration varies by mill ownership structure, with integrated steel complexes consolidating supplier relationships differently than equipment contractors serving brownfield retrofits.
- Manufacturers:Integrated steel and aluminum producers with in-house maintenance divisions specify rollers directly for continuous casting and hot-rolling lines. Private equity-owned North American steel restarts favor operational expenditure flexibility through lifecycle service contracts.
- Contractors:Engineering procurement construction firms sourcing rollers for greenfield mill installations in India's Odisha and Jharkhand PLI-scheme steel projects.
- Distributors:Regional inventory holders serving mid-tier mills with compression-molded replacement rollers.
- Service Providers:Specialized roller refurbishment operators extending operational lifespan through re-bonding and compound reconditioning services.
Manufacturers dominate current demand; contractors show fastest volume growth.
Technology:
Process selection hinges on roller diameter, bonding integrity requirements, and dimensional tolerance specifications for specific metal processing stages.
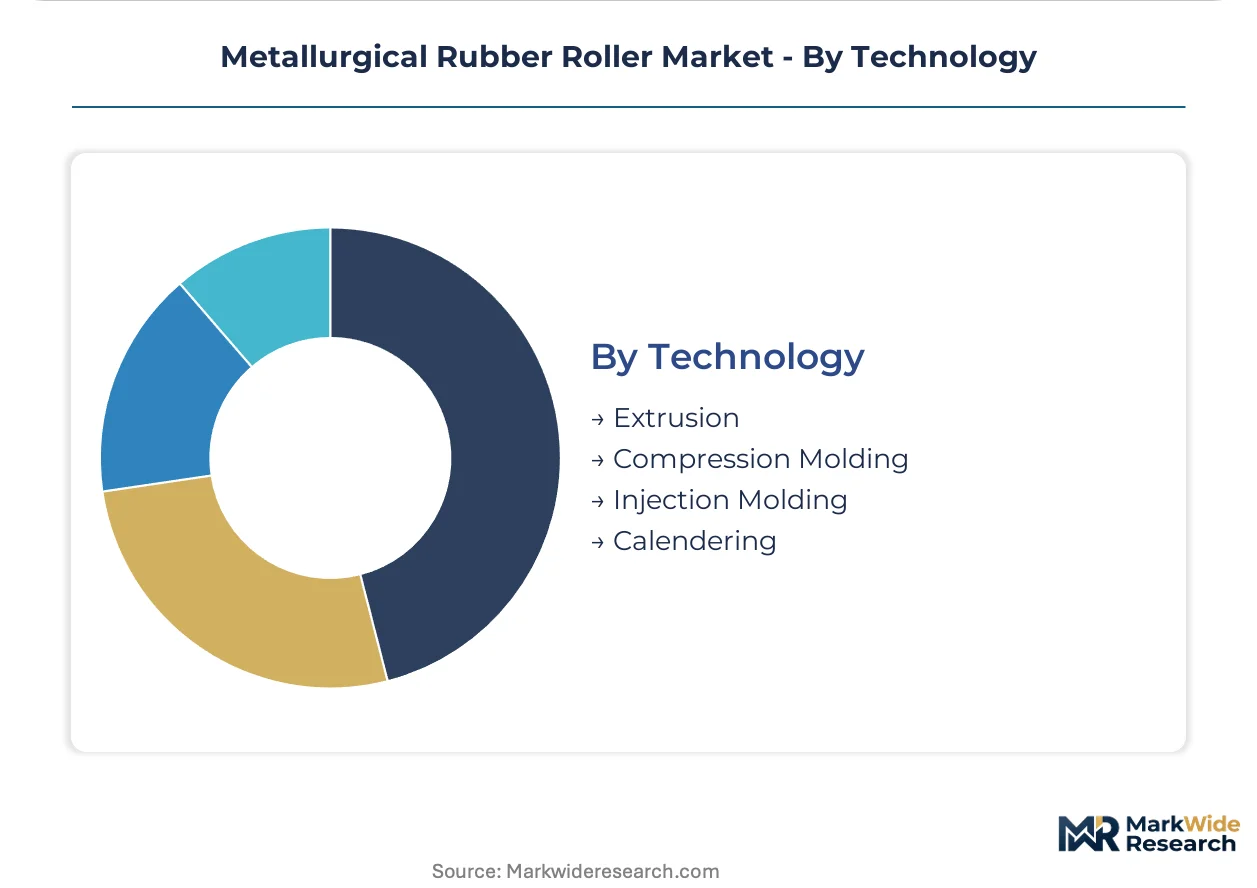
- Compression Molding:Large-diameter roller production for steel mill applications depends on void-free rubber-to-steel adhesion through conventional compression cycles. Retiring European and Japanese bonding technicians with 10,000+ hour apprenticeships constrain capacity expansion.
- Injection Molding:Precision coating applications requiring tighter dimensional tolerances gain adoption for thin-strip aluminum caster rollers. Plasma surface preparation of steel cores converges with injection processes to compress bonding cycle times.
- Extrusion:Continuous profile generation for roller covering operations in high-volume replacement programs.
- Calendering:Sheet rubber formation for subsequent roller covering in refurbishment operations.
Compression molding retains dominant volume position; injection molding climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bonding technician apprenticeships in compression molding concentrate in Germany, Japan, and China's Hebei province, creating geographic pockets of specialized metallurgical roller fabrication expertise that resist rapid replication elsewhere.
China
Hebei province steel complexes in Tangshan and surrounding cities drive bulk procurement of heat-resistant rollers for wide-strip lines rated above 2,000mm. MEE enforcement of dual carbon goals and provincial emissions caps is forcing roller plants to install regenerative thermal oxidizers on compressed timelines. Over 60% of domestic metallurgical roller capacity sits within 200km of Tangshan, exposing supply continuity to single-region environmental actions.
Japan
Integrated mills in the Chubu and Kansai regions pilot plasma surface preparation of steel cores for thin-strip aluminum casters requiring precision-bonded silicone rubber rollers. METI industrial standards shape quality benchmarks for oxide-free surface transport applications. Nagoya-area fabricators anchor supply relationships across Asian metallurgical complexes with specialized heat-resistant formulations.
Germany
Ruhr Valley steel producers under ECHA REACH Annex XVII compliance pressure demand batch-traceable compound documentation for coating rollers in continuous galvanizing lines. EU Green Deal carbon-border adjustments push suppliers toward bio-based curing agents and recycled rubber feedstocks. German compounders face 18-24 month requalification timelines for alternative curing accelerator packages.
United States
Private equity-owned steel restarts in the Midwest and Southeast favor operational expenditure flexibility through lifecycle service contracts over capital ownership of roller inventories. EPA emissions standards and OSHA workplace safety rules shape rubber compound formulations and refurbishment practices. Great Lakes region mills consolidate supplier bases as mega-complexes absorb lifecycle risk through performance-guaranteed arrangements.
India
Odisha and Jharkhand greenfield mill investments under the PLI-scheme for specialty steel create virgin demand for rollers without incumbent supplier relationships. BIS standards govern equipment specifications for new capacity. Eastern Indian steel clusters lack established roller refurbishment infrastructure, forcing reliance on imported bonded assemblies during commissioning phases.
Metallurgical Rubber Roller Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions in the metallurgical rubber roller market. Integrated steel and aluminum producers consolidate vendor relationships, compressing supplier bases into performance-guaranteed service contracts rather than transactional unit sales. Three archetypes dominate: North American manufacturers leveraging regional fabrication footprints, Asian compounders anchoring heat-resistant formulation expertise, and Chinese cost-efficient compression molders serving mid-tier replacement demand. Competitive moves center on backward integration into rubber compounding and geographic expansion through licensing arrangements with regional mill maintenance divisions.
Among Japanese fabricators, Nippon Steel & Sumikin Roll Co., Ltd. occupies a position exemplifying specialized heat-resistant formulation capabilities for integrated metallurgical complexes. Chinese manufacturers including Suzhou Baosu Mining and Metallurgical Equipment Co. and Jizhou Hengfeng Rubber Roll Co. represent the cost-efficient compression-molded segment serving steel production clusters. Menges Roller Company anchors North American supply relationships through regional manufacturing presence. These named entities illustrate how geographic origin and company structure correlate with archetype positioning rather than indicating specific strategic actions or market shares.
| Leading Market Players |
|---|
| Menges Roller Company |
| Western Roller Corporation |
| Mengxiang Rubber |
| REMCO Engineering |
| Suzhou Baosu Mining and Metallurgical Equipment Co. |
| Jizhou Hengfeng Rubber Roll Co. |
| Cangzhou Liwo Machinery Equipment Co. |
| Nanjing Jin Sanli Rubber & Plastic Co. |
| Nippon Steel & Sumikin Roll Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Integrated steel mills consolidating into mega-complexes across China's Hebei province and India's Odisha-Jharkhand belt are mandating performance-guaranteed service contracts over spot purchases, forcing roller manufacturers to absorb lifecycle risk and compress upfront pricing flexibility. This procurement shift concentrates volume with compounders capable of long-term bonding quality guarantees, squeezing mid-tier suppliers into commodity replacement cycles with thinner margins.
Pricing Analysis
Capacity additions in India's PLI-scheme steel corridors are reshaping price floors for heat-resistant formulations as new mills without incumbent relationships solicit aggressive bids from Chinese and European suppliers. Pricing stratifies across premium silicone compounds for thin-strip aluminum casters, standard nitrile formulations for hot-strip steel lines, and economy natural rubber grades for auxiliary conveying systems. Price differentiation hinges on REACH-compliant batch traceability and thermal degradation resistance certification. Cost compression in the economy tier is intensifying because Hebei manufacturers face MEE-mandated regenerative thermal oxidizer installations. Mid-tier steel mills in Southeast Asia exhibit highest price sensitivity; Japanese integrated aluminum smelters show least.
Supply Chain Analysis
Styrene-butadiene and nitrile rubber precursor supply rests on petrochemical complexes in China, South Korea, and Germany, with specialty silicone monomer production concentrating in Japan and the United States. Steel core fabrication draws from foundries in China's Hebei province, Japan's Chubu region, and Germany's Ruhr Valley. Bonding technician apprenticeship pipelines represent the critical chokepoint, with 10,000-hour training requirements constraining rapid capacity expansion. Distribution runs through mill maintenance divisions for integrated producers and regional distributors serving mid-tier replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH Annex XVII polycyclic aromatic hydrocarbon restrictions and China's MEE dual-carbon enforcement are accelerating reformulation investment and requalification timelines.
For Market Incumbents: To counter bonding technician scarcity eroding quality consistency, anchor supply relationships through captive apprenticeship programs in Hebei and Germany while securing backward integration into specialty silicone compounding to control thermal degradation resistance specifications. For New Entrants and Emerging Players: Capture virgin demand in India's Odisha-Jharkhand PLI-scheme steel installations where incumbent supplier relationships remain unformed. Prioritize compression-molded heat-resistant rollers for wide-strip lines rated above 2,000mm. Lead with lifecycle service contracts mimicking European performance-guarantee structures to differentiate from Chinese spot suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized compounders possessing REACH-compliant curing agent formulations and plasma surface preparation capabilities for thin-strip aluminum casters. Five-to-ten-year viability favors firms with demonstrated bonding requalification track records under tightening chemical content rules. Watch MEE enforcement intensity in Hebei as inflection signal for Chinese supply availability and export pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captures margin from Japanese monomer suppliers while securing thermal degradation resistance for 200°C+ casting lines. |
| Plasma Surface Preparation Adoption | Compresses bonding cycle times 30% for Japanese thin-strip aluminum casters demanding oxide-free transport. |
| REACH-Compliant Curing Agent Validation | Unlocks 18-24 month requalification contracts with German steel producers under ECHA Annex XVII pressure. |
| Lifecycle Service Contract Expansion | Aligns with North American private equity-owned mill preferences for operational expenditure flexibility over capital ownership. |
| Hebei Regenerative Thermal Oxidizer Installation | Preserves MEE compliance and export eligibility for China's concentrated metallurgical roller manufacturing base. |
Research Methodology
Coverage spans China, Japan, Germany, the United States, and India, with primary inputs from each market's steel and aluminum processing corridors. The research combines interviews with maintenance directors at integrated mills, procurement leads at engineering procurement construction firms, rubber compound technical R&D directors, and aftermarket service heads with secondary validation from customs and trade data, SEC 10-K filings of diversified industrial conglomerates, MEE emissions enforcement disclosures, and ECHA REACH restriction updates. Bottom-up roller unit demand estimates and top-down metallurgical equipment capex allocations were triangulated for convergence.
Segmentation granularity extends to compound type by thermal performance band, manufacturing technology by bonding precision requirement, end-use application by metal substrate sensitivity, and regional regulatory cluster by emissions and chemical content enforcement intensity. Value projections across the analysis window incorporate derived CAGRs from historic replacement cycle frequencies and greenfield capacity commissioning schedules. Forecast inputs include steel production capacity additions in Hebei and Odisha, aluminum thin-strip caster retrofits in Japanese integrated mills, and REACH requalification timeline bottlenecks affecting European supply availability.
Petrochemical feedstock volatility, MEE enforcement unpredictability in Hebei, and bonding technician apprenticeship pipeline collapse are the dominant revision risks to volume and value assumptions. Forecasts reflect documented assumptions about replacement cycle compression and procurement model shifts toward performance guarantees. A small set of named triggers—MEE provincial emissions cap adjustments, ECHA polycyclic aromatic hydrocarbon limit revisions, and Indian PLI-scheme steel capacity commissioning delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Hospital Rubber Sheet Market
Rubber
Rubber Sand Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Rubber Block Market
Rubber
EPDM Rubber Market
Rubber
Butyl Rubber Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Synthetic Rubber Market
Rubber
Rubber Flooring Market
Rubber
Europe Rubber Hose Market
Rubber
Global Chloroprene Rubber Market
Rubber
Conductive Silicone Rubber Market
Rubber
Rubber Rollers Market
Rubber
Tire Softener Market