
 Global Aluminum Foams Market | 2026-2036
Global Aluminum Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Foams Market Intelligence
Demand for aluminum foams is rotating from construction contractors and general industrial applications toward performance-driven aerospace manufacturers and automotive OEMs. ERG Aerospace Corporation leverages its specialization in high-specification materials to serve this shift. Cymat Technologies Ltd. competes on the basis of its proprietary melt foaming production processes. Meanwhile, Alantum Corporation sustains its market position through a focus on open-cell foam applications for sound insulation and thermal management.
Aluminum foams are advanced metallic materials featuring a cellular structure with a high volume of gas-filled pores. Their production via methods like melt foaming or powder metallurgy creates materials prized for lightweighting and energy absorption. The market for closed-cell foams remains the largest, anchored in demand for lightweight structures. However, open-cell products show higher growth potential, particularly for thermal management and sound insulation applications in the automotive sector.
Material specification is shaped by standards from bodies like the US NHTSA for automotive safety and the EU's CE marking for construction products. These regulations mandate specific performance criteria for energy absorption and fire resistance, influencing material selection. Concurrently, ISO standards provide a global benchmark for testing protocols. Future competitiveness depends on aligning product development with intensifying lightweighting mandates and circular economy principles.
Market Dynamics
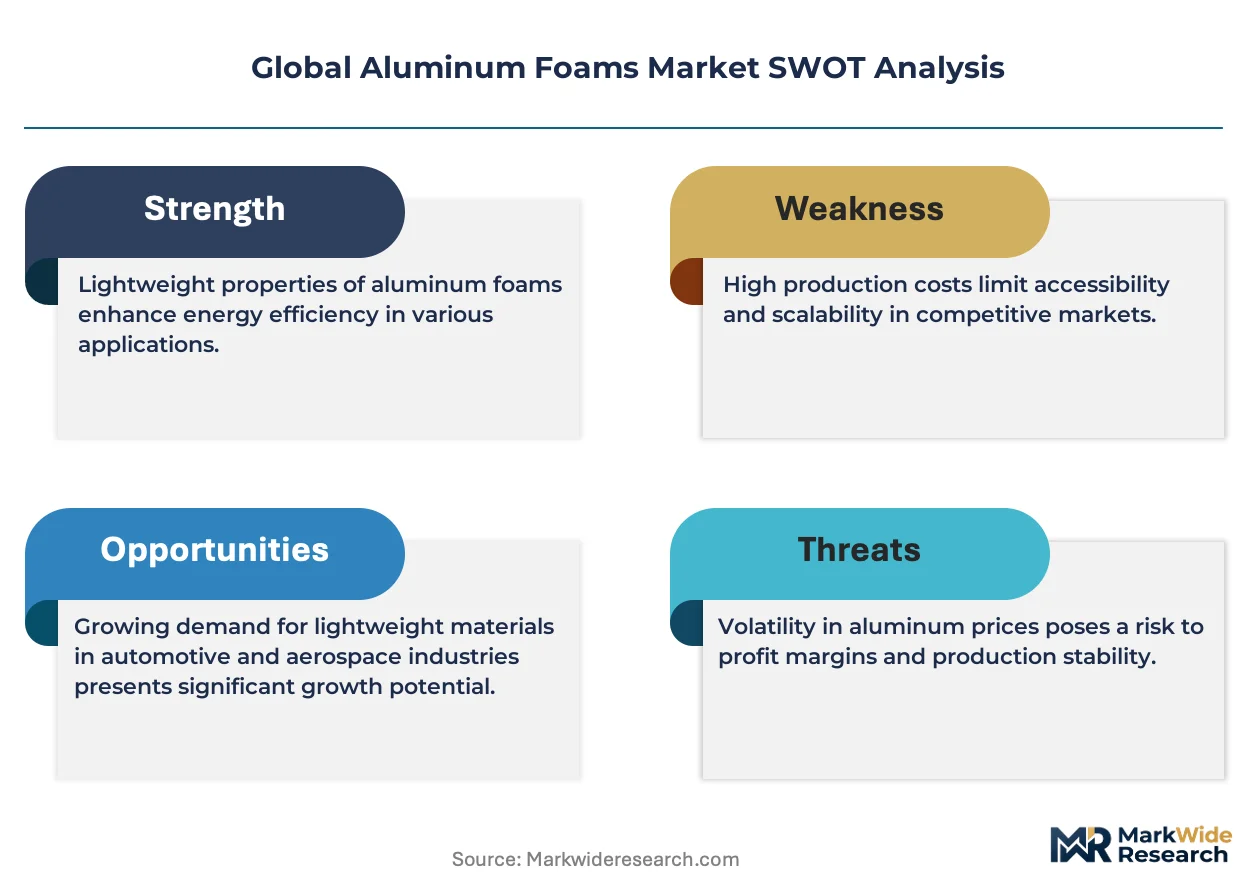
The market's central dynamic is the demand rotation from general industrial and construction applications toward performance-driven aerospace and automotive sectors. This shift prioritizes material properties like specific stiffness and energy absorption over pure cost-per-volume, reshaping production and specification.
Growth Catalysts
- Aerospace Lightweighting Mandates:Stringent fuel efficiency and emissions targets in the aviation industry drive demand for aluminum foams in lightweight structural components, such as fuselage panels and leading-edge wing sections, to reduce overall aircraft weight.
- Additive Manufacturing:The maturation of 3D printing technologies enables the fabrication of complex, functionally graded foam geometries that are impossible to produce with traditional methods, opening new design possibilities for heat exchangers and impact absorbers.
- Automotive Safety Standards:Regulations from bodies like the US NHTSA, which mandate specific crash-test performance, create consistent demand for aluminum foams in energy-absorbing structures like bumper beams and A-pillars in vehicles.
Market Restraints
- High Production Costs:The energy-intensive nature of production methods like melt foaming and powder metallurgy results in a high cost basis compared to conventional materials, limiting adoption in cost-sensitive, high-volume applications.
- Processing Complexity:Achieving consistent and uniform pore structures, a critical factor for predictable mechanical performance, remains a significant technical challenge, particularly for large or complex components.
- Substitution from Composites:In applications where ultimate weight savings are paramount, such as in motorsport or high-performance aerospace, aluminum foams face competition from carbon fiber and other polymer matrix composites.
Strategic Opportunities
- Electric Vehicle Thermal Management:The growing EV market presents a significant opportunity for open-cell foams in battery pack cooling systems, where their high surface area and thermal conductivity can improve heat dissipation and battery longevity.
- Acoustic Damping Applications:Developing specialized open-cell foams for sound insulation in luxury vehicles, high-speed rail, and aerospace cabins offers a path to enter high-margin, value-added segments beyond structural use cases.
- Circular Economy Alignment:EU Green Deal policies and similar global initiatives that favor recyclable materials create an opportunity to position aluminum foams as a sustainable alternative to plastics and non-recyclable composites in various industries.
Industry Challenges
- Standardization Gaps:A lack of universally accepted ISO standards for testing and characterizing aluminum foam properties creates friction in global supply chains, as specifications can vary between regions and suppliers.
- Capital Investment Hurdles:Scaling up production of advanced foam products, particularly those made via additive manufacturing, requires substantial capital expenditure in specialized equipment and controlled environment facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Foams Market |
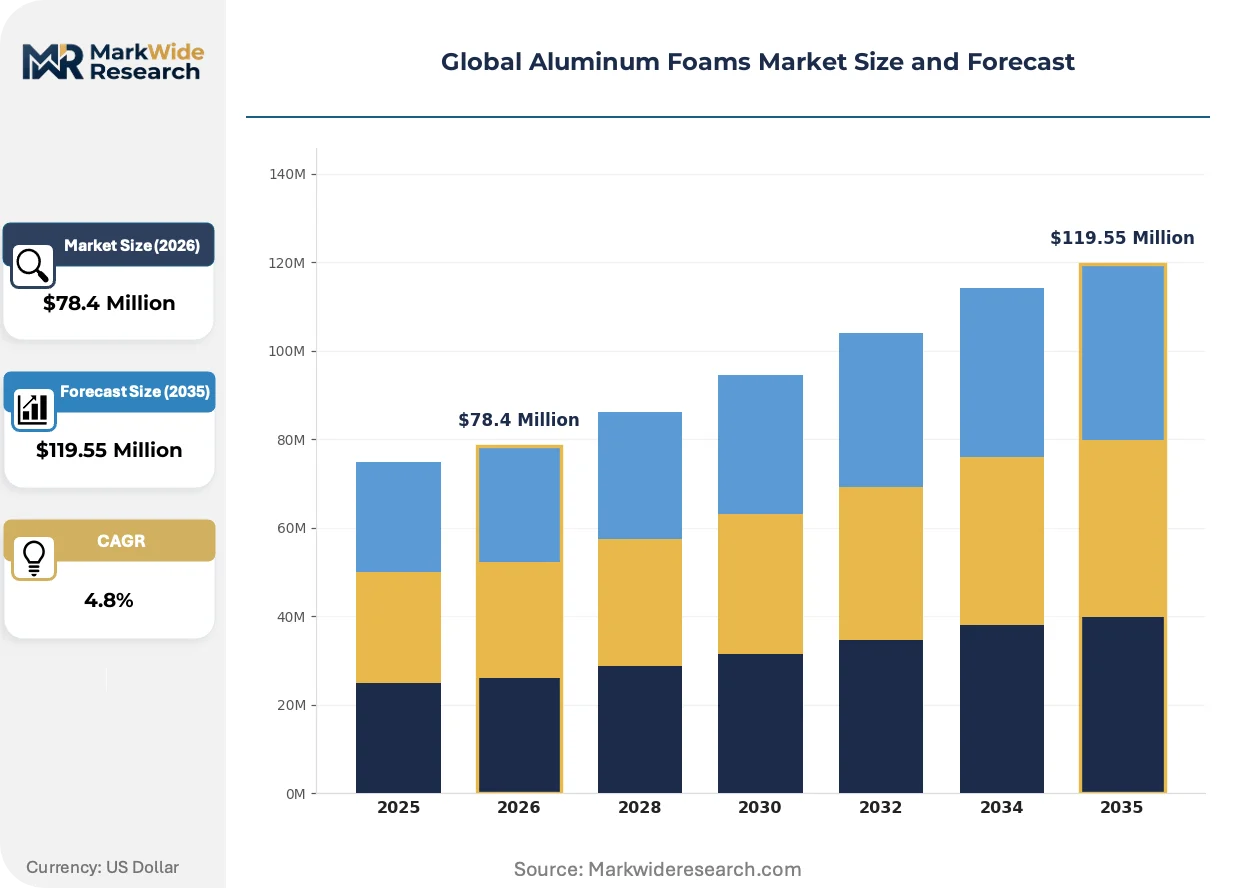
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $119.55 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Cell, Closed-Cell, Hybrid, Composite, Metallic Foam Application: Lightweight Structures, Sound Insulation, Thermal Management, Energy Absorption, Aerospace Components End User: Automotive OEMs, Aerospace Manufacturers, Shipbuilding Firms, Construction Contractors, Sports Equipment Producers Production Method: Powder Metallurgy, Melt Foaming, Gas Injection, Metal Foaming Agents, Additive Manufacturing |
| Companies Covered | ERG Aerospace Corporation, Cymat Technologies Ltd., Alantum Corporation, Pohltec Metalfoam GmbH, Havel Metal Foam GmbH, Aluinvent Zrt., Beihai Composite Materials Co., Ltd., American Elements, Liaoning Rontec Advanced Material Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Foams Market Strategic Shifts & Innovations
Specialization is the dominant theme, as producers move away from generic foam offerings toward materials engineered for specific performance outcomes. This trend is driven by sophisticated end-user demands in sectors where material failure is not an option, such as aerospace and automotive safety systems.
Additive manufacturing enables the creation of aluminum foam components with intricate internal geometries and functionally graded densities. Aerospace and medical device manufacturers are early adopters, using the technology for prototyping and producing highly optimized, low-volume parts. This capability is bifurcating the market between commoditized foam blocks and high-value, bespoke components designed for specific performance criteria.
Regulatory frameworks like the European Union's End-of-Life Vehicles (ELV) Directive are influencing material selection in the automotive industry. The directive incentivizes the use of materials with high recyclability rates, positioning aluminum favorably against polymer-based composites. Consequently, automotive OEMs in Germany and across the EU are increasing their evaluation of aluminum foams for structural components to meet circular economy targets.
A shift toward performance-based contracting is altering buyer-supplier relationships. Instead of purchasing foam based on material specifications like pores per inch, customers in the defense and aerospace sectors are defining requirements by desired outcomes, such as a specific level of kinetic energy absorption. This change is most visible within the US defense supply chain, favoring vendors with strong modeling and predictive analysis capabilities.
Global Aluminum Foams Market Segmentation
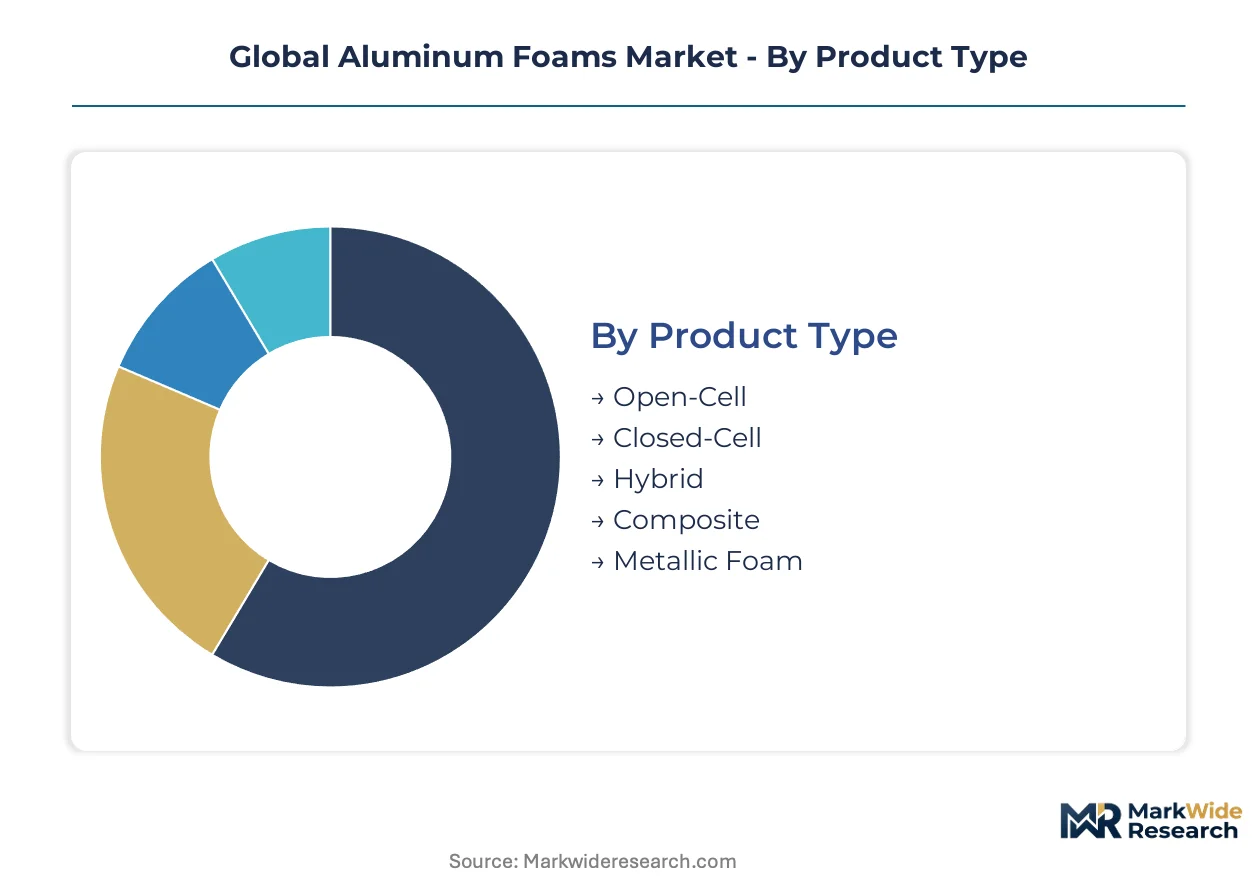
Market segmentation for aluminum foams provides a granular understanding of demand drivers and material property requirements across diverse industrial applications. This differentiation enables producers to align product development with specific end-user needs, optimizing material specifications for performance and cost-effectiveness. Strategic analysis of these segments helps identify high-growth areas and niche opportunities within the advanced materials landscape.
Product Type:
Margin pools in aluminum foam product types reflect material performance and manufacturing complexity.
- Closed-Cell:Closed-cell aluminum foams feature isolated pores, providing superior stiffness-to-weight ratios and enhanced buoyancy. Demand concentrates in Germany's automotive sector for lightweight structural components and crash-relevant parts, driven by stringent EU safety regulations.
- Open-Cell:Open-cell aluminum foams possess interconnected pores, offering high surface area and permeability for fluid flow. The automotive sector, particularly in the US, increasingly uses these foams for electric vehicle battery thermal management systems to improve cooling efficiency.
- Hybrid:Hybrid foams combine characteristics of both open and closed-cell structures for tailored performance in specialized applications.
- Composite:Composite aluminum foams integrate other materials to enhance properties like strength, stiffness, or fire resistance in demanding environments.
- Metallic Foam:Metallic foams represent a broader category encompassing various metal alloys beyond aluminum, used for diverse industrial applications.
Closed-Cell foam production holds installed capacity. Open-Cell foam is rotating up the share rankings.
Application:
The cost tier for aluminum foam applications varies significantly based on performance criticality and integration complexity.
- Lightweight Structures:Aluminum foams provide significant weight reduction in structural components, critical for fuel efficiency in transportation. Aerospace manufacturers in France utilize these materials for fuselage panels and wing sections to meet stringent emissions targets set by the EU.
- Energy Absorption:These foams dissipate kinetic energy during impact events, protecting occupants and critical systems. US automotive OEMs integrate aluminum foams into bumper beams and side impact protection, mandated by NHTSA safety standards.
- Sound Insulation:Open-cell aluminum foams effectively dampen acoustic vibrations, crucial for noise reduction in luxury vehicles and high-speed rail.
- Thermal Management:Aluminum foams facilitate heat exchange in systems like EV battery packs, leveraging their high surface area and thermal conductivity.
- Aerospace Components:Specific aerospace components, from engine nacelles to seating structures, benefit from aluminum foam's strength-to-weight advantages.
Lightweight Structures applications represent the largest segment. Thermal Management applications are gaining share fastest.
End User:
Application diversity drives end-user demand for aluminum foams, with specific industries requiring tailored material properties.
- Automotive OEMs:Automotive manufacturers integrate aluminum foams into vehicles for lightweighting and enhanced crashworthiness. German automotive companies use these materials extensively in EV platforms to improve range and meet EU ELV Directive recyclability goals.
- Aerospace Manufacturers:Aerospace companies utilize aluminum foams for structural and energy-absorbing components in aircraft. US aerospace firms apply foams in leading-edge wing sections and interior panels, driven by FAA regulations for material performance.
- Shipbuilding Firms:Shipbuilding firms employ aluminum foams for lightweight bulkheads and structural cores, improving vessel stability and fuel efficiency.
- Construction Contractors:Construction contractors use aluminum foams for façade elements and insulation panels, benefiting from their fire resistance and lightweight properties.
- Sports Equipment Producers:Sports equipment producers integrate foams into protective gear and performance components, balancing impact absorption with low weight.
Automotive OEMs currently represent the largest end-user segment. Aerospace Manufacturers show the steepest expansion trajectory.
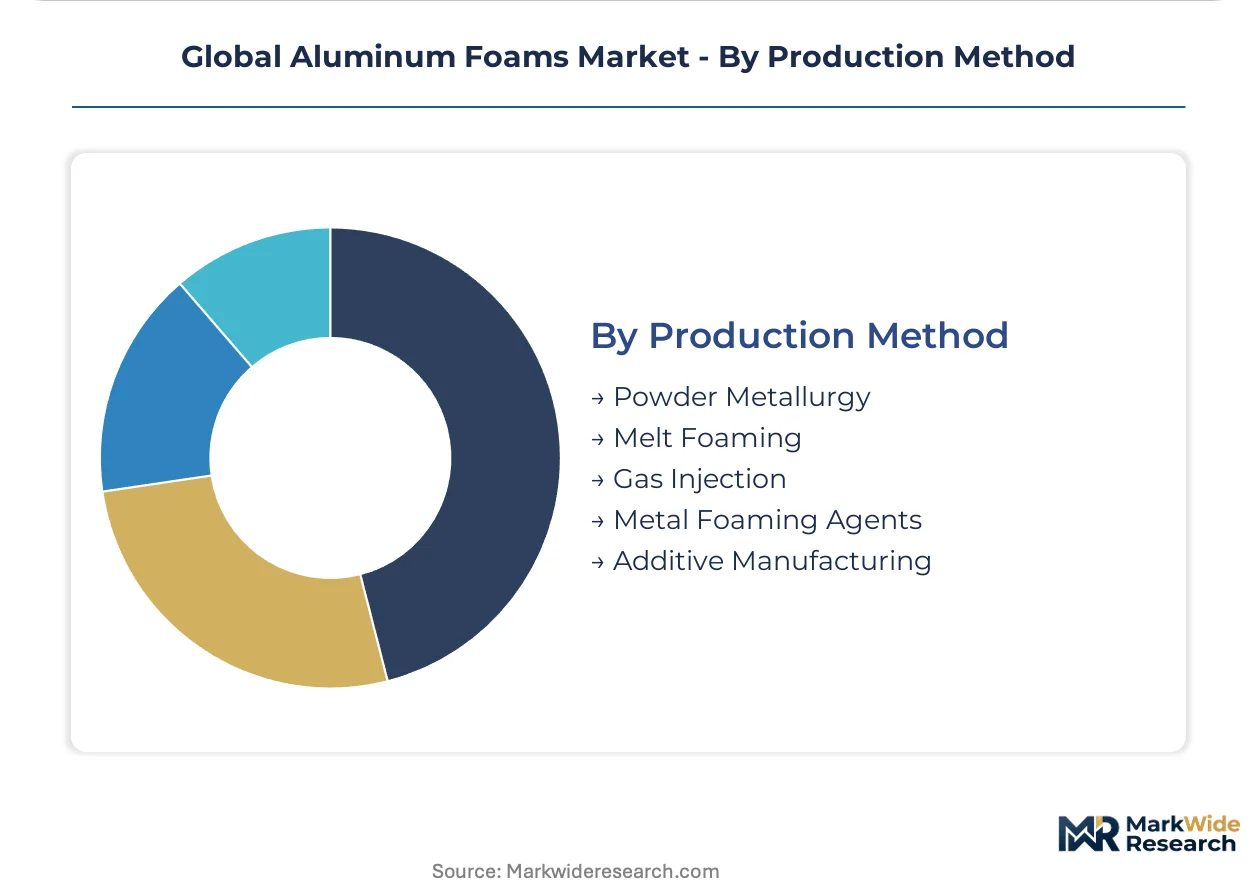
Production Method:
Customer type dictates the preferred production method for aluminum foams, balancing cost, complexity, and performance requirements.
- Melt Foaming:Melt foaming involves injecting gas into molten aluminum, creating a cellular structure upon solidification. This method is favored by high-volume manufacturers, such as Cymat Technologies Ltd., for producing large foam blocks for automotive applications.
- Additive Manufacturing:Additive manufacturing techniques, including 3D printing, enable complex, customized aluminum foam geometries. Aerospace and medical device manufacturers in Germany use this method for prototyping and specialized, low-volume components with optimized performance.
- Powder Metallurgy:Powder metallurgy consolidates aluminum powders and foaming agents under heat and pressure, yielding foams with fine, uniform pore structures.
- Gas Injection:Gas injection directly introduces gas into molten metal, a method often used for continuous production of aluminum foam panels.
- Metal Foaming Agents:Metal foaming agents decompose at high temperatures within a metal matrix, releasing gas to create the cellular foam structure.
Melt Foaming production holds significant installed capacity. Additive Manufacturing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market's supply-side dynamics reveal concentrated production capabilities in key industrialized nations. Specialized manufacturing processes for aluminum foams often align with end-user innovation hubs. This geographic alignment supports the high-performance demands from critical sectors like aerospace and automotive.
Germany
Demand for aluminum foams in Germany is particularly strong from its automotive and aerospace manufacturers. EU ELV Directive recyclability goals drive German automotive companies to integrate these materials into EV platforms. Industrial clusters in Bavaria and Baden-Württemberg are centers for advanced material development and application in high-performance vehicles.
United States
United States demand for aluminum foams is driven by aerospace lightweighting and automotive safety applications. NHTSA safety standards mandate specific crash-test performance, leading US automotive OEMs to use these foams in energy-absorbing structures. Aerospace firms in Washington state and California leverage foams for leading-edge wing sections and interior panels.
France
French aerospace manufacturers are significant consumers of aluminum foams for lightweight structural components. Stringent EU emissions targets influence material selection for fuselage panels and wing sections in French aircraft production. Toulouse's aerospace industry cluster actively researches and integrates advanced foams into next-generation aircraft designs.
Japan
Japan's automotive sector prioritizes aluminum foams for lightweighting and thermal management in electric vehicles. METI initiatives support advanced materials research, fostering innovation in foam production and application. Automotive manufacturing hubs around Nagoya and Yokohama are key areas for developing and implementing these advanced metallic materials.
China
China's rapidly expanding EV market and infrastructure development are driving the adoption of aluminum foams. National dual carbon goals encourage the use of lightweight and recyclable materials in transportation and construction. Manufacturing centers in the Yangtze River Delta focus on scaling up production for both domestic and international automotive supply chains.
Global Aluminum Foams Market Key Industry Players
Concentration sits with specialized material science firms capable of high-precision manufacturing. The market structure exhibits a tiered landscape, ranging from established industrial producers to agile additive manufacturing specialists. Two strategic archetypes emerge: volume producers focusing on melt foaming and niche players leveraging additive manufacturing for complex geometries. Companies pursue strategic partnerships and portfolio diversification to expand their application reach.
Among the specialized material providers, ERG Aerospace Corporation exemplifies a focus on high-specification materials for performance-driven sectors. Cymat Technologies Ltd. represents a segment of producers anchored by proprietary melt foaming production processes, enabling larger-scale output. Alantum Corporation occupies a position emphasizing open-cell foam applications, particularly for sound insulation and thermal management. These entities collectively highlight the market's differentiation across material properties and manufacturing approaches, catering to distinct end-user requirements within the advanced materials landscape.
| Leading Market Players |
|---|
| ERG Aerospace Corporation |
| Cymat Technologies Ltd. |
| Alantum Corporation |
| Pohltec Metalfoam GmbH |
| Havel Metal Foam GmbH |
| Aluinvent Zrt. |
| Beihai Composite Materials Co., Ltd. |
| American Elements |
| Liaoning Rontec Advanced Material Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
EU CE marking for construction products gates supply qualification for aluminum foams, simultaneously influencing price differentiation based on certified performance and regional compliance. This regulatory framework ensures material specification aligns with safety and environmental standards, impacting producer costs and market access.
Pricing Analysis
US NHTSA safety standards dictate the pricing tier structure for aluminum foams in automotive applications, emphasizing performance-based valuation over commodity pricing. Price differentiation stems from the material's specific energy absorption capabilities and the level of customization required for complex geometries. Cost compression in high-volume applications is intensifying due to the energy-intensive nature of production methods like melt foaming. Aerospace manufacturers represent the least price-sensitive segment, prioritizing performance specifications, while construction contractors are highly price-sensitive.
Supply Chain Analysis
Specialized melt foaming facilities underwrite the supply chain for aluminum foams, concentrating production capabilities in Germany, the United States, and China. The supply chain draws heavily from primary aluminum sources and specialized foaming agents. Capital investment hurdles for scaling up advanced production methods present a structural risk, limiting new entrants. Distribution to end-users typically occurs through direct sales channels to large automotive OEMs and aerospace manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum foam market faces a scarcity of advanced manufacturing expertise, particularly in consistent pore structure control for high-performance applications. This gap creates opportunities for focused investment and strategic development across the value chain.
For Market Incumbents: Consolidate market share by investing in advanced processing technologies to improve consistency and reduce production costs. Develop robust R&D programs focused on enhancing material specifications for extreme operating conditions to counter substitution from advanced composites. Pursue strategic partnerships with additive manufacturing specialists to expand capabilities for complex, bespoke component production.
For New Entrants and Emerging Players: Lead with innovation in open-cell foam applications for electric vehicle thermal management, leveraging high surface area and thermal conductivity. Target the automotive sector's growing demand for battery pack cooling systems as the most penetrable segment. Implement a go-to-market strategy centered on additive manufacturing capabilities, offering customized, high-performance components for niche applications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized material science firms holding proprietary melt foaming or powder metallurgy expertise. Evaluate targets with strong intellectual property in advanced foam geometries and established relationships with aerospace or automotive OEMs. The long-term viability of this market over the next 5-10 years rests on continued lightweighting mandates and circular economy pressures. Watch for progress in ISO standardization for aluminum foam characterization as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Additive Manufacturing | Enables complex geometries for aerospace and medical device applications, expanding design possibilities. |
| Develop Open-Cell Foams for EVs | Addresses critical thermal management needs in electric vehicle battery packs, improving longevity. |
| Standardize Material Testing Protocols | Reduces friction in global supply chains by providing universal benchmarks for aluminum foam properties. |
| Form Strategic Partnerships with OEMs | Secures long-term contracts and co-development opportunities for next-generation lightweight components. |
| Focus on Recyclability and Circularity | Aligns products with EU Green Deal policies and strengthens market position against non-recyclable materials. |
Research Approach
Operator-level perspectives from aerospace engineers, automotive procurement leads, materials scientists, and production line managers anchored the qualitative base for this analysis. This primary research was triangulated with extensive secondary data from ISO standards, US NHTSA reports, EU ELV Directive documents, and company annual reports. Both bottom-up and top-down approaches were utilized to ensure comprehensive data validation.
Sensitivity analysis framed the quantitative modeling, integrating key market dynamics across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, production method, and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected forward based on industry-specific inputs like EV production forecasts and aerospace build rates.
Forecasts assume regulatory continuity in EU and US regimes; material policy shifts would require re-modeling. These projections reflect assumptions regarding raw material price stability and sustained demand for lightweighting solutions. Practitioners should keep alternative scenarios live as new composite material breakthroughs and energy costs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Global Metal Foams Market