
 Tantalum Carbide Market | 2026-2036
Tantalum Carbide Market Size, Share, and Industry Trends Forecast 2026-2036
Tantalum Carbide Market Insights
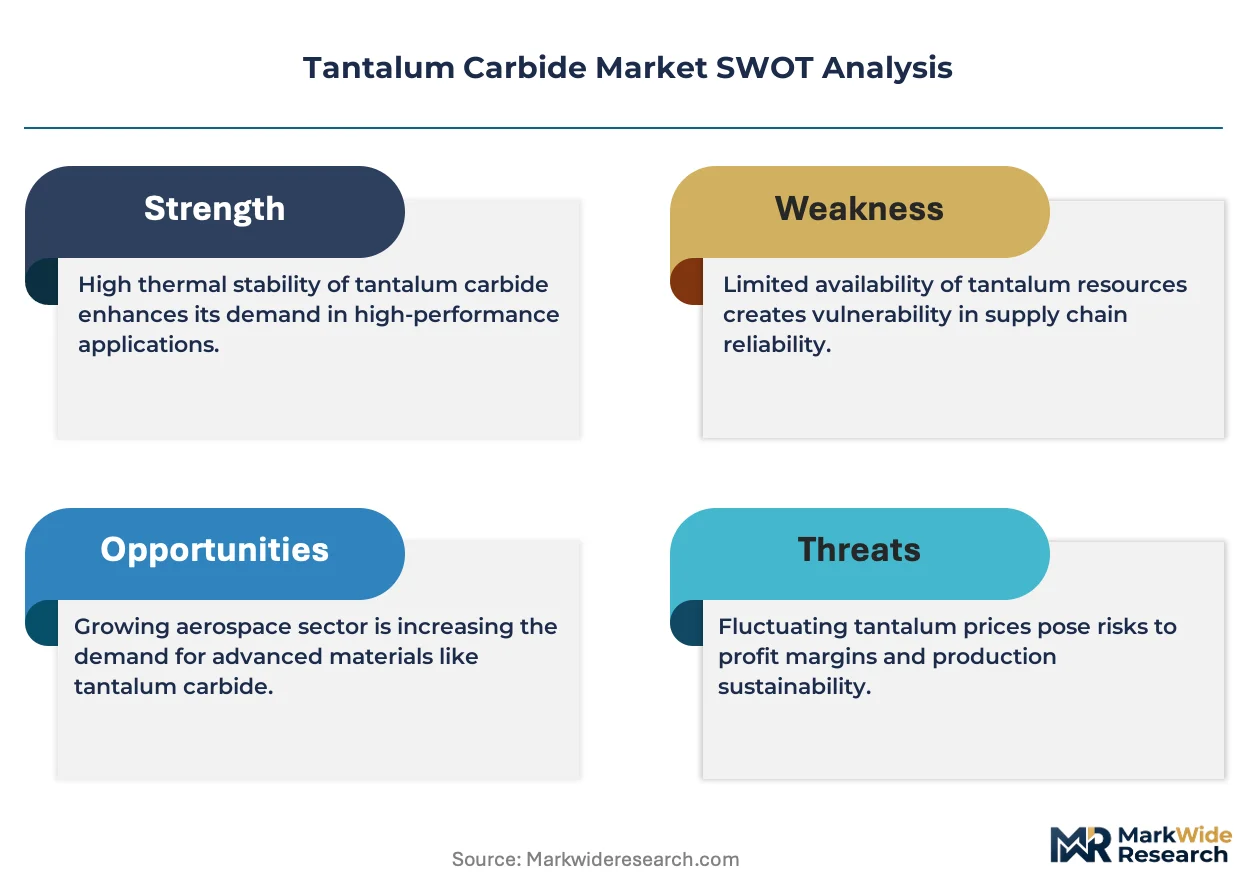
EU REACH substance restrictions on hexavalent chromium coatings is shifting procurement toward tantalum carbide alternatives in European aerospace supply chains. H.C. Starck Tungsten leverages captive tantalum sourcing to sustain powder purity leadership. Plansee SE anchors high-performance sintered component supply for aviation turbine applications. Kennametal differentiates through specialized cutting tool geometries that exploit tantalum carbide's extreme hardness.
Tantalum carbide is a refractory ceramic compound with a melting point near 3,880°C and Vickers hardness exceeding 1,500 HV, produced primarily through carbothermal reduction of tantalum pentoxide or direct synthesis from tantalum metal and carbon. Powder grades dominate volume throughput for cemented carbide additives and thermal spray feedstock, while sintered forms command premium positioning in wear-resistant aerospace bearings and seals. Coating applications represent the fastest-expanding segment as chemical vapor deposition processes advance for semiconductor chamber components.
EPA hazardous air pollutant standards and OSHA permissible exposure limits for refractory metal dusts shape workplace handling protocols and capital equipment requirements across U.S. production facilities. ECHA substance evaluation under REACH influences import certification burdens for non-European suppliers serving German and Austrian processing clusters. China's GB standards for industrial ceramics and MIIT rare material utilization quotas add compliance layers for producers with Asian supply chain exposure. Stakeholders must monitor evolving dual-use export controls affecting defense-related tantalum carbide allocations.
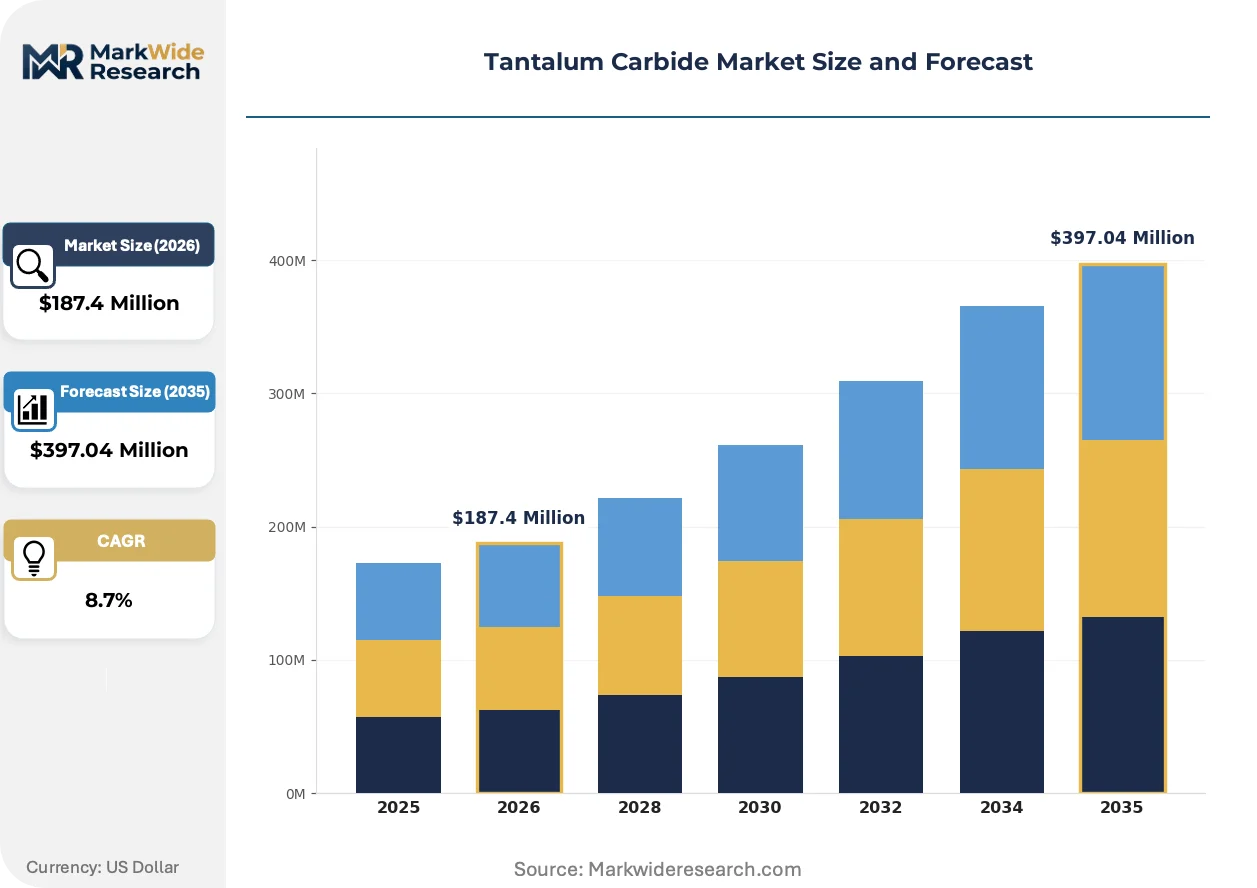
Market Dynamics
REACH substance restrictions on hexavalent chromium coatings are redirecting aerospace procurement toward tantalum carbide alternatives, while powder purity requirements tighten across European supply chains.
Growth Catalysts
- EPA hazardous air pollutant standards:Tighter emissions rules for refractory metal processing are accelerating investment in closed-loop tantalum carbide production systems across U.S. manufacturing clusters.
- Aerospace turbine blade coatings:Chemical vapor deposition processes for thermal barrier systems are expanding feedstock demand for ultra-high-purity tantalum carbide powder grades.
- German advanced ceramics clusters:Concentrated R&D infrastructure around Plansee SE and H.C. Starck Tungsten is anchoring specialized sintering capabilities for aviation bearing applications.
Market Restraints
- Tantalum ore supply concentration:Overreliance on Central African tantalite concentrates creates geopolitical exposure and conflict mineral tracing burdens for downstream processors.
- Carbothermal reduction energy intensity:Sintering temperatures exceeding 2,000°C require specialized furnace infrastructure that limits production scale economics for new entrants.
- Tungsten carbide substitution:Lower-cost cemented carbide alternatives retain cost advantage in non-critical cutting tool and wear part applications.
Strategic Opportunities
- Semiconductor chamber components:Plasma etching equipment manufacturers are qualifying tantalum carbide coatings for wafer processing hardware exposed to fluorinated chemistries.
- EU Green Deal industrial decarbonization incentives:Funding streams for energy-efficient refractory material production are supporting furnace technology upgrades in Austrian and German processing facilities.
- Direct sales to additive manufacturing feedstock suppliers:Spherical powder producers for electron beam melting are bypassing traditional distribution to secure long-term tantalum carbide offtake agreements.
Industry Challenges
- Refractory ceramics process engineering talent:Specialized expertise in high-temperature sintering atmosphere control is concentrated among retiring workforce cohorts in European production centers.
- Dual-use export control classification:Defense-related tantalum carbide allocations require license compliance that extends order fulfillment timelines for aerospace contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tantalum Carbide Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Coating, Sintered, Composite, Nanoparticles Application: Cutting Tools, Wear-Resistant Coatings, Aerospace Components, Electronics, Chemical Processing End User Industry: Metalworking, Semiconductor Manufacturing, Aviation, Petrochemical, Defense Form: Granules, Pellets, Films, Bulk Material, Powders |
| Companies Covered | H.C. Starck Tungsten, Plansee SE, Materion Corporation, Toyo Tanso Co., Ltd., Tokai Carbon Co., Ltd., Kennametal, Stanford Advanced Materials, Ningxia Orient Tantalum Industry, ABSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tantalum Carbide Market Trends and Innovations
Process intensification and regulatory chemistry shifts are compressing product development cycles while opening new application vectors beyond traditional cemented carbide additives.
Plasma spheroidization technology is integrating into tantalum carbide powder production workflows to produce flowable feedstock for additive manufacturing. Aerospace component suppliers are qualifying these spherical grades for directed energy deposition repair of turbine hardware. The structural consequence is that powder specification tiers are fragmenting, with additive-grade material commanding separate certification tracks from conventional thermal spray feedstock.
REACH authorization requirements for chromium trioxide in functional chrome plating are accelerating substitution timelines for hard chrome coatings on landing gear and hydraulic actuators. ECHA substance evaluation protocols are forcing aerospace Tier-1 suppliers to validate tantalum carbide alternative performance under salt spray and fatigue loading conditions. German and Austrian coating houses are responding by expanding chemical vapor deposition capacity dedicated to aviation qualification programs.
Long-term offtake contracting is displacing spot market purchasing for high-purity tantalum carbide powder. Aviation original equipment manufacturers are consolidating supplier bases to secure conflict-free certified material streams with full chain-of-custody documentation. This pattern is most pronounced in procurement offices serving Bundeswehr and NATO defense programs, where traceability mandates exceed commercial aerospace requirements.
Tantalum Carbide Market Segmentation
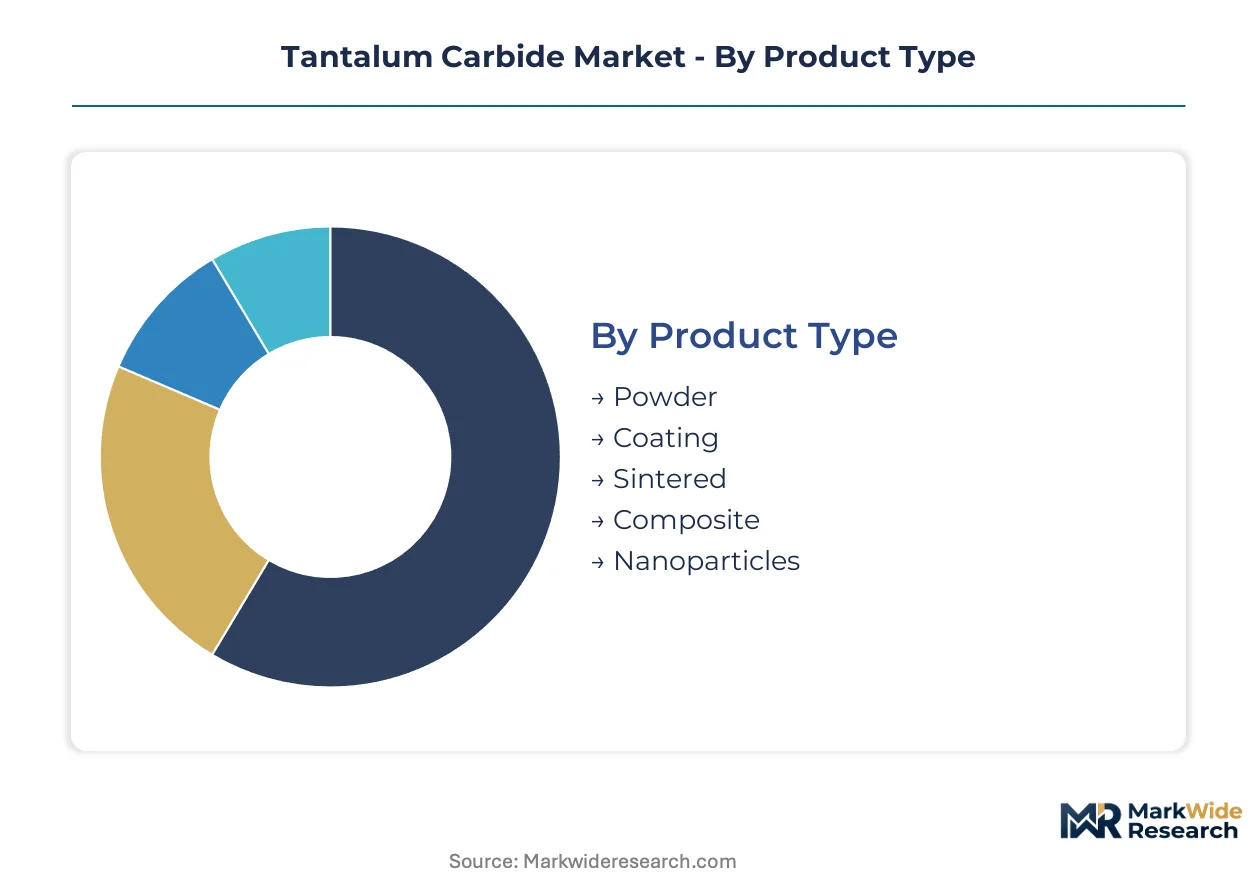
Tantalum carbide's extreme refractory properties create divergent value capture across physical forms and processing routes. Upgrade cycles in aerospace thermal protection and semiconductor etch chambers are fragmenting specification tiers faster than traditional carbide markets.
Product Type:
Replacement timelines for thermal barrier coatings in aviation turbines are compressing powder purity requirements while expanding chemical vapor deposition feedstock demand.
- Powder:Carbothermal reduction grades serve cemented carbide additives and thermal spray feedstock. Metalworking tool manufacturers in Germany and Austria consume volume placements for high-speed cutting insert production.
- Coating:Chemical vapor deposition and physical vapor deposition layers protect semiconductor chamber components from fluorinated plasma chemistries. Aviation original equipment manufacturers in the United States are qualifying these layers for turbine blade thermal protection under EPA hazardous air pollutant compliance timelines.
- Sintered:High-density bearings and seals for extreme-temperature aerospace applications.
- Composite:Reinforced matrices combining tantalum carbide with tungsten or carbon phases.
- Nanoparticles:Emerging feedstock for advanced ceramic matrix composites and precision additive manufacturing.
Volume placements concentrate in Powder; the faster expansion belongs to Coating.
Application:
Cost tiers separate commodity metalworking consumables from certified aerospace and semiconductor process hardware.
- Cutting Tools:Cemented carbide inserts exploit tantalum carbide's Vickers hardness exceeding 1,500 HV for machining hardened steels. Kennametal and comparable specialists command premium positioning through specialized geometries that outlast tungsten carbide alternatives in interrupted cuts.
- Wear-Resistant Coatings:Hard chrome substitution driven by REACH hexavalent chromium restrictions. German and Austrian coating houses are expanding chemical vapor deposition capacity dedicated to aviation qualification programs for landing gear and hydraulic actuator protection.
- Aerospace Components:Thermal barrier systems for turbine blades and combustion chambers.
- Electronics:Sputtering targets and diffusion barriers in semiconductor fabrication.
- Chemical Processing:Corrosion-resistant linings for reactor vessels handling aggressive media.
Metalworking applications dominate current volume; semiconductor process hardware is gaining share fastest.
End User Industry:
Customer type fragmentation separates spot-market metalworking purchasers from long-term offtake contractors in defense-linked aviation.
- Metalworking:Tooling manufacturers purchasing powder grades for cemented carbide production. Austrian and German clusters anchor demand through Plansee SE and H.C. Starck Tungsten captive processing capabilities.
- Semiconductor Manufacturing:Plasma etching equipment builders qualifying tantalum carbide chamber coatings. United States-based original equipment manufacturers are consolidating supplier bases to secure conflict-free certified material streams with full chain-of-custody documentation.
- Aviation:Turbine original equipment manufacturers and maintenance providers.
- Petrochemical:Process licensors specifying refractory linings for high-temperature reaction zones.
- Defense:Bundeswehr and NATO procurement offices imposing traceability mandates exceeding commercial aerospace requirements.
Procurement scale concentrates in Metalworking; the steepest expansion trajectory belongs to Semiconductor Manufacturing.
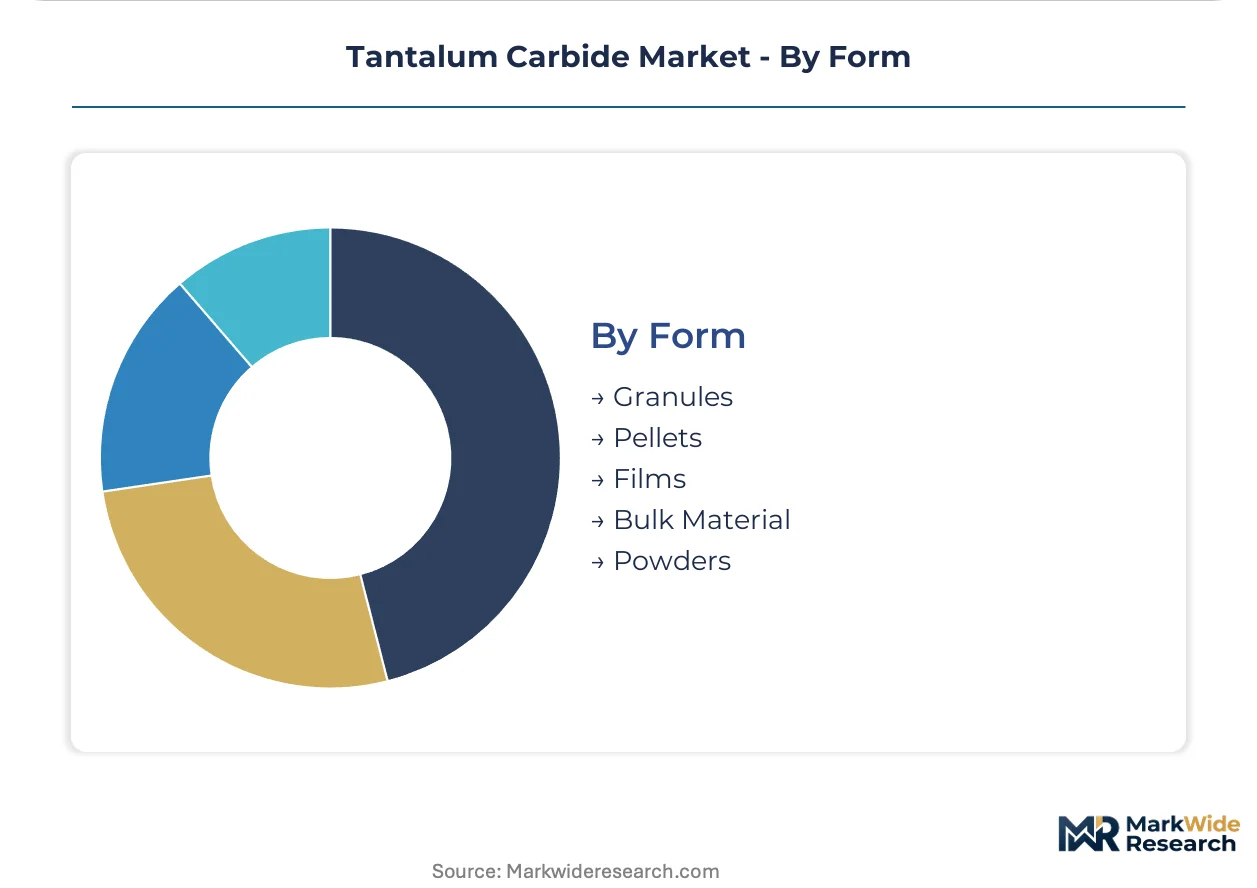
Form:
Supply concentration in spherical powder production for additive manufacturing is creating specification divergence from conventional thermal spray feedstock.
- Granules:Agglomerated feedstock for plasma spray deposition. Thermal spray contractors in German aerospace clusters consume volume for turbine component repair.
- Pellets:Pressed preforms for sintering operations.
- Films:Thin coatings produced through chemical vapor deposition for semiconductor wafer processing hardware.
- Bulk Material:Machined shapes for specialized research and development applications.
- Powders:Conventional angular grades for cemented carbide blending and traditional thermal spray.
Granules dominate current throughput; Films are climbing the fastest on semiconductor equipment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reutte anchors the world's densest concentration of tantalum carbide processing capability. Austrian and German industrial clusters along the Inn Valley corridor coordinate carbothermal reduction, sintering, and chemical vapor deposition operations for aviation and semiconductor end users.
Germany
Aviation turbine blade coating programs and semiconductor chamber hardware qualification drive procurement expansion. ECHA REACH substance restrictions on hexavalent chromium accelerate hard chrome substitution timelines. The Reutte-Landsberg corridor hosts Plansee SE and H.C. Starck Tungsten captive processing infrastructure.
United States
Plasma etching equipment manufacturers qualify tantalum carbide coatings for wafer processing hardware. EPA hazardous air pollutant standards tighten refractory metal dust exposure limits across production facilities. Pittsburgh and Cleveland metalworking clusters consume powder grades for cemented carbide cutting tool production.
Austria
EU Green Deal industrial decarbonization funding supports furnace technology upgrades in refractory ceramics production. ECHA substance evaluation protocols shape import certification requirements for non-European tantalum feedstock. The Tyrol region concentrates high-temperature sintering expertise for aviation bearing applications.
China
MIIT rare material utilization quotas and GB standards for industrial ceramics add compliance layers for producers with Asian supply chain exposure. Domestic semiconductor equipment builders expand chemical vapor deposition capacity. Ningxia processing clusters coordinate tantalite concentrate refining with downstream carbide production.
Japan
Carbon and graphite specialists advance physical vapor deposition coating technologies for semiconductor process hardware. METI industrial technology roadmaps prioritize refractory ceramic matrix composites for extreme-environment applications. Tokyo-Osaka industrial corridors integrate tantalum carbide feedstock into cutting tool and wear part supply chains.
Tantalum Carbide Market Competitive Landscape
The competitive structure tilts toward vertically integrated refractory metal specialists with captive tantalum sourcing. Austrian and German producers command premium positioning through powder purity leadership and aerospace qualification track records. Three archetypes dominate: integrated tantalum-to-carbide processors, specialized coating technology licensors, and regional powder distributors serving metalworking markets. Capacity expansion and long-term offtake contracting represent the dominant competitive moves as aviation OEMs consolidate supplier bases.
Among Austrian integrated processors, Plansee SE and H.C. Starck Tungsten occupy positions anchored by Reutte-based production infrastructure and captive supply chain control. Ningxia Orient Tantalum Industry exemplifies the Chinese state-linked processing archetype with vertical integration into Central African tantalite sourcing. These three entities represent distinct geographic and structural models for managing conflict mineral traceability, energy-intensive carbothermal reduction economics, and aerospace certification requirements.
| Leading Market Players |
|---|
| H.C. Starck Tungsten |
| Plansee SE |
| Materion Corporation |
| Toyo Tanso Co., Ltd. |
| Tokai Carbon Co., Ltd. |
| Kennametal |
| Stanford Advanced Materials |
| Ningxia Orient Tantalum Industry |
| ABSCO |
| Others |
Pricing and Supply Chain Analysis
Tantalum pentoxide spot quotations from the London Metal Exchange cascade through carbothermal reduction economics into three distinct pricing tiers for downstream powder grades. Aerospace certification requirements and conflict-free chain-of-custody documentation separate premium thermal spray feedstock from standard cemented carbide additives, with coating-grade material commanding substantial premia over metalworking consumables.
Pricing Analysis
Yield-based pricing anchors premium tiers, where semiconductor chamber component manufacturers pay for tantalum carbide coatings based on wafer throughput guarantees rather than unit material costs. Certification grade and volume scale differentiate tiers, with REACH-compliant powder from Austrian and German processors holding sustained premia over unverified Asian supply. Cost compression in standard-grade cemented carbide additives intensifies as tungsten carbide substitution pressures non-critical applications. Metalworking tool manufacturers exhibit highest price sensitivity, while semiconductor original equipment manufacturers prioritize purity and traceability over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from Bundeswehr and NATO procurement offices force aerospace contractors to qualify tantalum carbide suppliers across at least two geographic jurisdictions, fragmenting procurement concentration. Supply concentrates in Austria, Germany, and China, with Central African tantalite concentrates feeding carbothermal reduction operations. Raw material dependencies center on tantalum pentoxide, high-purity carbon sources, and specialized refractory furnace linings. Single-source vulnerability in tantalite concentrate supply creates geopolitical exposure for downstream processors. Distribution runs through long-term offtake contracts rather than spot markets, with aviation original equipment manufacturers consolidating supplier bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tantalum carbide supply operates under pronounced capacity constraints, with carbothermal reduction furnace infrastructure requiring capital-intensive upgrades that limit rapid scale-up. This bottleneck sustains pricing power for qualified producers.
For Market Incumbents: Extend captive tantalum sourcing advantages by securing additional conflict-free concentrate offtake from Central African traceability-certified operations. Invest in plasma spheroidization capacity to capture additive manufacturing feedstock demand before qualification windows close. Tungsten carbide substitution in non-critical cutting tools threatens volume placements in metalworking segments. For New Entrants and Emerging Players: Enter via semiconductor chamber coating qualification programs, where plasma etching equipment builders seek second-source tantalum carbide suppliers beyond established Austrian and German incumbents. Target spherical powder production for electron beam melting feedstock as the most penetrable entry vector. Pursue direct sales relationships with additive manufacturing feedstock specialists rather than conventional distribution channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor refractory ceramics specialists with existing high-temperature sintering expertise in Germany or Austria, where furnace infrastructure and workforce capabilities face generational transfer. Five-to-ten-year viability hinges on aerospace and semiconductor end-market durability. Monitor ECHA substance evaluation timelines for chromium trioxide as the critical inflection signal for hard chrome substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tantalite Concentrate Sourcing | Captive supply from conflict-free certified Central African operations secures powder purity leadership. |
| Plasma Spheroidization Capacity Addition | Spherical powder qualification for electron beam melting opens additive manufacturing revenue streams. |
| Chemical Vapor Deposition Coating Expansion | Semiconductor chamber hardware demand from Lam Research and Applied Materials drives capacity utilization. |
| EU Green Deal Furnace Technology Upgrade | Energy-efficient carbothermal reduction equipment qualifies for Austrian and German decarbonization incentives. |
| Long-term Offtake Contracting with Aviation OEMs | Consolidated supplier bases at Boeing and Airbus operations prioritize chain-of-custody documentation. |
Research Methodology
Multi-period observation of tantalum pentoxide price indices, REACH authorization timelines, and semiconductor capital expenditure patterns anchored the trend analysis, supplemented by interviews with refractory ceramics plant managers, aerospace procurement leads at Tier 1 suppliers, powder metallurgy R&D directors, and thermal spray contractors. Secondary validation drew from ECHA substance evaluation databases, SEC filings from listed industrial ceramics producers, EU customs trade statistics, and German engineering association technical reports. Bottom-up powder grade demand modeling and top-down aerospace and semiconductor end-market sizing provided triangulation checks.
Input-output matrices mapped carbothermal reduction capacity, furnace utilization rates, and downstream qualification status across product type and application segments over the projection horizon. Segmentation dimensions modeled included physical form, purity grade tier, end-use industry, and regional production hub clustering. CAGRs derived from slope-log regression of historical price-volume relationships and forward capacity buildout announcements. Industry-specific forecast inputs incorporated ECHA chromium trioxide sunset review timelines and plasma etching equipment shipment forecasts from semiconductor capital equipment analysts.
Revisions become necessary when Central African tantalite supply disruptions, REACH authorization delays for alternative coatings, or semiconductor capital expenditure cuts materialize. Deviation in EU Green Deal industrial decarbonization funding disbursement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Plastic-Metal Hybrids Market