
 Ultra High Strength Steel Market | 2026-2036
Ultra High Strength Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Strength Steel Market Intelligence
Aluminum-intensive designs in premium electric vehicle architectures is realigning product economics across the steel value chain. ArcelorMittal leverages integrated R&D corridors in Europe and North America to sustain leadership in third-generation advanced high-strength grades. SSAB AB anchors its competitive position through fossil-free hydrogen-based production pathways. Nippon Steel Corporation dominates patent activity around multi-phase microstructure control for crash-critical automotive components.
Ultra high strength steel encompasses alloyed and thermomechanically processed flat and long products with tensile strength exceeding 780 MPa, engineered primarily for structural weight reduction without sacrificing occupant safety or load-bearing integrity. The automotive application segment commands the dominant share of volume as OEMs pursue 25-40% mass reduction targets in body-in-white assemblies. Quenched and tempered product types capture premium margin pools where defense and aerospace procurement specifications demand validated through-thickness toughness. Grade standardization around EN 10149 and ASTM A992 creates regional moats for mills with accredited testing infrastructure.
The EPA tailpipe emissions framework and NHTSA corporate average fuel economy standards in the United States directly mandate material lightweighting that expands UHSS penetration in passenger vehicle platforms. EMA's oversight of medical device sterilization equipment and REACH chemical compliance requirements in Europe shape alloy composition restrictions and surface treatment specifications for steel suppliers. China's MIIT steel capacity replacement rules and GB standards for vehicle structural integrity create dual compliance obligations for multinational mills. Stakeholders must monitor hydrogen direct reduction cost curves and scrap-based electric arc furnace yield improvements to calibrate capacity commitments against evolving carbon border adjustment mechanisms.
Market Dynamics
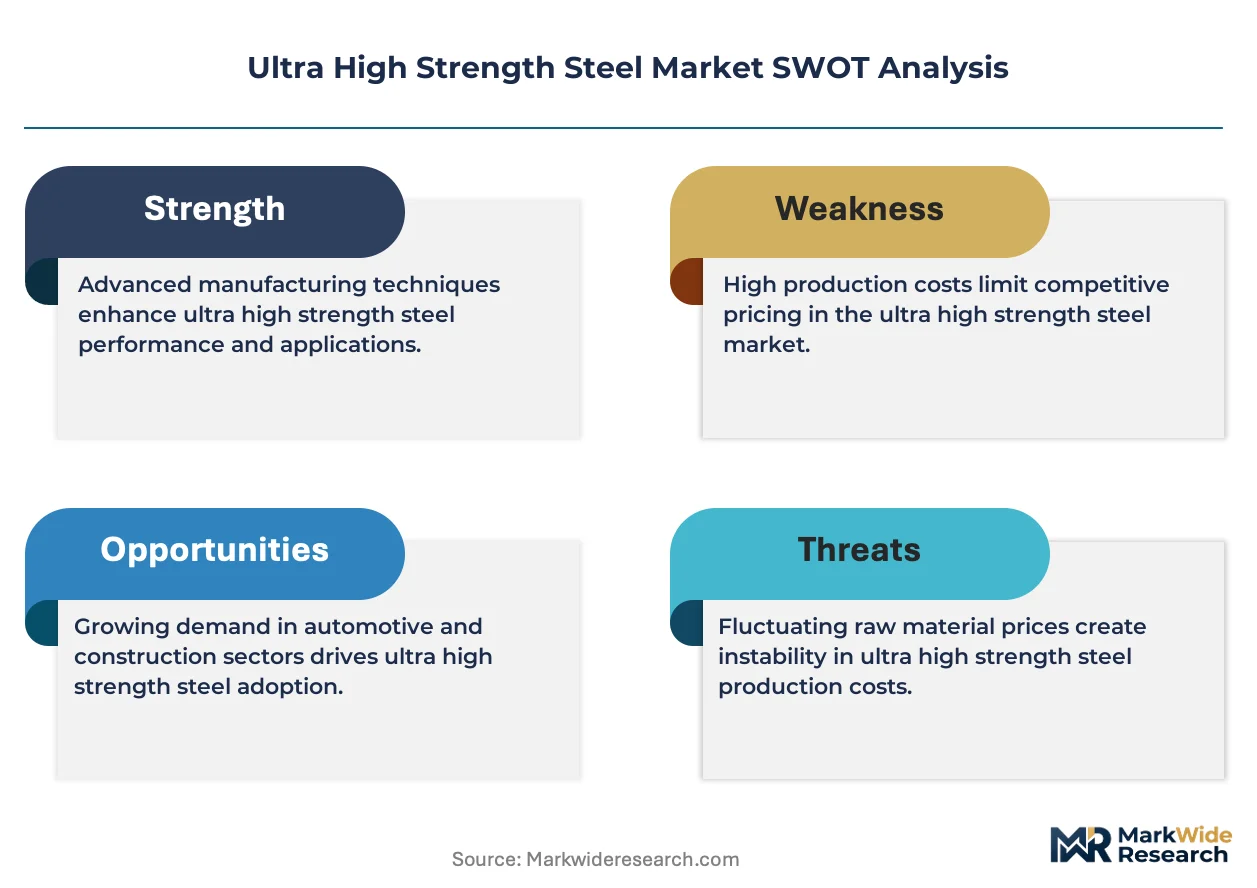
Automotive OEM procurement strategies are pivoting toward material substitution programs as Euro 7 and China's dual carbon goals harden compliance timelines, forcing tier suppliers to recalibrate mill relationships and alloy specifications simultaneously.
Growth Catalysts
- Emissions Compliance Mandates:Euro 7 standards and China's MIIT steel capacity replacement rules compel vehicle manufacturers to lightweight body-in-white assemblies through advanced high-strength grades, expanding mill order books for thermomechanically processed flat products.
- Crash Safety Architecture:Multi-phase microstructure control for occupant protection cells drives specification upgrades across C-segment and D-segment vehicle platforms, particularly in Germany and South Korea where assembly hub density concentrates demand.
- Hydrogen-Based Production:Fossil-free direct reduction pathways under development in Nordic integrated corridors are unlocking premium pricing pools for carbon-accounted steel procurement by sustainability-mandated automotive OEMs.
Market Restraints
- Aluminum Substitution Pressure:Premium electric vehicle architectures in the luxury segment are displacing UHSS in battery enclosure and closure panel applications where specific strength-per-kilogram ratios favor wrought aluminum alloys.
- Scrap Availability Constraints:Electric arc furnace operators face yield degradation when processing contaminated ferrous feedstock, limiting production scalability for quenched and tempered grades requiring precise through-thickness chemistry control.
- REACH Alloy Restrictions:ECHA oversight of nickel and chromium surface treatment specifications constrains coating formulation flexibility for European automotive supply contracts, extending qualification timelines.
Strategic Opportunities
- Defense Procurement Expansion:Validated through-thickness toughness specifications for armor and structural applications in NATO-aligned countries are opening premium margin pools outside automotive cyclicality.
- India Automotive Localization:PLI scheme incentives for domestic vehicle manufacturing are attracting mill capacity commitments near Pune and Chennai industrial corridors, creating first-mover positioning for accredited suppliers.
- Third-Generation Grade Development:Convergence of computational thermodynamics with inline process control is enabling tailored property gradients previously achievable only through post-forming heat treatment.
Industry Challenges
- Metallurgical Talent Scarcity:Deep expertise in phase transformation kinetics and thermomechanical processing simulation is concentrating among retiring cohorts at legacy integrated mills, constraining R&D pipeline velocity.
- Multi-Site Certification Burden:Simultaneous accreditation to EN 10149, ASTM A992, and GB standards for multinational OEM supply contracts demands redundant testing infrastructure and extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Strength Steel Market |
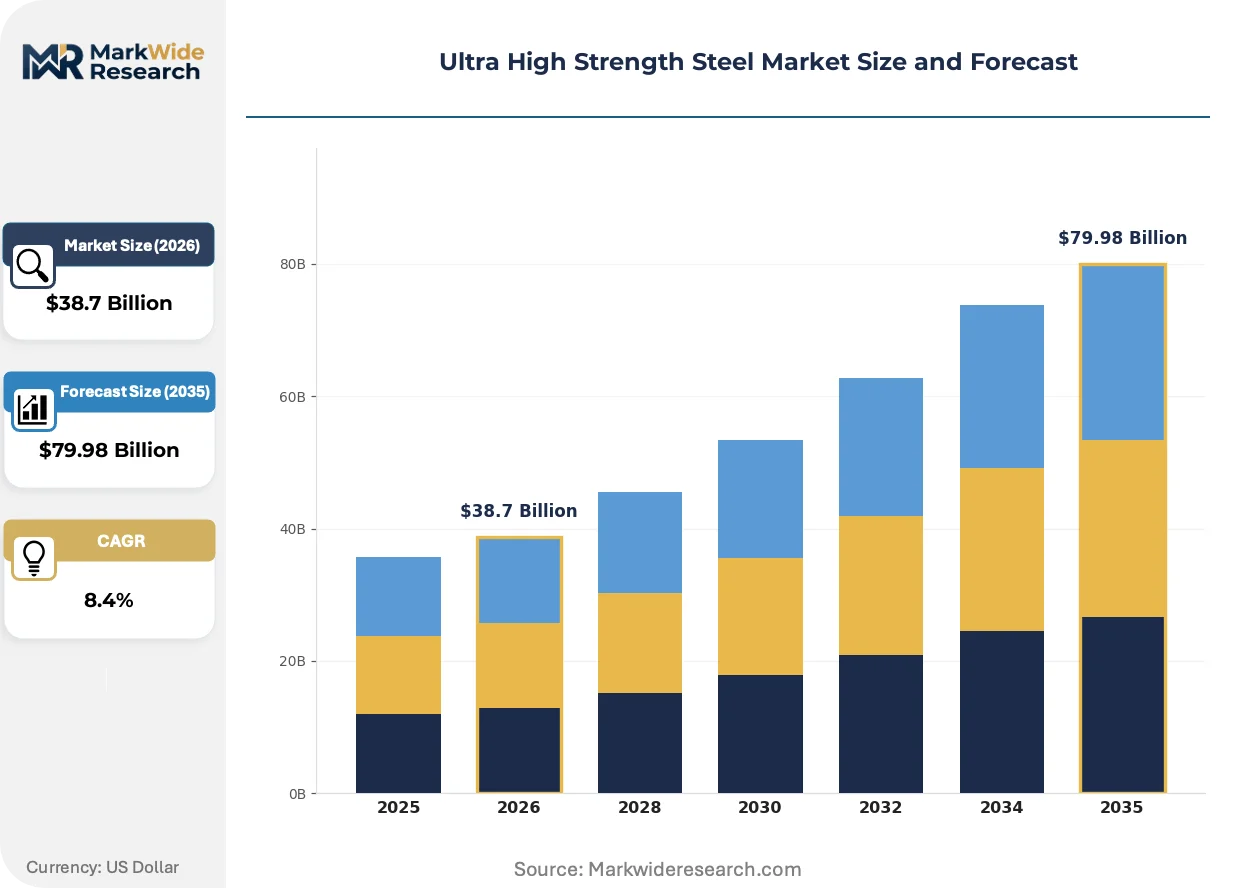
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
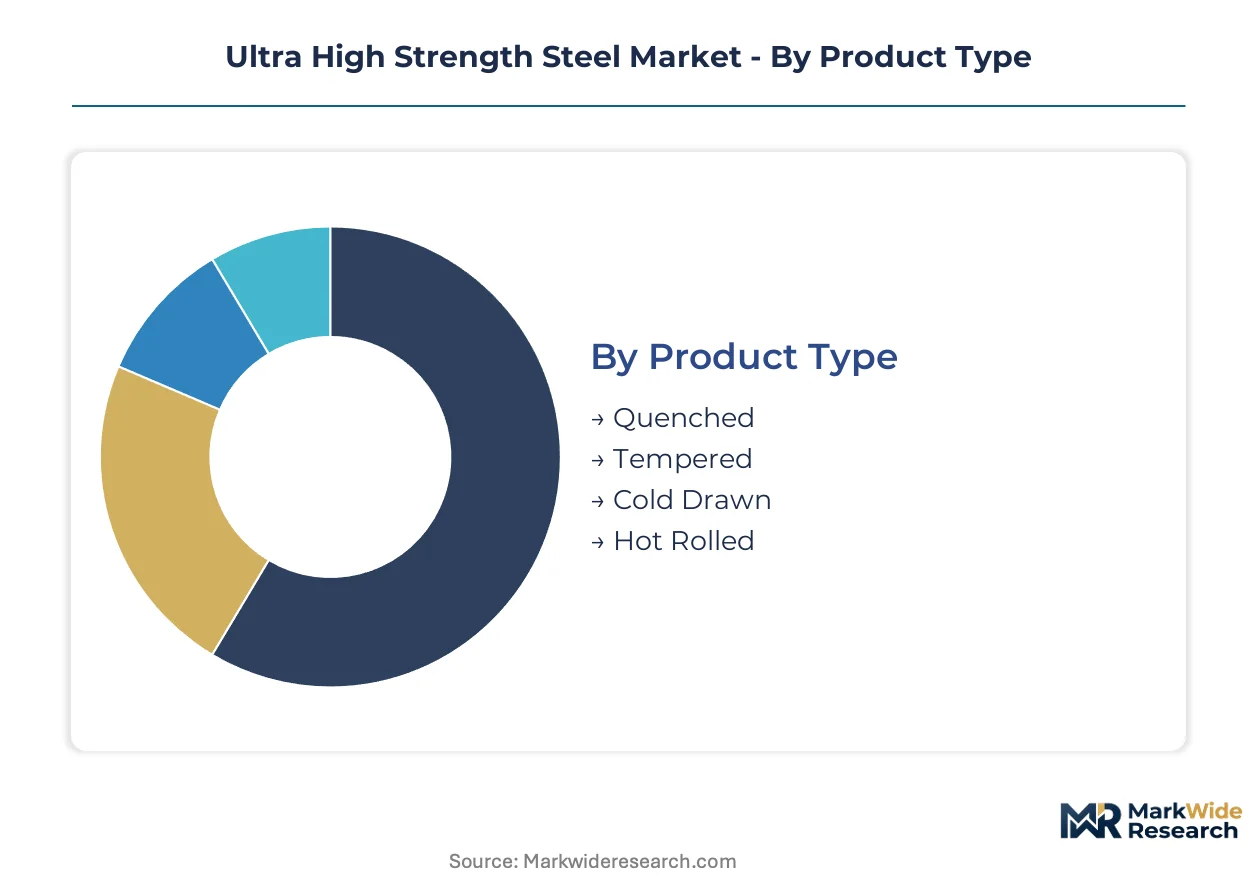
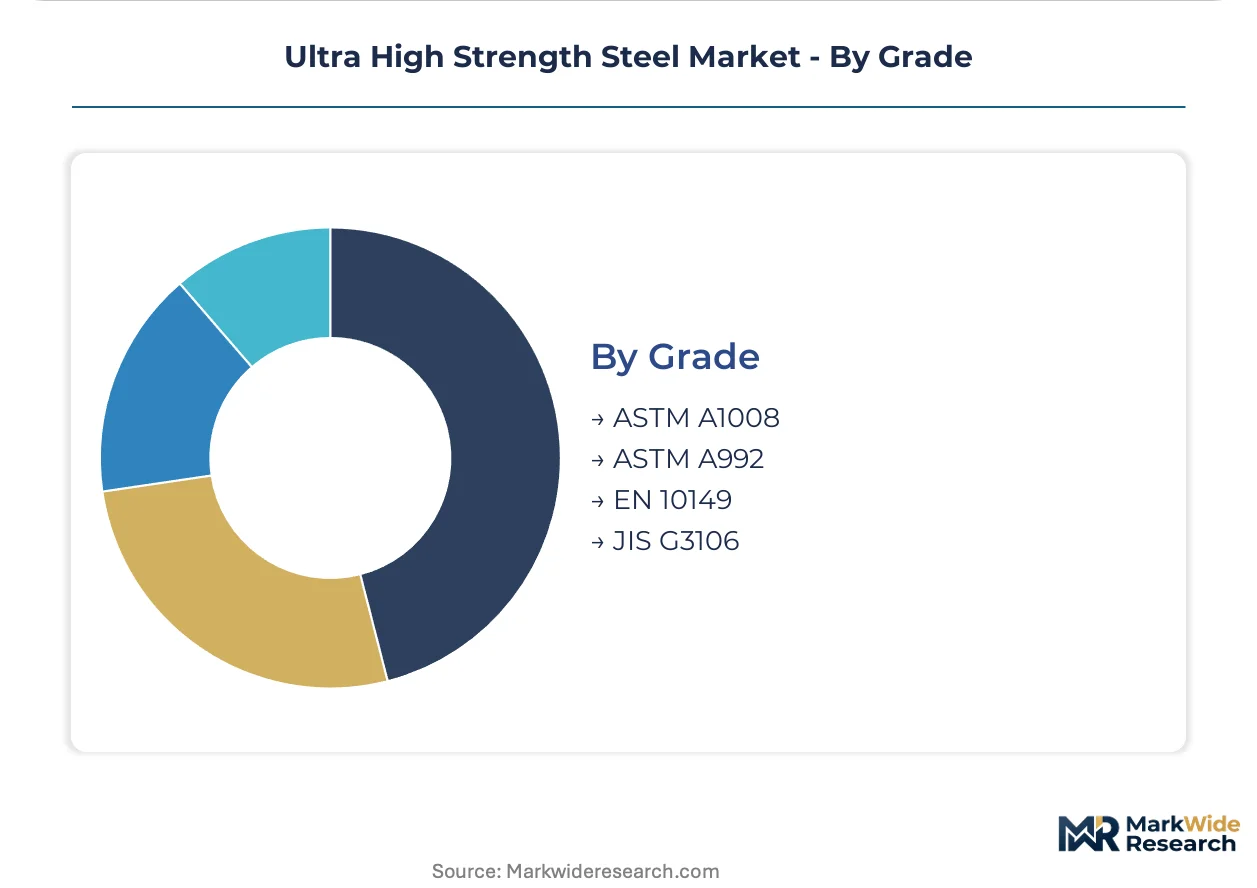
| Segmentation | Product Type: Quenched, Tempered, Cold Drawn, Hot Rolled Application: Aerospace, Construction, Automotive, Defense End User: Manufacturers, Builders, Engineers, Fabricators Grade: ASTM A1008, ASTM A992, EN 10149, JIS G3106 |
| Companies Covered | Tata Steel, United States Steel Corporation, ArcelorMittal, Baosteel Group Corporation, SSAB AB, Nippon Steel Corporation, Thyssenkrupp AG, JFE Steel Corporation, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Strength Steel Market Strategic Shifts & Innovations
Process intensification and digital thread integration are compressing development cycles for next-generation grades, while regulatory chemistry constraints and buyer sustainability accounting reshape specification priorities across the value chain.
Third-generation advanced high-strength steels with retained austenite microstructures deliver exceptional formability-strength combinations for complex press-hardened components. Automotive OEMs in Germany and Japan are qualifying these grades for A-pillar and roof rail applications at accelerated timelines. This metallurgical category is expanding into safety-critical zones previously reserved for hot-stamped boron steel, enabling further gauge reduction without sacrificing crash energy absorption.
REACH chemical compliance requirements and the EU Green Deal carbon border adjustment mechanism are tightening traceability obligations for alloy element sourcing and coating chemistry. Mills must now document scope 3 emissions and restricted substance content across multi-tier supply chains to maintain European automotive qualification. Asian exporters to EU assembly hubs are investing in hydrogen direct reduction pilot lines to preserve market access under evolving carbon intensity thresholds.
Automotive OEMs are consolidating supplier panels and demanding mill-direct relationships for strategic grades, bypassing traditional steel service center intermediaries. This disintermediation concentrates volume commitments with integrated producers capable of technical service co-development and just-in-sequence delivery. The restructuring is most visible in South Korea and China, where Hyundai, Kia, and domestic EV manufacturers are negotiating multi-year offtake agreements with tier-one mill technical teams.
Ultra High Strength Steel Market Segmentation
Ultra high strength steel procurement decisions pivot on validated mechanical specifications, regulatory compliance burdens, and carbon accounting requirements that vary sharply across end-use contexts. Buyers in automotive and defense channels impose distinct qualification protocols that fragment supplier relationships and pricing structures.
Product Type:
Automotive OEMs select grades based on press-hardening compatibility and crash energy absorption targets that dictate thermomechanical processing routes.
- Quenched:Rapid cooling from austenitizing temperatures produces martensitic microstructures with tensile strength exceeding 1500 MPa for armor plating and structural columns. Defense procurement in Germany and South Korea concentrates demand where validated through-thickness toughness specifications command premium pricing pools.
- Tempered:Controlled reheating after quenching optimizes ductility-toughness balances for heavy machinery booms and mining equipment frames. Construction OEMs in China specify tempered grades for infrastructure projects under GB standards compliance obligations.
- Cold Drawn:Room-temperature deformation through dies delivers precise dimensional tolerances for fasteners and precision shafts requiring surface finish control.
- Hot Rolled:Thermomechanical processing above recrystallization temperatures enables gauge reduction in body-in-white assemblies where formability-strength tradeoffs dominate.
Volume sits with Hot Rolled for automotive lightweighting programs; growth tilts toward Quenched for defense procurement expansion outside automotive cyclicality.
Application:
End-use certification requirements create divergent margin structures, with aerospace and defense channels demanding redundant testing infrastructure that smaller mills cannot support.
- Automotive:Body-in-white assemblies consume thermomechanically processed flat products as Euro 7 and EPA tailpipe mandates harden mass reduction targets. Hyundai and Kia in South Korea negotiate multi-year offtake agreements with integrated producers capable of just-in-sequence delivery.
- Defense:Armor and structural applications require validated through-thickness toughness under NATO procurement specifications. Mills serving this channel maintain redundant EN 10149 and ASTM A992 accreditation that extends qualification cycles.
- Aerospace:Landing gear and structural components demand precise chemistry control and ultrasonic testing protocols that limit supplier pools.
- Construction:High-rise structural frames and bridge components specify ASTM A992 grades where yield strength consistency reduces fabrication complexity.
Revenue concentrates in Automotive; steepest expansion trajectory belongs to Defense as NATO-aligned countries diversify material sourcing.
End User:
Procurement authority is consolidating toward direct mill relationships as OEMs bypass steel service centers for strategic grades.
- Manufacturers:Tier-one automotive suppliers and industrial equipment producers dominate volume procurement, negotiating technical service co-development clauses in supply agreements.
- Engineers:Design consultancies specify grade selection early in product development cycles, creating specification lock-in effects that constrain downstream substitution.
- Fabricators:Job shops processing cut-to-length and formed components face margin compression from rising alloy surcharges and energy costs.
- Builders:Construction contractors purchase through distributors with limited technical service support, prioritizing availability over grade optimization.
Specification authority rests with Engineers; order volume aggregates with Manufacturers consolidating supplier panels.
Grade:
Regional standardization creates accreditation moats that protect incumbent mills from cross-border competition.
- EN 10149:European thermomechanically rolled high-yield steels for cold forming dominate automotive supply contracts under ECHA REACH compliance requirements. ArcelorMittal leverages integrated R&D corridors to sustain leadership in grades serving German assembly hubs.
- ASTM A992:North American structural steel specification for wide-flange shapes commands construction procurement where seismic design requirements favor controlled yield ratios. Nippon Steel Corporation anchors supply relationships through multi-site certification infrastructure.
- ASTM A1008:Cold-rolled carbon steel specifications for exposed automotive panels require surface quality controls that concentrate production at integrated flat-rolled mills.
- JIS G3106:Japanese rolled steels for welded structures serve domestic construction and shipbuilding channels with chemistry restrictions that complicate scrap-based electric arc furnace production.
Procurement pools fragment by geography; EN 10149 claims the broadest multinational adoption as EU carbon border adjustments reshape sourcing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in Germany, China, and South Korea where integrated mills cluster near vehicle assembly hubs. These three markets anchor thermomechanically processed flat product demand as emissions compliance hardens material substitution timelines.
China
MIIT steel capacity replacement rules and GB standards for vehicle structural integrity create dual compliance obligations for multinational mills. Domestic EV manufacturers negotiate multi-year offtake agreements with Baosteel Group Corporation near Shanghai assembly corridors. Yangtze River Delta industrial clusters concentrate hydrogen direct reduction pilot investments to preserve EU market access under carbon border adjustments.
Germany
Euro 7 tailpipe mandates and ECHA REACH alloy restrictions force specification upgrades across C-segment and D-segment platforms. ArcelorMittal leverages integrated R&D corridors to sustain leadership in third-generation advanced high-strength grades. Bavarian and North Rhine-Westphalia automotive hubs concentrate demand for EN 10149-accredited thermomechanically rolled products.
South Korea
Hyundai and Kia procurement strategies bypass steel service centers for strategic grades requiring just-in-sequence delivery. KBA oversight of vehicle type approval shapes crash safety architecture specifications for multi-phase microstructure control. Busan-Ulsan industrial corridors anchor POSCO capacity commitments serving domestic OEM lightweighting programs.
United States
EPA tailpipe emissions frameworks and NHTSA corporate average fuel economy standards directly mandate material lightweighting in passenger vehicle platforms. United States Steel Corporation maintains ASTM A992 accreditation for construction procurement where seismic design requirements favor controlled yield ratios. Midwest automotive assembly clusters concentrate demand for quenched and tempered defense-grade specifications.
India
PLI scheme incentives for domestic vehicle manufacturing attract mill capacity commitments near Pune and Chennai industrial corridors. BIS grade standardization creates regional moats for mills with accredited testing infrastructure. Tata Steel anchors supply relationships through multi-site certification covering both automotive body-in-white and construction structural applications.
Ultra High Strength Steel Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding automotive procurement and regional mills serving construction channels. The vendor base concentrates around three strategic archetypes: global integrated steelmakers with R&D corridors, Nordic fossil-free production specialists, and Asia-Pacific scale producers with government-backed capacity expansion. Dominant competitive moves include hydrogen direct reduction pilot investments and multi-site certification infrastructure to compress qualification cycles.
Among global integrated producers, ArcelorMittal and Nippon Steel Corporation exemplify the R&D-intensive archetype anchored in European and Japanese automotive supply relationships. SSAB AB occupies a distinct position within the fossil-free production tier, representing Nordic hydrogen-based pathway development. Tata Steel and POSCO sit within the Asia-Pacific scale-driven segment, anchoring government-supported capacity localization strategies in India and South Korea respectively.
| Leading Market Players |
|---|
| Tata Steel |
| United States Steel Corporation |
| ArcelorMittal |
| Baosteel Group Corporation |
| SSAB AB |
| Nippon Steel Corporation |
| Thyssenkrupp AG |
| JFE Steel Corporation |
| POSCO |
| Others |
Cost & Logistics Intelligence
Automotive OEM direct procurement teams in Germany, China, and South Korea negotiate multi-year offtake agreements that compress margin pools for intermediate steel service centers. Contract-based long-term pricing with alloy surcharge pass-through mechanisms dominates strategic grade transactions, while spot-market volatility governs commodity construction specifications.
Pricing Analysis
High-volume hot-rolled automotive grades trade on thin margins anchored to raw material indices, while quenched defense specifications and third-generation advanced high-strength grades capture premium pricing through validated through-thickness toughness certification. Price differentiation rests on EN 10149 accreditation status and hydrogen direct reduction carbon accounting credentials. Cost compression in standard automotive grades is intensifying because scrap availability constraints and energy input volatility squeeze electric arc furnace operators. Tier-two fabricators and construction contractors exhibit the highest price sensitivity, whereas defense procurement programs and premium EV manufacturers prioritize performance certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle strategic grade demand from Hyundai, Kia, and domestic Chinese EV manufacturers, bypassing traditional steel service center intermediaries. Geographic supply concentrates in China, Germany, and South Korea where integrated mills cluster near vehicle assembly hubs. Production draws from iron ore pellet, metallurgical coal, and hydrogen feedstock inputs, with fossil-free direct reduction pathways gaining traction in Nordic corridors. Single-source vulnerability around specialized quench-and-temper capacity serving NATO defense specifications creates supply chain risk. Distribution runs through mill-direct technical service partnerships for automotive, while construction channels rely on regional distributor networks with limited alloy optimization support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation of supplier panels is forcing out regional mills lacking multi-site certification infrastructure, creating acquisition opportunities for integrated producers with accredited testing capabilities.
For Market Incumbents: Anticipate aluminum substitution pressure in premium battery enclosure applications by deepening R&D investment in third-generation grades with retained austenite microstructures. Secure backward integration into hydrogen direct reduction feedstock to defend margin position against carbon border adjustment compliance costs. Prioritize EN 10149, ASTM A992, and GB standards accreditation across multiple production sites to compress qualification cycles for multinational OEM contracts. For New Entrants and Emerging Players: Capture defense procurement expansion in NATO-aligned countries where validated through-thickness toughness specifications create premium margin pools outside automotive cyclicality. Target India's PLI scheme corridor near Pune and Chennai where domestic vehicle manufacturing localization attracts first-mover mill capacity commitments. Lead with technical service co-development capabilities rather than commodity volume positioning. For Investors and Strategic Acquirers: The window for entry favors integrated producers with fossil-free hydrogen-based production pathways and established automotive qualification relationships. Mid-scale electric arc furnace operators face stranded asset risk from carbon intensity thresholds and scrap quality constraints. Watch hydrogen direct reduction cost curves as the inflection indicator for sustainable steel premium capture viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Direct Reduction Investment | SSAB AB and Nordic integrated corridors unlock fossil-free production pathways for carbon-accounted automotive procurement. |
| Multi-Site Certification Infrastructure | Redundant EN 10149, ASTM A992, and GB accreditation compresses qualification cycles for multinational OEM supply contracts. |
| Third-Generation Grade Development | Computational thermodynamics convergence enables tailored property gradients for crash-critical A-pillar and roof rail applications. |
| Defense Procurement Qualification | Validated through-thickness toughness specifications open premium margin pools outside automotive demand cyclicality. |
| Mill-Direct Technical Service Partnership | Hyundai and Kia procurement strategies bypass steel service centers for just-in-sequence delivery requirements. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with Tier 1 automotive supplier procurement leads, OEM platform engineers, integrated mill technical directors, and steel service center operations managers. Secondary sources encompassed EPA tailpipe emission filings, ECHA REACH substance registrations, MIIT capacity replacement disclosures, vehicle production databases, and SEC 10-K filings from listed steel producers. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Segmentation-level granularity modeled product type, application, end user, and grade standard across the analysis window, with regional production cluster and propulsion architecture as additional dimensions. CAGRs derived from trend extrapolation of historical procurement patterns calibrated against OEM lightweighting program announcements and emissions compliance timeline acceleration. Forecast inputs incorporated hydrogen direct reduction pilot line commissioning schedules and carbon border adjustment mechanism implementation phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum substitution rates in premium EV architectures and scrap availability constraints for electric arc furnace yield optimization. Forecasts reflect documented assumptions regarding Euro 7 implementation timing and China's dual carbon goal enforcement stringency. Periodic stress-testing of base assumptions against hydrogen production cost curves and REACH alloy restriction expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Forgings Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Powder Metallurgy Components Market