
 Global Braze Alloys Market | 2026-2036
Global Braze Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Braze Alloys Market Foresight
Asset-light leasing models for vacuum furnace infrastructure is rewriting competitive entry barriers for mid-scale alloy suppliers. Johnson Matthey leverages captive precious metal refining to sustain margin control across silver-based product lines. Lucas-Milhaupt, Inc. anchors North American distribution through direct technical service networks. Umicore competes in Europe via closed-loop recycling integration for copper and nickel formulations.
Braze alloys are non-ferrous filler metals with liquidus temperatures above 450°C but below the base metal melting point, typically engineered as strips, pastes, or preforms with precise thermal expansion coefficients for metallurgical bonding. Their primary purpose is creating hermetic, high-strength joints in dissimilar metal assemblies where conventional welding risks distortion or phase degradation. Silver-based alloys command premium positioning in aerospace and electronics due to superior flow characteristics and joint ductility, while copper-based formulations dominate HVAC and plumbing applications where cost efficiency outweighs precious metal performance. Nickel-based segments are gaining structural share in power generation equipment as operating temperatures climb in combined-cycle turbines.
EPA air quality standards and OSHA workplace exposure limits govern alloy manufacturing emissions and worker protection protocols in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance content in finished brazing products. China's SAMR enforces GB standards for alloy composition labeling and traceability, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and alloy scrap recovery economics to calibrate regional production footprints against tightening environmental accountability.
Market Dynamics
REACH compliance in Europe and China's dual carbon goals are tightening material purity benchmarks, forcing alloy suppliers to reconfigure refining footprints and absorb certification costs that reshape margin structures across silver and nickel product lines.
Growth Catalysts
- Aerospace OEM expansion:Turbine blade assembly programs are consuming engineered nickel-based formulations as operating temperatures climb in next-generation engines, pulling volume from traditional copper alternatives.
- EU Green Deal carbon border adjustments:Importers face mounting documentation requirements for embedded emissions in copper and silver alloys, advantaging European producers with verified low-carbon supply chains.
- Closed-loop recycling economics:Precious metal recovery from spent brazing assemblies is migrating from cost center to profit driver, particularly for high-silver content electronics waste streams.
Market Restraints
- Silver price volatility:Precious metal input swings compress margins on aerospace-grade alloys where long-term supply agreements lock in formulation specifications.
- Chinese supply concentration:Base metal refining capacity clusters around specific industrial zones, creating single-point vulnerability for copper-phosphorus and brass filler metal sourcing.
- Substitution by mechanical fastening:Advanced laser welding and diffusion bonding are capturing joint applications in automotive heat exchangers where brazing previously dominated.
Strategic Opportunities
- India precision engineering corridor:Automotive component manufacturing around Pune and Chennai is generating demand for cadmium-free silver alloys compliant with EU export requirements.
- Hydrogen infrastructure buildout:Electrolyzer stack assembly requires hermetic nickel-chromium joints capable of sustaining thermal cycling in high-pressure alkaline environments.
- Digital alloy specification platforms:Technical buyers are migrating toward direct-to-manufacturer procurement portals that bypass traditional distributor markups on standard formulations.
Industry Challenges
- Vacuum furnace technician scarcity:Controlled atmosphere brazing operations require specialized metallurgists whose training pipelines have atrophied across German and Japanese industrial centers.
- REACH pre-registration timelines:Novel alloy compositions face extended safety data sheet validation periods that delay commercial launch by multiple regulatory cycles.
- Legacy ERP integration:Batch traceability requirements for aerospace certification conflict with older manufacturing execution systems still prevalent at mid-scale European foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Braze Alloys Market |
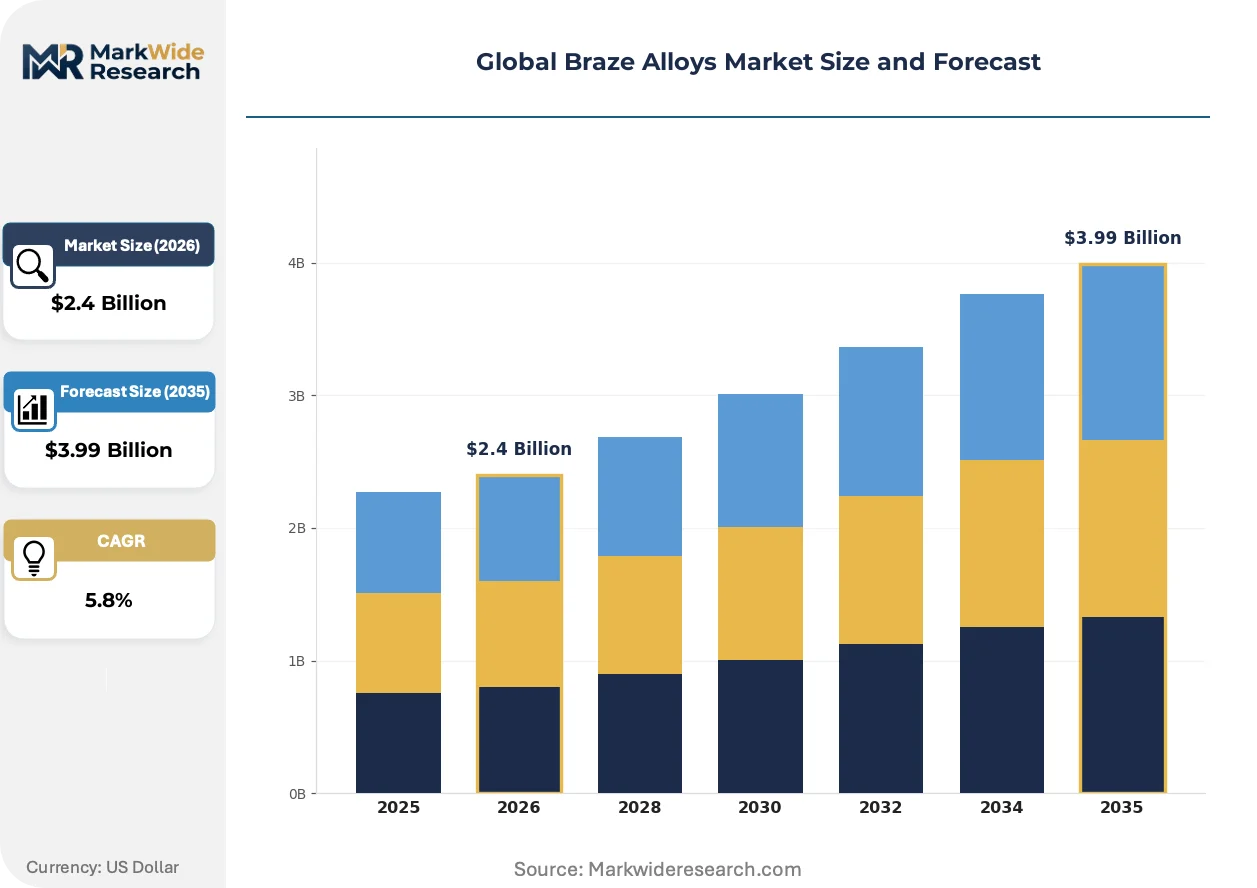
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Based, Copper-Based, Nickel-Based, Aluminum-Based, Gold-Based Technology: Vacuum Brazing, Furnace Brazing, Induction Brazing, Torch Brazing, Dip Brazing Application: HVAC Systems, Aerospace Components, Electronics Assembly, Power Generation Equipment, Plumbing Fixtures End User: Manufacturing Plants, Aerospace OEMs, Electronics Assemblers, Energy Producers, Metal Fabricators |
| Companies Covered | Lucas-Milhaupt, Inc., Johnson Matthey, Umicore, Morgan Advanced Materials, Harris Products Group, Prince & Izant Company, Wall Colmonoy Corporation, Fusion, Inc., Oerlikon Metco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Braze Alloys Market Shifts & Advancements
Active metal brazing formulations and predictive thermal modeling software are compressing joint design cycles while regulatory pressure on cadmium and lead content accelerates formulation turnover across established product portfolios.
Active metal brazing is migrating from laboratory-scale ceramic-to-metal sealing into volume production of power module substrates for electric vehicle inverters. Automotive Tier-1 suppliers in Japan and South Korea are qualifying titanium-modified filler systems that wet aluminum nitride without pre-metallization. This migration is compressing equipment qualification timelines from eighteen months to under six for qualified vacuum brazing houses.
REACH Annex XVII restrictions on cadmium content are forcing reformulation of low-melting silver-copper-zinc-cadmium alloys historically dominant in HVAC torch brazing. European distributors are clearing inventory of non-compliant grades ahead of enforcement deadlines while pushing tin-modified alternatives with higher liquidus temperatures. German precision engineering clusters around Stuttgart report the steepest compliance-driven product turnover, with cadmium-free alternatives now commanding formulation premiums.
Technical buyers are unbundling alloy supply from application engineering services that historically justified distributor margins. Large aerospace contractors in the United States are establishing direct metallurgical partnerships with primary alloy producers, internalizing joint design expertise that previously resided at Lucas-Milhaupt and regional technical service teams. This unbundling is most visible in California and Washington state, where Boeing and SpaceX procurement organizations have built captive brazing engineering capabilities.
Global Braze Alloys Market Segmentation
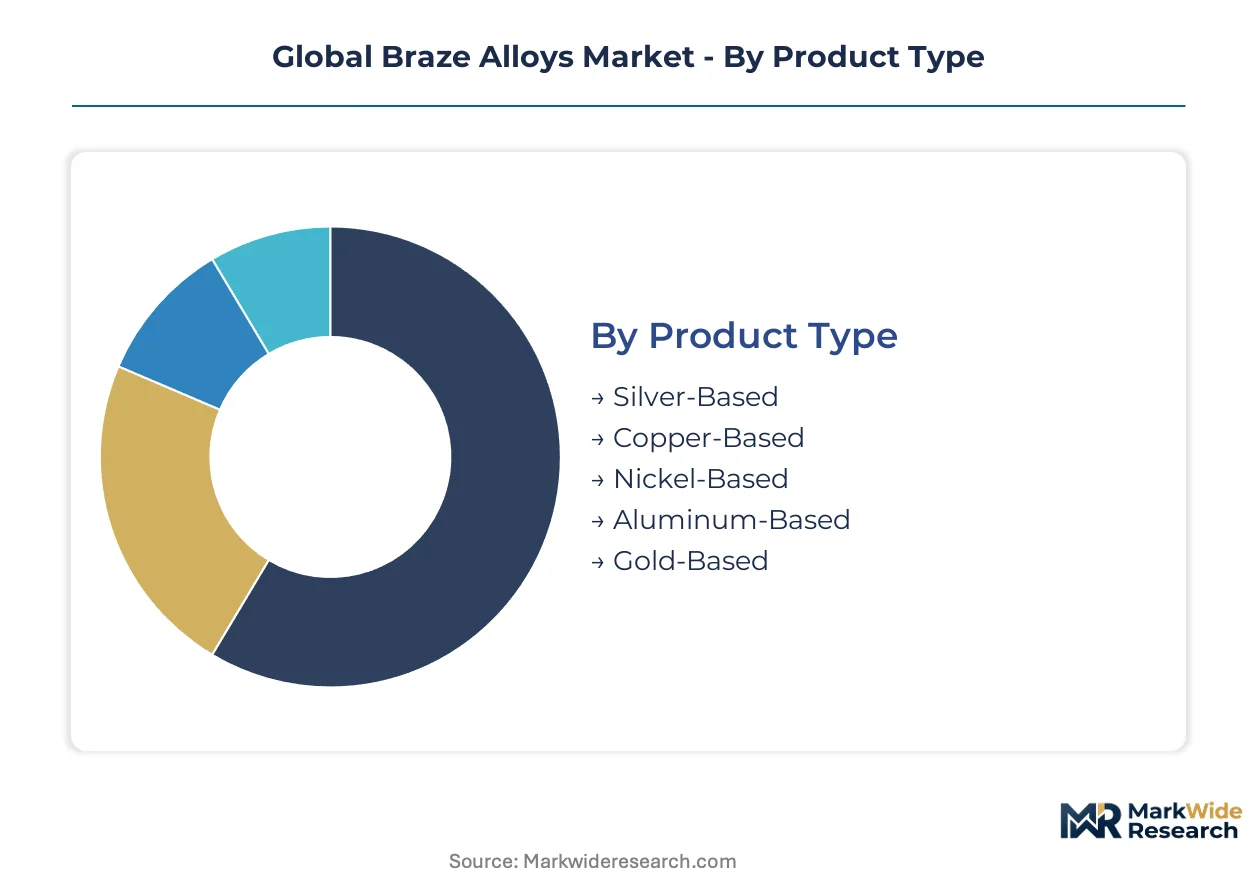
Braze alloy suppliers engineer distinct product portfolios around thermal performance thresholds and joint integrity requirements. Segmentation discipline separates commodity copper formulations from precision silver and nickel systems where technical service intensity determines contract renewal rates.
Product Type:
After-sales metallurgical support separates premium alloy tiers from commodity filler metals, with aerospace and electronics buyers demanding joint failure analysis and thermal cycle modeling as standard contract inclusions.
- Silver-Based:Alloys typically contain 15-70% silver with copper, zinc, and tin modifiers, engineered for narrow melting ranges and exceptional flow characteristics. Demand concentrates in aerospace blade assemblies and hermetic electronics sealing where joint ductility under thermal cycling is non-negotiable. Long-term supply agreements lock formulation specifications, exposing margins to London Bullion Market Association price swings.
- Nickel-Based:Chromium and boron-modified formulations withstand sustained operating temperatures above 900°C in gas turbine hot sections. Siemens Energy and GE Vernova procurement teams are qualifying nickel-chromium-silicon-boron systems for combined-cycle power generation equipment as firing temperatures climb.
- Copper-Based:Phosphorus and tin-modified brass fillers dominate HVAC heat exchanger manufacturing where cost efficiency outweighs precious metal performance.
- Aluminum-Based:Silicon-modified systems service automotive radiator assemblies and air conditioning components with sub-600°C liquidus requirements.
- Gold-Based:High-purity formulations serve semiconductor packaging and medical device hermeticity where oxidation resistance justifies extreme material costs.
By volume, Copper-Based leads. By growth pace, Nickel-Based is ahead.
Technology:
Equipment capital intensity stratifies the supplier base, with vacuum furnace infrastructure requiring 5-10 million dollar investments that filter out mid-scale competitors.
- Vacuum Brazing:Controlled atmosphere processing eliminates oxide formation on reactive metals like titanium and aluminum nitride ceramics. Stuttgart precision engineering clusters report technician scarcity is compressing qualified brazing house capacity despite automotive inverter substrate demand acceleration.
- Furnace Brazing:Continuous belt and batch atmosphere systems service high-volume HVAC and automotive component manufacturing with protective hydrogen-nitrogen atmospheres.
- Induction Brazing:Localized electromagnetic heating enables rapid joint cycling for plumbing fixture assembly and repair operations.
- Torch Brazing:Manual oxyfuel systems persist in field repair and artisan metalwork where equipment portability outweighs atmosphere control.
- Dip Brazing:Molten salt bath immersion achieves uniform heating for complex aluminum heat exchanger geometries in automotive radiator manufacturing.
Vacuum Brazing commands the highest service margins. Torch Brazing retains the largest installed base.
Application:
Regulatory jurisdiction fragmentation shapes alloy specification requirements, with EU REACH cadmium restrictions and EPA air quality standards forcing divergent formulation portfolios.
- Aerospace Components:Turbine blade assembly programs consume engineered nickel-based formulations certified to AMS specifications. Boeing and Safran procurement organizations have internalized joint design expertise, disintermediating traditional distributor technical service relationships.
- Power Generation Equipment:Combined-cycle turbine hot section repair drives demand for creep-resistant nickel-chromium filler systems as operating temperatures climb.
- HVAC Systems:Heat exchanger manufacturing consumes copper-phosphorus and brass filler metals where torch brazing dominates cost-sensitive residential and commercial installations.
- Electronics Assembly:Power module substrates and hermetic packaging require active metal brazing for ceramic-to-metal transitions in electric vehicle inverters.
- Plumbing Fixtures:Potable water contact applications mandate lead-free copper-silver-phosphorus formulations under Safe Drinking Water Act and NSF/ANSI 61 protocols.
HVAC Systems anchor volume consumption. Aerospace Components exhibit the steepest expansion trajectory.
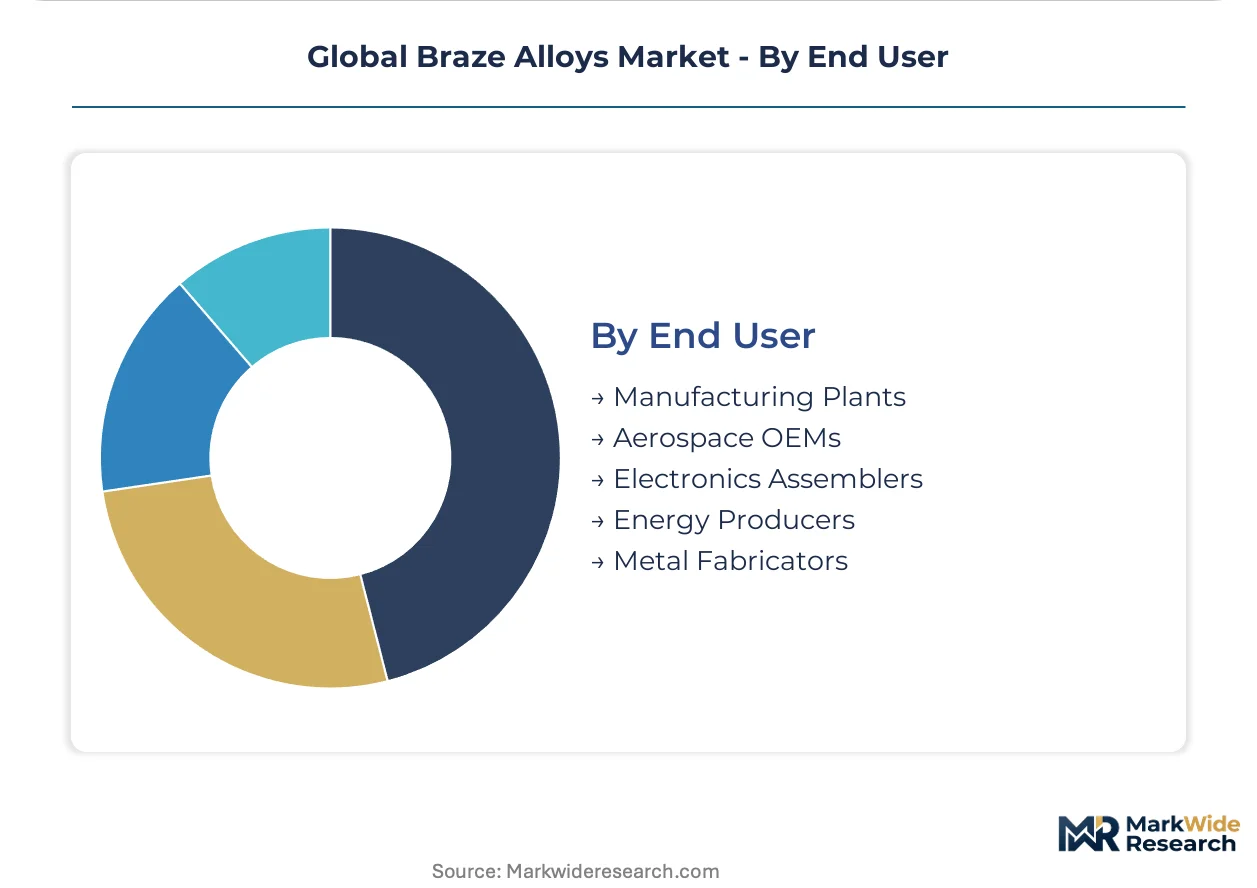
End User:
Procurement sophistication varies dramatically, with aerospace OEMs demanding batch traceability and metallurgical partnership while metal fabricators prioritize spot pricing and delivery velocity.
- Aerospace OEMs:Pratt & Whitney and Rolls-Royce procurement organizations enforce AMS-certified supply chains with mandatory vacuum brazing house audits and destructive joint testing protocols.
- Electronics Assemblers:Tier-1 automotive suppliers in Japan and South Korea are qualifying titanium-modified active metal brazing for silicon carbide power module substrates.
- Energy Producers:Siemens Energy and Mitsubishi Power maintenance organizations specify nickel-based repair alloys for turbine blade restoration with field service metallurgical support.
- Manufacturing Plants:General industrial brazing operations span automotive, appliance, and machinery production with standardized filler metal specifications.
- Metal Fabricators:Job shop operators serving construction and architectural metalwork prioritize distributor availability over technical service intensity.
Manufacturing Plants represent the broadest addressable base. Aerospace OEMs generate the highest lifetime value per account.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in braze alloys tilt toward net consumption in advanced manufacturing economies while China and Germany maintain surplus positions in refined copper and silver formulations. Trade documentation requirements under emerging carbon border mechanisms are redrawing traditional supply corridors.
United States
Aerospace OEMs in Washington and California are internalizing metallurgical partnerships for turbine blade assemblies, bypassing traditional distributor networks. EPA air quality standards and OSHA workplace exposure limits govern vacuum furnace emissions and technician safety protocols. The Pacific Northwest corridor around Seattle hosts concentrated demand from Boeing procurement organizations.
Germany
Precision engineering clusters around Stuttgart and Solingen are driving cadmium-free silver alloy reformulation ahead of REACH Annex XVII enforcement deadlines. ECHA registration timelines for novel compositions extend commercial launch cycles. Baden-Württemberg's automotive supplier ecosystem is qualifying active metal brazing for electric vehicle inverter substrates.
China
Dual carbon goals under MEE oversight are tightening smelter emissions benchmarks for copper-phosphorus refining capacity concentrated in eastern industrial zones. SAMR enforces GB standards for alloy composition labeling and batch traceability. Yangtze River Delta manufacturing bases are expanding nickel-based output for domestic power generation equipment.
Japan
Automotive Tier-1 suppliers are accelerating titanium-modified filler system qualification for silicon carbide power modules. METI industrial standards govern active metal brazing process certification. Chubu region vacuum brazing houses report compressed equipment qualification timelines for qualified suppliers.
India
Automotive component manufacturing around Pune and Chennai is generating demand for cadmium-free silver alloys compliant with EU export requirements. BIS certification mandates for imported filler metals create compliance friction for non-domestic suppliers. Maharashtra's precision engineering corridor is absorbing technical service investment from multinational alloy producers.
Global Braze Alloys Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material refining and formulation science. The supplier base stratifies between precious metal refiners with captive vertical integration and regional distributors dependent on technical service relationships. Three archetypes dominate: integrated precious metal houses, regional technical service networks, and specialized vacuum brazing contractors. Consolidation pressure is mounting through direct procurement partnerships between aerospace OEMs and primary producers, while alloy specification platforms are disintermediating traditional distributor markups.
Among UK-based precious metal refiners, Johnson Matthey occupies a position exemplifying captive supply chain control. Lucas-Milhaupt, Inc. represents the North American technical service network archetype with direct distribution infrastructure. Umicore anchors European closed-loop recycling integration for base metal formulations. These three entities illustrate divergent strategic postures around margin protection, geographic anchoring, and circular material economics.
| Leading Market Players |
|---|
| Lucas-Milhaupt, Inc. |
| Johnson Matthey |
| Umicore |
| Morgan Advanced Materials |
| Harris Products Group |
| Prince & Izant Company |
| Wall Colmonoy Corporation |
| Fusion, Inc. |
| Oerlikon Metco |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors absorb volatile bunker fuel surcharges that cascade through silver-alloy landed costs, amplifying price spreads between European vacuum brazing houses and Asian phosphorus-copper refiners while rewarding producers with backward-integrated precious metal recovery.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across aerospace-certified, industrial-grade, and commodity filler metal tiers. Price differentiation hinges on AMS certification level and after-sales metallurgical support intensity. Cost compression in copper-based formulations is intensifying because Chinese phosphorus refining capacity expansion outpaces German precision engineering demand growth. HVAC distributors exhibit highest price sensitivity; aerospace procurement teams at Boeing and Safran prioritize joint reliability over unit economics.
Supply Chain Analysis
Export-control restrictions on vacuum furnace technology limit equipment transfers to Russian and Iranian industrial zones, constraining qualified brazing house expansion in sanctioned markets. Supply concentrates in China for copper-phosphorus refining, Germany for precision silver formulations, and Japan for active metal brazing systems. Raw material flows draw from Chilean copper concentrate, South African chromium, and recycled electronics waste streams for silver recovery. Single-source vulnerability clusters around Yangtze River Delta smelter consolidation. Distribution runs through technical service networks for aerospace accounts and distributor inventories for metal fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics favor alloy suppliers bundling predictive thermal modeling software and joint failure analysis subscriptions, as recurring metallurgical support contracts expand faster than commodity filler metal volumes across the analysis window.
For Market Incumbents: Pre-empt disintermediation by aerospace OEMs through captive vacuum brazing house partnerships in Washington and California, while accelerating cadmium-free formulation portfolios ahead of REACH Annex XVII enforcement. Vertical integration into precious metal recycling secures margin control against London Bullion Market Association price swings. For New Entrants and Emerging Players: Build out asset-light leasing models for vacuum furnace infrastructure targeting mid-scale Indian precision engineering shops around Pune and Chennai, where EU-export-compliant cadmium-free silver alloy demand outstrips qualified local supply. Direct procurement portals bypass legacy distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates with neglected brazing alloy divisions lacking closed-loop recycling integration. Long-term viability rests on circular material economics and carbon-verified supply chains. Watch for carbon border adjustment mechanism implementation timelines as inflection signals for European production footprint revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Integration | Umicore's precious metal recovery economics now outperform virgin material sourcing for high-silver electronics waste streams. |
| Active Metal Brazing Qualification | Automotive Tier-1 suppliers in Japan and South Korea compress equipment qualification timelines for silicon carbide power modules. |
| Direct Procurement Platform Launch | Boeing and SpaceX procurement organizations internalize joint design expertise previously residing at Lucas-Milhaupt technical service teams. |
| Cadmium-Free Formulation Migration | German precision engineering clusters around Stuttgart absorb steepest compliance-driven product turnover premiums ahead of REACH deadlines. |
| Vacuum Furnace Infrastructure Leasing | Asset-light models rewrite competitive entry barriers for mid-scale alloy suppliers serving India's automotive component manufacturing corridor. |
Research Methodology
A standing panel of vacuum brazing house metallurgists, aerospace OEM procurement directors, and precious metal refining operations managers provided ongoing calibration across the study period. Primary interview data triangulated against secondary sources including ECHA REACH registration databases, SAMR GB standard filings, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up alloy volume estimates from end-use applications reconciled with top-down trade flow analysis.
Scenario-bracketing framed demand projections across the analysis window, modeling product type segments including silver-based, nickel-based, copper-based, aluminum-based, and gold-based formulations alongside technology tiers from vacuum to torch brazing. Application dimensions spanned aerospace components, power generation equipment, HVAC systems, electronics assembly, and plumbing fixtures. CAGR derivation incorporated operating temperature escalation curves in combined-cycle turbines and electric vehicle inverter substrate qualification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese copper refiners or accelerated carbon border adjustment enforcement would shift outcomes. Material shifts in REACH Annex XVII substance restrictions or MEE dual carbon goal implementation stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Aluminum Composite Panel Market