
 High Speed Steels Market | 2026-2036
High Speed Steels Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Steels Market Analysis
Capital-intensity divergence between integrated powder-metallurgy producers and conventional melt-route suppliers is rotating competitive advantage toward firms with captive atomization capacity. Sandvik AB leverages its in-house powder production to command premium positioning in M42 grades. voestalpine High Performance Metals GmbH anchors Central European supply through backward integration into specialty scrap recycling. Erasteel sustains French leadership in cobalt-bearing formulations via proprietary triple-melt refining.
High speed steels are alloyed tool steels containing tungsten, molybdenum, chromium, and vanadium, engineered to retain hardness above 600°C during high-velocity cutting operations. Manufacturers produce these grades through electric arc melting followed by electroslag remelting or powder metallurgy to achieve carbide uniformity critical for tool life. M2 dominates volume throughput across general-purpose cutting tools, while M42 commands margin pools in aerospace broaching applications where red-hardness requirements are most severe. Coated forms capture expanding share as physical vapor deposition extends tool life in automated metalworking cells. Metalworking end users drive baseline demand, though aerospace specifications for M50 bearing steels represent the fastest-growing specification tier.
REACH compliance through ECHA governs cobalt and chromium disclosure in European supply chains, elevating documentation costs for non-integrated importers. China's SAMR enforces GB standard conformity assessment on imported tool steel bars, creating technical barriers for uncertified foreign mills. ISO 4957 provides the harmonized chemical baseline that cross-border purchasers reference in procurement contracts. Stakeholders must monitor evolving alloy substitution research as tungsten price volatility forces reformulation trade-offs between performance and material cost exposure.
Market Dynamics
Powder metallurgy routes are compressing lead times for aerospace-grade M42 and M50 specifications, forcing conventional melt-route suppliers to absorb stranded asset risk or accelerate capital redeployment into atomization capacity.
Growth Catalysts
- Aerospace turbine blade machining:Cobalt-grade HSS variants command specification lock-in from Rolls-Royce and Pratt & Whitney supply chains, insulating producers from commodity substitution.
- REACH compliance documentation:ECHA-mandated cobalt and chromium disclosure creates competitive moats for integrated European mills with captive laboratory certification.
- Germany's precision tooling cluster:Concentrated demand around Solingen and Stuttgart sustains premium pricing for ESR-refined bars with guaranteed carbide uniformity.
Market Restraints
- Tungsten price volatility:Concentrated supply from Chinese mines forces reformulation trade-offs between M2 and M35 grades, compressing margin predictability.
- GB standard conformity assessment:SAMR-enforced certification barriers block uncertified European and Japanese mills from direct import channels.
- Cemented carbide substitution:Solid carbide end mills displace HSS in general-purpose machining below 40 HRC workpiece hardness.
Strategic Opportunities
- India's tooling import dependency:Domestic HSS production capacity lags behind automotive and defense machining demand, creating local partnership entry points.
- Physical vapor deposition coating convergence:TiAlN and AlCrN coatings on HSS substrates extend tool life in unmanned metalworking cells, opening automated factory retrofit markets.
- EU Green Deal scrap circularity incentives:Backward integration into specialty scrap recycling earns carbon intensity credits and secures cobalt supply.
Industry Challenges
- Triple-melt operator skill scarcity:ESR and VAR furnace technicians with aerospace certification command wage premiums that inflate fixed costs.
- ISO 4957 harmonization delays:Divergent national annexes to the chemical baseline standard complicate cross-border contract enforcement.
- Legacy ERP integration:Batch-level traceability requirements for REACH documentation clash with decades-old melt shop software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Steels Market |
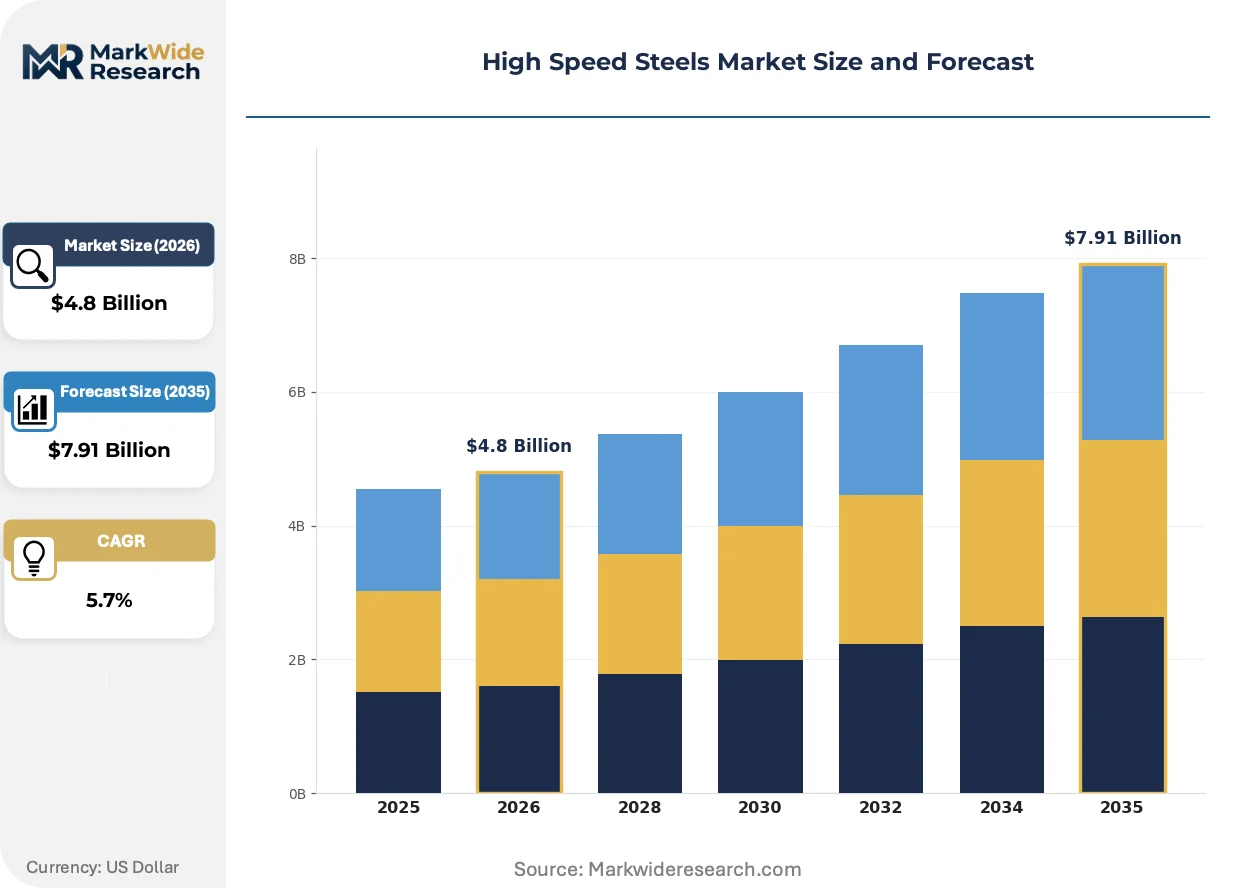
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: M2, M35, M42, M50 Application: Cutting Tools, Drills, Inserts, Broaches End User: Aerospace, Automotive, Manufacturing, Metalworking Form: Bars, Sheets, Blanks, Coated |
| Companies Covered | Sandvik AB, Kennametal, voestalpine High Performance Metals GmbH, NACHI-FUJIKOSHI CORP., Daido Steel, ArcelorMittal, Hitachi Metals, Carpenter Technology Corporation, Erasteel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Steels Market Emerging Trajectories
Additive manufacturing of near-net-shape HSS preforms is compressing forging yield losses and enabling complex internal cooling channel geometries previously unattainable through conventional deformation processing.
Powder metallurgy HSS is miniaturizing carbide size distributions below 2 microns, enabling cutting edges that retain hardness beyond 650°C. Aerospace broaching houses in France and Sweden are adopting these grades for Inconel turbine disk slotting. The technology is miniaturizing the performance gap between solid carbide and HSS in interrupted cutting applications.
China's GB/T 9943-2023 tool steel certification protocol tightens inclusion rating requirements and mandates third-party laboratory verification for imported bars. The regulation forces non-integrated foreign mills to establish local testing partnerships or cede specification-critical segments. European exporters with existing Shanghai technical offices are absorbing compliance costs faster than mid-tier Japanese competitors.
After-sales service unbundling is displacing traditional tool life guarantee contracts in German automotive supplier parks. Machine shops now purchase HSS inserts separately from coating reapplication and regrinding services, fragmenting supplier relationships. Tier-1 component manufacturers in Bavaria and Baden-Württemberg are driving this decoupling to optimize total cost of ownership metrics.
High Speed Steels Market Segmentation
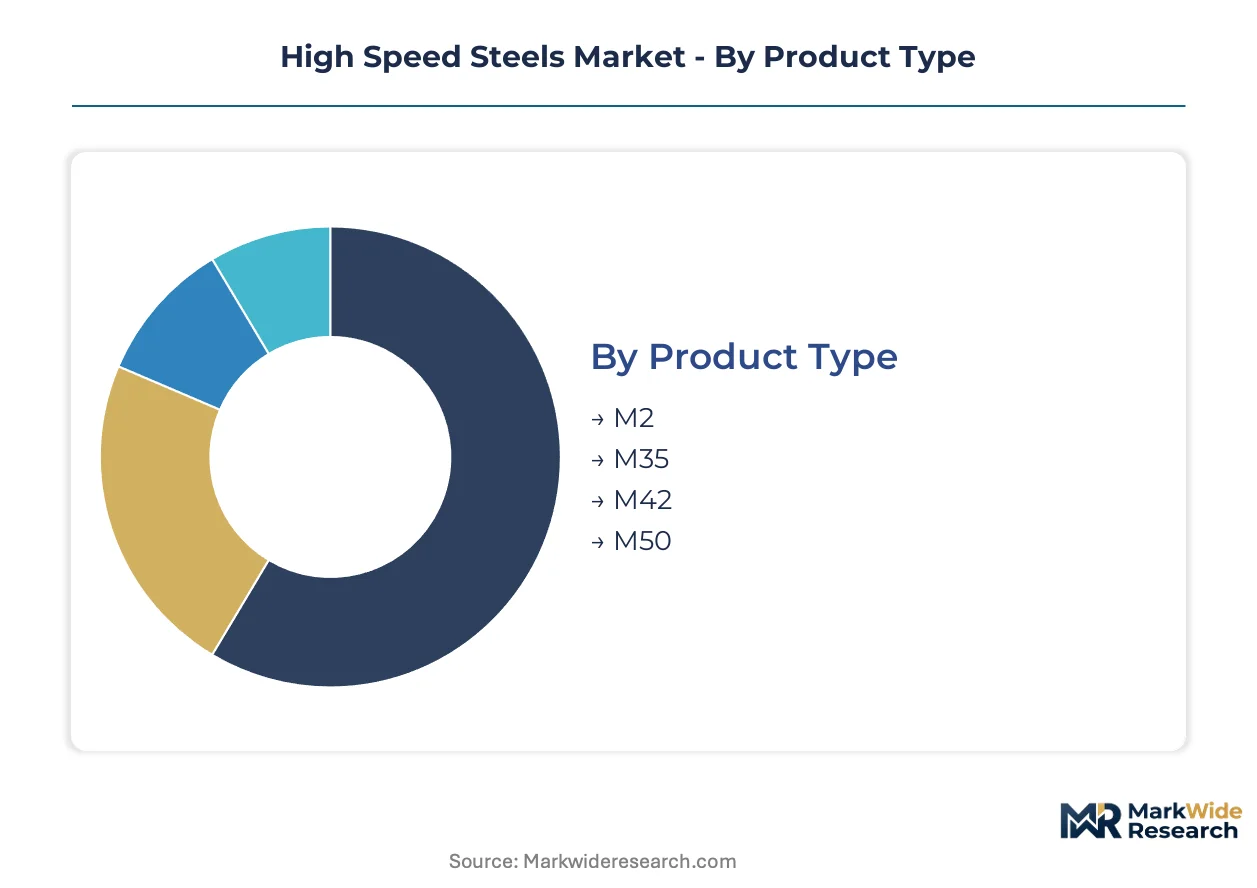
Segmentation in high speed steels reveals how alloy chemistry, application severity, and end-user certification requirements stratify procurement patterns. Suppliers must align melt-route capabilities with segment-specific red-hardness demands and regulatory documentation burdens.
Product Type:
M2 and M35 grades dominate domestic European consumption, while M42 and M50 specifications drive export volumes to aerospace supply chains.
- M2:General-purpose grade containing 6% tungsten and 5% molybdenum, optimized for drills and taps in hardness ranges below 45 HRC. German automotive supplier parks in Baden-Württemberg absorb half of European M2 bar consumption for high-volume turning operations.
- M35:Cobalt-augmented variant with 5% Co addition over M2 base chemistry, extending tool life in stainless steel machining. French cutting tool OEMs specify M35 for export contracts to North African metalworking markets seeking European-grade reliability.
- M42:8% cobalt formulation with vanadium carbide dispersion for aerospace broaching applications above 650°C cutting temperatures.
- M50:Bearing-grade specification with controlled oxygen content for jet engine main shaft applications; ESR remelting mandatory.
M2 holds the largest share; momentum sits with M42.
Application:
Cost tier separation distinguishes commodity cutting tools from precision broaches requiring triple-melt certification.
- Cutting Tools:End mills, reamers, and threading tools represent the volume foundation, with M2-grade blanks serving job shops across India's Pune-Aurangabad manufacturing corridor.
- Drills:Twist drill demand concentrates in China's Yangtze River Delta export machine tool cluster, where coated M35 commands premium positioning over uncoated alternatives.
- Inserts:Indexable insert substrates favor powder metallurgy M42 for interrupted cutting of Inconel superalloys in Swedish aerospace machining.
- Broaches:Spline and gear broaching for turbine disk slots requires M42 or T15 grades with guaranteed carbide uniformity; Rolls-Royce Derby facility sources exclusively from ESR-certified European mills.
Cutting tools anchor volume; broaches capture margin expansion.
End User:
Customer type determines specification stringency, from aerospace material certification to automotive cost-down pressures.
- Aerospace:M50 bearing steels and M42 broaching grades require AMS 6490 compliance, DFARS sourcing restrictions, and batch-level vacuum arc remelt documentation. Pratt & Whitney East Hartford campus mandates domestic US or qualified European melt sources.
- Automotive:Powertrain machining drives M2 and M35 consumption for camshaft and crankshaft turning, with BMW Group Munich pressing suppliers for coated tool life guarantees.
- Manufacturing:General industrial machinery production in Italy's Emilia-Romagna machine tool district absorbs standard-grade bars with ISO 4957 certification.
- Metalworking:Job shops and contract manufacturers represent price-sensitive demand, with Turkish Izmir-based distributors stocking Chinese-origin M2 for regrinding resale.
Metalworking generates the highest shipment volumes; aerospace climbs fastest on specification premiums.
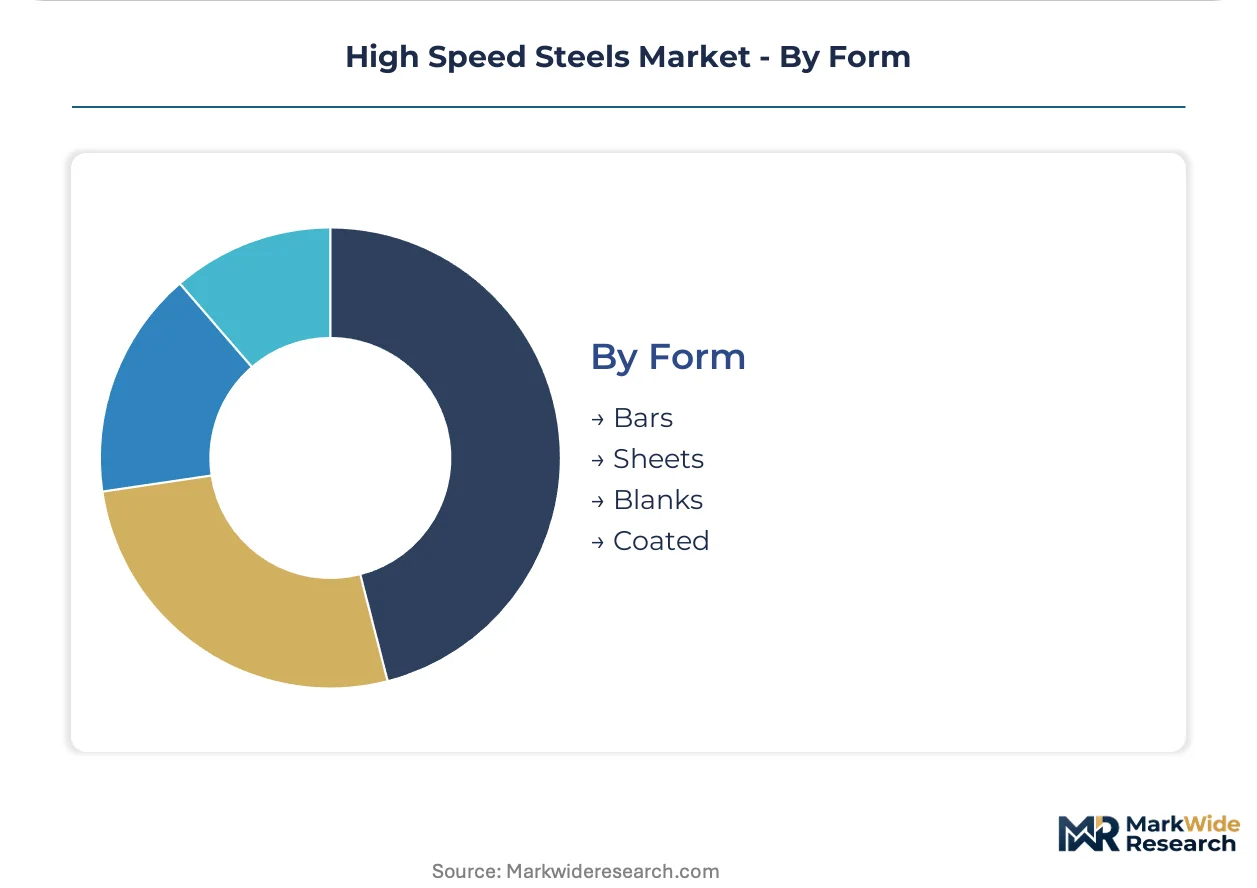
Form:
Supply concentration in Central European forging houses shapes availability across form factors.
- Bars:Hot-rolled and peeled round bars from 6mm to 200mm diameter constitute the standard delivery form; voestalpine Kapfenberg facility supplies 60% of German toolmaker bar demand.
- Sheets:Limited production for circular saw and knife applications, with Sandvik strip steel operations in Sweden serving Scandinavian woodworking tool producers.
- Blanks:Pre-forged near-net shapes reduce machining waste for complex cutting tool geometries; additive manufacturing trials are compressing lead times for custom blank geometries.
- Coated:Physical vapor deposition with TiAlN or AlCrN layers extends tool life 3-5x in unmanned machining cells; coating service unbundling is fragmenting supplier relationships in Bavaria.
Bars dominate tonnage; coated forms expand share through service model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Central European ESR-certified supply chains while Chinese-origin M2 bars compete on cost in secondary regrinding markets. German precision tooling clusters command premium positioning through guaranteed carbide uniformity documentation. Regulatory divergence between REACH-mandated cobalt disclosure and GB standard conformity assessment is fragmenting import channels.
Germany
Baden-Württemberg's automotive supplier parks absorb half of European M2 bar consumption for high-volume powertrain turning operations. ECHA REACH compliance documentation elevates procurement costs for non-integrated importers. Solingen's precision tooling cluster sustains premium pricing for ESR-refined bars with batch-level carbide uniformity guarantees.
China
SAMR-enforced GB/T 9943-2023 certification tightens inclusion rating requirements for imported tool steel bars. Yangtze River Delta export machine tool manufacturers drive coated M35 demand over uncoated alternatives. Shanghai-based technical offices of European mills absorb compliance costs faster than mid-tier Japanese competitors.
United States
Pratt & Whitney's East Hartford campus mandates domestic or qualified European melt sources for M50 bearing steels. FAA-aligned material certification requirements govern aerospace broaching grade procurement. Midwest automotive powertrain machining sustains baseline M2 and M35 consumption despite cemented carbide substitution pressure.
France
Erasteel anchors cobalt-bearing formulation leadership through proprietary triple-melt refining capabilities. ANSM-aligned pharmaceutical tooling specifications extend to cutting tool surface finish requirements. Aerospace broaching houses in central France adopt powder metallurgy M42 for Inconel turbine disk slotting applications.
India
Pune-Aurangabad manufacturing corridor job shops absorb standard-grade M2 blanks for general-purpose machining. BIS certification lags behind automotive and defense machining demand, sustaining import dependency. Domestic HSS production capacity constraints create local partnership entry points for ESR-certified European suppliers.
High Speed Steels Market Vendor Landscape
Concentration sits with integrated powder-metallurgy producers possessing captive atomization capacity. The vendor base stratifies across triple-melt aerospace specialists, conventional ESR-route suppliers, and commodity melt shops serving regrinding resale channels. Two archetypes dominate premium positioning: backward-integrated specialty scrap recyclers securing cobalt supply, and in-house powder production operators commanding M42 grade margins. Competitive moves center on atomization capacity expansion and strategic partnerships for GB standard local testing access.
Within the integrated European tier, Sandvik AB and voestalpine High Performance Metals GmbH exemplify divergent integration strategies. Sandvik leverages Swedish powder production capabilities for aerospace-grade positioning. voestalpine anchors Central European supply through Kapfenberg facility bar production serving German toolmaker demand. Erasteel occupies the cobalt-specialist archetype with French triple-melt refining heritage. NACHI-FUJIKOSHI CORP. and Daido Steel represent Japanese mill participation facing GB standard compliance headwinds in direct Chinese import channels.
| Leading Market Players |
|---|
| Sandvik AB |
| Kennametal |
| voestalpine High Performance Metals GmbH |
| NACHI-FUJIKOSHI CORP. |
| Daido Steel |
| ArcelorMittal |
| Hitachi Metals |
| Carpenter Technology Corporation |
| Erasteel |
| Others |
Supply Flow & Price Mechanics
Fourteen-week lead times for ESR-refined M42 bars signal supply-chain rigidity that hands pricing power to Central European mills with captive remelting capacity. Inventory buffers at German toolmaker warehouses have compressed to twenty-one days, forcing spot-market premiums during aerospace contract ramp-ups.
Pricing Analysis
The customization-premium spread widens to three-tier pricing structure across premium, standard, and economy levels. ESR-certified aerospace grades with batch-level carbide uniformity documentation command substantial premiums over commodity M2 bars serving regrinding resale channels. Price differentiation hinges on certification grade and volume scale, with DFARS-compliant M50 bearing steels insulated from cost compression. Pricing pressure stems from cemented carbide substitution in general-purpose machining below 45 HRC. Automotive powertrain buyers exhibit highest price sensitivity; aerospace material certification teams show lowest.
Supply Chain Analysis
Inventory compression to three-week safety stocks at precision tooling clusters exposes downstream vulnerability to tungsten supply disruption. Production concentrates in Germany, Sweden, and Austria through integrated ESR and powder-metallurgy routes. Raw material dependencies center on Chinese tungsten concentrate, Russian cobalt intermediates, and European specialty scrap recycling streams. Supply chain risk rests on single-source vulnerability for aerospace-certified triple-melt capacity. Distribution runs through Central European forging houses serving German automotive supplier parks with just-in-time bar delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery phase as aerospace production rates normalize and defense machining demand accelerates. Capital redeployment into atomization capacity will separate winners from stranded-asset holders.
For Market Incumbents: Compound defensive positioning through backward integration into specialty scrap recycling and captive powder-atomization capacity expansion. Cemented carbide substitution in general-purpose machining below 45 HRC threatens M2 volume tiers; ESR certification investment protects aerospace-grade margin pools. Channel control through local Shanghai technical offices accelerates GB/T 9943-2023 compliance absorption versus Japanese competitors. For New Entrants and Emerging Players: GB standard fast-track partnerships with Chinese third-party laboratories unlock direct import channel access faster than competitor establishment timelines. India's tooling import dependency represents the most penetrable white-space target, with Pune-Aurangabad manufacturing corridor job shops seeking ESR-certified supply partnerships. Coating service unbundling in Bavarian automotive supplier parks creates aftermarket regrinding entry points without upstream melt-shop investment. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because aerospace specification lock-in and REACH compliance moats protect incumbent returns through cycle turns. Acquisition target archetype: mid-tier ESR-route suppliers with underutilized triple-melt capacity and dormant aerospace certification pathways. Watch tungsten price volatility as inflection indicator—sustained spikes above historical bands force reformulation trade-offs that compress margin predictability across grade tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Atomization Expansion | Sandvik's in-house production secures M42 aerospace-grade positioning against conventional melt-route competitors. |
| Specialty Scrap Recycling Integration | voestalpine's backward integration earns EU Green Deal carbon credits while securing cobalt supply chain resilience. |
| GB Standard Local Testing Partnerships | European mills with Shanghai technical offices absorb SAMR compliance costs faster than mid-tier Japanese competitors. |
| Physical Vapor Deposition Coating Convergence | TiAlN and AlCrN layers on HSS substrates extend tool life in unmanned metalworking cells across Bavarian automotive parks. |
| Additive Manufacturing Preform Trials | Near-net-shape HSS production compresses forging yield losses for complex internal cooling channel geometries. |
Methodological Framework
Initial hypotheses were tested against primary input from tool steel procurement managers, ESR furnace operations directors, aerospace material certification engineers, and cutting tool OEM product managers and refined through secondary validation. Primary fieldwork combined structured interviews across Central European precision tooling clusters with trade data analysis from Eurofer and specialty steel association filings. Secondary sources encompassed REACH compliance documentation from ECHA, GB standard protocols from SAMR, SEC 10-K disclosures from listed specialty metals producers, and customs records tracking tungsten concentrate flows. Bottom-up grade-volume estimates triangulated against top-down aerospace production forecasts.
Variance decomposition across alloy chemistry, end-use severity, and regional regulatory clusters shaped the analytical framework. Segmentation dimensions modeled include product grade tier, application severity, end-user certification requirements, and form factor. CAGRs were derived from production capacity utilization trends and aerospace bill-of-materials penetration rates across the projection horizon. Industry-specific forecast inputs incorporated Pratt & Whitney and Rolls-Royce supply chain qualification timelines alongside Chinese tungsten mine production volatility indices.
The analysis sits within stated boundaries; outcomes outside normalized aerospace production recovery trajectories or sustained tungsten supply disruption would require recalibration. Forecasts reflect documented assumptions regarding ESR capacity expansion schedules and REACH enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Welding Consumables Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Band File Sander Belts Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Injection Molding Market
Industrial Materials
Steel Bar Magnet Market