
 Thermoelectric Generator (TEG) Market | 2026-2036
Thermoelectric Generator (TEG) Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoelectric Generator (TEG) Market Analytics
Buyer concentration in the Thermoelectric Generator (TEG) market is restructuring as automotive OEMs consolidate procurement while military and research institutions fragment across specialized programs. Gentherm leverages its thermal management heritage to anchor automotive waste heat recovery development. Kyocera Corporation sustains ceramic-to-semiconductor integration advantages that differentiate its bismuth telluride modules. Global Power Technologies competes in remote power generation for oil and gas infrastructure.
A thermoelectric generator converts thermal gradients directly into electrical energy through the Seebeck effect, typically employing semiconductor junctions of bismuth telluride or silicon-germanium operating across temperature differentials from 50°C to 600°C for distributed power in off-grid or waste-heat environments. Modular TEG systems dominate current deployment in industrial settings where scalability matters, while microminiature TEG formats capture emerging aerospace and wearable electronics applications with the steepest growth trajectories. Silicon-germanium materials occupy the highest-temperature segment, whereas skutterudite research advances next-generation efficiency for military end users.
EPA emissions standards and the EU F-Gas Regulation are tightening thermal efficiency requirements for industrial equipment, directly expanding addressable demand for waste heat recovery TEG installations. NHTSA fuel economy mandates and the EU Green Deal carbon pricing framework incentivize automotive OEMs to integrate TEG subsystems into exhaust streams. Military procurement through defense agencies in the United States and Japan prioritizes silent, maintenance-free power for forward operating bases. Stakeholders must monitor which material platform achieves cost-parity first against competing solid-state energy harvesters.
Market Dynamics
The TEG market is reconfiguring around material platform competition, where skutterudite research and silicon-germanium advances are compressing the efficiency gap that has historically constrained adoption in automotive and defense applications.
Growth Catalysts
- EU F-Gas Regulation:Industrial emissions standards are mandating waste heat recovery retrofits across German and French manufacturing facilities, expanding addressable demand for modular TEG installations.
- Silent power requirements:Forward operating base procurement by defense agencies in the United States and Japan is prioritizing maintenance-free TEG systems for remote power generation.
- Bismuth telluride scalability:Ceramic-to-semiconductor integration advances are lowering unit costs for automotive exhaust stream applications.
Market Restraints
- Tellurium supply concentration:Refining capacity for this critical input clusters in China, creating price volatility exposure for bismuth telluride module producers.
- Efficiency ceiling:The Seebeck coefficient limitation in conventional semiconductor junctions caps conversion rates below what competing solid-state harvesters achieve.
- NHTSA certification timelines:Extended validation protocols for automotive exhaust-integrated systems delay OEM deployment schedules.
Strategic Opportunities
- Wearable electronics convergence:Microminiature TEG formats paired with low-power IoT sensors are opening white space in aerospace crew monitoring applications.
- Japan METI funding:National R&D subsidies for next-generation thermoelectric materials are accelerating skutterudite commercialization timelines.
- Oil and gas infrastructure:Pipeline monitoring and wellhead power applications in remote North American basins remain underpenetrated by solid-state alternatives.
Industry Challenges
- Thermal interface engineering:Specialized heat exchanger design talent scarcity constrains system integration speed for industrial waste heat projects.
- Multi-physics simulation:Coupled thermal-electric-mechanical modeling capabilities are required for aerospace qualification, creating hiring bottlenecks.
- Legacy exhaust architecture:Retrofitting TEG subsystems into existing vehicle platforms demands extensive thermal management redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoelectric Generator (TEG) Market |
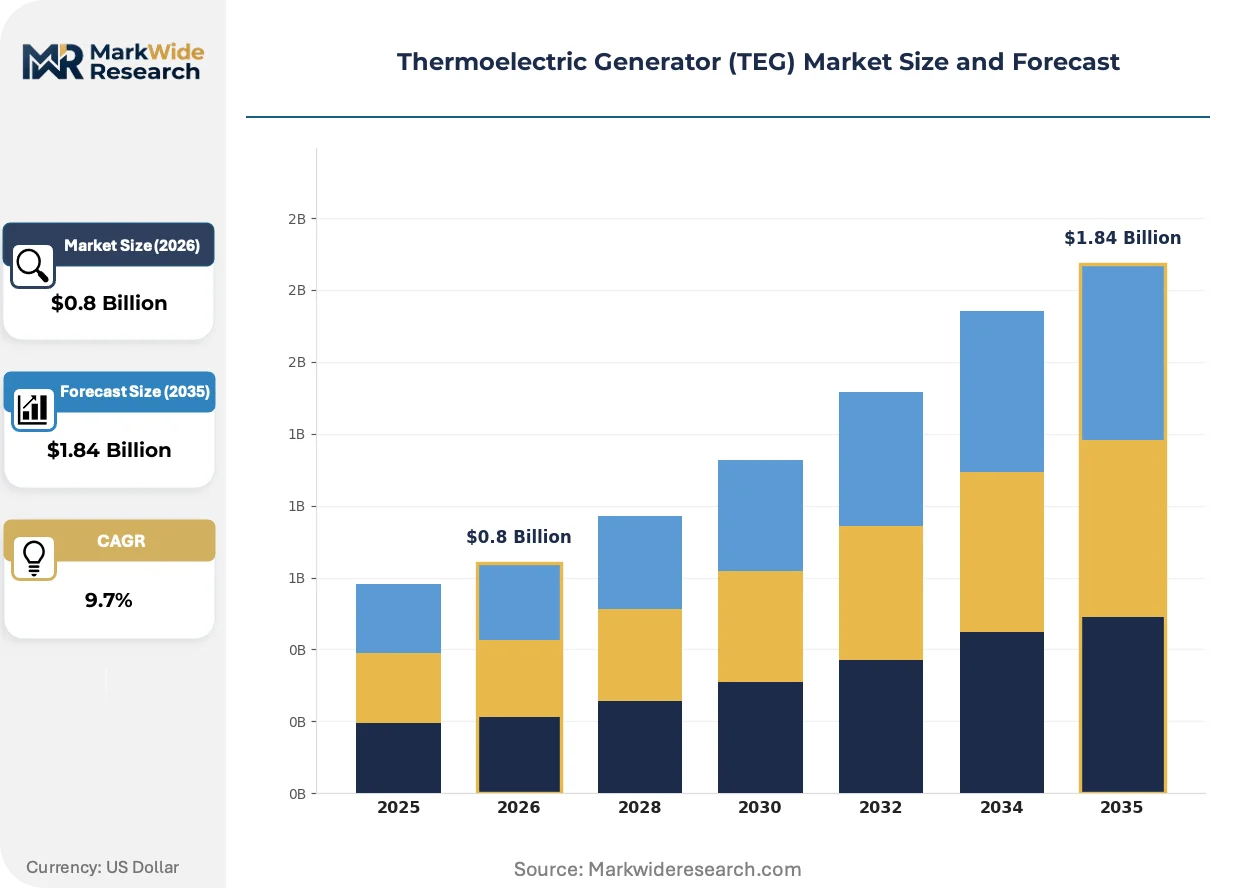
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular TEG, System TEG, Microminiature TEG, Portable TEG Material: Bismuth Telluride, Lead Telluride, Silicon-Germanium, Skutterudites Application: Automotive Waste Heat Recovery, Industrial Waste Heat Recovery, Remote Power Generation, Aerospace End User: Automotive OEMs, Industrial Manufacturers, Research Institutions, Military |
| Companies Covered | Komatsu Ltd., Kyocera Corporation, Gentherm, Laird Thermal Systems, Hi-Z Technology, Coherent Corp., Global Power Technologies, Yamaha Corporation, Ferrotec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoelectric Generator (TEG) Market Evolving Landscape
Active material research and procurement restructuring are compressing development cycles across the TEG value chain, with efficiency gains and buyer consolidation reshaping competitive positioning faster than historical norms.
Skutterudite compounds are unifying high-temperature performance with improved manufacturability, addressing the traditional silicon-germanium cost barrier. Defense research institutions in the United States and Japan are accelerating pilot programs for forward base power. This material convergence is unifying previously separate military and industrial supply chains around shared qualification protocols.
EPA emissions standards and the EU Green Deal carbon pricing framework are tightening thermal efficiency mandates for industrial equipment and automotive exhaust systems. Manufacturing facilities in Germany face binding waste heat recovery requirements under F-Gas Regulation amendments. Automotive OEMs are responding by integrating TEG subsystems into next-generation exhaust architectures to maintain compliance.
Buyer concentration among automotive OEMs is compressing supplier negotiation cycles while fragmenting military procurement across specialized research programs. Tier-1 thermal management suppliers are displacing direct module sales with integrated subsystem contracts. This pattern is most visible in Germany and the United States, where consolidated automotive buyers demand turnkey waste heat recovery solutions.
Thermoelectric Generator (TEG) Market Segmentation
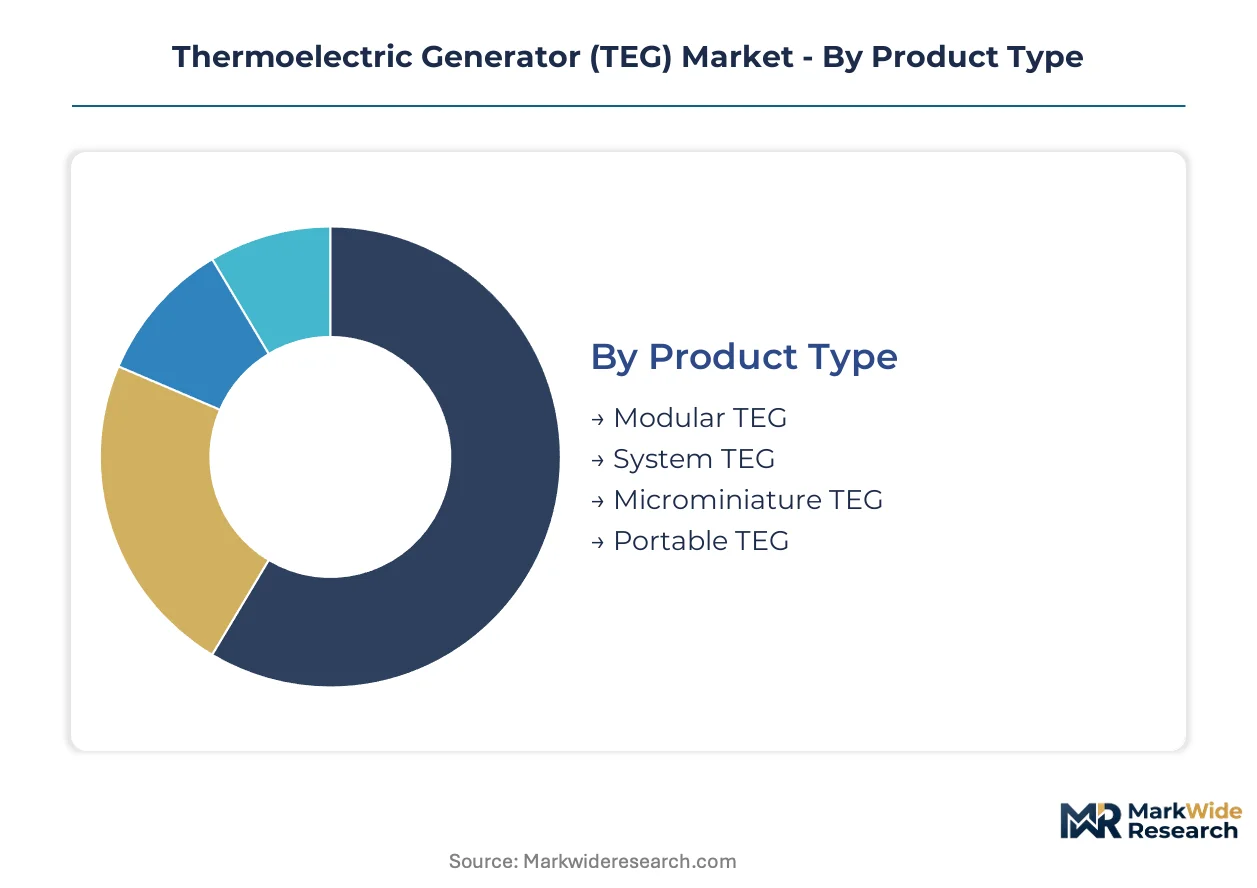
TEG procurement patterns diverge sharply across product architectures and material platforms. Upgrade cycles in automotive exhaust integration and defense research programs are compressing vendor qualification timelines. Understanding segment-specific thermal requirements and supply chain dependencies shapes effective market entry.
Product Type:
Replacement cycles vary from decade-long industrial installations to sub-annual iterations in aerospace prototyping. Upgrade urgency correlates with temperature regime and accessibility constraints.
- Modular TEG:Standardized bismuth telluride junction arrays packaged for scalable industrial deployment. Demand concentrates in German manufacturing facilities facing EU F-Gas Regulation compliance deadlines; retrofit economics favor modularity over custom engineering.
- System TEG:Integrated subsystems combining thermoelectric modules with heat exchangers and power conditioning. Automotive OEMs in the United States specify these for exhaust stream integration under NHTSA fuel economy mandates; thermal interface engineering talent scarcity constrains deployment speed.
- Microminiature TEG:Thin-film formats for body-worn and embedded sensors.
- Portable TEG:Self-contained units for field deployment in remote locations.
Volume placements concentrate in Modular TEG; the faster expansion belongs to Microminiature TEG.
Material:
Cost tiers stratify around raw material availability, processing complexity, and temperature ceiling. Tellurium supply concentration in China creates asymmetric exposure across the platform stack.
- Bismuth Telluride:Room-to-moderate temperature semiconductor junctions dominating commercial production. Kyocera Corporation's ceramic-to-semiconductor integration advances lower unit costs for Japanese automotive programs; tellurium price volatility remains the persistent constraint.
- Silicon-Germanium:High-temperature alloys for aerospace and defense applications. United States military research institutions prioritize this material for forward operating base power; efficiency gains justify cost premiums in mission-critical deployments.
- Lead Telluride:Intermediate-temperature performance for industrial waste heat.
- Skutterudites:Next-generation compounds unifying manufacturability with thermal performance.
Silicon-Germanium commands the highest unit margins; skutterudites are climbing the fastest toward commercial scale.
Application:
Customer types fragment procurement specifications across thermal source characteristics and grid connectivity requirements. Application selection dictates regulatory exposure and integration complexity.
- Automotive Waste Heat Recovery:Exhaust-integrated systems converting engine thermal losses to auxiliary power. OEM consolidation in Germany and the United States compresses supplier negotiation cycles; NHTSA certification timelines delay deployment schedules.
- Industrial Waste Heat Recovery:Manufacturing facility retrofits capturing process heat. French and German plants face binding F-Gas Regulation amendments; modular architectures reduce engineering lead times for compliance-driven purchases.
- Remote Power Generation:Off-grid installations for pipeline monitoring and wellhead equipment.
- Aerospace:Crew monitoring and satellite thermal management applications.
Industrial Waste Heat Recovery absorbs the largest project volumes; Aerospace is gaining share fastest on microminiature format adoption.
End User:
Procurement concentration and technical sophistication vary dramatically across buyer categories. Contract structures range from multi-year automotive supply agreements to fragmented research grants.
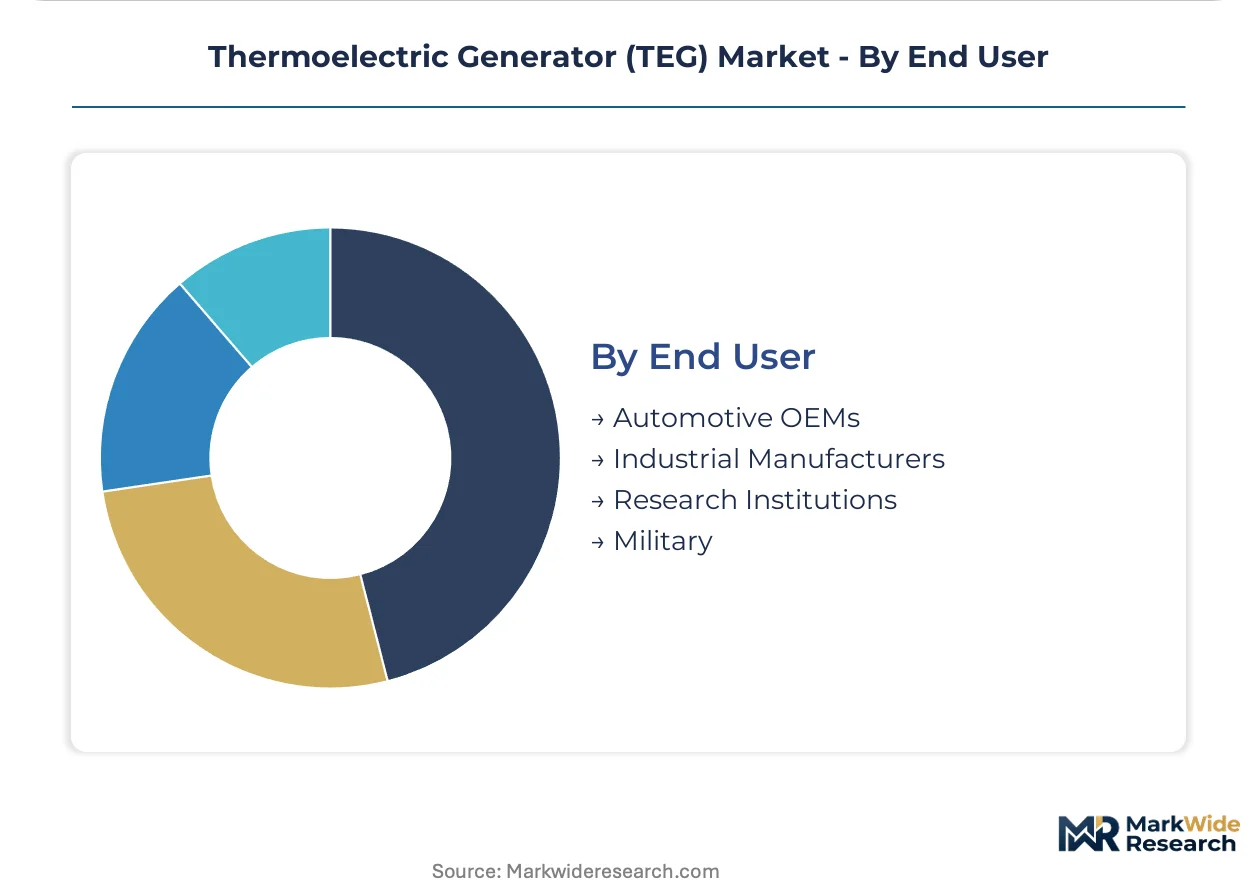
- Automotive OEMs:Consolidated buyers demanding turnkey subsystem integration. Tier-1 thermal management suppliers in Germany and the United States are displacing direct module sales with packaged waste heat recovery solutions; qualification protocols extend 18-36 months.
- Military:Defense agencies in the United States and Japan prioritizing silent, maintenance-free power. Forward operating base procurement fragments across specialized research programs; skutterudite pilot programs accelerate under METI and DARPA funding.
- Industrial Manufacturers:Facility operators retrofitting for emissions compliance.
- Research Institutions:Universities and national laboratories advancing material science.
Automotive OEMs dominate contract value; Military procurement is expanding most quickly on next-generation material programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in Germany, Japan, and the United States, while defense agencies fragment demand across specialized research programs. Military end users in the United States and Japan accelerate skutterudite pilot deployments. Industrial retrofit demand clusters in German and French manufacturing corridors facing binding emissions deadlines.
United States
Defense agencies prioritize silent power for forward operating bases, while automotive OEMs scale exhaust-integrated TEG pilots under NHTSA fuel economy mandates. DARPA funding accelerates skutterudite commercialization timelines. Detroit thermal management clusters anchor subsystem integration development for next-generation vehicle architectures.
Germany
Automotive OEM consolidation compresses supplier negotiation cycles around turnkey waste heat recovery solutions. EU F-Gas Regulation amendments bind manufacturing facilities to retrofit deadlines. Bavarian industrial corridors drive modular TEG deployment for process heat capture in automotive supply chain plants.
Japan
METI R&D subsidies accelerate next-generation thermoelectric material programs, while defense procurement fragments across specialized research initiatives. Ceramic-to-semiconductor integration advances lower unit costs for domestic automotive programs. Nagoya industrial clusters concentrate bismuth telluride module production for regional OEM supply chains.
France
Industrial manufacturers face binding waste heat recovery requirements under EU F-Gas Regulation compliance schedules. National carbon pricing frameworks tighten thermal efficiency mandates for process equipment. Lyon-Grenoble manufacturing corridors concentrate retrofit demand for modular TEG installations in chemical and metals processing.
China
Tellurium refining capacity concentration creates supply leverage for bismuth telluride module producers serving domestic industrial markets. National dual carbon goals intensify waste heat recovery adoption in steel and cement sectors. Yangtze River Delta manufacturing clusters integrate TEG subsystems into process heat networks for export-oriented facilities.
Thermoelectric Generator (TEG) Market Competitive Landscape
Japanese and United States producers anchor the premium materials tier; European thermal management specialists hold integrated subsystem positions. Buyer consolidation among automotive OEMs compresses vendor qualification timelines while fragmenting defense procurement across research programs. Three archetypes dominate: ceramic-to-semiconductor integrators, high-temperature alloy specialists, and turnkey subsystem packagers. Strategic moves concentrate on backward integration into critical raw materials and technology licensing for next-generation compounds.
Within the ceramic-to-semiconductor integration tier, Kyocera Corporation exemplifies advanced packaging capabilities, while Gentherm occupies a position bridging thermal management heritage with automotive subsystem development. Global Power Technologies anchors remote power generation archetypes for oil and gas infrastructure applications. These three represent distinct competitive vectors: materials science depth, automotive systems integration, and ruggedized field deployment.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| Kyocera Corporation |
| Gentherm |
| Laird Thermal Systems |
| Hi-Z Technology |
| Coherent Corp. |
| Global Power Technologies |
| Yamaha Corporation |
| Ferrotec Corporation |
| Others |
Value Network & Pricing Analysis
Tellurium refining costs cascade through bismuth telluride module production, concentrating pricing power in Chinese upstream suppliers while compressing margins for Japanese and German integrators serving automotive OEMs. This input-cost architecture stratifies the market into three tiers: silicon-germanium premium systems for defense, ceramic-integrated mid-range modules for industrial retrofit, and commodity bismuth telluride units facing persistent price erosion.
Pricing Analysis
Volume placements concentrate in commodity bismuth telluride modules where Chinese tellurium supply concentration erodes pricing power, while silicon-germanium and skutterudite formats capture premium margins in defense and aerospace procurement. Pricing stratifies across premium, standard, and economy tiers based on temperature ceiling certification and automotive OEM qualification status. Cost compression in the standard tier intensifies because Tier-1 thermal management suppliers are displacing direct module sales with integrated subsystem contracts. Military end users exhibit lowest price sensitivity due to mission-critical reliability requirements, while industrial manufacturers facing EU F-Gas Regulation compliance deadlines drive hardest bargain negotiations.
Supply Chain Analysis
Automotive qualification protocols gate supplier access, extending vendor approval timelines to 18-36 months and freezing out uncertified competitors from OEM procurement channels. Manufacturing concentrates in Japan, Germany, and the United States for high-reliability modules, while China dominates tellurium refining and bismuth telluride wafer production. The supply chain draws from concentrated tellurium feedstock, ceramic substrate foundries, and specialized thermal interface engineering talent pools. Single-source vulnerability runs through Chinese tellurium refining capacity. Distribution runs through Tier-1 automotive thermal management suppliers and defense procurement agencies rather than direct module sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TEG market is consolidating around material platform winners as automotive OEM procurement compression and tellurium supply volatility force weaker module producers toward exit or acquisition. Buyers are consolidating supplier relationships while defense research fragmentation creates asymmetric opportunities for specialized entrants.
For Market Incumbents: Deploy backward integration into tellurium sourcing to insulate margin structures from Chinese supply concentration. Kyocera Corporation's ceramic-to-semiconductor integration model demonstrates how captive packaging capabilities defend against Tier-1 subsystem displacement. Gentherm's thermal management heritage positions it to capture automotive exhaust integration contracts as NHTSA certification timelines compress vendor pools. Accelerate skutterudite pilot programs under DARPA and METI funding channels before material efficiency curves commoditize silicon-germanium premiums. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for modular TEG specialists targeting industrial waste heat retrofit deadlines with turnkey compliance solutions. White space concentrates in North American oil and gas remote power generation, where pipeline monitoring applications remain underpenetrated by solid-state alternatives. Aerospace microminiature formats for crew monitoring systems offer fastest qualification pathways outside automotive certification bottlenecks. Pursue technology licensing arrangements with Japanese ceramic foundries rather than capital-intensive manufacturing scale-up. For Investors and Strategic Acquirers: Distressed-cycle entries favor ceramic-to-semiconductor integrators in Japan and Germany with existing automotive qualification credentials and METI or EU Green Deal funding access. Long-term viability hinges on material platform selection, with skutterudite commercialization timelines determining which incumbents survive the silicon-germanium to next-generation transition. Watch for DARPA program acceleration signals as inflection indicators for defense procurement scaling beyond pilot volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tellurium Sourcing | Chinese refining concentration creates asymmetric margin exposure for bismuth telluride producers without captive supply. |
| Skutterudite Commercialization Partnership | DARPA and METI funding channels accelerate qualification timelines for next-generation military power systems. |
| Tier-1 Subsystem Packaging Capability | Automotive OEM consolidation favors turnkey waste heat recovery suppliers over direct module vendors. |
| Aerospace Microminiature Format Development | Crew monitoring applications bypass automotive certification bottlenecks with faster qualification cycles. |
| Industrial Retrofit Turnkey Solutions | German and French F-Gas Regulation deadlines compress procurement timelines for compliance-driven purchases. |
Research Methodology
Document review covered EPA emissions filings, EU F-Gas Regulation amendments, NHTSA fuel economy dockets, and METI R&D subsidy disclosures, complemented by interviews with thermal management procurement directors at automotive OEMs, defense agency program officers, industrial facility engineering managers, and ceramic foundry technical leads. Secondary validation drew from customs trade data for tellurium and bismuth compounds, SEC 10-K thermal management segment disclosures, and national laboratory research publication databases. Bottom-up module shipment estimates triangulated against top-down industrial waste heat recovery project announcements and automotive platform integration timelines.
Segment-level outputs across material platforms, product architectures, and end-user categories were derived through coupled thermal-electric performance modeling and procurement cycle analysis throughout the forecast period. The analytical framework incorporated temperature regime requirements, qualification protocol durations, and funding program acceleration factors as industry-specific forecast inputs. CAGRs were computed from installation base growth, replacement cycle compression, and emerging application penetration curves rather than extrapolated trend fitting.
The model assumes a particular technology adoption path; alternative pathways for skutterudite or advanced silicon-germanium alloys would alter the outlook if efficiency gains outpace projected timelines. Forecasts reflect assumptions about automotive OEM consolidation continuity, defense procurement fragmentation persistence, and tellurium supply concentration stability. A model refresh is warranted upon material change in DARPA or METI funding acceleration, EU F-Gas Regulation enforcement intensity, or NHTSA certification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market
Power Systems
Vehicle Inverter Market
Power Systems
Hybrid Inverters Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
USB Power Adapters Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
String Inverter Market
Power Systems
DC Power Supplies Market