
 US Variable Frequency Drive Market | 2026-2036
US Variable Frequency Drive Market Size, Share, and Industry Trends Forecast 2026-2036
US Variable Frequency Drive Market Analysis
Remote condition monitoring and predictive maintenance subscriptions is consolidating around VFD portfolios, shifting vendor revenue from hardware sales to recurring service contracts. Schneider Electric SE leverages its EcoStruxure platform to anchor long-term client relationships through digital energy management. Rockwell Automation Inc. competes with integrated control architectures that embed VFD intelligence within broader automation stacks. Eaton Corporation differentiates through specialized hazardous-duty drives serving upstream oil and gas operations.
A variable frequency drive modulates electric motor speed by varying input frequency and voltage, typically operating across 0.5 to 500 horsepower ranges with switching frequencies between 2 and 16 kHz to optimize torque delivery and minimize harmonic distortion. The device serves primarily to reduce energy consumption in motor-driven systems where load conditions fluctuate. Closed-loop vector control configurations command premium positioning in precision manufacturing environments where torque response accuracy determines process yield. Pump and compressor applications generate the deepest retrofit demand pools as municipal water authorities and hydrocarbon processors face escalating electricity costs. HVAC end-use installations represent a mature, replacement-driven segment with compressed margins but stable volume throughput.
The Department of Energy enforces minimum efficiency standards under 10 CFR 431 for polyphase induction motors paired with VFDs, compelling facility operators to upgrade legacy fixed-speed installations. NEMA and IEEE 519 harmonics guidelines further constrain product design, filtering out non-compliant suppliers from commercial and industrial procurement channels. OSHA electrical safety regulations govern VFD enclosure ratings and arc-flash mitigation requirements in heavy manufacturing deployments. Stakeholders must track how pending EPA industrial emissions rules could accelerate electrification retrofits in fossil-fuel-dependent process industries.
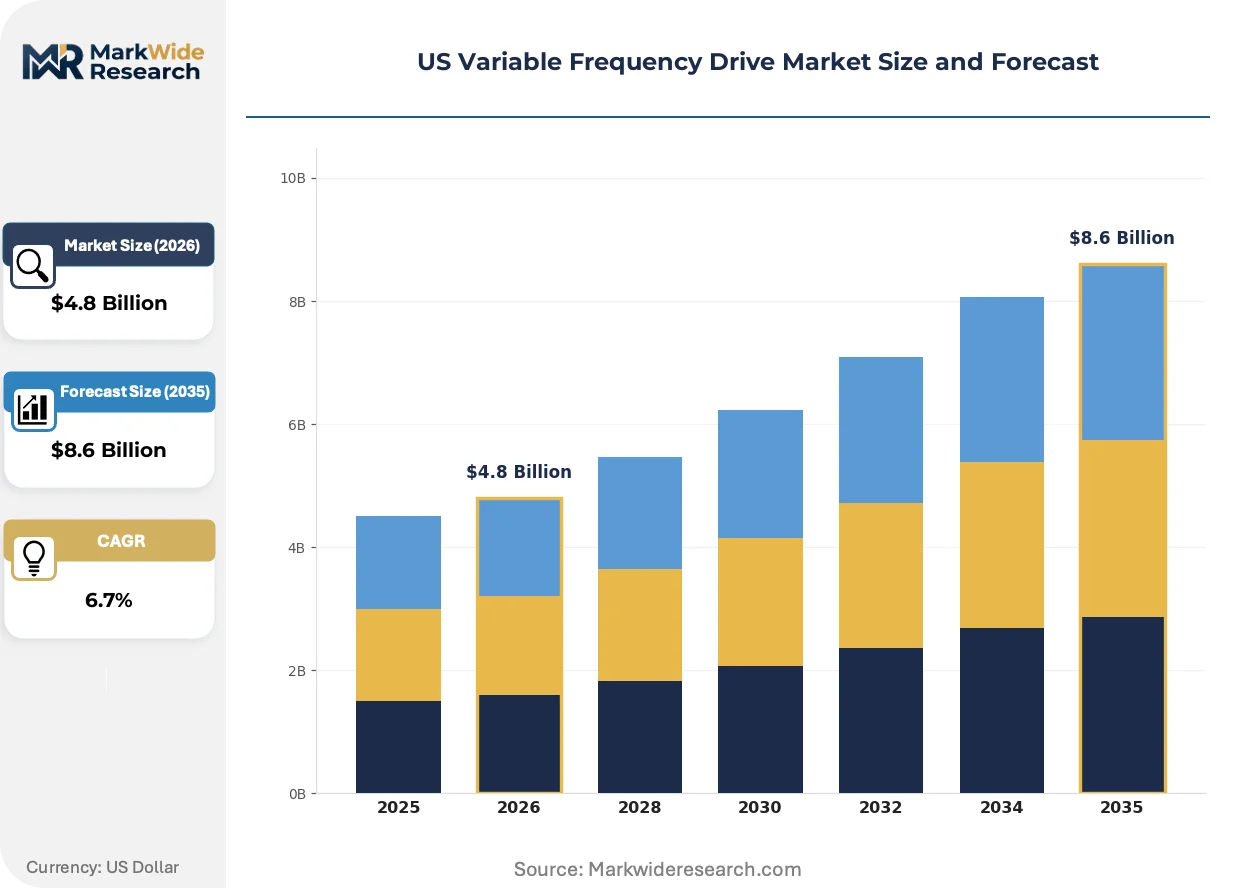
Market Dynamics
The US Variable Frequency Drive Market is compressing around predictive maintenance architectures as water utilities and petrochemical operators prioritize uptime over capital expenditure, forcing vendors to bundle hardware with recurring software subscriptions.
Growth Catalysts
- DOE 10 CFR 431 Efficiency Mandates:Tightening motor system standards compel facility operators to retire fixed-speed installations, creating mandatory retrofit demand across industrial and municipal sectors.
- Southwest Water Infrastructure Expansion:Drought-driven aquifer management projects in Arizona, Nevada, and New Mexico deploy VFD-controlled pumping stations to optimize energy draw during peak tariff hours.
- Gulf Coast Petrochemical Electrification:Hydrocarbon processors facing carbon pricing pressure convert mechanical drive systems to electric motor-VFD combinations for process compressors and cooling loops.
Market Restraints
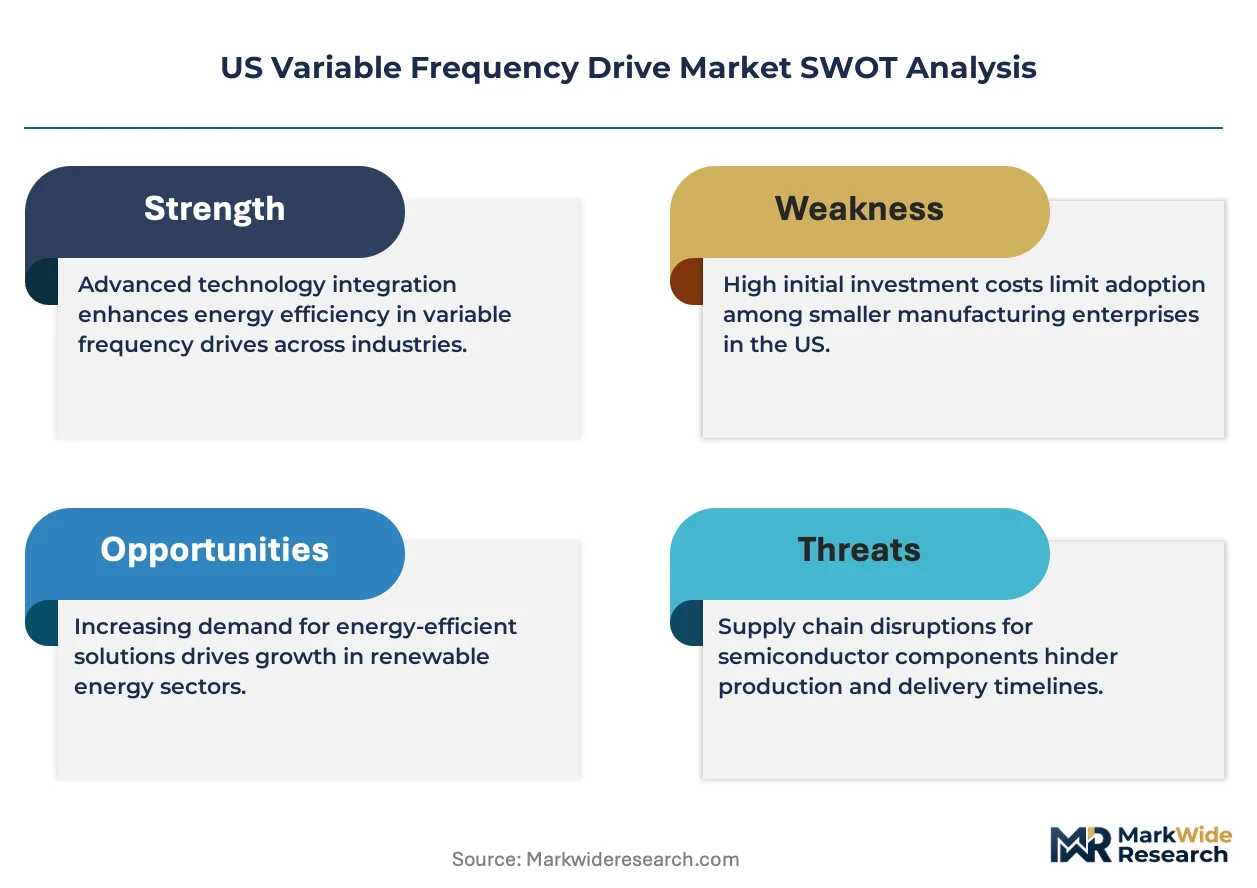
- IGBT and SiC Semiconductor Supply Concentration:Power module sourcing depends on Asian foundry capacity, exposing lead times to geopolitical friction and foundry allocation decisions.
- IEEE 519 Harmonics Compliance Costs:Grid interconnection standards require active front-end or line reactor configurations that add 15-25% to base drive cost, squeezing margin on small horsepower units.
- Mechanical Variable Speed Drives:Eddy current and hydraulic coupling systems retain cost advantage in explosive atmosphere applications where VFD enclosure ratings escalate pricing.
Strategic Opportunities
- Appalachian Shale Basin Electrification:Upstream oil and gas operators in Pennsylvania and West Virginia seek hazardous-duty drives for artificial lift and gas compression as field electrification accelerates.
- California Title 24 Building Efficiency Code:HVAC retrofit mandates in commercial structures create replacement demand for integrated fan and pump control systems with utility rebate eligibility.
- Edge Analytics Convergence:Embedding vibration and thermal sensing within drive enclosures enables condition-based monitoring without separate sensor infrastructure, opening mid-market segments.
Industry Challenges
- Power Electronics Engineering Talent Scarcity:Design and field commissioning of active harmonic filter configurations requires specialized expertise concentrated among aging practitioner cohorts.
- Legacy Motor-Drive Compatibility:Retrofit installations face winding insulation stress and bearing current damage when inverter-duty rated motors are unavailable for immediate replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Variable Frequency Drive Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Loop, Closed Loop, Vector Control, Direct Torque Control Application: Pumps, Conveyors, Fans, Compressors End User: Manufacturing, Water Treatment, HVAC, Oil & Gas Installation: Indoor, Outdoor, Skid-Mounted, Panel-Mounted |
| Companies Covered | Schneider Electric SE, Eaton Corporation, Siemens AG, General Electric Company, Yaskawa Electric Corporation, ABB Ltd., Danfoss A/S, Delta Electronics Inc., Rockwell Automation Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Variable Frequency Drive Market Emerging Trajectories
Silicon carbide power semiconductors and edge-native analytics are restructuring competitive differentiation away from horsepower range coverage toward energy efficiency performance and predictive service attach rates.
Wide-bandgap silicon carbide MOSFETs are overtaking silicon IGBTs in mid-voltage drive designs, cutting switching losses by half and enabling smaller thermal management footprints. Texas and California data center operators specify SiC-based drives for cooling tower applications where energy recovery justifies premium hardware cost. The technology is overtaking traditional topologies in 100-500 horsepower ranges where efficiency gains compound across 24-hour operational profiles.
OSHA electrical safety regulations and NFPA 70E arc-flash standards now govern VFD enclosure specifications and maintenance access protocols in heavy manufacturing deployments. Facility safety managers mandate arc-resistant bus designs and remote disconnect capabilities, adding engineering complexity to custom drive packages. Metal fabrication and chemical processing plants in Ohio and Illinois face the steepest compliance retrofit timelines.
Water authorities in Texas and Arizona now bundle 10-year service contracts with initial VFD procurement, shifting vendor relationships from transactional equipment supply to guaranteed availability performance. Municipal procurement departments in drought-stressed regions prioritize total cost of ownership models over lowest capital bid, rewarding suppliers with local technician networks and spare parts inventory commitments.
US Variable Frequency Drive Market Segmentation
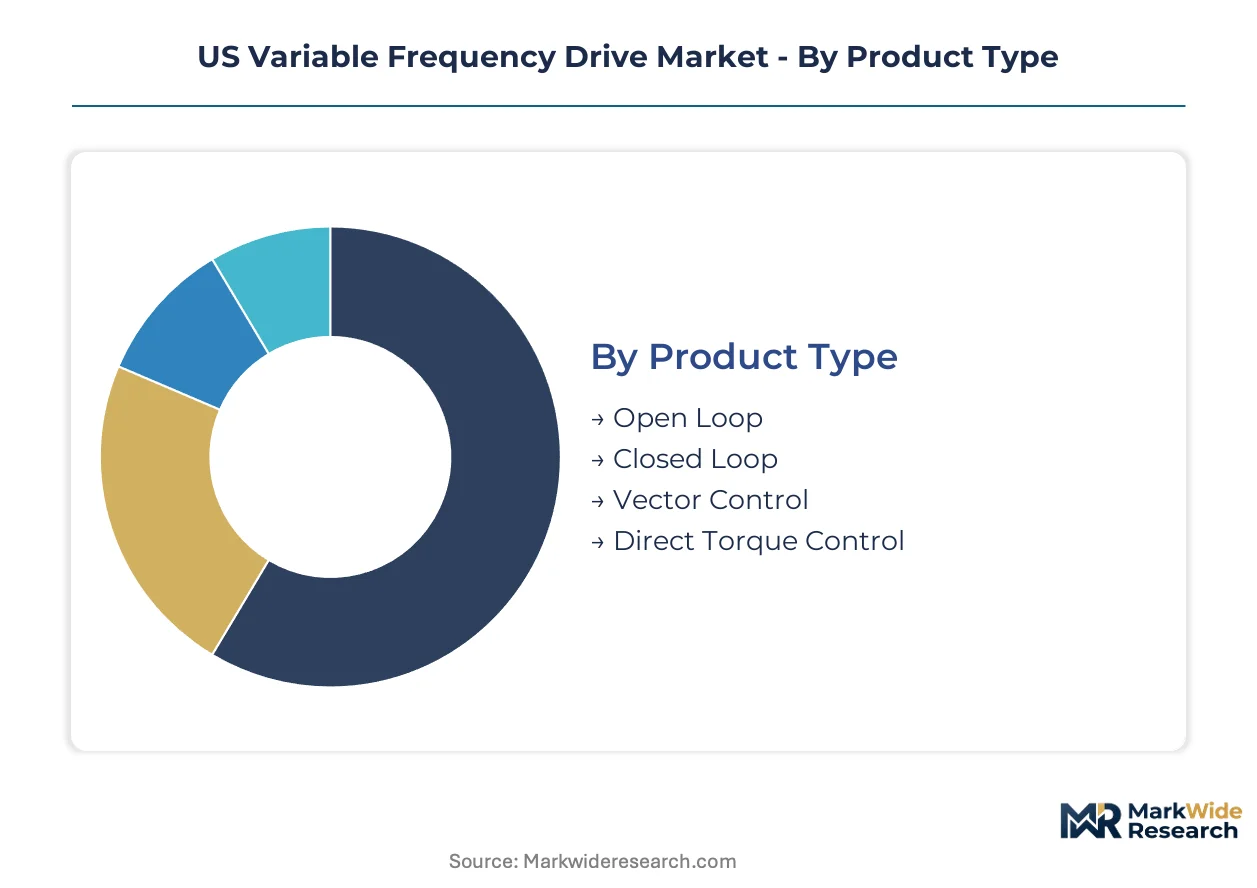
VFD procurement decisions hinge on matching control precision to load dynamics, with facility engineers weighing initial hardware cost against lifecycle energy recovery. Segmentation reveals where technical specifications translate into contract value across power ranges and environmental enclosures.
Product Type:
Control architecture determines torque response accuracy and pricing tier, with facility engineers selecting configurations based on process criticality and speed regulation tolerance.
- Closed Loop:Encoder feedback systems deliver sub-rpm speed accuracy for precision manufacturing lines where spindle synchronization determines yield. Texas semiconductor fabs and California aerospace machine shops specify these drives despite 40% cost premiums over open-loop alternatives.
- Vector Control:Sensorless flux vector algorithms enable full torque at zero speed without encoder hardware, dominating metal stamping and extrusion applications across Ohio and Illinois industrial corridors where mid-range precision meets budget constraints.
- Open Loop:Volts-per-hertz control suits centrifugal pumps and fans with quadratic torque curves where speed accuracy tolerance exceeds 3%.
- Direct Torque Control:Direct stator flux and torque calculation achieves fastest dynamic response for crane hoists and rolling mill stands.
Vector Control leads on scale; Closed Loop leads on momentum as precision manufacturing reshoring accelerates.
Application:
Load profile characteristics dictate drive sizing and harmonic mitigation requirements, with rotating equipment type determining retrofit versus greenfield procurement patterns.
- Pumps:Centrifugal and positive displacement pump control generates the deepest retrofit demand pool as municipal water authorities face escalating electricity tariffs. Arizona and Nevada aquifer management projects deploy VFD-controlled variable-speed pumping to shift energy draw off-peak, with DOE efficiency mandates compelling upgrades at legacy fixed-speed installations.
- Compressors:Rotary screw and centrifugal compressor applications command premium drive configurations with active front-end rectifiers to meet IEEE 519 harmonics limits at high power. Gulf Coast petrochemical processors converting mechanical drive systems to electric motor-VFD combinations for process gas compression represent concentrated demand.
- Fans:HVAC air handling and industrial ventilation applications operate as mature replacement-driven segment with utility rebate eligibility shaping procurement timing.
- Conveyors:Bulk material handling systems require coordinated multi-drive control architectures for tension regulation across long distances.
Pumps lead on scale; Compressors lead on momentum as carbon pricing pressure accelerates electrification retrofits.
End User:
Facility type determines procurement authority structure, with municipal water districts and industrial operators diverging on total cost of ownership versus capital budget constraints.
- Water Treatment:Municipal authorities in drought-stressed Southwest states now bundle decade-long service contracts with initial VFD procurement, prioritizing guaranteed availability over lowest bid. Texas and Arizona procurement departments reward suppliers with local technician networks and spare parts inventory commitments.
- Manufacturing:Discrete and process manufacturers specify integrated control architectures embedding VFD intelligence within broader automation stacks, with Ohio and Illinois metal fabrication plants facing steep OSHA electrical safety compliance retrofit timelines.
- HVAC:Commercial building efficiency retrofits under California Title 24 create replacement demand for integrated fan and pump control systems.
- Oil & Gas:Upstream operators in Appalachian shale basins seek hazardous-duty drives for artificial lift and gas compression as field electrification accelerates.
Water Treatment leads on scale; Manufacturing leads on momentum as predictive maintenance subscriptions reshape vendor relationships.
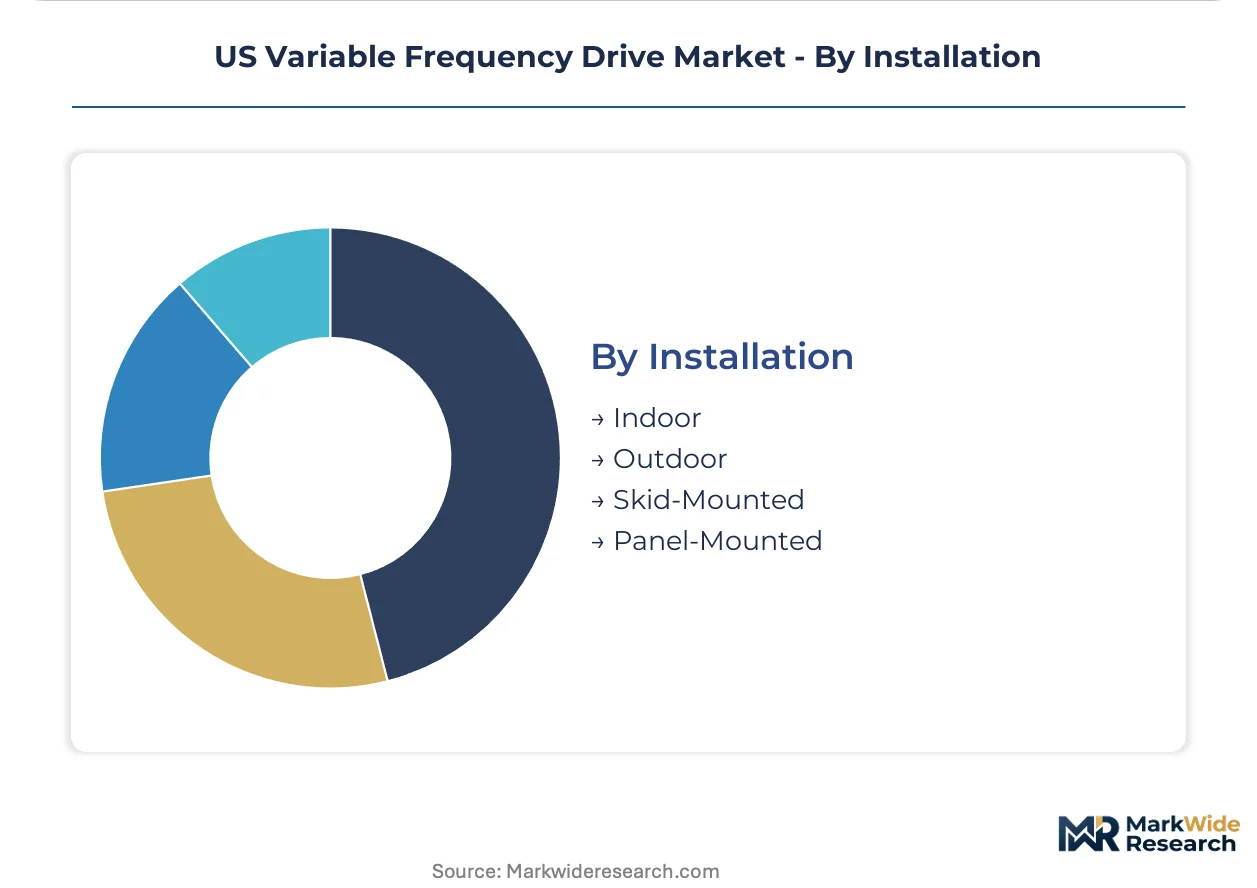
Installation:
Environmental exposure and maintenance access requirements determine enclosure engineering and thermal management specifications, with total installed cost varying substantially across mounting configurations.
- Indoor:Climate-controlled electrical rooms accommodate standard NEMA 1 or NEMA 12 enclosures with passive convection cooling, dominating manufacturing and commercial building applications where ambient conditions remain stable.
- Outdoor:NEMA 3R and 4X rated enclosures with sealed gaskets and thermostatically controlled heaters protect against rain, dust, and temperature extremes at remote pumping stations and well pads.
- Skid-Mounted:Pre-engineered packages integrate drive, isolation transformer, and harmonic filter on structural steel bases for rapid field deployment at oil and gas facilities.
- Panel-Mounted:Compact drives install within existing motor control centers, minimizing footprint in space-constrained retrofit applications.
Indoor leads on scale; Outdoor leads on momentum as distributed water infrastructure expands into harsh-environment locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas concentrates more VFD procurement volume than California, though California's Title 24 building codes generate steeper retrofit intensity per installed base. The Southwest drought corridor and Gulf Coast petrochemical belt anchor regional demand geography.
Texas
Municipal water authorities across the Rio Grande Valley deploy VFD-controlled pumping stations for aquifer management under severe drought conditions. The Texas Commission on Environmental Quality enforces efficiency standards for public water systems that accelerate fixed-speed motor retirements. Houston-area petrochemical complexes convert mechanical drive systems to electric motor-VFD combinations for process compressors.
California
Data center operators in Silicon Valley specify silicon carbide-based drives for cooling tower energy recovery under 24-hour operational profiles. The California Energy Commission's Title 24 Building Efficiency Standards mandate HVAC fan and pump controls with utility rebate eligibility in commercial structures. Los Angeles Basin water treatment facilities bundle decade-long service contracts with initial VFD procurement.
Arizona
Colorado River aquifer management projects deploy variable-speed pumping to shift energy draw off-peak tariff hours. The Arizona Corporation Commission oversees utility rebate programs that shape commercial building retrofit timing. Phoenix metropolitan water districts prioritize total cost of ownership models over lowest capital bid, rewarding suppliers with local technician networks.
Ohio
Metal fabrication plants across the Rust Belt industrial corridor face steep OSHA electrical safety compliance retrofit timelines for arc-flash mitigation. The Ohio Environmental Protection Agency coordinates with municipal utilities on industrial efficiency programs. Cleveland-area automotive stamping facilities specify sensorless flux vector drives for mid-range precision applications.
Louisiana
Upstream operators in the Haynesville Shale seek hazardous-duty drives for artificial lift and gas compression as field electrification accelerates. The Louisiana Department of Environmental Quality monitors emissions from process industries converting mechanical drives to electric systems. Baton Rouge refinery complexes drive demand for active front-end rectifier configurations to meet IEEE 519 harmonics limits.
US Variable Frequency Drive Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated automation vendors capturing manufacturing accounts while electrical equipment specialists dominate municipal water and oil and gas verticals. The vendor base concentrates around three strategic archetypes: full-stack automation platforms, power electronics specialists with hazardous-duty certifications, and digital energy management platform operators. Competitive moves center on predictive maintenance subscription bundling and silicon carbide technology transitions that reshape hardware margins.
Among European-headquartered industrial conglomerates, ABB Ltd. and Siemens AG occupy positions anchoring the premium-tier integrated drive systems market, while Danfoss A/S represents the power electronics specialist archetype with concentrated exposure to HVAC and refrigeration applications. Schneider Electric SE exemplifies the digital platform operator model, leveraging cloud-based energy management architectures to convert transactional equipment relationships into recurring service revenue streams. These three companies collectively illustrate how vendor strategy diverges between hardware-centric and service-centric monetization approaches.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Eaton Corporation |
| Siemens AG |
| General Electric Company |
| Yaskawa Electric Corporation |
| ABB Ltd. |
| Danfoss A/S |
| Delta Electronics Inc. |
| Rockwell Automation Inc. |
| Others |
Supply Flow & Price Mechanics
Silicon carbide MOSFET adoption in mid-voltage drive designs simultaneously compresses switching losses and concentrates power module sourcing among Asian foundry operators, reshaping both cost economics and supply vulnerability. This technology transition elevates hardware premiums for efficiency-optimized units while tethering margin structures to semiconductor allocation decisions beyond vendor control.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for IGBT and SiC power modules, yet contract-based long-term offtake agreements dominate procurement for tier-one drive manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop vector configurations from open-loop alternatives, with IEEE 519 compliance certification and hazardous-duty UL ratings commanding substantial markups. Cost compression in small horsepower units is intensifying because active front-end rectifier requirements add 15-25% to base hardware cost. Municipal water authorities exhibit lowest price sensitivity due to total cost of ownership procurement mandates, while commercial HVAC retrofitters face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundry capacity for advanced SiC substrates and China's dominance in rare earth magnet processing for high-efficiency motor pairings. Power module assembly draws from Japan, Germany, and Malaysia for final integration, while copper busbar fabrication and aluminum heatsink extrusion rest on North American and Mexican metalworking capacity. Tariff exposure on Chinese-sourced magnetic components and semiconductor substrates presents structural risk to landed cost stability. Distribution runs through electrical equipment distributors serving industrial automation accounts, with direct OEM relationships capturing large petrochemical and water utility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Variable Frequency Drive Market functions as a geographic-arbitrage play where Appalachian shale basin electrification demand outpaces Gulf Coast supply capacity, creating margin capture opportunities for vendors with Pennsylvania and West Virginia technician networks.
For Market Incumbents: Acquire field service organizations with hazardous-duty certification capabilities to defend against power electronics specialists entering the oil and gas vertical. Backward integration into SiC module sourcing through joint development agreements with Taiwanese foundries mitigates single-source exposure. Channel control through exclusive distribution pacts with electrical contractors serving municipal water districts locks out emerging competitors. For New Entrants and Emerging Players: Independent service contractors with vibration analysis expertise represent the most penetrable partner channel for predictive maintenance subscription attach. California Title 24 HVAC retrofit compliance creates white-space demand for integrated fan and pump control systems with utility rebate navigation services. Arizona and Nevada water authorities prioritize local spare parts inventory commitments over brand recognition, enabling regional entrants to displace national suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among power electronics engineering firms with active harmonic filter design capabilities and aging principal ownership. Five-to-ten year viability hinges on SiC technology transition execution and recurring service revenue attach rates. The inflection signal to watch is municipal procurement department adoption of guaranteed availability contracts with penalty clauses for downtime.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Technology Transition | Texas data center operators specify wide-bandgap drives for cooling tower energy recovery applications. |
| Predictive Maintenance Subscription Bundling | Arizona water authorities now require decade-long service contracts with initial VFD procurement. |
| Hazardous-Duty Certification Investment | Appalachian shale electrification creates demand for UL-listed drives in explosive atmosphere applications. |
| Backward Integration into Power Module Sourcing | Vendor margin stability hinges on direct SiC substrate relationships with Taiwanese foundry operators. |
| Local Technician Network Expansion | Phoenix metropolitan water districts reward suppliers with regional spare parts inventory commitments. |
Methodological Framework
Direct dialogue with plant engineers, maintenance directors at municipal water authorities, electrical contractors, OEM procurement teams, and aftermarket service heads grounded qualitative insights in operational reality. Secondary validation drew from DOE 10 CFR 431 regulatory filings, IEEE standards documentation, SEC 10-K disclosures from listed automation vendors, EIA industrial electricity consumption data, and municipal procurement records. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate market sizing.
Bottom-up modeling aggregated unit shipments across power rating tiers, control architectures, and end-use applications, while top-down analysis calibrated aggregate market value against industrial electricity expenditure patterns and motor system efficiency retrofit penetration rates. Segmentation dimensions spanned product type, application load profile, end-user facility category, and environmental installation requirements. CAGRs were derived from regression analysis of historical efficiency mandate compliance cycles and projected electrification investment trajectories across the analysis window. Forecast inputs incorporated drought-driven aquifer management capital programs and carbon pricing pressure on Gulf Coast petrochemical processors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry allocation decisions, pending EPA industrial emissions rulemaking, and IEEE harmonics standard revisions. Forecasts reflect documented assumptions regarding efficiency mandate enforcement timelines and utility rebate program continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Linear Voltage Regulators Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
Global Excitation Systems Market
Power Systems
Smart Power Strips Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Central Battery Systems Market
Power Systems
Asia Pacific Transformer Monitoring System Market
Power Systems
Vehicle Inverter Market
Power Systems
Battery Charge Controller Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Flyback Transformer Market
Power Systems
Power Electronics Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Thermoelectric Coolers Market