
 North America Variable Frequency Drive Market | 2026-2036
North America Variable Frequency Drive Market Size, Share, and Industry Trends Forecast 2026-2036
North America Variable Frequency Drive Market Outlook
Capital-intensity divergence between integrated power electronics manufacturers and assembly-focused competitors is unwinding competitive stability in the North America Variable Frequency Drive landscape. ABB leverages its silicon-to-systems vertical integration to control component costs across medium-voltage drive portfolios. Rockwell Automation anchors its position through deep embedded software capabilities in integrated motion control platforms.
A variable frequency drive modulates AC motor speed by varying input frequency and voltage, typically operating between 0.5 Hz and 400 Hz with adjustable carrier frequencies from 2 kHz to 16 kHz to match torque requirements and minimize harmonic distortion. Low-voltage drives dominate unit shipments across North American manufacturing floors, though medium-voltage drives command disproportionate margin pools in heavy process industries. Flux vector control technology leads precision applications in oil and gas upstream operations, while scalar control occupies cost-sensitive HVAC retrofit segments where open-loop performance suffices.
EPA efficiency standards under the Energy Policy Act and NEMA MG1 motor regulations shape VFD specification requirements across U.S. industrial installations, while CSA C390 energy verification protocols govern Canadian market access. IEEE 519 harmonic limits constrain drive topology selection in grid-connected applications, particularly across Texas and California utility territories. Stakeholders must monitor evolving FERC interconnection rules and state-level decarbonization procurement mandates as these frameworks increasingly dictate retrofit timelines and technology selection criteria.
Market Dynamics
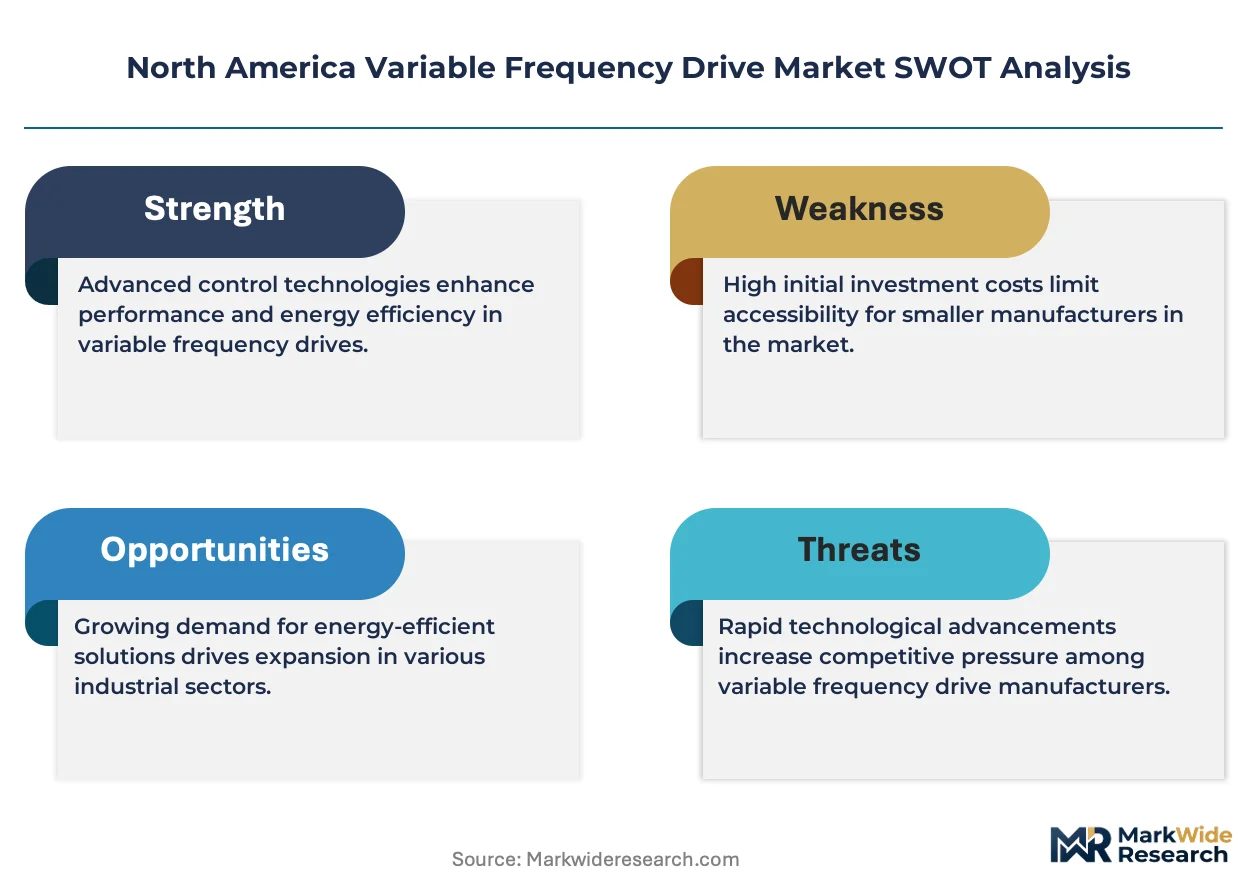
Water and wastewater utilities across the United States and Canada are retrofitting aging pump stations with VFD-equipped motor systems to satisfy tightening EPA energy efficiency mandates and reduce electricity expenditures in high-volume treatment operations.
Growth Catalysts
- EPA Energy Policy Act compliance:Industrial facilities must install premium-efficiency motor-drive combinations to meet federal efficiency floors, accelerating replacement cycles across U.S. manufacturing plants.
- Texas and California grid interconnection rules:IEEE 519 harmonic compliance requirements are forcing heavy process industries to upgrade to active front-end drive topologies in these high-growth utility territories.
- Petrochemical corridor expansion:Gulf Coast process industries are retrofitting aging extruder and compressor motor systems with medium-voltage drives to capture demand from polyethylene and polypropylene capacity additions.
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor fabrication capacity concentrates in East Asian foundries, exposing North American drive manufacturers to input cost volatility and extended lead times.
- NEMA MG1 motor compatibility friction:Retrofit installations face technical limitations matching legacy NEMA B and C motor designs with modern flux vector control algorithms without rewinding.
- Skilled commissioning technician scarcity:The shortage of certified drive application engineers in the U.S. Midwest and Canadian Prairies extends project timelines and inflates implementation costs.
Strategic Opportunities
- Canadian provincial decarbonization procurement:Ontario and British Columbia carbon reduction mandates are creating dedicated funding streams for municipal VFD retrofits in HVAC and water infrastructure.
- Edge analytics convergence:Integration of drive-embedded vibration monitoring with cloud-based predictive maintenance platforms opens recurring revenue streams in oil and gas upstream operations.
- Direct-to-utility channel development:Bypassing traditional electrical distributor networks to sell integrated motor-drive packages through utility rebate programs is capturing price-sensitive commercial building retrofits.
Industry Challenges
- Legacy DCS integration complexity:Brownfield process plants struggle to synchronize modern Ethernet-based drive communications with aging 4-20mA and DeviceNet control architectures.
- UL 508C certification timeline compression:Accelerated product development cycles strain testing laboratory capacity, delaying market entry for new drive platforms targeting industrial automation segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Variable Frequency Drive Market |
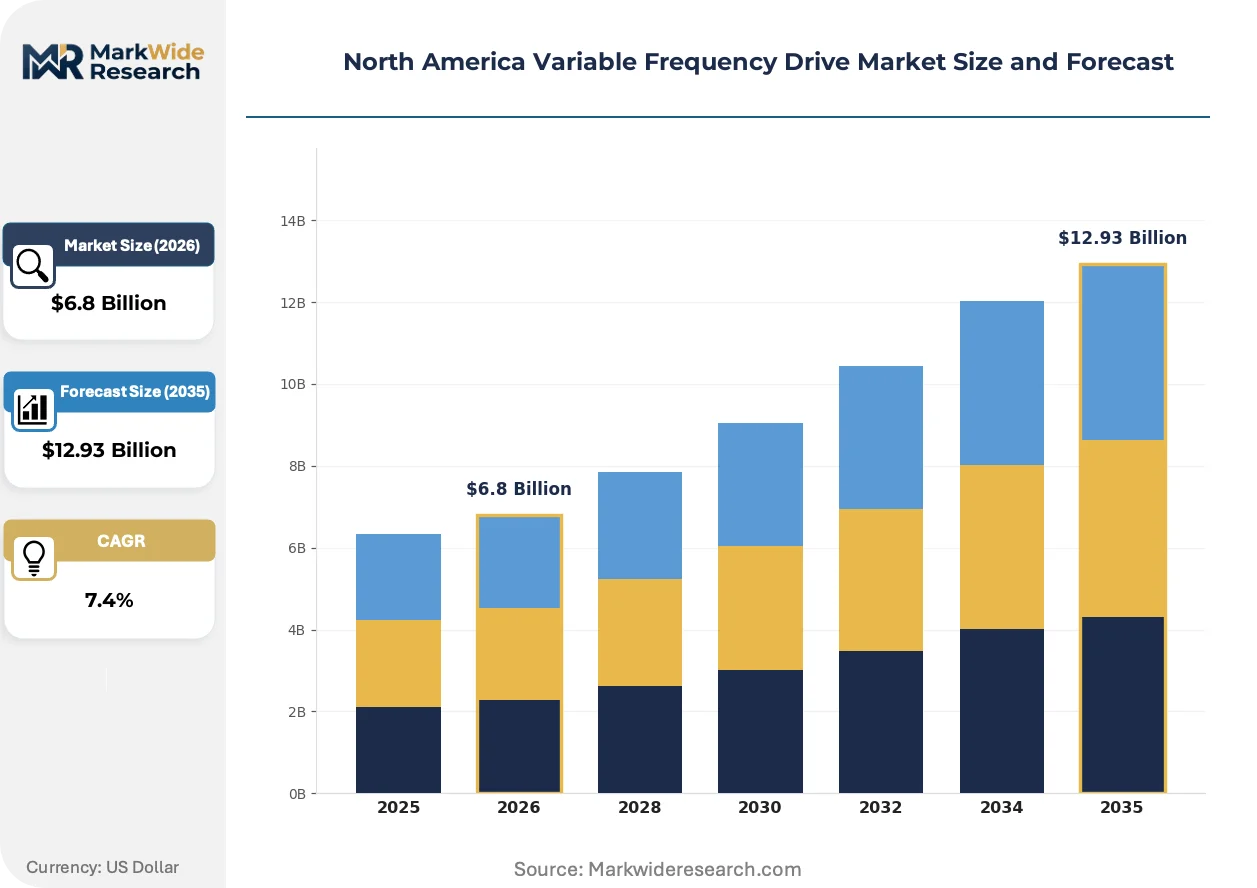
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Voltage Drives, Medium-Voltage Drives, High-Voltage Drives, Servo Drives End User: Manufacturing, Water & Wastewater, Oil & Gas, HVAC Technology: Flux Vector Control, Voltage Control, Current Control, Scalar Control Application: Pumps, Compressors, Fans, Conveyors |
| Companies Covered | ABB, Rockwell Automation, Danfoss, Siemens, Eaton, Schneider Electric, Yaskawa America, Phase Technologies, WEG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Variable Frequency Drive Market Strategic Shifts
Several concurrent developments are reshaping how VFDs are specified, procured, and deployed across North American industrial and infrastructure applications. These shifts span hardware architecture, regulatory compliance frameworks, and commercial engagement models.
Silicon carbide power modules are fragmenting the traditional IGBT-dominated landscape by enabling higher switching frequencies with reduced thermal losses. Oil and gas upstream operators in the Permian Basin are early adopters, deploying SiC-based medium-voltage drives for electric submersible pump applications where footprint and cooling constraints are severe. This transition is fragmenting supplier hierarchies as semiconductor specialists capture margin pools previously held by integrated drive manufacturers.
FERC interconnection standards are tightening harmonic emission requirements for grid-connected industrial loads across Texas ERCOT and California CAISO territories. The revised standards are compelling heavy process industries to abandon six-pulse rectifier topologies in favor of active front-end or harmonic-filtered drive configurations. Petrochemical facilities along the Gulf Coast are responding by front-loading capital budgets to pre-empt compliance deadlines and avoid production curtailment risks.
Equipment-as-a-service contracting is displacing traditional capital purchase models in commercial HVAC and municipal water segments. Building automation integrators and regional mechanical contractors are bundling VFD installation, maintenance, and energy performance guarantees into multi-year agreements with predictable monthly payments. This shift is most visible in California and New York metro areas where property owners face carbon disclosure mandates and seek to offload operational technology risk.
North America Variable Frequency Drive Market Segmentation
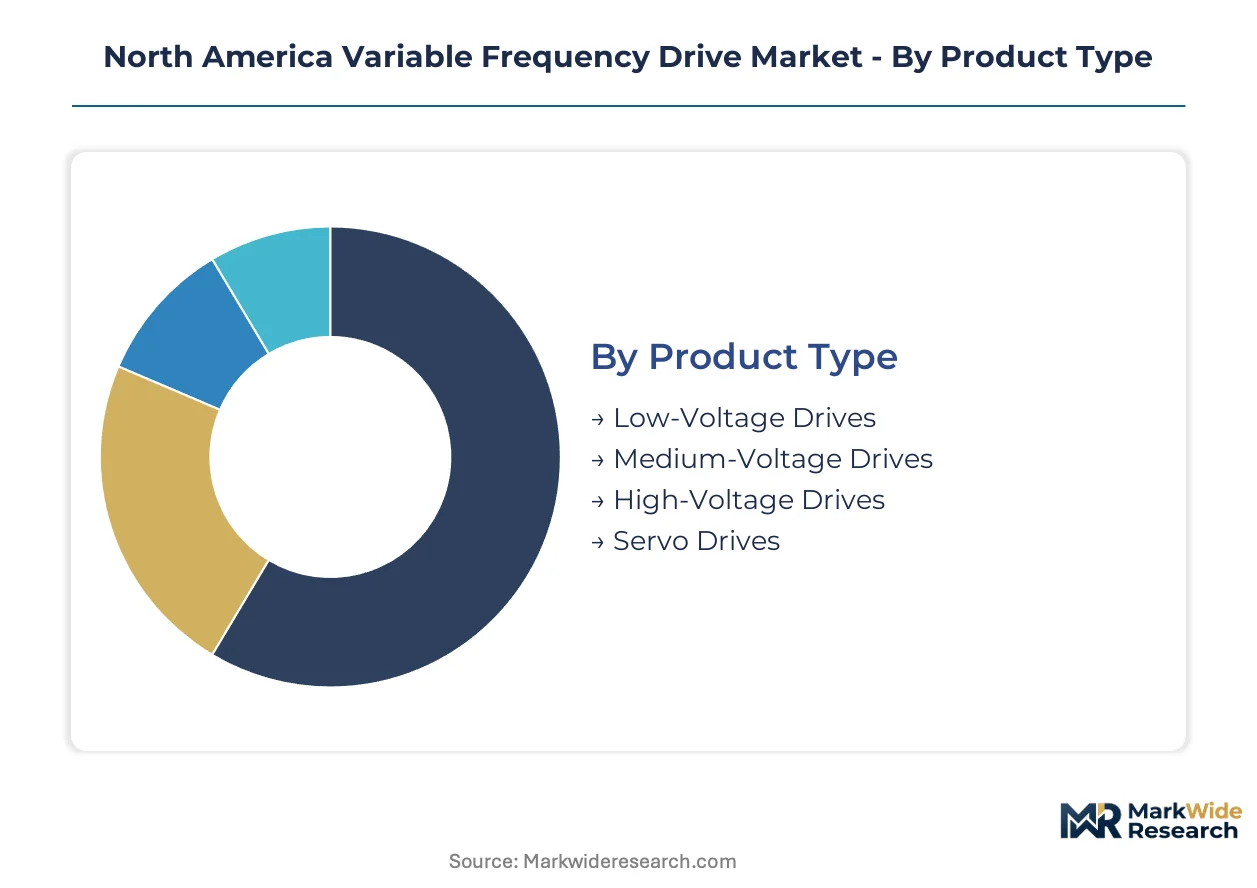
Channel strategy in the North America Variable Frequency Drive market diverges sharply by segment, with electrical distributors dominating low-voltage unit flows while direct OEM partnerships capture medium-voltage project value. Understanding these pathway distinctions enables suppliers to align inventory positioning with margin capture opportunities.
Product Type:
Low-voltage drives move primarily through authorized electrical distributor networks serving MRO replacement cycles, while medium-voltage systems deploy through systems integrator channels tied to EPC project timelines.
- Low-Voltage Drives:These units operate below 690V input and utilize IGBT-based power modules with carrier frequencies tunable between 2-16 kHz. Manufacturing floors across the U.S. Midwest concentrate replacement demand as aging motor systems face NEMA MG1 efficiency mandates, with distributor stocking locations in Chicago and Detroit anchoring fulfillment velocity.
- Medium-Voltage Drives:Designed for 2.3-13.8 kV applications, these drives employ multi-level inverter topologies with active front-end rectification. Gulf Coast petrochemical corridors generate project demand as polyethylene capacity expansions retrofit extruder motor controls, with front-end engineering packages flowing through Houston-based systems integrators.
- High-Voltage Drives:Specialized units above 13.8 kV serving utility-scale pump storage and mine hoist applications with limited North American manufacturing presence.
- Servo Drives:Precision motion control systems integrating encoder feedback for positioning accuracy, concentrated in automotive stamping and packaging machinery OEM channels.
Low-voltage drives dominate installed base across North American industrial facilities. Medium-voltage drives represent the steepest expansion trajectory as process industries front-load capital budgets ahead of FERC interconnection rule tightening.
End User:
Cost tier stratification separates specification authority, with municipal water utilities prioritizing lifecycle cost optimization while manufacturing procurement targets unit cost minimization within rebate program constraints.
- Manufacturing:Discrete and process factories deploy VFDs across material handling, machining, and batch processing lines. Automotive assembly plants in Tennessee and Kentucky drive specification volume for integrated motor-drive packages with Ethernet/IP connectivity.
- Water & Wastewater:Municipal treatment facilities and distribution pump stations represent the fastest-growing procurement segment. EPA energy efficiency mandates are forcing utilities across California and Texas to retrofit centrifugal pumps with variable speed controls, with funding flowing through state revolving fund mechanisms.
- Oil & Gas:Upstream electric submersible pump applications and midstream compressor stations in the Permian Basin and Bakken formation.
- HVAC:Commercial building retrofits and new construction specifying drives for chilled water pumps and air handling units, concentrated in urban cores with carbon disclosure mandates.
Manufacturing retains the largest historical installed base. Water and wastewater infrastructure is where procurement velocity is accelerating most quickly under regulatory pressure.
Technology:
Application complexity determines control algorithm selection, with precision positioning requirements forcing flux vector adoption while constant torque HVAC loads tolerate simpler scalar methods.
- Flux Vector Control:Closed-loop systems utilizing rotor flux orientation with encoder feedback achieve torque response below 5 milliseconds. Oil and gas upstream operators in the Permian Basin specify these drives for electric submersible pump speed regulation where reservoir pressure fluctuations demand rapid adjustment.
- Voltage Control:Open-loop V/Hz regulation maintaining constant volts-per-hertz ratio for general-purpose fan and pump applications with stable load curves.
- Current Control:Direct torque control variants eliminating encoder requirements through motor current observation, gaining traction in conveyor and extruder applications.
- Scalar Control:Basic frequency-voltage proportioning without vector mathematics, dominating cost-sensitive HVAC retrofit segments where open-loop performance satisfies static pressure modulation requirements.
Scalar control retains volume leadership across installed base. Flux vector architectures are expanding most quickly as precision process applications retrofit aging DC drive systems.
Application:
Equipment duty cycle and torque profile shape drive sizing and cooling requirements, with continuous pump operation demanding thermal margin while intermittent conveyor service permits compact packaging.
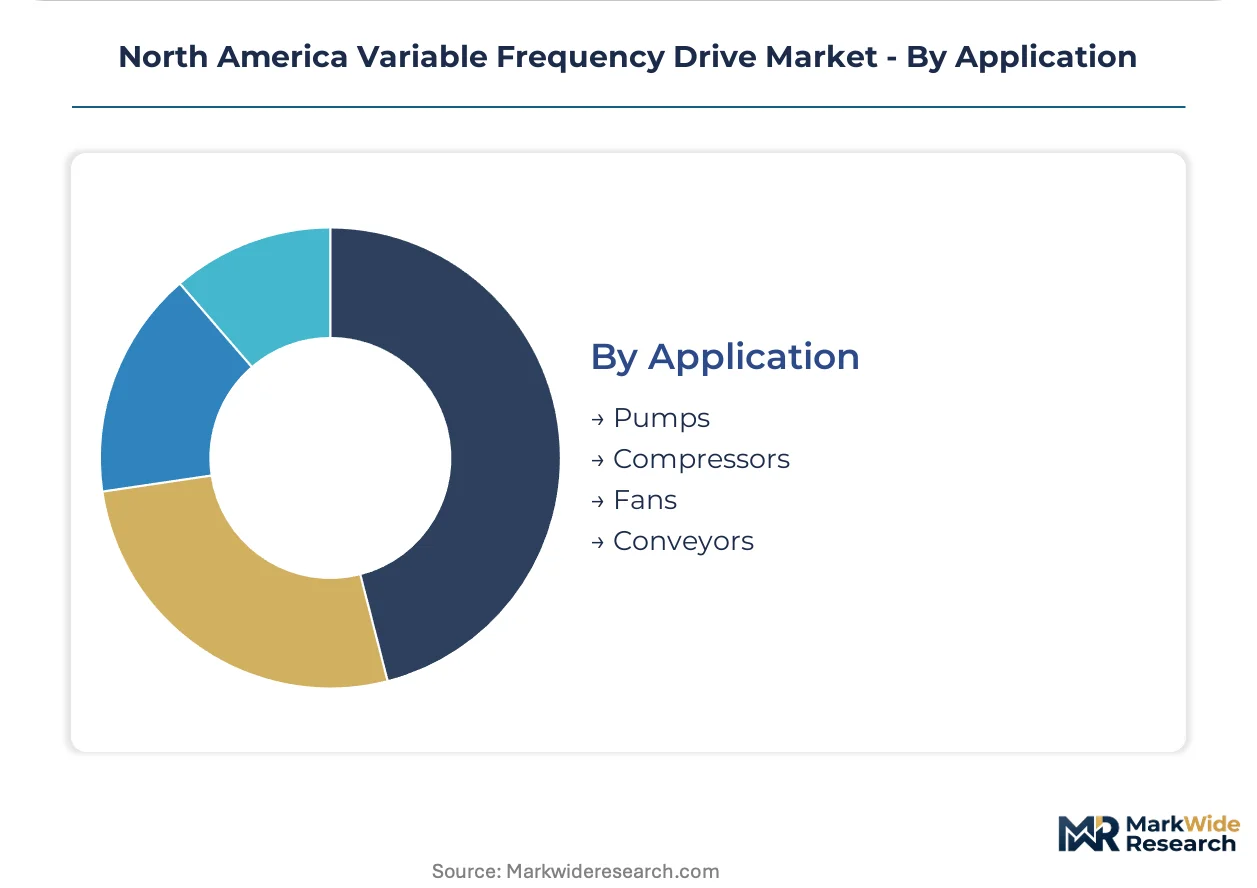
- Pumps:Centrifugal and positive displacement pump applications constitute the largest addressable equipment class. Water utilities across Ontario and British Columbia are retrofitting aging wastewater lift stations, with provincial decarbonization procurement mandates accelerating specification timelines.
- Compressors:Rotary screw and centrifugal gas compression in petrochemical and natural gas processing. Gulf Coast ethylene crackers are deploying medium-voltage drives on cracked gas compressors to capture polyethylene demand expansion.
- Fans:Axial and centrifugal air movement in HVAC, combustion, and process ventilation with quadratic torque curves suited to variable speed efficiency gains.
- Conveyors:Bulk material handling systems in mining and aggregate operations, concentrated in the Canadian Prairies and U.S. Mountain West where commissioning technician scarcity extends project timelines.
Pump applications dominate historical deployment by unit count. Compressor retrofits represent the fastest-climbing segment as petrochemical capacity expansion accelerates across the Gulf Coast corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the U.S. Gulf Coast petrochemical corridor while Canadian utilities extract sharper procurement terms through provincial decarbonization funds. This asymmetry shapes how manufacturers allocate technical resources and channel support across North American territories.
United States
EPA energy efficiency mandates under the Energy Policy Act and NEMA MG1 regulations accelerate VFD retrofit cycles across manufacturing floors. FERC interconnection standards tighten harmonic emission limits in Texas ERCOT and California CAISO territories. Gulf Coast petrochemical facilities in Houston and Corpus Christi front-load capital budgets to capture polyethylene capacity expansion demand.
Canada
Ontario and British Columbia carbon reduction procurement mandates create dedicated funding streams for municipal VFD retrofits in HVAC and water infrastructure. CSA C390 energy verification protocols govern market access and product certification requirements. Prairie Provinces face skilled commissioning technician scarcity that extends project timelines and inflates implementation costs.
Mexico
Nearshoring manufacturing expansion drives specification volume for integrated motor-drive packages with Ethernet/IP connectivity in automotive assembly plants. CFE grid interconnection rules shape harmonic compliance requirements for heavy industrial loads. Northern Border States concentrate demand as Tier 1 suppliers retrofit material handling and machining lines.
North America Variable Frequency Drive Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the North America Variable Frequency Drive landscape. Integrated power electronics manufacturers with silicon-to-systems capabilities capture margin pools in medium-voltage portfolios, while assembly-focused competitors compete on fulfillment velocity in low-voltage replacement cycles. Three archetypes dominate: vertically integrated semiconductor-to-drive specialists, embedded software-centric automation platforms, and distributor-anchored volume suppliers. Competitive moves center on backward integration into power module fabrication and strategic partnerships with utility rebate program administrators.
Among European-based industrial conglomerates, ABB and Siemens occupy positions exemplifying integrated power electronics depth, while Rockwell Automation represents the embedded software-centric automation platform archetype. These three anchors illustrate how competitive positioning diverges between component-cost control and motion control algorithm sophistication.
| Leading Market Players |
|---|
| ABB |
| Rockwell Automation |
| Danfoss |
| Siemens |
| Eaton |
| Schneider Electric |
| Yaskawa America |
| Phase Technologies |
| WEG |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide module substitution for conventional IGBT power stages is redrawing procurement geography and compressing cost structures across medium-voltage drive portfolios. This materials transition simultaneously fragments supplier hierarchies and erodes the cost advantages of integrated manufacturers who lack captive semiconductor fabrication.
Pricing Analysis
Configured-to-order pricing for active front-end medium-voltage drives commands substantial premiums over standard six-pulse rectifier units. Three-tier pricing structure across premium, standard, and economy levels reflects UL 508C certification status, embedded software capability depth, and after-sales service bundling. Pricing pressure stems from East Asian power module foundries capturing margin pools previously held by drive assemblers. Municipal water utilities exhibit highest price sensitivity due to public procurement constraints, while Gulf Coast petrochemical operators prioritize lifecycle cost optimization over upfront capital outlay.
Supply Chain Analysis
China, Taiwan, and South Korea anchor power semiconductor fabrication for IGBT and silicon carbide modules serving North American drive manufacturers. Silicon wafers, copper busbar assemblies, and aluminum heat sinks constitute critical input dependencies. Single-source vulnerability concentrates in 1700V+ SiC MOSFET die supply from Taiwanese foundries. Distribution runs through authorized electrical distributor networks for low-voltage replacement cycles, while medium-voltage project flows bypass traditional channels through direct OEM and systems integrator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Variable Frequency Drive market functions as a defensive-moat arena where regulatory entrenchment creates durable switching costs. NEMA MG1 and IEEE 519 compliance requirements lock in specification authority for incumbents with certified product portfolios and established utility rebate program relationships.
For Market Incumbents: Secure backward integration into power module packaging capabilities to offset East Asian foundry pricing power and protect medium-voltage margins. Deepen embedded software differentiation in integrated motion control platforms to raise switching costs for Rockwell Automation's installed base. Counter silicon carbide specialists by accelerating active front-end topology development ahead of FERC interconnection rule tightening.
For New Entrants and Emerging Players: Differentiate on edge analytics convergence by bundling vibration monitoring with predictive maintenance platforms for Permian Basin oil and gas operators. Target Canadian provincial decarbonization procurement streams in Ontario and British Columbia where funding mechanisms reduce price sensitivity. Pursue direct-to-utility channel development bypassing electrical distributor networks in California and New York metro commercial HVAC retrofits.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors semiconductor-to-systems specialists with captive power module capabilities. Long-term viability over the projection horizon rests on regulatory compliance entrenchment and software-defined service revenue expansion. Acquisition candidates should demonstrate UL 508C certification breadth and embedded firmware differentiation. Monitor IEEE 519 enforcement intensity across Texas ERCOT and California CAISO territories as inflection indicator for active front-end adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Module Fabrication | Captures margin pools from East Asian foundries and insulates against SiC supply volatility. |
| Active Front-End Topology Development | Pre-empts FERC interconnection compliance deadlines across Texas and California utility territories. |
| Edge Analytics Platform Integration | Opens recurring revenue streams in Permian Basin electric submersible pump applications. |
| Direct-to-Utility Channel Development | Bypasses electrical distributor markups in California and New York commercial building retrofits. |
| Provincial Decarbonization Procurement Alignment | Captures Ontario and British Columbia municipal funding streams for water infrastructure VFD retrofits. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and utility planning officers anchored the qualitative base for this study. Primary fieldwork across the U.S. Gulf Coast petrochemical corridor, Canadian Prairies water utilities, and Midwest manufacturing floors combined with secondary validation from FERC interconnection filings, EPA enforcement databases, NEMA technical standards, and SEC 10-K disclosures from publicly traded automation suppliers. Bottom-up unit shipment estimates triangulated against top-down capital expenditure projections across water infrastructure and process industry segments.
Sensitivity analysis tested forecast robustness across alternative scenarios for semiconductor supply normalization and regulatory enforcement intensity. The analytical framework modeled volume and value outputs across product type, end user, control technology, and application dimensions throughout the forecast period. CAGRs derived from regression against historical retrofit cycle timing, efficiency mandate phase-in schedules, and petrochemical capacity expansion announcements. Key inputs included IEEE 519 compliance cost curves and provincial decarbonization fund allocation trajectories.
Decision-makers should treat outputs as directional under stable FERC interconnection rule implementation and continued East Asian semiconductor supply access; material deviation in either assumption would warrant model refresh. Recalibration cycles align with material shifts in EPA enforcement priorities, CSA C390 certification requirement updates, and silicon carbide foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
BCD Power IC Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Medium Voltage Drives Market
Power Systems
Electrical and Automation System Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Buck-Boost Controller Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Thyristor Market
Power Systems
Synchronous Condenser Market
Power Systems
DC-DC Converter Market