
 Asia-Pacific Automotive DC-DC Converters Market | 2026-2036
Asia-Pacific Automotive DC-DC Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive DC-DC Converters Market Outlook
A wide capability gap in silicon carbide packaging and thermal management is redrawing competitive tiers across the Asia-Pacific Automotive DC-DC Converters Market. Denso Corporation leverages its captive semiconductor division to sustain vertical control over substrate sourcing and module assembly. Infineon Technologies anchors its position through dedicated SiC foundry partnerships with Japanese and Korean module integrators. Bosch competes by extending its power electronics R&D footprint into Chinese joint ventures with local OEMs.
Asia-Pacific automotive DC-DC converters are power-electronic modules that transform high-voltage battery output into stable low-voltage rails for auxiliary systems, typically operating at efficiency thresholds above 94% in 400V architectures and above 96% in 800V platforms to minimize thermal loss during energy transfer. Their primary purpose is to protect sensitive vehicle electronics from voltage transients while enabling the 12V or 48V subsystem loads that control infotainment, lighting, and chassis functions. Isolated converter topologies dominate current OEM specifications due to their inherent galvanic separation between high-voltage and low-voltage domains, though non-isolated designs are gaining traction in cost-optimized hybrid platforms where space constraints override safety redundancy. Gallium nitride technology leads the fastest-growing technology tier, displacing silicon MOSFETs in premium electric vehicle programs where switching frequency directly reduces magnetics volume and cooling mass.
China's MIIT enforces GB standards for electromagnetic compatibility and functional safety in automotive power electronics, while Japan's METI coordinates JIS certification pathways that module suppliers must complete for domestic OEM qualification. South Korea's MFDS-aligned automotive safety framework and India's BIS compulsory registration scheme for electronic components together create a multi-jurisdictional compliance burden that favors suppliers with regional testing laboratories. Stakeholders must monitor how China's SAMR interprets evolving dual carbon goals into procurement mandates for domestic converter content, as this determines whether foreign module makers can maintain access to the region's largest demand pool without local manufacturing joint ventures.
Market Dynamics
Silicon carbide packaging capability is concentrating procurement power among vertically integrated suppliers across China's Yangtze River Delta, where captive semiconductor fabrication determines converter qualification timelines for battery-electric platforms.
Growth Catalysts
- Dual carbon goals:China's SAMR procurement mandates for domestic converter content accelerate localized module production and joint venture formation.
- Gallium nitride switching:Premium electric vehicle programs adopt GaN transistors to reduce magnetics volume and cooling mass in 800V architectures.
- India's PLI scheme:Automotive manufacturing incentives draw tier-1 suppliers to establish converter assembly operations near Chennai and Pune.
Market Restraints
- Substrate supply concentration:Silicon carbide wafer production clusters in Japanese and Korean foundries, exposing converters to allocation constraints.
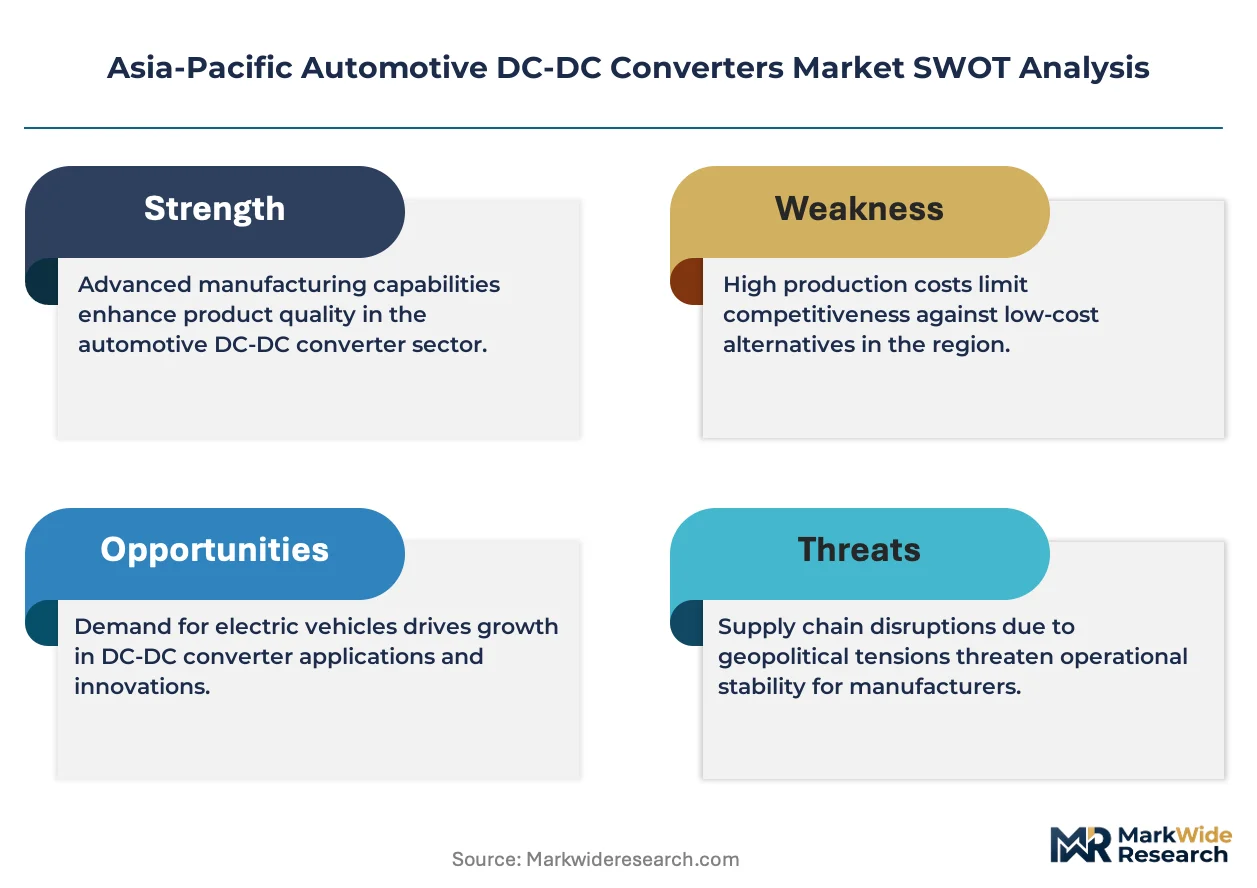
- Multi-jurisdictional compliance:China's GB standards, Japan's JIS certification, and South Korea's MFDS-aligned frameworks create redundant testing burdens without mutual recognition.
- Thermal management cost:High-efficiency targets above 96% in 800V platforms require exotic ceramic substrates and liquid cooling loops that inflate bill-of-materials costs.
Strategic Opportunities
- Non-isolated topologies:Cost-optimized hybrid platforms in Southeast Asia adopt simplified converter designs where space constraints override galvanic separation requirements.
- 48V auxiliary rails:Mild-hybrid architectures in Japan and South Korea create incremental demand for intermediate voltage conversion modules.
- Regional testing laboratories:Suppliers investing in BIS-accredited facilities in India bypass certification delays for subcontinent OEM qualification.
Industry Challenges
- Power electronics talent scarcity:Module integrators in China compete for analog design engineers capable of optimizing switching losses in wide-bandgap semiconductors.
- Legacy 12V integration:Converter suppliers must maintain backward compatibility with established lighting and infotainment subsystems while scaling high-voltage inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive DC-DC Converters Market |
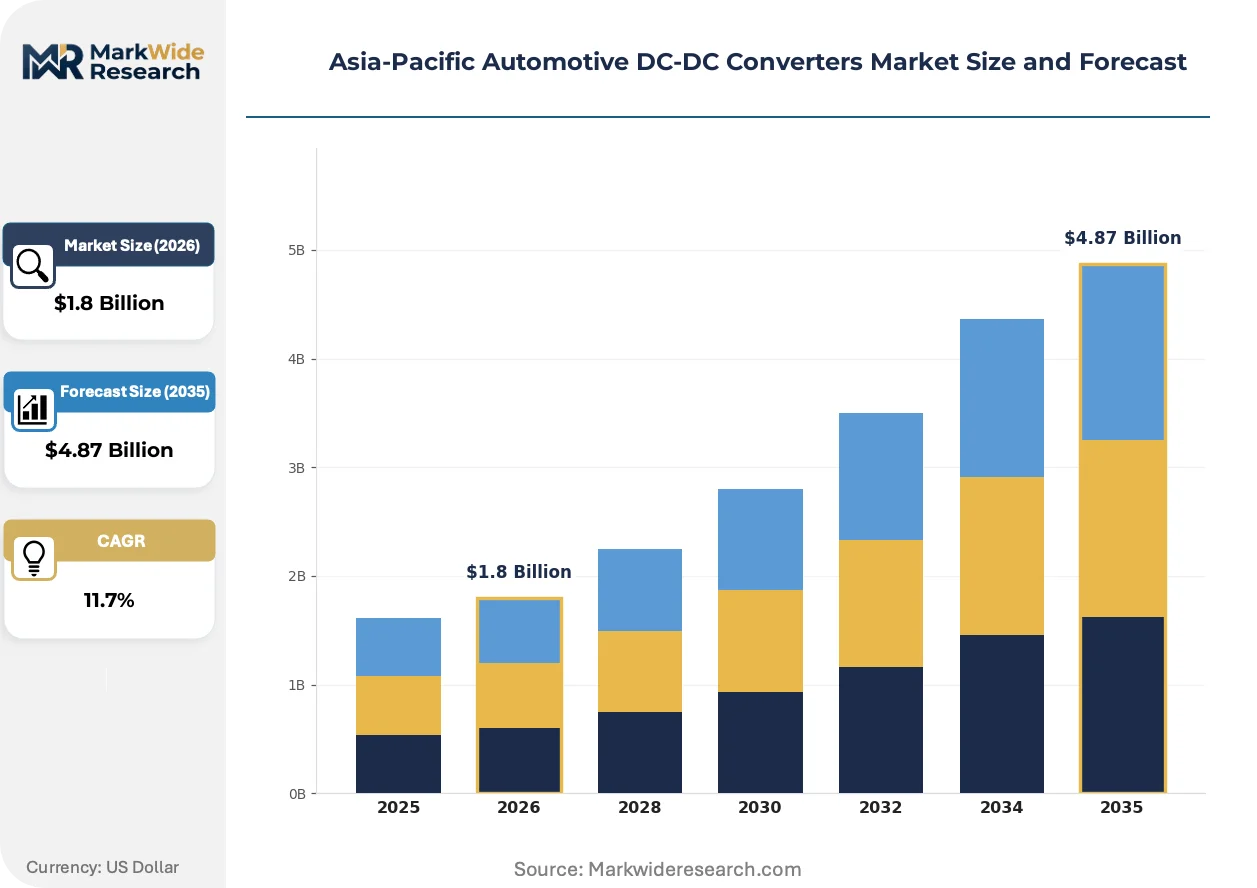
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolated, Non-Isolated, Step-Up, Step-Down Application: Electric Vehicles, Hybrid Vehicles, Starting Systems, Battery Management Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Silicon, GaN, SiC, Integrated |
| Companies Covered | Denso Corporation, Infineon Technologies, Continental AG, Bosch, Toyota Industries Corporation, Renesas Electronics Corporation, Hyundai Mobis, Delta Electronics, Mitsubishi Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive DC-DC Converters Market Strategic Shifts
Gallium nitride semiconductors are compressing converter form factors while regulatory pressure on electromagnetic compatibility tightens qualification protocols across the region.
GaN transistors is displacing silicon MOSFETs in 800V electric vehicle platforms where switching frequencies above 100kHz enable smaller inductors and reduced thermal mass. Japanese and Korean OEMs specify GaN modules for premium battery-electric powertrains. This displacement is compressing the cost gap between silicon and wide-bandgap solutions.
China's MIIT enforces updated GB/T standards for electromagnetic compatibility in automotive power electronics, mandating conducted and radiated emission limits that exceed prior thresholds. Module suppliers must redesign filter networks and shielding topologies to achieve compliance. Domestic OEMs in the Yangtze River Delta cluster prioritize pre-certified converters to accelerate vehicle homologation.
Direct sourcing agreements between OEMs and substrate manufacturers are fragmenting traditional tier-1 supplier relationships. Converter assemblers in South Korea and Japan now compete with their own component vendors for silicon carbide wafer allocation. This pattern concentrates most visibly in China's state-owned vehicle enterprises, where procurement departments negotiate long-term supply contracts independently of module integrators.
Asia-Pacific Automotive DC-DC Converters Market Segmentation
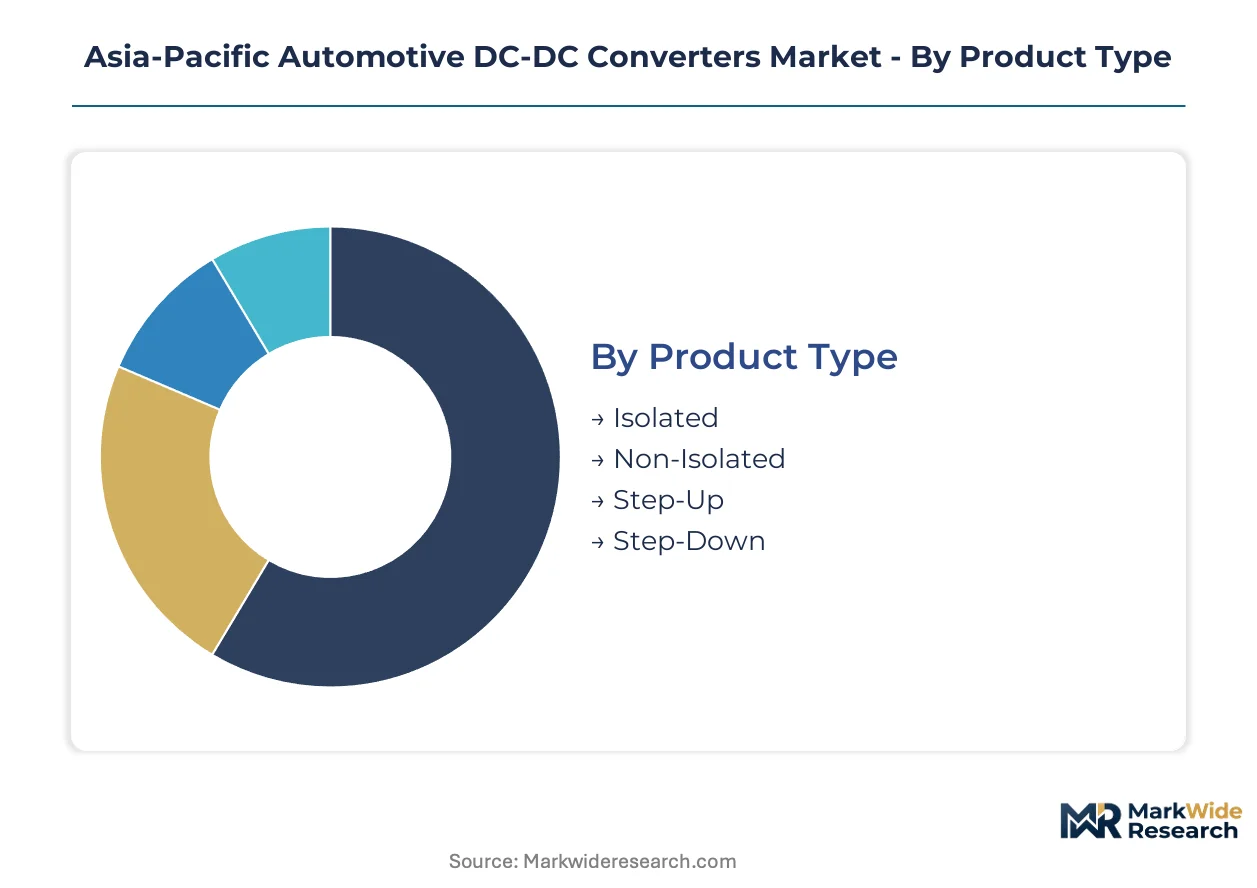
Converter segmentation in Asia-Pacific reflects divergent technical requirements across 400V and 800V architectures. Procurement patterns vary sharply between state-backed Chinese OEMs and Japanese-Korean premium platforms.
Product Type:
Substitution pressure runs highest against legacy silicon-based modules as wide-bandgap alternatives achieve cost parity in high-volume programs.
- Isolated:Galvanic separation between high-voltage and low-voltage domains protects sensitive vehicle electronics from transients. China's Yangtze River Delta OEMs specify isolated topologies for all battery-electric platforms under MIIT safety guidelines.
- Non-Isolated:Simplified architectures eliminate transformer windings to reduce magnetics volume and assembly cost. Southeast Asian hybrid programs adopt these designs where space constraints override redundant safety separation.
- Step-Up:Boost converters raise auxiliary rail voltages for 48V mild-hybrid subsystems.
- Step-Down:Buck topologies dominate 12V legacy integration for lighting and infotainment loads.
Isolated converters anchor the volume base while non-isolated designs gain share at the steepest rate.
Application:
Cost tier differentiation separates premium battery-electric specifications from cost-optimized hybrid implementations across the region.
- Electric Vehicles:Full battery-electric platforms demand 800V-capable modules with efficiency thresholds above 96%. Japanese and Korean OEMs prioritize GaN switching to minimize cooling mass in premium powertrains.
- Hybrid Vehicles:Dual-voltage architectures require intermediate conversion stages between combustion and electric subsystems. Indian OEMs near Chennai source locally assembled converters under PLI scheme incentives.
- Starting Systems:Traditional 12V cranking applications persist in internal combustion legacy platforms.
- Battery Management Systems:Cell balancing and monitoring circuits require precision voltage references.
Electric vehicle applications dominate procurement value while hybrid vehicle demand expands most quickly across Southeast Asian manufacturing hubs.
End User:
Customer type determines qualification burden, with captive semiconductor capabilities separating vertically integrated OEMs from module-dependent suppliers.
- OEMs:Vehicle manufacturers with in-house power electronics divisions specify proprietary converter architectures. Chinese state-owned enterprises negotiate direct substrate contracts, fragmenting traditional tier-1 relationships.
- Tier-1 Suppliers:Module integrators compete for silicon carbide wafer allocation against their own component vendors. Denso's captive semiconductor division sustains supply security independent of external foundries.
- Aftermarket Providers:Replacement converters for legacy vehicle parc face less stringent electromagnetic compatibility testing.
- Fleet Operators:Commercial vehicle aggregators specify standardized converter platforms across multi-brand deployments.
OEMs control the highest-margin procurement while tier-1 suppliers face the steepest margin compression from substrate supply constraints.
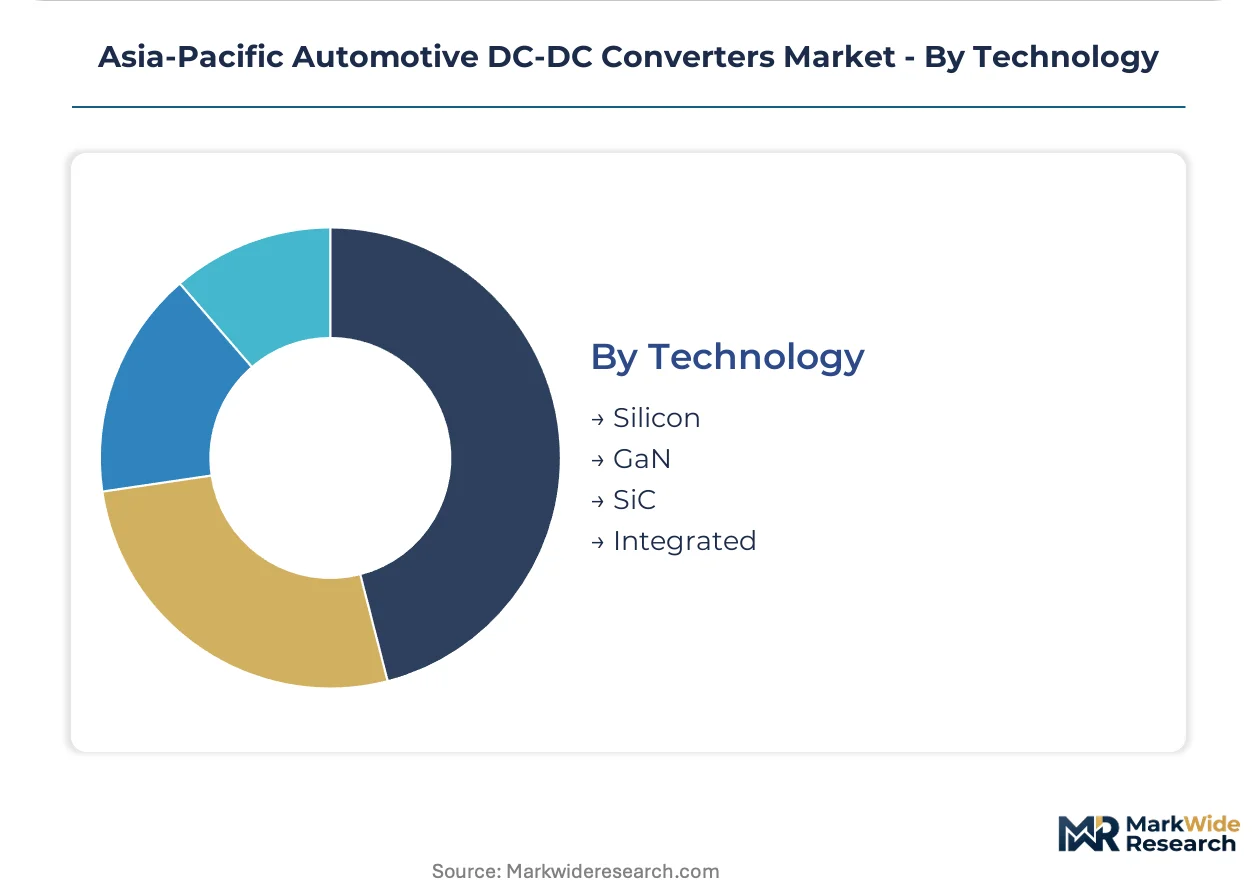
Technology:
Supply concentration in Japanese and Korean foundries shapes technology adoption timelines for module assemblers throughout the region.
- GaN:Gallium nitride transistors enable switching frequencies above 100kHz, compressing inductor volume and thermal mass. Premium Japanese and Korean battery-electric programs specify GaN for 800V architectures where magnetics reduction justifies device cost premiums.
- SiC:Silicon carbide modules sustain efficiency above 94% in 400V platforms with superior thermal performance. Substrate supply concentrates in Japanese and Korean foundries, exposing converters to allocation bottlenecks.
- Silicon:Mature MOSFET technology retains cost advantage in 12V legacy integration.
- Integrated:Monolithic power stages combine gate drivers and protection circuits in single packages.
Silicon technology retains the largest installed base while GaN climbs the fastest as cost gaps compress against wide-bandgap alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan and South Korea where captive semiconductor fabrication commands premium converter valuations, while Chinese assemblers compete on scale despite substrate import dependencies. This asymmetry shapes procurement patterns across the region's battery-electric supply chains.
China
Domestic OEMs in the Yangtze River Delta cluster source high-voltage DC-DC modules for 800V architectures under MIIT's GB/T electromagnetic compatibility mandates. SAMR procurement directives tied to dual carbon goals require localized content, accelerating joint venture formation between foreign tier-1 suppliers and state-owned vehicle enterprises. Shanghai and Suzhou host co-located semiconductor packaging and converter assembly operations.
Japan
Japanese OEMs specify GaN-based converters for premium battery-electric powertrains, prioritizing magnetics reduction over device cost premiums. METI coordinates JIS certification pathways that module suppliers must complete for domestic qualification, extending development timelines. Nagoya and Tokyo metropolitan areas concentrate tier-1 R&D facilities and captive semiconductor divisions.
South Korea
Korean battery-electric platforms drive demand for SiC modules with efficiency thresholds above 96%, sourced through direct substrate agreements with domestic foundries. MFDS-aligned automotive safety frameworks impose redundant testing requirements without mutual recognition with neighboring jurisdictions. Seoul and Busan-Ulsan industrial corridors anchor module integrator operations.
India
PLI scheme incentives draw tier-1 suppliers to establish converter assembly near Chennai and Pune for hybrid vehicle programs. BIS compulsory registration for electronic components creates certification bottlenecks that favor suppliers with accredited regional laboratories. Domestic OEMs source step-down modules for 12V legacy integration in cost-optimized architectures.
Thailand
Southeast Asian hybrid manufacturing hubs adopt non-isolated converter designs where space constraints override galvanic separation requirements. Japanese and Korean OEMs operating export-oriented assembly plants specify intermediate voltage conversion modules for dual-voltage architectures. Bangkok and Eastern Economic Corridor provinces concentrate tier-2 component sourcing.
Asia-Pacific Automotive DC-DC Converters Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Automotive DC-DC Converters Market. Vertically integrated OEMs with captive semiconductor divisions control substrate allocation and module qualification timelines, while independent tier-1 suppliers compete for foundry access and design wins. The competitive landscape stratifies into three archetypes: captive integrators with in-house wafer sourcing, fabless specialists relying on external foundry partnerships, and diversified industrial conglomerates leveraging power electronics R&D scale. Dominant competitive moves include backward integration into substrate supply and geographic expansion through manufacturing joint ventures in China and India.
Among Japanese and Korean captive integrators, Denso Corporation and Hyundai Mobis exemplify the vertically controlled archetype with in-house semiconductor operations that insulate converter supply from external allocation constraints. Infineon Technologies anchors the fabless specialist tier through dedicated SiC foundry partnerships with regional module assemblers. Bosch represents the diversified conglomerate archetype, extending power electronics development footprints into Chinese joint ventures to secure OEM qualification pathways.
| Leading Market Players |
|---|
| Denso Corporation |
| Infineon Technologies |
| Continental AG |
| Bosch |
| Toyota Industries Corporation |
| Renesas Electronics Corporation |
| Hyundai Mobis |
| Delta Electronics |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Wafer fabrication scale economies in Japanese and Korean foundries concentrate substrate bargaining power among vertically integrated OEMs, compressing margin floors for module assemblers dependent on external SiC supply. This asymmetry propagates through converter pricing tiers, where captive semiconductor capabilities command premium valuations against fabless competitors.
Pricing Analysis
Configured-to-order GaN modules for 800V platforms command substantial premiums over standard SiC offerings for 400V architectures. Pricing stratifies across premium, standard, and economy tiers based on efficiency certification thresholds and thermal performance grade. Cost compression in hybrid-vehicle segments intensifies because Indian and Southeast Asian OEMs prioritize bill-of-materials reduction over switching frequency. Fleet operators exhibit highest price sensitivity due to standardized multi-brand deployments, while Japanese premium OEMs prioritize magnetics reduction over device cost.
Supply Chain Analysis
Japan and South Korea anchor silicon carbide wafer fabrication, while China's Yangtze River Delta concentrates module packaging and converter assembly. Converter production draws from SiC substrates, ceramic thermal management materials, and magnetics copper windings. Single-source vulnerability runs through Japanese substrate foundries exposed to allocation constraints during battery-electric platform ramp-ups. Distribution runs through tier-1 supplier networks co-located with OEM engineering centers for qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor displacement constitutes a high-growth disruption reshaping competitive tiers, with GaN adoption in 800V architectures and China's dual carbon procurement mandates serving as the primary inflection points.
For Market Incumbents: Secure captive semiconductor supply through upstream substrate agreements or joint venture foundry partnerships to insulate against allocation bottlenecks. Denso's vertical control model demonstrates how in-house wafer sourcing defends margin position against fabless competitors. Prioritize BIS-accredited testing laboratory investment in India to bypass certification delays under the PLI scheme. For New Entrants and Emerging Players: Lead with non-isolated converter designs for Southeast Asian hybrid platforms where space constraints override galvanic separation requirements and incumbent qualification burdens are lightest. Target India's Chennai-Pune manufacturing corridor for assembly operations under automotive manufacturing incentives. Pursue direct OEM engineering relationships rather than tier-1 supplier channel dependence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-1 suppliers with certified module platforms locked into multi-year OEM supply agreements. Long-term viability over the next decade hinges on SiC packaging capability and regional regulatory accreditation breadth. Monitor China's SAMR interpretation of dual carbon goals into procurement mandates as the critical signal for foreign market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures substrate allocation independent of external wafer supply constraints. |
| Regional Testing Laboratory Accreditation | BIS certification in India accelerates OEM qualification timelines under PLI incentives. |
| GaN Module Platform Launch | Magnetics reduction in 800V architectures justifies premium positioning against SiC alternatives. |
| Joint Venture Manufacturing Formation | Localized content compliance under China's SAMR dual carbon mandates preserves market access. |
| Non-Isolated Topology Development | Cost-optimized designs capture Southeast Asian hybrid vehicle procurement outside incumbent strongholds. |
Study Parameters
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, semiconductor foundry operations managers, and automotive regulatory affairs directors anchored the qualitative base. These primary insights combined with secondary validation from MIIT GB standard filings, METI JIS certification databases, vehicle production registration data, and SEC disclosures from listed component suppliers. Bottom-up module shipment estimates triangulated against top-down OEM platform forecasts across the analysis window.
Sensitivity analysis tested forecast robustness across adoption scenarios for 800V architectures and GaN penetration curves. Segmentation dimensions modeled include propulsion architecture, voltage platform, isolation topology, and regional production cluster. CAGRs derived from fitted growth curves applied to technology-specific adoption phases, with inputs from power electronics talent availability and substrate capacity expansion announcements.
Forecasts assume regulatory continuity in China's SAMR procurement mandates, Japan's METI certification pathways, and India's BIS registration schemes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Grid Tie Inverter Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Europe Micro Inverter Market
Power Systems
HVDC Converters Market
Power Systems
Shunt Voltage References Market
Power Systems
Global Inverter Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Modular Inverter Market
Power Systems
Automotive Power Semiconductor Market