
 Buck-Boost Controller Market | 2026-2036
Buck-Boost Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Buck-Boost Controller Market Insights
Automotive OEMs is rotating share away from traditional consumer-electronics buyers as 800-volt EV platforms proliferate. Texas Instruments leverages its integrated gate-driver portfolio to anchor design wins across mild-hybrid and full-electric architectures. Infineon Technologies dominates silicon-carbide MOSFET pairings that enable higher switching frequencies in traction inverters. STMicroelectronics competes through module-level integration that reduces BOM count for tier-one suppliers.
A buck-boost controller is a DC-DC power converter that maintains regulated output voltage regardless of whether the input sits above or below the target, typically operating across input ranges from 2.5 V to 100 V with switching frequencies between 100 kHz and 3 MHz to serve battery-fed systems where source voltage fluctuates. Non-isolated converters lead unit shipments because of lower cost and footprint in portable electronics, yet isolated variants capture disproportionate margin pools in medical and industrial safety-critical installations. Battery management systems represent the fastest-growing application segment as lithium-ion pack voltages scale and cell-balancing circuits demand bidirectional current control.
The U.S. EPA and NHTSA coordinate fuel-economy and emissions rules that indirectly mandate regenerative-braking efficiency, while the EU F-Gas Regulation and Ecodesign standards constrain auxiliary power losses in HVAC and thermal management. China's GB standards and MIIT directives enforce domestic EV charging-interface compatibility that shapes controller pinout and protection-feature requirements. Stakeholders must monitor how regional efficiency thresholds diverge and whether to qualify single platforms across multiple certification regimes or fragment SKUs by geography.
Market Dynamics
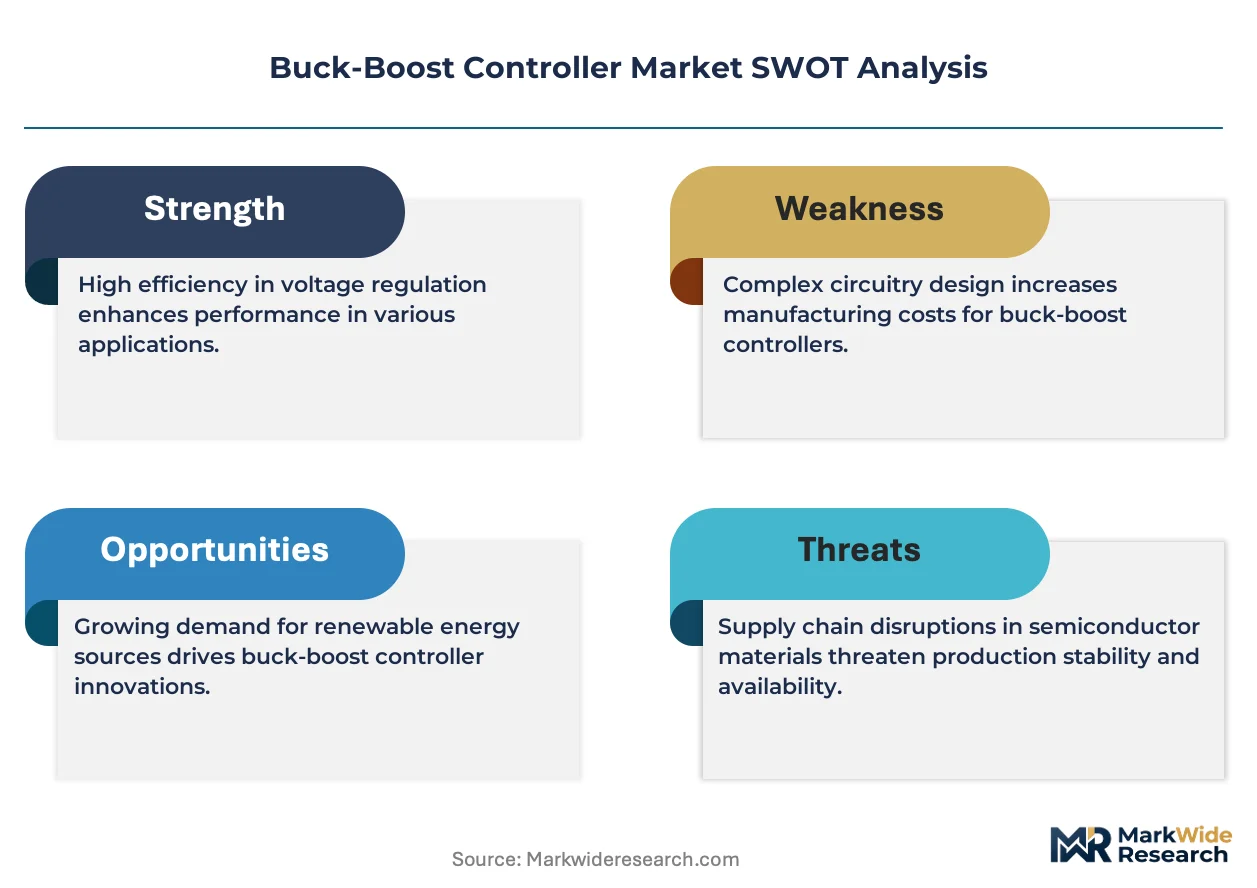
Silicon-carbide MOSFET adoption is compressing switching losses and forcing legacy silicon-based controller architectures into obsolescence across traction inverter and onboard charger applications.
Growth Catalysts
- EU Ecodesign Directive:Standby-loss thresholds below 0.5 W are mandating topology upgrades in HVAC auxiliary power units across European appliance manufacturing.
- Battery management systems:Bidirectional current control requirements in lithium-ion packs are pulling controller demand from EV and stationary storage OEMs.
- China MIIT directives:Domestic GB standards for EV charging-interface compatibility are standardizing protection-feature specifications across tier-one automotive suppliers.
Market Restraints
- Silicon-carbide substrate costs:Wafer scarcity and epitaxy bottlenecks are inflating BOM costs for wide-bandgap controller designs versus silicon alternatives.
- Foundry concentration in Taiwan:Advanced node capacity constraints are extending lead times for integrated gate-driver controllers destined for automotive qualification.
- Thermal management complexity:Higher switching frequencies from SiC adoption are demanding advanced cooling architectures that offset footprint advantages.
Strategic Opportunities
- Industrial microgrids:Bidirectional DC-DC conversion for solar-plus-storage installations in Germany and Australia is opening controller sockets outside automotive.
- Medical isolation requirements:Reinforced isolation ratings for patient-contact equipment are creating margin pools in diagnostic imaging and surgical robotics.
- GaN-SiC convergence:Hybrid topologies pairing gallium-nitride switches with silicon-carbide diodes are enabling MHz-range frequencies in compact adapter designs.
Industry Challenges
- Automotive functional safety:ISO 26262 ASIL-D certification timelines are extending 18-24 months for new controller platforms targeting EV traction systems.
- Packaging expertise scarcity:Thermally enhanced QFN and power-module design capabilities are concentrated among a narrow pool of analog semiconductor veterans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buck-Boost Controller Market |
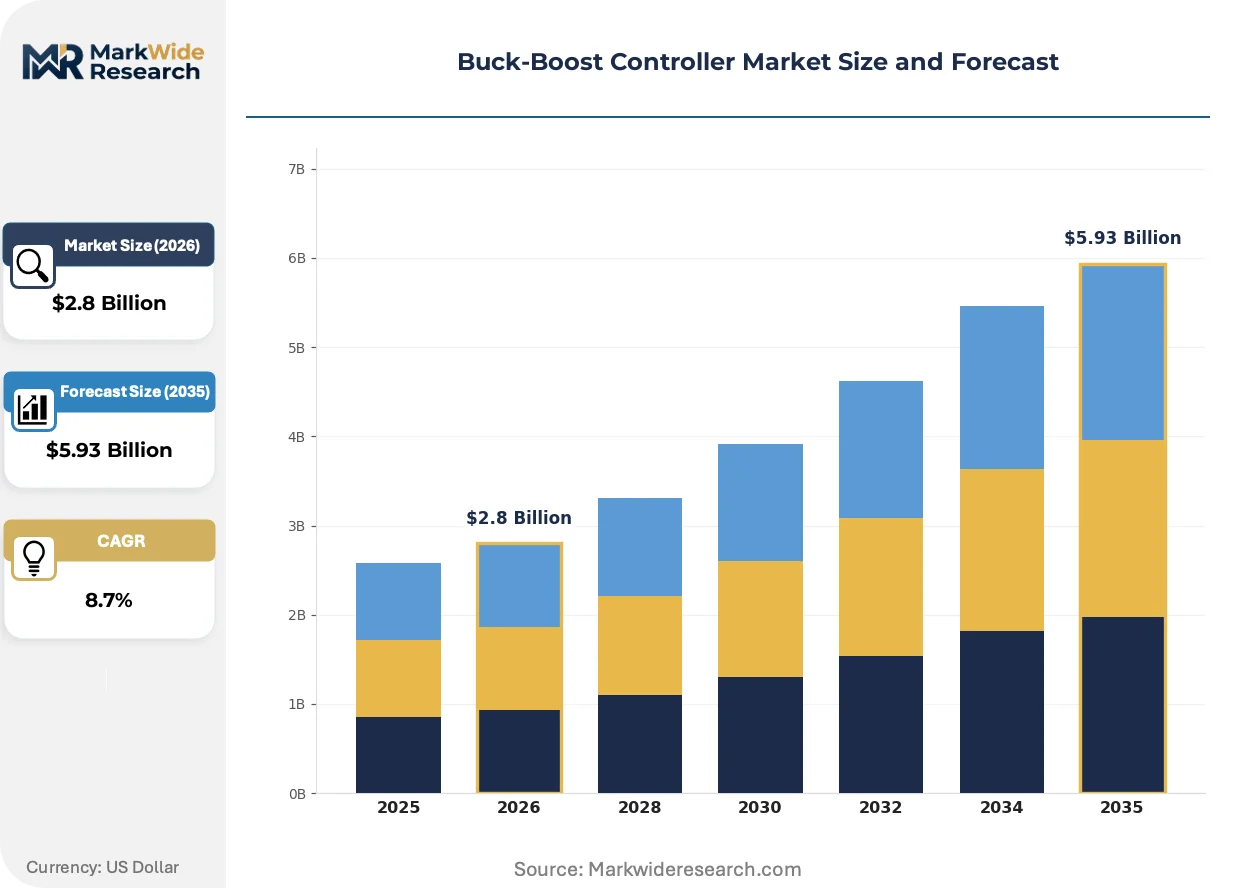
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-Up Converter, Step-Down Converter, ISOLATED Converter, Non-ISOLATED Converter Component: Inductor, Capacitor, Diode, MOSFET Application: Electric Vehicles, Renewable Energy Systems, Power Supplies, Battery Management Systems End User: Automotive, Consumer Electronics, Industrial Automation, Telecommunications |
| Companies Covered | Texas Instruments, Analog Devices, Infineon Technologies, STMicroelectronics, Renesas Electronics, NXP Semiconductors, Microchip Technology, ROHM, Vicor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buck-Boost Controller Market Trends and Innovations
Controller architectures are fragmenting between discrete multi-chip implementations and highly integrated power-stage modules as end-users optimize for either flexibility or time-to-market.
Silicon-carbide power stages are decomposing traditional two-stage conversion chains in onboard chargers. EV manufacturers in Germany and South Korea are adopting single-stage buck-boost topologies for 800-volt to 12-volt conversion. This compression is eliminating intermediate bus capacitors and shrinking magnetic component volume by half.
The U.S. Department of Energy's appliance efficiency standards are mandating minimum power-factor-correction performance in residential HVAC equipment. Controller vendors must now integrate active PFC stages with buck-boost regulation in single ICs. Residential heat-pump OEMs in the Midwest and Southeast are qualifying these integrated solutions for seasonal energy-efficiency ratio compliance.
Direct sourcing contracts between automotive OEMs and semiconductor foundries are bypassing traditional distribution channels. Tier-one inverter suppliers in China are negotiating wafer allocations directly with TSMC and GlobalFoundries. This disintermediation is compressing gross margins for authorized distributors while securing supply certainty for high-volume EV platforms.
Buck-Boost Controller Market Segmentation
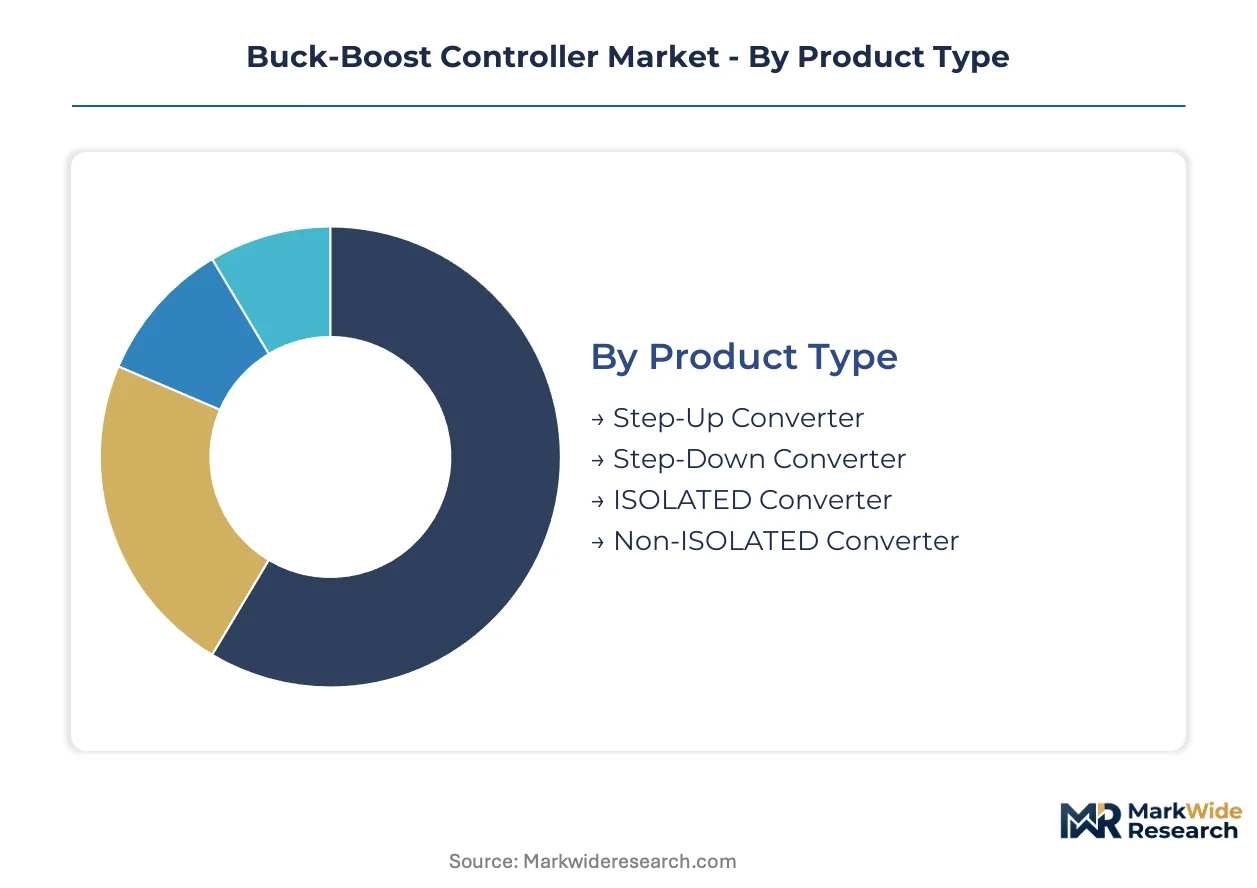
Buck-boost controller procurement channels diverge sharply by segment—automotive OEMs negotiate direct foundry contracts while industrial buyers route through authorized distributors. Understanding these channel dynamics reveals where margin pools concentrate and which segments justify dedicated sales force deployment.
Product Type:
Non-isolated converters move through high-volume electronics distributors serving consumer and industrial accounts, while isolated variants channel through specialized medical and aerospace distributors with certification documentation capabilities.
- Step-Up Converter:Boost-only architectures operate when input voltage sits below output requirements, employing single-switch topologies with simplified gate-drive requirements. Demand clusters in portable electronics supply chains across Shenzhen and Dongguan manufacturing clusters, constrained by voltage-stress limitations in high-ratio applications.
- Step-Down Converter:Buck-only designs dominate where input voltage exceeds output needs, achieving higher efficiency through reduced switch-node voltage stress. Automotive 12-volt auxiliary systems in Germany and Japan anchor procurement volumes, pressured by load-transient response requirements under start-stop cycling.
- ISOLATED Converter:Transformer-coupled designs with reinforced insulation ratings serve patient-contact medical equipment and grid-tied solar inverters.
- Non-ISOLATED Converter:Single-inductor architectures capture unit volume in smartphones, tablets, and IoT edge devices through cost-optimized QFN packages.
Non-ISOLATED Converter dominates installed base. ISOLATED Converter is where expansion concentrates.
Component:
Component selection determines whether controllers ship as discrete multi-chip boards or integrated power modules, with discrete implementations carrying 40-60% lower ASPs but requiring longer customer design cycles.
- Inductor:Magnetic components store and transfer energy across switching cycles, with ferrite-core designs dominating below 1 MHz and powder-core materials penetrating higher-current EV applications. Tier-one automotive suppliers in South Korea are qualifying molded inductors for 150°C ambient operation under hood.
- MOSFET:Power transistors switch current at frequencies from 100 kHz to 3 MHz, with silicon-carbide devices displacing silicon in 800-volt traction inverters. Infineon and STMicroelectronics are shipping automotive-qualified SiC MOSFETs with integrated anti-parallel diodes to reduce parasitic inductance.
- Capacitor:Ceramic and aluminum electrolytic technologies filter ripple current and stabilize control loops across load transients.
- Diode:Freewheeling and synchronous rectification diodes manage reverse recovery in hard-switching topologies.
MOSFET captures the steepest expansion trajectory as wide-bandgap adoption accelerates. Inductor retains the largest cumulative design-in footprint across legacy platforms.
Application:
Application segmentation reveals divergent customer technical support requirements—EV traction systems demand 18-24 month qualification support while power supply customers prioritize rapid sample turnaround.
- Battery Management Systems:Bidirectional current control enables cell balancing and state-of-charge estimation across lithium-ion packs operating from 48 volts to 800 volts. Stationary storage OEMs in Australia and Germany are specifying controllers with sub-1% current-sense accuracy for grid-frequency regulation services.
- Electric Vehicles:Onboard chargers and DC-DC converters bridge high-voltage traction batteries to 12-volt auxiliary networks, with 800-volt architectures eliminating intermediate conversion stages. Chinese EV manufacturers are adopting single-stage buck-boost topologies to shrink magnetic component volume by half.
- Renewable Energy Systems:Solar inverters and energy storage interfaces require wide input-range operation across varying irradiance conditions.
- Power Supplies:Adapter and server PSU applications prioritize power density and active power-factor correction integration.
Power Supplies dominates cumulative shipment volume. Battery Management Systems is where design-win activity concentrates.
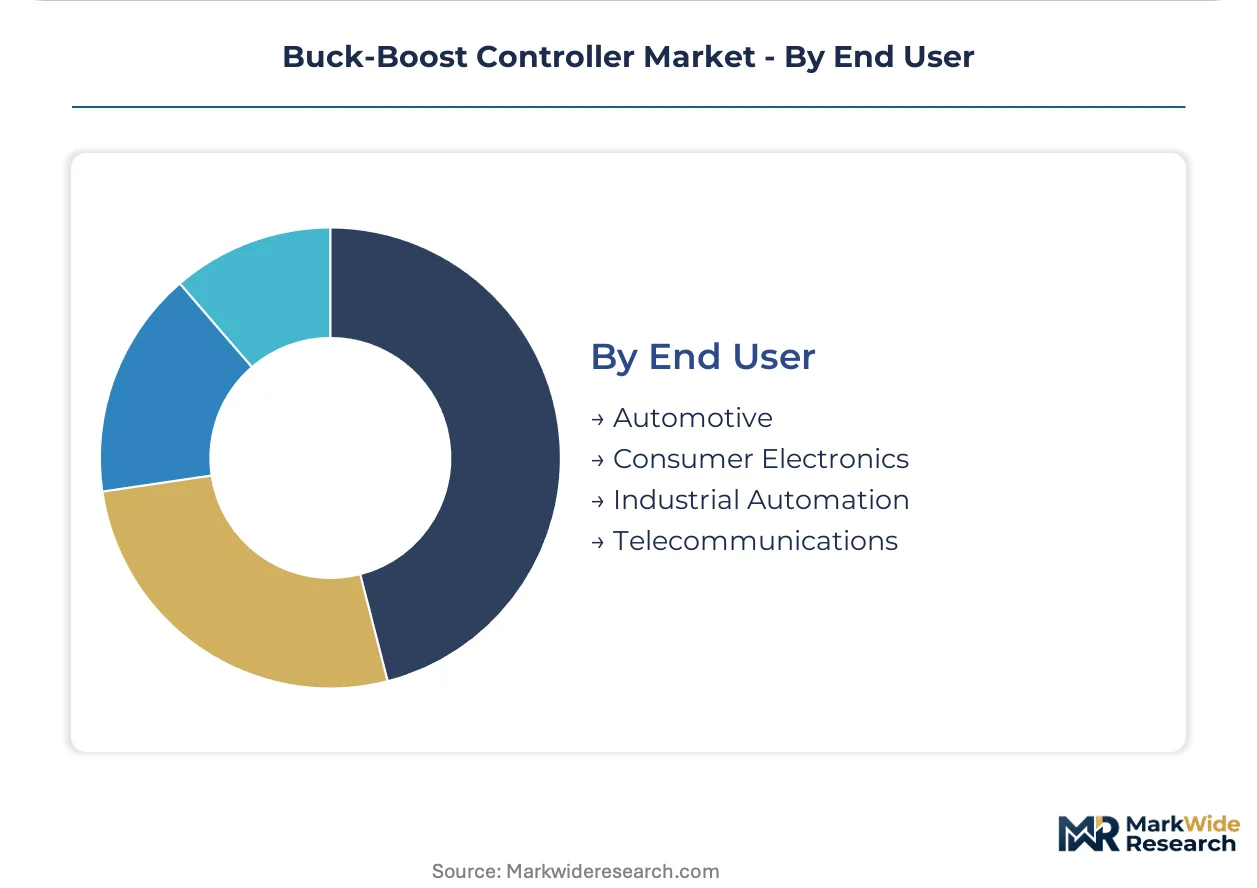
End User:
End-user concentration shapes pricing architecture—automotive customers negotiate multi-year supply agreements with indexed wafer pricing while consumer electronics buyers compete on spot-market component costs.
- Automotive:OEMs and tier-one inverter suppliers specify AEC-Q100 qualified controllers with ISO 26262 functional safety documentation, sourcing through direct foundry relationships that bypass distribution. Chinese EV manufacturers are negotiating wafer allocations directly with TSMC and GlobalFoundries.
- Industrial Automation:Factory equipment and robotics OEMs demand extended temperature ranges and reinforced isolation for motor drives and servo controllers. German automation suppliers are qualifying controllers with integrated safe torque-off functionality under Machinery Directive requirements.
- Consumer Electronics:Smartphone and laptop manufacturers drive high-volume, low-ASP procurement through Asian contract manufacturers.
- Telecommunications:Base station and data center power architects prioritize efficiency across light-load conditions for 24/7 operation.
Consumer Electronics dominates unit shipments. Automotive is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in China and Germany are driving the steepest procurement acceleration, while U.S. industrial automation and Japanese consumer electronics sustain diversified demand bases. Regulatory divergence across efficiency mandates and EV charging standards is fragmenting qualification requirements by geography.
China
Domestic EV manufacturers and renewable-energy inverter deployers are outpacing other manufacturing basins in controller procurement volume. MIIT directives enforce GB standards for EV charging-interface compatibility that standardize protection-feature specifications across tier-one automotive suppliers. Shenzhen and Dongguan manufacturing clusters anchor high-volume production of non-isolated converters for portable electronics supply chains.
Germany
Industrial automation suppliers and residential heat-pump OEMs are qualifying controllers with integrated safe torque-off functionality and active PFC stages. EU Ecodesign Directive standby-loss thresholds below 0.5 W mandate topology upgrades in HVAC auxiliary power units across European appliance manufacturing. Bavaria-based automotive tier-one suppliers are adopting single-stage buck-boost topologies for 800-volt to 12-volt conversion.
United States
Midwest and Southeast residential heat-pump OEMs are qualifying integrated PFC-buck-boost solutions for seasonal energy-efficiency ratio compliance under DOE appliance efficiency standards. EPA and NHTSA coordinated fuel-economy rules indirectly mandate regenerative-braking efficiency that shapes controller specifications. Greater Boston and Pacific Northwest technology corridors concentrate design activity for wide-voltage-range controllers targeting diversified battery architectures.
Japan
Automotive 12-volt auxiliary system suppliers anchor buck-only design procurement volumes, pressured by load-transient response requirements under start-stop cycling. METI efficiency guidelines and JIS standards constrain auxiliary power losses in thermal management systems. Kansai and Chubu industrial belts host concentrated controller integration activity for robotics and servo motor drives.
South Korea
Tier-one automotive suppliers are qualifying molded inductors for 150°C ambient operation under hood in EV traction inverter applications. MFDS medical device regulations and industrial safety standards create demand for reinforced isolation ratings in diagnostic equipment. Busan-Ulsan manufacturing corridors concentrate power-module assembly for wide-bandgap controller designs.
Buck-Boost Controller Market Competitive Landscape
Player mix skews toward diversified analog semiconductor conglomerates with integrated gate-driver portfolios and power-discrete specialists with wide-bandgap MOSFET capabilities. Market structure concentrates design wins among five to seven vertically integrated suppliers capable of automotive qualification support. Two strategic archetypes dominate: silicon-carbide MOSFET pairing specialists and module-level integration providers. Competitive moves center on direct foundry contracting for automotive wafer allocation and topology convergence between discrete multi-chip and highly integrated power-stage architectures.
Among U.S.-based analog conglomerates, Texas Instruments and Analog Devices occupy positions anchoring design wins across mild-hybrid and full-electric architectures through integrated gate-driver portfolios. Infineon Technologies, STMicroelectronics, and Renesas Electronics exemplify the European-Japanese tier dominating silicon-carbide MOSFET pairings and module-level integration that reduces BOM count for tier-one suppliers. These five entities represent the core competitive set, with NXP Semiconductors, Microchip Technology, ROHM, and Vicor Corporation sitting within specialized niches spanning automotive functional safety, industrial temperature ranges, and high-density power-module applications.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Infineon Technologies |
| STMicroelectronics |
| Renesas Electronics |
| NXP Semiconductors |
| Microchip Technology |
| ROHM |
| Vicor Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term foundry capacity reservations with indexed wafer pricing lock automotive OEMs into predictable unit economics while insulating tier-one suppliers from spot-market volatility in silicon-carbide substrate costs. Chinese EV manufacturers leverage direct TSMC negotiations to compress gross margins for authorized distributors, fragmenting procurement economics across automotive and industrial segments.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate automotive procurement, tying controller ASPs to commodity input trajectories. Price differentiation rests on AEC-Q100 certification grade and ISO 26262 ASIL-D documentation depth, with medical isolation variants commanding sustained premiums over consumer-grade QFN packages. Cost compression in non-isolated consumer tiers is intensifying because Shenzhen contract manufacturers optimize for spot-market component costs. Consumer electronics buyers exhibit acute price sensitivity, while automotive OEMs prioritize supply certainty over marginal unit savings.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port corridors are inflating landed costs for European and North American automotive tier-one suppliers dependent on Asian power-module assembly. Manufacturing concentrates in Taiwan, South Korea, and China, with advanced node foundry capacity and silicon-carbide epitaxy facilities anchoring regional specialization. Raw material dependencies span 300mm silicon wafers, rare-earth magnetic powders for molded inductors, and copper-clad laminates for thermal substrates. Single-source vulnerability concentrates in Taiwanese foundry concentration for integrated gate-driver controllers. Distribution runs through authorized distributors for industrial accounts and direct foundry contracting for automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The buck-boost controller market functions as a defensive-moat arena where regulatory entrenchment—specifically 18-24 month automotive qualification timelines—erects structural barriers against rapid competitive displacement.
For Market Incumbents: Secure captive wafer allocations through multi-year foundry agreements before advanced node capacity tightens further. Deepen backward integration into silicon-carbide substrate sourcing to offset epitaxy bottlenecks threatening BOM stability. ISO 26262 documentation libraries represent the critical lever for defending tier-one automotive sockets against emerging wide-bandgap specialists. For New Entrants and Emerging Players: Anchor in medical isolation controller segments where reinforced insulation ratings create margin pools underserved by automotive-focused incumbents. Industrial microgrids in Germany and Australia present the most penetrable white-space, with bidirectional DC-DC requirements outpacing established supplier coverage. A certification-first go-to-market angle—front-loading UL and IEC medical approvals—accelerates design-win velocity against analog conglomerates. For Investors and Strategic Acquirers: Capital is best deployed toward analog semiconductor specialists with captive gate-driver IP and existing AEC-Q100 qualification infrastructure. Long-term viability hinges on automotive platform consolidation toward 800-volt architectures sustaining controller content per vehicle. The signal to watch is direct OEM-foundry contracting velocity as an inflection indicator for distributor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide MOSFET Integration | Infineon and STMicroelectronics leverage SiC pairings to displace silicon in 800-volt traction inverters. |
| Direct Foundry Contracting | Chinese EV manufacturers bypass distribution channels through TSMC and GlobalFoundries wafer allocations. |
| Module-Level Integration | STMicroelectronics reduces BOM count for tier-one suppliers through power-stage consolidation. |
| Medical Isolation Certification | Reinforced insulation ratings open margin pools in diagnostic imaging and surgical robotics equipment. |
| GaN-SiC Hybrid Topology Development | MHz-range frequencies in compact adapter designs enable adapter miniaturization for consumer electronics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with automotive platform engineers, tier-one inverter procurement leads, industrial automation R&D directors, and medical device power architects. Secondary validation drew from MIIT directive filings, EU Ecodesign Directive implementation guidance, EPA appliance efficiency standards, SEC semiconductor company disclosures, and customs trade data for power semiconductor imports. Bottom-up unit shipment estimates triangulated against top-down value projections across product type, component, application, and end-user segmentation dimensions.
Across the analysis window, analytical frameworks modeled volume and value trajectories through discrete multi-chip versus integrated power-module adoption curves, wide-bandgap penetration rates by voltage class, and regional regulatory divergence in efficiency mandates. CAGRs were derived from segment-level growth rate blending anchored to EV production forecasts and renewable energy deployment pipelines. Industry-specific inputs included silicon-carbide wafer supply elasticity and automotive qualification timeline distributions.
Decision-makers should treat outputs as directional under assumptions of sustained EV platform voltage escalation and stable Taiwan foundry capacity expansion; material deviation in either driver would warrant model refresh. Forecasts reflect base-case assumptions regarding GB standard harmonization and EU Ecodesign Directive enforcement continuity. Recalibration cycles align with material shifts in automotive OEM sourcing strategies and wide-bandgap substrate supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Ultrafast Rectifiers Market
Power Systems
Synchronous Condenser Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Thermal Management Systems Market
Power Systems
Solid State Power Controller Market
Power Systems
PV Inverter Market
Power Systems
Flyback Transformer Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
EV Power Module Market
Power Systems
Electrical and Automation System Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Power Supply and Charger Market
Power Systems
Battery Equalizer Market
Power Systems
Power Integrated Modules Market
Power Systems
Synchrophasors Market
Power Systems
Solid State Transformer Market