
 Power Load Switches Market | 2026-2036
Power Load Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Power Load Switches Market Analytics
Wide-bandgap semiconductor migration is reconfiguring power load switch architectures across industrial and consumer applications. Schneider Electric SE leverages its integrated energy management portfolio to anchor premium positions in electromechanical switching. Renesas Electronics Corporation specializes in MOSFET-based solutions for precision PCB-mounted deployments. ABB Ltd. competes through its dominance in ruggedized installations serving utility-scale power distribution networks.
Power load switches are electromechanical or solid-state devices designed to interrupt, connect, or redirect electrical current paths, typically rated from milliamps to kiloamps with switching speeds ranging from microseconds to milliseconds depending on technology type. They serve to protect circuits, enable load shedding, and manage power sequencing across industrial, commercial, and residential electrical systems. MOSFET and IGBT variants are capturing margin pools in renewable energy inverters where fast switching and thermal efficiency determine system performance. Electromechanical switches retain volume leadership in utility power distribution where mechanical isolation and visible break points remain mandatory under safety codes. PCB-mounted installations are expanding fastest in consumer electronics as device miniaturization demands integrated power management at the board level.
The US Department of Energy appliance efficiency standards and FCC electromagnetic compatibility rules shape product design requirements for switches entering North American markets. China's GB standards and MIIT certification protocols govern access for imported and domestically manufactured switching equipment. The EU Ecodesign Directive and CE marking requirements enforce minimum efficiency thresholds and material restrictions across European supply chains. Stakeholders must monitor evolving semiconductor material regulations and efficiency tier migrations to align R&D roadmaps with compliance timelines.
Market Dynamics
Wide-bandgap semiconductor migration is compressing switching losses and thermal footprints, forcing incumbent electromechanical architectures toward obsolescence in precision power management applications.
Growth Catalysts
- MIIT Efficiency Mandates:China's tightening certification requirements for electrical equipment are accelerating domestic replacement cycles and opening procurement windows for advanced solid-state solutions.
- Automotive Electrification:Battery management systems and onboard charging modules in electric vehicle powertrains are absorbing high-current MOSFET switches at accelerating rates.
- Silicon Carbide Penetration:Semiconductor fabrication clusters in East Asia are prioritizing SiC substrate capacity expansion to feed downstream switch manufacturing.
Market Restraints
- Substrate Supply Concentration:SiC wafer production remains geographically concentrated among a handful of specialized foundries, creating input bottlenecks for switch manufacturers.
- Copper and Rare Earth Volatility:Electromechanical switch producers face margin compression from fluctuating copper conductor and permanent magnet material costs.
- Mechanical Isolation Codes:Utility safety regulations mandating visible break points prevent solid-state displacement in distribution infrastructure despite performance advantages.
Strategic Opportunities
- Renewable Inverter Integration:Solar and wind power conversion equipment represents an underpenetrated application where fast-switching wide-bandgap devices command premium positioning.
- Board-Level Miniaturization:Consumer electronics OEMs are consolidating discrete power management functions into single-package load switches for space-constrained designs.
- US IRA Clean Energy Incentives:Domestic content requirements for tax-credit-eligible renewable projects are creating localized demand for certified switch assemblies.
Industry Challenges
- Wide-Bandgap Packaging Expertise:Thermal management and parasitic inductance control for SiC and GaN devices require specialized engineering talent in short supply.
- Multi-Jurisdiction Certification Overlap:Simultaneous compliance with US FCC electromagnetic rules, EU CE marking, and China GB standards extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Load Switches Market |
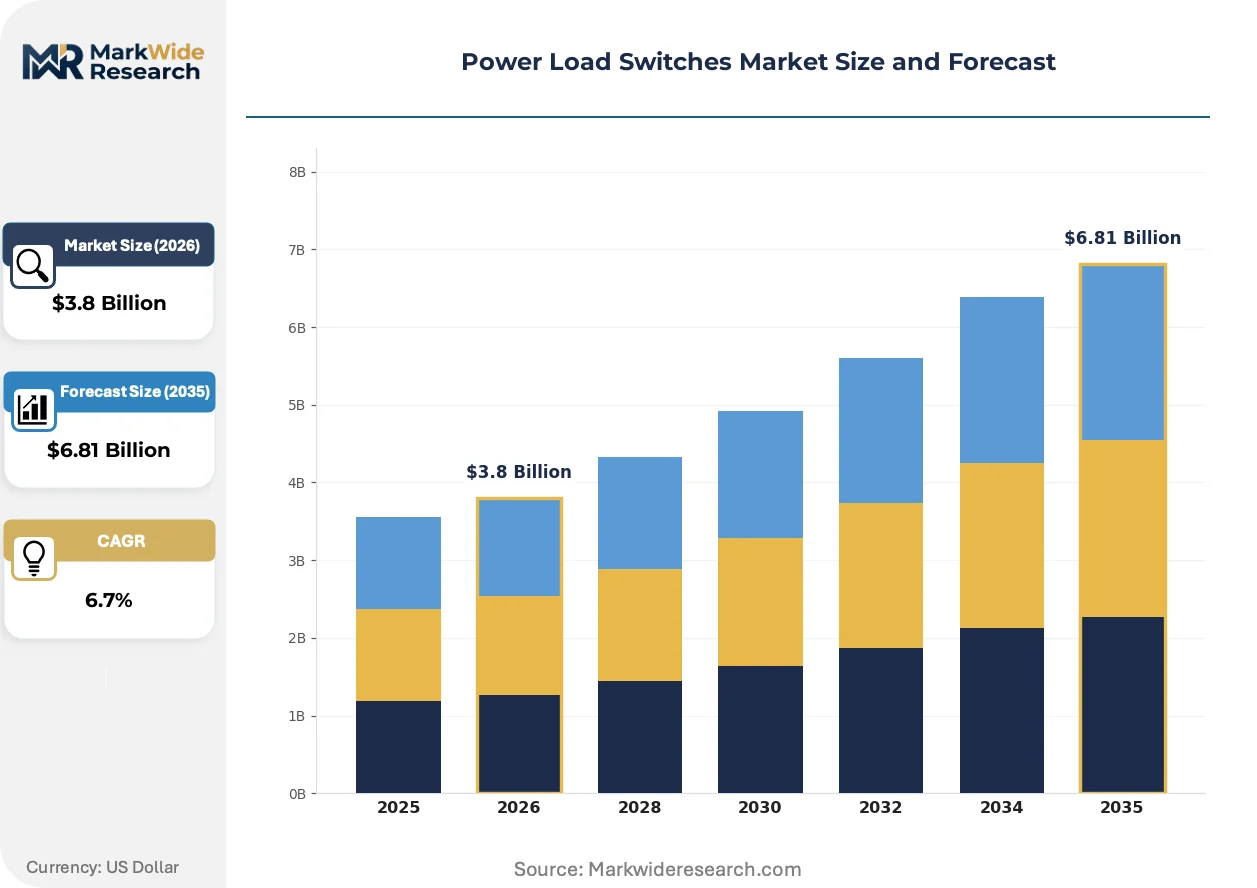
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Relay, MOSFET, IGBT Application: Industrial Automation, Renewable Energy, Consumer Electronics, Power Distribution End User: Manufacturers, Utilities, Residential, Commercial Installation: Panel-Mounted, PCB-Mounted, DIN-Rail, Ruggedized |
| Companies Covered | Schneider Electric SE, ABB Ltd., Siemens AG, Eaton Corporation plc, Nexperia B.V., ITALWEBER S.p.A., Renesas Electronics Corporation, KATKO Oy, Lucy Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Load Switches Market Evolving Landscape
Active material substitution and policy-driven efficiency floors are compressing technology refresh cycles while reshaping how power switches are specified, procured, and integrated into end systems.
Silicon carbide MOSFET technology is digitizing gate drive architectures and enabling higher-frequency operation with reduced switching losses. Industrial motor drive manufacturers and renewable inverter producers are adopting these devices at accelerating rates. The technology is digitizing control loop response times and compressing passive component requirements in power conversion stages.
The EU Ecodesign Directive and F-Gas Regulation are enforcing minimum efficiency thresholds and material restrictions across European supply chains. These frameworks are eliminating marginal electromechanical products from certified equipment categories. Industrial automation OEMs serving EU markets are redesigning around solid-state architectures to maintain compliance eligibility.
Specification consolidation among tier-one automotive and industrial OEMs is compressing approved vendor lists and elevating certification-driven purchasing criteria. Distributors are repositioning from inventory intermediaries to technical specification partners with in-house application engineering. This concentration is most visible in German and Japanese automotive supply chains where single-source qualification periods exceed eighteen months.
Power Load Switches Market Segmentation
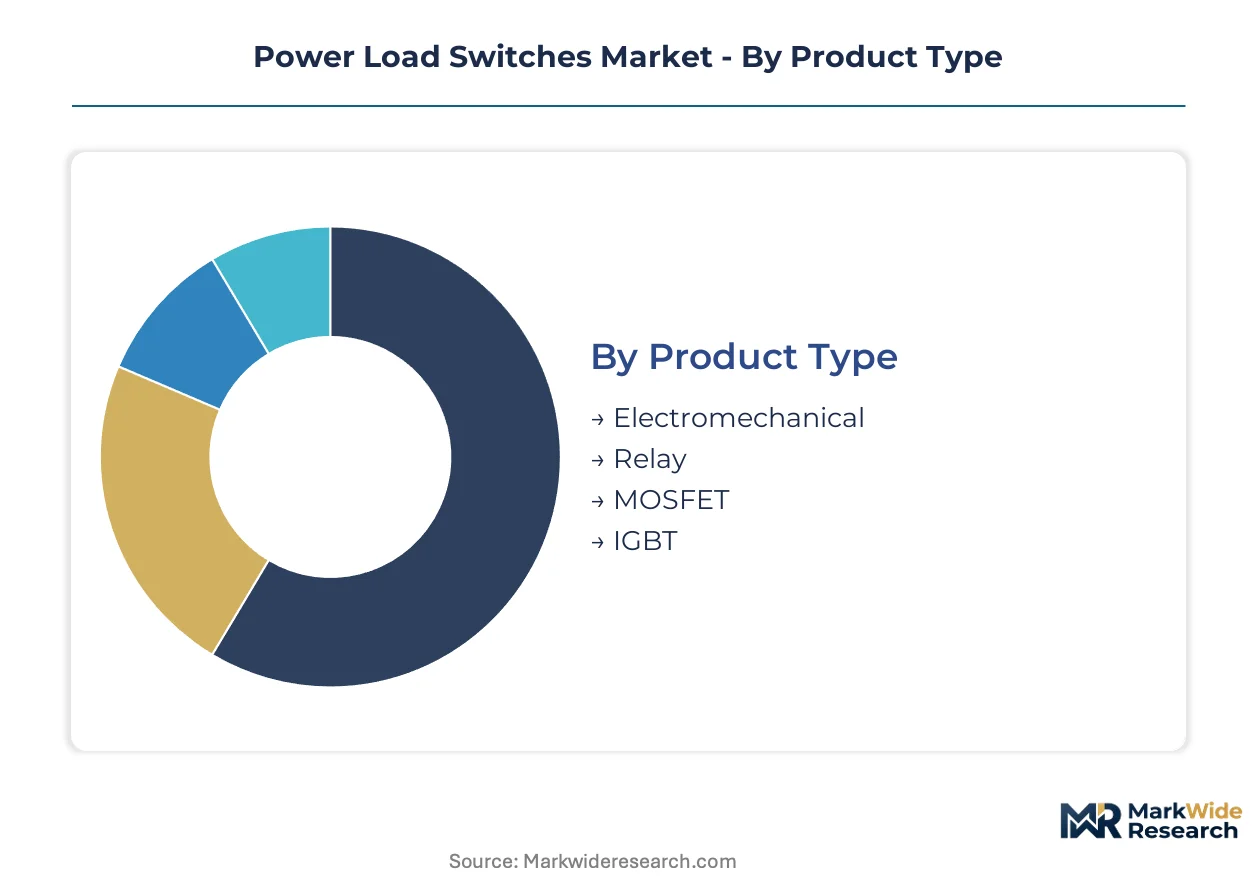
Power load switch procurement varies sharply by installation environment and operational duty cycle. After-sales service intensity differs across segments, with ruggedized industrial deployments demanding field engineering support while PCB-mounted consumer variants require minimal technical intervention. Specification complexity and replacement frequency together determine margin structures and distributor engagement models.
Product Type:
After-sales service intensity peaks with electromechanical switches requiring periodic contact inspection and arc chute replacement, while solid-state alternatives shift value toward upfront thermal design consultation.
- Electromechanical:Mechanical contact assemblies with visible break points satisfy utility safety codes mandating physical isolation. Demand concentrates in North American and European distribution infrastructure where NERC reliability standards and EU grid codes enforce mechanical redundancy. Copper conductor costs and contact wear rates drive replacement cycles.
- MOSFET:Silicon and silicon carbide variants enable microsecond switching speeds with minimal conduction losses. Automotive battery management systems in German and Japanese OEM supply chains absorb high-current trench MOSFETs for onboard charging and DC-DC conversion. Wide-bandgap substrate availability constrains capacity expansion.
- Relay:Electromechanical coil-actuated switches bridge control and power circuits across industrial control panels. Food processing and packaging machinery OEMs in Italy and Spain specify sealed relays for washdown environments.
- IGBT:Bipolar transistor structures with MOSFET gate control handle kiloamp currents in medium-frequency applications. Wind turbine converters and traction motor drives in Chinese and Indian rail electrification projects dominate procurement.
By volume, electromechanical switches lead. By growth pace, MOSFET variants are gaining share fastest.
Application:
Application-specific certification requirements fragment procurement, with renewable energy inverters demanding IEC 62109 safety compliance while consumer electronics prioritize FCC Part 15 electromagnetic emissions clearance.
- Industrial Automation:Programmable logic controller integration and motor starter assemblies require deterministic switching response. German automotive manufacturing plants and Japanese semiconductor fabrication facilities specify IEC 60947-4 certified switches for production line reliability.
- Consumer Electronics:Smartphone and laptop motherboard designs integrate load switches for power sequencing and brownout protection. South Korean and Taiwanese ODMs consolidate discrete functions into single-package solutions for space-constrained designs.
- Renewable Energy:Solar string inverters and wind power converters demand wide-bandgap devices for high-frequency operation with reduced cooling overhead. US IRA domestic content requirements are reshaping supplier qualification for tax-credit-eligible projects.
- Power Distribution:Utility substations and feeder automation systems specify electromechanical and hybrid switches with mechanical isolation. Chinese State Grid and Indian Power Grid Corporation procurement tenders emphasize visible break points under operating procedures.
Industrial automation commands the largest revenue pool. Consumer electronics exhibits the steepest expansion trajectory.
End User:
End user technical sophistication determines specification authority, with utilities maintaining internal engineering standards while residential installations defer to contractor recommendations.
- Utilities:Transmission and distribution operators specify switches for substation automation and feeder sectionalization. FERC reliability standards in the US and Central Electricity Authority regulations in India govern equipment qualification.
- Manufacturers:Industrial OEMs and system integrators embed switches in motor controls, power supplies, and process automation equipment. Japanese and German machine builders maintain approved vendor lists with eighteen-month qualification periods.
- Commercial:Building automation and data center operators prioritize energy efficiency and remote monitoring capability. LEED certification requirements in North America and BREEAM standards in the UK influence product selection.
- Residential:Home electrical panels and smart energy management systems specify cost-optimized electromechanical breakers. Chinese and Indian urbanization drives volume in multi-unit residential construction.
Manufacturers represent the deepest specification engagement. Utilities anchor replacement demand with longest asset lifecycles.
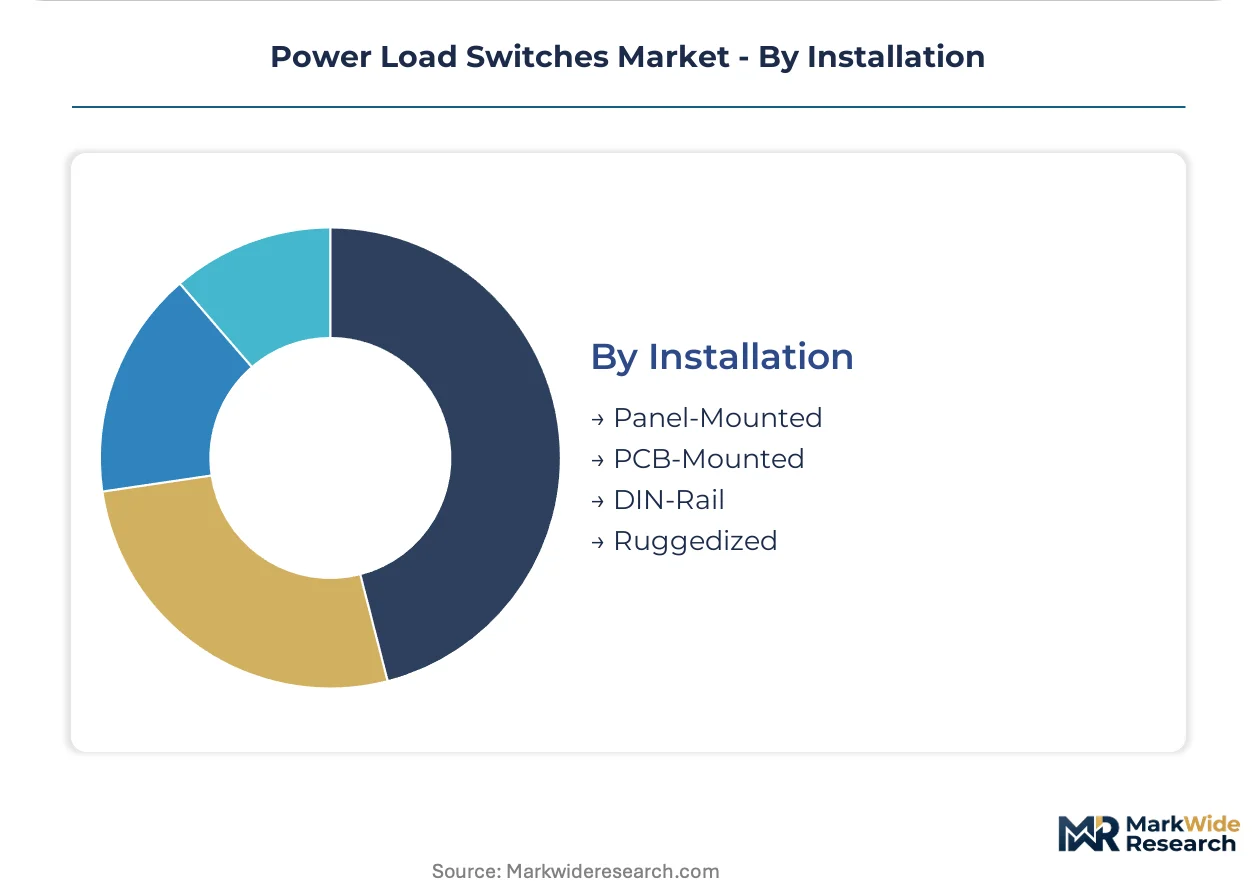
Installation:
Installation method dictates thermal management architecture and enclosure standards, with panel-mounted designs requiring forced air cooling while PCB-mounted variants leverage copper plane dissipation.
- PCB-Mounted:Surface-mount and through-hole packages integrate directly onto printed circuit boards for power management IC companion functions. Wearable devices and IoT sensors in South Korean and Chinese consumer electronics supply chains drive miniaturization requirements.
- Panel-Mounted:Enclosed switch assemblies bolt into electrical panels with busbar or cable terminations. US and Canadian industrial control panel builders specify NEMA enclosure ratings for harsh environment resilience.
- DIN-Rail:Standardized 35mm rail mounting enables rapid installation and modular replacement in control cabinets. European machinery OEMs and system integrators prefer this format for maintenance accessibility.
- Ruggedized:Sealed, shock-resistant enclosures withstand extreme temperature, vibration, and contamination. Mining equipment in Australia and oil and gas installations in Saudi Arabia specify IP67-rated switches with extended temperature ranges.
Panel-mounted installations dominate current revenue. PCB-mounted formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese automotive OEMs source precision MOSFET load switches from South Korean fabrication clusters, creating a concentrated east-west trade corridor that shapes regional supply allocation.
United States
Data center expansion in Northern Virginia and renewable inverter manufacturing in Texas drive demand for wide-bandgap switching solutions. FERC reliability standards and the Inflation Reduction Act's domestic content requirements govern utility and clean energy procurement. Silicon carbide device packaging specialists concentrate in Research Triangle Park, North Carolina, serving defense and aerospace applications.
Germany
Industrial automation OEMs in Bavaria and automotive powertrain developers in Baden-Württemberg specify IEC-certified switches for production equipment. The EU Ecodesign Directive and F-Gas Regulation enforce efficiency tiers and material restrictions. Munich-based system integrators consolidate approved vendor lists with eighteen-month qualification cycles for automotive supply chains.
China
State Grid Corporation procurement tenders and electric vehicle battery management system production absorb high-current solid-state switches. MIIT efficiency mandates and GB standards tighten certification protocols for imported equipment. Yangtze River Delta semiconductor fabrication clusters in Shanghai and Suzhou prioritize SiC substrate capacity for downstream switch manufacturing.
Japan
Semiconductor fabrication facilities in Kyushu and precision machine builders in Nagoya demand deterministic switching response for process automation. METI energy efficiency guidelines and JIS standards shape product specifications. Tokyo-based electronics conglomerates maintain captive supply relationships with domestic MOSFET specialists for consumer electronics integration.
South Korea
Smartphone and display panel manufacturers in Seoul and Suwon consolidate discrete power management into single-package load switches. MFDS electromagnetic compatibility rules and national industrial policy support domestic semiconductor ecosystem development. Pangyo Techno Valley hosts design centers for wearable device power management ICs.
Power Load Switches Market Competitive Landscape
On the supply side, the industry is bifurcated between electromechanical incumbents with utility-scale installed bases and semiconductor specialists capturing growth in solid-state applications. Two strategic archetypes dominate: integrated energy management conglomerates leveraging portfolio breadth, and focused wide-bandgap device fabricators with captive substrate access. Competitive moves center on SiC foundry partnerships and qualification engineering investments to compress automotive OEM approval timelines.
Among European-based industrial conglomerates, Schneider Electric SE and ABB Ltd. exemplify the integrated energy management archetype, anchoring premium positions through specification authority in utility and heavy industrial procurement. Renesas Electronics Corporation represents the precision semiconductor specialist tier, occupying a position in PCB-mounted and automotive-integrated switching solutions where MOSFET architectures dominate.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd. |
| Siemens AG |
| Eaton Corporation plc |
| Nexperia B.V. |
| ITALWEBER S.p.A. |
| Renesas Electronics Corporation |
| KATKO Oy |
| Lucy Electric |
| Others |
Value Network & Pricing Analysis
SiC wafer fabrication concentrates in East Asian foundries, anchoring margin capture at the substrate tier and compressing downstream switch manufacturers into assembly and packaging value-add. Electromechanical incumbents source copper conductors and silver contacts from commodity metal exchanges, leaving them exposed to volatility without pricing power to pass through costs.
Pricing Analysis
Silicon IGBT pricing sits at a 40-60% discount to silicon carbide MOSFET equivalents, with gallium nitride devices occupying a mid-tier premium position for sub-650V applications. Pricing stratifies across automotive-grade AEC-Q101 certified, industrial IEC-rated, and consumer-grade unqualified tiers, with certification level and thermal performance as primary differentiation drivers. Cost compression in electromechanical segments is intensifying because Chinese manufacturers are absorbing copper volatility to gain share. Utilities exhibit lowest price sensitivity due to 30-year asset replacement cycles, while consumer electronics ODMs negotiate on fractions of a cent per unit.
Supply Chain Analysis
Copper cathode and silicon carbide substrate feedstock draws from Chilean mining operations and Chinese synthetic crystal growth facilities respectively, with silver contact plating sourced from Mexican refiners. Electromechanical switch assembly rests on stamped metal components from Chinese and Indian Tier 2 suppliers, while solid-state device packaging hinges on ceramic substrate availability from Japanese and German specialists. Single-source vulnerability concentrates in 6-inch SiC wafer supply from Wolfspeed and Coherent facilities. Distribution runs through authorized distributors with in-house application engineering for industrial accounts, and direct OEM contracting for high-volume automotive and consumer placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology generation fragmentation creates defendable niches as wide-bandgap migration outpaces electromechanical obsolescence timelines. Specification authority is dispersing from traditional utilities toward automotive OEMs and renewable inverter manufacturers.
For Market Incumbents: Entrench specification authority by embedding switches into integrated energy management platforms with predictive maintenance software bundles. Acquire SiC packaging specialists in Research Triangle Park or Bavaria to secure thermal engineering talent before automotive qualification windows close. Defend against semiconductor entrants by emphasizing mechanical isolation compliance in utility procurement codes. For New Entrants and Emerging Players: Pursue board-level miniaturization opportunities in South Korean wearable device supply chains where incumbent distributors lack application engineering depth. Target solar string inverter manufacturers in Texas seeking IRA-compliant domestic content switches as the most penetrable white-space. Lead with reference designs that compress customer thermal validation cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electromechanical specialists carrying 2017-2019 vintage leverage and limited SiC transition roadmaps. Five-to-ten year viability hinges on captive substrate access or automotive qualification momentum. Watch for Chinese State Grid tender shifts toward solid-state hybrid architectures as the inflection signal for electromechanical value erosion.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Foundry Partnership | Secures substrate allocation from Yangtze River Delta fabrication clusters for automotive switch production. |
| Automotive Qualification Investment | Compresses eighteen-month AEC-Q101 approval timelines for German and Japanese OEM supply chains. |
| Application Engineering Expansion | Transforms distributors from inventory intermediaries into specification partners for industrial automation. |
| IRA Domestic Content Certification | Unlocks tax-credit-eligible renewable project procurement in Texas and California inverter markets. |
| Thermal Packaging Acquisition | Addresses wide-bandgap parasitic inductance and heat dissipation expertise gaps in short supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade databases, and IEC certification registries. Semiconductor fabrication executives, utility procurement officers at State Grid and FERC-regulated operators, automotive Tier 1 supplier quality directors, and industrial control panel builders contributed structured interviews. Bottom-up demand modeling across installation types and end-user segments triangulates against top-down supply-side capacity assessments from foundry and electromechanical manufacturer disclosures.
Forecast inputs span technology substitution curves between silicon and wide-bandgap devices, regulatory efficiency tier migrations under EU Ecodesign and China MIIT mandates, and automotive electrification content-per-vehicle trajectories. Segmentation modeling covers product architecture, application environment, end-user technical sophistication, and installation method across the projection horizon. CAGRs derive from installed base replacement cycles and new build absorption rates rather than extrapolated historical growth.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility, Chinese export license restrictions, or IRA credit eligibility rulings would shift the trajectory. Cross-checking against FERC interconnection queue data and automotive OEM production schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Transfer Switch Market
Switches
North America Medium Voltage Switchgear Market
Switches
Smart Dimmer Switch Market
Switches
Zero Speed Switch Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Italy Reed Sensors Switches Market
Switches
Smart Pole-Mounted Switch Market
Switches
Global Push Buttons and Signalling Devices Market
Switches
Low Voltage Disconnect Switch Market
Switches
Cross Point Switch Market
Switches
South Korea Reed Sensors Switches Market
Switches
Membrane Switch Market
Switches
Analog Switches Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Miniature-Circuit Breaker Market
Switches
Reed Switch Market