
 Global Network Switches Market | 2026-2036
Global Network Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Switches Market Intelligence
The integration of Software-Defined Networking (SDN) is reconfiguring the architecture of enterprise and data center networks by separating the control plane from the data plane. This shift enables greater network automation and programmability. Cisco Systems leverages its extensive portfolio and channel partnerships to maintain a significant market presence. Arista Networks specializes in high-performance switches for cloud and data center environments, differentiating on software quality.
A network switch is a hardware device that operates at the data link layer of the OSI model to connect devices on a computer network. It uses MAC addresses to intelligently forward data packets only to the specific destination device, which reduces unnecessary traffic and improves overall network efficiency. Managed switches command a premium due to their advanced configuration and security features, essential for enterprise applications. The adoption of Power over Ethernet (PoE) technology represents a key growth area, simplifying the deployment of devices.
Compliance with standards from bodies like the US Federal Communications Commission (FCC) for electromagnetic interference is mandatory for market entry. In parallel, regulations such as the EU's RoHS directive on hazardous substances and China's MIIT requirements for telecommunications equipment influence material use and product certification. Navigating these varied international compliance landscapes remains a critical task for manufacturers seeking broad market access.
Market Dynamics
The fundamental architecture of networking is being reconfigured by the separation of the control and data planes, a core principle of Software-Defined Networking (SDN). This structural shift away from monolithic, hardware-centric designs enables unprecedented network programmability and automation for enterprises and cloud providers.
Growth Catalysts
- Cloud Infrastructure Expansion:The build-out of massive data center clusters by cloud service providers, particularly in the United States and China, necessitates continuous investment in high-radix, low-latency switches to support east-west traffic.
- Power over Ethernet (PoE) Adoption:The proliferation of IoT devices in smart buildings and industrial settings, such as IP cameras and wireless access points, drives demand for PoE switches that simplify deployment by providing both data connectivity and electrical power.
- Government Digitalization Initiatives:National programs, including India's Digital India campaign and the EU's Connecting Europe Facility, stimulate public and private investment in modern network infrastructure, creating a stable demand floor for enterprise-grade switches.
Market Restraints
- Semiconductor Supply Volatility:The network switch market is highly dependent on a concentrated supply chain for high-performance processors and ASICs, making it vulnerable to price fluctuations and lead-time extensions from foundries located primarily in Taiwan and South Korea.
- Legacy System Integration:Many enterprises face significant technical hurdles and operational risks when integrating modern, programmable switches with existing legacy network equipment, slowing down refresh cycles and technology adoption.
- High Power Consumption:Increasing port speeds and switch densities in data centers lead to greater power consumption and heat dissipation challenges, which can increase total cost of ownership and limit rack density without significant cooling infrastructure investment.
Strategic Opportunities
- Edge Computing Infrastructure:The emergence of edge data centers to support low-latency applications like autonomous vehicles and real-time analytics creates a new market for compact, ruggedized, and remotely manageable switches deployed outside traditional IT environments.
- AI/ML Workload Optimization:Developing switches with specialized hardware and software to handle the unique, high-bandwidth traffic patterns of Artificial Intelligence and Machine Learning training clusters represents a significant value-creation opportunity.
- Network-as-a-Service (NaaS):Offering subscription-based models that bundle hardware, software, and management services provides a recurring revenue stream and appeals to customers seeking to shift from capital expenditures to operational expenditures.
Industry Challenges
- Cybersecurity Threat Sophistication:Switches are increasingly targeted by advanced persistent threats, requiring manufacturers to continuously invest in embedded security features and faster patch-release cycles to protect network integrity against evolving attack vectors.
- Multi-Vendor Interoperability:Ensuring seamless interoperability between different vendors' SDN controllers, orchestration software, and hardware remains a persistent operational challenge, potentially leading to vendor lock-in and limiting customer choice.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Switches Market |
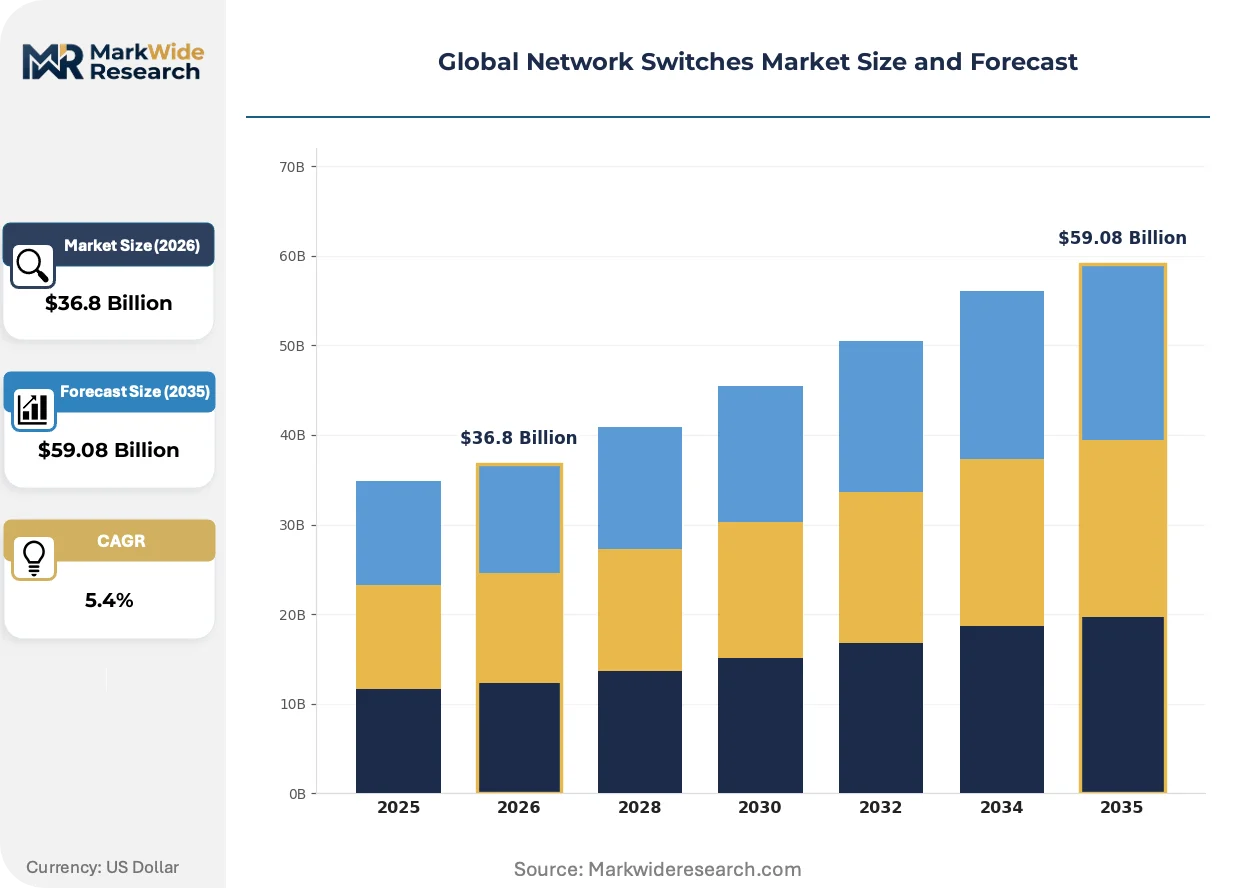
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $59.08 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Managed Switches, Unmanaged Switches, Smart Switches, Industrial Switches, Modular Switches Technology: Ethernet, Fiber Channel, Power over Ethernet, Software-Defined Networking, Multi-Gigabit, Automation Application: Data Centers, Cloud Service Providers, Telecom Operators, Government Agencies, Financial Institutions, Educational Institutes End User: Telecom Carriers, Internet Service Providers, Managed Service Providers, Content Delivery Networks, Enterprise Corporations |
| Companies Covered | Cisco Systems, Huawei Technologies, Hewlett Packard Enterprise, Juniper Networks, Arista Networks, Dell Technologies, Extreme Networks, H3C Technologies, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Switches Market Strategic Shifts & Innovations
The disaggregation of network hardware and software is redefining vendor business models and enterprise procurement strategies. This allows for greater customization and flexibility, moving value from integrated systems to specialized software functions and open-source network operating systems.
Network Operating System (NOS) disaggregation enables the use of third-party software on generic white-box or branded brite-box hardware. Hyperscale cloud operators and large financial services firms are the primary adopters, seeking to customize network functions and accelerate innovation. This trend is digitizing network control, unbundling software value from the physical switch and fostering a new ecosystem of independent NOS vendors.
Regulations governing electromagnetic compatibility, such as the US Federal Communications Commission (FCC) Part 15 rules, impose strict design constraints. These rules mandate rigorous testing to ensure that switches do not cause harmful interference to other electronic devices. All product categories, from small business switches to large chassis-based systems for data centers, must achieve FCC certification prior to being marketed in the United States.
A notable behavioral change is the enterprise pivot toward consumption-based IT procurement for network infrastructure. This model replaces large, infrequent capital purchases with flexible, subscription-based access to both hardware and advanced software features. This pattern is most visible in the North American and European mid-market, where companies leverage it to access enterprise-grade capabilities while managing operational budgets more effectively.
Global Network Switches Market Segmentation
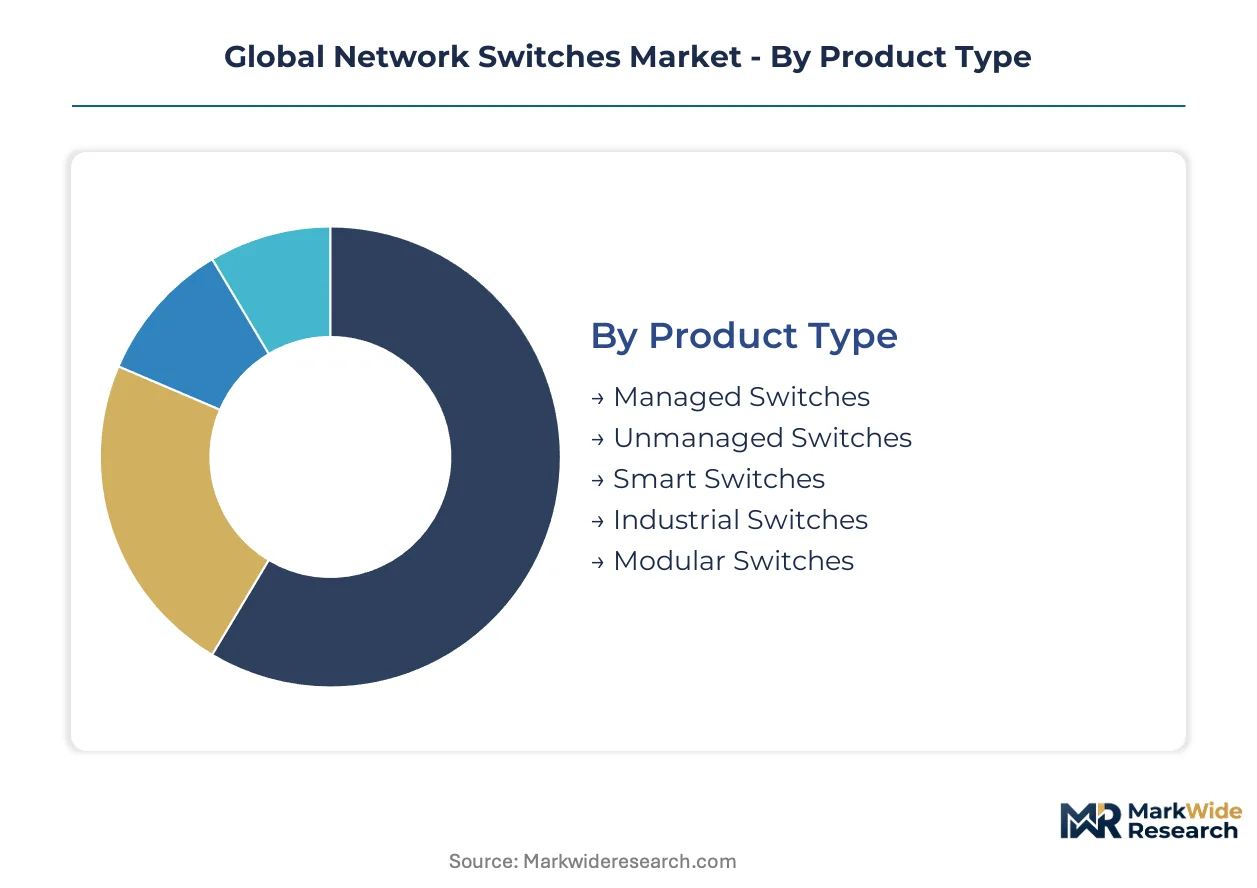
The segmentation of the global network switches market provides a granular understanding of product functionalities, underlying technologies, diverse application areas, and distinct end-user requirements. This detailed classification aids stakeholders in identifying specific growth pockets and tailoring product development strategies to address evolving market needs.
Product Type:
The after-sales service intensity varies significantly across product types, with more complex and mission-critical switches demanding extensive support and specialized expertise from vendors.
- Managed Switches:These devices offer advanced configuration options, enhanced security features, and remote management capabilities through a web interface or command-line interface. Demand from enterprise data centers in the United States and Europe concentrates on managed switches for their granular control over network traffic and robust performance.
- Industrial Switches:Engineered for harsh environments, these switches feature ruggedized designs, extended operating temperatures, and resistance to vibrations and electromagnetic interference. Demand for industrial switches is expanding in smart factory deployments across Germany and Japan, driven by the need for reliable connectivity in operational technology networks.
- Unmanaged Switches:Functioning as plug-and-play devices, these switches provide basic connectivity without requiring any configuration or management.
- Smart Switches:Positioned between unmanaged and fully managed switches, these devices offer some management capabilities at a lower cost, suitable for small to medium-sized businesses.
- Modular Switches:These switches allow for flexible expansion and customization of ports and modules, accommodating diverse networking requirements in large enterprise networks.
Managed Switches hold the largest share; momentum sits with Industrial Switches.
Technology:
The application of various technologies dictates the performance, scalability, and integration capabilities of network switches across different network environments.
- Software-Defined Networking:SDN separates the control plane from the data plane, enabling centralized network management, automation, and programmability through software. Hyperscale cloud providers in China and the United States are heavily investing in SDN to optimize resource utilization and dynamically reconfigure network paths for massive workloads.
- Power over Ethernet:PoE technology delivers both data connectivity and electrical power over a single Ethernet cable, simplifying the deployment of network-powered devices. The proliferation of IP cameras and wireless access points in smart building projects across India and the United Kingdom drives significant demand for PoE switches.
- Ethernet:This foundational technology provides the standard for wired local area networks, supporting a wide range of speeds and protocols.
- Fiber Channel:Primarily used in storage area networks (SANs), Fiber Channel offers high-speed data transfer for connecting servers to shared storage devices.
- Multi-Gigabit:This technology supports intermediate Ethernet speeds beyond 1 Gigabit but below 10 Gigabit, catering to high-bandwidth wireless access points.
- Automation:Network automation leverages software tools and scripts to manage and configure network devices, reducing manual errors and improving operational efficiency.
The adoption of Software-Defined Networking technology is accelerating, while Ethernet remains foundational.
Application:
Cost tiers for network switches are often determined by their intended application, with mission-critical infrastructure demanding higher-performance and more resilient solutions.
- Data Centers:These facilities house large volumes of servers and networking equipment, requiring high-density, low-latency switches to handle immense east-west traffic within the cluster. Data centers in Ireland and Singapore demand high-radix switches for efficient workload distribution and rapid data exchange.
- Cloud Service Providers:These entities offer computing resources and services over the internet, necessitating scalable and programmable switches to support multi-tenancy and dynamic resource allocation. Cloud infrastructure expansion by major providers in the United States and Germany drives continuous investment in advanced network switches.
- Telecom Operators:These companies provide telecommunications services, relying on robust switches for their core networks, mobile backhaul, and fixed-line broadband infrastructure.
- Government Agencies:Public sector entities require secure and reliable network switches for internal communications, public services, and national defense applications.
- Financial Institutions:Banks and trading firms demand ultra-low-latency and highly secure switches for real-time transaction processing and data analytics.
- Educational Institutes:Universities and schools deploy network switches to support campus-wide connectivity, e-learning platforms, and administrative functions.
Demand from Data Centers drives significant volume, with Cloud Service Providers representing a high-value segment.
End User:
The specific customer type influences procurement patterns and the demand for specialized features, ranging from scalability to embedded security.
- Enterprise Corporations:These large organizations require sophisticated network switches to support their diverse business operations, internal communications, and data storage needs. Enterprise corporations across Japan and France prioritize switches with advanced security features and robust management capabilities.
- Telecom Carriers:These providers build and maintain vast communication networks, requiring carrier-grade switches that offer high reliability, scalability, and support for various traffic types. Telecom carriers in Brazil and Australia invest in high-capacity switches for their core and access networks.
- Internet Service Providers:ISPs deliver internet access to homes and businesses, utilizing switches to manage subscriber traffic and connect to the broader internet backbone.
- Managed Service Providers:MSPs offer outsourced IT services, deploying network switches as part of their infrastructure to deliver managed networking solutions to clients.
- Content Delivery Networks:CDNs distribute content closer to end-users, relying on high-performance switches to accelerate content delivery and reduce latency.
The shift towards subscription-based models impacts procurement across all End User segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor components from East Asian foundries frequently flow into manufacturing hubs that then supply network switches to major consumption markets. This global trade dynamic underpins the regional market variations in demand and regulatory frameworks. Each major economic zone exhibits distinct drivers for network switch adoption and infrastructure development.
United States
Cloud service providers in the United States continuously invest in high-radix, low-latency switches for massive data center clusters. Compliance with US Federal Communications Commission (FCC) Part 15 rules is mandatory for market entry. Northern Virginia's data center alley, a major hub, demands advanced switching infrastructure for efficient east-west traffic.
China
Hyperscale cloud providers in China drive significant investment in Software-Defined Networking (SDN) to optimize resource utilization. China's Ministry of Industry and Information Technology (MIIT) sets stringent requirements for telecommunications equipment certification. Shenzhen's technology manufacturing cluster produces a wide range of network switches for domestic and international markets.
Germany
Smart factory deployments across Germany increase demand for ruggedized industrial switches in operational technology networks. Manufacturers must comply with the EU's RoHS directive on hazardous substances for product market access. The industrial heartland of North Rhine-Westphalia requires robust network solutions for its advanced manufacturing facilities.
Japan
Enterprise corporations in Japan prioritize switches with advanced security features and robust management capabilities for internal networks. The Ministry of Economy, Trade and Industry (METI) guides industrial policy impacting network infrastructure development. Tokyo's dense urban infrastructure and financial institutions demand ultra-low-latency and highly secure network solutions.
India
India's Digital India campaign stimulates public and private investment in modern network infrastructure. The Bureau of Indian Standards (BIS) formulates technical standards for electronic and telecommunications equipment. Bangalore's burgeoning IT sector and smart city projects drive demand for Power over Ethernet (PoE) switches.
Global Network Switches Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share across diverse network switch segments. The market exhibits a tiered structure, from comprehensive portfolio providers to niche high-performance specialists. Strategic archetypes include integrated solution providers, specialized hardware vendors, and disaggregated software-centric players. Software differentiation and continuous investment in embedded security features represent dominant competitive moves.
Within the established vendor tier, Cisco Systems, a US-based corporation, exemplifies a comprehensive portfolio approach, leveraging its extensive channel partnerships and broad product offerings. Arista Networks, also a US-based corporation, occupies a position as a high-performance specialist, differentiating on software quality and low-latency performance for demanding cloud and data center environments. Hewlett Packard Enterprise, another US-based entity, provides a broad range of networking solutions, including switches, for enterprise and data center applications, catering to diverse customer requirements with its integrated IT infrastructure strategy.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Arista Networks |
| Dell Technologies |
| Extreme Networks |
| H3C Technologies |
| NEC Corporation |
Cost & Logistics Intelligence
Semiconductor manufacturing capacity utilization dictates component availability for network switches, directly influencing both vendor production schedules and end-user pricing. This tight coupling means that fluctuations in foundry output translate rapidly into market-wide cost adjustments.
Pricing Analysis
The technology-generation pricing gap is pronounced, with next-generation high-radix switches commanding significant premiums over prior-gen models. The dominant pricing structure is per-unit transactional, often bundled with multi-year software licenses and after-sales service contracts. Customization level and embedded security features drive significant price differentiation. Pricing pressure stems from the commoditization of basic Ethernet switches, making small-to-medium businesses highly price-sensitive compared to hyperscale cloud providers.
Supply Chain Analysis
High-performance processor and ASIC foundries form the critical upstream feedstock for network switches, with production heavily concentrated in Taiwan and South Korea. Key raw material dependencies include specialized silicon wafers, rare earth elements for internal components, and advanced packaging materials. A structural supply chain risk is the single-source vulnerability for advanced chipsets, creating potential chokepoints. Downstream, distribution runs through a mix of direct sales to large enterprises and cloud providers, alongside extensive channel partnerships with value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The network switch market is experiencing a platform-economics inflection, driven by the increasing interoperability demands of Software-Defined Networking (SDN) ecosystems. This shift redefines value creation beyond hardware, emphasizing integrated software and services.
For Market Incumbents: Entrench market leadership by aggressively investing in SDN controller development and securing long-term supply agreements for advanced semiconductor components. Diversify channel partnerships to reach emerging edge computing markets, mitigating the threat from specialized software-centric entrants. Continuous R&D in embedded security features remains a critical lever against evolving cybersecurity threats. Prioritize customer retention through outcome-based service models.
For New Entrants and Emerging Players: Geographic underpenetration in industrial IoT deployments across Southeast Asia and Latin America offers significant white-space targets. Focus on specialized, ruggedized industrial switches for operational technology networks, which remain underserved by traditional vendors. Leverage open-source network operating systems to reduce entry barriers and offer competitive software-defined solutions. A direct-to-enterprise go-to-market angle focusing on niche applications provides differentiation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across high-performance data center switches, signaling a long-term viability for specialized hardware manufacturers. Target acquisition archetypes include agile software-defined networking startups and niche providers of secure, ruggedized edge switches. The increasing demand for AI/ML workload optimization in data centers is a key signal to watch as an inflection indicator. Focus on companies with strong intellectual property in custom ASICs.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI/ML Optimized Switches | This initiative addresses the unique high-bandwidth demands of Artificial Intelligence training clusters. |
| Enhance SDN Controller Interoperability | Seamless integration with diverse Network Operating Systems expands market reach for enterprise clients. |
| Form Network-as-a-Service Partnerships | Collaboration with cloud providers shifts procurement to OpEx models for enterprise customers. |
| Acquire Edge Computing Hardware Specialist | Gaining expertise in compact, ruggedized switches supports low-latency edge applications. |
| Expand Industrial Market Footprint | Targeting smart factory deployments in Germany secures demand for specialized ruggedized switches. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase, combining insights from various industry stakeholders. Interviews included CTOs, IT procurement officers, network architects, and channel partners across key geographies. These primary insights were triangulated against extensive secondary data sources, including hyperscaler capital expenditure disclosures, telecommunications equipment certification databases, and national technology policy documents. A robust bottom-up and top-down approach ensured comprehensive market sizing and validation.
The calibration approach leveraged historical market data and projected technology adoption curves to model future growth across the analysis window. Segmentation dimensions modeled included product type, underlying technology, application area, end-user, and regional regulatory compliance frameworks. Compound annual growth rates were derived through a proprietary analytical framework, integrating macro-economic indicators with industry-specific growth catalysts. Key forecast inputs included projected data center build-out rates and Power over Ethernet device proliferation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new entrants or disruptive technology shifts would shift outcomes. Forecasts reflect assumptions regarding stable regulatory environments and consistent semiconductor supply chain performance. Cross-checking against major industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Global Network Management Market
Network Technology
Virtual Router Market
Network Technology
Global Routing Market
Network Technology
Network Management Solutions Market
Network Technology
Network Performance Monitoring Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Optical Network Equipment Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Network Telemetry Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Industrial Ethernet Market
Network Technology
Global Internet Transit Market
Network Technology
Intelligent Network Management Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market