
 Global Routing Market | 2026-2036
Global Routing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Routing Market Foresight
Enterprise procurement of routing infrastructure is rewriting how vendors compete for data center contracts. Cisco Systems leverages its installed base in enterprise campuses to sustain recurring service revenue. Huawei Technologies anchors supply relationships across Asia-Pacific through integrated optical-routing portfolios. Arista Networks specializes in low-latency spine architectures for cloud-scale environments.
Routing equipment directs packet traffic across IP networks using forwarding tables, buffer memory, and specialized ASICs operating at terabit-per-second throughput. Edge routers handle last-mile aggregation for enterprise branches and mobile base stations. Core routers dominate capital expenditure for internet backbone upgrades. Software-defined networking segments within enterprise networking applications are capturing margin pools as programmable control planes displace hardware-centric designs.
FCC spectrum policies in the United States, EU Cybersecurity Act certification requirements, and China's GB standards for network equipment collectively shape product roadmaps and market access timelines. ETSI NFV specifications and IEEE 802.1 time-sensitive networking standards further constrain interoperability claims. Stakeholders must weigh sovereign data routing mandates against the cost of region-specific hardware variants.
Market Dynamics
Hyperscale cloud providers are compressing refresh cycles for core routing infrastructure as AI training clusters demand terabit-scale east-west bandwidth. This demand concentration is forcing architectural shifts from chassis-based systems to disaggregated white-box platforms.
Growth Catalysts
- AI Workload Density:Cloud operators in Northern Virginia, Frankfurt, and Singapore are deploying 800G-capable spine fabrics to interconnect GPU clusters. This density surge mandates parallel upgrades to backbone aggregation layers.
- IPv6 Migration Mandates:Germany's BSI, Japan's MIC, and the US OMB have established procurement deadlines requiring native IPv6 support. Government and enterprise tenders now exclude legacy IPv4-only equipment.
- ETSI NFV Specifications:European telecom operators are virtualizing packet core functions. This standardization accelerates merchant silicon adoption and opens routing software to third-party vendors.
Market Restraints
- Merchant Silicon Concentration:Advanced routing ASIC supply concentrates among three foundry-dependent designers. Geopolitical trade restrictions disrupt delivery timelines for 7nm and 5nm process nodes.
- Optical Component Volatility:Coherent DSP and laser supply tightens during submarine cable build cycles. Input cost swings compress gross margins on high-capacity edge platforms.
- Technical Debt in Legacy MPLS:Enterprise WANs retain extensive label-switched path configurations. Migration to SRv6 segment routing demands parallel operational overhead during transition windows.
Strategic Opportunities
- India's BharatNet Expansion:The country's rural broadband initiative requires cost-optimized aggregation routers. Vendors offering indigenized hardware through the PLI scheme gain preferential access.
- Converged Optical-Routing:Integration of IP-over-DWDM functions collapses layer count in long-haul networks. This convergence reduces power consumption and rack space for inter-data-center connectivity.
- Subscription Software Models:Cloud-managed routing platforms enable recurring revenue streams. Channel partners in Southeast Asia are pivoting from box resale to lifecycle service contracts.
Industry Challenges
- Specialized Talent Scarcity:Expertise in P4 programming and SONiC-based network operating systems remains concentrated. Hiring timelines for control-plane software engineers extend beyond eighteen months.
- Certification Timeline Compression:Common Criteria EAL4+ and FIPS 140-3 validation cycles for government deployments now exceed product development schedules. This lag risks obsolescence before market entry.
- Interoperability Testing Burden:Multi-vendor segment routing deployments require extensive lab validation. Integration complexity delays production cutovers and strains professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Routing Market |
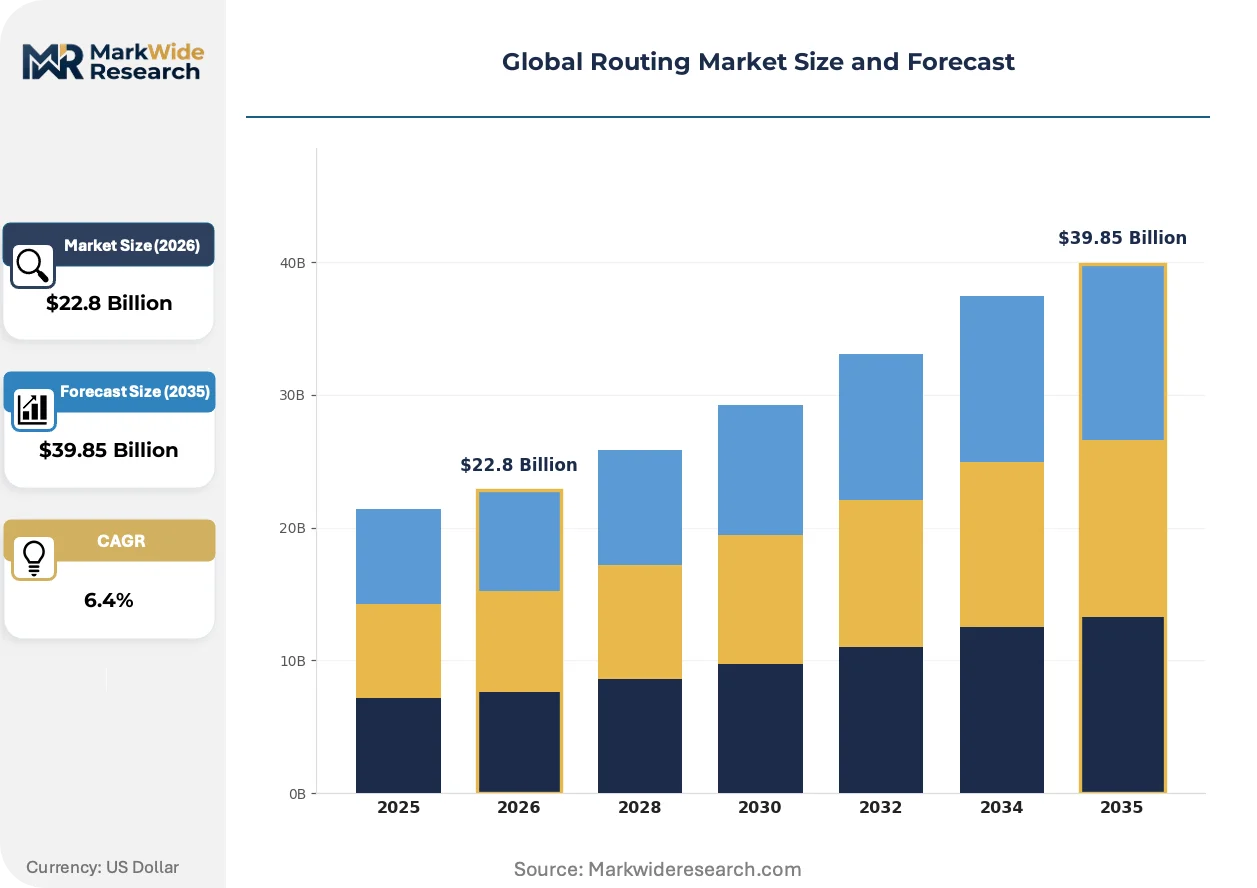
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Routers, Edge Routers, Virtual Routers, Wireless Routers, Industrial Routers Technology: Multiprotocol Label Switching, Border Gateway Protocol, Open Shortest Path First, Software-Defined Networking, Segment Routing Application: Enterprise Networking, Internet Service Providers, Data Centers, Cloud Connectivity, Content Delivery Networks End User: Telecommunication Carriers, Managed Service Providers, Government Agencies, Educational Institutions, Financial Organizations |
| Companies Covered | Cisco Systems, Huawei Technologies, Juniper Networks, Hewlett Packard Enterprise, Arista Networks, New H3C Technologies, ASUSTeK Computer, NETGEAR, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Routing Market Shifts & Advancements
Silicon photonics and programmable forwarding pipelines are converging to redefine cost-per-bit economics at network edge and core simultaneously. This convergence is compressing the traditional three-layer hierarchy into flattened fabrics.
Merchant silicon routing platforms built on Broadcom Tomahawk and Cisco Silicon One architectures are hybridizing hardware and software responsibilities. Cloud operators in hyperscale facilities are deploying these platforms to disaggregate control plane intelligence from forwarding engines. This architecture enables independent scaling of bandwidth and feature velocity, compressing traditional vendor lock-in cycles.
The EU Cybersecurity Act's Common Criteria certification scheme is mandating formal verification for network equipment processing sensitive data. Hardware vendors must submit ASIC designs and firmware to accredited evaluation facilities before CE marking. German critical infrastructure operators and French defense contractors are now excluding non-certified products from tender processes, extending procurement timelines by twelve to eighteen months.
Enterprise buyers are consolidating vendor relationships and demanding unified management planes across campus, branch, and cloud edge. Financial services firms in Singapore and healthcare networks in Switzerland are unbundling hardware acquisition from software licensing and operational support. This unbundling shifts margin capture toward multi-year SaaS contracts and away from perpetual license models.
Global Routing Market Segmentation
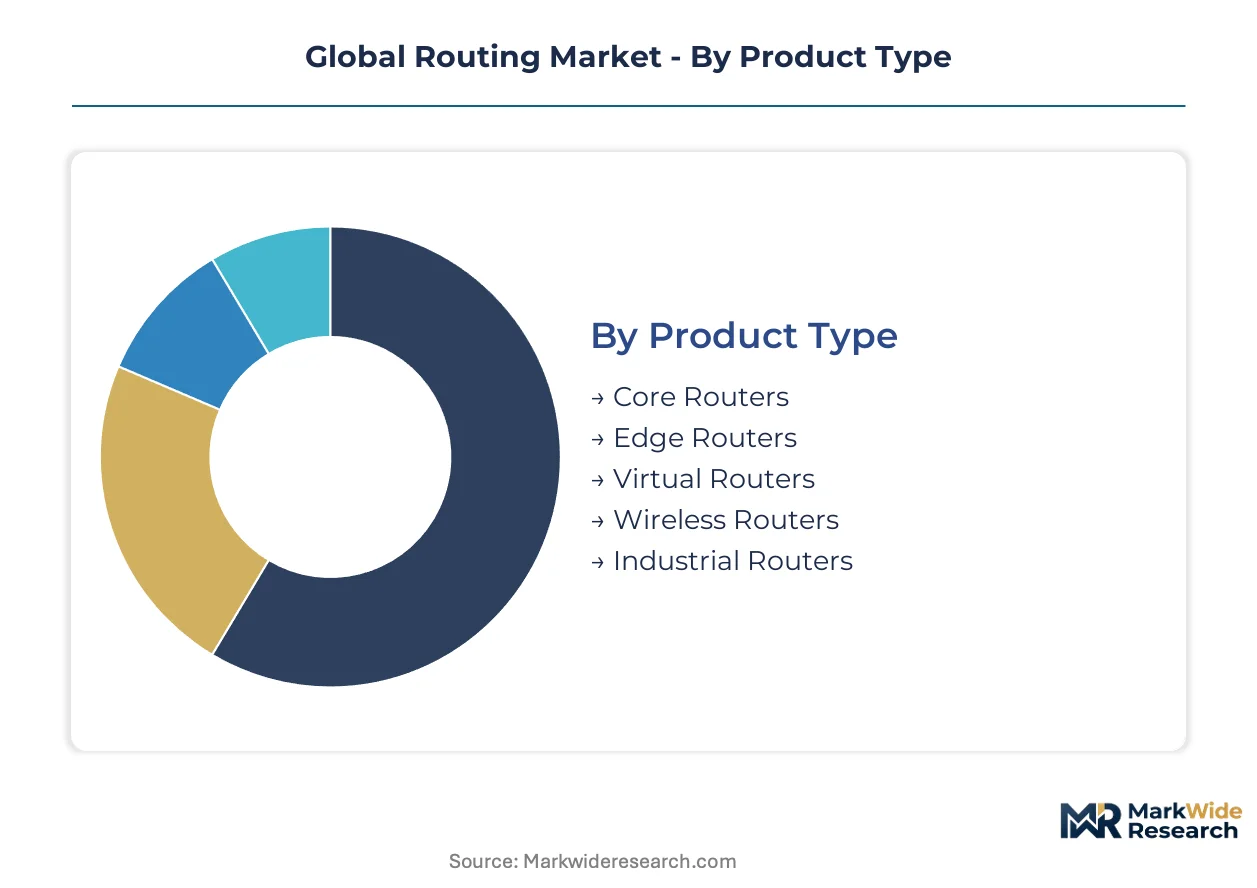
Routing infrastructure procurement patterns diverge sharply across deployment contexts, with service intensity and lifecycle support obligations varying by product architecture and customer operational maturity. Equipment vendors structure warranty tiers and professional services attach rates around these segment boundaries, creating distinct margin profiles that reshape competitive positioning.
Product Type:
After-sales service intensity escalates with chassis complexity and mean-time-between-failure sensitivity, driving multi-year support contracts for high-capacity platforms.
- Core Routers:These centralized switching platforms process petabit-scale aggregate traffic through redundant fabric cards and line-rate forwarding engines. Hyperscale facilities in Northern Virginia and Frankfurt mandate 800G-capable backplane upgrades to interconnect AI training clusters, compressing refresh cycles from five to three years.
- Edge Routers:Distributed aggregation nodes consolidate last-mile traffic from enterprise branches and mobile base stations using modular interface cards. India's BharatNet rural broadband initiative is driving volume demand for cost-optimized 100G platforms with indigenized hardware content.
- Virtual Routers:Cloud-native forwarding instances running on commodity servers enable elastic capacity scaling without physical hardware swaps.
- Wireless Routers:Integrated access platforms combine cellular baseband processing with IP routing for mobile backhaul and private 5G networks.
- Industrial Routers:Hardened platforms withstand temperature extremes and vibration in manufacturing floors, utility substations, and transportation infrastructure.
Core routers hold the largest share; momentum sits with virtual routers expanding most quickly as cloud operators disaggregate hardware from control plane software.
Technology:
Cost tier differentiation separates legacy protocol implementations from programmable forwarding pipelines, with premium pricing attached to software-defined control planes.
- Multiprotocol Label Switching:Established traffic engineering technology uses label-switched paths to prioritize latency-sensitive flows across carrier backbones. Technical debt burdens in existing MPLS deployments are slowing enterprise migration timelines to newer architectures.
- Software-Defined Networking:Centralized controllers program forwarding behavior through open APIs, enabling automation and policy-driven network management. ETSI NFV specifications are accelerating merchant silicon adoption among European telecom operators virtualizing packet core functions.
- Border Gateway Protocol:The inter-domain routing standard exchanges reachability information between autonomous systems on the public internet.
- Open Shortest Path First:Link-state interior gateway protocol calculates shortest paths for enterprise campus and data center networks.
- Segment Routing:Source-based path steering using SRv6 headers collapses MPLS label distribution complexity while enabling traffic engineering.
MPLS retains dominant installed base; SDN architectures are climbing the fastest as programmable control planes displace hardware-centric designs.
Application:
Customer type concentration shapes procurement volume, with hyperscale cloud operators commanding custom silicon roadmaps and dedicated supply allocation.
- Data Centers:Spine-leaf architectures interconnect server racks through low-latency switching fabrics optimized for east-west traffic patterns. Singapore's data center cluster is deploying 800G-capable platforms to support GPU-intensive AI inference workloads.
- Internet Service Providers:Backbone aggregation and peering infrastructure requires terabit-scale throughput with five-nines reliability commitments. Germany's BSI procurement mandates for native IPv6 support are excluding legacy equipment from government tenders.
- Enterprise Networking:Campus and branch connectivity prioritizes unified management planes and zero-touch provisioning capabilities.
- Cloud Connectivity:Direct cloud on-ramps and dedicated interconnects demand consistent latency for hybrid workload placement.
- Content Delivery Networks:Distributed caching nodes require high-density 100G/400G ports for origin server synchronization.
Data center applications command premium pricing tiers; cloud connectivity is gaining share fastest as enterprise workload migration accelerates.
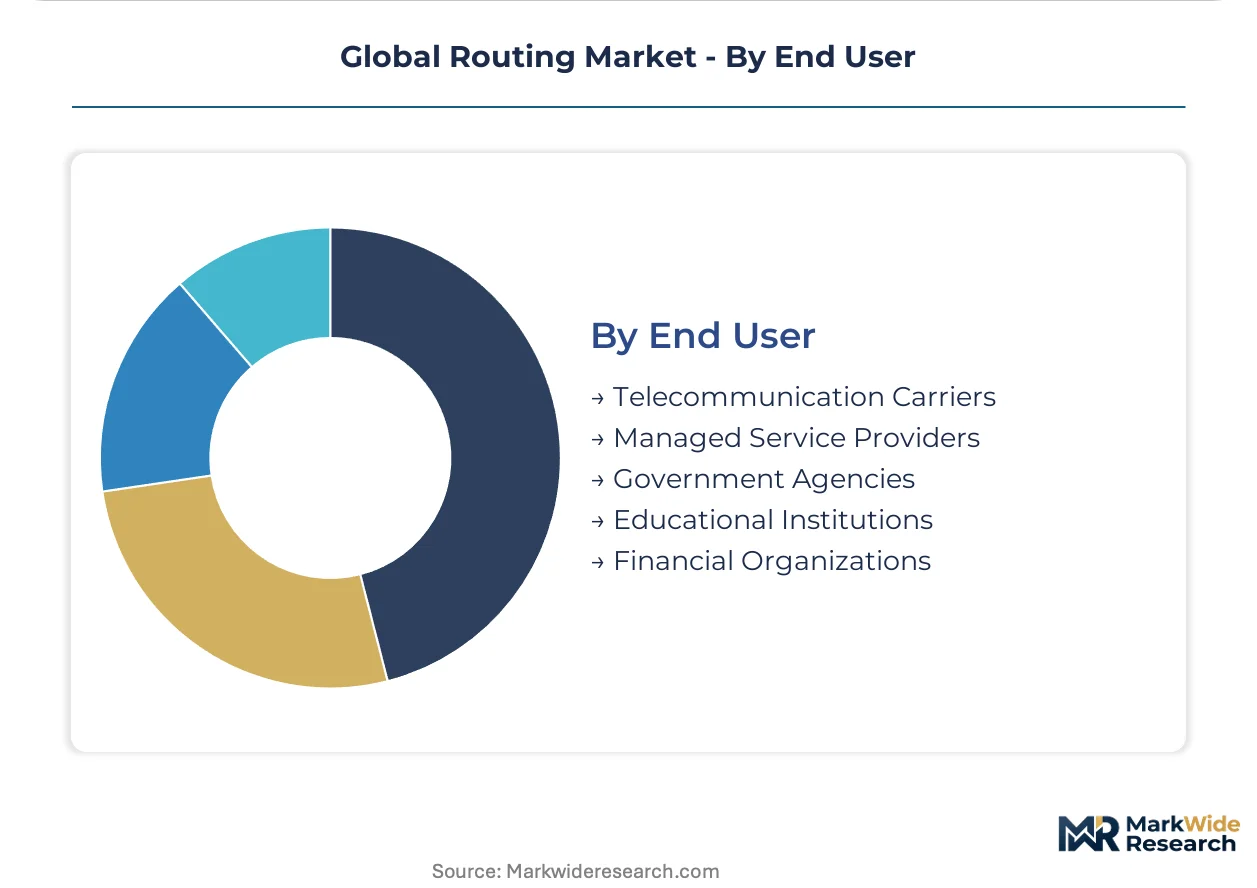
End User:
Margin maturity varies by buyer sophistication, with financial organizations demanding formal verification and extended validation cycles that extend sales timelines.
- Telecommunication Carriers:National backbone operators procure chassis-based systems through multi-year framework agreements with stringent reliability specifications. Japan's MIC has established IPv6 migration deadlines that now exclude IPv4-only equipment from procurement eligibility.
- Financial Organizations:Trading networks and payment infrastructure require microsecond-level latency with deterministic performance guarantees. Swiss banking regulators are mandating Common Criteria EAL4+ certification for network equipment processing transaction data.
- Government Agencies:Defense and civilian networks prioritize supply chain security and domestic content requirements.
- Managed Service Providers:Multi-tenant platform operators seek cloud-managed routing with subscription billing models.
- Educational Institutions:Research networks and campus connectivity balance performance requirements against constrained capital budgets.
Telecommunication carriers represent the largest procurement volume; financial organizations are expanding most quickly as low-latency trading infrastructure demands accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum policies in the United States, Germany's BSI procurement mandates, and Japan's MIC IPv6 deadlines are collectively redirecting vendor investment toward certified, next-generation platforms. Cloud operators in Northern Virginia, Frankfurt, and Singapore are compressing backbone refresh cycles to support AI workload density.
United States
Hyperscale facilities in Northern Virginia deploy 800G-capable spine fabrics for GPU cluster interconnect. The FCC's spectrum allocation policies shape mobile backhaul router specifications for 5G densification. Cloud operators in Ashburn and Loudoun County command custom silicon roadmaps from merchant silicon vendors.
Germany
Frankfurt's data center cluster anchors European demand for core router upgrades with native IPv6 support. BSI procurement mandates exclude legacy IPv4-only equipment from government tenders. Critical infrastructure operators in Hesse prioritize Common Criteria EAL4+ certified platforms for financial and defense networks.
Japan
Tokyo's internet exchange points drive demand for terabit-scale peering infrastructure. MIC-established IPv6 migration deadlines now bar IPv4-only routers from carrier procurement eligibility. NTT and KDDI backbone operators in the Kanto region accelerate disaggregated white-box deployments.
Singapore
The city-state's data center cluster deploys 800G platforms for AI inference workload aggregation. IMDA regulatory frameworks mandate cybersecurity certification for network equipment processing financial data. Cloud operators in Jurong and Tuas concentrate capital expenditure on low-latency spine architectures.
India
BharatNet's rural broadband initiative requires cost-optimized aggregation routers for village-level connectivity. PLI scheme incentives favor vendors offering indigenized hardware content. State-run BSNL and private operators in Maharashtra and Gujarat expand 100G edge router deployments.
Global Routing Market Competitive Landscape
On the supply side, the industry is consolidating around three merchant silicon-dependent designers for advanced routing ASICs, with geopolitical trade restrictions disrupting 7nm and 5nm process node delivery. Tiered competition separates chassis-based incumbents from disaggregated white-box specialists and cloud-native software vendors. Dominant competitive moves include strategic partnerships for optical-routing convergence and geographic expansion through indigenization schemes in India and Southeast Asia.
Within the incumbent tier, Cisco Systems and Juniper Networks occupy positions sustained by installed base service revenue and carrier framework agreements. Arista Networks exemplifies the cloud-scale specialist archetype, anchoring low-latency spine deployments for hyperscale facilities. Huawei Technologies sits within the integrated portfolio segment, though supply constraints in Western markets redirect its Asia-Pacific focus.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Arista Networks |
| New H3C Technologies |
| ASUSTeK Computer |
| NETGEAR |
| Nokia Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in merchant silicon foundries serving the 7nm and 5nm process nodes is compressing ASIC pricing premiums while simultaneously constraining supply allocation to tier-one routing vendors. This utilization asymmetry forces equipment manufacturers to pre-commit wafer starts eighteen months ahead of demand, locking in cost structures before pricing negotiations with hyperscale buyers conclude.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with Common Criteria EAL4+ and FIPS 140-3 validated platforms commanding substantial premiums over uncertified alternatives. The dominant pricing structure combines perpetual hardware licensing with multi-year SaaS support contracts, particularly for cloud-managed edge deployments. Cost compression in core router chassis is intensifying because merchant silicon commoditizes forwarding plane differentiation. Government agencies and financial organizations exhibit the lowest price sensitivity due to mandated certification requirements, while India's rural broadband initiative and Southeast Asian MSPs drive volume demand at aggressive price points.
Supply Chain Analysis
TSMC and Samsung Foundry hold concentrated capacity for advanced routing ASICs at 7nm and below, with Intel Foundry Services emerging as a secondary source for less aggressive geometries. Taiwan, South Korea, and the United States anchor geographic supply concentration for merchant silicon design and fabrication. Coherent DSPs, laser components, and specialized buffer memory draw from Japanese and German optical component specialists. Single-source vulnerability in coherent optical subassembly supply creates exposure during submarine cable build cycles. Distribution runs through direct OEM relationships with hyperscale cloud operators and tiered channel partners serving enterprise and government verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Routing Market is undergoing high-growth disruption as AI workload density forces architectural shifts from chassis-based systems to disaggregated white-box platforms, with IPv6 migration mandates from Germany's BSI, Japan's MIC, and the US OMB compressing procurement timelines for next-generation equipment.
For Market Incumbents: Harden recurring revenue streams through multi-year SaaS support contracts attached to merchant silicon platforms, insulating against margin erosion from white-box competition. Deepen backward integration into optical component supply through strategic partnerships with coherent DSP vendors, reducing exposure to laser and modulator price volatility. Prioritize certification investment for Common Criteria EAL4+ and EU Cybersecurity Act compliance to maintain eligibility in German critical infrastructure and French defense tenders. For New Entrants and Emerging Players: India's BharatNet rural broadband expansion represents the most penetrable geographic underpenetration, with PLI scheme incentives favoring indigenized hardware content for cost-optimized 100G edge aggregation. Target Southeast Asian managed service providers pivoting from box resale to lifecycle service contracts, where cloud-managed routing platforms enable subscription revenue conversion. Pursue SONiC-based network operating system specialization as the primary go-to-market angle, addressing talent scarcity in P4 programming and control-plane software engineering. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native software vendors with merchant silicon-agnostic routing platforms, positioning these archetypes for premium valuation multiples. Over the projection horizon, vertically integrated specialists with captive optical component supply and established carrier framework agreements demonstrate superior margin resilience. Monitor hyperscale capex disclosure trends for AI training cluster buildouts as the critical inflection indicator for backbone router demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Platform Development | Enables disaggregated white-box architectures for hyperscale cloud operators in Northern Virginia and Frankfurt. |
| Optical-Routing Convergence Partnership | Collapses layer count in long-haul networks, reducing power consumption for inter-data-center connectivity. |
| IPv6-Native Product Certification | Secures procurement eligibility under Germany's BSI, Japan's MIC, and US OMB migration mandates. |
| Indigenized Hardware Localization | Unlocks preferential access to India's BharatNet rural broadband initiative through PLI scheme compliance. |
| Cloud-Managed SaaS Transition | Captures recurring revenue streams as Southeast Asian channel partners pivot from perpetual license resale. |
Research Methodology
Initial hypotheses were tested against primary input from network engineering executives at hyperscale cloud operators, carrier backbone procurement leads, enterprise IT infrastructure directors, and optical component supply specialists, then refined through secondary validation. SEC filings from merchant silicon vendors, hyperscaler capex disclosures, ETSI NFV specification documents, and national regulatory procurement mandates provided quantitative anchors. Bottom-up equipment shipment estimates triangulated against top-down addressable market sizing derived from data center construction permits and broadband subsidy program allocations.
Demand-supply balance modeling across the analysis window incorporated hyperscale AI cluster buildout timelines, IPv6 migration regulatory deadlines, and foundry capacity allocation for advanced process nodes. Segmentation dimensions included product architecture (chassis-based versus disaggregated), control plane technology (hardware-centric versus SDN-programmable), deployment context (data center core, edge aggregation, enterprise branch), and end-user sophistication (carrier framework agreements versus spot procurement). CAGRs were derived from slope-intercept analysis of historical equipment refresh cycles adjusted for AI-driven compression effects.
Practitioners should monitor foundry utilization rates, coherent optical component lead times, and hyperscale capex guidance revisions for early signals of supply constraint or demand inflection. Forecasts reflect assumptions regarding regulatory deadline adherence, merchant silicon roadmap execution, and geopolitical trade restriction stability. Quarterly review of national broadband subsidy disbursements, data center permitting velocity, and carrier backbone RFP issuance patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Gigabit Ethernet Market
Network Technology
US Private 5G Network Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Global LWAN Market
Network Technology
Passive Optical Network Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Gigabit Wi-Fi Access Points Market
Network Technology
Low-Power WAN Market
Network Technology
Industrial Ethernet Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Private Network Services Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Carrier Wi-Fi Equipment Market