
 Optical Wireless Communication and Li-Fi Market | 2026-2036
Optical Wireless Communication and Li-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Wireless Communication and Li-Fi Market Analytics
Multi-source procurement for LED and photodetector components is broadening as vendors diversify beyond traditional RF semiconductor supply chains. PureLiFi Limited leverages its Edinburgh-based R&D campus to sustain intellectual property leadership in IEEE 802.11bb standardization. Signify Holding BV anchors the luminaire-to-communication hardware pipeline through its global lighting installed base. Renesas Electronics Corporation competes by integrating Li-Fi modulators with its microcontroller portfolios for embedded OEM designs.
Optical Wireless Communication and Li-Fi encompasses data transmission through modulated visible, infrared, or ultraviolet light, typically operating at wavelengths between 400 and 700 nanometers with modulation bandwidths exceeding one gigahertz in commercial-grade LEDs. The technology serves environments where electromagnetic interference must be eliminated or where radio frequency spectrum congestion renders conventional wireless impractical, including hospital operating theaters and aircraft cabins. Li-Fi and VLC technologies capture the dominant share of near-term deployment value as lighting infrastructure retrofit cycles accelerate. Data centers and smart lighting applications generate the steepest growth trajectories among application segments, driven by latency-sensitive machine-to-machine coordination and building automation convergence.
The Federal Communications Commission in the United States and the European Telecommunications Standards Institute jointly shape market access through spectrum allocation rulings and optical wireless certification frameworks that determine interoperability requirements. Japan's Ministry of Internal Affairs and Communications accelerates domestic adoption through targeted R&D subsidies for visible light communication integration with 6G roadmaps. Stakeholders must monitor which standardization body secures de facto protocol dominance, as this will determine patent licensing structures and hardware compatibility obligations for the next decade of infrastructure deployment.
Market Dynamics
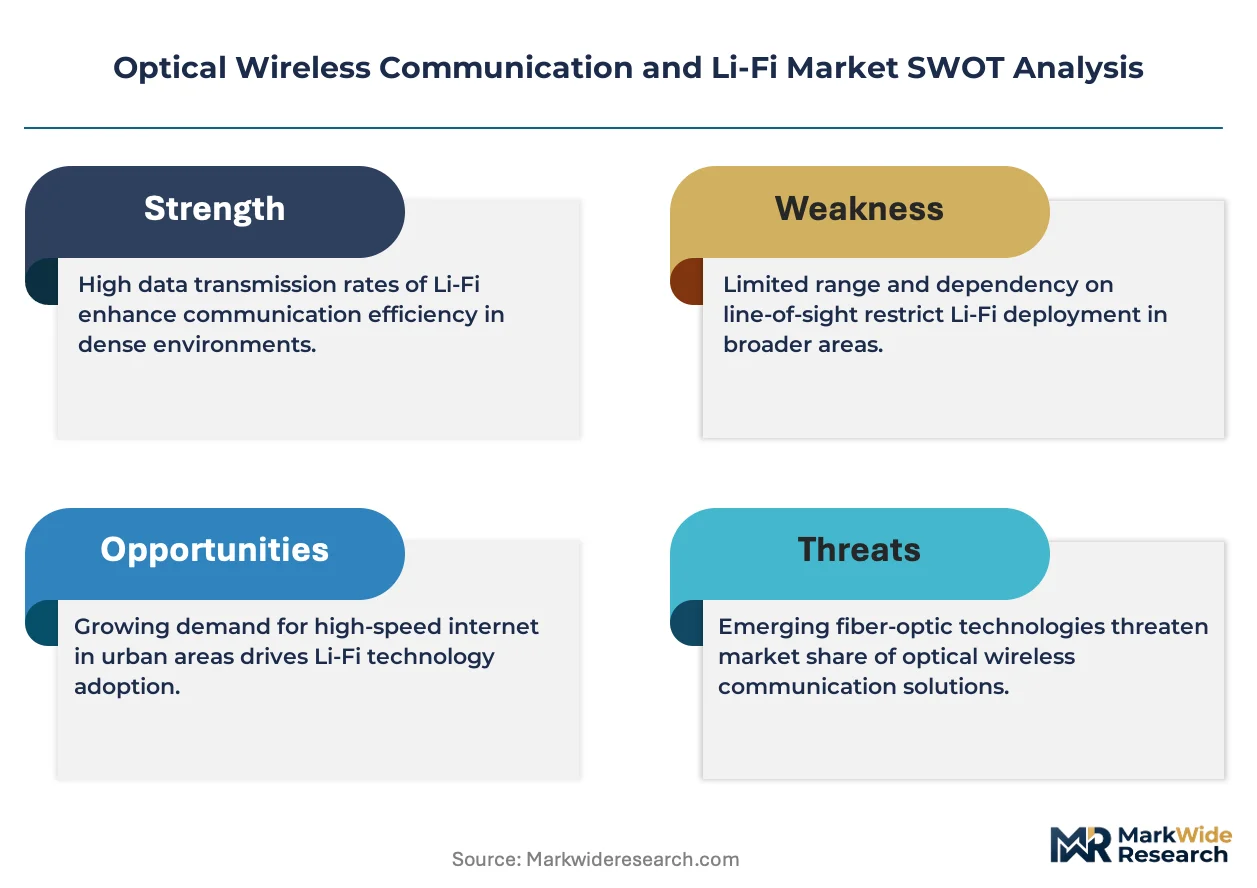
The transition from RF-dependent connectivity to optical alternatives is compressing deployment timelines across electromagnetic-sensitive environments, with IEEE 802.11bb ratification eliminating interoperability uncertainty that previously stalled capital allocation.
Growth Catalysts
- Spectrum congestion relief:The FCC's spectrum allocation rulings and ETSI's optical wireless certification frameworks are accelerating Li-Fi deployment in hospital operating theaters where RF interference risks patient safety.
- Industrial automation demand:Factory-floor machine-to-machine coordination in Germany's automotive R&D centers is piloting Li-Fi networks for latency-sensitive robotics control.
- Defense procurement expansion:Secure line-of-sight data links for aerospace integrators are displacing conventional RF in classified communications infrastructure.
Market Restraints
- Photodetector supply concentration:Specialized avalanche photodiode manufacturing concentrates among a limited vendor base, creating input cost volatility for OEM module assemblers.
- Line-of-sight limitation:The fundamental physics of visible light propagation restricts mobility applications, capping addressable market scope in consumer electronics.
- Retrofit capex burden:Existing LED infrastructure requires controller replacement and network backbone upgrades, extending payback periods for building automation deployments.
Strategic Opportunities
- Data center density:Server-to-server optical interconnects within hyperscale facilities in Singapore and Ireland are bypassing copper cable electromagnetic constraints.
- 6G convergence:Japan's Ministry of Internal Affairs and Communications R&D subsidies are integrating visible light communication into next-generation mobile roadmaps.
- Underwater communications:Subsea oilfield robotics and aquaculture monitoring represent greenfield applications where RF propagation fails entirely.
Industry Challenges
- Optical engineering talent scarcity:The intersection of photonics design and RF protocol engineering creates recruitment friction for product development teams.
- Multi-standard certification complexity:Simultaneous IEEE 802.11bb, IEC safety, and national telecom equipment approvals extend time-to-market for hardware vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Wireless Communication and Li-Fi Market |
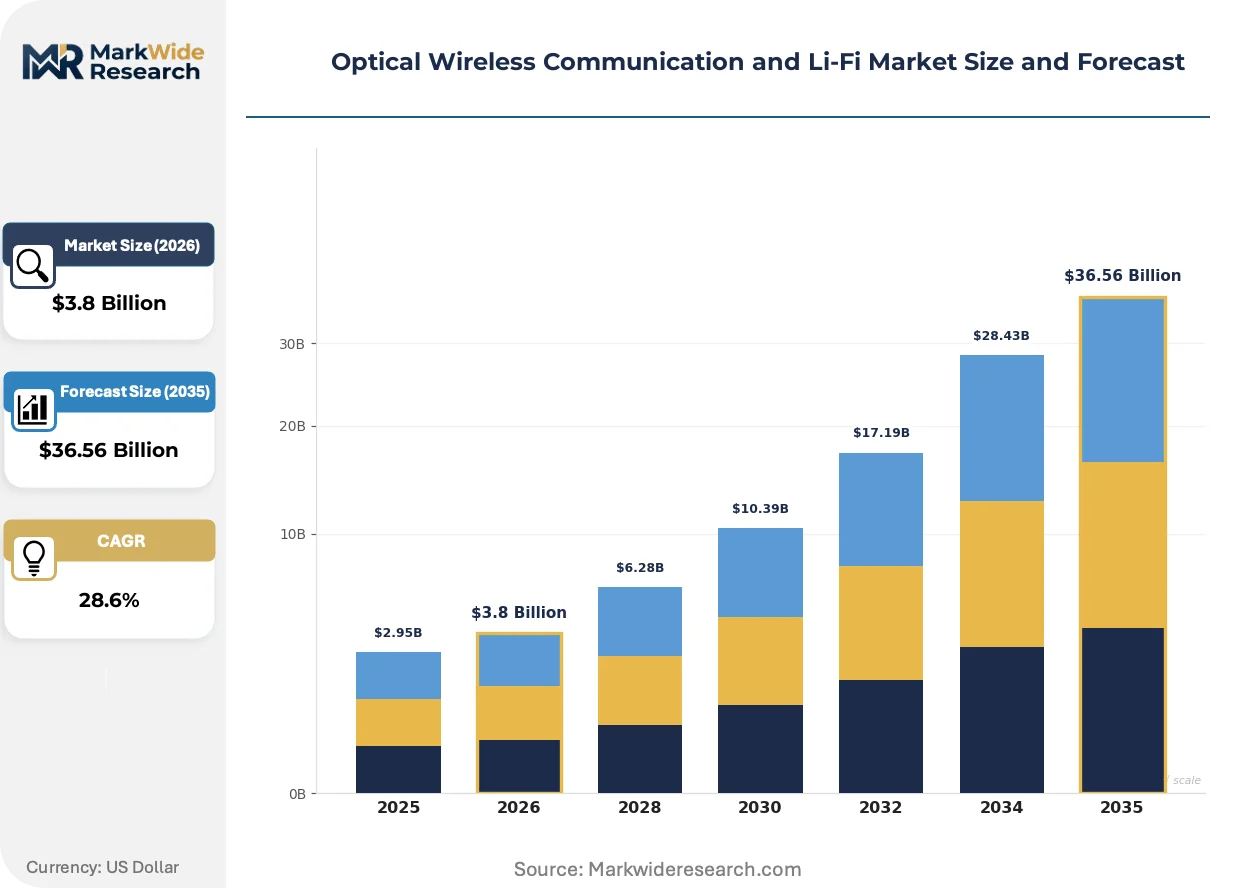
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Li-Fi, VLC, FSO, Optical Infrared Application: Smart Lighting, Data Centers, Internet Access, Underwater Communication End User: Healthcare, Educational Institutions, Transportation, Government Delivery Mode: Point-to-Point, Broadcast, Multi-User, Point-to-Multipoint |
| Companies Covered | Oledcomm SAS, Velmenni, Signify Holding BV, Renesas Electronics Corporation, General Electric, PureLiFi Limited, VLNComm Inc., Acuity Brands, Inc., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Wireless Communication and Li-Fi Market Evolving Landscape
Modulation bandwidth expansion in commercial-grade LEDs is automating the boundary between illumination and communication infrastructure, collapsing what were historically separate capital budgets into unified smart building investments.
Micro-LED arrays with sub-nanosecond switching speeds are automating gigabit-per-second throughput in aircraft cabin entertainment systems. Airlines including Emirates and Lufthansa are retrofitting narrow-body fleets to eliminate RF interference with avionics. This compression of installation complexity is reducing MRO contractor certification timelines from eighteen to six months.
The European Commission's Radio Spectrum Policy Programme is mandating spectrum-efficient alternatives across member states, directly channeling public infrastructure grants toward visible light communication. Municipal lighting tenders in Rotterdam and Barcelona now weight Li-Fi compatibility at fifteen percent of technical scoring. Hardware vendors are reconfiguring sales organizations to pursue utilities rather than IT departments.
Buying committees for smart lighting have shifted from facilities managers to CIO-led digital transformation teams, unbundling luminaire procurement from network architecture decisions. Channel partners in North American commercial real estate are restructuring around system integrators capable of converging building automation with enterprise WLAN. This reorganization is most pronounced in Class A office developments across Manhattan and San Francisco where tenant connectivity specifications now exclude copper backbone requirements.
Optical Wireless Communication and Li-Fi Market Segmentation
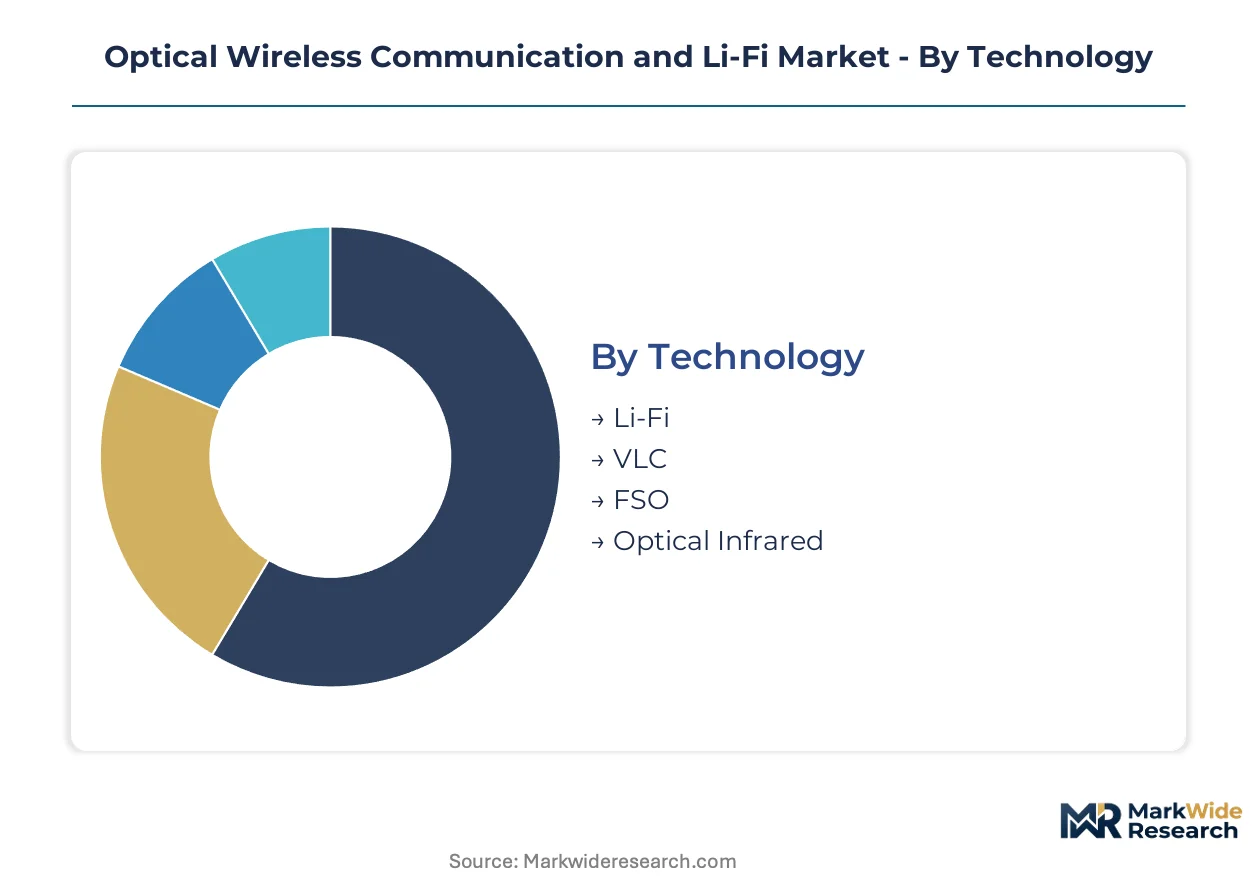
Li-Fi and optical wireless technologies fragment across multiple deployment architectures, each demanding distinct capital commitments and technical integration paths. Understanding segment boundaries reveals where infrastructure spending concentrates and which configurations justify premium pricing.
Technology:
Capital intensity varies sharply across these four technology families, with photodetector array density and LED modulation bandwidth driving upfront hardware costs.
- Li-Fi:IEEE 802.11bb-compliant systems deploy gallium-nitride micro-LED arrays with sub-nanosecond switching for gigabit throughput. Hospital operating theaters in Germany pilot these networks to eliminate electromagnetic interference with patient monitoring equipment.
- VLC:Visible light communication operates through standard phosphor-converted white LEDs without dedicated communication chipsets, lowering per-node costs. Municipal streetlight retrofits in Rotterdam and Barcelona favor this tier for smart city backbone applications.
- FSO:Free-space optical links deploy telescopic transceivers for kilometer-scale point-to-point connectivity. Defense integrators fund these deployments for secure base-to-base communications where fiber trenching proves impractical.
- Optical Infrared:Infrared-based systems bypass visible spectrum constraints for always-on connectivity in aircraft cabins. Emirates and Lufthansa narrow-body retrofits demonstrate commercial viability.
Li-Fi absorbs the bulk of installed capacity; VLC is expanding most quickly.
Application:
Deployment complexity scales with environmental electromagnetic sensitivity and latency requirements.
- Smart Lighting:Converged illumination-communication infrastructure collapses separate capital budgets into unified building automation investments. Class A office developments in Manhattan and San Francisco now exclude copper backbone requirements from tenant specifications.
- Data Centers:Server-to-server optical interconnects within hyperscale facilities bypass copper cable electromagnetic constraints. Singapore and Ireland host the steepest deployment trajectories among colocation markets.
- Internet Access:Consumer-facing connectivity faces mobility limitations from line-of-sight physics, restricting addressable scope despite IEEE 802.11bb standardization.
- Underwater Communication:Subsea oilfield robotics and aquaculture monitoring represent greenfield applications where RF propagation fails entirely.
Smart Lighting carries the heaviest cumulative deployment value; Data Centers show the steepest expansion trajectory.
End User:
Procurement authority shifts dramatically across these verticals, from facilities managers to CIO-led digital transformation teams.
- Healthcare:Operating theater EMI elimination drives capital allocation, with FCC spectrum rulings and ETSI certification frameworks accelerating adoption.
- Educational Institutions:Campus-wide deployments compete with conventional Wi-Fi upgrade cycles, extending sales cycles.
- Transportation:Aircraft cabin retrofits and automotive R&D centers in Germany generate concentrated demand for latency-sensitive machine coordination.
- Government:Classified communications infrastructure displaces conventional RF for secure line-of-sight data links.
Healthcare dominates near-term revenue concentration; Government procurement shows the most aggressive displacement of legacy RF.
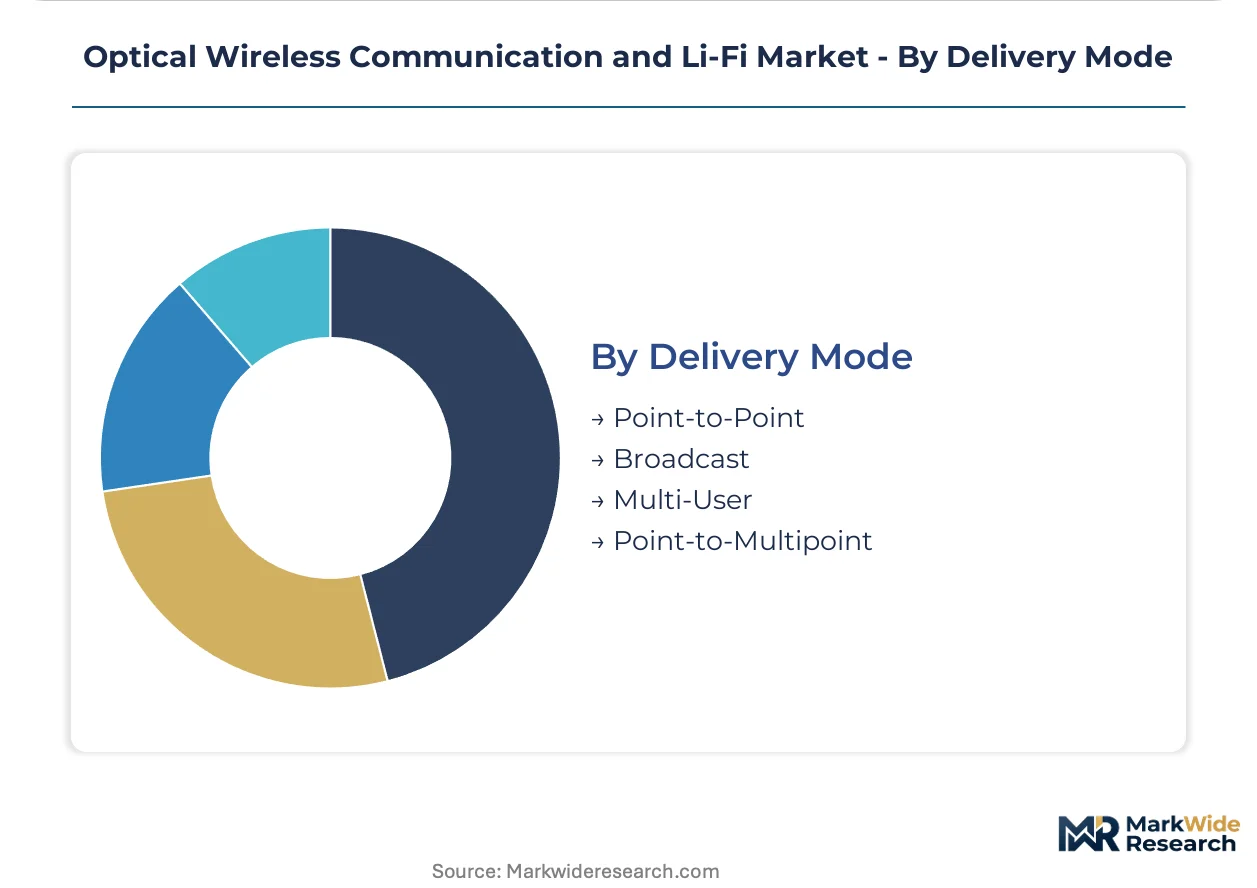
Delivery Mode:
Network topology selection determines photodetector count, optical beam steering complexity, and software-defined resource allocation requirements.
- Point-to-Point:Dedicated transceiver pairs maximize security and bandwidth efficiency for defense and financial sector backhaul.
- Broadcast:Single-to-many transmission suits public information dissemination with minimal upstream capability.
- Multi-User:Spatial division multiple access enables concurrent sessions through micro-LED array subdivision, demanding sophisticated signal processing.
- Point-to-Multipoint:Hub-and-spoke architectures reduce per-node hardware costs for building automation deployments.
Point-to-Point absorbs premium pricing; Multi-User configurations are climbing the fastest as micro-LED costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium-nitride substrate fabrication in the United States and precision photodetector manufacturing in Japan anchor geographic supply chains for optical wireless components.
United States
Defense procurement for secure line-of-sight data links and hyperscale data center expansion in Virginia and Oregon drive deployment. The FCC's spectrum allocation rulings accelerate hospital operating theater installations. San Francisco and Manhattan Class A office developments now exclude copper backbone requirements from tenant specifications.
Germany
Industrial automation clusters and automotive R&D centers pilot factory-floor Li-Fi networks for latency-sensitive robotics control. The European Commission's Radio Spectrum Policy Programme channels public infrastructure grants toward visible light communication. Stuttgart and Munich host concentrated pilot programs integrating Li-Fi with Industry 4.0 architectures.
Japan
6G roadmap integration and aircraft cabin retrofit programs for Emirates and Lufthansa generate component demand. METI's R&D subsidies accelerate visible light communication adoption. Tokyo and Nagoya electronics corridors concentrate micro-LED array manufacturing for sub-nanosecond switching applications.
Singapore
Hyperscale colocation facilities deploy server-to-server optical interconnects to bypass copper electromagnetic constraints. The Infocomm Media Development Authority promotes spectrum-efficient alternatives. Data center clusters in Jurong and Tanjong Kling host the steepest deployment trajectories in Southeast Asia.
Netherlands
Municipal lighting tenders in Rotterdam weight Li-Fi compatibility at fifteen percent of technical scoring. Signify Holding BV's Eindhoven headquarters anchors luminaire-to-communication hardware pipelines. Randstad utilities now structure procurement around converged illumination-communication infrastructure.
Optical Wireless Communication and Li-Fi Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge lighting infrastructure and semiconductor expertise. The vendor base organizes around three tiers: established lighting conglomerates with global installed bases, specialized Li-Fi pure-plays with IEEE 802.11bb standardization leadership, and diversified electronics manufacturers integrating optical modulators into microcontroller portfolios. Competitive positioning hinges on technology licensing agreements and joint development programs with building automation integrators.
Within the pure-play specialist tier, PureLiFi Limited and Oledcomm SAS exemplify R&D-intensive models centered on standard-setting and intellectual property accumulation. Signify Holding BV and Acuity Brands, Inc. occupy positions reflecting lighting-to-communication convergence strategies. Renesas Electronics Corporation represents the embedded semiconductor integration archetype, leveraging existing microcontroller distribution channels.
| Leading Market Players |
|---|
| Oledcomm SAS |
| Velmenni |
| Signify Holding BV |
| Renesas Electronics Corporation |
| General Electric |
| PureLiFi Limited |
| VLNComm Inc. |
| Acuity Brands, Inc. |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Defense procurement specifications for secure line-of-sight data links are tightening electromagnetic interference tolerances, forcing module assemblers toward specialized avalanche photodiode vendors and compressing margins on standardized LED arrays.
Pricing Analysis
Warranty and service bundling separates premium Li-Fi deployments from commodity VLC retrofits, with IEEE 802.11bb certification and multi-year maintenance contracts commanding substantial premiums over unbundled hardware transactions. Three-tier pricing structure across premium, standard, and economy levels reflects photodetector array density and LED modulation bandwidth specifications. Cost compression in the standard tier is intensifying because municipal lighting tenders in Rotterdam and Barcelona now weight Li-Fi compatibility at fifteen percent of technical scoring. Government and defense integrators exhibit the lowest price sensitivity, while educational institutions competing with conventional Wi-Fi upgrade cycles drive the most aggressive procurement negotiations.
Supply Chain Analysis
Domestic-content mandates in Japan's Ministry of Internal Affairs and Communications R&D programs are reshaping sourcing patterns for micro-LED arrays, redirecting component flows toward Tokyo and Nagoya electronics corridors. Gallium-nitride substrate fabrication concentrates in the United States and Japan, while precision photodetector manufacturing draws from Japanese and German precision optics clusters. Specialized avalanche photodiode supply rests on a limited vendor base, creating single-source vulnerability for OEM module assemblers. Distribution runs through lighting conglomerates with global installed bases and semiconductor distributors serving embedded OEM designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Avalanche photodiode manufacturing capacity constraints are propping pricing power for qualified vendors, as defense and healthcare procurement timelines outstrip photodetector foundry expansion.
For Market Incumbents: Deepen backward integration into gallium-nitride substrate fabrication to secure input cost stability against RF semiconductor supply chain volatility. Expand IEEE 802.11bb certification investment to maintain interoperability leadership as ETSI and FCC frameworks converge. Control channel relationships with building automation integrators to defend against lighting-to-communication convergence strategies from diversified electronics manufacturers.
For New Entrants and Emerging Players: Capture underwater communications deployments for subsea oilfield robotics and aquaculture monitoring, where RF propagation failures create uncontested white space. Target municipal lighting retrofits in European smart city programs, where the European Commission's Radio Spectrum Policy Programme channels public infrastructure grants toward visible light communication. Pursue system integrator partnerships rather than direct luminaire sales to bypass Signify Holding BV's global installed base advantage.
For Investors and Strategic Acquirers: The window for entry favors photonics design specialists with RF protocol engineering capabilities, as optical engineering talent scarcity creates acquisition premiums for qualified teams. Long-term viability hinges on standardization body dominance determining patent licensing structures across the next decade of infrastructure deployment. Monitor IEEE 802.11bb ratification velocity as the inflection indicator for capital allocation acceleration in electromagnetic-sensitive environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | IEEE 802.11bb ratification eliminates interoperability uncertainty previously stalling hospital and defense procurement. |
| Strategic Partnership | Joint development programs with building automation integrators bridge lighting infrastructure and semiconductor expertise gaps. |
| Acquisition of Specialist Firm | Photonics design specialists with sub-nanosecond switching capabilities command premiums from aircraft cabin retrofit programs. |
| Geographic Expansion | Germany's industrial automation clusters and automotive R&D centers pilot factory-floor networks for latency-sensitive robotics control. |
| Technology Licensing | Patent licensing structures from IEEE 802.11bb standardization leadership determine hardware compatibility obligations for OEM module assemblers. |
Research Methodology
Document review covered FCC spectrum allocation rulings, ETSI optical wireless certification frameworks, and IEEE 802.11bb standardization proceedings, complemented by interviews with Li-Fi module engineering directors, hospital biomedical equipment managers, defense procurement officers, smart lighting facilities directors, and semiconductor distribution channel partners. Secondary validation drew from SEC filings of lighting conglomerates, European Commission Radio Spectrum Policy Programme documentation, Japan METI R&D subsidy disclosures, and hyperscale data center capex announcements. Bottom-up deployment tracking across hospital operating theaters, aircraft cabin retrofit programs, and factory-floor pilot networks was triangulated against top-down infrastructure spending forecasts.
Market sizing outputs reflect segment-level modeling across technology families, application environments, end-user verticals, and network topology configurations throughout the forecast period. CAGRs were derived from deployment timeline compression in electromagnetic-sensitive environments and retrofit cycle acceleration in commercial LED infrastructure. Industry-specific forecast inputs incorporated IEEE 802.11bb ratification schedules, gallium-nitride micro-LED cost decline curves, and defense procurement budget allocations for secure communications infrastructure.
The model holds under stable spectrum allocation regimes and continued LED infrastructure replacement cycles; deviation in regulatory certification timelines or photodetector supply disruptions would shift deployment trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wimax Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
Global Wireless Data Radio Modem Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Telecom Wireless Data Market