
 Liquid Cooling Racks Market | 2026-2036
Liquid Cooling Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Cooling Racks Market Insights
China is tilting toward domestic liquid cooling manufacturing capacity with state-backed incentives for thermal management infrastructure. Schneider Electric leverages integrated power and cooling architectures to anchor large-scale data center projects across Asia-Pacific. Vertiv Group Corp. sustains engineering density in precision cooling through dedicated R&D centers in Ohio and Ireland. Green Revolution Cooling Inc. differentiates through single-phase immersion designs optimized for GPU-intensive workloads.
Liquid cooling racks are engineered heat rejection systems that circulate dielectric fluids or water-glycol mixtures through cold plates, immersion baths, or vapor chambers to maintain server temperatures below 85°C at rack densities surpassing 50 kW. These systems serve the primary purpose of enabling continuous operation of high-performance computing clusters where air cooling reaches thermodynamic limits. Chilled liquid racks occupy the largest installed base among product types due to retrofit compatibility with existing facility plumbing. Immersion racks represent the fastest-expanding category as hyperscalers validate two-phase designs for AI training nodes. Cold plate racks concentrate margin pools in the ultra high power band where thermal interface materials and pump redundancy command premium pricing.
The U.S. Department of Energy enforces efficiency benchmarks through FERC-interfaced standards that shape data center PUE thresholds and cooling technology procurement. China's MIIT mandates GB-standard compliance for data center energy intensity, directly filtering which liquid cooling architectures qualify for national cloud infrastructure tenders. The EU F-Gas Regulation restricts fluorinated coolant chemistries, pushing European operators toward water-based and natural refrigerant alternatives. Stakeholders must monitor evolving thermal design power trajectories from semiconductor foundries to validate cooling capacity planning assumptions.
Market Dynamics
Rack power densities exceeding 100 kW per cabinet are collapsing the thermodynamic viability of air-cooled infrastructure across hyperscale facilities. Operators face immediate retrofit decisions as GPU clusters for AI training push thermal design power beyond legacy cooling capacity.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated coolants accelerate European operator migration toward water-based and natural refrigerant liquid cooling architectures.
- AI Training Clusters:Hyperscale deployment of NVIDIA H100 and Blackwell GPU racks mandates direct-to-chip and immersion solutions for thermal management.
- China MIIT Mandates:GB-standard compliance requirements for data center energy intensity filter procurement toward qualified liquid cooling vendors in national cloud tenders.
Market Restraints
- Copper and Nickel Price Volatility:Cold plate manufacturing depends on thermal interface materials and precision-machined metalwork exposed to commodity swings.
- Dielectric Fluid Supply Concentration:Two-phase immersion coolants rely on specialized fluorochemical production concentrated among limited chemical suppliers.
- Facility Retrofit Friction:Existing raised-floor data centers require structural reinforcement and plumbing reconstruction to support liquid infrastructure.
Strategic Opportunities
- India Data Center Expansion:Mumbai and Chennai hyperscale projects under construction specify liquid-ready designs for anticipated AI cloud demand.
- Edge AI Inference Nodes:Distributed micro data centers for autonomous systems and smart manufacturing deploy compact immersion units.
- US IRA Clean Energy Credits:Tax incentives for energy-efficient infrastructure reduce payback periods for liquid cooling capital investments.
Industry Challenges
- Thermal Engineer Scarcity:Fluid dynamics and two-phase heat transfer expertise remains concentrated among semiconductor and aerospace talent pools.
- ASHRAE Certification Timelines:Evolving thermal guidelines create uncertainty in cooling capacity planning for facilities with 15-year depreciation schedules.
- Legacy Air-Cooled Integration:Hybrid environments require sophisticated control systems to manage mixed thermal zones without efficiency penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Cooling Racks Market |
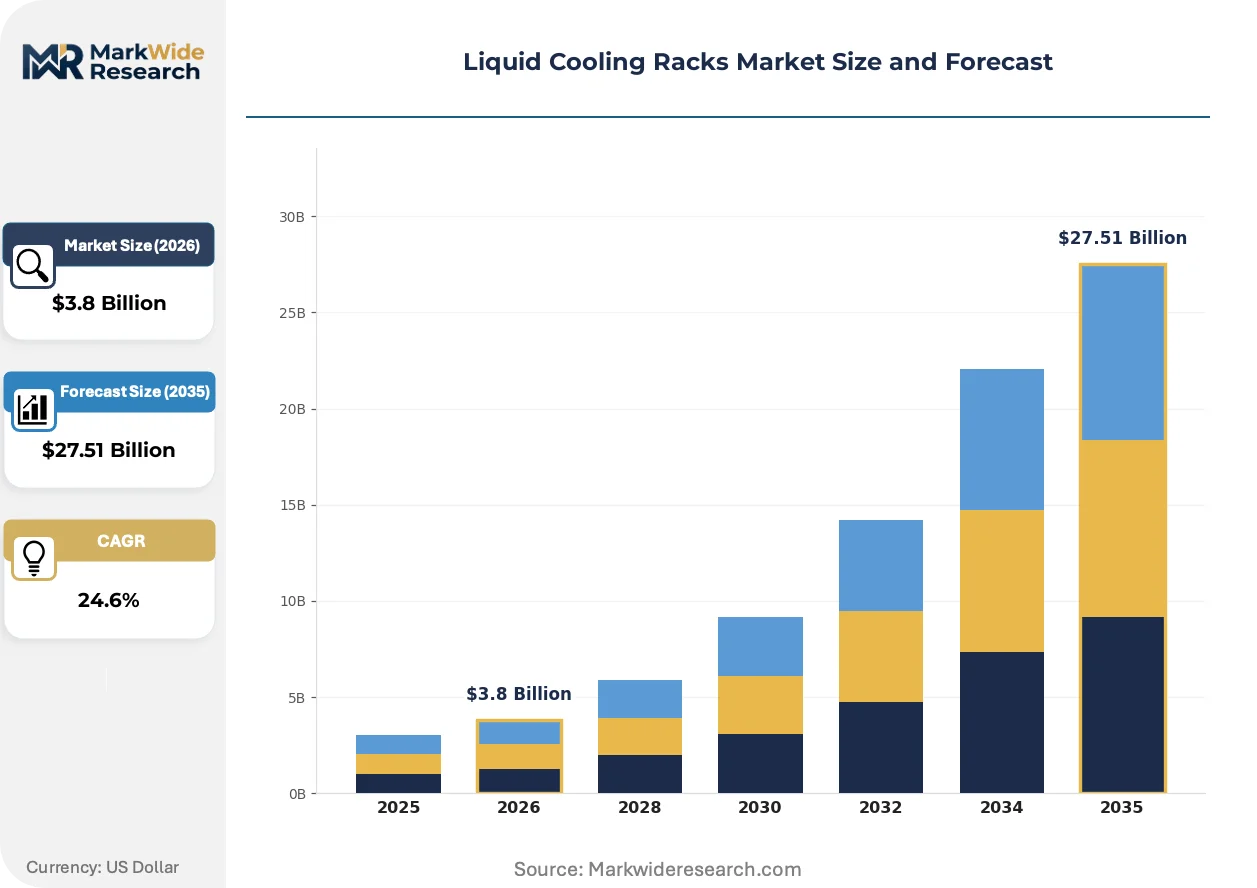
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled Liquid Racks, Vapor Chamber Racks, Immersion Racks, Cold Plate Racks End User: Data Centers, Telecommunications, Industrial Facilities, Research Laboratories Installation: On-Premises, Modular, Containerized, Rack-Mounted Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Schneider Electric, Vertiv Group Corp., Supermicro, Green Revolution Cooling Inc., Alfa Laval Corporate AB, LiquidStack Inc., DCX Liquid Cooling Systems, Asetek Inc., CoolIT Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Cooling Racks Market Trends and Innovations
Direct-to-chip cooling architectures are compressing facility footprints while enabling sustained compute density growth. The transition from air to liquid represents a fundamental infrastructure redesign rather than incremental efficiency improvement.
Single-phase immersion cooling is collapsing the cost differential against chilled water systems for GPU-intensive workloads. Hyperscale operators in Northern Virginia and Singapore validate bath-based designs at 500 kW per rack. This technology is collapsing the traditional separation between server hardware and facility infrastructure.
The EU F-Gas Regulation restricts fluorinated coolant chemistries in two-phase systems. European operators pivot toward engineered water-glycol mixtures and natural refrigerant alternatives. German and Dutch data center projects now specify F-Gas-compliant thermal management as a procurement gate.
Colocation buyers increasingly specify liquid-ready space as a condition of contract renewal. Wholesale providers in Northern Virginia and Frankfurt retrofit white space with underfloor plumbing and coolant distribution units. This behavioral shift concentrates demand among operators with demonstrated liquid deployment experience.
Liquid Cooling Racks Market Segmentation
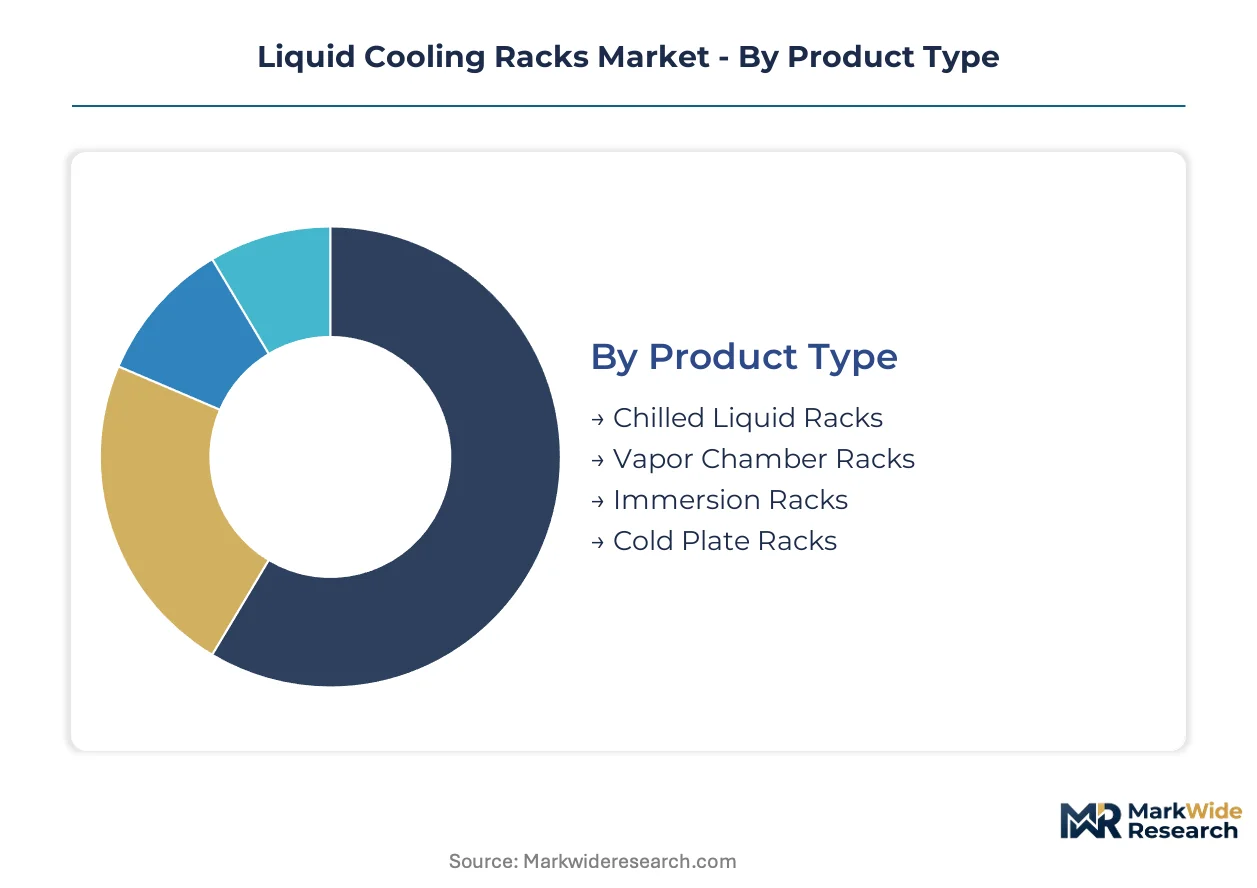
Liquid cooling rack segmentation reflects divergent thermal engineering requirements across deployment scales. Product architecture, facility type, installation constraints, and power density thresholds each create distinct procurement criteria and margin structures.
Product Type:
Use cases span retrofit compatibility to radical density compression, with each architecture serving different infrastructure maturity levels.
- Chilled Liquid Racks:These systems circulate water-glycol mixtures through rear-door heat exchangers or in-row cooling units, preserving existing raised-floor infrastructure. Data center operators in Northern Virginia favor this architecture for brownfield GPU cluster retrofits where plumbing modifications must minimize operational disruption.
- Immersion Racks:Servers submerge directly in dielectric fluid baths, eliminating thermal interface resistance entirely. Hyperscale facilities in Singapore validate two-phase designs at densities exceeding 500 kW per rack for AI training nodes where air cooling reaches hard thermodynamic limits.
- Cold Plate Racks:Direct-to-chip liquid cooling with microchannel cold plates bonded to processors.
- Vapor Chamber Racks:Passive two-phase heat spreaders integrated into rack-level thermal management.
Established volume favors Chilled Liquid Racks; emerging adoption favors Immersion Racks.
End User:
Facility archetypes determine cooling redundancy requirements and capital deployment timelines.
- Data Centers:Hyperscale and colocation operators drive procurement volume, with Northern Virginia and Frankfurt facilities specifying liquid-ready white space as contract renewal conditions. Sovereign cloud tenders in China mandate GB-standard compliance, filtering vendor selection toward qualified domestic and international suppliers.
- Research Laboratories:National supercomputing centers and university clusters operate at the extreme edge of thermal design power. Lawrence Livermore National Laboratory and Forschungszentrum Jülich deploy custom immersion architectures for exascale systems where sustained computational load demands sub-ambient coolant temperatures.
- Telecommunications:Edge computing nodes and 5G infrastructure require compact thermal management.
- Industrial Facilities:Manufacturing automation and process control systems deploy ruggedized liquid cooling.
Procurement concentration sits with Data Centers; Research Laboratories command premium engineering margins.
Installation:
Deployment modality shapes facility integration complexity and speed-to-operation.
- On-Premises:Permanent infrastructure requiring structural reinforcement and dedicated mechanical rooms. Enterprises in Germany retrofit legacy facilities with underfloor coolant distribution networks to accommodate EU F-Gas Regulation compliance timelines.
- Containerized:Factory-integrated systems in ISO-standard enclosures enable rapid deployment. Modular data center projects in India specify containerized liquid cooling for Mumbai hyperscale builds where construction acceleration offsets land cost premiums.
- Modular:Prefabricated mechanical and electrical units for incremental capacity expansion.
- Rack-Mounted:Self-contained cooling integrated at the cabinet level for targeted density zones.
Speed-to-deploy favors Containerized; long-term efficiency optimization favors On-Premises.
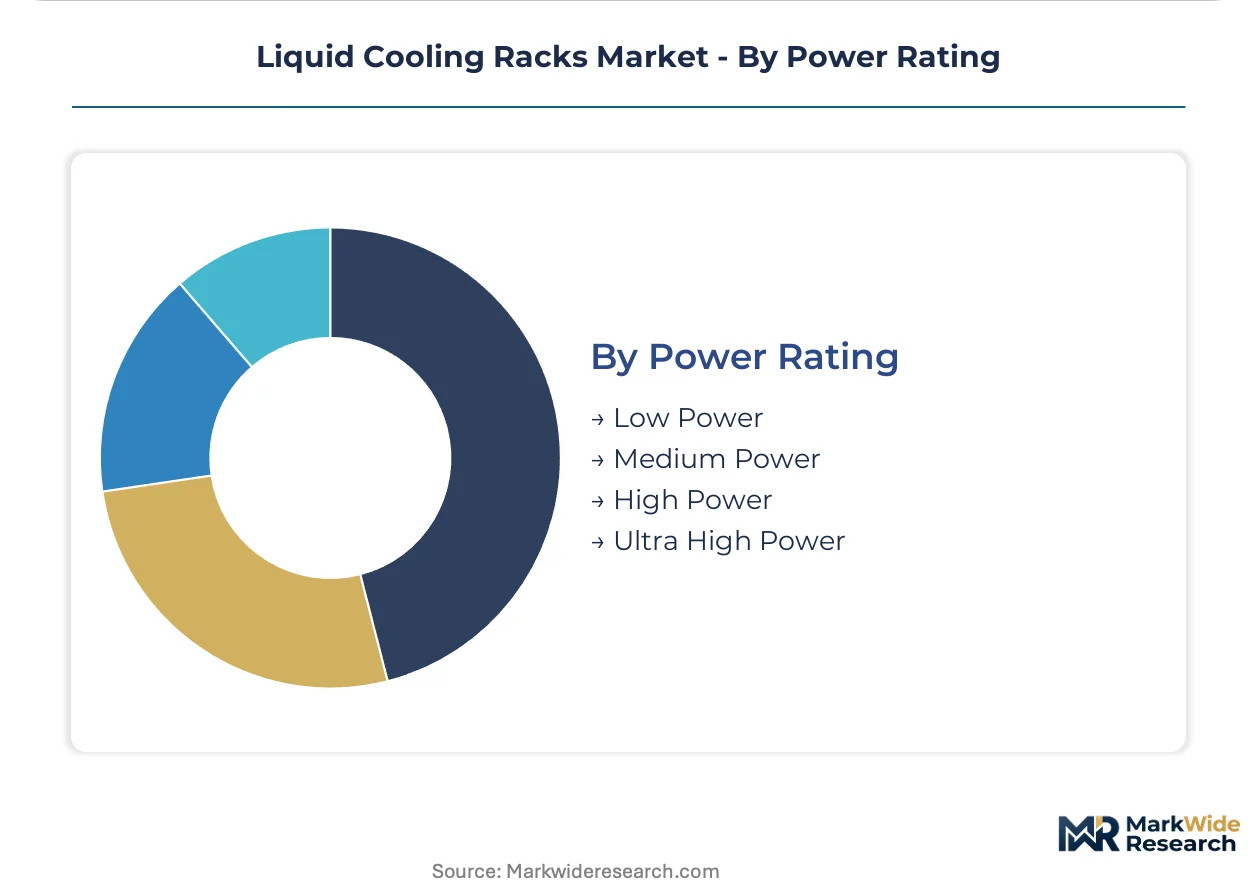
Power Rating:
Thermal load thresholds segment engineering complexity and component specification tiers.
- Ultra High Power:Systems rated above 100 kW per rack serve AI training clusters with NVIDIA H100 and Blackwell GPU densities. Cold plate redundancy, pump failover architectures, and specialized thermal interface materials command substantial price premiums at this tier.
- High Power:Racks between 50-100 kW accommodate dense storage and inference workloads. Facilities in Singapore concentrate procurement here as transitional infrastructure before full immersion adoption.
- Medium Power:20-50 kW range serves mainstream enterprise compute refresh cycles.
- Low Power:Sub-20 kW deployments retain air-cooled alternatives in cost-sensitive segments.
Technology leadership concentrates in Ultra High Power; volume scale concentrates in High Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dulles Technology Corridor's fiber backbone and Dominion Energy substation network underwrites Northern Virginia's concentration of hyperscale liquid cooling deployments. Frankfurt's position atop the DE-CIX internet exchange anchors Central European demand for high-density thermal management.
United States
Northern Virginia's Ashburn-Loudoun data center cluster hosts the densest concentration of liquid-cooled GPU racks outside Asia. FERC-interfaced efficiency benchmarks through the Department of Energy shape procurement criteria for facilities exceeding 50 MW capacity. Microsoft and Amazon Web Services validate direct-to-chip architectures across Prince William County campuses.
Germany
Sovereign cloud tenders and AI research initiatives at Forschungszentrum Jülich drive immersion cooling adoption. The EU F-Gas Regulation restricts fluorinated coolant chemistries, pushing operators toward water-glycol mixtures. Frankfurt's Kleyerstrasse district hosts retrofit projects converting legacy raised-floor facilities to liquid-ready white space.
China
MIIT-mandated GB standards for data center energy intensity filter national cloud procurement toward qualified liquid cooling architectures. State-backed incentives accelerate domestic manufacturing capacity in thermal management infrastructure. Beijing-Tianjin-Hebei corridor facilities deploy direct-to-chip systems for AI training clusters.
Singapore
Land scarcity and tropical ambient temperatures make air cooling thermodynamically unviable for GPU-intensive workloads. The Infocomm Media Development Authority's sustainability standards mandate PUE thresholds below 1.3 for new data center approvals. Tuas and Loyang industrial zones concentrate two-phase immersion validation projects at 500 kW per rack.
India
Mumbai and Chennai hyperscale builds specify liquid-ready designs for anticipated AI cloud demand. The Ministry of Electronics and Information Technology's data center policy incentivizes energy-efficient infrastructure through state-level subsidies. Navi Mumbai's Jawaharlal Nehru Port connectivity supports rapid containerized cooling deployment.
Liquid Cooling Racks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cold plates, pumps, and dielectric fluids. The vendor base separates into three strategic tiers: diversified electrical infrastructure conglomerates, precision thermal engineering specialists, and immersion-focused technology developers. Consolidation pressure intensifies as hyperscale operators demand single-source accountability for power-and-cooling packages. Competitive moves concentrate on vertical integration into coolant distribution networks and strategic partnerships with semiconductor foundries for thermal design power roadmaps.
Among diversified platform providers, Schneider Electric and Vertiv Group Corp. occupy positions anchoring large-scale integrated infrastructure projects. Green Revolution Cooling Inc. exemplifies the immersion-specialist archetype with single-phase bath designs. These three represent distinct competitive vectors: electrical-mechanical integration, precision cooling engineering density, and radical density-compression technology.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp. |
| Supermicro |
| Green Revolution Cooling Inc. |
| Alfa Laval Corporate AB |
| LiquidStack Inc. |
| DCX Liquid Cooling Systems |
| Asetek Inc. |
| CoolIT Systems |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese thermal interface material production is compressing cold plate margins while concentrating bargaining power among hyperscale buyers in Northern Virginia and Singapore. This utilization asymmetry forces European vendors to absorb F-Gas Regulation compliance costs rather than pass them through, reshaping supplier behavior across the liquid cooling value chain.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by imposing compliance premiums on fluorinated coolant architectures while rewarding water-glycol alternatives. Three-tier pricing structure across premium, standard, and economy levels separates immersion systems with redundant pump architectures from basic rear-door heat exchanger retrofits. Cost compression in the standard tier is intensifying because Chinese MIIT-mandated GB certification requirements filter vendor pools. Colocation operators in Frankfurt exhibit the highest price sensitivity, whereas national supercomputing centers accept substantial premiums for sub-ambient coolant guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for precision-machined cold plates and microchannel heat exchangers. Manufacturing concentrates in China, Germany, and the United States, with dielectric fluid synthesis anchored in Japanese and American chemical facilities. Component sourcing draws from copper-nickel alloy suppliers, ceramic pump housings, and specialized fluorochemical producers. Single-source vulnerability persists for two-phase immersion coolants subject to ECHA regulatory review. Distribution runs through direct OEM partnerships for hyperscale contracts and regional systems integrators for enterprise retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid cooling market is approaching a platform-economics inflection as interoperability between server hardware and facility infrastructure collapses traditional procurement boundaries. This shift rewards vendors who control both thermal management IP and coolant distribution network deployment.
For Market Incumbents: Harden defensive positions by securing captive supply of thermal interface materials through backward integration into copper-nickel alloy processing. Anchor large-scale integrated infrastructure projects across Asia-Pacific before Chinese domestic manufacturers achieve GB certification parity. The threat of state-backed Chinese thermal management capacity requires accelerated R&D investment in two-phase immersion architectures where technical moats remain deeper. For New Entrants and Emerging Players: Pursue white-space opportunities in containerized liquid cooling for Indian hyperscale builds where construction acceleration commands premium pricing. Edge AI inference nodes for autonomous systems and smart manufacturing represent the most penetrable segment with limited incumbent saturation. A go-to-market angle emphasizing rapid deployment speed and modular scalability bypasses entrenched relationships in established data center clusters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across immersion cooling sub-segments as two-phase validation projects demand extended engineering cycles before commercial scale. Long-term viability across the next decade rests on vendors demonstrating sustained deployment experience at densities exceeding 500 kW per rack. Acquisition targets should display vertical integration into coolant distribution unit manufacturing and established partnerships with semiconductor foundries for thermal design power roadmap alignment. The signal to watch is hyperscale operator consolidation of vendor panels toward single-source power-and-cooling accountability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Interface Materials | Captive supply of copper-nickel alloys insulates margins from commodity volatility and MIIT procurement filters. |
| Two-Phase Immersion Validation Partnerships | Collaboration with NVIDIA and AMD on Blackwell GPU thermal roadmaps secures design-win precedence for next-generation clusters. |
| Containerized Cooling Platform Launch | Factory-integrated ISO-standard systems address land scarcity constraints in Singapore and construction acceleration demands in Mumbai. |
| F-Gas Compliance Certification Investment | Water-glycol architecture validation opens procurement pathways for Frankfurt and Amsterdam sovereign cloud tenders. |
| Strategic Partnership with Semiconductor Foundries | Early access to thermal design power trajectories from TSMC and Samsung enables cooling capacity planning alignment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center engineering directors, thermal management procurement leads, hyperscale facility operators, and coolant distribution system integrators; and secondary validation against SEC filings from infrastructure conglomerates, hyperscaler capex disclosures, EU F-Gas Regulation implementation guidance, and China MIIT GB standard documentation. Bottom-up triangulation across installation modality and power rating segments was cross-checked against top-down market sizing from facility construction databases and thermal management equipment trade flows.
Forecast inputs considered rack density trajectories from semiconductor foundry roadmaps, regulatory compliance timelines across the EU and China, and hyperscale operator deployment schedules throughout the projection horizon. The analytical framework modeled product architecture, facility type, installation constraints, and power density thresholds as core segmentation dimensions. CAGRs were derived from capacity expansion announcements and validated against historical adoption curves for infrastructure technology transitions. Thermal design power evolution and PUE threshold enforcement intensity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed thermal management manufacturers or accelerated ASHRAE guideline revision would shift outcomes substantially. Forecasts reflect assumptions regarding continued GPU cluster deployment growth and sustained F-Gas regulatory stringency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market