
 EV Smart HVAC System Market | 2026-2036
EV Smart HVAC System Market Size, Share, and Industry Trends Forecast 2026-2036
EV Smart HVAC System Market Insights
Asset-light leasing models for thermal management infrastructure is reconfiguring how fleet operators and charging network providers access smart HVAC capabilities without full capital ownership. Denso leverages its integrated compressor-inverter architecture to sustain technology leadership in electric compressor systems. MAHLE Group anchors European supply through its dedicated e-mobility thermal division, while Valeo competes aggressively in China via localized R&D centers for battery thermal interfaces.
EV smart HVAC systems integrate electric compressors, heat pumps, and sensor-driven climate algorithms to regulate cabin temperature while optimizing battery thermal conditioning across ambient ranges from minus forty to sixty degrees Celsius. The primary purpose is to extend vehicle range by reducing HVAC energy draw and protecting lithium-ion cells from thermal runaway. Component integrations dominate current revenue as OEMs bundle compressors, valves, and controllers into single procurement packages, while IoT integration represents the fastest-expanding margin pool as predictive maintenance and over-the-air calibration commands reshape service economics. Distributed systems are gaining share in retrofitting applications where charging stations require modular climate units.
The EPA tailpipe standards and NHTSA fuel economy rules in the United States, combined with EU F-Gas Regulation and CE marking requirements, are mandating lower-global-warming-potential refrigerants and stricter energy efficiency thresholds for cabin climate systems. China's MIIT dual carbon goals and GB standards for new energy vehicles add parallel compliance layers that shape product design for any supplier seeking multi-region market access. Stakeholders must monitor how refrigerant chemistry transitions and vehicle-to-grid integration standards redefine thermal system specifications before committing to platform architectures.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice sets while heat pump architectures displace conventional compressor systems, forcing OEMs to redesign thermal platforms around lower-global-warming-potential chemistries.
Growth Catalysts
- Fleet electrification mandates:Commercial vehicle operators in Germany face binding zero-emission procurement quotas that require climate-controlled cabins to protect battery thermal stability across route profiles.
- MIIT dual carbon goals:China's GB standards for new energy vehicles mandate stricter cabin efficiency codes, accelerating heat pump adoption in domestic EV platforms.
- Charging network density:The United States deploys the largest fast-charging infrastructure clusters, creating distributed demand for modular climate units at high-traffic charging stations.
Market Restraints
- Refrigerant chemistry transition costs:R-1234yf and CO2 systems require incompatible sealing materials and compressor architectures, raising platform redesign costs for suppliers serving multiple regulatory zones.
- Rare earth magnet concentration:Permanent magnet motors for electric compressors depend on neodymium processing concentrated in China, exposing supply chains to export control volatility.
- Vehicle-to-grid standard fragmentation:Divergent thermal interface specifications between IEEE 1547 in North America and IEC 61851 in Europe delay unified platform development.
Strategic Opportunities
- Retrofit charging station climate:Modular HVAC units for existing charging infrastructure in the United States address range anxiety without full vehicle replacement cycles.
- Battery thermal interface convergence:Integration of solid-state battery conditioning algorithms with cabin climate control creates unified thermal management platforms.
- Asset-light infrastructure leasing:Fleet operators access compressor-inverter systems through service contracts rather than capital purchase, expanding addressable market to mid-size logistics providers.
Industry Challenges
- Cross-functional thermal engineering scarcity:OEMs compete for talent combining refrigerant thermodynamics, battery electrochemistry, and embedded control systems.
- Multi-regional certification timelines:Simultaneous EPA SNAP approval, EU CE marking, and China Compulsory Certification for new refrigerant blends extend product launch cycles.
- Legacy vehicle integration complexity:Aftermarket smart HVAC retrofits face CAN bus protocol incompatibilities across pre-2020 EV platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Smart HVAC System Market |
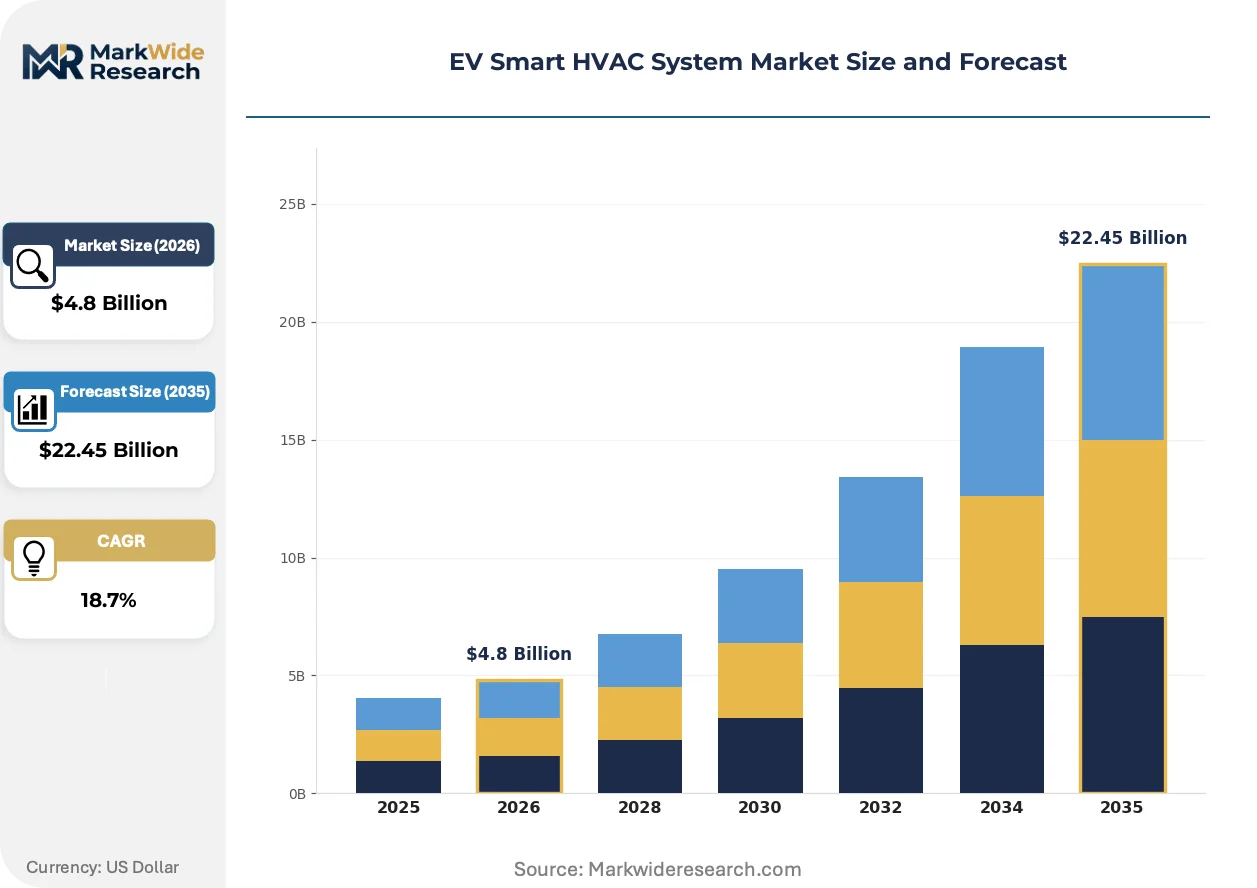
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized Systems, Distributed Systems, Hybrid Systems, Component Integrations Technology: IoT Integration, Energy Recovery Ventilation, Smart Thermostats, Variable Refrigerant Flow End User: Residential Buildings, Commercial Buildings, Industrial Facilities, EV Charging Stations Installation: New Construction, Retrofitting, Modular Systems, Custom Installations |
| Companies Covered | Sanden Corporation, Delphi, Denso, Titanx, Highly Marelli, MAHLE Group, Hanon Systems, NORMA Group, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Smart HVAC System Market Trends and Innovations
Sensor-driven climate algorithms are compressing the gap between cabin comfort optimization and battery thermal protection, reshaping how OEMs specify integrated thermal platforms.
Predictive maintenance software is digitizing service economics for fleet operators. Commercial vehicle buyers in Germany deploy over-the-air calibration commands to optimize compressor duty cycles across ambient temperature swings. This capability is compressing traditional dealership service revenue pools while shifting margin capture to software licensors.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants with global warming potential above 150. Automotive suppliers reformulate thermal platforms around CO2 transcritical cycles and R-1234yf systems. European OEMs face the steepest compliance timeline, with 2027 model year vehicles requiring full transition to approved chemistries.
Fleet procurement managers unbundle HVAC service contracts from vehicle acquisition agreements. Logistics operators in China negotiate outcome-based thermal performance guarantees separate from chassis procurement. This pattern concentrates supplier selection authority with fleet technical directors rather than OEM sales channels.
EV Smart HVAC System Market Segmentation
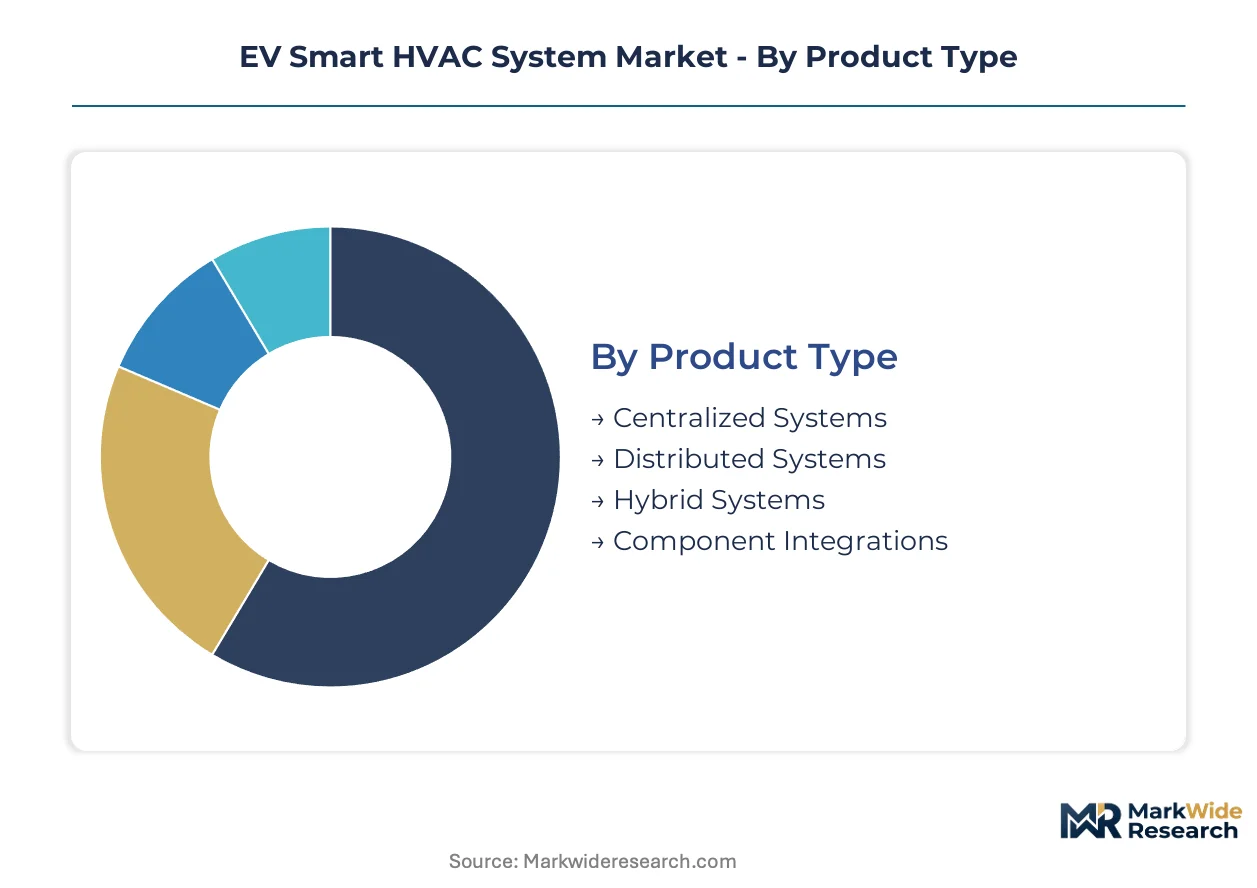
Segmentation in EV smart HVAC systems determines procurement patterns, service contract structures, and margin capture across fundamentally different thermal management architectures. Fleet operators, charging network providers, and building managers each impose distinct specifications that reshape supplier product roadmaps and aftermarket revenue pools.
Product Type:
After-sales service intensity varies sharply across product architectures, with distributed and hybrid systems demanding localized technician networks while centralized platforms concentrate service at OEM hubs.
- Centralized Systems:Single thermal management units regulate cabin and battery conditioning through unified compressor-inverter architectures. German commercial vehicle fleets specify these for electric bus depots where maintenance centralization reduces technician training costs across standardized route profiles.
- Distributed Systems:Modular compressor and heat pump units deploy at charging station clusters rather than onboard vehicles. Demand concentrates in United States highway corridor retrofits where existing infrastructure requires climate units without full electrical upgrades.
- Hybrid Systems:Dual-mode architectures switch between heat pump and resistive heating based on ambient temperature thresholds.
- Component Integrations:Bundled procurement packages combine valves, controllers, and sensors into single SKU offerings for OEM assembly lines.
Component integrations hold the largest share; momentum sits with distributed systems.
Technology:
Technology selection follows cost tier differentiation, with premium IoT-enabled platforms commanding service contract premiums over baseline ventilation hardware.
- IoT Integration:Sensor networks transmit compressor duty cycle data and refrigerant pressure readings to cloud-based predictive maintenance platforms. United States fleet operators deploy over-the-air calibration commands to optimize thermal performance across ambient temperature swings, compressing traditional dealership service revenue.
- Energy Recovery Ventilation:Heat exchangers capture exhaust air thermal energy to precondition incoming cabin air. Chinese electric bus manufacturers specify these for northern corridor routes where winter heating loads drain battery capacity.
- Smart Thermostats:Machine learning algorithms learn occupancy patterns and adjust setpoints to minimize HVAC energy draw.
- Variable Refrigerant Flow:Modulating compressor speeds match refrigerant delivery to real-time thermal load requirements.
IoT integration commands premium pricing; energy recovery ventilation expands most quickly in cold-climate deployments.
End User:
End user segmentation maps to application-specific thermal load profiles, with EV charging stations presenting retrofit opportunities distinct from new vehicle cabin specifications.
- Residential Buildings:Home charging integration packages combine garage climate control with vehicle preconditioning schedules. German households with rooftop solar specify these to align HVAC energy draw with photovoltaic generation peaks.
- Commercial Buildings:Workplace charging installations require scalable thermal management across multi-vehicle parking structures. United States corporate campuses negotiate outcome-based performance guarantees tied to employee satisfaction metrics.
- Industrial Facilities:Heavy-duty logistics hubs demand ruggedized compressor units for fleet charging at warehouse scale.
- EV Charging Stations:Standalone public charging infrastructure requires modular climate units to protect battery thermal stability during high-power charging sessions.
Commercial buildings anchor current procurement volume; EV charging stations show the steepest expansion trajectory as network density increases.
Installation:
Installation type reflects customer maturity and capital cycle timing, with retrofitting dominating aftermarket revenue while new construction locks in long-term platform standards.
- New Construction:Integrated thermal management specification during building design enables optimized heat pump sizing and refrigerant line routing. Chinese green building codes mandate these installations for new commercial developments seeking MIIT dual carbon compliance certification.
- Retrofitting:Post-installation upgrades adapt existing charging infrastructure for climate-controlled battery conditioning. United States highway corridor operators deploy these to address range anxiety without full electrical service upgrades.
- Modular Systems:Prefabricated thermal units enable rapid deployment across distributed charging networks.
- Custom Installations:Bespoke engineering addresses non-standard site constraints or specialized fleet requirements.
New construction captures the largest installed base; retrofitting gains share fastest as charging network expansion outpaces greenfield development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's zero-emission procurement quotas for commercial fleets are accelerating climate-controlled cabin specifications across electric bus and logistics vehicle deployments.
United States
Fast-charging infrastructure density along interstate corridors creates distributed demand for modular thermal management units. EPA tailpipe standards and NHTSA fuel economy rules mandate stricter cabin efficiency thresholds. California's freight electrification programs anchor procurement volume for electric truck HVAC systems serving port-to-warehouse routes.
Germany
Binding zero-emission procurement quotas for municipal bus fleets require climate-controlled cabins to protect battery thermal stability across variable route profiles. EU F-Gas Regulation mandates transition to lower-global-warming-potential refrigerants by 2027. The Stuttgart industrial cluster concentrates supplier engineering centers for integrated compressor-inverter architectures.
China
MIIT dual carbon goals and GB standards for new energy vehicles mandate stricter cabin efficiency codes across domestic EV platforms. SAMR certification requirements shape product design for multi-region market access. The Yangtze River Delta manufacturing corridor hosts the densest concentration of electric compressor assembly capacity serving both domestic OEMs and export markets.
Japan
METI technology roadmaps prioritize heat pump efficiency improvements for cold-climate EV deployments. JIS standards for automotive thermal systems establish baseline performance requirements for cabin climate control. The Nagoya industrial cluster sustains specialized engineering talent for refrigerant thermodynamics and embedded control systems integration.
South Korea
Corporate fleet electrification targets under national carbon neutrality commitments expand addressable market for smart HVAC service contracts. MFDS-equivalent automotive certification protocols align with international refrigerant safety standards. The Seoul Capital Area concentrates R&D investment for battery thermal interface algorithms and predictive maintenance software platforms.
EV Smart HVAC System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The supplier base clusters around integrated system architects, component bundlers, and software-centric service providers. Strategic archetypes include captive OEM thermal divisions, independent tier-one integrators, and retrofit-focused distributed system specialists. Dominant competitive moves span capacity expansion for CO2 transcritical cycle production and technology licensing agreements for predictive maintenance platforms.
Within the integrated system architect tier, Denso Corporation and MAHLE Group exemplify compressor-inverter architecture leadership, while Valeo S.A. occupies a position emphasizing localized R&D presence for battery thermal interface development. These three anchors represent divergent geographic emphases—Japanese, German, and French engineering traditions respectively—while converging on unified thermal management platform strategies.
| Leading Market Players |
|---|
| Sanden Corporation |
| Delphi |
| Denso |
| Titanx |
| Highly Marelli |
| MAHLE Group |
| Hanon Systems |
| NORMA Group |
| Valeo |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's energy cost dynamics compress margins for electric compressor manufacturers while concentrating pricing power among suppliers with captive neodymium processing capabilities in China, forcing tier-one integrators to differentiate through after-sales service bundling rather than hardware premiums alone.
Pricing Analysis
Certification level creates the primary spread between CE-marked European systems and baseline configurations for emerging markets, with EPA SNAP approval adding further cost tiers for United States access. Three-tier pricing structure across premium, standard, and economy levels reflects heat pump efficiency ratings and IoT predictive maintenance inclusion. Cost compression in mid-tier compressor-inverter bundles is intensifying because Chinese OEMs are internalizing thermal system production. Fleet operators represent the most price-sensitive segment, while charging network providers absorbing infrastructure leasing costs show lower sensitivity to unit pricing.
Supply Chain Analysis
Extended payment terms from German automotive OEMs now stretch to 120 days, forcing tier-two valve and sensor suppliers to access supply-chain finance facilities anchored in Stuttgart banking clusters. Manufacturing concentrates in China, Germany, and Japan, with the Yangtze River Delta hosting electric motor winding capacity and the Nagoya corridor sustaining refrigerant thermodynamics engineering. Permanent magnet motors draw from neodymium processing concentrated in China, exposing the chain to export control volatility. Distribution runs through captive OEM thermal divisions and independent tier-one integrators serving aftermarket retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across refrigerant chemistry standards and vehicle-to-grid interface specifications creates specialized niches for regional specialists as fleet operators unbundle HVAC procurement from chassis acquisition.
For Market Incumbents: Pre-empt platform standardization by securing IEEE 1547 and IEC 61851 dual-certification for thermal interface controllers before regulatory convergence forces redesign cycles. Expand CO2 transcritical cycle capacity in European production hubs to capture EU F-Gas Regulation compliance premiums as 2027 model year deadlines approach. Lock in rare earth magnet supply through offtake agreements with Chinese processors to defend against supply disruption.
For New Entrants and Emerging Players: Build out modular distributed systems for United States highway corridor retrofits where charging network operators seek climate units without full electrical infrastructure replacement. Target mid-size logistics providers in China through asset-light leasing models that bypass capital-intensive OEM sales channels. Lead with predictive maintenance software platforms that compress traditional dealership service revenue pools.
For Investors and Strategic Acquirers: Software-centric thermal management specialists with embedded control systems IP represent the most defensible acquisition targets as predictive maintenance digitizes service economics. Long-term viability hinges on refrigerant chemistry transition execution and solid-state battery interface development. Watch for IEEE-IEC standard convergence as the inflection signal triggering platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Cycle Capacity Expansion | EU F-Gas Regulation compliance secures access to German and French OEM procurement pipelines. |
| Predictive Maintenance Platform Development | Over-the-air calibration commands shift margin capture from hardware to software licensors. |
| Rare Earth Magnet Supply Agreement | Neodymium processing access in China insulates against export control disruption. |
| Dual-Certification Investment (IEEE 1547/IEC 61851) | Unified thermal interface specifications enable multi-region platform deployment. |
| Asset-Light Infrastructure Leasing Launch | Service contracts expand addressable market to mid-size logistics providers without capital purchase. |
Research Methodology
The analysis maps centralized compressor-inverter architectures, distributed charging station climate units, and IoT-enabled predictive maintenance platforms, each validated through primary interviews with OEM platform engineers, tier-one supplier procurement directors, fleet technical managers, and charging network infrastructure planners. Secondary sources include EPA SNAP submissions, EU F-Gas Regulation implementation guidance, MIIT GB standard filings, vehicle production databases, and customs trade records for electric compressor components. Bottom-up unit economics triangulate against top-down market sizing across the projection horizon.
Assumptions held fixed include refrigerant chemistry transition timelines under EU F-Gas Regulation and MIIT dual carbon goal enforcement intensity, while battery energy density improvement trajectories and vehicle-to-grid standard convergence pace were varied across sensitivity scenarios. Segmentation dimensions span product architecture, technology tier, end-user application, and installation type, with CAGRs derived from regression analysis against EV fleet penetration curves and charging network density buildout rates. Heat pump adoption velocity and solid-state battery commercialization timing served as key forecast inputs.
Stress conditions across neodymium export restriction severity, refrigerant price volatility, and vehicle-to-grid standard fragmentation persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic contraction, regulatory delay, or breakthrough solid-state battery thermal management architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Smart HVAC Controls Market