
 Global Enterprise Session Border Controller (SBC) Market | 2026-2036
Global Enterprise Session Border Controller (SBC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Session Border Controller (SBC) Market Foresight
India is tilting toward cloud-first voice infrastructure as enterprises abandon legacy TDM networks. Ribbon Communications leverages deep interoperability expertise to anchor carrier-grade deployments across Asia-Pacific. Cisco Systems, Inc. dominates enterprise accounts through integrated security and session management portfolios. AudioCodes Ltd. specializes in Microsoft Teams-certified SBC appliances for hybrid work environments.
An enterprise session border controller is a network appliance or virtualized function that secures and manages real-time communications sessions at the network perimeter, typically handling SIP protocol normalization, encryption via TLS/SRTP, and traffic policing between trusted and untrusted domains. Its primary purpose is to enable secure VoIP and video interoperability while shielding core communications infrastructure from denial-of-service attacks and toll fraud. Cloud deployment now captures the fastest expansion as enterprises prioritize elastic capacity and reduced capital overhead, while on-premises solutions sustain margin pools in regulated sectors requiring localized data sovereignty. Security-focused solution types lead current procurement decisions amid rising toll fraud sophistication and regulatory encryption mandates.
The Federal Communications Commission enforces STIR/SHAKEN caller ID authentication rules that compel US enterprises to upgrade SBC infrastructure for robocall mitigation, while the EU Cybersecurity Act and GDPR data-localization requirements shape product certification and deployment architecture across European member states. India's Telecom Regulatory Authority mandates lawful interception capabilities that influence vendor feature roadmaps for subcontinent deployments. Stakeholders must weigh cloud migration timelines against evolving encryption backdoor requirements and regional certification fragmentation.
Market Dynamics
The migration from premises-based PBX systems to cloud-native unified communications platforms is compressing deployment cycles and forcing vendors to rearchitect session border controllers for Kubernetes-orchestrated elasticity rather than fixed appliance form factors.
Growth Catalysts
- FCC STIR/SHAKEN Mandates:US carriers and enterprises must upgrade SBC infrastructure to authenticate caller ID and mitigate robocall volumes, triggering replacement demand across legacy installed bases.
- Financial Services VoIP Expansion:Banks and insurance firms are scaling real-time trading floor communications and customer contact centers, requiring carrier-grade session management with millisecond latency guarantees.
- EU NIS2 Directive:Critical infrastructure operators across European member states must harden real-time communications perimeters against cyber intrusion, mandating TLS 1.3 and SRTP encryption on all external session borders.
Market Restraints
- Silicon Supply Concentration:Specialized packet-processing ASICs and FPGA components for high-density transcoding remain concentrated among a handful of foundry operators in Taiwan, exposing lead time volatility.
- Encryption Backdoor Requirements:India's TRAI lawful interception mandates and similar frameworks in Gulf states force vendors to maintain dual code bases, fragmenting engineering resources and certification timelines.
- Appliance-to-Cloud Substitution:Virtualized and containerized SBC instances are displacing physical hardware, compressing margin pools for vendors dependent on chassis-based recurring maintenance contracts.
Strategic Opportunities
- Microsoft Teams Hybrid Deployments:Direct Routing certification gaps in mid-market enterprises create attach opportunities for SBC vendors offering certified appliances bridging on-premises PSTN connectivity to Teams cloud PBX.
- Germany Legacy Modernization:Mittelstand manufacturers and public sector agencies are replacing TDM trunking with SIP infrastructure, concentrating demand for session border controllers with ISDN interworking capabilities.
- 5G Standalone Voice Core:Convergence of SBC functions with IMS core virtualization is collapsing traditional demarcations between access and core network equipment, opening greenfield deployment architectures.
Industry Challenges
- SIP Protocol Normalization Complexity:Vendor-specific header implementations and non-standard codec negotiations require extensive interoperability testing, extending proof-of-concept cycles and delaying revenue recognition.
- Multi-Cloud Orchestration Talent Scarcity:Enterprise IT teams lack expertise in Kubernetes-based SBC lifecycle management, forcing vendors to absorb professional services costs or risk deployment failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Session Border Controller (SBC) Market |
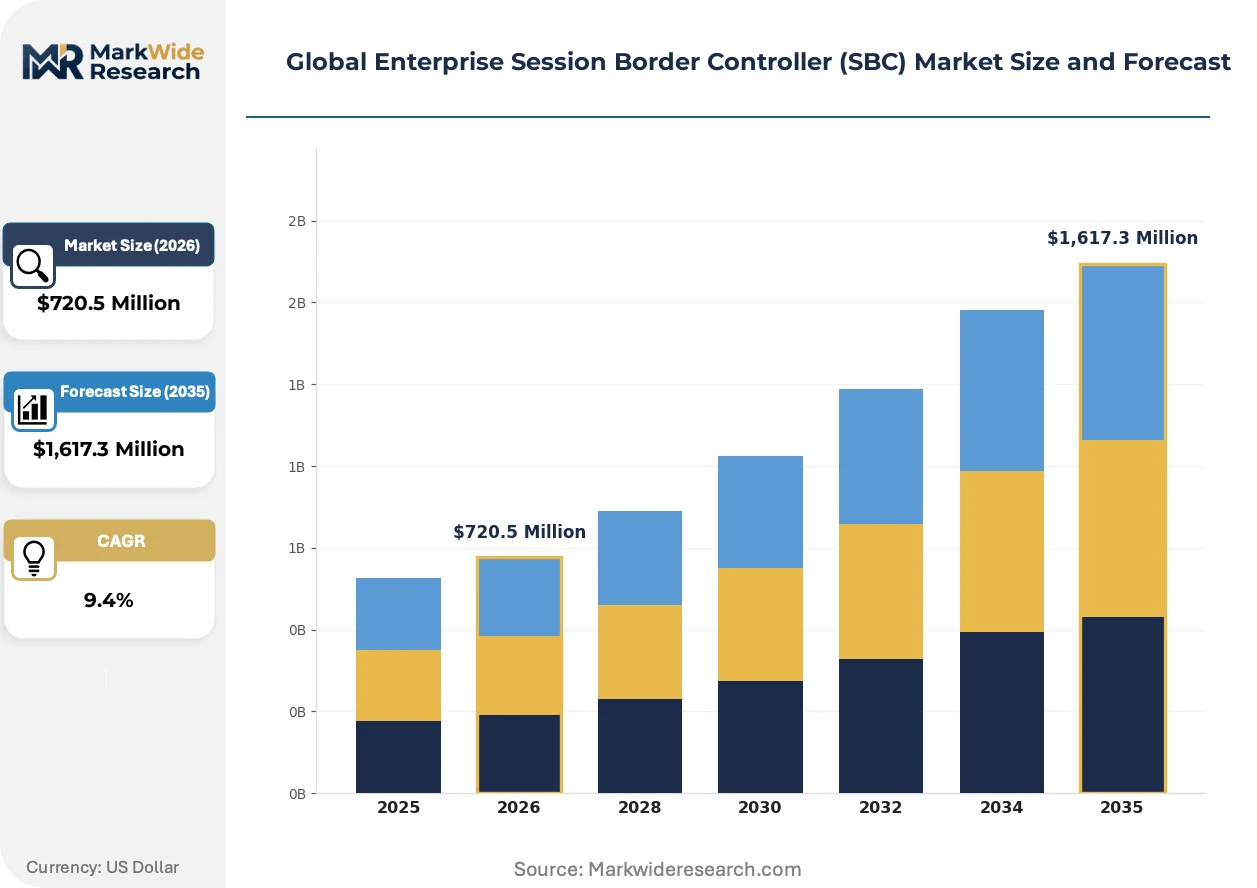
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,617.3 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Managed Services Solution Type: Security, Interoperability, Session Management, Media Services, Analytics Use Case: Voice over IP, Video Conferencing, Unified Communications, Contact Centers, Collaboration Platforms End User: Telecommunication Operators, IT Companies, Large Enterprises, Managed Service Providers, Contact Center Providers |
| Companies Covered | Ribbon Communications, ADTRAN, Inc., AudioCodes Ltd., Sangoma Technologies Corp., Patton Electronics Co., Cisco Systems, Inc., Avaya Inc., Edgewater Networks, Inc., Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Session Border Controller (SBC) Market Shifts & Advancements
Artificial intelligence is embedding into session border operations for real-time fraud detection and adaptive traffic engineering, while containerization and API-first architectures are dismantling the monolithic appliance model that dominated prior decades.
Containerized SBC software is collapsing the distinction between network edge and cloud core by enabling identical session management functions to deploy across bare-metal data centers, public cloud regions, and distributed edge locations. Large financial institutions in London and Singapore are piloting these architectures for unified trading floor communications. The structural consequence is collapsing procurement boundaries between networking and cloud infrastructure teams, forcing vendors to sell through dual channels.
The EU AI Act's risk classification framework for biometric and emotion recognition systems is extending to real-time communications analytics, compelling SBC vendors to document algorithmic decision-making in traffic policing and fraud detection modules. Manufacturers must now maintain technical documentation and conformity assessment records previously unnecessary for pure network equipment. German healthcare and French public sector buyers are demanding these certifications ahead of formal enforcement timelines.
Enterprise sourcing of session border capacity is fragmenting from three-year appliance purchases toward monthly subscription models indexed to concurrent session peaks. Systems integrators and managed service providers are capturing this transition by white-labeling vendor software and bundling operational support. This pattern is most pronounced in Australia and Canada where mid-market enterprises lack in-house VoIP engineering depth and prefer outcome-based contracts with guaranteed SLA credits.
Global Enterprise Session Border Controller (SBC) Market Segmentation
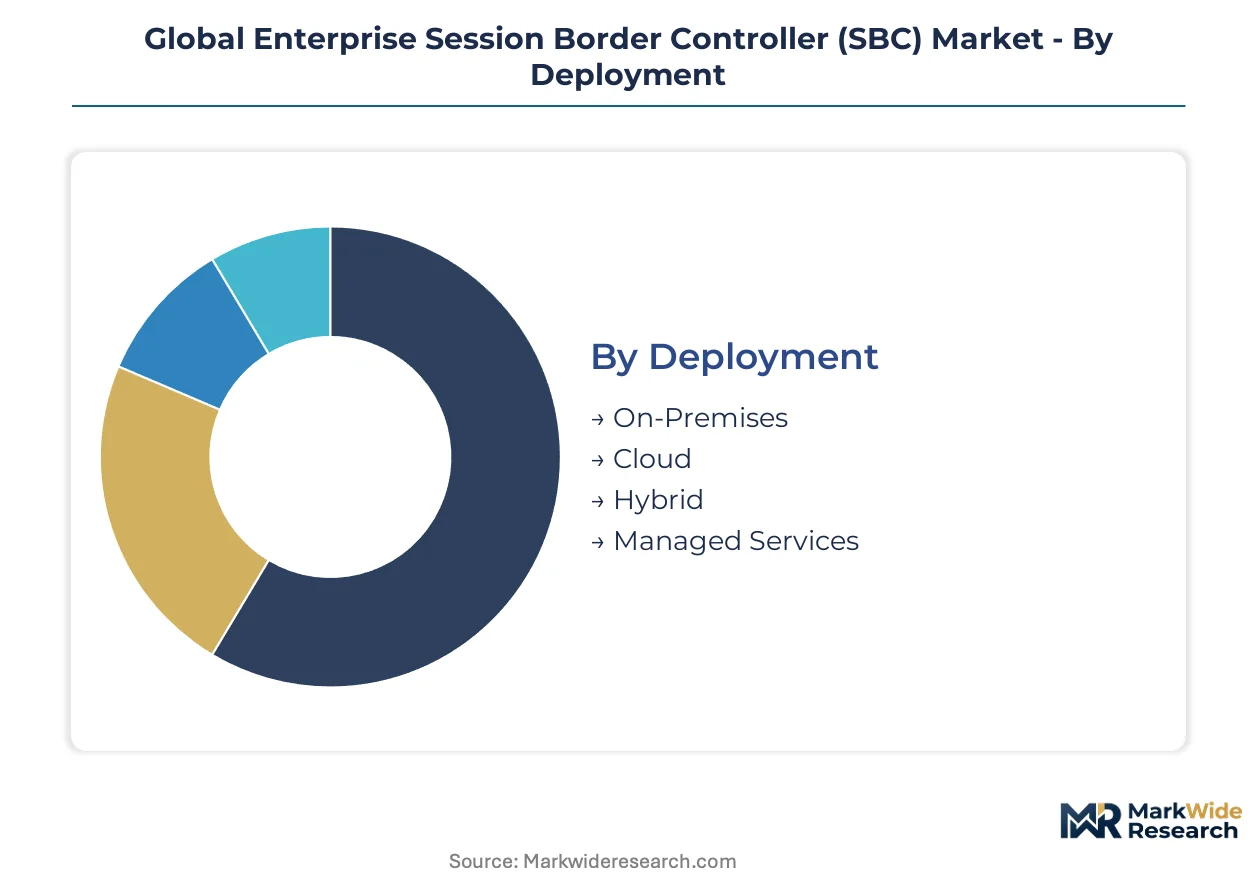
Enterprise SBC procurement patterns diverge sharply across deployment models, solution architectures, and operational use cases. Vendors must architect flexible pricing and delivery mechanisms that map to these distinct buying contexts rather than forcing uniform product structures.
Deployment:
Cost tier separates capex-heavy perpetual licensing from elastic operational expenditure models.
- On-Premises:Physical appliance or bare-metal software deployed within enterprise data centers with full administrative control. German automotive manufacturers and French defense contractors favor this model to satisfy GDPR data localization requirements and air-gapped security policies.
- Cloud:Virtualized SBC functions delivered via SaaS or public cloud infrastructure with metered session pricing. Singaporean fintech startups and Australian mid-market enterprises are migrating here to eliminate hardware refresh cycles and align costs with seasonal contact center volumes.
- Hybrid:Split architectures maintaining on-premises PSTN gateways while bursting overflow capacity to cloud instances. UK National Health Service trusts deploy hybrid configurations to preserve legacy ISDN trunks for emergency services while modernizing internal UC platforms.
- Managed Services:Fully outsourced session border operations with SLA-backed availability guarantees. Canadian provincial governments and Japanese regional banks prefer this model where internal VoIP engineering expertise is scarce.
On-Premises commands the established base. The steepest expansion runs through Cloud.
Solution Type:
Application focus determines whether procurement prioritizes threat mitigation, protocol bridging, or traffic optimization.
- Security:Encryption termination, DDoS protection, toll fraud prevention, and signaling firewall functions. US financial services firms under FCC STIR/SHAKEN mandates are upgrading security modules to authenticate caller identity and block robocall injection.
- Interoperability:Protocol normalization between vendor-specific SIP implementations and legacy TDM networks. German Mittelstand manufacturers require ISDN-to-SIP interworking as they decommission aging PBX infrastructure.
- Session Management:Call routing, load balancing, and quality-of-service enforcement across distributed endpoints. Indian IT services companies scaling work-from-home contact centers depend on session management for geographic redundancy.
- Media Services:Transcoding, echo cancellation, and bandwidth optimization for heterogeneous codec environments. Video-intensive use cases in Brazilian healthcare telemedicine drive media services attachment.
- Analytics:Real-time traffic monitoring, fraud pattern detection, and predictive capacity planning. UAE government communications authorities mandate analytics modules for lawful interception compliance.
Security solutions anchor current procurement budgets. Analytics is climbing the fastest as AI-embedded traffic inspection matures.
Use Case:
Volume intensity and latency tolerance vary dramatically across real-time communications workloads.
- Voice over IP:Core telephony replacement with PSTN interconnectivity and emergency calling compliance. US healthcare systems modernizing nurse call systems represent concentrated demand.
- Video Conferencing:High-bandwidth session handling with packet loss concealment and dynamic resolution adaptation. Hybrid work policies in UK professional services firms sustain investment.
- Unified Communications:Integrated voice, video, messaging, and presence across Microsoft Teams, Cisco Webex, or Zoom Phone ecosystems. Direct Routing certification requirements in Australian enterprises create vendor selection pressure.
- Contact Centers:High-density agent environments with CRM integration, recording compliance, and predictive dialer support. Philippine BPO operators scale here for North American client contracts.
- Collaboration Platforms:Persistent team workspaces with embedded voice and video threading. Technology sector deployments in Israel and South Korea favor cloud-native collaboration stacks.
Voice over IP retains the largest installed footprint. Contact Centers is expanding most quickly as outsourcing and AI-augmented agent models proliferate.
End User:
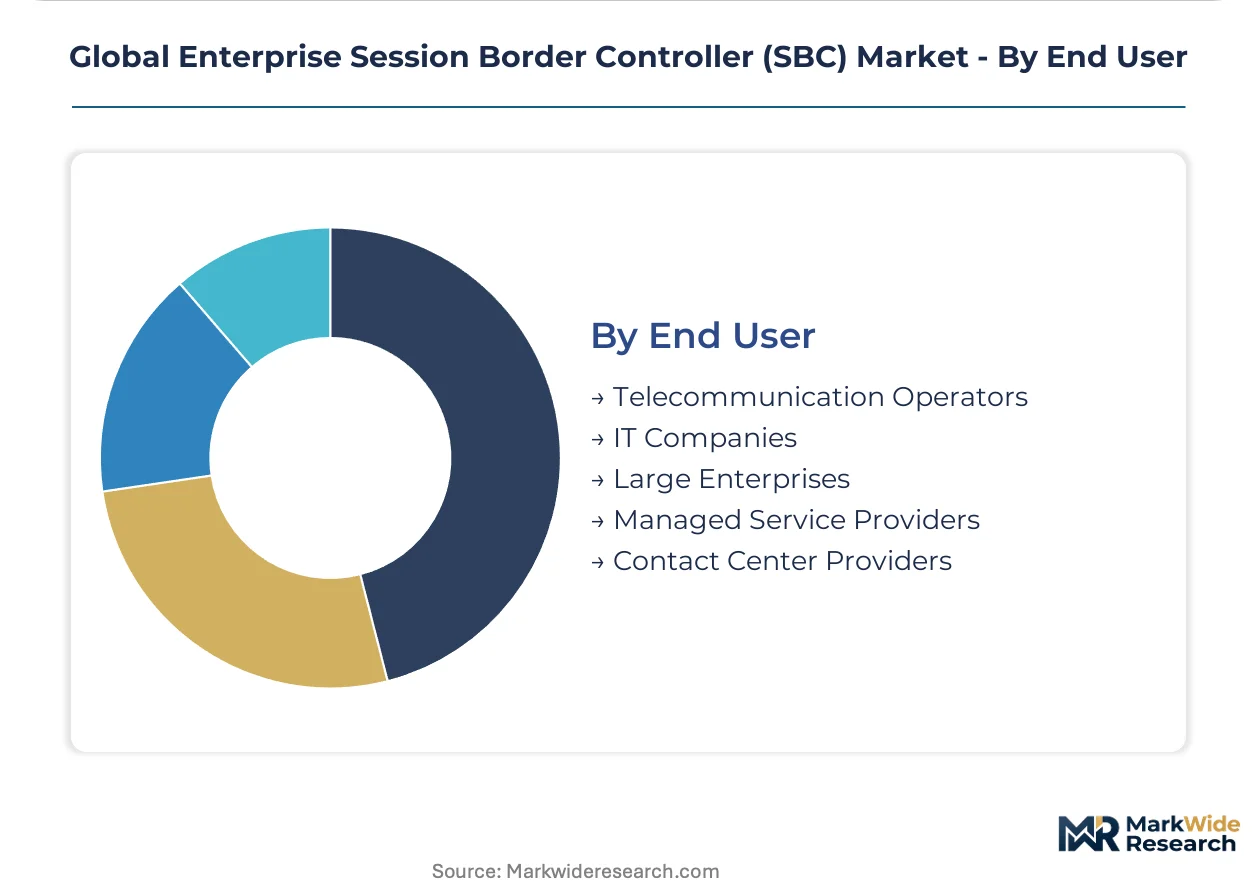
Customer type dictates sales cycle length, technical support intensity, and pricing negotiation leverage.
- Telecommunication Operators:Tier-1 carriers requiring carrier-grade scalability, five-nines availability, and regulatory compliance across national footprints. NTT in Japan and Telstra in Australia anchor this segment.
- IT Companies:Technology vendors integrating SBC functions into broader networking or security portfolios. This category captures OEM and white-label arrangements.
- Large Enterprises:Fortune 500 multinationals with distributed global campuses and complex multi-vendor UC environments. Swiss pharmaceutical conglomerates and US energy majors typify procurement complexity.
- Managed Service Providers:Regional integrators bundling SBC operations with WAN optimization and helpdesk services. French and Italian MSPs dominate European mid-market penetration.
- Contact Center Providers:Specialized outsourcers delivering agent capacity to enterprise clients with strict SLA and compliance requirements. Indian and Mexican operators lead volume scaling.
Telecommunication Operators represent the deepest revenue concentration. Managed Service Providers are gaining share fastest as subscription economics displace direct enterprise sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC anchors the dominant geography through STIR/SHAKEN mandates that compel US enterprises to modernize SBC infrastructure for robocall mitigation. Germany concentrates replacement demand as Mittelstand manufacturers decommission legacy PBX systems. India's cloud-first migration accelerates alongside TRAI lawful interception requirements.
United States
Financial services firms in New York and Chicago are expanding VoIP infrastructure for trading floor communications and customer contact centers. The FCC enforces STIR/SHAKEN caller ID authentication rules that trigger SBC replacement cycles across legacy installed bases. Healthcare systems in Boston and Dallas modernize nurse call systems, driving security-focused procurement decisions.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg favor on-premises deployments to satisfy GDPR data localization requirements and air-gapped security policies. The EU NIS2 Directive mandates TLS 1.3 and SRTP encryption on all external session borders for critical infrastructure operators. Mittelstand manufacturers in North Rhine-Westphalia require ISDN-to-SIP interworking capabilities as they decommission aging PBX infrastructure.
India
IT services companies in Bangalore and Hyderabad scale work-from-home contact centers, demanding session management for geographic redundancy. TRAI mandates lawful interception capabilities that influence vendor feature roadmaps for subcontinent deployments. Fintech startups in Mumbai migrate toward cloud-native voice infrastructure to eliminate hardware refresh cycles.
United Kingdom
National Health Service trusts deploy hybrid configurations to preserve legacy ISDN trunks for emergency services while modernizing internal UC platforms. Professional services firms in London sustain investment in video conferencing infrastructure amid persistent hybrid work policies. The UK regulator shapes procurement through cybersecurity frameworks that emphasize encryption standards for real-time communications.
Singapore
Large financial institutions pilot containerized SBC architectures for unified trading floor communications across bare-metal data centers and cloud regions. The Monetary Authority of Singapore imposes operational resilience requirements that accelerate perimeter hardening for real-time communications. Regional banks prefer managed service models where internal VoIP engineering expertise remains scarce.
Global Enterprise Session Border Controller (SBC) Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where specialists command premium positioning in regulated verticals while diversified networking vendors capture volume through integrated portfolios. The vendor base organizes around three strategic archetypes: carrier-grade infrastructure specialists, cloud-native software vendors, and diversified networking conglomerates with security-anchored portfolios. Competitive moves concentrate on Kubernetes-orchestrated product rearchitecture and Microsoft Teams Direct Routing certification acquisition.
Within the carrier-grade infrastructure tier, Ribbon Communications and AudioCodes Ltd. exemplify positioning anchored in interoperability expertise and Microsoft-certified appliance portfolios respectively. Cisco Systems, Inc. occupies the diversified networking archetype, leveraging integrated security and session management portfolios to dominate enterprise accounts. ADTRAN, Inc. and Patton Electronics Co. represent mid-market specialists with regional density in North American and European sub-markets. Oracle Corporation and Avaya Inc. sit within the legacy-integrated communications tier, navigating appliance-to-cloud substitution pressures through hybrid deployment architectures.
| Leading Market Players |
|---|
| Ribbon Communications |
| ADTRAN, Inc. |
| AudioCodes Ltd. |
| Sangoma Technologies Corp. |
| Patton Electronics Co. |
| Cisco Systems, Inc. |
| Avaya Inc. |
| Edgewater Networks, Inc. |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration for packet-processing ASICs and FPGA components determines both margin compression in hardware-dependent tiers and vendor migration toward software-centric delivery models. Buyers facing silicon lead time volatility accept premium pricing for secured allocation while cloud-native alternatives erode appliance-based maintenance revenue pools.
Pricing Analysis
North American deployments command 15-25% premiums over Asia-Pacific SaaS equivalents due to FCC STIR/SHAKEN compliance bundling and domestic support requirements. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade certification from mid-market Teams-certified appliances and unmanaged virtual instances. Cost compression in hardware tiers is intensifying because containerized substitutes displace chassis-based perpetual licenses. Managed service providers exhibit lowest price sensitivity due to SLA-backed outcome contracts, while Indian fintech startups drive hardest bargain on metered session rates.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries and supply-chain finance facilities at Singaporean distributors stabilize working capital for hardware-dependent vendors. Manufacturing draws from Taiwan, China, and South Korea for specialized silicon, with Mexico and Germany hosting final assembly for regional compliance labeling. Single-source vulnerability concentrates in 7nm and below packet-processing ASICs where two foundries dominate. Distribution runs through systems integrators in Europe, direct enterprise sales in North America, and carrier partnerships across Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer power is shifting toward consolidated procurement teams at Fortune 500 multinationals, fragmenting vendor access and compressing negotiation cycles for specialized SBC suppliers.
For Market Incumbents: Insulate carrier-grade revenue streams by embedding Kubernetes orchestration expertise into professional services offerings, countering cloud-native entrants. Anchor TLS 1.3 and SRTP certification investment against EU NIS2 Directive enforcement timelines. Secure backward integration into FPGA design houses to reduce Taiwanese foundry dependency.
For New Entrants and Emerging Players: German Mittelstand manufacturers replacing ISDN trunking present the most penetrable white-space target, with limited incumbent saturation in sub-500 employee segments. Target Microsoft Teams Direct Routing certification gaps in Australian mid-market enterprises where systems integrators lack vendor alternatives. Lead with API-first deployment models that collapse proof-of-concept cycles.
For Investors and Strategic Acquirers: The market sits at a substitution phase that favors cloud-native software vendors over hardware-dependent incumbents. Long-term viability hinges on containerization expertise and multi-cloud orchestration capabilities rather than appliance installed bases. Monitor 5G standalone voice core deployment announcements as inflection indicator for IMS-SBC convergence demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Kubernetes-Native Product Rearchitecture | Enables elastic scaling for Singaporean financial institutions piloting distributed edge deployments. |
| Microsoft Teams Direct Routing Certification | Unlocks Australian mid-market procurement where hybrid PSTN connectivity requirements dominate. |
| EU NIS2 Directive Compliance Investment | Mandatory TLS 1.3 and SRTP encryption secures German critical infrastructure operator contracts. |
| FPGA Design House Acquisition | Reduces Taiwanese foundry dependency and stabilizes silicon allocation for carrier-grade appliances. |
| Managed Service Provider Partnership | Captures Canadian and Japanese buyer segments lacking internal VoIP engineering depth. |
Research Methodology
A spread of perspectives from enterprise IT architects, carrier network engineers, systems integration leads, and regulatory compliance officers converged on the working assumptions. Primary interviews with CTOs at financial services firms and procurement directors at German automotive manufacturers combined with secondary validation from SEC filings, FCC enforcement records, EU NIS2 implementation guidance, and TRAI lawful interception mandates. Bottom-up session volume modeling and top-down infrastructure spend analysis provided triangulation across deployment modes.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeled across deployment architecture, solution type, end-user category, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted replacement curves and greenfield adoption rates incorporated 5G standalone voice core deployment timelines and Microsoft Teams migration patterns as industry-specific inputs.
Practitioners should monitor silicon allocation announcements from Taiwanese foundries, EU AI Act enforcement precedents on biometric communications analytics, and Indian TRAI lawful interception specification updates for early signals. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Enterprise Routers Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Microduct Market
Network Technology
Gigabit Ethernet Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Global Home Networking Device Market
Network Technology
Wi-Fi Extender Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Router and Switch Market
Network Technology
5G Enterprise Private Network Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Hyperconnectivity Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Residential Routers Market
Network Technology
Fiber to the Premises Market