
 Global Programmable Logical Controllers Automation Market | 2026-2036
Global Programmable Logical Controllers Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Programmable Logical Controllers Automation Market Foresight
The capability gap between capital-heavy integrated automation providers and lean software-centric competitors is redrawing competitive boundaries in PLC supply. Siemens AG leverages its digital twin ecosystem to sustain premium positioning across process automation. Rockwell Automation anchors its North American installed base with deep domain expertise in discrete manufacturing. Mitsubishi Electric Corporation differentiates through in-house semiconductor production that controls critical I/O module supply.
Programmable logical controllers automation encompasses industrial computing systems that execute ladder logic, structured text, or function block diagram instructions with scan cycles typically ranging from one to ten milliseconds to control machinery and production processes. These systems integrate central processing units, power supplies, communication modules, and expandable I/O cards to convert sensor signals into actuator commands across manufacturing environments. Modular PLCs command the largest installed base due to flexible expansion architectures that protect long-term customer investment. Safety PLCs represent the fastest-expanding product category as functional safety certifications become mandatory in automotive and chemical processing lines. Process automation applications generate the deepest margin pools because oil refining units and water treatment facilities demand ruggedized hardware with extended temperature tolerances and redundant processor configurations.
The EU Green Deal and F-Gas Regulation are compelling European PLC vendors to redesign thermal management and power consumption profiles in new controller generations. FDA validation requirements and OSHA machine guarding standards shape safety PLC specification sheets for food processing facilities and manufacturing plants across the United States. Stakeholders must weigh the pace of soft PLC displacement against the reliability premiums that hardwired modular systems still command in critical infrastructure environments.
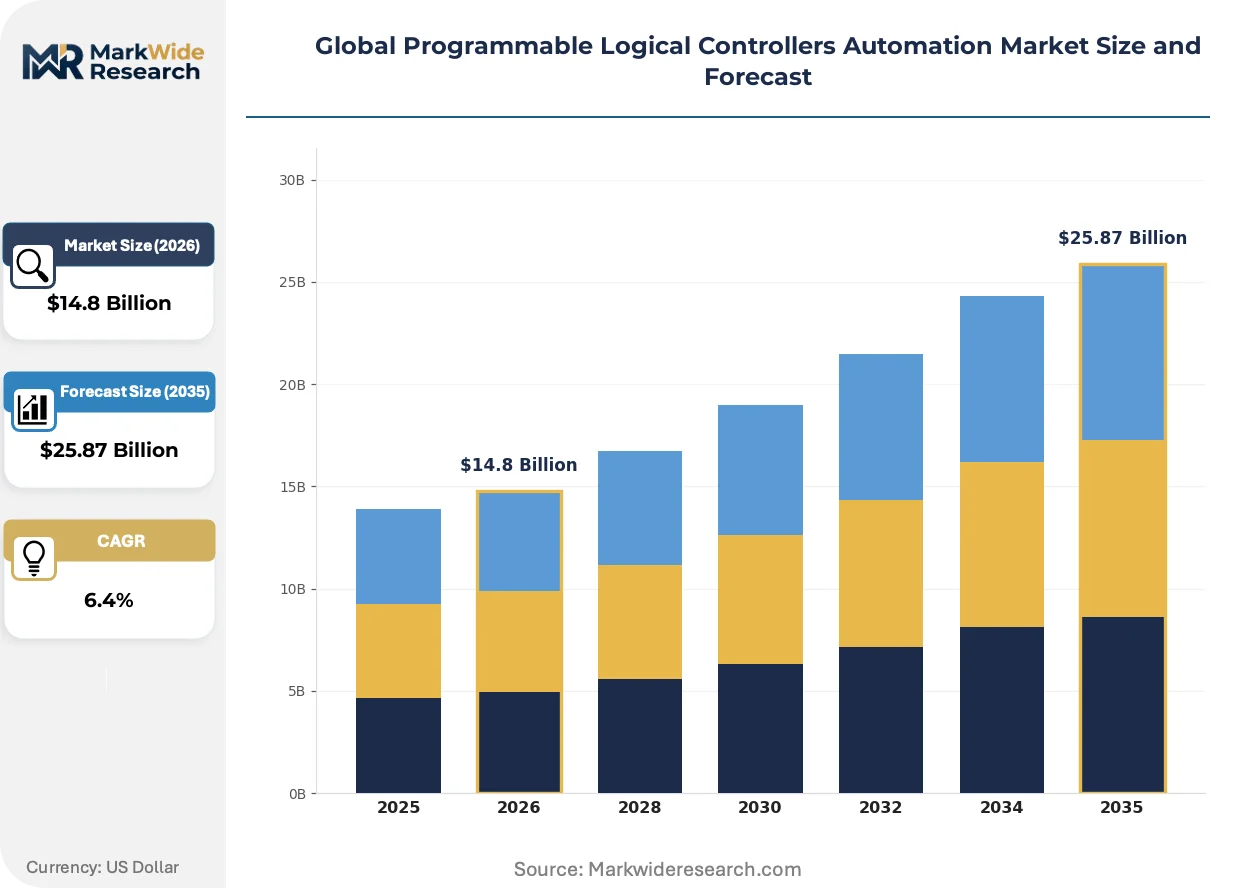
Market Dynamics
The hardwired-to-software transition is compressing PLC hardware margins while expanding software licensing revenue pools across industrial automation architectures.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and F-Gas Regulation force thermal redesign in controller hardware, creating replacement demand for energy-efficient PLC generations across German and French process industries.
- Semiconductor fabrication expansion:Advanced lithography and wafer processing facilities in Taiwan and South Korea deploy precision PLCs for chamber pressure and temperature control at nanometer tolerances.
- Functional safety certification:IEC 61508 and ISO 13849 compliance requirements in automotive assembly lines mandate safety PLC deployment for robot cell guarding and emergency stop circuits.
Market Restraints
- Silicon supply concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced node production, exposing I/O module manufacturers to geopolitical disruption risk and allocation constraints.
- Soft PLC substitution:Industrial PCs running real-time Linux or Windows variants erode standalone controller demand in non-safety-critical packaging and material handling applications.
- Copper and rare earth volatility:Neodymium and dysprosium price swings for servo motor magnets compress margin predictability in motion-integrated PLC systems.
Strategic Opportunities
- India manufacturing incentives:The PLI scheme for electronics and automotive sectors positions Gujarat and Tamil Nadu as greenfield PLC deployment markets with limited incumbent saturation.
- Edge-to-cloud convergence:PLC vendors integrating MQTT brokers and OPC UA pub-sub with AWS IoT and Azure Industrial IoT capture recurring connectivity revenue streams.
- Water infrastructure modernization:EPA Lead and Copper Rule revisions drive SCADA-PLC upgrades in US municipal treatment plants for real-time contaminant monitoring and automated chemical dosing.
Industry Challenges
- IEC 62443 cybersecurity certification:Achieving SL-2 or SL-3 security levels for networked controllers extends development timelines by 12-18 months and requires specialized firmware architecture expertise.
- Legacy protocol integration:Fieldbus migration from PROFIBUS to PROFINET and from DeviceNet to EtherNet/IP forces parallel hardware support and complicates customer upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Programmable Logical Controllers Automation Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact PLCs, Modular PLCs, Rack-mounted PLCs, Soft PLCs, Safety PLCs Technology: Ladder Logic, Functional Block Diagram, Structured Text, Instruction List, Sequential Function Chart Application: Process Automation, Machine Automation, Building Automation, Transportation Systems, Energy Management End User: Manufacturing Plants, Oil Refining Units, Food Processing Facilities, Water Treatment Facilities, Semiconductor Fabrication Units |
| Companies Covered | Siemens AG, Rockwell Automation, Mitsubishi Electric Corporation, Schneider Electric SE, ABB Ltd, Omron Corporation, Honeywell International Inc, Emerson Electric Company, Delta Electronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Programmable Logical Controllers Automation Market Shifts & Advancements
Software-defined control architectures are dissolving the boundary between dedicated PLCs and general-purpose computing platforms, reshaping how automation logic is deployed and monetized.
Containerized PLC runtimes executing ladder logic within Docker or Kubernetes orchestration layers on industrial edge devices are fragmenting the traditional hardware-software bundling model. Automotive and consumer electronics manufacturers in Germany and Japan pilot these architectures for flexible line reconfiguration. The shift is fragmenting vendor lock-in patterns as customers mix runtime licenses from multiple suppliers on shared hardware substrates.
The EU AI Act's risk classification framework for industrial automation systems is tightening validation documentation requirements for AI-integrated PLCs in predictive maintenance and quality inspection roles. Manufacturers must now maintain algorithmic transparency logs and human oversight interfaces for high-risk deployments. German automotive OEMs and French aerospace suppliers are front-loading compliance costs into 2025-2026 procurement budgets.
After-sales service unbundling is accelerating as end-users in process industries separate hardware warranties from software support contracts and predictive analytics subscriptions. Oil refineries in Texas and chemical complexes in Rotterdam now negotiate these elements with distinct vendors rather than accepting bundled packages. The disaggregation is most pronounced in North American and North Sea installations where procurement functions have centralized technical specification authority.
Global Programmable Logical Controllers Automation Market Segmentation
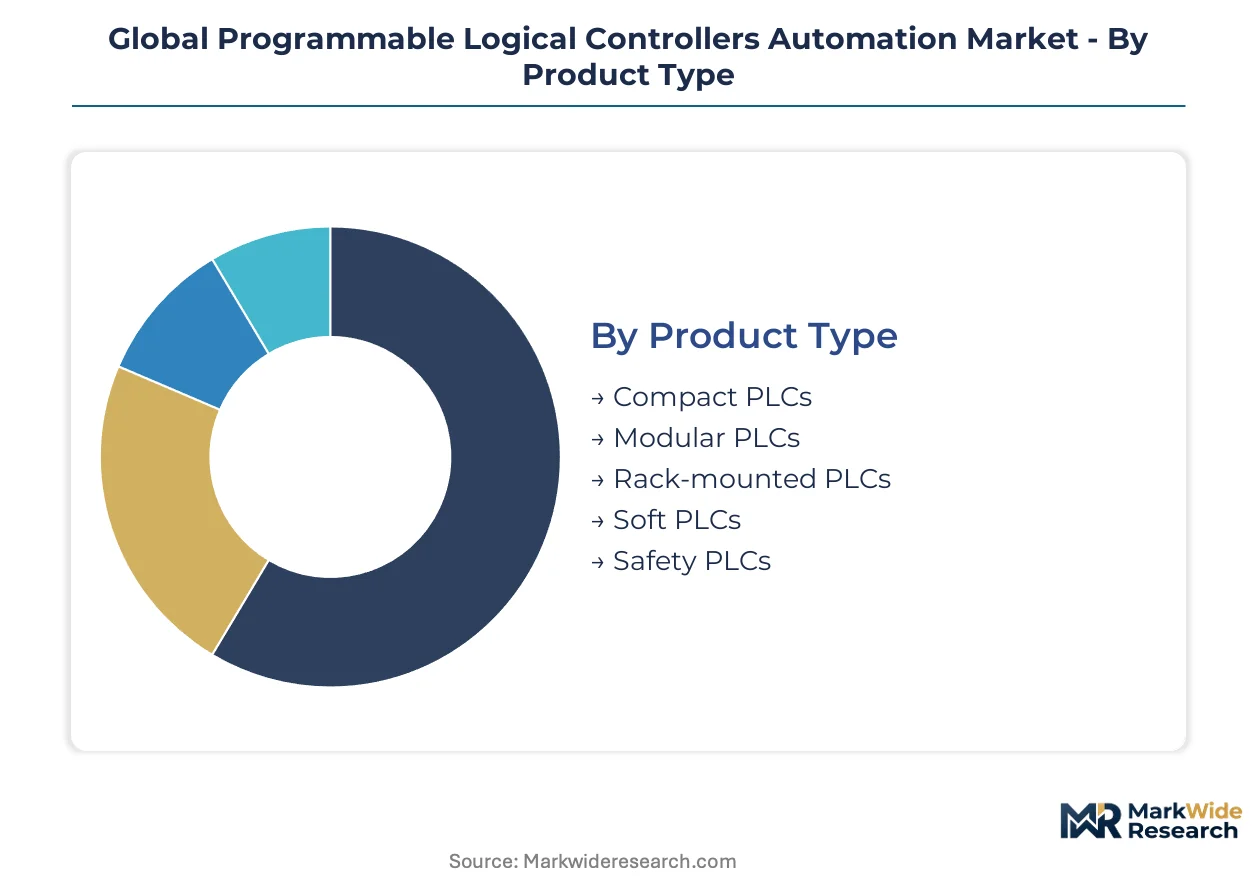
PLC segmentation reveals how hardware architectures, programming paradigms, and vertical applications create distinct margin profiles and competitive battlegrounds. Understanding these partitions exposes where Siemens, Rockwell, and Mitsubishi concentrate R&D resources versus where soft PLC challengers erode incumbency.
Product Type:
EU Green Deal energy efficiency mandates and IEC 61508 safety certifications create divergent compliance burdens across hardware form factors, reshaping replacement cycles and vendor selection criteria.
- Modular PLCs:Expandable chassis architectures accommodate I/O card additions without processor replacement. German automotive OEMs and Texas oil refineries favor these systems for 15-20 year asset lifecycles where incremental capacity expansion protects capital deployment.
- Safety PLCs:Redundant processor configurations with SIL-3 certification for emergency stop circuits and robot cell guarding. ISO 13849 compliance in French aerospace and South Korean automotive assembly lines accelerates specification.
- Compact PLCs:Integrated CPU-I/O-power units for space-constrained material handling stations.
- Rack-mounted PLCs:High-density I/O configurations for semiconductor fabrication cleanrooms in Taiwan and South Korea.
- Soft PLCs:Runtime software executing on industrial PCs, gaining traction in Japanese consumer electronics packaging lines seeking flexible line reconfiguration.
Established volume favors Modular PLCs; emerging adoption favors Safety PLCs.
Technology:
Programming language selection tracks engineer skill availability and application complexity, with structured text climbing fastest in process industries requiring advanced algorithm implementation.
- Ladder Logic:Graphical relay-style programming dominates legacy maintenance pools and technician training programs. US manufacturing plants and Indian automotive suppliers under PLI scheme incentives specify ladder logic for workforce accessibility.
- Structured Text:Pascal-derived syntax enables complex mathematical operations and data manipulation. Water treatment facilities in Rotterdam and chemical complexes in Ludwigshafen deploy structured text for advanced PID control and predictive algorithms.
- Functional Block Diagram:Visual data-flow representation for continuous process control.
- Instruction List:Low-level mnemonic code retained for legacy system compatibility.
- Sequential Function Chart:State-machine programming for batch processing sequences.
Maintenance familiarity sustains Ladder Logic dominance; algorithmic sophistication propels Structured Text expansion.
Application:
Application segmentation aligns with capital intensity cycles and regulatory exposure, with process automation commanding premium pricing for hazardous environment certifications.
- Process Automation:Continuous flow control in oil refining, chemical processing, and water treatment with redundant architectures and extended temperature tolerances. EPA Lead and Copper Rule revisions drive SCADA-PLC upgrades in US municipal plants.
- Machine Automation:Discrete manufacturing control for assembly, packaging, and material handling with sub-10 millisecond scan cycles. Japanese robotics integrators and German machine builders specify these systems for precision motion control.
- Building Automation:HVAC and lighting integration for commercial and industrial facilities.
- Transportation Systems:Railway signaling and tunnel ventilation control with specialized environmental hardening.
- Energy Management:Grid-tied power distribution and renewable integration with IEC 61850 protocol support.
Margin depth concentrates in Process Automation; deployment velocity peaks in Machine Automation.
End User:
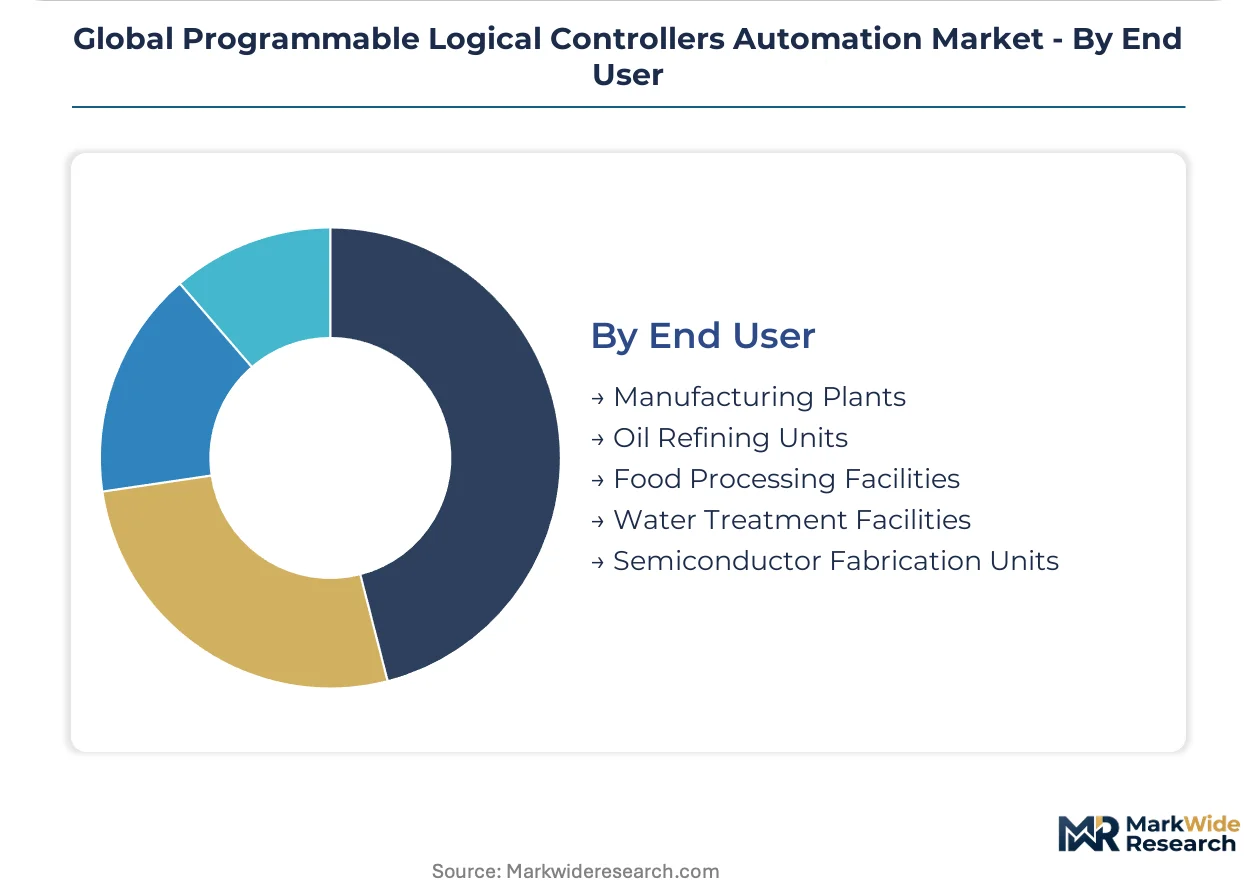
End user segmentation reflects vertical specialization requirements, with semiconductor fabrication demanding nanometer-scale precision and food processing requiring FDA-validated sanitary designs.
- Oil Refining Units:Explosion-proof enclosures and redundant safety systems for hydrocarbon processing. Texas Gulf Coast and Rotterdam complexes prioritize ruggedized hardware with 25-year operational lifespans.
- Semiconductor Fabrication Units:Vibration-isolated, contamination-resistant controllers for lithography and etching equipment. Taiwan and South Korean foundries deploy precision PLCs for chamber pressure control at atomic-layer tolerances.
- Manufacturing Plants:General discrete automation across automotive, electronics, and consumer goods.
- Food Processing Facilities:Stainless steel housings and washdown ratings for FDA-compliant sanitary operations.
- Water Treatment Facilities:Chemical dosing and filtration control with real-time contaminant monitoring integration.
Capital intensity anchors Oil Refining demand; technology upgrade cycles accelerate Semiconductor Fabrication replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, China, and the United States generate the deepest PLC automation demand pools, though their trade balances diverge sharply. German engineering houses export integrated automation systems while Chinese fabricators narrow import dependency through domestic controller production. American process industries sustain premium hardware sourcing despite soft PLC substitution pressures.
United States
Texas Gulf Coast refineries and Pennsylvania shale gas processors deploy ruggedized PLCs for hydrocarbon flow control with 25-year operational lifecycles. EPA Lead and Copper Rule revisions mandate SCADA-PLC upgrades in municipal water treatment plants. Detroit automotive assembly lines specify safety PLCs for robot cell guarding under OSHA machine guarding standards.
Germany
Ludwigshafen chemical complexes and Bavarian automotive OEMs anchor European process automation demand. EU Green Deal energy efficiency mandates force thermal redesign in controller hardware, accelerating replacement cycles. Stuttgart industrial machinery builders integrate PLCs with digital twin architectures for precision motion control.
China
Yangtze River Delta electronics manufacturers and Pearl River Delta packaging facilities drive compact PLC deployment for space-constrained production lines. MIIT industrial internet policies accelerate domestic controller development to reduce import dependency. Shenzhen automation integrators pilot containerized PLC runtimes on industrial edge devices.
Japan
Nagoya automotive suppliers and Osaka robotics integrators specify sub-10 millisecond scan cycle PLCs for precision assembly operations. METI smart manufacturing initiatives fund edge-to-cloud convergence in factory automation. Kyushu semiconductor equipment manufacturers demand vibration-isolated controllers for lithography systems.
South Korea
Seoul Capital Area foundries and Busan shipyards deploy rack-mounted PLCs for high-density I/O configurations. MFDS pharmaceutical manufacturing standards shape validation requirements for automated batch processing. Gwangju industrial zones adopt safety PLCs under ISO 13849 compliance for automotive component lines.
Global Programmable Logical Controllers Automation Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that bundle hardware, software, and service capabilities into multi-decade customer relationships. Siemens AG and Rockwell Automation anchor the premium tier through digital twin ecosystems and deep domain expertise respectively. Mitsubishi Electric Corporation occupies a distinct position through captive semiconductor production that insulates I/O module supply. Competitive moves center on strategic partnerships for edge-to-cloud connectivity and portfolio diversification into predictive analytics subscriptions.
Within the integrated automation tier, Siemens AG exemplifies the European engineering conglomerate archetype through its Munich-based industrial digitalization portfolio. Rockwell Automation represents the North American discrete manufacturing specialist with Milwaukee-anchored domain expertise. Mitsubishi Electric Corporation occupies the East Asian vertically integrated position through its Tokyo-based in-house semiconductor capabilities. These three anchors illustrate how geographic origin and captive supply chain control shape competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| ABB Ltd |
| Omron Corporation |
| Honeywell International Inc |
| Emerson Electric Company |
| Delta Electronics, Inc. |
| Others |
Supply & Pricing Matrix
Soft PLC runtime substitution for dedicated hardware controllers simultaneously redistributes manufacturing geography toward industrial PC assemblers in Taiwan and compresses margin capture from capital equipment toward recurring software licenses. This displacement dynamic concentrates pricing power with semiconductor foundries supplying I/O modules while eroding premium positioning for traditional chassis-based systems.
Pricing Analysis
Configured-to-order pricing for safety-certified PLCs with SIL-3 redundancy commands substantial premiums over standard compact units for material handling. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Pricing pressure stems from soft PLC erosion in non-safety packaging applications where industrial PCs undercut hardware margins. System integrators in Japanese consumer electronics represent the most price-sensitive buyers; German chemical processors show least sensitivity due to validation lock-in.
Supply Chain Analysis
Extended lead times for advanced-node semiconductors from Taiwan and South Korea force PLC manufacturers into buffer inventory positions that tie up working capital. I/O module production draws from Taiwan Semiconductor Manufacturing and Samsung Foundry for processor chips, alongside copper and rare earth magnets from Chinese refiners for servo integration. Single-source vulnerability concentrates in advanced lithography nodes below seven nanometers. Distribution runs through authorized system integrators and direct OEM relationships rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive analytics subscriptions and cybersecurity firmware update contracts expand recurring revenue pools faster than hardware replacement cycles, transforming PLC vendors into service-anchored automation platforms.
For Market Incumbents: Shield installed base relationships by embedding IEC 62443 SL-3 cybersecurity certification into firmware architectures before soft PLC competitors achieve compliance parity. Accelerate captive semiconductor production or long-term foundry offtake agreements to neutralize Taiwan supply concentration risk. Prioritize digital twin integration contracts that raise switching costs for German automotive and Texas refinery accounts.
For New Entrants and Emerging Players: Anchor in India's PLI scheme electronics manufacturing corridors where incumbent saturation remains limited and domestic controller demand is accelerating. Target water treatment SCADA upgrade cycles driven by EPA Lead and Copper Rule enforcement as the most penetrable vertical. Lead with containerized runtime licensing on edge hardware to bypass capital-intensive chassis manufacturing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed industrial software platforms seeking PLC hardware anchoring for vertical integration. Five-to-ten year viability hinges on successful service revenue transition exceeding fifty percent of total mix. Monitor soft PLC adoption rates in Japanese packaging lines as the inflection signal for hardware displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Platform Integration | MQTT broker and OPC UA pub-sub integration with AWS IoT captures recurring connectivity revenue from German OEMs. |
| Safety Certification Investment | IEC 61508 SIL-3 compliance for automotive robot cell guarding locks out unqualified competitors from French assembly lines. |
| Semiconductor Supply Agreement | Long-term foundry offtake with Taiwan or South Korean producers secures I/O module allocation against geopolitical disruption. |
| Predictive Analytics Subscription | Unbundled after-sales service contracts in Rotterdam chemical complexes separate hardware from software monetization. |
| Green Manufacturing Transition | EU Green Deal thermal redesign in controller hardware accelerates replacement demand across Ludwigshafen process industries. |
Research Methodology
The analysis maps modular PLC, safety PLC, compact PLC, rack-mounted PLC, and soft PLC sub-sectors, each validated through plant engineers, OEM procurement teams, system integrators, and aftermarket service heads. Primary interviews with automation directors at German automotive OEMs, Texas refinery maintenance chiefs, and Taiwan semiconductor equipment manufacturers combined with secondary validation from SEC 10-K filings, customs trade data, IEC certification registries, and EPA enforcement databases. Bottom-up unit shipment estimates triangulated against top-down industrial automation capital expenditure benchmarks.
Consistency checks against external semiconductor equipment capex disclosures and regional industrial production indices validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product architecture, programming language, application vertical, and end-user industry dimensions. CAGRs derived from regression analysis of replacement cycle timing, regulatory compliance deadlines, and technology substitution elasticities. Forecast inputs included MIIT industrial internet policy implementation pace and EU AI Act validation documentation requirements.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and no Taiwan supply disruption; material deviation would warrant model refresh. Semiconductor allocation constraints, soft PLC substitution velocity, and cybersecurity certification timeline slippage represent primary forecast revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Smart Handwriting Machine Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
HMI Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Smart Elevator Automation System Market