
 Network Management Solutions Market | 2026-2036
Network Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Network Management Solutions Market Foresight
ISO/IEC 27001 certification cycles for information security management systems is collapsing the vendor qualification window for enterprise procurement teams. Cisco Systems, Inc. dominates the integrated solutions tier through its DNA Center platform and extensive channel partnerships. Huawei Technologies Co., Ltd. competes aggressively in the Asia-Pacific infrastructure layer with proprietary 5G network management stacks. Juniper Networks, Inc. differentiates through Mist AI integration and cloud-native automation frameworks.
Network management solutions encompass software platforms and hardware appliances that monitor, configure, analyze, and secure distributed communication infrastructure through protocols including SNMP, NetFlow, and streaming telemetry. These systems enable real-time fault detection, capacity planning, and policy enforcement across multi-vendor environments spanning LAN, WAN, and cloud edge deployments. Performance monitoring commands the largest revenue pool as enterprises confront visibility gaps in hybrid cloud architectures, while SaaS deployment models are displacing traditional on-premises installations among mid-market buyers. Configuration management retains premium pricing power due to compliance automation requirements in regulated verticals.
The Federal Communications Commission enforces network reliability standards that mandate outage reporting thresholds, directly elevating fault management module procurement among US carriers. The European Union's Cybersecurity Act and NIS2 Directive impose baseline security requirements on critical network operators, creating mandatory upgrade cycles for legacy management platforms. India's Telecom Regulatory Authority mandates quality of service benchmarks that drive continuous monitoring investments. Stakeholders must weigh sovereign data localization rules against cloud-native architecture roadmaps when selecting deployment architectures.
Market Dynamics
The Federal Communications Commission's net neutrality restoration rules are forcing carriers to rearchitect traffic prioritization systems, compressing procurement cycles for intelligent orchestration platforms that can demonstrate policy-compliant bandwidth allocation.
Growth Catalysts
- 5G Backhaul Complexity:Telecommunication carriers face exponential growth in radio access network endpoints. Automated orchestration platforms resolve configuration sprawl across multi-vendor infrastructure.
- TRAI Quality Mandates:India's Telecom Regulatory Authority imposes strict service benchmarks on license holders. Continuous monitoring investments satisfy reporting requirements while reducing churn.
- Hybrid Cloud Visibility Gaps:Enterprise IT teams struggle with performance blind spots spanning on-premises and cloud edge deployments. Unified monitoring consoles consolidate telemetry from distributed workloads.
Market Restraints
- Semiconductor Supply Concentration:Specialized ASICs for telemetry processing face fabrication bottlenecks concentrated in East Asian foundries. Lead times for hardware appliances extend qualification windows.
- ISO/IEC 27001 Compression:Certification cycles for information security management systems are collapsing. Vendor qualification timelines now exceed procurement team capacity.
- Legacy Protocol Entrenchment:SNMPv2 remains embedded in brownfield infrastructure. Migration to streaming telemetry requires forklift upgrades that carriers defer.
Strategic Opportunities
- EU NIS2 Directive Compliance:The European Union's cybersecurity baseline mandates upgrade cycles for critical network operators. Legacy management platform replacements create immediate addressable demand.
- SaaS Displacement in Mid-Market:Cloud-native deployment models bypass capital constraints that previously blocked smaller enterprises. Subscription pricing unlocks segments historically served by open-source tools.
- AI-Driven Root Cause Analysis:Machine learning integration with NetFlow data reduces mean time to resolution. Early adopters in financial services report operational cost compression.
Industry Challenges
- Streaming Telemetry Skill Scarcity:Network engineering teams lack proficiency in gRPC and protocol buffer implementations. Training programs lag adoption curves for modern data collection methods.
- Multi-Vendor Integration Friction:API heterogeneity across equipment suppliers forces custom adapter development. Each integration project extends deployment timelines and strains professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Management Solutions Market |
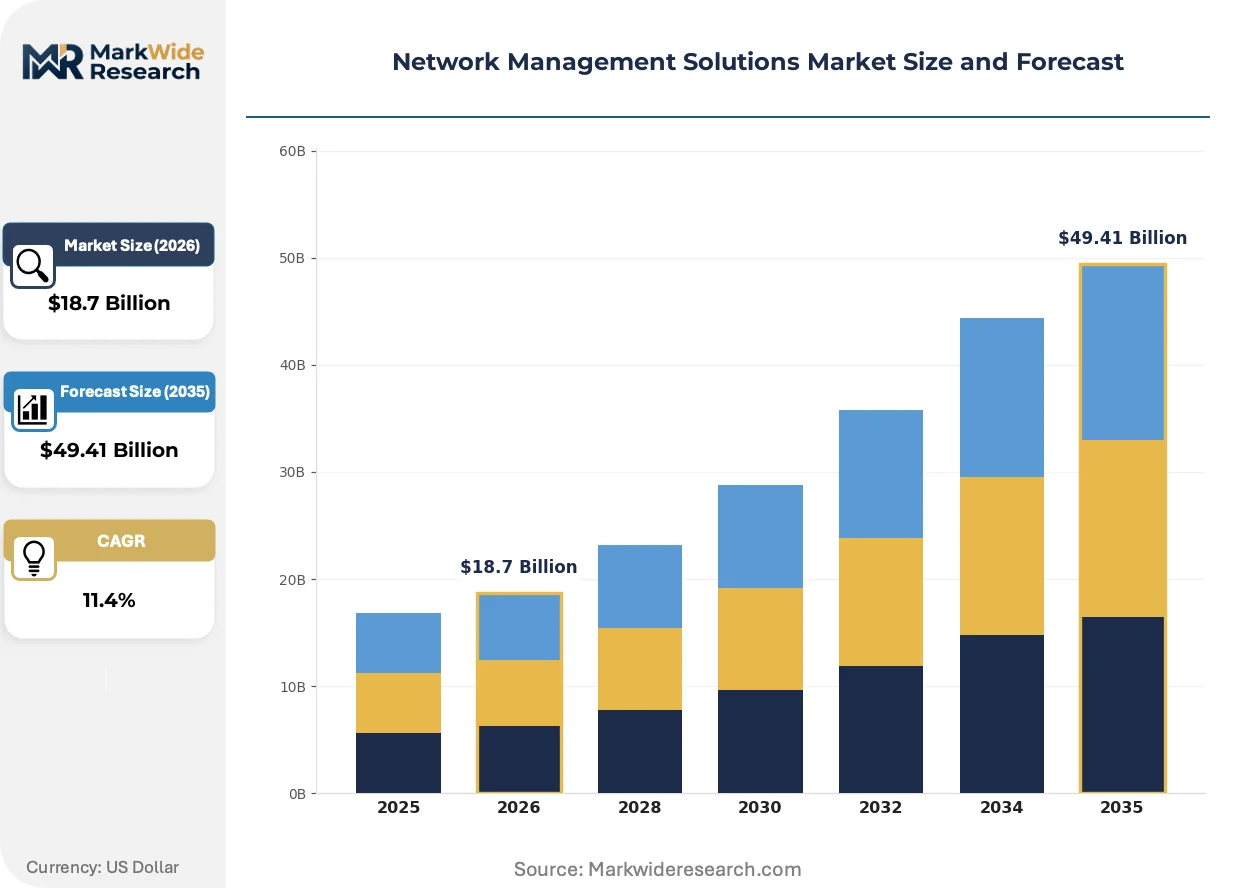
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Performance Monitoring, Configuration Management, Fault Management, Traffic Analysis Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: Telecommunication, IT Services, Government, Educational Institutions Solution: Integrated Solutions, Standalone Tools, Open-Source Software, Proprietary Systems |
| Companies Covered | Cisco Systems, Inc., Hewlett Packard Enterprise Company, Huawei Technologies Co., Ltd., Juniper Networks, Inc., Nokia Corporation, SolarWinds, IBM Corporation, NETSCOUT, Extreme Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Management Solutions Market Shifts & Advancements
Network management architectures are pivoting from reactive polling to predictive streaming, with artificial intelligence inference engines now embedding directly into data plane telemetry paths rather than residing solely in centralized analytics clusters.
Streaming telemetry using gRPC and protocol buffers is miniaturizing the data collection footprint within switch and router operating systems. Cloud service providers are deploying these agents at line rate across hyperscale fabrics. The shift is miniaturizing monitoring overhead from megabits of SNMP polling traffic to kilobits of precise, timestamped events, enabling sub-second anomaly detection that polling intervals cannot achieve.
The European Union's NIS2 Directive imposes mandatory incident reporting thresholds on critical infrastructure operators. Network operators must demonstrate continuous situational awareness or face regulatory penalties. Telecommunication carriers in Germany, France, and the Netherlands are accelerating fault management module procurement to satisfy documentation requirements before enforcement deadlines.
Enterprise procurement teams are consolidating vendor relationships around platforms that bundle configuration management with compliance automation. Mid-market buyers previously reliant on point solutions now prefer integrated suites that satisfy ISO 27001, SOC 2, and sector-specific mandates through unified policy engines. Financial services and healthcare verticals in the United States demonstrate the strongest preference for consolidated procurement, driven by overlapping HIPAA and SEC cybersecurity disclosure obligations.
Network Management Solutions Market Segmentation
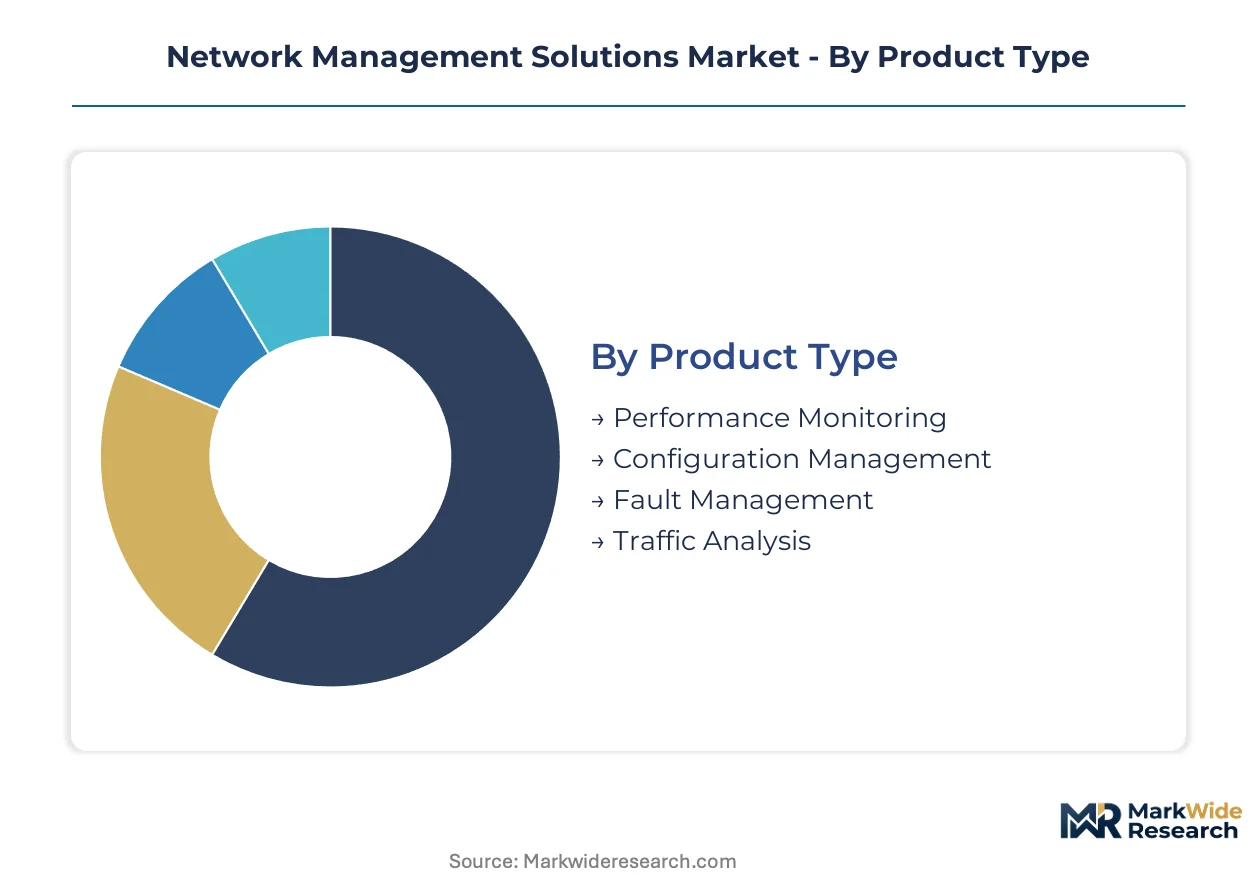
Network management solutions fragment across four critical dimensions that determine procurement priorities and vendor positioning. Product type differentiation reflects the technical maturity of buyer infrastructure, while deployment models signal organizational cloud readiness and capital constraints.
Product Type:
Performance monitoring faces acute substitution pressure from observability platforms that collapse network metrics into unified telemetry streams.
- Performance Monitoring:Unified consoles aggregate SNMP, NetFlow, and streaming telemetry from hybrid cloud architectures. Financial services firms in New York and London deploy these systems to eliminate visibility gaps between on-premises data centers and AWS or Azure edge instances.
- Configuration Management:Policy engines automate compliance enforcement across multi-vendor device fleets. Telecommunication carriers in India prioritize these tools to satisfy TRAI quality reporting mandates while reducing manual provisioning errors.
- Fault Management:Real-time alerting systems correlate events across distributed infrastructure layers.
- Traffic Analysis:Deep packet inspection and flow records enable bandwidth optimization and security forensics.
Performance monitoring anchors the volume base while configuration management gains share at the steepest rate.
Deployment:
Cost tier stratification separates enterprise buyers with dedicated infrastructure teams from mid-market organizations seeking operational simplicity.
- Cloud-based:Managed service delivery eliminates capital expenditure for hardware appliances. European enterprises under NIS2 Directive pressure favor these deployments to accelerate compliance timelines without internal platform development.
- SaaS:Subscription pricing unlocks network management capabilities for organizations below 500 employees. Mid-market buyers in the United States displace open-source tools with these offerings to access enterprise-grade features without dedicated engineering headcount.
- On-premises:Air-gapped installations satisfy sovereign data requirements in defense and critical infrastructure sectors.
- Hybrid:Split architectures retain sensitive control plane functions locally while pushing analytics to cloud substrates.
SaaS deployments anchor the volume base while cloud-based models expand most quickly among regulated European verticals.
End User:
Application intensity varies dramatically across buyer categories, with telecommunications demanding real-time orchestration at scale.
- Telecommunication:Carriers manage millions of endpoints across 5G radio access networks. Verizon, Jio, and Deutsche Telekom drive procurement of automated orchestration platforms to resolve configuration sprawl in multi-vendor infrastructure.
- IT Services:Managed service providers deliver white-labeled network operations to enterprise clients. Indian IT services firms deploy these solutions to meet SLA commitments across distributed client environments.
- Government:Federal agencies mandate FedRAMP-authorized platforms with encryption standards exceeding commercial baselines.
- Educational Institutions:University networks face seasonal traffic spikes and bring-your-own-device complexity without proportional security staffing.
Telecommunication anchors the volume base while IT services climbs the fastest as outsourcing accelerates.
Solution:
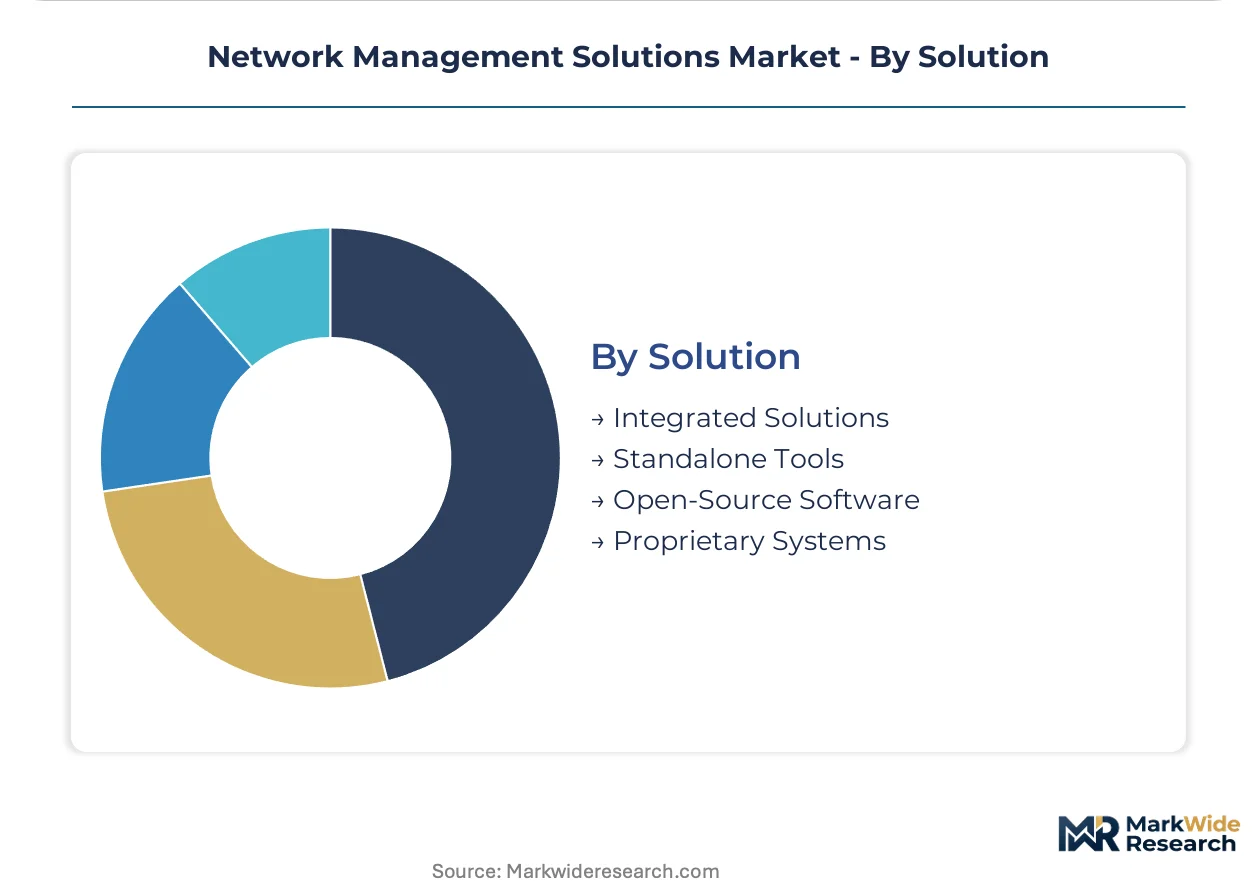
Customer type segmentation reveals a bifurcation between integrated platform buyers and specialized tool adopters.
- Integrated Solutions:Unified suites bundle monitoring, configuration, and security functions through single policy engines. Healthcare systems in the United States consolidate procurement around these platforms to satisfy overlapping HIPAA and SEC cybersecurity disclosure obligations.
- Standalone Tools:Point solutions address specific pain points without platform lock-in. Engineering teams in technology startups prefer these for targeted troubleshooting without enterprise licensing overhead.
- Open-Source Software:Community-developed alternatives reduce licensing costs for technically sophisticated operators.
- Proprietary Systems:Vendor-locked implementations optimize for specific hardware ecosystems.
Integrated solutions anchor the volume base while open-source software gains share fastest among cloud-native enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Communications Commission's net neutrality restoration rules are accelerating procurement cycles for intelligent orchestration platforms among United States carriers. Telecommunication infrastructure investments concentrate where regulatory mandates intersect with 5G deployment density.
United States
Telecommunication carriers face compressed timelines to rearchitect traffic prioritization systems under FCC mandates. The Federal Communications Commission enforces network reliability standards that mandate outage reporting thresholds, directly elevating fault management module procurement. Verizon and AT&T drive automated orchestration platform deployment across their 5G radio access networks to resolve configuration sprawl.
Germany
Critical infrastructure operators accelerate legacy management platform replacements to satisfy EU NIS2 Directive compliance deadlines. The European Union's Cybersecurity Act imposes baseline security requirements that create mandatory upgrade cycles for network operators. Deutsche Telekom anchors procurement demand in the Rhine-Ruhr industrial corridor, deploying continuous monitoring investments to demonstrate situational awareness.
India
Telecommunication license holders confront stringent network performance reporting requirements from the Department of Telecommunications. TRAI quality mandates impose strict service benchmarks that drive continuous monitoring investments while reducing subscriber churn. Reliance Jio and Bharti Airtel expand automated orchestration deployments across Mumbai and Bangalore to satisfy compliance obligations.
Japan
Enterprise IT teams address hybrid cloud visibility gaps spanning on-premises data centers and cloud edge deployments. METI industrial policy encourages digital infrastructure modernization through subsidy programs for small and medium enterprises. Tokyo and Osaka metropolitan clusters concentrate demand for unified monitoring consoles that consolidate telemetry from distributed workloads.
United Kingdom
Financial services firms in London deploy performance monitoring systems to eliminate visibility gaps between legacy infrastructure and AWS or Azure edge instances. The UK national cybersecurity center imposes incident reporting thresholds that elevate fault management procurement among critical network operators. The London-Southeast technology corridor anchors SaaS displacement trends as mid-market buyers seek operational simplicity without dedicated engineering headcount.
Network Management Solutions Market Competitive Landscape
Listed leaders compete with private specialists across integrated platform and point solution dimensions. The vendor base clusters around three strategic tiers: diversified technology conglomerates with extensive channel partnerships, networking specialists with proprietary hardware-software integration, and cloud-native challengers with subscription delivery models. Dominant competitive moves include portfolio consolidation through strategic acquisitions and geographic expansion via regional data center deployments.
Within the integrated solutions tier, Cisco Systems, Inc. and Hewlett Packard Enterprise Company occupy positions exemplifying platform breadth through unified policy engines. Juniper Networks, Inc. sits within the networking specialist archetype, representing cloud-native automation frameworks. These three companies anchor competitive positioning across enterprise procurement segments where configuration management and compliance automation command premium pricing power.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise Company |
| Huawei Technologies Co., Ltd. |
| Juniper Networks, Inc. |
| Nokia Corporation |
| SolarWinds |
| IBM Corporation |
| NETSCOUT |
| Extreme Networks |
| Others |
Supply & Pricing Matrix
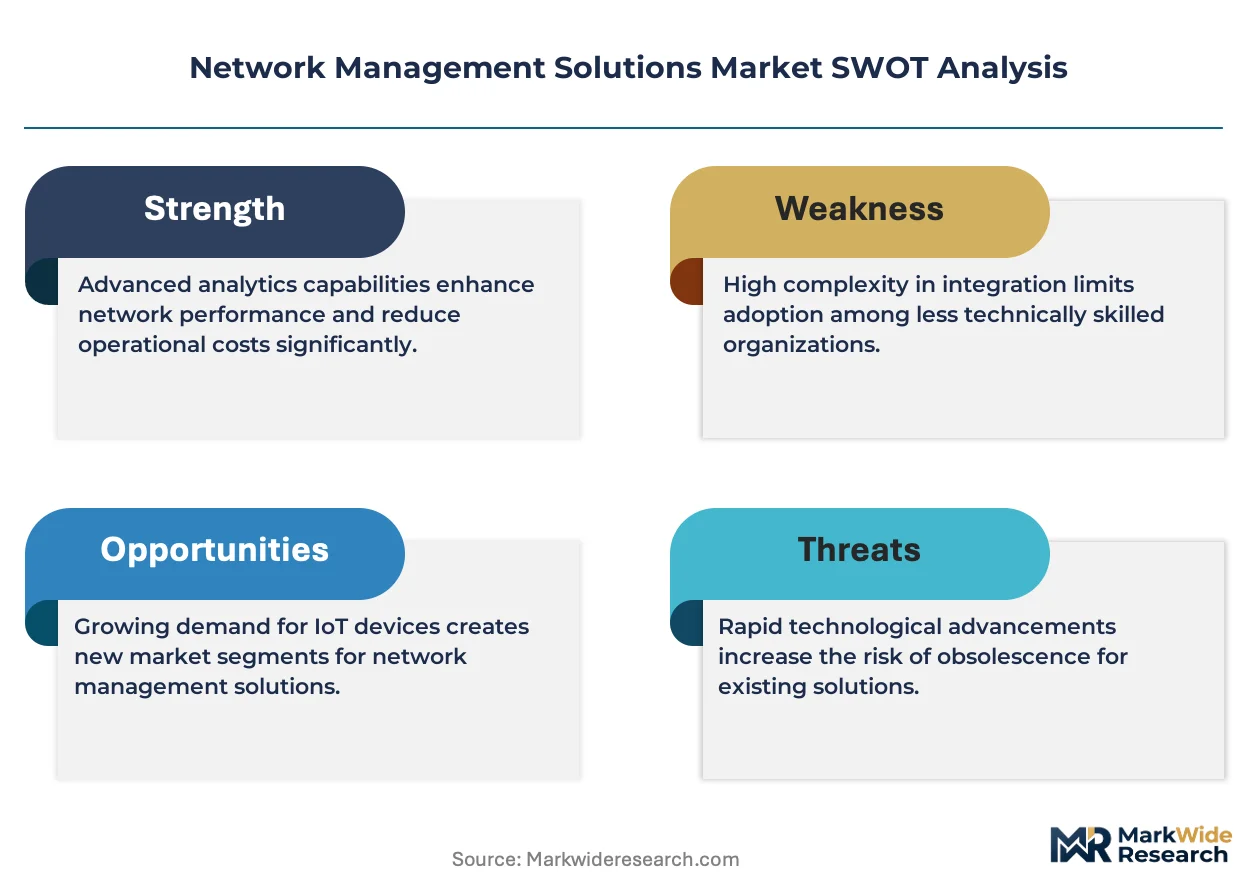
ISO/IEC 27001 certification cycles gate both vendor qualification timelines and price differentiation across enterprise procurement tiers, compressing supplier windows while elevating premium pricing for pre-certified platforms. This dual constraint reshapes how buyers evaluate total cost of ownership against deployment velocity.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO 27001-certified platforms commanding subscription premiums over uncertified alternatives. SaaS-tiered pricing dominates deployment models, though configuration management modules retain project-based licensing for regulated verticals. Price differentiation rests on compliance automation depth and after-sales service bundling. Cost compression in mid-market SaaS tiers intensifies as open-source tools mature. Telecommunication carriers demonstrate lowest price sensitivity due to regulatory non-compliance penalties, while educational institutions face acute budget constraints.
Supply Chain Analysis
Port congestion across the Shanghai-Singapore trade lane elevates inbound logistics costs for specialized telemetry processing hardware. Geographic supply concentrates in Taiwan for advanced ASIC fabrication, South Korea for memory components, and China for commodity networking hardware. Raw material dependencies span silicon wafers, rare earth elements for magnetics, and high-purity copper for interconnects. Single-source vulnerability in East Asian foundries exposes qualification timelines to disruption. Distribution runs through authorized channel partners with certified integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates among telecommunication carriers consolidating vendor relationships around integrated platforms, fragmenting pricing leverage for point solution providers.
For Market Incumbents: Fortify platform stickiness through embedded AI-driven root cause analysis that raises switching costs for carrier clients. Deepen backward integration into streaming telemetry ASIC design to secure supply continuity against foundry bottlenecks. Invest in FedRAMP and EU Cybersecurity Act pre-certification to compress competitor qualification windows. For New Entrants and Emerging Players: Anchor in SaaS displacement opportunities among mid-market enterprises below 500 employees, where open-source tool limitations create immediate upgrade demand. Target European verticals under NIS2 Directive pressure seeking accelerated compliance without internal platform development. Lead with unified observability positioning that collapses network metrics into telemetry streams. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed networking specialists possessing cloud-native automation frameworks but limited channel scale. Five-to-ten year viability hinges on AI inference integration at the data plane edge. Monitor gRPC and protocol buffer adoption curves as inflection indicators for modern telemetry stack transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified policy engines satisfy overlapping HIPAA and SEC cybersecurity disclosure obligations for US healthcare systems. |
| Acquisition of Specialist Firm | Mist AI capabilities accelerate cloud-native automation differentiation against legacy polling architectures. |
| Geographic Expansion | Regional data center deployments in Frankfurt and Mumbai address EU data localization and TRAI reporting mandates. |
| Strategic Partnership | Channel alliances with Indian IT services firms unlock SLA-driven procurement across distributed client environments. |
| Product Launch | Streaming telemetry modules using gRPC reduce monitoring overhead from megabits to kilobits for hyperscale fabrics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network operations executives, IT procurement officers, platform engineers, and channel integration specialists. Secondary validation drew from SEC filings, hyperscaler capex disclosures, carrier outage reporting databases, and regulatory enforcement records. Bottom-up sizing of vendor bookings triangulated against top-down infrastructure spending estimates.
Across the analysis window, forecasts modeled deployment model transitions, organization size tiers, vertical regulatory intensity, and integration complexity gradients. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Network endpoint density projections and compliance mandate enforcement timelines served as industry-specific calibration inputs.
Material uncertainties — semiconductor fabrication capacity constraints, sovereign data localization rule changes, and streaming telemetry skill scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and vendor consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Europe SD-WAN Market
Network Technology
Residential Routers Market
Network Technology
Virtual Router Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
ISP Management Systems Market
Network Technology
Enterprise Network Equipment Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Protocol Analyzer Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Global Network Monitoring Market
Network Technology
US Private 5G Network Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Passive Optical Network Market