
 Global Mica Market | 2026-2036
Global Mica Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mica Market Intelligence
Expertise in ethical sourcing and supply chain traceability is rotating from a niche compliance function to a core operational capability for mica suppliers. Imerys SA leverages its global footprint to implement and certify responsible mining practices across its operations. Daruka Minerals specializes in high-purity grades for the cosmetics industry, while Franklin Industrial Minerals controls significant reserves in the United States.
Mica refers to a group of naturally occurring silicate minerals characterized by their perfect basal cleavage, which allows separation into thin, flexible laminae. This unique physical property makes it an essential material for applications requiring high dielectric strength and thermal resistance, particularly in electrical equipment. Ground mica constitutes the largest product segment by volume, driven by its use as a functional filler in paints and plastics reinforcement. In contrast, high-value sheet mica remains critical for specialized electronics insulation applications.
Market access and operational conduct are governed by a complex web of regulations, including the EU's REACH framework for chemical safety and OSHA standards for worker dust exposure in the United States. In major producing countries like India, national and state-level mining laws directly impact extraction methods and labor practices. Supplier selection will increasingly hinge on the ability to provide transparent, verifiable documentation of compliance with both environmental and ethical sourcing mandates.
Market Dynamics
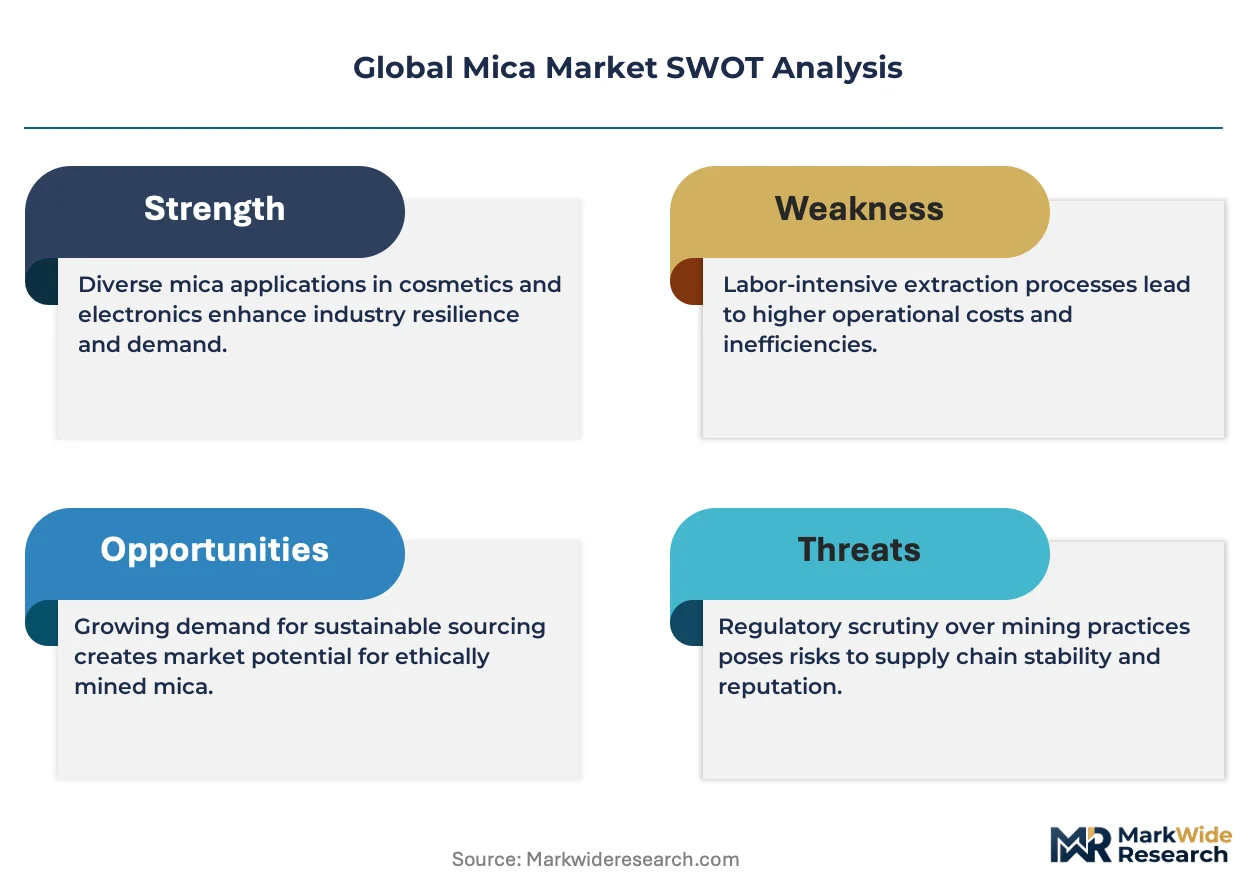
The mica market's central dynamic is the escalating pressure for supply chain transparency and ethical sourcing. Mandates like the EU's CSRD are forcing a structural shift, compelling downstream users in automotive and cosmetics to demand verifiable proof of responsible mining practices.
Growth Catalysts
- Automotive Sector Expansion:The automotive industry's continuous drive for lightweighting vehicles boosts demand for mica as a reinforcing agent in plastics, while its use in pearlescent paints for vehicle coatings provides further momentum.
- Ethical Sourcing Mandates:Regulations requiring supply chain due diligence, such as the EU's Corporate Sustainability Reporting Directive, create a premium market for mica that is certified as ethically sourced and traceable.
- Electronics Miniaturization:Ongoing miniaturization of consumer electronics and industrial equipment sustains demand for high-quality sheet mica, valued for its exceptional dielectric strength and thermal insulation properties in compact designs.
Market Restraints
- Supply Chain Concentration:Heavy reliance on a few key producing regions, particularly India, for a significant portion of global mica sheet and scrap supply creates vulnerability to localized regulatory changes, logistical disruptions, and labor issues.
- Substitution by Synthetics:The development of synthetic mica (fluorphlogopite) presents a significant substitution threat, especially in high-value applications like cosmetics and pearlescent pigments where its purity and ethical certainty are advantages.
- Regulatory Compliance Costs:Adherence to stringent occupational health standards, including OSHA regulations on silica dust exposure in the US, and environmental mining laws in producing nations increases operational costs and capital expenditure for miners.
Strategic Opportunities
- Electric Vehicle Batteries:The expanding electric vehicle market opens new applications for mica as a thermal barrier and insulator within battery packs, offering a high-growth avenue for specialized mica products.
- Geographic Diversification:Establishing and certifying new, ethical mica mining operations in geographies outside of the traditional Indian subcontinent, such as in Brazil or parts of Africa, can meet demand for diversified and secure supply chains.
- Advanced Composite Materials:Developing high-aspect-ratio and surface-modified mica grades offers opportunities to create superior performance fillers for advanced polymer composites in aerospace and industrial applications.
Industry Challenges
- Traceability Implementation:A primary operational hurdle is the high cost and complexity of implementing and auditing robust traceability systems, particularly across a fragmented supply base of small-scale and artisanal mines.
- Child Labor Eradication:Despite industry initiatives, the complete eradication of child labor from informal mining sectors remains a persistent and complex challenge that carries significant reputational risk for the entire supply chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mica Market |
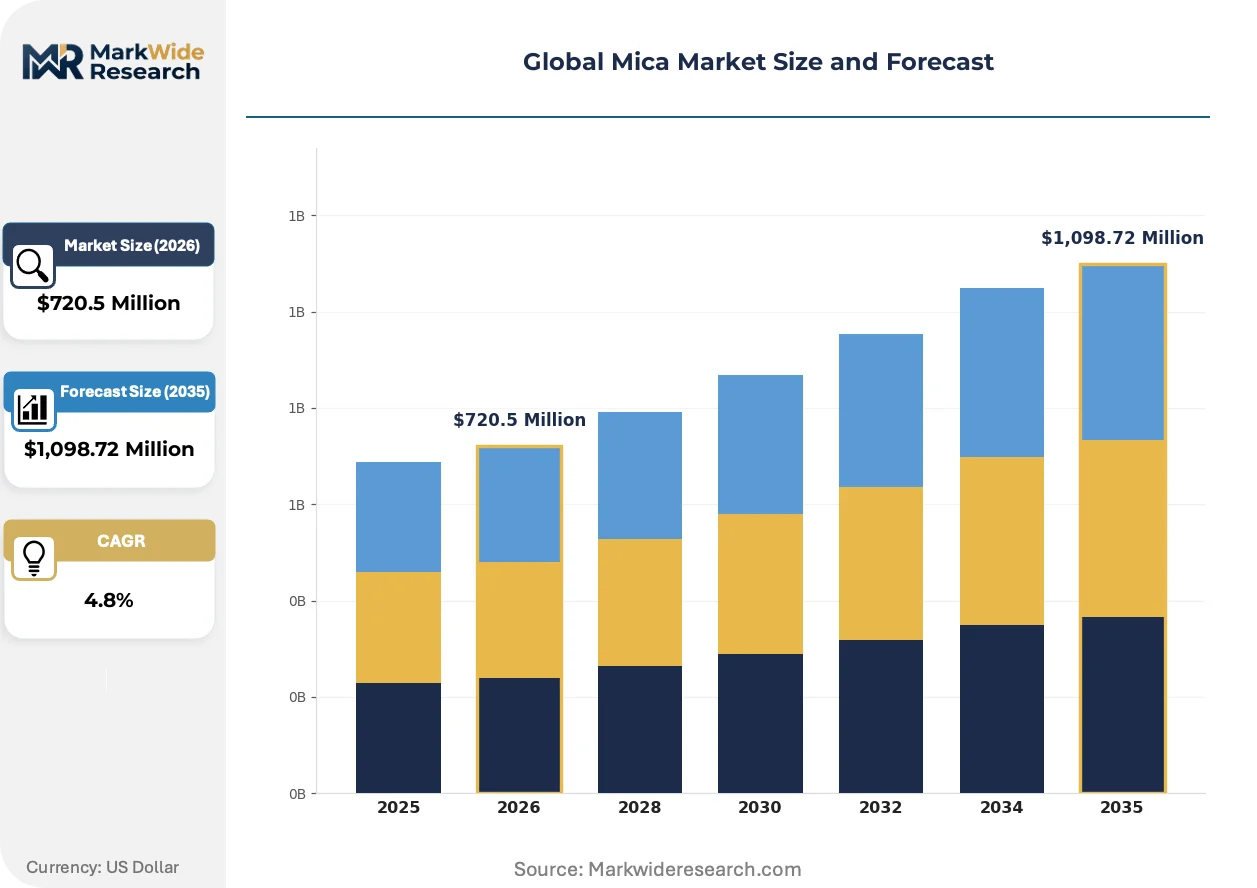
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,098.72 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Mica, Flake Mica, Ground Mica, Scrap Mica, Mica Powders Application: Electronics Insulation, Paints Coatings, Plastics Reinforcement, Rubber Additives, Drilling Fluids End User Industry: Construction Sector, Automotive Manufacturing, Cosmetics Production, Electrical Equipment, Oil Exploration Packaging Type: Bulk Bags, Paper Sacks, Plastic Bags, Fiber Drums, Cardboard Boxes |
| Companies Covered | BASF Catalysts, Franklin Industrial Minerals, Imerys SA, Daruka Minerals, Asheville-Schoonmaker Mica Company, Sibelco Group NV, Premier Mica Company, Shandong Jinhe Industrial Group Co., Ltd., Rio Tinto Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mica Market Strategic Shifts & Innovations
The mica industry is undergoing a significant formalization, driven by technological advancements in material science and a non-negotiable regulatory push for supply chain accountability. This shift prioritizes verifiable data and material purity over historical sourcing relationships, reshaping competitive dynamics.
Synthetic fluorphlogopite, a lab-grown material, provides exceptional purity and brightness for specialized applications. Cosmetics and automotive coatings manufacturers are increasingly specifying this material to eliminate supply chain uncertainties and ethical risks associated with natural mica. The adoption of synthetic mica is displacing a portion of the natural mica market, particularly in high-end segments where performance consistency is critical.
India's framework for mining laws, combined with state-level enforcement, directly governs extraction practices and environmental compliance for a large part of the global supply. These regulations impact everything from mine lease allocation to labor standards, forcing processors and exporters to maintain rigorous documentation. The cosmetics and pigments industries are most affected, often investing in local community programs and direct mine oversight to ensure compliance.
Buyer selection criteria are evolving from a pure cost-per-ton basis to a model emphasizing certified ethical production and transparent supply chains. This change disrupts traditional sourcing from aggregators, favoring direct relationships with suppliers who can provide auditable proof of compliance with standards like the Responsible Mica Initiative. This preference shift is most visible among publicly-traded consumer goods companies headquartered in North America and Europe.
Global Mica Market Segmentation
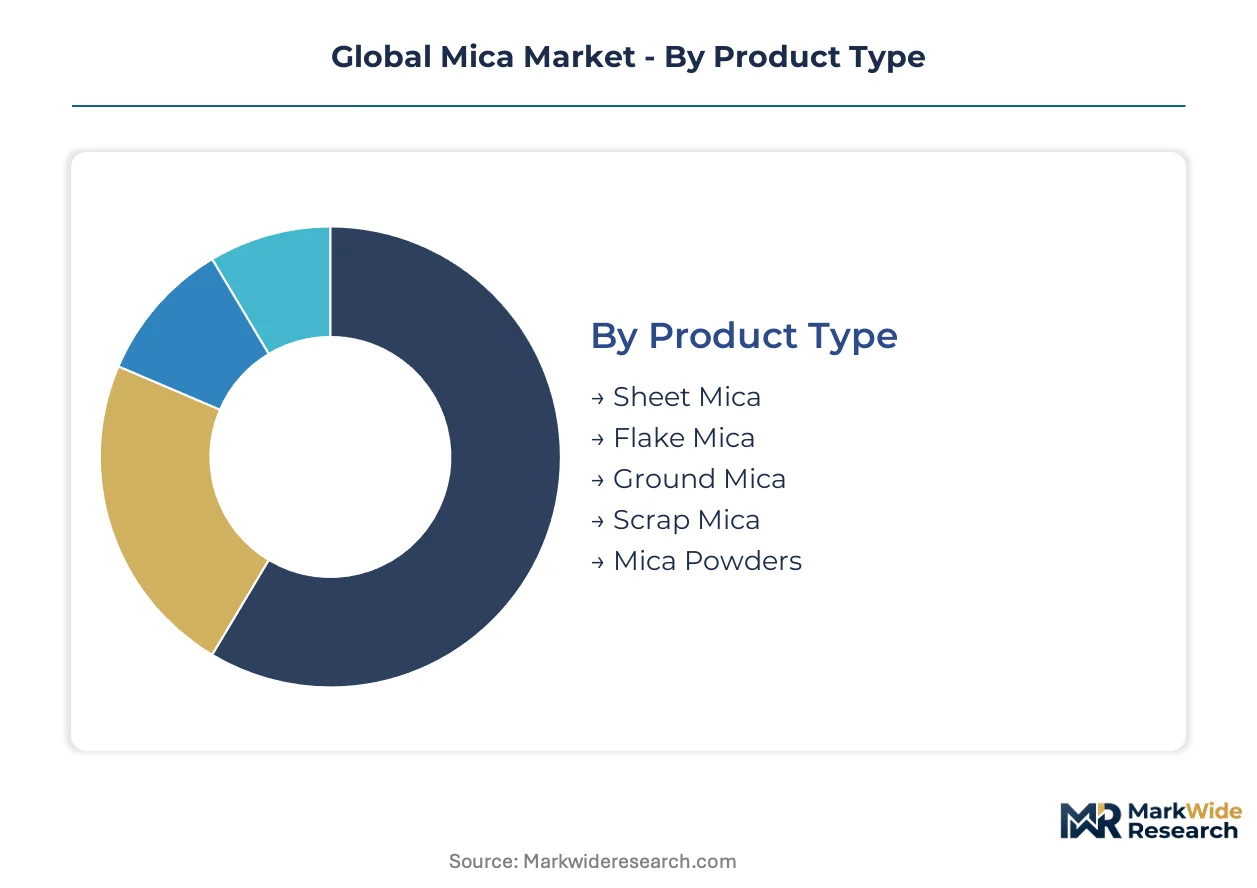
The global mica market is delineated by distinct product forms, varied applications, and diverse end-user industries. Understanding these segments clarifies the specific material properties driving demand and the varied compliance requirements across different value chains. Each segment presents unique challenges regarding supply chain transparency and ethical sourcing mandates.
Product Type:
Substitution pressure from synthetic alternatives impacts certain mica product types more significantly than others, particularly in high-purity applications. This dynamic influences pricing and market share across different forms of mica.
- Sheet Mica:Comprising thin, flexible laminae with exceptional dielectric strength, sheet mica is indispensable for high-voltage insulation in specialized electronics. Demand is sustained in specialized electronics and industrial equipment due to its thermal resistance in compact designs.
- Flake Mica:Small, irregular pieces, serving as raw material for ground mica and industrial fillers.
- Ground Mica:Mica processed into various mesh sizes, providing functional filler properties for paints and plastics. Its high volume demand comes from the automotive manufacturing sector for lightweighting and pearlescent paint applications.
- Scrap Mica:Irregular remnants from processing, a lower-cost input for grinding into powders.
- Mica Powders:Fine-grained mica used in cosmetics, pigments, and specialized coatings for pearlescent effects.
Ground Mica anchors the volume base while Sheet Mica gains share at the steepest rate.
Application:
The cost structure for mica varies significantly across applications, influenced by the purity requirements and processing demands of each end-use. High-performance applications typically command a premium for specialized mica grades.
- Electronics Insulation:Mica provides exceptional dielectric strength and thermal resistance, critical for insulating components in capacitors, circuit boards, and industrial electrical equipment. Miniaturization trends in consumer electronics sustain demand.
- Paints Coatings:Mica serves as a functional filler and pigment, imparting pearlescent effects and improving durability in automotive coatings and industrial paints. The automotive sector's demand for aesthetic finishes drives this application.
- Plastics Reinforcement:Mica flakes enhance mechanical properties and dimensional stability of plastics, especially in automotive components.
- Rubber Additives:Mica acts as reinforcing filler and anti-blocking agent, improving stiffness in rubber products.
- Drilling Fluids:Mica incorporated into drilling muds to prevent fluid loss in porous rock formations during oil exploration.
Supply concentration is most pronounced for electronics insulation grades, whereas paints and coatings applications draw from a broader range of mica sources.
End User Industry:
Volume consumption patterns for mica are dictated by the scale of industrial activity and the material's functional importance within each end-user industry. Certain sectors represent foundational demand for mica products.
- Construction Sector:Mica is utilized in gypsum boards, joint compounds, and roofing materials for its fire-retardant properties and improved workability. Its use enhances the durability and finish of various building products.
- Automotive Manufacturing:The automotive industry uses mica in lightweight plastics for vehicle components and pearlescent pigments for exterior paints. Demand is closely tied to vehicle production volumes and aesthetic trends.
- Cosmetics Production:Mica provides natural shimmer and pearlescent effect in makeup, personal care products, and nail polishes.
- Electrical Equipment:Mica's excellent insulating properties are essential for high-voltage capacitors, motors, and generators.
- Oil Exploration:Mica in drilling fluids helps seal porous formations and prevent fluid loss during extraction.
Automotive manufacturing represents a customer type with sophisticated technical requirements, while the construction sector prioritizes cost-effectiveness and bulk supply.
Packaging Type:
Packaging types often reflect the volume and value of the mica product, influencing storage, transport costs, and ultimately, supplier margins. Specialized packaging can command a premium for sensitive materials.
- Bulk Bags:These large, flexible containers are used for high-volume, cost-effective transport of ground mica and scrap mica for industrial applications. They optimize logistics for large-scale operations.
- Paper Sacks:Used for smaller quantities of ground or flake mica, offering cost-effective protection.
- Plastic Bags:Suitable for fine mica powders and smaller orders, providing moisture resistance and ease of handling.
- Fiber Drums:Robust and secure, fiber drums are preferred for high-purity mica, specialized grades, or materials requiring enhanced protection during transit. They are often used for cosmetic-grade mica.
- Cardboard Boxes:Employed for small quantities of processed mica or samples, offering light protection for finished product distribution.
Bulk bags represent a mature packaging solution for commodity grades, while fiber drums reflect the specialized requirements of high-value, niche mica products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's national and state-level mining laws significantly shape global mica extraction practices and environmental compliance. These regulations directly influence the supply chain for a substantial portion of the world's mica. The global market navigates diverse regional demands and regulatory landscapes, impacting sourcing strategies and operational costs across continents.
India
India's robust domestic demand for mica stems from its significant cosmetics and construction sectors. India's national and state-level mining laws critically impact extraction methods and labor practices. The Jharkhand and Bihar regions anchor primary mica extraction, influencing global supply dynamics and ethical sourcing initiatives.
United States
United States manufacturing sustains demand for mica in electronics insulation and automotive components. OSHA standards for worker dust exposure enforce stringent safety measures within mica processing facilities. North Carolina's industrial mineral processing centers contribute to domestic supply for specialized applications.
Germany
German automotive and electronics industries require mica for lightweight plastics and advanced insulation. The EU's REACH framework and CSRD compel verifiable ethical sourcing. Bavaria and Baden-Württemberg's automotive clusters drive demand for high-performance mica in vehicle coatings.
China
China's expansive electronics and construction sectors consume substantial mica for insulation and fillers. China's national environmental protection laws guide mineral processing and waste management. The Yangtze River Delta manufacturing hub utilizes mica extensively in consumer electronics and building materials.
Brazil
Brazil's construction sector and industrial paint manufacturers utilize mica as a functional filler. Brazil's National Mining Agency (ANM) regulates mineral extraction and responsible mining practices. Minas Gerais state offers potential for new, ethically certified mica mining operations.
Global Mica Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the global mica market. This tiered structure reflects varying capabilities in raw material control and processing sophistication. Strategic archetypes include large-scale mineral conglomerates, specialized high-purity processors, and regional suppliers focusing on specific applications. Dominant competitive moves involve strategic partnerships for supply chain transparency and geographic diversification of sourcing operations.
Within this tiered structure, companies like Imerys SA represent large-scale global mineral groups with extensive operational footprints. Franklin Industrial Minerals, a United States-based entity, exemplifies a significant reserve holder with domestic processing capabilities. Daruka Minerals, operating within India, occupies a position as a specialized high-purity processor, particularly for the demanding cosmetics industry. These players collectively anchor different segments of the value chain, from raw material extraction to high-value product supply.
| Leading Market Players |
|---|
| BASF Catalysts |
| Franklin Industrial Minerals |
| Imerys SA |
| Daruka Minerals |
| Asheville-Schoonmaker Mica Company |
| Sibelco Group NV |
| Premier Mica Company |
| Shandong Jinhe Industrial Group Co., Ltd. |
| Rio Tinto Group Limited |
| Others |
Cost & Logistics Intelligence
Synthetic fluorphlogopite's increasing adoption as a substitute simultaneously reshapes natural mica's supply geography and pricing economics, particularly for high-purity applications. This shift compels suppliers to differentiate through ethical sourcing and verifiable traceability, impacting market access and cost structures.
Pricing Analysis
Geographic price spreads for mica reflect varying extraction costs and regulatory compliance burdens across regions. The dominant pricing model combines contract-based long-term offtake for industrial grades with commodity spot pricing for scrap mica. Price differentiation stems from quality grade, ethical certification level, and geographic delivery costs. Pricing pressure stems from synthetic mica substitution in high-value segments like cosmetics and pearlescent pigments. The construction sector exhibits the highest price sensitivity, while electronics insulation applications demonstrate the least.
Supply Chain Analysis
Heavy reliance on India for sheet and scrap mica supply presents a significant chokepoint, creating single-source vulnerability. The global mica supply chain draws heavily from key producing regions like India, China, and Brazil. Raw material dependencies include the mica ore itself and various processing chemicals. Regulatory restrictions and labor issues in concentrated regions represent a structural risk. Distribution runs through a dual model, with direct relationships for ethically certified products and traditional aggregators for commodity mica grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global mica market exhibits a defensive moat, primarily due to the high switching costs associated with specialized applications like electronics insulation and advanced composites.
For Market Incumbents:Shield core market share by deepening vertical integration into certified mining operations outside traditional regions. Invest in ethical sourcing certifications and robust traceability systems to mitigate reputational risk from child labor allegations. Diversify mining operations geographically, establishing new capacity in regions like Brazil or Africa. This strategy counteracts synthetic mica substitution and strengthens supply chain resilience.
For New Entrants and Emerging Players:A service-layer gap exists in providing fully traceable, ethically sourced high-purity mica for consumer goods manufacturers. Target niche high-purity grades for cosmetics and advanced composite materials, where performance consistency and ethical certainty command a premium. Penetrate the market by offering direct relationships with auditable proof of compliance. A go-to-market angle focusing on transparent, verifiable ethical supply from diversified geographies will appeal to publicly-traded consumer brands.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-cap specialized processors capable of delivering high-purity, ethically certified mica. The long-term viability of the mica market rests on sustained demand for specialized electronics insulation and a premium for ethically sourced materials. Identify acquisition targets among vertically integrated high-purity processors or certified mining operations with diversified geographic footprints. The signal to watch is the increasing regulatory enforcement of supply chain due diligence across major consumer markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Certified Mines | Secures long-term supply of ethically sourced mica, reducing reliance on high-risk regions. |
| Green Manufacturing Transition | Enhances environmental compliance and meets growing demand for sustainable material inputs. |
| Long-term Supply Agreement with OEMs | Stabilizes demand and pricing for specialized mica grades in high-value applications. |
| Joint Venture for Traceability Technology | Improves supply chain transparency and compliance with ethical sourcing mandates. |
| Product Launch: Advanced Composite Grades | Captures new demand in aerospace and industrial applications requiring superior performance. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved discussions with mica producers, chemical engineers, procurement managers, and regulatory compliance officers across the value chain. Secondary sources included industry association reports, government mining statistics, company financial filings, and academic literature. This approach facilitated bottom-up and top-down triangulation of market data.
The forecast framework integrated historical data with future projections across the analysis window. The quantitative model segmented the market by product type, application, end-user industry, packaging type, and regional regulatory landscape. Compound annual growth rates were derived from an assessment of market drivers, restraints, and strategic opportunities. Key forecast inputs included global automotive production forecasts and electronics miniaturization trends.
Forecasts assume regulatory continuity in the EU, US, and India; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding economic stability and technological progression. Geopolitical instability, accelerated synthetic material adoption, or unforeseen supply chain disruptions represent specific risk factors. Practitioners should keep alternative scenarios live as ethical sourcing mandates and material science advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Post Consumer Recycled Bottles Market
Others
Cathode Battery Material Market
Others
Global Digital Market
Others
Cloud DVR Market
Others
Ultrasonic Flow Meter Market
Others
Food Technology Market
Others
Mobile Retina Services Market
Others
Bicycle Panniers Market
Others
Global Compact Wheel Loaders Market
Others
Wearable Translator Market
Others
Liquid Density Meters Market
Others
Europe Legal Services Market
Others
Convenience Stores Market
Others
Egg Market
Others
Magnesite Market
Others
Powder Coating Equipment Market