
 Liquid Density Meters Market | 2026-2036
Liquid Density Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Density Meters Market Outlook
Consolidation among multinational chemical producers is realigning procurement patterns for inline density instrumentation. Anton Paar GmbH leverages its Austrian manufacturing base to dominate vibrating U-tube supply for European pharmaceutical clients. Emerson Electric Co. sustains competitive positioning through its Rosemount division's integration with DeltaV distributed control systems. Yokogawa Electric Corporation anchors Asian petrochemical demand with density transmitters engineered for high-pressure refinery environments.
Liquid density meters are precision instruments that measure fluid mass per unit volume, typically achieving accuracies of 0.0001 g/cm³ in laboratory-grade vibrating U-tube designs and serving critical functions in process control, custody transfer, and formulation consistency. Online meters command the largest installed base across continuous chemical processing, while portable meters represent the fastest-expanding category as field calibration protocols tighten in food safety and environmental compliance regimes. Benchtop laboratory meters retain the highest margin pools due to pharmaceutical validation requirements and recurring consumables revenue.
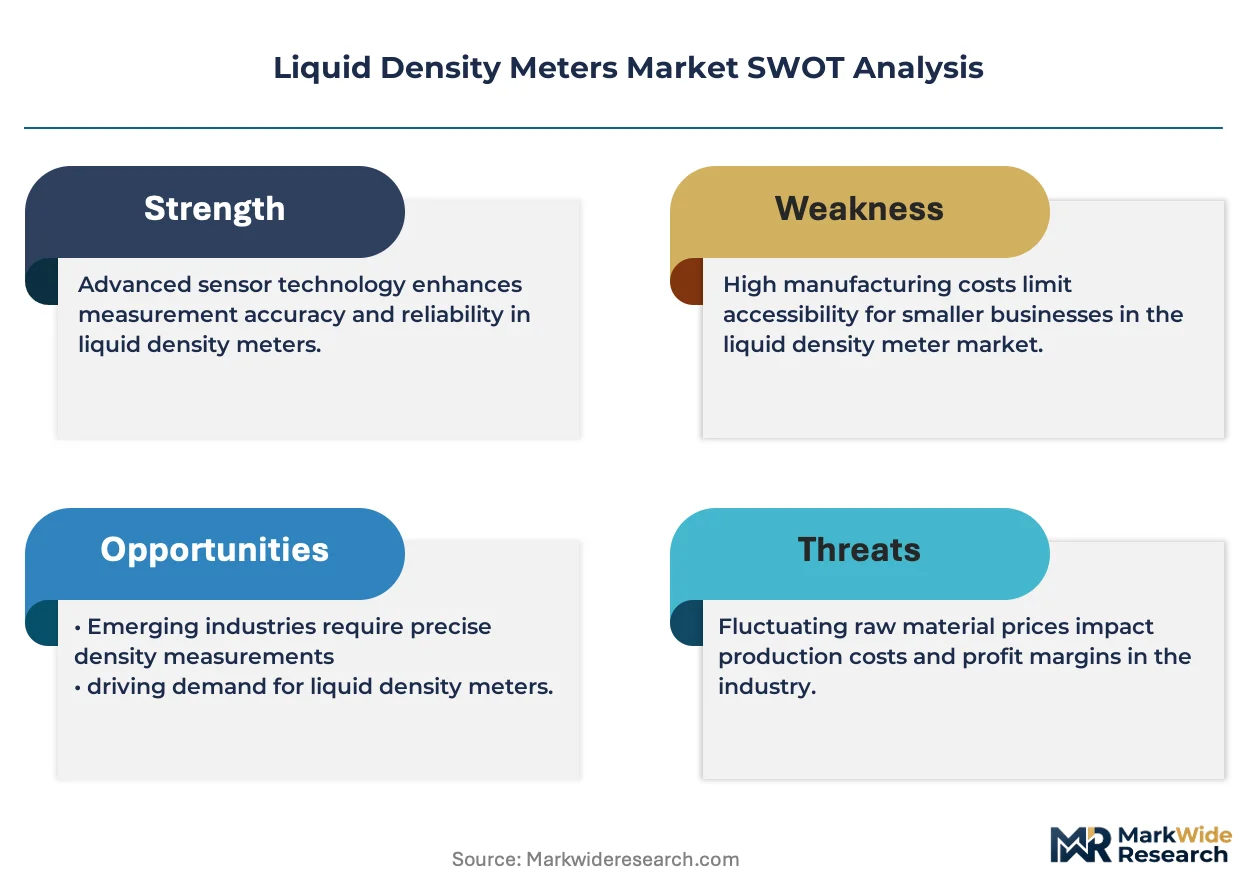
The US FDA mandates process analytical technology frameworks that elevate density monitoring to quality-critical status in drug manufacturing, while EPA discharge regulations enforce continuous effluent density tracking at chemical plants. REACH compliance in Europe restricts hazardous material contact in certain density sensor designs, redirecting R&D toward corrosion-resistant alloys and polymer-lined measurement cells. Stakeholders must weigh capital deployment between laboratory certification upgrades and inline retrofit opportunities as customer audit standards converge across pharmaceutical and food processing verticals.
Market Dynamics
Vibrating U-tube technology is consolidating process control architectures across petrochemical and pharmaceutical manufacturing, compressing calibration cycles and displacing hydrometer-based quality verification workflows.
Growth Catalysts
- FDA Process Analytical Technology:The US FDA mandates real-time density monitoring as quality-critical infrastructure in drug manufacturing, forcing continuous inline deployment across formulation suites.
- Inline retrofit programs:Petrochemical complexes on the US Gulf Coast are replacing batch sampling with continuous density verification to optimize yield and reduce laboratory turnaround.
- Corrosion-resistant alloys:REACH restrictions on hazardous material contact are redirecting sensor development toward polymer-lined measurement cells and specialty alloy construction.
Market Restraints
- Platinum sensor element volatility:Vibrating U-tube meters depend on precision-wound platinum temperature elements, exposing manufacturers to precious metal price swings and supply concentration in South African refining.
- Calibration infrastructure scarcity:Certified reference fluid laboratories remain concentrated in Germany, Switzerland, and the United States, creating logistics friction for Asian and Middle Eastern deployments.
- Optical refractometry substitution:Multi-parameter optical sensors are capturing share in beverage and sugar processing applications where density-refractive index correlation suffices.
Strategic Opportunities
- India specialty chemical expansion:CDSCO quality mandates and PLI scheme incentives are creating first-mover advantage for inline density instrumentation at contract manufacturing organizations.
- Digital twin integration:Density transmitter data streams are converging with predictive maintenance platforms, enabling subscription-based calibration and remote diagnostics revenue models.
- Cell therapy manufacturing:CGMP requirements for continuous bioprocessing are opening laboratory-grade vibrating U-tube demand in perfusion culture media monitoring.
Industry Challenges
- Metrology talent scarcity:Certified calibration technicians with ISO 17025 traceability expertise are concentrated in legacy industrial regions, constraining service network expansion.
- Legacy DCS integration complexity:Retrofitting digital density transmitters into analog-era distributed control systems requires custom signal conditioning and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Density Meters Market |
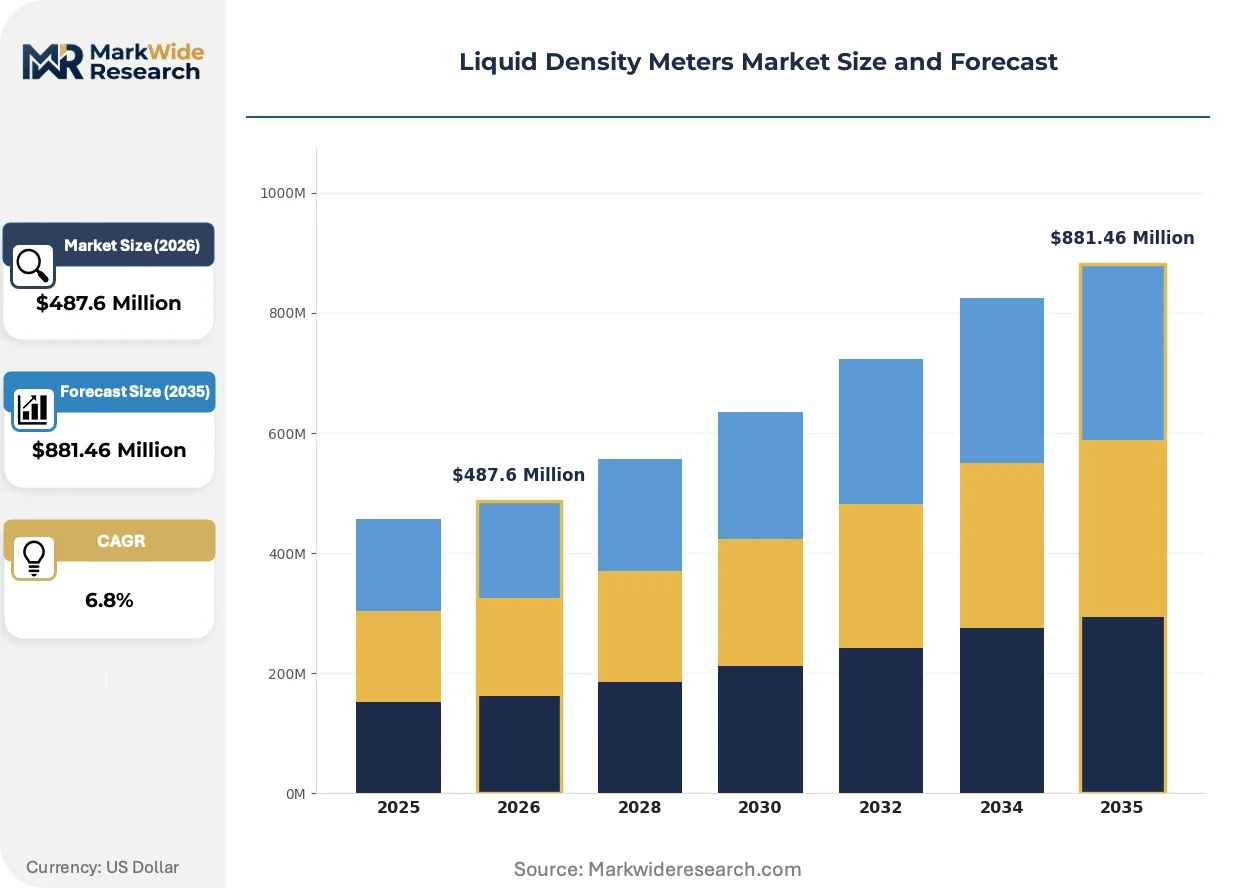
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Laboratory Meters, Online Meters, Benchtop Meters End User: Pharmaceuticals, Food & Beverage, Chemicals, Petrochemicals Technology: Hydrometer, Viscosity Meters, Ultrasonic Density Meters, Vibrating U-Tube Application: Quality Control, Process Monitoring, Research & Development, Environmental Testing |
| Companies Covered | Anton Paar GmbH, Mettler Toledo, Emerson Electric Co., Endress+Hauser Group Services AG, Yokogawa Electric Corporation, Thermo Fisher Scientific, Horiba Scientific, Berthold Technologies GmbH & Co. KG, Kyoto Electronics Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Density Meters Market Strategic Shifts
Measurement architectures are fragmenting between high-precision laboratory certification and ruggedized field deployment, with connectivity standards and service models diverging accordingly.
MEMS-based resonant density sensors are electrifying portable and handheld instrument categories, compressing form factors from benchtop units to smartphone-integrated probes. Food safety inspectors and environmental field teams are adopting these devices for rapid spot-checking without laboratory logistics. This electrification is collapsing the price-performance boundary between laboratory and field-grade instrumentation.
REACH substance restrictions are forcing material science pivots in European-manufactured density sensors, eliminating mercury-containing thermometers and certain epoxy potting compounds from sealed measurement cells. Chemical producers in Germany's Rhine corridor are demanding compliance documentation extending through Tier 3 suppliers. The restriction cascade is accelerating qualification programs for fluoropolymer-lined sensors in corrosive process streams.
Service unbundling is fragmenting traditional density meter procurement, with pharmaceutical buyers separating hardware acquisition from calibration contracts and software maintenance. Large molecule manufacturers are negotiating standalone validation protocols rather than accepting vendor-standard documentation. This pattern is most pronounced in Switzerland and the Netherlands, where centralized metrology services are displacing manufacturer-direct service agreements.
Liquid Density Meters Market Segmentation
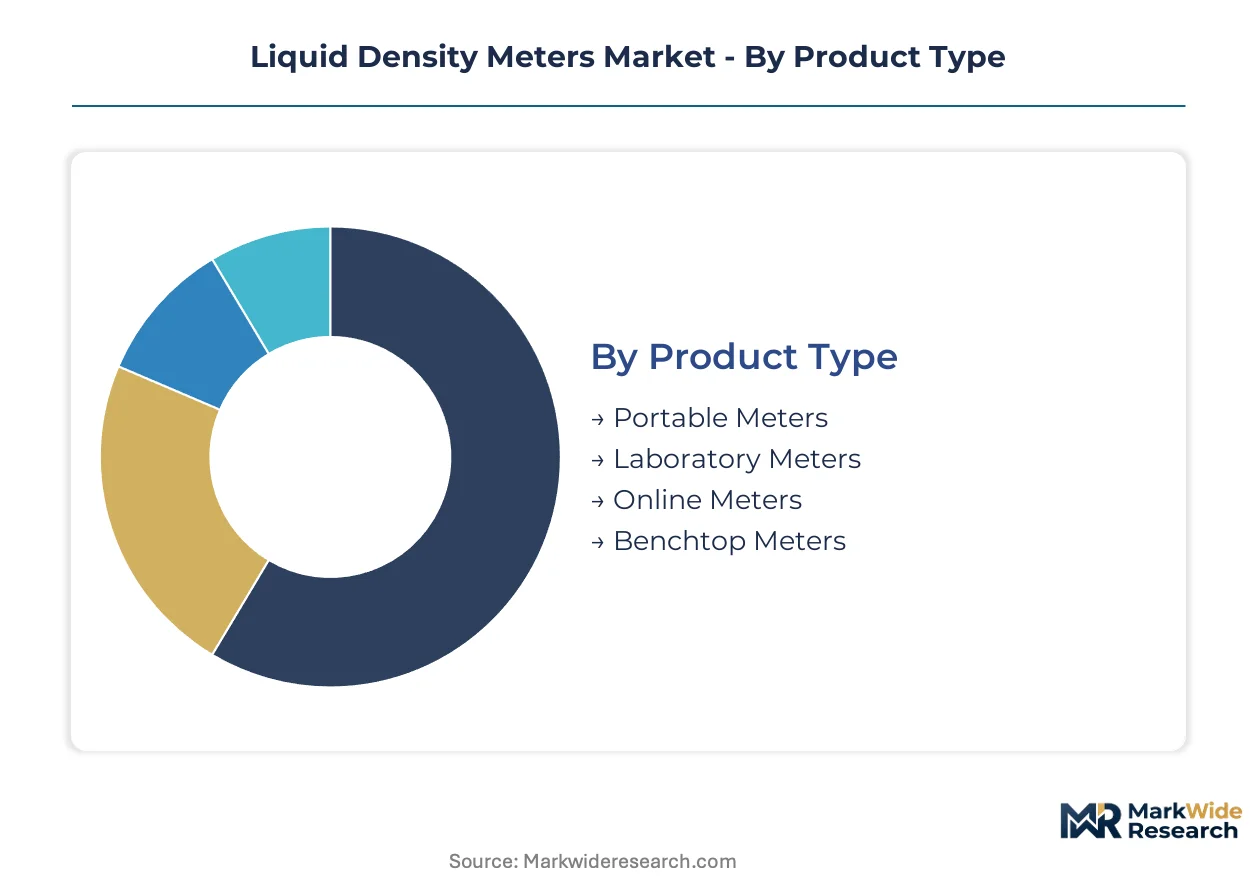
Liquid density meters fragment across four distinct classification axes that shape procurement workflows and margin structures differently. Product type determines the balance between capital intensity and service revenue, while technology choice locks customers into specific calibration infrastructures and regulatory compliance pathways.
Product Type:
Standalone instruments dominate laboratory and field deployments, whereas embedded sensors integrate directly into process control architectures with minimal operator intervention.
- Online Meters:Continuous measurement devices installed directly in process pipelines, achieving real-time density verification without sampling delays. Demand concentrates in US Gulf Coast petrochemical complexes where operators prioritize yield optimization over laboratory turnaround cycles.
- Portable Meters:Handheld or transportable units designed for field calibration and spot-checking protocols. Environmental compliance teams in Germany's chemical corridor are expanding deployments for rapid effluent verification at multiple discharge points.
- Laboratory Meters:High-precision instruments requiring controlled environmental conditions and certified reference fluids. Pharmaceutical quality control labs in Switzerland and the Netherlands specify these for validation-critical measurements.
- Benchtop Meters:Compact laboratory units optimized for routine analysis with moderate throughput requirements. Contract manufacturing organizations in India are standardizing on these for CDSCO-compliant documentation.
Volume placements concentrate in Online Meters; the faster expansion belongs to Portable Meters.
End User:
Regulatory stringency varies sharply across verticals, with pharmaceutical and food safety mandates demanding higher documentation burdens than industrial chemical applications.
- Petrochemicals:Refinery and upstream processing operations requiring corrosion-resistant designs for high-pressure hydrocarbon streams. Middle Eastern complexes are retrofitting inline density verification to replace manual sampling.
- Pharmaceuticals:Drug manufacturing facilities subject to FDA Process Analytical Technology mandates and EMA quality guidelines. Formulation suites in Ireland and Puerto Rico are upgrading to continuous density monitoring for real-time release.
- Chemicals:Diverse industrial producers spanning commodity and specialty chemicals with varying precision requirements. BASF and Lanxess facilities in Germany's Rhine corridor drive demand for process optimization instrumentation.
- Food & Beverage:Producers requiring hygiene-compliant designs for sugar concentration, alcohol content, and formulation consistency. Beverage processors are adopting multi-parameter optical alternatives where density-refractive index correlation suffices.
Revenue concentration sits with Petrochemicals; the steepest expansion trajectory is in Pharmaceuticals.
Technology:
Measurement principle selection determines accuracy ceilings, maintenance intervals, and compatibility with aggressive process chemistries.
- Vibrating U-Tube:Resonant frequency-based measurement achieving laboratory-grade precision through precision-wound platinum temperature compensation. Anton Paar GmbH dominates European pharmaceutical supply from its Austrian manufacturing base.
- Hydrometer:Traditional buoyancy-based methods experiencing displacement in regulated industries but retaining cost advantage in educational and non-critical applications. REACH restrictions on mercury thermometers are accelerating phase-out timelines.
- Ultrasonic Density Meters:Transit-time or Doppler-based measurement suitable for slurries and multiphase flows where mechanical resonance fails. Mining and wastewater applications in Australia favor these for abrasive media compatibility.
- Viscosity Meters:Combined density-viscosity instruments serving lubricant and polymer characterization needs. Rheology laboratories specify these for comprehensive fluid property mapping.
Installed base dominance belongs to Vibrating U-Tube; MEMS-based resonant alternatives are gaining share fastest in portable categories.
Application:
Workflow integration depth separates at-line quality verification from fully automated process control with closed-loop adjustment.
- Process Monitoring:Continuous measurement integrated with distributed control systems for real-time adjustment of temperature, pressure, or composition. Emerson Electric's Rosemount division anchors this segment through DeltaV system compatibility.
- Quality Control:At-line or laboratory verification ensuring batch release against specification limits. FDA validation requirements elevate this to quality-critical infrastructure in US drug manufacturing.
- Research & Development:Experimental characterization supporting formulation development and scale-up studies. Academic and corporate research centers prioritize flexibility over production-hardened specifications.
- Environmental Testing:Compliance monitoring of effluent density for discharge permit adherence. EPA enforcement is tightening continuous tracking requirements at chemical plants.
Deployment scale favors Process Monitoring; tightening field calibration protocols are expanding Quality Control most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical refineries on the US Gulf Coast and pharmaceutical quality control laboratories in Switzerland and the Netherlands concentrate the highest-value demand for precision density instrumentation. Process analytical technology mandates and tightening environmental discharge regulations are accelerating retrofit investments across these clusters.
United States
FDA Process Analytical Technology frameworks elevate density monitoring to quality-critical status in drug manufacturing, forcing continuous inline deployment across formulation suites. EPA discharge regulations enforce continuous effluent density tracking at chemical plants. Petrochemical complexes on the Gulf Coast are replacing batch sampling with continuous density verification to optimize yield and reduce laboratory turnaround.
Germany
REACH compliance restricts hazardous material contact in certain density sensor designs, redirecting R&D toward corrosion-resistant alloys and polymer-lined measurement cells. BASF and Lanxess facilities in the Rhine corridor require continuous density verification for process optimization. Chemical producers in this region are demanding compliance documentation extending through Tier 3 suppliers.
Switzerland
Swissmedic quality mandates and centralized metrology services are displacing manufacturer-direct service agreements in pharmaceutical quality control. Large molecule manufacturers negotiate standalone validation protocols rather than accepting vendor-standard documentation. Laboratory-grade vibrating U-tube demand concentrates in Basel and Zurich for validation-critical measurements.
India
CDSCO quality mandates and PLI scheme incentives create first-mover advantage for inline density instrumentation at contract manufacturing organizations. Specialty chemical expansion in Gujarat and Maharashtra is driving demand for benchtop laboratory meters for compliant documentation. CMOs in Hyderabad and Ahmedabad are standardizing on these instruments for regulatory submissions.
United Arab Emirates
Middle Eastern petrochemical complexes are expanding inline monitoring deployments to replace manual sampling workflows. MOHAP pharmaceutical regulations are beginning to mirror FDA process analytical technology frameworks. Refinery and upstream processing operations in the Jebel Ali corridor require corrosion-resistant designs for high-pressure hydrocarbon streams.
Liquid Density Meters Market Competitive Environment
European producers anchor the premium laboratory tier; Japanese and US specialists hold process control and field instrumentation positions. The vendor base organizes around three strategic archetypes: Austrian and Swiss precision instrument houses, diversified industrial automation conglomerates with sensing divisions, and specialized Asian component suppliers. Competitive moves concentrate on digital twin integration partnerships and service unbundling to capture recurring calibration revenue.
Within the precision instrument tier, Anton Paar GmbH and Mettler Toledo exemplify European laboratory-grade positioning through Austrian and Swiss manufacturing heritage. Emerson Electric Co. occupies the industrial automation integration vector through its Rosemount instrumentation division. Yokogawa Electric Corporation represents Asian process control specialization with density transmitters engineered for high-pressure refinery environments. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across laboratory certification, distributed control system compatibility, and ruggedized field deployment.
| Leading Market Players |
|---|
| Anton Paar GmbH |
| Mettler Toledo |
| Emerson Electric Co. |
| Endress+Hauser Group Services AG |
| Yokogawa Electric Corporation |
| Thermo Fisher Scientific |
| Horiba Scientific |
| Berthold Technologies GmbH & Co. KG |
| Kyoto Electronics Manufacturing Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
FDA Process Analytical Technology mandates for continuous inline density monitoring are forcing pharmaceutical buyers to prioritize ISO 17025-certified calibration infrastructure over unit cost, compelling suppliers to absorb Tier 3 compliance documentation costs and defend margin through service unbundling rather than hardware premiumization.
Pricing Analysis
Volume placements concentrate in online meters serving petrochemical yield optimization, while laboratory-grade vibrating U-tube instruments retain margin leadership through pharmaceutical validation requirements and recurring consumables revenue. Price differentiation hinges on certification tier (ISO 17025 vs. factory-standard traceability) and after-sales calibration bundling. Pricing pressure stems from MEMS-based resonant alternatives collapsing the price-performance boundary in portable categories. Contract manufacturing organizations in India exhibit the highest price sensitivity, whereas Swiss large-molecule manufacturers prioritize validation protocol autonomy over unit economics.
Supply Chain Analysis
Precision-wound platinum temperature element fabrication concentrates in Austria, Germany, and Switzerland, where metrology workforce density supports the tight tolerances required for laboratory-grade resonant frequency measurement. Manufacturing draws from South African platinum refining, fluoropolymer-lined cell components, and precision glass forming for U-tube resonators. Single-source vulnerability in certified reference fluid supply creates logistics friction for Asian deployments. Distribution runs through manufacturer-direct service agreements in Europe and system integrator channels in North American process control markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA Process Analytical Technology frameworks erect barrier-to-entry moats favoring incumbents with established ISO 17025 calibration networks and pharmaceutical validation documentation libraries.
For Market Incumbents: Acquire certified reference fluid laboratories in Germany and Switzerland to secure calibration infrastructure scarcity rents against emerging MEMS-based portable competitors. Deepen backward integration into corrosion-resistant alloy supply chains to offset REACH restriction compliance costs. Anchor positioning through captive validation protocol development for large-molecule manufacturers in Basel and Zurich. For New Entrants and Emerging Players: System integrators in India's Gujarat and Maharashtra chemical corridors offer the most penetrable channel for benchtop laboratory meter penetration under CDSCO quality mandates. Target contract manufacturing organizations seeking compliant documentation for regulatory submissions. Differentiate through standalone calibration contracts rather than bundled hardware-service pricing. For Investors and Strategic Acquirers: The window for entry favors precision instrument houses with existing pharmaceutical relationships and transferable metrology expertise. Long-term viability centers on recurring calibration revenue streams and digital twin integration capabilities. Watch for inflection where pharmaceutical buyers accelerate service unbundling negotiations in Switzerland and the Netherlands.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Acquisition | Captures ISO 17025 scarcity rents and anchors pharmaceutical customer retention. |
| Corrosion-Resistant Alloy Integration | Defends margin against REACH compliance cost pass-through in European manufacturing. |
| Digital Twin Platform Partnership | Enables subscription-based remote diagnostics with Emerson DeltaV system compatibility. |
| India CMO Channel Development | Secures first-mover positioning under CDSCO mandates and PLI scheme incentives. |
| MEMS Resonant Sensor R&D | Collapses portable category price floors and expands field calibration addressable market. |
Study Parameters
Independent corroboration across plant managers at BASF and Lanxess facilities, procurement leads at US Gulf Coast petrochemical complexes, and aftermarket service heads at European precision instrument houses underwrites the qualitative findings. Secondary validation draws from FDA 483 inspection observations, EMA quality guideline documentation, SEC 10-K instrument division disclosures, and customs data for vibrating U-tube component trade flows. Bottom-up demand modeling triangulates against top-down petrochemical capacity expansion announcements.
Comparable-period anchoring to historical inline instrumentation deployment cycles shapes the projection horizon across the analysis window. Segmentation dimensions span product type (online, portable, laboratory, benchtop), technology (vibrating U-tube, ultrasonic, hydrometer), end-use vertical (petrochemicals, pharmaceuticals, chemicals, food and beverage), and application depth (process monitoring, quality control, R&D, environmental testing). CAGRs derive from elasticity-adjusted replacement demand curves and greenfield capacity expansion schedules. Forecast inputs incorporate platinum price volatility assumptions and pharmaceutical audit standard convergence trajectories.
Caveats apply where platinum supply disruption from South African refining concentration or accelerated MEMS substitution in beverage processing could materially shift the outlook. Regulatory timeline uncertainty around EPA effluent enforcement and CDSCO inspectorate capacity expansion introduces revision risk. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Digital Thermal Plates Market
Others
Safety Instrumented System (SIS) Market
Others
Allogeneic Human Chondrocyte Market
Others
Solid White Films Market
Others
Global Webinar and Webcast Market
Others
Floor Cleaning and Mopping Machine Market
Others
Global Surface Analysis Market
Others
Mainframe Market
Others
Connected Homes Market
Others
Fresh Durian Market
Others
Digital Media Adaptor (DMA) Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Deflectometer Market
Others
Global Electronic Filters Market
Others
Channel-In-A-Box (Ciab) Market
Others
Dried Egg Market