
 Air Separation Unit Market | 2026-2036
Air Separation Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Air Separation Unit Market Analysis
Membrane materials are hardening cost advantages over traditional cryogenic systems in small-to-mid scale deployments. Linde Plc leverages its cryogenic heritage while extending into modular membrane units for remote industrial sites. Air Liquide S.A. anchors its position through backward integration into air separation catalyst manufacturing. Chart Industries specializes in brazed aluminum heat exchangers that dominate the cold box assembly layer.
An air separation unit fractionates atmospheric air into constituent gases—principally nitrogen, oxygen, and argon—through cryogenic distillation at temperatures below minus 180 degrees Celsius, yielding product purities exceeding 99.5 percent for industrial process feedstocks. Cryogenic systems command the largest installed base and margin pool due to unmatched throughput economics, while membrane technology captures the fastest expansion in mobile and offshore installations where footprint constraints override energy efficiency priorities. Vacuum pressure swing adsorption occupies a stable niche in healthcare oxygen concentrators and small-volume nitrogen generators.
EPA emissions guidelines and EU F-Gas Regulation constrain refrigerant selection and energy intensity in new cryogenic plant deployments, compressing payback thresholds for efficiency upgrades. China's MEE enforces dual carbon goals that redirect investment toward lower-carbon air separation architectures in steel and chemical clusters. Stakeholders must weigh stranded asset risk in legacy cryogenic infrastructure against the modular flexibility that membrane and adsorption systems offer for decentralized industrial gas supply.
Market Dynamics
Cryogenic distillation's energy intensity is forcing capital allocation toward modular alternatives as EU F-Gas Regulation and China's MEE dual carbon goals tighten compliance thresholds for new plant deployments.
Growth Catalysts
- Healthcare oxygen networks:Hospital infrastructure expansion across India and China is pulling small-scale VPSA units into secondary cities where cryogenic distribution economics fail.
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating cold box efficiency upgrades in European steel and chemical clusters.
- Membrane materials:Polymer hollow-fiber advances are capturing offshore platform and remote mining contracts where footprint constraints dominate.
Market Restraints
- Helium supply concentration:Cryogenic plant cooling depends on helium sourcing concentrated in Qatar and the United States, exposing project timelines to export quota volatility.
- Electricity cost structure:Cryogenic distillation consumes 0.5-0.6 kWh per cubic meter of oxygen, compressing margins in markets with industrial tariff escalation.
- Steel substitution:Electric arc furnace expansion in scrap-rich regions is displacing basic oxygen furnace gas demand that historically anchored large cryogenic contracts.
Strategic Opportunities
- Green hydrogen integration:Electrolyzer projects require nitrogen for inerting and oxygen for oxy-combustion, creating bundled gas offtake contracts.
- Carbon capture retrofits:Post-combustion capture at ammonia and ethanol plants demands high-purity oxygen, opening membrane-VPSA hybrid architectures.
- India PLI scheme:Production-linked incentives for specialty chemicals and pharmaceuticals are triggering captive air separation investments in Gujarat and Maharashtra clusters.
Industry Challenges
- Cryogenic welder scarcity:Stainless steel and aluminum welding for cold box fabrication faces a generational skills gap across European and North American contractor pools.
- Legacy DCS integration:Brownfield sites running 1990s distributed control systems require costly protocol bridging to implement predictive maintenance analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Separation Unit Market |
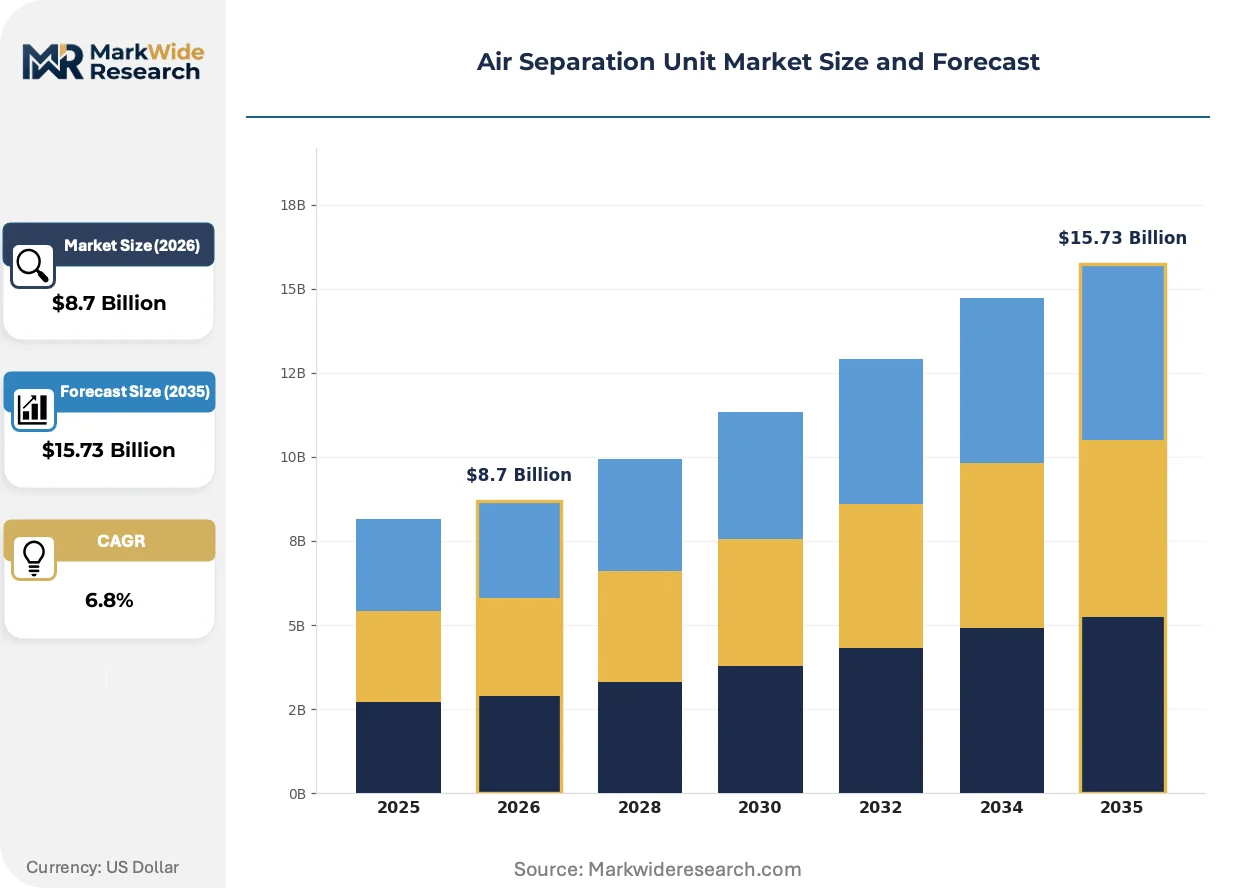
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cryogenic, Membrane, Vacuum Pressure Swing Adsorption, Physisorption Application: Oxygen Production, Nitrogen Production, Argon Production, Industrial Gases End User: Metallurgy, Oil & Gas, Healthcare, Electronics Installation: Onshore, Offshore, Mobile, Stationary |
| Companies Covered | Linde Plc, Air Liquide S.A., Air Products and Chemicals Inc., Taiyo Nippon Sanso Corporation, Messer Group GmbH, Praxair Technology Inc., Universal Industrial Gases Inc., SIAD Macchine Impianti S.p.A., Chart Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Separation Unit Market Emerging Trajectories
Technology convergence between cryogenic heritage and membrane modularity is fragmenting the traditional single-technology procurement model. Regulatory energy-intensity benchmarks are reshaping plant architecture decisions. Demand patterns are rotating toward decentralized supply chains.
Membrane-based nitrogen generation is expanding into floating LNG pre-treatment and subsea pipeline inerting where deck space and weight limits exclude cryogenic hardware. Offshore engineering contractors are specifying polymer hollow-fiber skids with 40-foot container footprints. This technology is expanding into applications previously reserved for liquid nitrogen bulk delivery, compressing the addressable market for small-scale cryogenic plants.
China's MEE dual carbon enforcement is mandating energy-efficiency disclosures for air separation units above 10,000 Nm³/h capacity in steel and chemical parks. Plants must document specific power consumption per unit gas output or face production quota restrictions. State-owned enterprise procurement committees are now weighting lifecycle carbon intensity equally with capital cost in tender evaluations.
Industrial gas buyers are unbundling long-term take-or-pay contracts into separate equipment lease, maintenance, and molecule supply agreements. Large chemical producers in Germany and the Netherlands are negotiating power purchase agreements directly with renewable developers to supply captive air separation, bypassing traditional utility-tied merchant gas contracts. This procurement restructuring is most advanced in markets with liquid wholesale electricity trading.
Air Separation Unit Market Segmentation
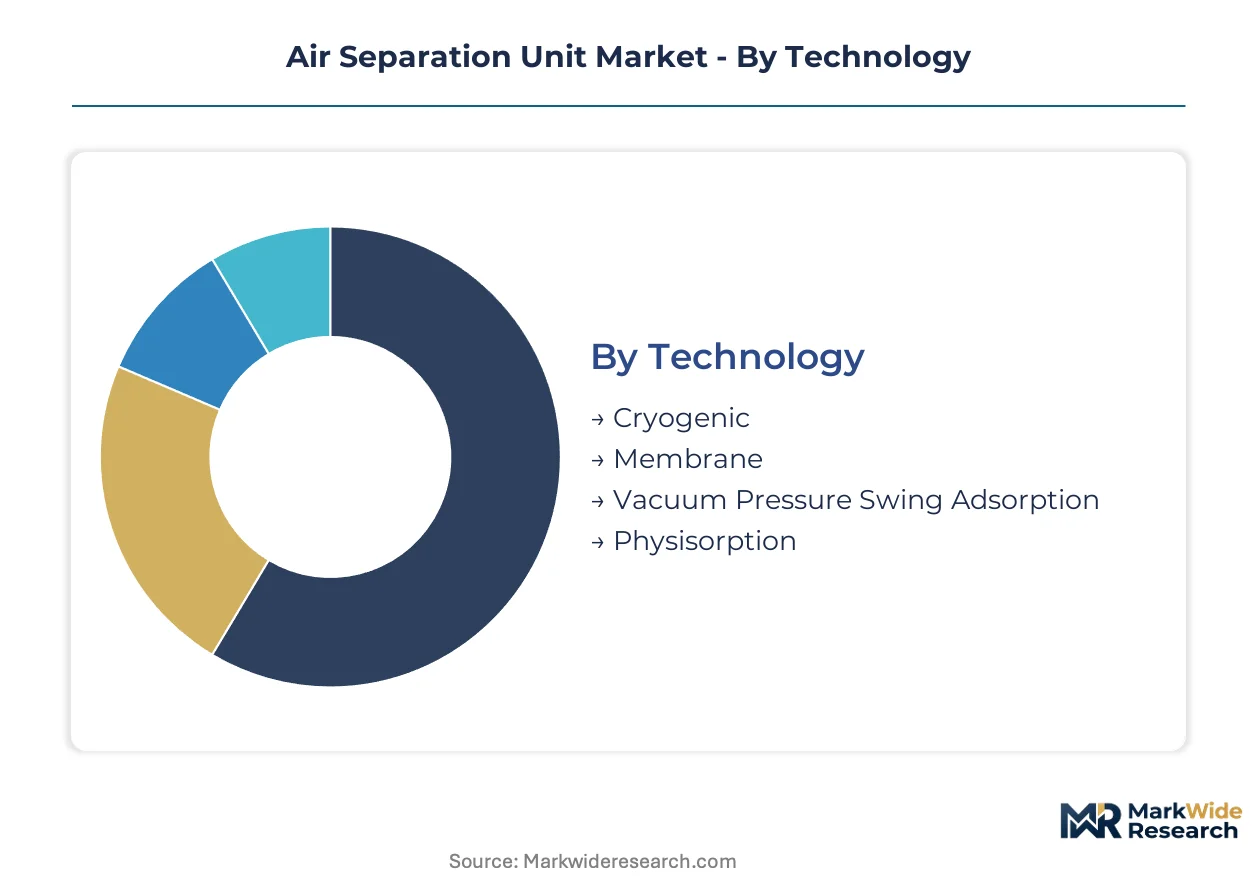
Technology choice in air separation units determines capital intensity, energy consumption, and operational flexibility across industrial gas supply chains. Buyer procurement committees weight lifecycle cost against purity requirements and footprint constraints when selecting system architecture. Segment boundaries are blurring as hybrid configurations emerge for carbon capture and hydrogen integration applications.
Technology:
Capital efficiency and energy cost exposure dominate technology selection for industrial gas buyers.
- Cryogenic:Fractionates atmospheric air through distillation at sub-minus-180°C temperatures, achieving 99.5%+ purity for nitrogen, oxygen, and argon simultaneously. Steel and chemical clusters in Germany and China specify cryogenic trains above 10,000 Nm³/h capacity where throughput economics override electricity intensity concerns under EU F-Gas Regulation and MEE dual carbon enforcement.
- Membrane:Polymer hollow-fiber modules separate gases by selective permeation, sacrificing purity for modularity and reduced footprint. Floating LNG pre-treatment and offshore platform contracts in the North Sea and Gulf of Mexico favor membrane skids where deck space constraints and weight limits exclude cryogenic hardware.
- Vacuum Pressure Swing Adsorption:Cyclic adsorption-desorption on zeolite or carbon molecular sieves delivers oxygen or nitrogen at moderate purity. Hospital networks across India deploy VPSA units for captive oxygen generation where cryogenic liquid distribution economics fail in secondary cities.
- Physisorption:Surface-based gas separation using porous materials at near-ambient temperatures. Emerging deployments target small-scale argon recovery and helium purification in specialty gas applications.
Cryogenic leads on scale; membrane leads on momentum.
Application:
End-use purity specifications and volume requirements fragment procurement patterns across industrial sectors.
- Oxygen Production:Steel basic oxygen furnaces, medical therapy, and oxy-combustion for carbon capture drive demand. China's steel sector accounts for the largest oxygen offtake under MEE production quota systems.
- Nitrogen Production:Inerting, blanketing, and purge applications dominate chemical and electronics manufacturing. Electronics fabs in South Korea and Taiwan specify ultra-high-purity nitrogen for semiconductor wafer processing.
- Argon Production:Tungsten inert gas welding and silicon crystal growing consume argon as a byproduct of cryogenic air separation. Argon recovery rates constrain project economics in smaller-scale deployments.
- Industrial Gases:Bundled supply contracts covering multiple molecules for integrated chemical complexes. Green hydrogen electrolyzer projects are creating new bundled offtake structures combining nitrogen for inerting with oxygen for process use.
Oxygen captures volume concentration; industrial gases bundles are climbing the fastest.
End User:
Process integration depth and gas purity requirements vary sharply across buyer industries.
- Metallurgy:Basic oxygen furnaces and electric arc operations consume oxygen for steel refining. Scrap-rich regions transitioning to electric arc technology are displacing legacy cryogenic contracts tied to basic oxygen furnace demand.
- Oil & Gas:Enhanced oil recovery, LNG inerting, and refinery hydrogen production require nitrogen and oxygen. Offshore platform specifications favor membrane systems for nitrogen generation where logistics constrain liquid bulk delivery.
- Healthcare:Hospital oxygen networks and home concentrators drive VPSA deployment. India's hospital infrastructure expansion is pulling small-scale units into tier-2 and tier-3 cities.
- Electronics:Semiconductor and display manufacturing demand ultra-high-purity nitrogen and argon. Fabs in South Korea and Japan specify contaminant levels below one part per billion for critical process steps.
Metallurgy anchors installed base; electronics commands premium pricing.
Installation:
Logistics constraints and operational mobility requirements determine site configuration.
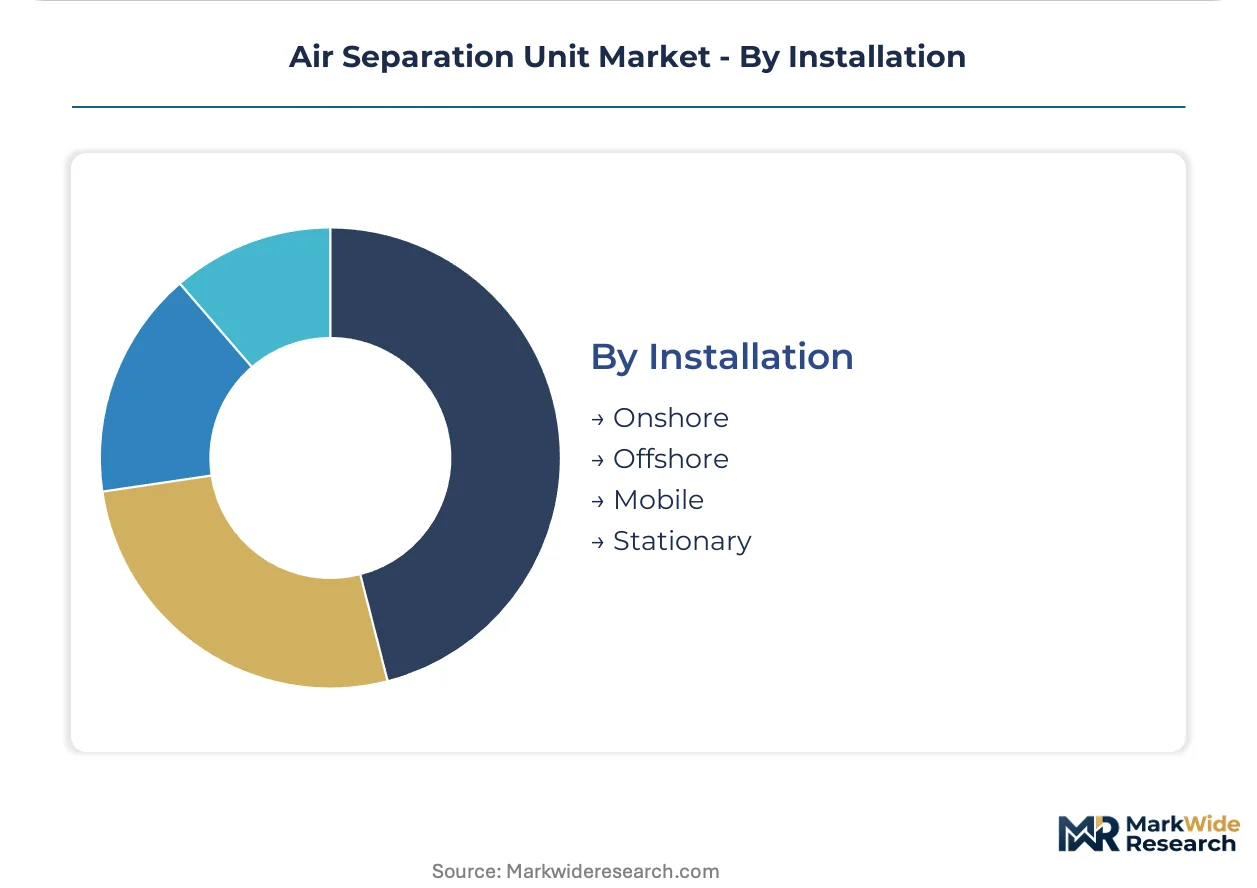
- Onshore:Permanent industrial gas plants integrated with steel, chemical, or refining complexes. German and Dutch chemical producers are negotiating renewable power purchase agreements for captive onshore supply.
- Offshore:Platform-based nitrogen generation for well intervention and pipeline inerting. North Sea contractors specify containerized membrane skids with 40-foot footprints.
- Mobile:Trailer-mounted units for temporary industrial gas supply and emergency response. Mining operations in remote regions deploy mobile VPSA systems where infrastructure is absent.
- Stationary:Fixed-site installations with decades-long operational horizons. Brownfield stationary assets face stranded asset risk as efficiency regulations tighten.
Onshore dominates capital deployment; offshore is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta steel and chemical corridor drives the dominant share of global air separation capacity investment, with state-owned enterprise procurement committees now weighting lifecycle carbon intensity equally with capital cost in tender evaluations.
China
Steel sector oxygen demand under MEE production quota systems anchors the largest cryogenic train deployments. The MEE dual carbon enforcement mandates energy-efficiency disclosures for units above 10,000 Nm³/h capacity. Jiangsu and Shandong provinces concentrate new captive investments as chemical parks consolidate under environmental compliance pressure.
Germany
Basic oxygen furnace gas demand in the Ruhr industrial belt sustains large cryogenic contracts despite electric arc transition in scrap-rich regions. The EU F-Gas Regulation accelerates cold box efficiency upgrades with refrigerant phase-down mandates. Chemical producers in North Rhine-Westphalia negotiate renewable power purchase agreements for captive supply, bypassing traditional merchant gas contracts.
United States
Shale gas processing and hydrogen hub development pull nitrogen and oxygen demand across Gulf Coast petrochemical complexes. EPA emissions guidelines constrain refrigerant selection for new cryogenic plant deployments. The Permian Basin and Appalachia clusters see membrane system adoption where logistics constrain liquid bulk delivery to remote well sites.
India
Hospital infrastructure expansion across tier-2 and tier-3 cities deploys small-scale VPSA units where cryogenic liquid distribution economics fail. The PLI scheme for specialty chemicals and pharmaceuticals triggers captive air separation investments in Gujarat and Maharashtra clusters. Mumbai-Pune industrial corridor leads private capital deployment for on-site gas generation.
Japan
Semiconductor and display manufacturing in Kyushu and Kansai regions demand ultra-high-purity nitrogen with contaminant levels below one part per billion. METI industrial gas efficiency standards tighten operational benchmarks for existing cryogenic assets. Osaka-Tokyo electronics corridor sustains premium pricing for argon and specialty gas recovery systems.
Air Separation Unit Market Vendor Landscape
Global majors compete with regional champions across technology heritage and modular system deployment. The vendor base separates into three tiers: integrated industrial gas conglomerates with cryogenic distillation legacies, mid-scale membrane specialists capturing offshore and remote contracts, and national champions serving protected domestic markets. Strategic differentiation concentrates on backward integration into catalyst and heat exchanger manufacturing, and on geographic expansion through equipment lease-to-own structures rather than molecule supply contracts.
Within the integrated industrial gas tier, Linde Plc and Air Liquide S.A. occupy positions defined by cryogenic heritage extending into modular membrane architectures. Chart Industries exemplifies the component-specialist archetype, anchoring supply relationships through dominance in brazed aluminum heat exchanger fabrication for cold box assemblies. These three entities represent the spectrum from full-system integration through critical subsystem supply.
| Leading Market Players |
|---|
| Linde Plc |
| Air Liquide S.A. |
| Air Products and Chemicals Inc. |
| Taiyo Nippon Sanso Corporation |
| Messer Group GmbH |
| Praxair Technology Inc. |
| Universal Industrial Gases Inc. |
| SIAD Macchine Impianti S.p.A. |
| Chart Industries |
| Others |
Supply Flow & Price Mechanics
Aluminum alloy price indices cascade through brazed heat exchanger fabrication costs into three distinct procurement tiers for cold box assemblies, with cryogenic train buyers absorbing premium volatility while membrane system purchasers lock in polymer hollow-fiber contracts at fixed conversion spreads.
Pricing Analysis
Input-cost pass-through from electricity tariffs and helium spot markets governs contract structures across the industry. Long-term take-or-pay agreements with steel and chemical clusters dominate the cryogenic segment, while equipment lease-to-own structures separate molecule supply from hardware ownership. Price differentiation separates ultra-high-purity argon recovery systems for semiconductor fabs from standard nitrogen generators for chemical inerting. Cost compression in small-scale VPSA units is intensifying because hospital procurement committees in India and China are consolidating supplier panels. Steel basic oxygen furnace operators show least price sensitivity due to process-critical oxygen requirements, whereas remote mining contractors exhibit highest sensitivity to delivered gas costs.
Supply Chain Analysis
Cryogenic welder availability constraints in Germany and the United States are extending cold box fabrication lead times and compressing contractor margins. Supply concentration centers on China for brazed aluminum heat exchangers, Germany for precision valve assemblies, and Qatar for helium refrigeration cycles. Raw material dependencies span nickel-based superalloys for cryogenic piping, polymer resins for membrane hollow fibers, and zeolite molecular sieves for adsorption systems. Single-source vulnerability in helium sourcing from Qatar and the United States exposes project timelines to export quota volatility. Distribution runs through industrial gas majors with captive logistics networks for liquid bulk delivery, supplemented by regional equipment lessors for on-site generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on membrane materials cost-down curves and the premium-tier shift toward ultra-high-purity argon recovery for semiconductor manufacturing.
For Market Incumbents: Lock in backward integration into catalyst and heat exchanger manufacturing to defend against membrane specialists encroaching on remote industrial contracts. Deepen service bundling through predictive maintenance analytics to raise switching costs for steel and chemical cluster buyers. Prioritize cold box efficiency upgrade programs in European installations facing EU F-Gas Regulation refrigerant phase-down deadlines. For New Entrants and Emerging Players: Offshore engineering contractors represent the most penetrable channel partner type for containerized membrane nitrogen skids with 40-foot footprints. Target floating LNG pre-treatment and subsea pipeline inerting contracts where deck space constraints exclude legacy cryogenic hardware. Pursue lease-to-own equipment structures rather than molecule supply agreements to bypass incumbent logistics advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with component-specialist firms dominating brazed aluminum heat exchanger fabrication for cold box assemblies. Long-term viability over the next decade hinges on positioning for green hydrogen electrolyzer bundled gas offtake contracts combining nitrogen inerting with oxygen process supply. Watch membrane-VPSA hybrid architecture adoption rates at carbon capture retrofit projects as the inflection indicator for technology convergence timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Manufacturing | Air Liquide's captive supply of adsorption materials reduces input cost volatility for VPSA system deployments. |
| Membrane System Modularization | Linde's containerized nitrogen skids capture offshore platform contracts where logistics constrain liquid bulk delivery. |
| Renewable Power Purchase Agreements | German chemical producers bypass traditional merchant gas contracts through direct renewable supply for captive generation. |
| Cold Box Efficiency Upgrades | EU F-Gas Regulation refrigerant phase-down mandates accelerate retrofit investments in European steel clusters. |
| Helium Supply Diversification | Chart Industries reduces Qatar concentration risk through United States sourcing partnerships for cryogenic plant cooling cycles. |
Methodological Framework
Bottom-up steel and chemical sector modeling reconciled against top-down cryogenic train capacity tracking forms the analytical core of this study. Primary interviews with plant engineers at basic oxygen furnace operations, procurement leads at semiconductor fabs, and aftermarket service heads at industrial gas majors combined with secondary validation from customs trade data, SEC filings of listed equipment manufacturers, and MEE energy-efficiency disclosure databases. Triangulation across stakeholder inputs and documentary sources ensures coverage of both disclosed capacity investments and unreported captive installations.
Historical trendline analysis of specific power consumption metrics and capacity utilization rates established baseline trajectories across the projection horizon. Segmentation modeling spans technology architecture, gas purity tier, end-use industry, and regional regulatory framework. CAGRs were derived through regression analysis of installed base expansion against industrial production indices and healthcare infrastructure investment cycles. Forecast inputs incorporate MEE dual carbon enforcement timelines and EU F-Gas Regulation implementation phases.
Revisions become necessary when helium export quota restrictions, electricity tariff restructuring, or steel sector technology substitution toward electric arc furnaces materialize at scales exceeding modeled thresholds. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and industrial gas buyer contract unbundling velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Industrial Hooters Market
Others
Technical Films Market
Others
Rugged Devices Market
Others
Asia-Pacific Medical Simulation Market
Others
Gas Holders Market
Others
Global Solder Balls Market
Others
Military Sensors Market
Others
Synthetic Leather Market
Others
North America Compressor Oil Market
Others
Profilometer Market
Others
Global Cosmetovigilance Market
Others
Digital Education Projector Market
Others
Japan Coal Market
Others
Durian Market
Others
Qatar Smartphone Market
Others
Hearables Market