
 Global Personal Care Packaging Market | 2026-2036
Global Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Care Packaging Market Intelligence
Airless and premium dispensing specifications are redrawing competitive boundaries in personal care packaging. Amcor plc leverages its global film extrusion network to supply multi-layer barrier solutions for sensitive formulations. Albea Group anchors European tube production with dedicated manufacturing in France and Poland. AptarGroup, Inc. dominates precision pump and closure technologies for fragrance and skincare applications.
Personal care packaging encompasses primary and secondary containment systems engineered from plastics, glass, aluminum, paperboard, biodegradable polymers, and metalized films, designed to protect product integrity, enable controlled dispensing, and communicate brand identity at point of sale. Mono-material polyethylene tubes and polypropylene pumps now lead material innovation streams as recyclability becomes a functional specification rather than a marketing attribute. Glass bottles and jars retain margin concentration in prestige fragrance and premium skincare segments where weight and optical clarity signal quality. Sachets and flexible formats compete aggressively in emerging-market hair care and bath categories where unit economics favor low-cost, single-use distribution.
EU REACH and the F-Gas Regulation constrain certain polymer additives and propellant systems used in aerosol dispensers across European supply chains. FDA cosmetic labeling requirements and EPA guidance on recycled content claims shape formulation-to-package compatibility testing in the United States. China's SAMR enforces GB standards for cosmetic packaging safety and migration limits that directly affect imported and domestically produced containers. Stakeholders must monitor how diverging extended producer responsibility schemes across Germany, France, and California reshape cost allocation between brand owners and packaging converters.
Market Dynamics
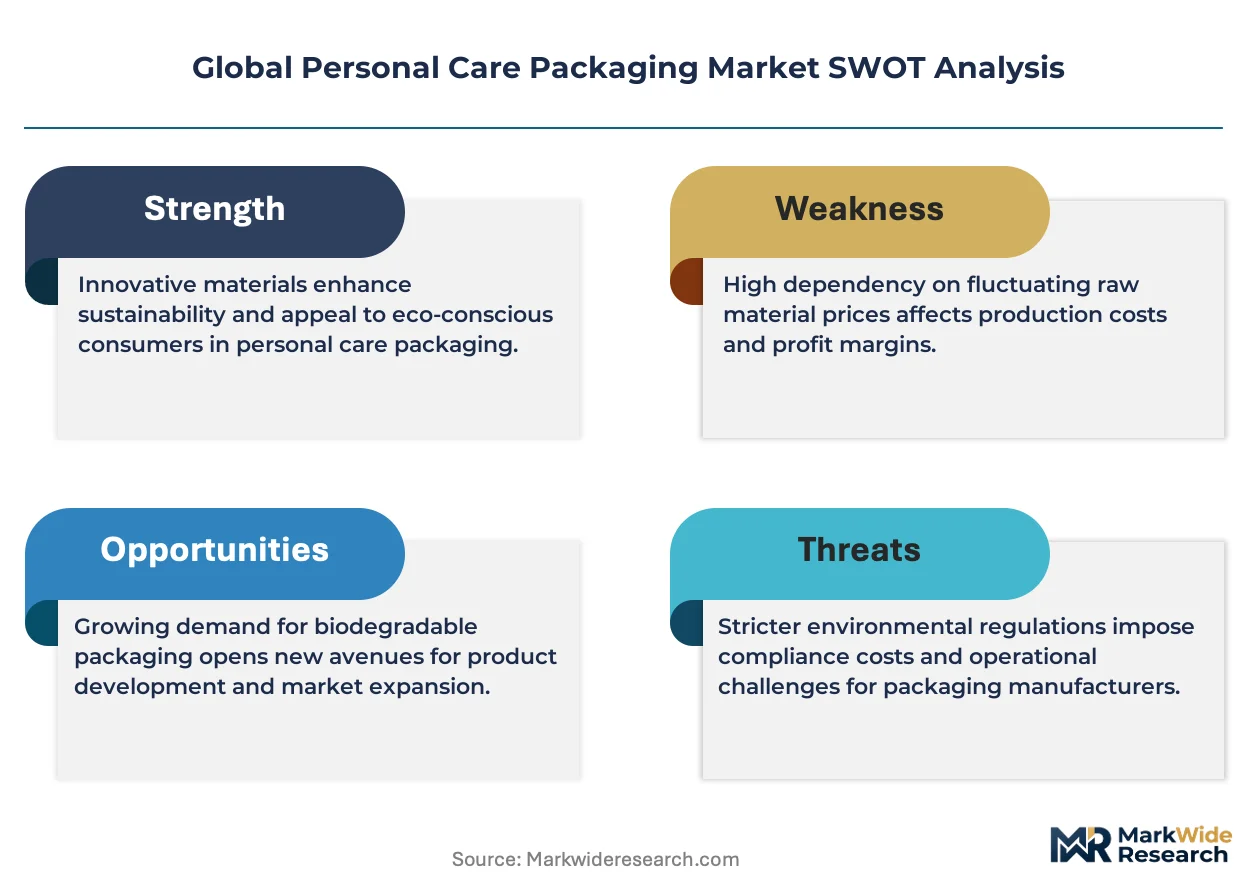
Extended producer responsibility mandates across Germany, France, and California are forcing brand owners to internalize end-of-life packaging costs, converting recyclability from a voluntary design preference into a compliance-driven engineering specification.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon propellants accelerate investment in mechanical pump alternatives and compressed air dispensing systems for aerosol-dependent categories.
- Refillable format adoption:Skincare and fragrance houses in Paris and New York specify mono-material pump mechanisms and aluminum-free tubes to meet internal sustainability targets ahead of regulatory deadlines.
- India's expanding middle-class consumption:Urban households in Mumbai and Delhi pull premium tube and pump demand toward domestic manufacturing clusters in Gujarat and Maharashtra.
Market Restraints
- Polypropylene resin volatility:Feedstock cost swings tied to naphtha cracking margins compress converter profitability on fixed-price annual contracts with multinational beauty brands.
- Barrier film supply concentration:Multi-layer coextrusion capacity clusters among a limited set of European and Japanese equipment operators, creating allocation risk during demand surges.
- Technical limitation in mono-material barriers:Current polyethylene and polypropylene structures struggle to match the oxygen and UV protection of legacy nylon-EVOH laminates for retinol and vitamin C formulations.
Strategic Opportunities
- Brazil's underserved premium segment:São Paulo-based beauty brands lack local access to airless pump manufacturing, creating import substitution potential for regional converters.
- China dual carbon policy alignment:SAMR's GB standards for reduced packaging weight and recycled content create first-mover advantage for converters with verified post-consumer feedstock chains.
- Direct-to-consumer channel expansion:Subscription box fulfillment requirements for damage-resistant, lightweight formats favor flexible pouch and tube innovations over rigid glass.
Industry Challenges
- Multi-material separation expertise:Converters lack sufficient polymer chemists and recycling process engineers to redesign legacy barrier structures within compressed brand timelines.
- Capex intensity for EPR compliance:In-house sorting and washing equipment for post-industrial scrap recovery demands capital deployment that mid-tier converters cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Care Packaging Market |
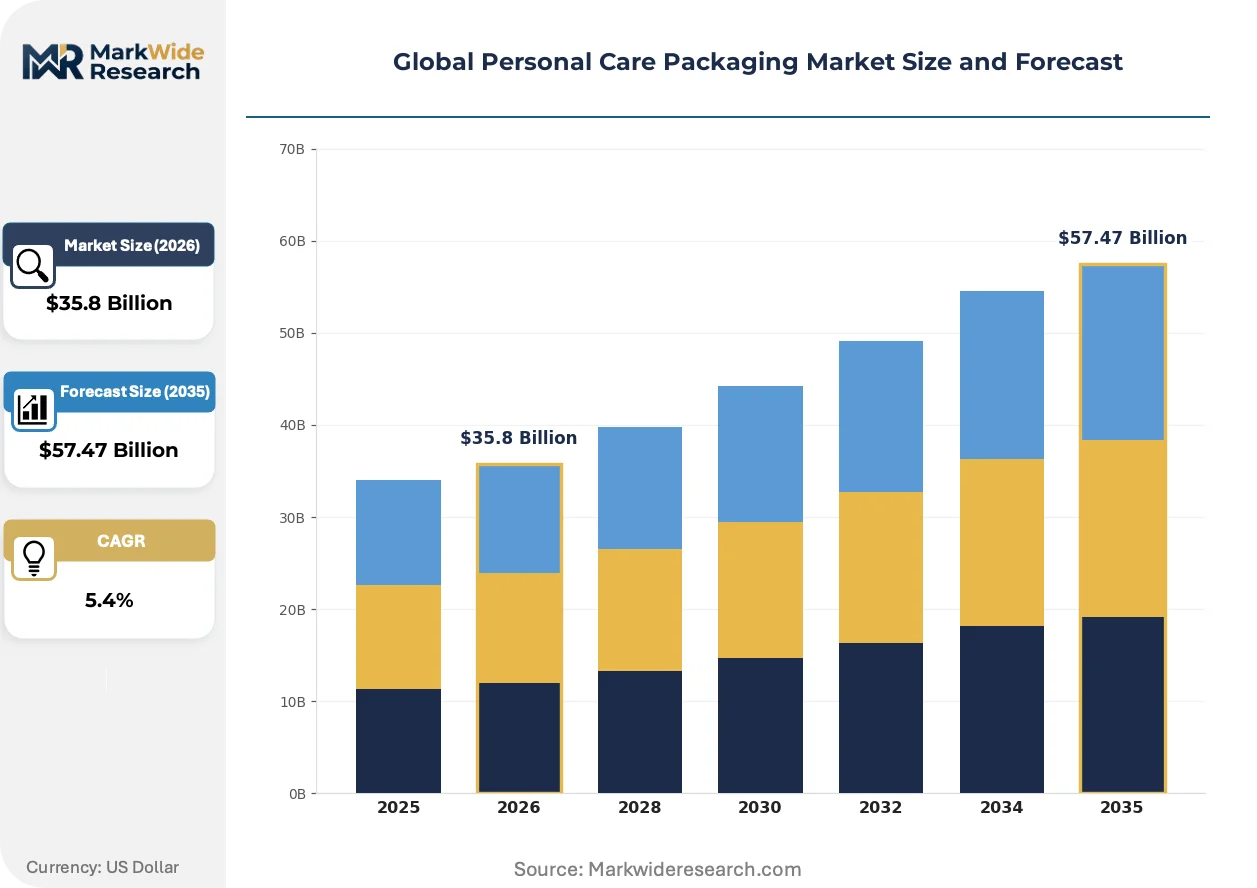
| Market Size in 2026 | $35.8 Billion |
| Market Size in 2035 | $57.47 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
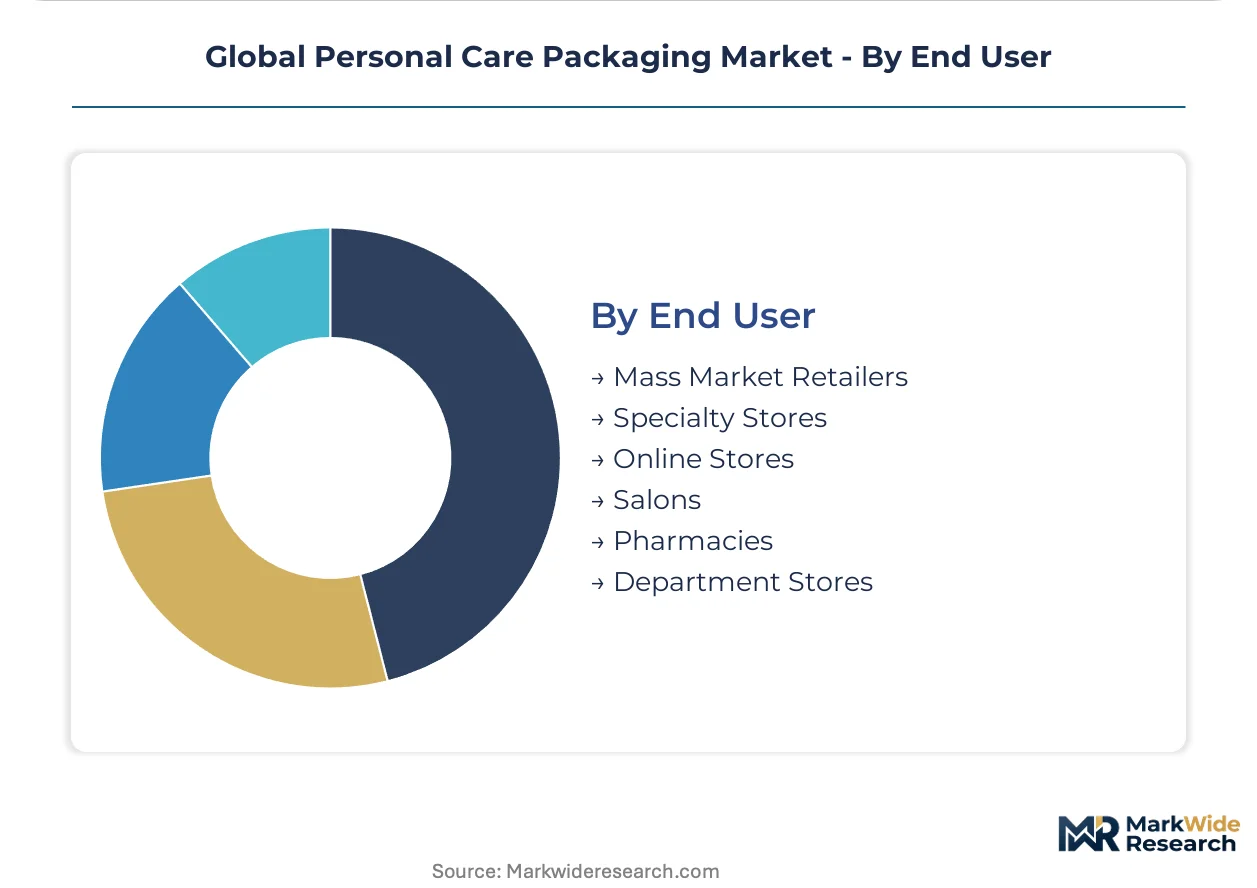
| Segmentation | Packaging Type: Bottles, Jars, Tubes, Pumps, Sachets, Compacts Material: Plastic, Glass, Aluminum, Paperboard, Biodegradable Polymers, Metalized Films Application: Skincare, Hair Care, Makeup, Oral Care, Fragrances, Bath & Body End User: Mass Market Retailers, Specialty Stores, Online Stores, Salons, Pharmacies, Department Stores |
| Companies Covered | Amcor plc, Albea Group, Sonoco Products Company, Ardagh Group, Gerresheimer AG, HCP Packaging, AptarGroup, Inc., Mondi plc, Silgan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Care Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory pressure are converging to dismantle established packaging hierarchies, with functional performance and circular credentials now co-equal design inputs rather than sequential trade-offs.
Mono-material polyethylene tubes with enhanced ethylene-vinyl alcohol copolymer replacement layers are fragmenting the traditional multi-layer laminate market for sensitive skincare. European prestige brands in Germany and France specify these structures for retinol and antioxidant serums previously requiring nylon barriers. The shift is fragmenting converter specialization, with extrusion houses now competing directly with laminate specialists for formulation-sensitive accounts.
China's SAMR enforcement of GB standards for cosmetic packaging safety and migration limits is compressing import approval timelines for foreign-made containers. The regulation requires documented compliance with specific heavy metal thresholds and additive restrictions that differ from EU REACH specifications. Multinational brands operating in Shanghai and Guangzhou now maintain parallel specification sheets, increasing testing overhead but creating advantage for domestic converters with pre-certified material libraries.
Beauty brand procurement teams are consolidating supplier panels and demanding verified recycled content certificates aligned to ISO 14021 environmental claims. The concentration is displacing spot-market purchasing for commodity tubes and closures in favor of multi-year partnership agreements with traceable feedstock documentation. This pattern is most visible in California and New York, where pending state-level recycled content mandates exceed federal EPA guidance thresholds.
Global Personal Care Packaging Market Segmentation
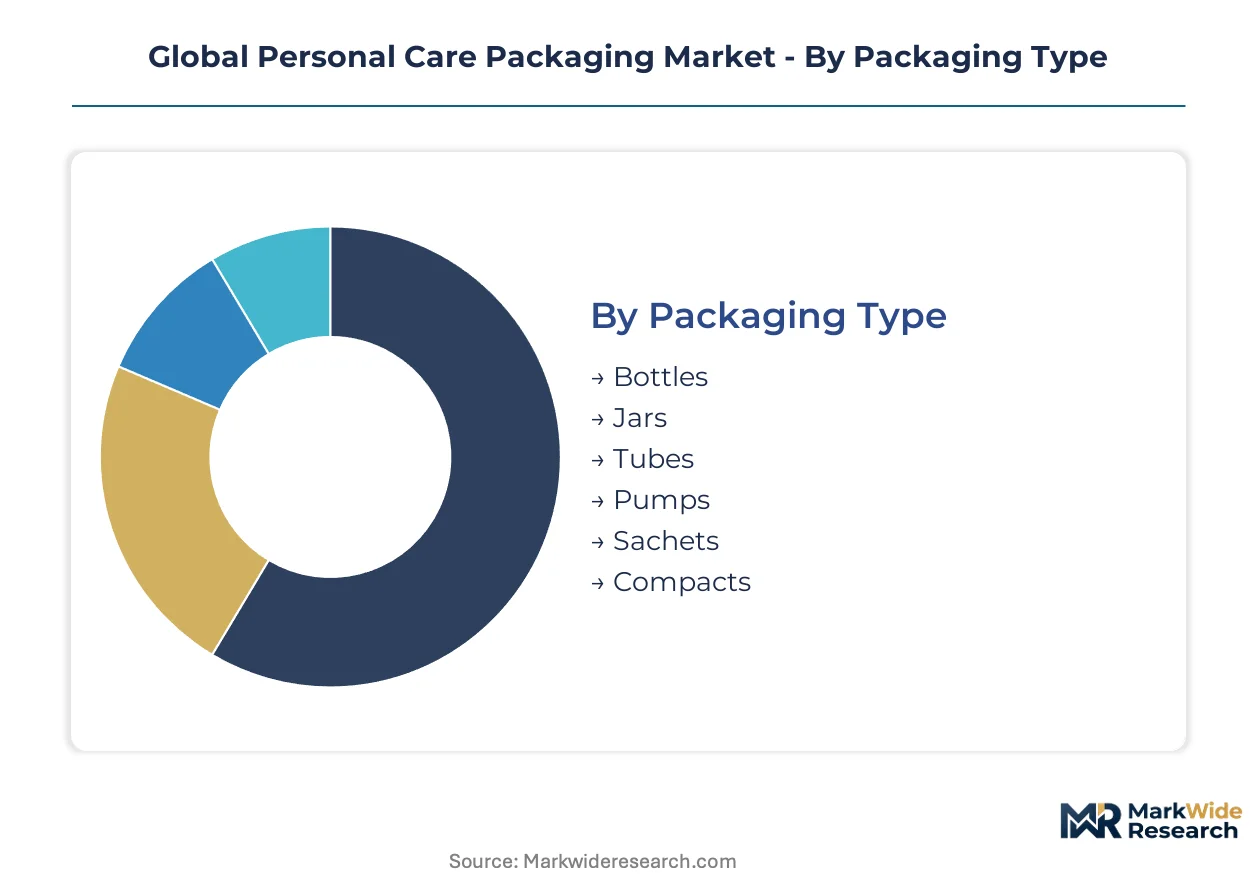
Personal care packaging segments fragment across incompatible performance requirements. Skincare demands oxygen barriers that bath products ignore. Fragrance houses prize glass weight while direct-to-consumer brands punish it.
Packaging Type:
Pumps and airless dispensers capture the highest margin pools as formulation sensitivity escalates.
- Bottles:Polyethylene terephthalate and glass structures dominate shampoo and body wash containment. European prestige fragrance brands specify heavy-walled glass with metallized closures despite freight cost penalties.
- Jars:Wide-mouth configurations accommodate thick creams and balms requiring finger access. South Korean skincare houses drive demand for dual-wall polypropylene jars with metallized overcaps.
- Tubes:Mono-material polyethylene laminates displace multi-layer structures for toothpaste and hair mask distribution. Indian converters in Gujarat expand extrusion capacity to serve domestic oral care brands.
- Pumps:Precision-molded polypropylene dispensing mechanisms command premium positioning in serum and foundation categories. California's pending recycled content mandates force pump suppliers to certify post-industrial feedstock chains.
- Sachets:Flexible foil laminates serve single-use shampoo and conditioner samples across Southeast Asian hospitality channels. Unit economics favor high-speed form-fill-seal operations over rigid alternatives.
- Compacts:Injection-molded polystyrene or acrylonitrile butadiene styrene shells house pressed powder and cream-to-powder formulations. Japanese cosmetic brands specify magnetic closure systems with metallized finishes.
Bottles hold installed capacity across every major manufacturing cluster. Pumps are rotating up the share rankings as airless technology penetrates mid-tier skincare.
Material:
Plastic resin tonnage drives volume economics while glass and aluminum defend premium price tiers.
- Plastic:Polyethylene, polypropylene, and polyethylene terephthalate structures account for bulk personal care containment. China's SAMR enforces GB migration limits that exclude certain recycled feedstocks from cosmetic contact layers.
- Glass:Soda-lime and borosilicate containers signal prestige in fragrance and premium skincare. French glassworks in Normandy and Italian suppliers in Lombardy anchor European supply for luxury houses.
- Aluminum:Lightweight, infinitely recyclable metal serves aerosol cans and collapsible tubes. EU F-Gas Regulation restrictions on propellant systems compress aerosol growth despite aluminum's circular credentials.
- Paperboard:Secondary cartons and rigid boxes provide shelf presence and tamper evidence. German EPR frameworks now require fiber-based packaging to carry sorting instructions and recycled content labeling.
- Biodegradable Polymers:Polylactic acid and polyhydroxyalkanoate alternatives target brands with explicit compostability commitments. Industrial composting infrastructure gaps limit practical end-of-life performance.
- Metalized Films:Vacuum-deposited aluminum layers on polyester or polypropylene substrates create barrier properties for sachets and flexible laminates. Japanese equipment operators dominate multi-layer coextrusion capacity.
Plastic holds installed capacity across converter networks on every continent. Biodegradable polymers are rotating up the share rankings as brand sustainability targets harden into procurement specifications.
Application:
Skincare commands specification intensity that other categories cannot justify economically.
- Skincare:Retinol and vitamin C formulations require oxygen and UV barriers that drive multi-layer or metallized packaging investments. California and New York brand procurement teams now mandate recycled content verification.
- Hair Care:Shampoo and conditioner bottles tolerate lower barrier specifications, favoring cost-optimized polyethylene structures. Brazilian brands in São Paulo source increasingly from domestic converters rather than imported Asian supply.
- Makeup:Foundation, mascara, and lip product packaging demands precise dispensing mechanisms and optical clarity. Korean beauty exports pull airless pump and compact manufacturing toward Busan and Incheon clusters.
- Oral Care:Toothpaste tubes and mouthwash bottles prioritize unit economics and shelf stability over premium aesthetics. Indian mass market consumption expands domestic tube extrusion capacity in Maharashtra.
- Fragrances:Heavy glass bottles with elaborate closures dominate prestige positioning. French regulatory requirements through ANSM shape material safety documentation for imported components.
- Bath & Body:Body wash, lotion, and soap packaging spans pump bottles, jars, and flexible pouches. Direct-to-consumer subscription fulfillment favors lightweight, damage-resistant formats over glass.
Skincare holds installed capacity across barrier film and precision molding specialists. Bath and body flexible formats are rotating up the share rankings as e-commerce penetration accelerates.
End User:
Channel mix determines packaging specification complexity and order fragmentation patterns.
- Mass Market Retailers:High-volume, standardized SKUs with extended production runs suit commodity converters. Walmart and Target procurement consolidation pressures mid-tier suppliers on pricing and EPR compliance documentation.
- Specialty Stores:Sephora and Ulta Beauty channels demand differentiated aesthetics and limited-edition formats. Shorter runs and faster changeovers favor converters with digital printing and agile mold capabilities.
- Online Stores:Amazon and brand-direct fulfillment requires damage-resistant, lightweight formats optimized for parcel conveyance. Returns economics punish glass breakage and leakage failures.
- Salons:Professional hair care and treatment products specify larger format sizes and pump dispensers suited to back-bar use. L'Oréal and Kérastase professional divisions drive dedicated packaging lines.
- Pharmacies:CVS and Walgreens channels merge personal care with quasi-medical positioning, requiring tamper-evident features and regulatory labeling precision. FDA cosmetic labeling requirements shape specification sheets.
- Department Stores:Macy's and Nordstrom prestige counters demand gift-ready packaging with elaborate secondary cartons and ribbon attachments. Seasonal volume spikes strain converter capacity planning.
Mass market retailers hold installed capacity across every major converter. Online stores are rotating up the share rankings as direct-to-consumer brand launches proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in personal care packaging tilt toward net-import positions across Western Europe and North America, while China and India build domestic converter capacity to serve expanding middle-class consumption. Currency volatility and freight cost resets are redirecting procurement decisions toward regional sourcing clusters.
United States
California's SB 54 mandates 30% recycled content in plastic packaging by 2028, forcing converters to certify post-industrial feedstock chains. FDA cosmetic labeling requirements shape specification sheets for CVS and Walgreens channels. New Jersey and Pennsylvania host extrusion capacity serving mass-market shampoo and body wash brands.
Germany
EPR frameworks through the Verpackungsgesetz internalize end-of-life costs for brand owners, converting recyclability into compliance-driven engineering. REACH restrictions constrain polymer additives in sensitive skincare formulations. Bavarian converters near Munich supply mono-material tubes to prestige fragrance houses.
China
SAMR enforcement of GB standards for cosmetic packaging safety compresses import approval timelines for foreign-made containers. Dual carbon policy alignment creates first-mover advantage for converters with verified post-consumer feedstock chains. Guangdong and Zhejiang manufacturing clusters expand airless pump production for domestic skincare brands.
India
Urban households in Mumbai and Delhi pull premium tube and pump demand toward domestic manufacturing clusters in Gujarat and Maharashtra. BIS standards for plastic packaging safety affect imported container specifications. Maharashtra converters expand extrusion capacity to serve mass-market oral care brands.
Brazil
São Paulo-based beauty brands lack local access to airless pump manufacturing, creating import substitution potential for regional converters. ANVISA cosmetic packaging regulations shape material safety documentation requirements. Southeast industrial zones near São Paulo develop tube laminating capacity for hair care brands.
Global Personal Care Packaging Market Key Industry Players
Listed leaders compete with private specialists across capital access and agility trade-offs. Publicly traded converters leverage balance sheet capacity for multi-year EPR compliance investments while family-owned extrusion houses win on changeover speed and limited-edition flexibility. Three archetypes dominate: integrated resin-to-package conglomerates, precision dispensing technology specialists, and regional tube-and-bottle converters. Consolidation through acquisition and backward integration into recycled feedstock sourcing represent the dominant competitive vectors.
Among diversified packaging conglomerates, Amcor plc and Mondi plc occupy positions spanning film extrusion and flexible formats. Precision dispensing technology is anchored by AptarGroup, Inc. and Gerresheimer AG. Regional tube specialists include Albea Group, which exemplifies the European converter archetype with concentrated manufacturing in France and Poland.
| Leading Market Players |
|---|
| Amcor plc |
| Albea Group |
| Sonoco Products Company |
| Ardagh Group |
| Gerresheimer AG |
| HCP Packaging |
| AptarGroup, Inc. |
| Mondi plc |
| Silgan Holdings |
| Others |
Cost & Logistics Intelligence
Sixty-day resin inventory cycles at European converters now determine contract pricing leverage against fixed-price annual commitments from multinational beauty brands. This lead-time compression concentrates margin pressure on mid-tier extrusion houses while integrated conglomerates absorb feedstock volatility through captive supply chains.
Pricing Analysis
Industrial OEM buyers anchor contract structures across three-tier pricing separating airless pump premiums from commodity tube baselines. Price differentiation hinges on ISO 14021 recycled content certification and volume scale commitments exceeding ten million units annually. Pricing pressure intensifies in standard-grade polyethylene segments as Gujarat-based converters expand capacity for domestic Indian oral care brands. Mass-market retailers exhibit highest price sensitivity, while prestige fragrance houses tolerate freight cost penalties for heavy-walled glass from Normandy glassworks.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for aluminum coil and specialty resin shipments. Raw material supply concentrates in China, Germany, and Saudi Arabia for polypropylene feedstock, borosilicate glass, and metallized film substrates respectively. Converter networks draw from Japanese equipment operators for multi-layer coextrusion capacity, creating single-source vulnerability during demand surges. Distribution runs through regional hub-and-spoke models serving Sephora and Ulta Beauty specialty channels alongside Amazon fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of polymer chemists capable of redesigning legacy nylon-EVOH barriers into mono-material structures constrains converter response times to brand sustainability mandates. This capability gap fragments competitive positioning between integrated resin-to-package conglomerates and agile regional specialists.
For Market Incumbents: Secure backward integration into post-industrial scrap recovery to meet California SB 54 recycled content thresholds without spot-market feedstock exposure. Expand airless pump manufacturing capacity in São Paulo industrial zones to preempt import substitution by Brazilian hair care brands. Defend margin pools through captive supply of EVOH replacement layers for retinol-sensitive skincare formulations.
For New Entrants and Emerging Players: Differentiate on SAMR pre-certified material libraries to capture procurement consolidation among Shanghai-based multinational brands. Target white-space in Brazil's underserved premium pump segment where ANVISA documentation requirements currently favor established suppliers. Pursue direct-to-consumer subscription box fulfillment contracts favoring damage-resistant flexible pouches over rigid glass alternatives.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned European extrusion houses lacking capital access for EPR compliance equipment but possessing agile changeover capabilities for limited-edition formats. Long-term viability favors converters with verified post-consumer feedstock chains aligned to dual carbon policy enforcement. Monitor BIS standard harmonization timelines as inflection indicator for Indian import substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Secures California SB 54 compliance ahead of 2028 mandates without spot-market resin exposure. |
| Airless Pump Manufacturing Scale-Up | Captures São Paulo-based beauty brand demand currently served by imported Asian supply. |
| SAMR Pre-Certification Investment | Compresses import approval timelines for multinational brands operating in Shanghai and Guangzhou. |
| Mono-Material Barrier R&D Partnership | Addresses technical limitations in oxygen protection for retinol and vitamin C formulations. |
| Direct-to-Consumer Channel Expansion | Aligns with Amazon and brand-direct fulfillment requirements for lightweight, damage-resistant formats. |
Research Approach
Desk research of customs trade records, SEC 10-K filings, and SAMR GB standard documentation preceded structured interviews with converter plant managers, beauty brand procurement directors, and polymer chemists at barrier film specialists. Primary fieldwork with European tube extrusion houses and Asian pump manufacturers combined with secondary validation through ECHA REACH restriction databases and EPA recycled content guidance. Bottom-up capacity assessments at Gujarat and Maharashtra manufacturing clusters triangulated against top-down demand modeling from Nielsen retail audit data.
Variance decomposition across packaging type, material grade, application sensitivity, and channel mix shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by regional regulatory enforcement intensity and brand sustainability procurement timelines. Industry-specific inputs included EPR cost pass-through elasticity and mono-material adoption curves for oxygen-sensitive skincare formulations.
Material uncertainties — polymer resin price volatility, REACH additive restriction expansion, and SAMR enforcement acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding feedstock certification timelines and converter capex deployment patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Baking Paper Market
Others
Automatic Barriers and Bollards Market
Others
Evidence Management Market
Others
Ultrasonic Flow Meter Market
Others
Air Separation Plant Market
Others
Industrial Wearable Devices Market
Others
UAE Location-Based Services Market
Others
India Data Center Physical Security Market
Others
Inorganic Tin Chemicals Market
Others
Global Crowdsourced Testing Market
Others
Moveable Water Tap Market
Others
Traditional PC Market
Others
Hot Air System Market
Others
Spain Smart Home Market
Others
Vegan Confectionery Market
Others
Signal Transformer Market