
 Global Military and Aerospace Sensors Market | 2026-2036
Global Military and Aerospace Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military and Aerospace Sensors Market Foresight
Defense contractors are reorganizing procurement priorities around unmanned platforms and distributed kill chains. Space agencies and military forces now dominate sensor demand, while Honeywell International Inc. leverages its vertical integration across inertial measurement units to anchor North American supply. RTX Corporation sustains competitive pressure through R&D intensity in quantum sensing, and Thales Group dominates European radar and electronic warfare sensor markets through manufacturing scale and national program capture.
Military and aerospace sensors encompass transducers and detection systems engineered to operate across temperature extremes from minus 55 to 125 degrees Celsius, converting physical stimuli into actionable data for navigation, targeting, and situational awareness in contested electromagnetic environments. Radar and infrared sensor types command the largest installed base, though quantum sensors represent the fastest-growing technology category as defense agencies fund beyond-line-of-sight detection. Fighter jets and unmanned aerial vehicles concentrate platform-level demand, with missile systems generating the highest unit margins due to survivability specifications and limited supplier pools.
The U.S. Department of Defense, EU Defense Fund frameworks, and NATO standardization agreements collectively shape sensor interoperability mandates, export licensing thresholds, and cybersecurity certification requirements that determine market access. FAA and EASA airworthiness standards extend regulatory reach into dual-use aerospace applications, constraining design cycles but elevating barriers for non-compliant suppliers. Stakeholders must monitor shifting electromagnetic spectrum allocation decisions and emerging counter-sensor threats to align R&D portfolios with operational doctrine evolution.
Market Dynamics
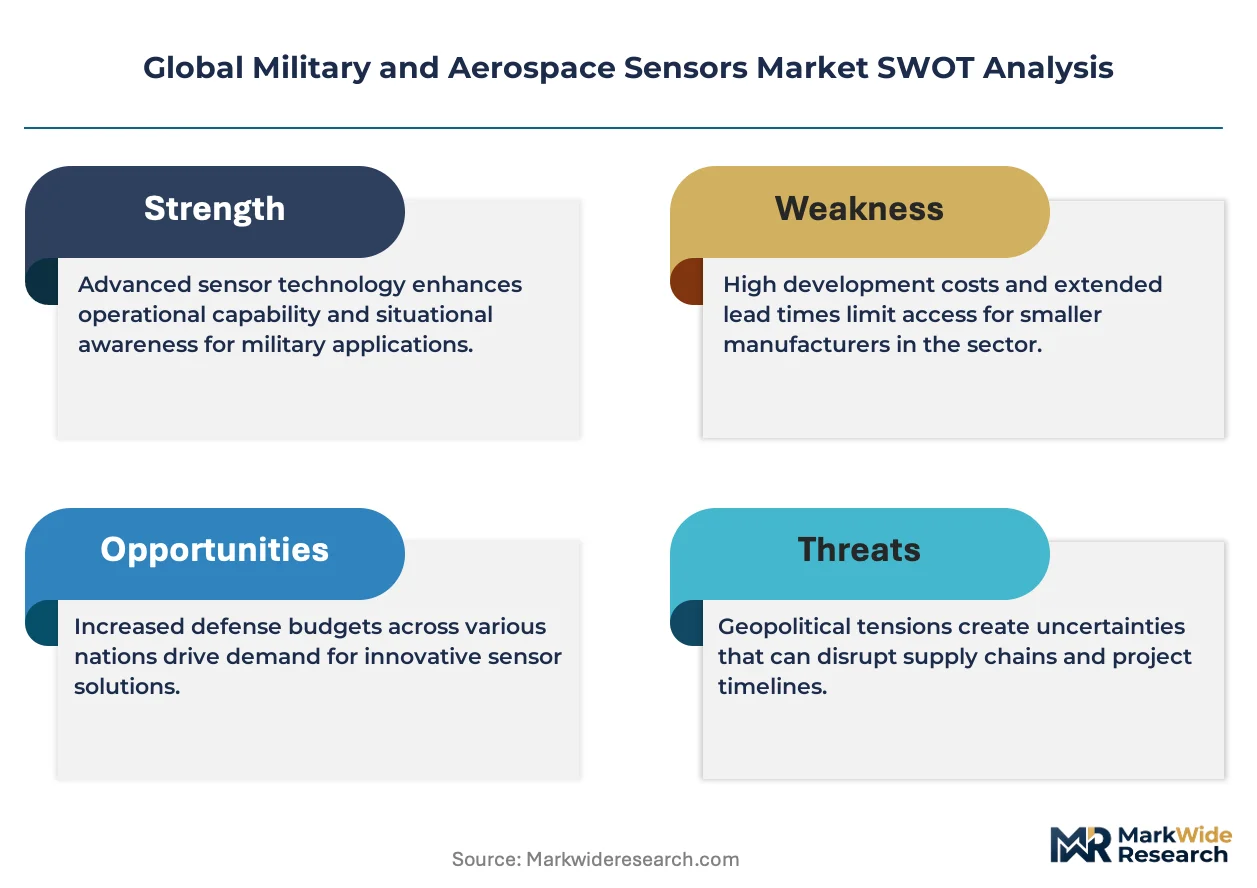
Distributed sensing architectures for contested electromagnetic environments are compressing procurement cycles and forcing suppliers to requalify under stricter NATO electromagnetic compatibility standards. Pentagon modernization budgets now prioritize sensor fusion across unmanned platforms over legacy standalone systems.
Growth Catalysts
- Unmanned platform proliferation:NATO militaries are accelerating procurement of multi-spectral sensor suites for drone programs, creating sustained demand for hardened components rated to minus 55 degrees Celsius operational thresholds.
- EU defense procurement frameworks:Stricter electromagnetic compatibility standards under EU defense procurement frameworks are reshaping supplier qualification requirements and elevating technical barriers for non-compliant manufacturers.
- Quantum sensing R&D intensity:Defense agencies are funding beyond-line-of-sight detection capabilities, positioning quantum sensors as the fastest-growing technology category in military applications.
Market Restraints
- Specialized component scarcity:Inertial measurement unit-grade gyroscopes and radiation-hardened semiconductors face concentrated supply from a limited pool of qualified foundries, creating single-source vulnerabilities.
- Extended certification timelines:FAA and EASA airworthiness standards for dual-use aerospace applications constrain design cycles, stretching development schedules by 18-36 months for new sensor introductions.
- Survivability specification costs:Missile system sensors must meet extreme temperature, shock, and radiation tolerance requirements that multiply unit costs relative to commercial equivalents.
Strategic Opportunities
- Space-based sensor deployment:Military forces and space agencies are expanding constellation architectures for persistent surveillance, opening procurement channels for radiation-hardened optical and radar systems.
- India defense industrial corridor:The country's PLI scheme for aerospace and defense manufacturing is creating localized production incentives for foreign sensor suppliers establishing domestic assembly.
- Cybersecurity certification tailwinds:EU Defense Fund frameworks are mandating encrypted data transmission standards for sensor networks, generating upgrade demand across legacy installed bases.
Industry Challenges
- Electromagnetic spectrum allocation friction:Military and civilian spectrum users are competing for bandwidth in contested frequency bands, forcing sensor designers to implement adaptive frequency-hopping architectures that complicate hardware design.
- Legacy system integration complexity:Fourth-generation fighter platforms require backward-compatible sensor interfaces that limit performance extraction from modern distributed architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military and Aerospace Sensors Market |
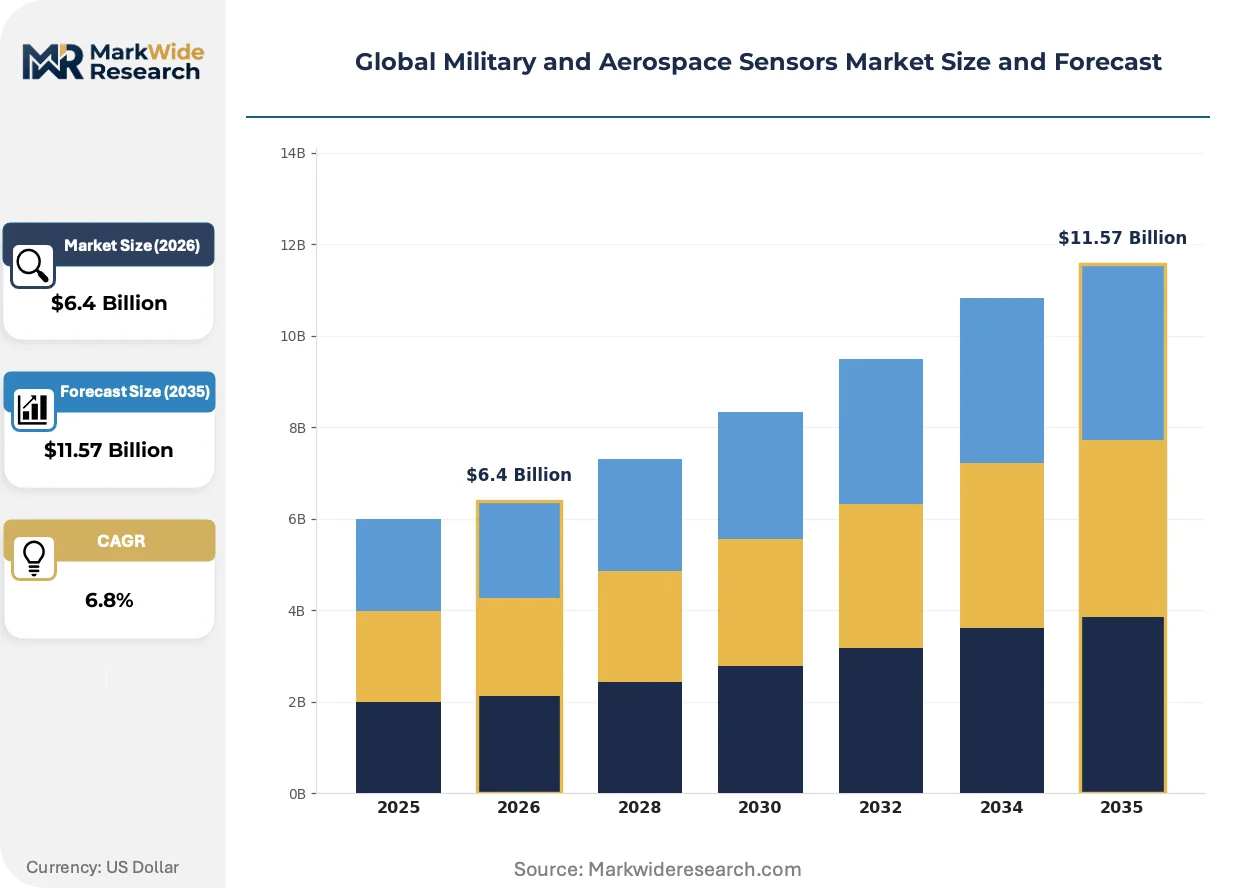
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Radar, Infrared, Lidar, Acoustic, Optical, Magnetic Platform: Unmanned Aerial Vehicles, Fighter Jets, Satellites, Missile Systems, Naval Vessels, Ground Vehicles Technology: Fiber Optic, MEMS, Microbolometer, CCD, Quantum Sensors, Piezoelectric End User: Defense Contractors, Space Agencies, Military Forces, Aerospace Manufacturers, Homeland Security Agencies, Research Institutions |
| Companies Covered | Honeywell International Inc., Lockheed Martin Corporation, RTX Corporation, BAE Systems plc, Thales Group, L3Harris Technologies Inc., Leonardo S.p.A., General Dynamics Corporation, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military and Aerospace Sensors Market Shifts & Advancements
Sensor fusion algorithms and hardened packaging techniques are compressing the gap between laboratory performance and battlefield reliability. Three developments are restructuring competitive positioning.
Photonic integrated circuits are replacing discrete fiber-optic components in inertial navigation systems, reducing weight and power consumption for unmanned aerial vehicle payloads. Defense contractors in the United States are adopting these at prototype-to-production velocity for next-generation distributed kill chains. The technology is miniaturizing gyroscope assemblies from rack-mounted enclosures to chip-scale packages.
REACH and RoHS substance restrictions are extending into EU defense procurement frameworks, prohibiting lead solders and specific flame retardants in sensor electronics. Manufacturers serving NATO supply chains must reformulate printed circuit board assemblies and requalify thermal management systems. Radar and electronic warfare sensor categories face the steepest compliance cost escalation.
Platform prime contractors are unbundling sensor procurement from airframe contracts, creating direct commercial relationships between subsystem suppliers and military program offices. This disintermediation compresses margin structures for integrated platform vendors while elevating pricing power for specialized sensor houses. The United States Department of Defense is most aggressive in this structural separation.
Global Military and Aerospace Sensors Market Segmentation
Segmentation in military and aerospace sensors reveals how procurement priorities diverge across threat environments and platform architectures. Each dimension—sensor physics, host platform, underlying technology, and buyer institution—creates distinct qualification barriers and margin structures that reshape supplier competitive positioning.
Sensor Type:
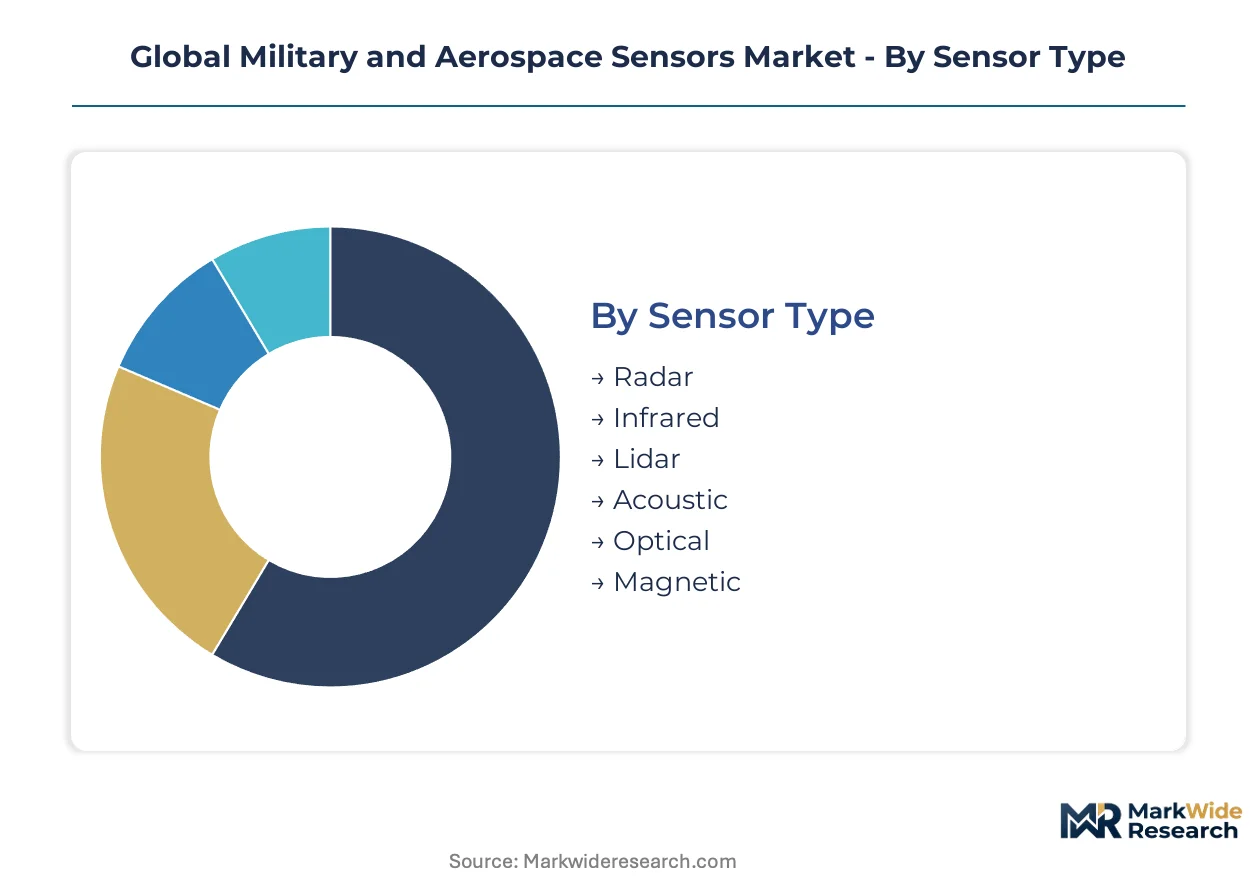
Radar and infrared sensors anchor domestic procurement in the United States and United Kingdom, while acoustic and magnetic variants concentrate in export-led NATO standardization programs.
- Radar:Active electronically scanned arrays and synthetic aperture systems dominate contested airspace detection. Pentagon programs in the United States and BAE Systems procurement in the United Kingdom drive demand for gallium nitride transmit-receive modules rated to 125 degrees Celsius operational thresholds.
- Infrared:Cooled and uncooled thermal imagers convert electromagnetic radiation into targeting data across mid-wave and long-wave spectra. German-French bilateral programs through the Franco-German Defense and Security Council accelerate procurement of quantum well infrared photodetector focal plane arrays for next-generation fighter platforms.
- Lidar:Pulsed laser ranging systems enable terrain mapping and obstacle avoidance for autonomous navigation.
- Acoustic:Passive sonar and microphone arrays detect sub-surface and aerial signatures in littoral environments.
- Optical:Visible-spectrum imagers provide identification-grade resolution for manned reconnaissance platforms.
- Magnetic:Anomaly detection systems locate ferrous objects for anti-submarine and unexploded ordnance applications.
Radar commands the established base. The steepest expansion runs through infrared as multi-spectral fusion architectures proliferate across unmanned platforms.
Platform:
Cost tiering separates missile system sensors—where survivability specifications multiply unit economics—from volume-driven ground vehicle applications.
- Unmanned Aerial Vehicles:Multi-rotor and fixed-wing drones carry miniaturized electro-optical/infrared gimbals below five-kilogram payload limits. Australian Defence Force procurement through the LAND 129 program and Polish Territorial Defence Force acquisitions exemplify tier-two nation acceleration in tactical drone sensor suites.
- Fighter Jets:Fifth-generation platforms integrate distributed aperture systems and helmet-mounted cueing sensors. Japan's F-X program and Italy's participation in the Global Combat Air Programme drive qualification of high-g tolerant inertial reference units.
- Satellites:Low-earth orbit constellations demand radiation-hardened star trackers and synthetic aperture radar payloads.
- Missile Systems:Seeker heads combine millimeter-wave radar with imaging infrared for terminal guidance.
- Naval Vessels:Hull-mounted and towed array sonars dominate undersea warfare sensor suites.
- Ground Vehicles:Active protection systems and driver vision enhancers concentrate in mechanized infantry modernization.
Missile systems extract the highest unit margins. Unmanned aerial vehicles are climbing the fastest as procurement volumes compress cost curves across NATO inventories.
Technology:
Supply concentration in radiation-hardened foundries and inertial-grade gyroscope manufacturing creates single-source vulnerabilities for fiber optic and MEMS categories.
- Fiber Optic:Interferometric gyroscopes and accelerometers exploit Sagnac effect measurement for navigation-grade precision. French iXblue and American KVH Industries anchor transatlantic supply for maritime and aviation inertial systems requiring bias stability below 0.01 degrees per hour.
- MEMS:Silicon micromachined accelerometers and gyroscopes enable tactical-grade navigation at consumer-electronics cost structures. South Korean defense industrial base expansion through Hanwha Aerospace and LIG Nex1 accelerates localized MEMS foundry qualification for indigenous missile programs.
- Microbolometer:Uncooled thermal detectors eliminate cryogenic cooling for infrared imagers.
- CCD:Charge-coupled devices persist in legacy space imaging despite CMOS displacement in terrestrial applications.
- Quantum Sensors:Atomic interferometry and nitrogen-vacancy diamond magnetometry enable beyond-line-of-sight detection.
- Piezoelectric:Ceramic transducers convert mechanical stress into electrical signals for pressure and vibration measurement.
Fiber optic commands the established base. Quantum sensors are gaining share fastest as defense agency R&D budgets reorient toward counter-stealth detection.
End User:
Customer type determines contracting modality—cost-plus development for space agencies versus fixed-price production for defense contractors.
- Defense Contractors:Lockheed Martin, RTX Corporation, and Northrop Grumman integrate subsystems into platform primes. Their supplier qualification processes impose AS9100D and NIST 800-171 cybersecurity standards that filter non-compliant sensor houses from tier-one supply chains.
- Space Agencies:NASA, ESA, and JAXA procure radiation-hardened optical systems for earth observation and deep space missions. European Space Agency's Copernicus expansion and Japan's Epsilon rocket program sustain demand for star trackers with arc-second pointing accuracy.
- Military Forces:Direct procurement by army, navy, and air force program offices bypasses prime contractor margins.
- Aerospace Manufacturers:Boeing and Airbus Defense and Space embed sensors in commercial-military dual-use platforms.
- Homeland Security Agencies:Border surveillance and critical infrastructure protection drive lower-specification thermal camera demand.
- Research Institutions:DARPA, ONR, and European Defence Fund grantees prototype next-generation sensing physics.
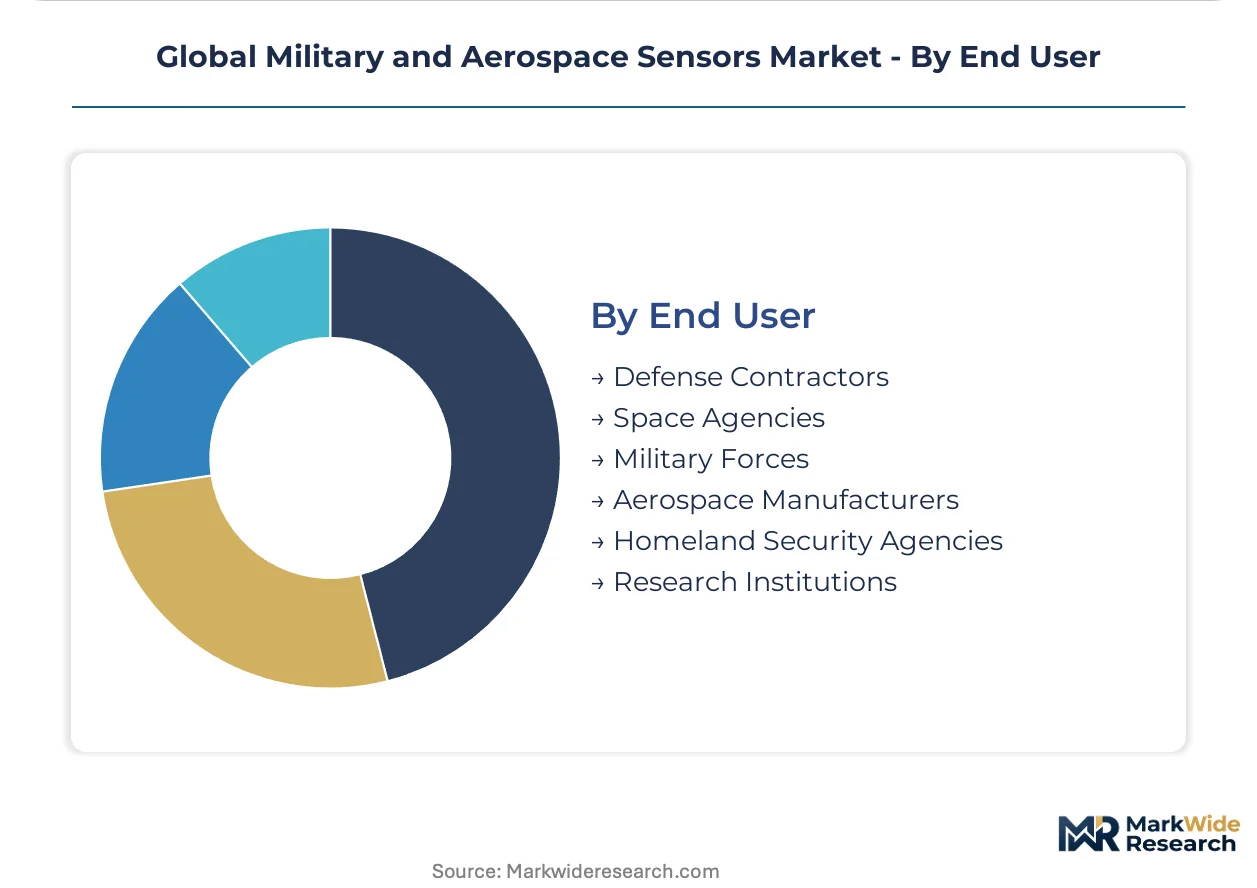
Defense contractors command the established base. Space agencies are expanding most quickly as constellation architectures multiply sensor counts per orbital plane.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pentagon program offices concentrate sensor procurement authority in the United States, while European defense ministries and Asian industrializers are fragmenting demand across national qualification regimes. Military end-users in each geography impose distinct electromagnetic compatibility and cybersecurity standards that filter supplier access.
United States
Distributed aperture systems for fifth-generation fighters and unmanned platform sensor suites drive procurement volumes. FAA airworthiness standards and NIST 800-171 cybersecurity mandates constrain dual-use aerospace applications. Defense contractors in the Greater Washington-Baltimore corridor and Southern California aerospace cluster manage subsystem integration for contested environment architectures.
Germany
Franco-German bilateral programs through the Franco-German Defense and Security Council accelerate quantum well infrared photodetector procurement for next-generation platforms. REACH and RoHS substance restrictions under EU defense procurement frameworks prohibit lead solders in sensor electronics. Manufacturing concentration in Bavaria and Baden-Württemberg anchors radar and electronic warfare sensor production for NATO standardization.
United Kingdom
BAE Systems procurement drives demand for gallium nitride transmit-receive modules in active electronically scanned arrays. UK Ministry of Defence electromagnetic compatibility standards reshape supplier qualification requirements. The Southwest England aerospace corridor around Bristol and the Southeast cluster near London sustain inertial measurement unit and radar subsystem assembly.
Japan
The F-X indigenous fighter program and participation in the Global Combat Air Programme drive qualification of high-g tolerant inertial reference units. METI industrial policy and JIS standards govern defense-aerospace component sourcing. The Chubu region around Nagoya and the Kanto corridor near Tokyo concentrate precision gyroscope and optical sensor manufacturing.
India
The Defense Industrial Corridor and PLI scheme for aerospace manufacturing create localized production incentives for foreign sensor suppliers. BIS certification requirements and DGFT import substitution mandates elevate technical barriers for non-compliant manufacturers. The Tamil Nadu and Uttar Pradesh defense corridors are attracting MEMS foundry and tactical-grade navigation sensor assembly investments.
Global Military and Aerospace Sensors Market Competitive Landscape
Player mix skews toward vertically integrated defense primes and specialized sensor houses with captive foundry access. Market structure concentrates around platform-integrated primes that control subsystem sourcing decisions, while tier-two component specialists compete on radiation-hardening and temperature-extreme qualifications. Two strategic archetypes dominate: diversified aerospace-industrial conglomerates with inertial navigation heritage, and pure-play sensor specialists with quantum sensing R&D pipelines. Competitive dynamics center on electromagnetic compatibility requalification under shifting NATO standards and disintermediation of sensor procurement from airframe contracts.
Among diversified aerospace-industrial conglomerates, Honeywell International Inc. and RTX Corporation exemplify the integrated-platform model with upstream control over inertial measurement unit supply chains. Thales Group occupies a position representing European manufacturing scale in radar and electronic warfare categories. These three entities anchor transatlantic competitive positioning through national program capture and distributed sensing architecture contracts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Lockheed Martin Corporation |
| RTX Corporation |
| BAE Systems plc |
| Thales Group |
| L3Harris Technologies Inc. |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| Others |
Supply & Pricing Matrix
Gallium nitride foundry utilization rates above 85 percent in United States and Japanese facilities compress unit economics for active electronically scanned array transmit-receive modules while elevating price floors for qualified suppliers. Pentagon cost-plus contracts with named labor and materials indexation clauses insulate prime contractors from input volatility, though tier-two sensor houses absorb margin compression from extended FAA airworthiness certification cycles.
Pricing Analysis
Cost-plus contracts with Defense Federal Acquisition Regulation Supplement labor and materials indexation dominate procurement for development-phase sensor programs. Price differentiation separates radiation-hardened space-grade components from tactical-grade equivalents through AS9100D certification tier and thermal cycling test documentation. Cost compression in uncooled microbolometer categories intensifies as South Korean MEMS foundries expand wafer capacity. Missile system integrators exhibit lowest price sensitivity due to survivability specification non-substitutability, while unmanned platform primes negotiate aggressively on electro-optical gimbal volumes.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port complexes constrain just-in-time delivery of precision gyroscope assemblies from Japanese Chubu region manufacturers. Radiation-hardened semiconductor supply concentrates in United States, France, and Israel, drawing from specialized foundry capacity at Honeywell and Teledyne facilities. Single-source vulnerability pervades inertial-grade fiber coil winding equipment and molecular beam epitaxy systems for quantum well infrared photodetectors. Distribution runs through Defense Logistics Agency-managed stockpiles for critical items, with direct commercial sales channels expanding for non-military-specification components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Military and Aerospace Sensors Market enters a cyclical recovery phase as NATO electromagnetic compatibility requalification waves force replacement demand across legacy installed bases. Pentagon sensor fusion program acceleration and EU Defense Fund cybersecurity mandates sustain procurement momentum through the analysis window.
For Market Incumbents: Compound defensive positioning through backward integration into gallium nitride wafer fabrication and captive inertial-grade gyroscope coil winding capacity. Lockheed Martin and RTX Corporation procurement qualification processes filter non-compliant suppliers; incumbents should preemptively certify under stricter NATO STANAG electromagnetic compatibility protocols before 2026 implementation deadlines. Quantum sensing R&D pipelines represent the priority capability lever against emerging atomic interferometry specialists.
For New Entrants and Emerging Players: Anchor in India's Defense Industrial Corridor PLI scheme for aerospace manufacturing, where localized MEMS foundry assembly incentives reduce import substitution barriers. The unmanned aerial vehicle electro-optical gimbal segment offers most penetrable entry point given platform prime contractor disintermediation trends. Pursue direct commercial relationships with Australian Defence Force and Polish Territorial Defence Force program offices as alternative procurement channels outside United States prime contractor capture.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play sensor specialists with quantum sensing R&D pipelines over diversified platform primes facing margin compression from airframe contract unbundling. Long-term viability through the next decade rests on radiation-hardening qualification depth and national program capture in United States, Germany, or Japan. Watch electromagnetic spectrum allocation decisions by FCC and national regulators as inflection indicator for adaptive frequency-hopping architecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum Sensing R&D Pipeline Investment | DARPA and European Defence Fund grants accelerate atomic interferometry beyond-line-of-sight detection capabilities. |
| Radiation-Hardened Foundry Capacity Expansion | United States and French facilities secure supply for low-earth orbit constellation star tracker procurement. |
| NATO STANAG Electromagnetic Compatibility Certification | EU defense procurement frameworks mandate requalification that filters non-compliant sensor manufacturers. |
| Direct Commercial Sales Channel Development | Pentagon disintermediation of sensor procurement from airframe contracts elevates specialized supplier pricing power. |
| India Defense Industrial Corridor Localization | PLI scheme incentives attract MEMS foundry and tactical navigation sensor assembly investments from foreign suppliers. |
Research Methodology
The analysis maps radar and electronic warfare sensors, infrared and electro-optical systems, inertial navigation units, and quantum sensing technologies, each validated through program office procurement leads at defense contractors, electromagnetic compatibility certification engineers, radiation-hardening test facility directors, and unmanned platform subsystem integration specialists. Primary interview intelligence combined with secondary validation from Pentagon budget justification documents, NATO standardization agreement repositories, ESA Copernicus procurement disclosures, and FAA airworthiness certification databases. Bottom-up sensor unit demand estimates triangulated against top-down defense expenditure allocations across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including national defense budget sensor line items, prime contractor subcontractor awards, and space agency payload procurement records. Segmentation modeling incorporated sensor physics type, host platform architecture, underlying technology category, and end-user contracting modality across the projection horizon. CAGRs derived from regression analysis of historical procurement cycles adjusted for electromagnetic compatibility requalification waves and quantum sensing R&D funding trajectories. Forecast inputs included Pentagon distributed sensing architecture deployment timelines and EU Defense Fund cybersecurity mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained NATO electromagnetic compatibility standard enforcement and continued Pentagon sensor fusion program funding; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as electromagnetic spectrum allocation decisions and counter-sensor threat evolution reshape operational doctrine and procurement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cloud Gaming Baas Market
Others
Canada Feed Additives Market
Others
Mobile Retina Services Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
India Home Automation Market
Others
Europe Aircraft Lighting Systems Market
Others
Advanced Combat Helmet Market
Others
Industrial Wearable Devices Market
Others
Cellular-Connected Laptops Market
Others
ASEAN Agricultural Logistics Market
Others
Rugged Tablet Market
Others
Cat Food Market
Others
United States Indoor LBS Market
Others
US Luxury Travel Market
Others
North America Commercial Vehicles Lubricants Market
Others
Small Office Home Office (SOHO) Servers Market