
 Cloud DVR Market | 2026-2036
Cloud DVR Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud DVR Market Analysis
The pay-TV distribution channel is narrowing as operators consolidate around IP-delivered cloud recording platforms. Comcast Corp. leverages its X1 platform architecture to control subscriber migration from physical DVR hardware to virtualized storage. Verizon Communications Inc. competes through Fios TV One, which anchors its fiber-based cloud recording strategy against satellite and cable rivals. Charter Communications Inc. sustains market presence via Spectrum TV's cloud DVR rollout across its hybrid coax-fiber footprint.
Cloud DVR refers to network-based digital video recording systems that store encoded television content on remote server infrastructure rather than local hard drives, typically supporting MPEG-4/H.264 or HEVC compression with multi-tenant storage virtualization. These platforms enable time-shifted viewing, pause-live-TV functionality, and cross-device content access for residential subscribers and commercial venues. The deployment model dimension shows public cloud configurations capturing the largest installed base due to elastic capacity scaling, while hybrid cloud architectures represent the fastest-expanding segment as operators balance latency-sensitive edge processing with centralized archive economics. Among end user categories, service providers command the dominant revenue share through wholesale platform licensing, whereas residential users generate the highest transaction volume via direct subscription uptake.
The FCC enforces net neutrality and accessibility mandates that influence how broadband providers prioritize cloud DVR traffic across last-mile networks. GDPR and the EU AI Act impose data localization and algorithmic transparency requirements on European deployments, affecting recommendation engines and viewing analytics architectures. Stakeholders must monitor evolving spectrum allocation decisions and content licensing frameworks that determine territorial availability windows for recorded programming.
Market Dynamics
Pay-TV operators are dismantling legacy set-top infrastructure and migrating subscribers to virtualized cloud recording platforms, a structural shift that compresses hardware capital intensity while expanding per-subscriber storage economics through centralized data center consolidation.
Growth Catalysts
- GDPR Data Localization Mandates:European operators are redesigning cloud DVR architectures to keep recorded content within EU territorial boundaries, triggering infrastructure investment cycles in regional data centers.
- HEVC Compression Adoption:Service providers are deploying HEVC encoding to halve storage footprints per hour of recorded programming, enabling tiered subscription models with expanded recording hours.
- United States:Cable operators and telcos are retiring physical DVR hardware at scale, driving wholesale demand for virtualized recording platforms that integrate with IP-delivered video services.
Market Restraints
- Net Neutrality Uncertainty:FCC regulatory ambiguity around traffic prioritization creates architectural risk for operators investing in low-latency cloud DVR delivery over broadband last-mile networks.
- Content Licensing Fragmentation:Territorial availability windows for recorded programming vary by studio agreement, forcing complex rights-management engineering that limits cross-border service portability.
- Edge Computing Capex Requirements:Hybrid cloud deployments demand simultaneous investment in centralized archive infrastructure and distributed edge nodes, straining operator balance sheets against pure public cloud alternatives.
Strategic Opportunities
- EU AI Act Algorithmic Transparency:European cloud DVR platforms can differentiate through auditable recommendation engines that comply with mandated explainability standards for automated content curation.
- Commercial Venue Segment:Hotels, hospitals, and multi-dwelling units represent underpenetrated demand for managed cloud recording services with centralized billing and administrative controls.
- 5G Network Slicing Convergence:Mobile operators can bundle guaranteed-bitrate slices with cloud DVR subscriptions, creating quality-of-service differentiation against best-effort broadband competitors.
Industry Challenges
- Virtualization Engineering Talent Scarcity:Operators face acute shortages of engineers skilled in Kubernetes-orchestrated video pipelines and multi-tenant storage isolation.
- Legacy Conditional Access Integration:Migrating subscriber entitlements from physical smart cards to cloud-native DRM systems requires parallel operation of incompatible security architectures during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud DVR Market |
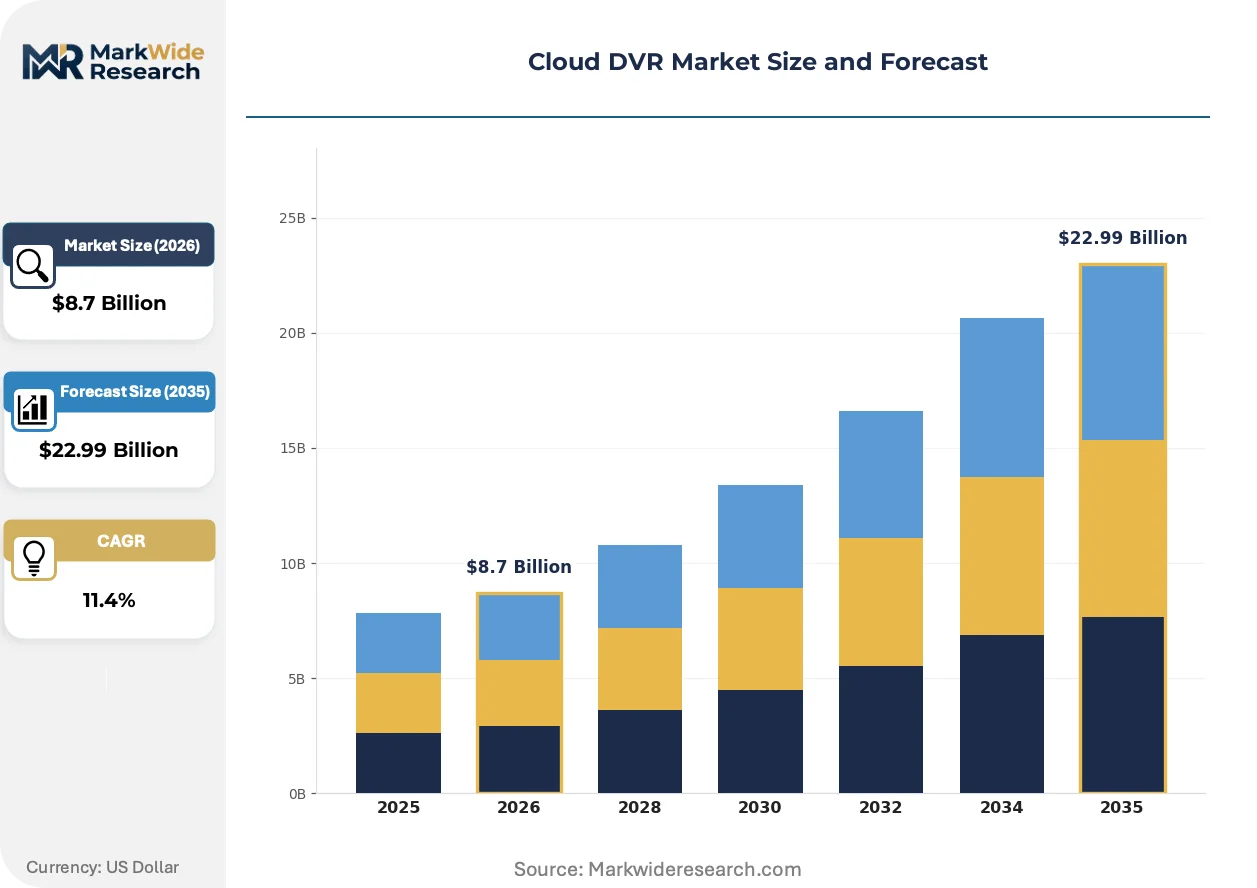
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription-Based, Pay-Per-View, Free, Ad-Supported Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Residential Users, Service Providers, Enterprises, Educational Institutions Content Type: Live Sports, Movies, TV Shows, News |
| Companies Covered | Verizon Communications Inc., Cisco Systems Inc., AT&T Inc., Telefonaktiebolaget LM Ericsson, Harmonic Inc., Comcast Corp., EchoStar Corp., Xperi Holding Corp., Charter Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud DVR Market Emerging Trajectories
Virtualization of video processing functions is collapsing the boundary between network edge and core, enabling operators to deploy recording capabilities as software-defined services rather than purpose-built appliances.
Serverless encoding pipelines are rendering obsolete the dedicated transcoding hardware that previously dominated cable headends. Tier-1 operators in the United States are deploying these elastic compute architectures to scale recording capacity dynamically with subscriber demand. The shift is rendering obsolete fixed-capacity MPEG-4 encoder farms that required three-to-five-year depreciation cycles regardless of utilization.
The EU AI Act imposes algorithmic transparency requirements on automated content recommendation systems deployed within European cloud DVR platforms. Operators must now maintain audit trails for machine-learning models that suggest recorded programming to subscribers. French and German deployments are most affected, with engineering teams rearchitecting inference pipelines to generate human-interpretable decision logs.
Subscriber expectations for instantaneous cross-device playback are compressing synchronization cycles between mobile applications and cloud recording libraries. Streaming aggregators are responding with predictive content pre-positioning algorithms that stage recordings on edge caches before explicit user requests. This behavioral shift is most visible in United States metropolitan markets where fiber-to-the-home penetration supports sub-50-millisecond latency to regional data centers.
Cloud DVR Market Segmentation
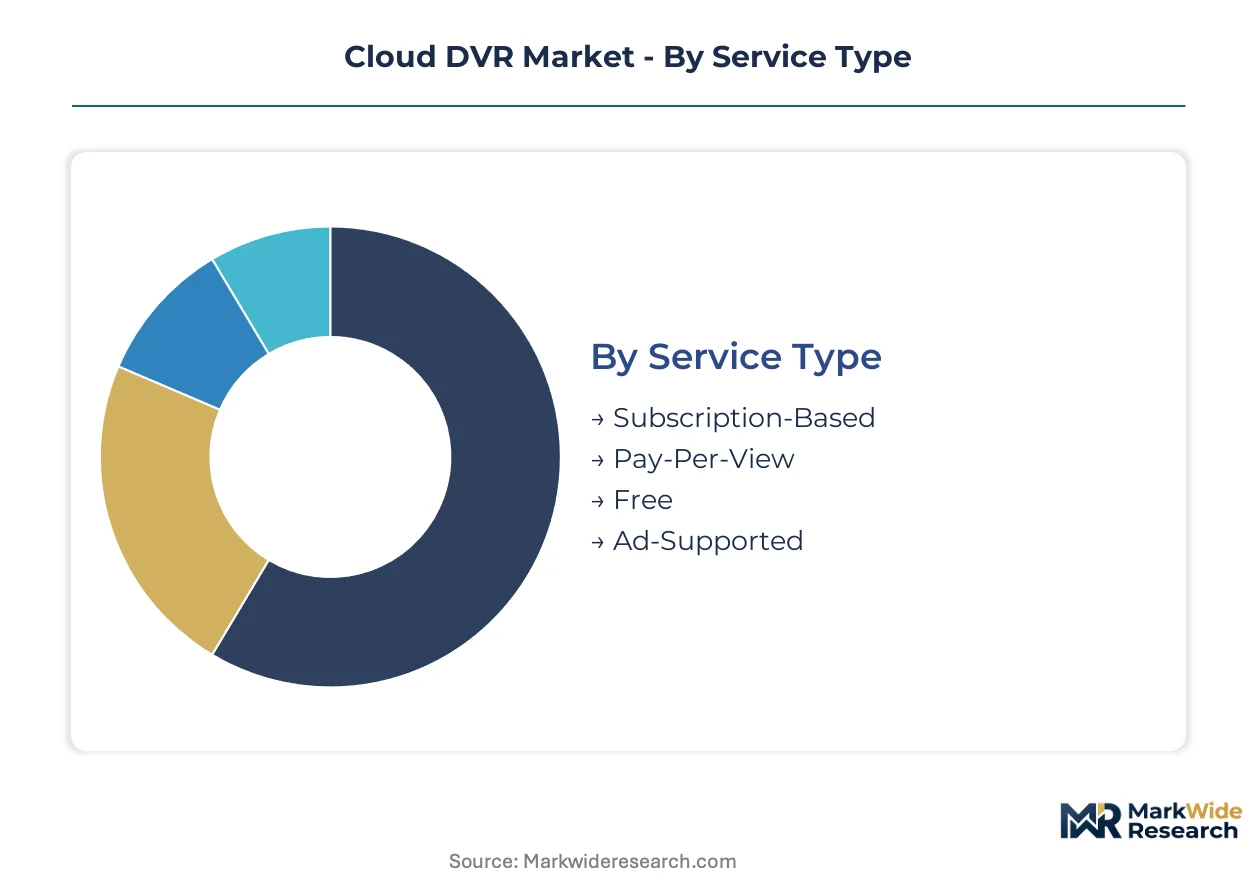
Cloud DVR architectures fragment across monetization mechanisms, infrastructure ownership, audience profiles, and content genres. Each dimension shapes capital allocation, latency requirements, and rights-management complexity differently.
Service Type:
Monetization models span prepaid commitment, transactional access, zero-fee entry, and advertising-funded consumption—each demanding distinct subscriber acquisition economics and churn management protocols.
- Subscription-Based:Recurring revenue contracts anchor operator cash flow predictability. United States cable operators and European telcos concentrate investment here, driven by subscriber lifetime value metrics that justify upfront platform deployment costs.
- Pay-Per-View:Transactional recording of premium live events generates event-specific revenue spikes. Sports-centric deployments in Germany and Brazil leverage this model for championship programming where time-shifted viewing commands premium pricing.
- Free:Limited-capacity tiers with basic recording hours serve as subscriber acquisition funnels. India's broadcasters deploy these to compete with ad-supported streaming alternatives.
- Ad-Supported:Recording capabilities subsidized through targeted pre-roll and mid-roll inventory. FAST platform integrations in the United Kingdom and Australia monetize through programmatic advertising rather than direct subscriber fees.
The dominant share belongs to Subscription-Based, while Ad-Supported is closing the gap fastest.
Deployment Model:
Infrastructure ownership decisions hinge on data sovereignty mandates, latency sensitivity, and amortization timelines for existing capital stock.
- Public Cloud:Elastic compute and storage scaling without fixed asset commitment. Operators in Singapore and the Netherlands favor AWS, Azure, and Google Cloud deployments to avoid data center construction delays.
- Private Cloud:Dedicated infrastructure serving single-tenant security and compliance requirements. French and German operators under GDPR pressure maintain sovereign recording archives within national borders.
- Hybrid Cloud:Edge caching for latency-critical playback combined with centralized cold storage. This architecture expands most quickly as operators balance real-time performance against archive economics.
- On-Premises:Legacy headend equipment retained for regulatory compliance or contractual obligations. Japanese and South Korean incumbents phase these out gradually due to depreciation schedules.
Public Cloud retains the largest installed base, though Hybrid Cloud shows the steepest expansion trajectory.
End User:
Demand concentrates differently across household consumption, wholesale platform licensing, corporate deployments, and campus environments.
- Residential Users:Individual households consuming time-shifted programming across multiple screens. United States fiber-to-the-home markets and South Korean gigabit broadband deployments drive per-subscriber storage growth.
- Service Providers:Wholesale platform licensing to regional operators lacking in-house virtualization capability. Tier-2 cable operators in Spain and Italy source recording infrastructure from specialized vendors.
- Enterprises:Managed recording services for hospitality, healthcare, and corporate campuses. Hotels in Dubai and Singapore deploy centralized billing with administrative controls for guest room entertainment.
- Educational Institutions:Lecture capture and archival systems for university media libraries. Australian and Canadian universities integrate cloud recording with learning management platforms.
Service Providers command the dominant revenue share, while Enterprises gain share fastest through commercial venue penetration.
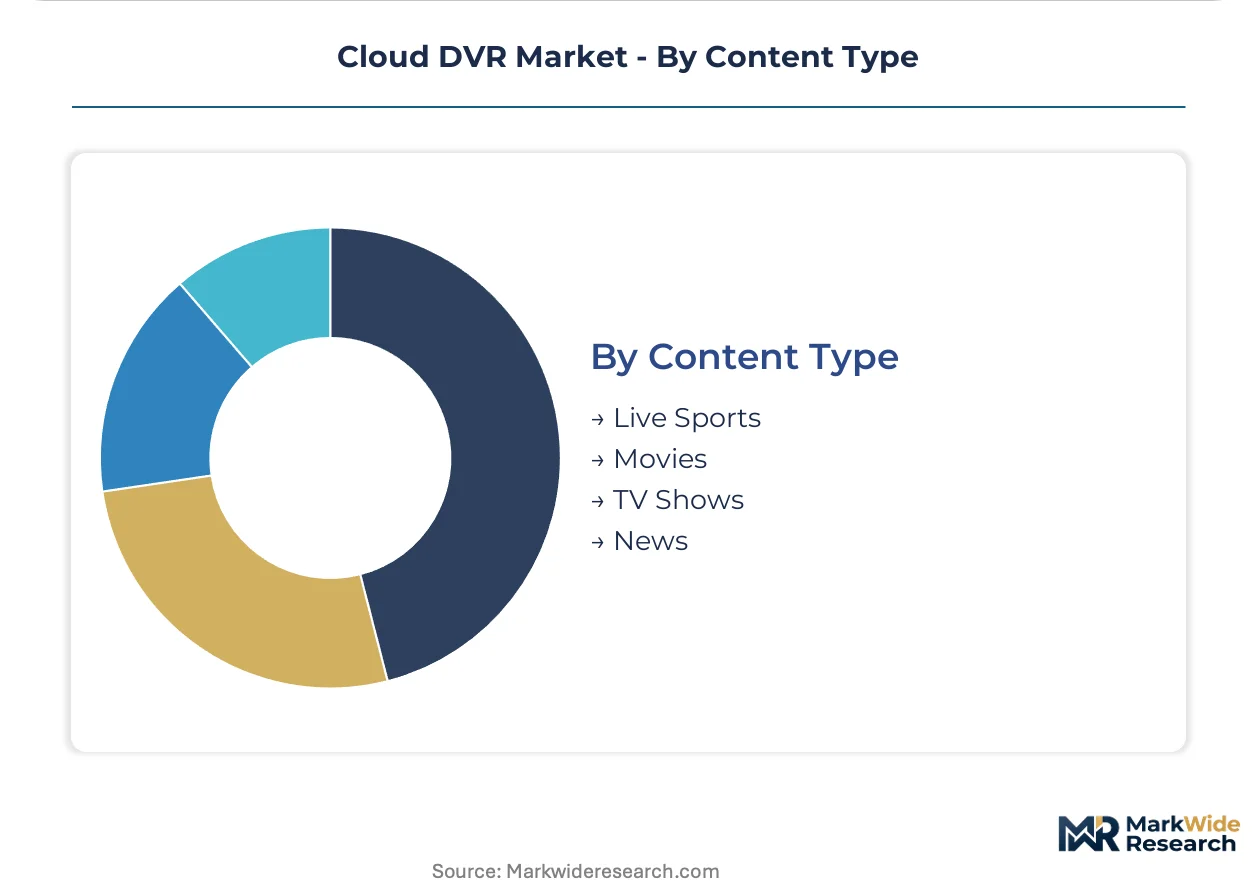
Content Type:
Genre-specific recording behaviors differ in storage duration, compression ratios, and cross-device synchronization urgency.
- Live Sports:Time-sensitive recordings with high immediate viewership decay. Operators in Brazil, Argentina, and the United Kingdom prioritize low-latency edge delivery for match replays.
- Movies:Long-tail library value with extended storage retention. Studio licensing windows in France and Germany constrain territorial availability despite subscriber recording requests.
- TV Shows:Serialized content with binge-watching consumption patterns. United States streaming aggregators optimize predictive pre-positioning for episode sequences.
- News:Rapidly depreciating value with minimal long-term archival demand. Local broadcasters in India and Indonesia offer abbreviated retention periods to manage storage costs.
TV Shows capture the dominant recording volume, while Live Sports is expanding most quickly through premium tier differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where fiber-to-the-home penetration supports premium cloud DVR tiers, while Indian operators compete through ad-subsidized entry-level recording hours that compress per-subscriber revenue.
United States
Comcast Corp. and Charter Communications Inc. dismantle legacy set-top infrastructure at scale, converting physical DVR subscribers to virtualized X1 and Spectrum TV platforms. FCC net neutrality rulings force traffic prioritization disclosures that shape last-mile delivery architectures. The Northeast Corridor corridor from Boston to Washington anchors deployment density, with Verizon Communications Inc. extending Fios TV One fiber-based recording across this footprint.
Germany
Telefonaktiebolaget LM Ericsson supplies virtualization infrastructure to Deutsche Telekom and Vodafone Germany as they retire MPEG-2 headend equipment. GDPR data localization mandates require recorded content storage within national borders, triggering regional data center investment cycles. The Cologne-Düsseldorf-Ruhr cluster hosts the densest concentration of edge caching nodes serving time-shifted sports programming.
United Kingdom
Sky Group and BT Group deploy hybrid cloud architectures balancing low-latency edge playback against centralized archive economics for Premier League recordings. Ofcom accessibility mandates influence cross-device synchronization requirements for subscriber libraries. London's Docklands and Manchester's MediaCityUK concentrate engineering talent for Kubernetes-orchestrated video pipelines.
India
Reliance Jio and Bharti Airtel leverage 5G network slicing to bundle guaranteed-bitrate tiers with cloud DVR subscriptions against cable competitors. TRAI tariff regulations constrain pricing flexibility for premium recording hours. The Mumbai-Pune corridor and Bengaluru's Whitefield electronics cluster host the primary vendor engineering centers supporting regional operator migrations.
Brazil
Claro and Vivo compete for sports-centric recording demand around Campeonato Brasileiro and Copa Libertadores fixtures, where time-shifted viewing commands premium pricing. ANATEL's net neutrality framework shapes traffic management for streaming video delivery. São Paulo's Brooklin Novo district anchors Latin American platform development operations for multinational vendors.
Cloud DVR Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encoding, storage virtualization, and DRM modules. The vendor base stratifies across three tiers: Tier-1 operators with captive cloud infrastructure, Tier-2 regional licensees sourcing wholesale platforms, and pure-play technology vendors licensing software stacks. Dominant competitive moves include strategic partnerships between telcos and cloud hyperscalers, plus vertical integration into edge computing hardware to reduce latency for live sports replay.
Within the integrated operator tier, Comcast Corp., Verizon Communications Inc., and Charter Communications Inc. exemplify the infrastructure-owning archetype that controls subscriber migration from physical to virtualized recording. Cisco Systems Inc. and Harmonic Inc. occupy positions as technology specialists supplying encoding and virtualization software to operators lacking in-house development capability. AT&T Inc. anchors the converged communications-provider segment where mobile and fixed broadband recording services bundle under unified billing.
| Leading Market Players |
|---|
| Verizon Communications Inc. |
| Cisco Systems Inc. |
| AT&T Inc. |
| Telefonaktiebolaget LM Ericsson |
| Harmonic Inc. |
| Comcast Corp. |
| EchoStar Corp. |
| Xperi Holding Corp. |
| Charter Communications Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwanese semiconductor foundries for video encoding ASICs compresses both tier spreads and geographic diversification strategies across cloud DVR infrastructure procurement. FCC net neutrality uncertainty and GDPR data localization mandates force parallel supply chain configurations that inflate configured-to-order premiums against standardized public cloud deployments.
Pricing Analysis
The customization-premium spread separates hyperconverged edge nodes with sub-50-millisecond latency guarantees from commodity public cloud storage tiers by factors reflecting fiber density and data sovereignty compliance costs. Subscription-based SaaS-tiered pricing dominates operator procurement, with price differentiation driven by HEVC compression certification tiers and geographic delivery costs to edge caching nodes. Cost compression in standard tiers intensifies as AWS, Azure, and Google Cloud expand elastic compute offerings. Wholesale platform licensees exhibit highest price sensitivity; tier-1 operators with captive infrastructure demonstrate lowest sensitivity due to amortized data center investments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing strategies for encoding hardware and edge server assemblies. Supply concentrates in Taiwan for video processing silicon, South Korea for high-density memory modules, and the Netherlands for optical networking gear. Raw material dependencies span gallium nitride substrates, DDR5 DRAM, and specialized fiber optic transceivers. Single-source vulnerability persists at the 7nm and 5nm process nodes where TSMC anchors global foundry capacity. Distribution runs through direct OEM relationships with Ericsson, Harmonic, and Cisco Systems, supplemented by systems integrators serving tier-2 operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud DVR infrastructure is undergoing platform virtualization disruption accelerated by FCC mandates on set-top box energy efficiency and European GDPR data localization requirements. This regulatory-technological inflection compresses hardware depreciation cycles while expanding software-defined service margins.
For Market Incumbents: Harden cloud-native DRM architectures against emerging pure-play SaaS competitors offering serverless encoding pipelines. Prioritize backward integration into edge computing hardware to reduce latency for live sports replay delivery. Consolidate subscriber migration programs from physical DVR estates to virtualized platforms before competitive overbuild accelerates.
For New Entrants and Emerging Players: Latin American commercial venue deployments represent underpenetrated white space with concentrated hospitality and healthcare demand for managed recording services. Target Brazil's São Paulo corridor and Mexico City's multi-dwelling unit clusters where legacy cable infrastructure requires wholesale platform replacement. Pursue channel partnerships with regional telcos lacking in-house Kubernetes orchestration capability.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized encoding software vendors with proven hyperscaler deployments. Long-term viability rests on algorithmic transparency compliance for EU AI Act recommendation engines and HEVC patent portfolio depth. Monitor ANATEL and TRAI net neutrality rulings as inflection indicators for traffic prioritization monetization.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Architecture Deployment | Balances GDPR-compliant sovereign storage against low-latency edge playback for sports-centric operators. |
| HEVC Patent Portfolio Acquisition | Secures royalty positioning as MPEG-4 encoding farms face obsolescence from serverless compression pipelines. |
| 5G Network Slicing Partnership | Enables guaranteed-bitrate cloud DVR bundles that differentiate mobile operators from best-effort broadband rivals. |
| EU AI Act Compliance Engineering | Generates auditable recommendation engines with human-interpretable decision logs for French and German deployments. |
| Commercial Venue Platform Licensing | Captures hospitality and healthcare demand through centralized billing with administrative tier controls. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC rulings, ETSI technical specifications, and hyperscaler capex disclosures to establish infrastructure deployment trajectories. Interviews with pay-TV platform engineering directors, telco cloud procurement officers, and video encoding specialists informed capacity planning assumptions. Secondary validation drew from SEC 10-K infrastructure disclosures, TRAI tariff orders, and ANATEL regulatory filings. Bottom-up subscriber migration modeling triangulated against top-down operator capital expenditure analysis.
Forecast inputs span deployment model segmentation across public, private, hybrid, and on-premises architectures; end-user categories from residential households to enterprise venues; and content type dynamics distinguishing live sports latency requirements from long-tail movie storage economics. CAGRs derived from subscriber conversion rates, per-user storage growth curves, and compression efficiency gains across the projection horizon. Industry-specific inputs include fiber-to-the-home penetration by metropolitan market and GDPR data center construction timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers into direct operator relationships would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Battery Packaging Market
Others
AI in Precision Medicine Market
Others
Global Molded Plastics Market
Others
Liquid-Cooled Heat Sink Market
Others
Gas Radiators Market
Others
Fresh Durian Market
Others
Global Hardware As a Service (Haas) Market
Others
Smart Home Technologies Market
Others
Magnetic Stripe Readers Market
Others
Global Sports and Fitness Wears Market
Others
Photo Booth/Kiosk Market
Others
Digital Tattoos Market
Others
Global Maritime Freight Transport Market
Others
India Smart Home Market
Others
Evidence Management Market
Others
North America Commercial Vehicles Lubricants Market