
 Post Consumer Recycled Bottles Market | 2026-2036
Post Consumer Recycled Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Post Consumer Recycled Bottles Market Analytics
Food and beverage packaging is rebalancing toward post-consumer recycled content as brand owners face compliance deadlines. Veolia leverages its European sorting infrastructure to supply food-grade rPET flake directly to bottlers. Eastman Chemical Company anchors molecular recycling capacity that converts colored and contaminated bottles into virgin-quality polyester. Suez SA competes through deposit-return scheme operations across multiple EU member states.
Post consumer recycled bottles are discarded polymer containers collected through municipal and commercial waste streams, then sorted, washed, and processed into flake or pellet for remanufacturing. The feedstock must achieve less than 200 ppm contamination to qualify for food-contact applications under EFSA safety evaluations. PET dominates material flows due to established bottle-to-bottle recycling economics and FDA letter of no objection pathways. HDPE trails in volume but sustains premium pricing in household and personal care applications where color consistency requirements are less stringent. The food and beverage end user segment leads absolute consumption, while cosmetics represents a faster-growing niche as luxury brands adopt ocean-bound and traceable recycled content claims.
The EU Green Deal's Packaging and Packaging Waste Regulation sets mandatory recycled content minimums that reshape demand trajectories across member states. FDA letters of no objection for specific recycling processes determine which technologies qualify for US food-contact applications, creating a bifurcated compliance landscape. ECHA's REACH restrictions on certain additive legacy chemicals in recovered plastics add another layer of material qualification. Stakeholders must monitor how evolving extended producer responsibility fee structures alter collection economics and whether chemical recycling outputs gain mass-balance certification acceptance under emerging EU frameworks.
Market Dynamics
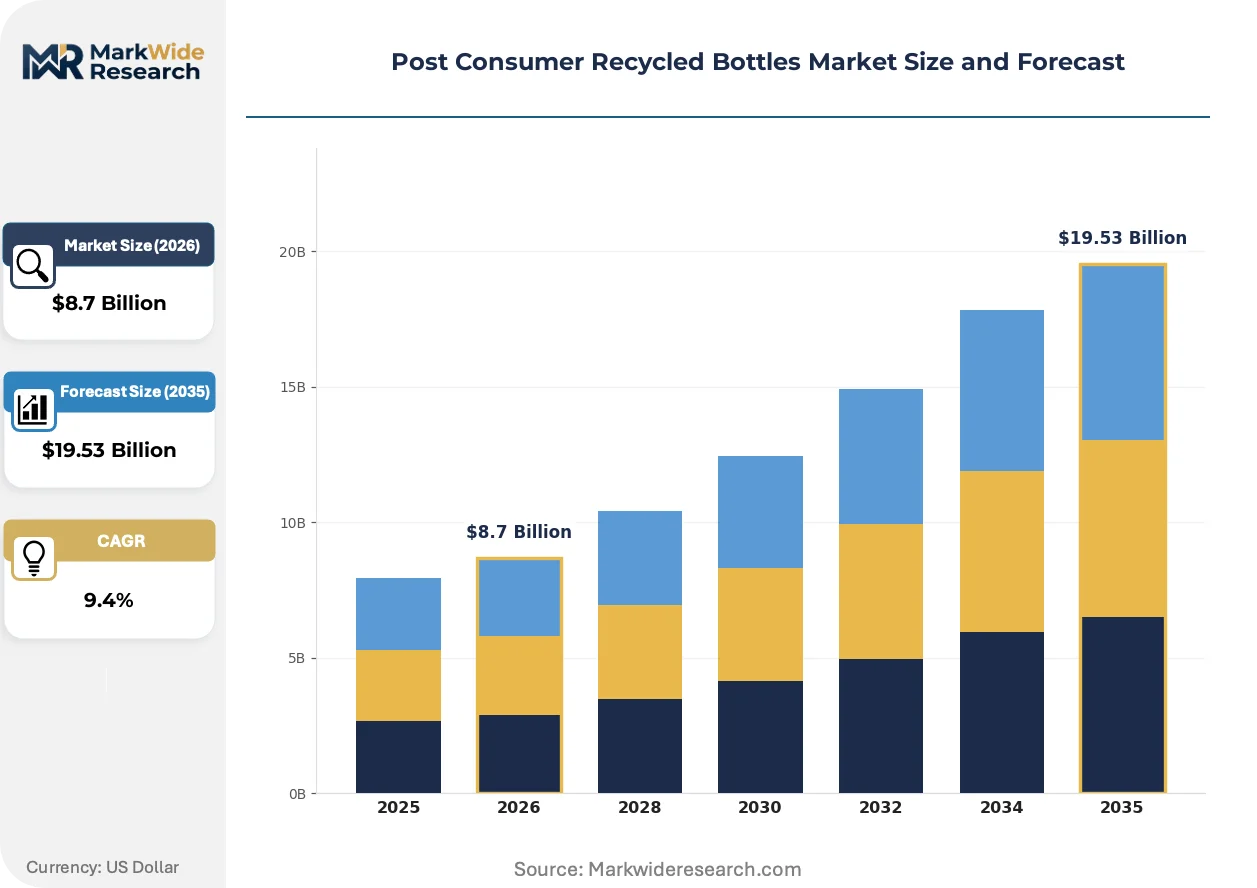
EU Green Deal packaging mandates are compressing timelines for food-grade rPET qualification, forcing bottlers to secure flake supply before 2030 compliance deadlines lock in. This regulatory pressure is restructuring collection infrastructure investments and sorting technology deployment across member states.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds for beverage containers create guaranteed offtake demand. Bottlers must source 25 percent recycled PET by 2025, escalating to 30 percent by 2030.
- Deposit-return scheme expansion:France, Germany, and Italy are extending DRS coverage to all beverage formats. Higher collection rates improve feedstock availability for food-grade recycling streams.
- Cosmetics sector premium positioning:Luxury personal care brands are adopting ocean-bound and traceable recycled content claims. This segment pays material premiums that subsidize collection economics.
Market Restraints
- Food-grade flake supply concentration:Western European sorting infrastructure dominates qualified output. Bottlers in Eastern Europe face supply deficits and transport cost premiums.
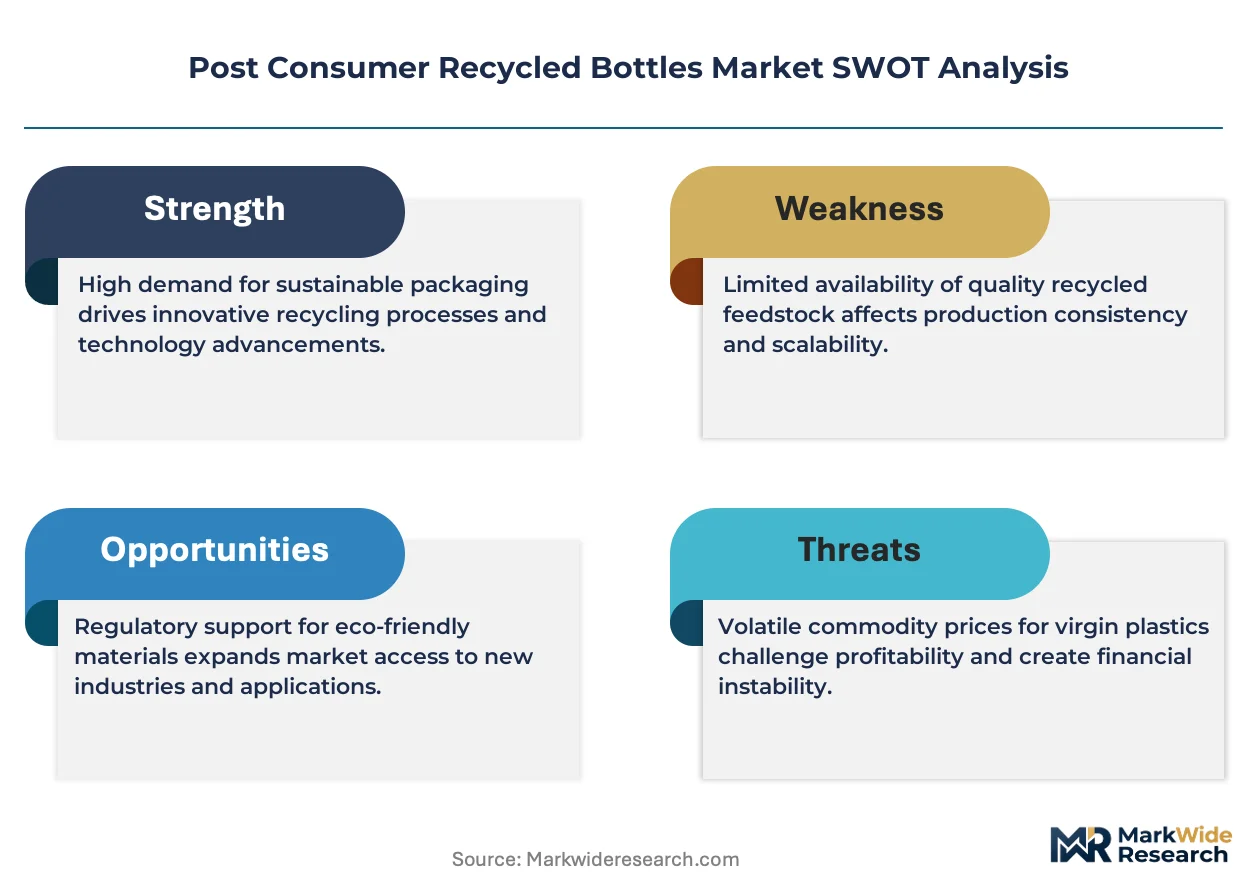
- Legacy additive contamination:ECHA REACH restrictions on certain recovered plastic additives disqualify substantial post-consumer volumes from food-contact pathways. Remediation requires costly washing and testing protocols.
- HDPE color inconsistency:Household and personal care applications demand precise color matching. Mixed-color bale sourcing limits HDPE adoption in premium cosmetic packaging.
Strategic Opportunities
- Polish and Romanian collection network buildout:Underpenetrated municipal waste streams in these EU member states offer virgin feedstock territory. Early infrastructure investors capture long-term supply contracts.
- Molecular recycling certification:Mass-balance frameworks under emerging EU methodologies would validate chemical recycling outputs for food-contact claims. Eastman Chemical Company and competitors are positioning for this regulatory opening.
- Direct-to-bottler flake supply contracts:Bypassing compounder intermediaries reduces cost stack and improves traceability. Veolia and Suez SA are piloting this channel innovation.
Industry Challenges
- EFSA safety evaluation timelines:Novel recycling processes require 18-24 month regulatory review before food-contact authorization. Process developers face working capital strain during qualification periods.
- Optical sorting technician shortage:Advanced NIR and robotics systems require specialized maintenance skills. Training pipelines lag equipment deployment in expanding facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post Consumer Recycled Bottles Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PET, HDPE, PVC, LDPE Application: Beverage Packaging, Household Products, Personal Care, Food Containers Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale End User: Food & Beverage, Healthcare, Cosmetics, Consumer Goods |
| Companies Covered | Veolia, Suez SA, REMONDIS SE & Co. KG, WM Intellectual Property Holdings, L.L.C., Republic Services, Waste Connections, Biffa, Clean Harbors, Inc., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post Consumer Recycled Bottles Market Evolving Landscape
Sorting and decontamination technologies are advancing faster than regulatory frameworks can certify them, creating a qualification backlog that favors early movers with established FDA letters of no objection. This technical-regulatory gap is determining competitive positioning.
Advanced optical sorting systems using artificial intelligence and robotics are expanding into municipal material recovery facilities across Europe. These systems identify and eject non-target polymers with precision that manual sorting cannot match. Bottlers in Germany and France are demanding this grade of flake purity, and suppliers without upgraded lines are losing contract renewals.
REACH restrictions on legacy chemical additives in recovered plastics are tightening material qualification standards. ECHA evaluations are disqualifying specific additive chemistries from food-contact applications regardless of washing intensity. Processors must either source cleaner bales or invest in molecular recycling that breaks down polymer chains entirely.
Brand procurement teams are consolidating supplier lists around certified circular content claims. Cosmetics and beverage buyers now require third-party chain-of-custody documentation for recycled content marketing. This certification-driven preference shift concentrates volume with processors that invested early in traceability infrastructure, particularly in France and the Netherlands where luxury brand headquarters cluster.
Post Consumer Recycled Bottles Market Segmentation
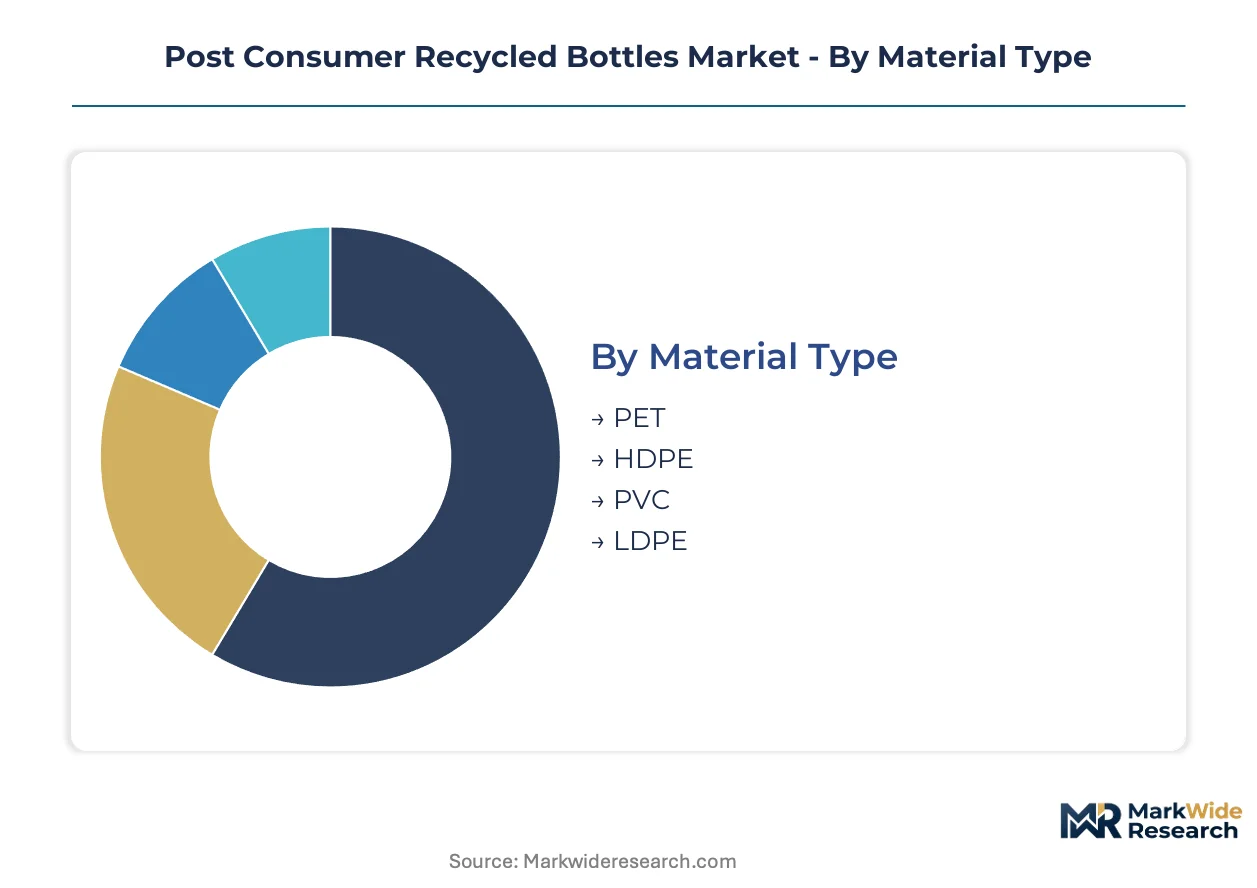
Post consumer recycled bottles flow through distinct material and channel pathways that determine contamination thresholds, pricing tiers, and regulatory qualification. Segmentation reveals where food-grade premiums concentrate versus commodity-grade volumes.
Material Type:
PET operates as a standalone recycling stream with dedicated bottle-to-bottle infrastructure, while other polymers embed into broader plastic recovery systems with different purity economics.
- PET:Clear thermoplastic polyester with established decontamination protocols for food-contact applications. German and French bottlers under EU Green Deal mandates drive qualified flake demand for beverage packaging. EFSA safety evaluations govern authorization timelines for novel recycling processes.
- HDPE:Stiff polyethylene with natural color variation that limits premium cosmetic applications. Household and personal care brands in the Netherlands accept mixed-color feedstock for non-food containers where visual consistency matters less.
- PVC:Chlorinated polymer with restricted food-contact pathways due to additive legacy concerns. Construction and industrial applications absorb most recovered volumes.
- LDPE:Flexible polyethylene common in squeeze bottles and film applications. Lower recycling economics push material toward downcycling into non-packaging uses.
PET leads volumes today; HDPE is gaining share fastest in household and personal care segments.
Application:
Cost tier stratification separates food-contact premiums from industrial-grade commodity pricing across end-use categories.
- Beverage Packaging:Rigid bottle formats requiring less than 200 ppm contamination under EFSA evaluations. Deposit-return schemes in Germany, France, and Italy channel clean feedstock directly into this highest-value pathway.
- Food Containers:Trays, tubs, and clamshells with comparable purity demands to beverage applications. French supermarkets are piloting dedicated collection streams for this format.
- Household Products:Cleaning and detergent bottles where color inconsistency is acceptable. Eastern European processors supply this segment with lower-grade flake.
- Personal Care:Shampoo and cosmetic bottles with emerging traceability requirements. Luxury brand headquarters in France and the Netherlands are driving chain-of-custody certification adoption.
Beverage packaging commands the steepest price premiums; personal care represents the most rapid certification-driven expansion.
Distribution Channel:
Customer type determines traceability depth and contract structure, with direct relationships favoring food-grade qualification and intermediaries handling commodity grades.
- Direct Sales:Long-term supply contracts between processors and bottlers with embedded quality specifications. Veolia and Suez SA are piloting direct-to-bottler flake channels to reduce cost stack.
- Wholesale:Aggregated volumes through compounder intermediaries serving mid-tier packaging converters. This channel dominates HDPE and LDPE flows where traceability requirements are minimal.
- Retail:Limited role for post-consumer recycled bottles given food-contact regulatory barriers; primarily serves non-food household applications.
- E-commerce:Niche channel for specialty recycled content claims in cosmetics and premium consumer goods.
Direct sales capture the highest margins; wholesale channels move the greatest tonnage.
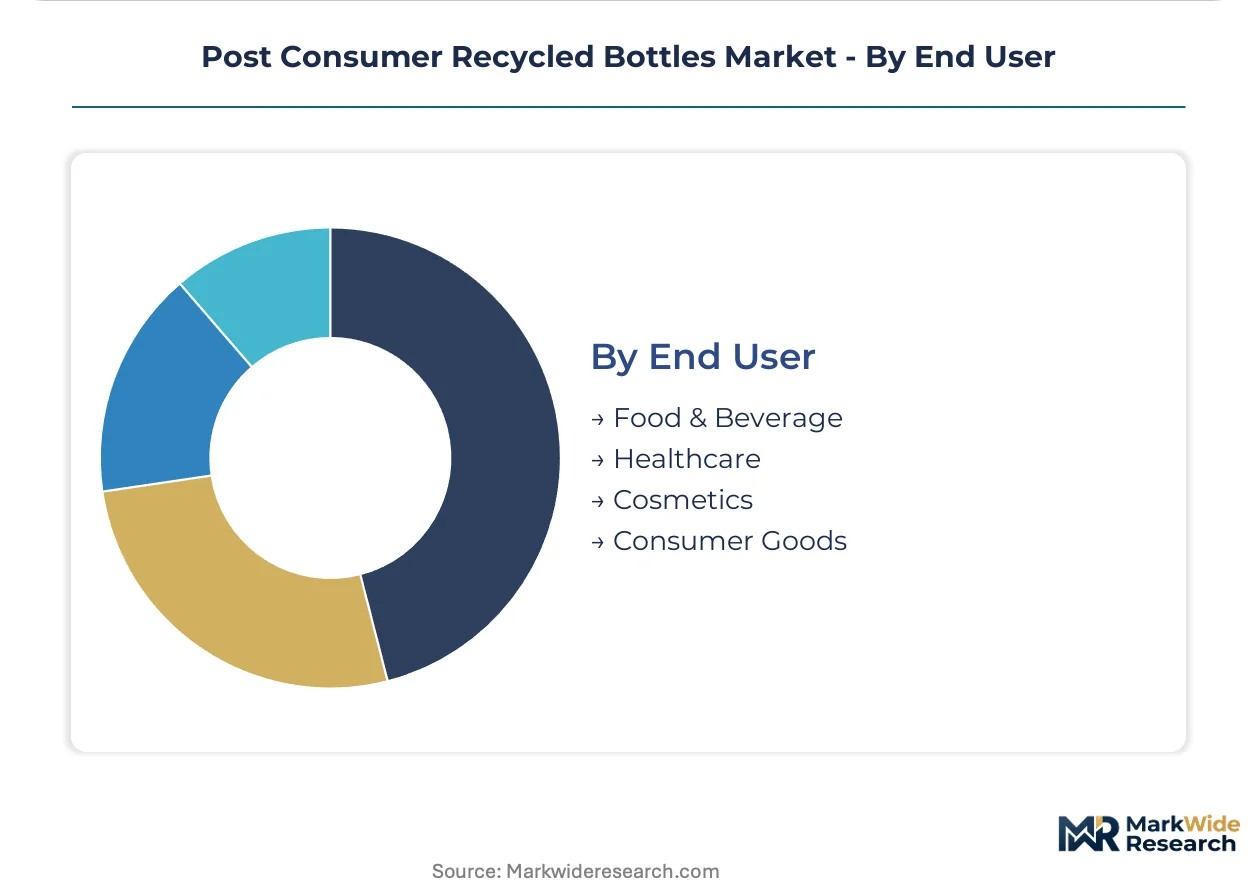
End User:
Supply concentration in Western European sorting infrastructure shapes which end users secure qualified feedstock versus facing supply deficits.
- Food & Beverage:Largest absolute consumption segment with mandatory recycled content thresholds under EU Packaging and Packaging Waste Regulation. Bottlers must secure 25 percent rPET by 2025, escalating to 30 percent.
- Cosmetics:Premium positioning around ocean-bound and traceable recycled content claims. This segment pays material premiums that subsidize collection economics for lower-grade streams.
- Consumer Goods:Durable product packaging with flexible material specifications. Eastern European manufacturers source through wholesale channels with minimal certification overhead.
- Healthcare:Emerging demand for pharmaceutical-grade recycled content with stringent purity requirements that few processors currently meet.
Food and beverage dominates current offtake; cosmetics is climbing the fastest on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REMONDIS SE & Co. KG anchors European collection infrastructure through its German operational base, channeling post-consumer PET into food-grade recycling streams that supply beverage bottlers across the continent.
Germany
Deposit-return scheme operations generate the continent's cleanest PET bale feedstock, with REMONDIS operating sorting facilities that achieve sub-200 ppm contamination thresholds required for EFSA food-contact authorization. The country's national packaging regulator enforces strict extended producer responsibility fee structures that incentivize high-purity collection. Bavarian chemical recycling clusters near Leipzig are piloting molecular decontamination units for colored and contaminated bottle streams.
France
Veolia leverages its national sorting network to supply rPET flake directly to Paris-headquartered luxury beverage brands facing 2025 EU Green Deal compliance deadlines. ECHA REACH restrictions on legacy additives in recovered plastics have triggered processor investments in advanced washing protocols. The Île-de-France region concentrates cosmetics brand procurement teams demanding third-party chain-of-custody certification for recycled content claims.
United States
FDA letters of no objection govern which recycling technologies qualify for food-contact applications, creating a bifurcated compliance landscape separate from European EFSA pathways. WM Intellectual Property Holdings and Republic Services operate material recovery facilities across the Midwest and Southeast that supply domestic reprocessors. California's state-level recycled content mandates for beverage containers are compressing timelines for rPET qualification ahead of federal action.
Italy
Deposit-return scheme expansion to all beverage formats is improving feedstock availability for food-grade recycling streams in a market previously dependent on mixed municipal collection. Suez SA competes through DRS operations across multiple EU member states including Italian municipal contracts. Northern industrial clusters near Milan are upgrading optical sorting capacity to meet German and French bottler purity specifications.
Poland
Underpenetrated municipal waste streams offer virgin feedstock territory for infrastructure investors seeking long-term supply contracts with Western European processors. The country's national environmental regulator is aligning collection standards with EU Packaging and Packaging Waste Regulation thresholds. Silesian recycling facilities are expanding NIR sorting lines to capture PET volumes currently landfilled or downcycled.
Post Consumer Recycled Bottles Market Competitive Landscape
Capacity expansion dominates the current landscape as processors race to secure EFSA food-grade authorization before 2030 compliance deadlines lock in supply relationships. The vendor base concentrates around integrated waste management conglomerates with captive collection infrastructure and specialized chemical recyclers pursuing molecular decontamination certification. Three archetypes define competitive positioning: municipal contract operators with DRS access, chemical recycling technology licensors, and direct-to-bottler flake suppliers. M&A activity and strategic partnerships between collection networks and beverage brands are accelerating as bottlers seek supply security.
Within the integrated infrastructure tier, Veolia and Suez SA exemplify the collection-to-flake model that bypasses compounder intermediaries, while Eastman Chemical Company anchors the chemical recycling vector pursuing mass-balance certification under emerging EU frameworks. These three entities represent distinct strategic pathways—municipal contract leverage, direct channel innovation, and molecular recycling scale—that are restructuring competitive positioning as regulatory timelines compress.
| Leading Market Players |
|---|
| Veolia |
| Suez SA |
| REMONDIS SE & Co. KG |
| WM Intellectual Property Holdings, L.L.C. |
| Republic Services |
| Waste Connections |
| Biffa |
| Clean Harbors, Inc. |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
Family-owned municipal contract operators across Germany and France anchor collection infrastructure that channels post-consumer PET into food-grade streams, their long-term concession agreements insulating flake pricing from spot-market volatility while compressing margins for independent reprocessors lacking captive feedstock.
Pricing Analysis
Distributor margin layers in wholesale channels absorb 12-18 percent of final flake cost, while direct-to-bottler contracts eliminate this stack entirely. Three-tier pricing structure across food-grade, industrial-grade, and downcycled tiers reflects EFSA certification status and contamination thresholds. Pricing pressure stems from Eastern European bottlers competing for limited Western European qualified supply. Mid-tier packaging converters show highest price sensitivity; luxury cosmetics brands demonstrate least.
Supply Chain Analysis
Direct-to-bottler channels handle hyperscale beverage demand from German and French brand owners, bypassing compounder intermediaries that traditionally aggregated fragmented volumes. Feedstock concentrates in Germany, France, and Italy through deposit-return scheme operations. Raw material flows draw from municipal collection networks, commercial waste brokers, and ocean-bound plastic recovery initiatives. Single-source vulnerability runs through REMONDIS and Veolia sorting infrastructure controlling qualified flake output. Distribution runs through long-term offtake contracts with embedded quality specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The post-consumer recycled bottles market functions as a regulatory compounder where EU Green Deal packaging mandates create demand acceleration that outpaces supply qualification timelines.
For Market Incumbents: Cement food-grade authorization moats by accelerating EFSA novel process submissions before 2030 compliance deadlines lock in supply relationships. Secure backward integration into underpenetrated Polish and Romanian collection networks to capture virgin feedstock territory. Molecular recycling certification investment represents the critical lever against additive contamination threats from ECHA REACH restrictions. For New Entrants and Emerging Players: Direct-to-brand digital platforms offer bypass routes around incumbent compounder channels, enabling traceability documentation that commands premium positioning. Target cosmetics procurement teams in Paris and Amsterdam headquarters with ocean-bound plastic certification claims. Polish municipal contract bidding represents the most penetrable white-space geography with aligning national standards to EU Packaging and Packaging Waste Regulation thresholds. For Investors and Strategic Acquirers: Valuations sit cheapest among Eastern European collection network operators lacking Western European food-grade qualification pathways. Five-to-ten year viability hinges on mass-balance framework adoption validating chemical recycling outputs. The specific signal to watch is EFSA authorization timeline compression for novel decontamination technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade Recycling Certification | EFSA safety evaluation authorization unlocks beverage packaging premiums under EU Green Deal mandates. |
| Collection Network Expansion | Polish and Romanian municipal contracts offer virgin feedstock territory with long-term supply security. |
| Molecular Recycling Scale-Up | Mass-balance certification under emerging EU frameworks validates chemical recycling for food-contact claims. |
| Direct-to-Bottler Channel Development | Bypassing compounder intermediaries reduces cost stack and improves traceability for luxury brand procurement. |
| Deposit-Return Scheme Operations | DRS coverage expansion in France, Germany, and Italy channels clean feedstock into highest-value recycling streams. |
Research Methodology
Coverage spans Western Europe, Eastern Europe, and North America, with primary inputs from each region combined with secondary validation. Interviews with sorting facility operators, beverage procurement directors, regulatory affairs specialists, and waste management contract managers informed supply-side and demand-side dynamics. Secondary sources included EFSA safety evaluation databases, EU Packaging and Packaging Waste Regulation implementation documents, ECHA REACH restriction updates, and national extended producer responsibility fee structures. Bottom-up volume modeling triangulated against top-down regulatory mandate analysis.
Granularity-level framing modeled material type at polymer-specific contamination thresholds, application at food-contact versus industrial-grade tiers, and distribution channel at direct versus intermediary structures. End-user segmentation captured beverage packaging mandates, cosmetics premium positioning, and healthcare emerging demand. CAGRs derived from regulatory timeline compression effects and collection infrastructure deployment schedules. Feedstock availability curves and EFSA authorization backlogs served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for molecular recycling mass-balance certification would alter the outlook. Forecasts reflect assumptions about deposit-return scheme expansion timelines and EFSA evaluation throughput capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Nanomedicine for Drug Delivery Market
Others
Latin America Fire Sprinklers Market
Others
Cashew Kernel Market
Others
Global Multi-Access Edge Computing Market
Others
Vegetable Carbon Market
Others
Global Pumpkin Candles Market
Others
South America Automotive LED Lighting Market
Others
Enterprise Video Market
Others
Belt Press Filter Market
Others
Digital Audio Decoders Market
Others
Badminton Apparel Market
Others
Digital Signage Media Player Market
Others
Nyerereite Market
Others
Canada 3D Printing Construction Market
Others
Global Multi Domain Controller Market
Others
North America Thermoformed Plastics Market