
 North America Orange Market | 2026-2036
North America Orange Market Size, Share, and Industry Trends Forecast 2026-2036
North America Orange Market Analytics
Juice manufacturers are redrawing procurement priorities across the North America orange supply chain, shifting volume toward premium extraction-grade fruit and away from commodity fresh channels. Wonderful Citrus dominates branded retail shelf space through year-round varietal scheduling. Sunkist Growers anchors cooperative marketing strength across Western growing regions. Citrosuco leverages Brazilian-origin processing expertise to compete in North American concentrate supply.
Oranges are citrus fruits of the species Citrus sinensis, typically harvested at soluble solids-to-acid ratios between 10:1 and 20:1 depending on intended use, with juice extraction requiring higher Brix levels than fresh consumption. The fruit serves commercial purposes spanning fresh retail, beverage manufacturing, and foodservice ingredient applications. Navels and Valencias together occupy the core volume positions, with Navels commanding fresh premium positioning and Valencias sustaining juice processing dominance. Organic certification under USDA Grade A standards is capturing margin expansion as retailers tighten provenance requirements.
The USDA Agricultural Marketing Service sets grading and size standards that determine access to federal procurement channels and export eligibility. The FDA enforces juice Hazard Analysis and Critical Control Points rules that shape pasteurization and labeling obligations for processors. Mexico's national food safety authority coordinates cross-border phytosanitary protocols that govern seasonal import windows. Stakeholders must monitor how water allocation rulings across the Colorado River basin and Florida aquifer districts reshape planting decisions and regional cost structures.
Market Dynamics
Water scarcity rulings across the Colorado River basin and Florida aquifer districts are forcing planting decisions toward drought-tolerant rootstocks and pressuring regional cost structures throughout the supply chain.
Growth Catalysts
- USDA National Organic Program:Retailers tightening provenance requirements are expanding certified acreage premiums as organic Grade A standards capture margin expansion across extraction-grade channels.
- Cold-pressed extraction technology:Juice manufacturers are redirecting procurement volumes toward premium not-from-concentrate varieties that command shelf space differentiation.
- Sonora corridor expansion:Mexico's phytosanitary protocol coordination is extending seasonal import windows and diversifying supply origins beyond California and Florida.
Market Restraints
- Huanglongbing vector pressure:Asian citrus psyllid spread through Texas and Louisiana is elevating input costs for grove management and tree replacement cycles.
- Florida aquifer depletion:Water allocation rulings are compressing bearing acreage in the Indian River and Ridge production zones.
- Concentrate substitution:Brazilian-origin not-from-concentrate imports are displacing domestic processing margins for Valencia-grade fruit.
Strategic Opportunities
- FDA juice safety standard evolution:Pasteurization and labeling obligation updates are creating compliance service demand for mid-scale processors seeking federal channel access.
- Foodservice ingredient channel:Fresh-cut and zest applications for craft beverage manufacturing are opening volume contracts outside traditional retail procurement.
- Desert citrus expansion:Arizona and California Imperial Valley microclimates are enabling off-season Navel production that extends branded year-round scheduling.
Industry Challenges
- Phytosanitary certification timelines:Cross-border seasonal window approvals require advance coordination with Mexico's national food safety authority that delays harvest-to-export velocity.
- Rootstock propagation bottlenecks:Drought-tolerant citrus variety nursery capacity constraints are extending orchard replanting cycles and delaying yield recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Orange Market |
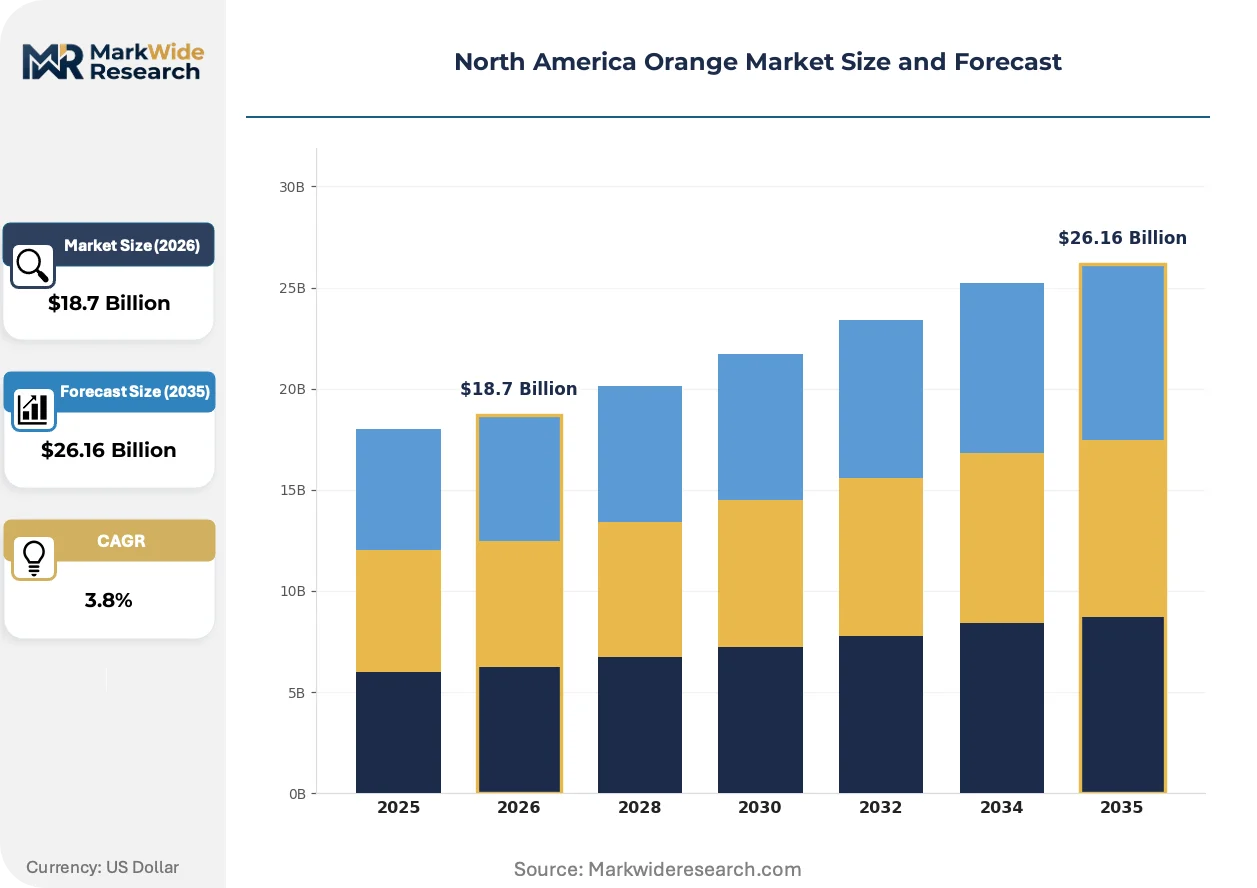
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navels, Valencias, Blood Oranges, Cara Cara End User: Fresh Produce Retailers, Juice Manufacturers, Food Services, Exporters Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Wholesale Quality Grade: USDA Grade A, USDA Grade B, Organic, Conventionally Grown |
| Companies Covered | Citrus World, Citrosuco, Sunkist Growers, Tropicana Products, Florida's Natural Growers, Sun Pacific, Wonderful Citrus, Dole Food Company, Fresh Del Monte Produce, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Orange Market Evolving Landscape
Extraction technology and certification protocols are redrawing procurement hierarchies across fresh and processed channels, compressing legacy concentrate margins while elevating traceability premiums.
Near-infrared Brix sensors installed at receiving stations are supplanting manual soluble solids testing. Large-scale juice processors in Florida's citrus belt are adopting inline spectroscopy for real-time payment grading. This precision is compressing price arbitration disputes between growers and handlers while accelerating load turnaround times.
The FDA's evolving juice Hazard Analysis and Critical Control Points enforcement is mandating enhanced pasteurization documentation for all interstate shipments. Processors must now maintain continuous temperature logging that extends from extraction through distribution. Mid-scale operators in California's Central Valley are responding by consolidating under cooperative inspection protocols to spread compliance overhead.
Retailers are unbundling year-round supply contracts into varietal-specific procurement windows that match consumer preference cycles. Grocery chains are replacing blanket orange category agreements with separate Navel and Valencia purchase schedules. This pattern is most visible in Texas and Arizona markets where Mexican import timing creates overlapping origin options.
North America Orange Market Segmentation
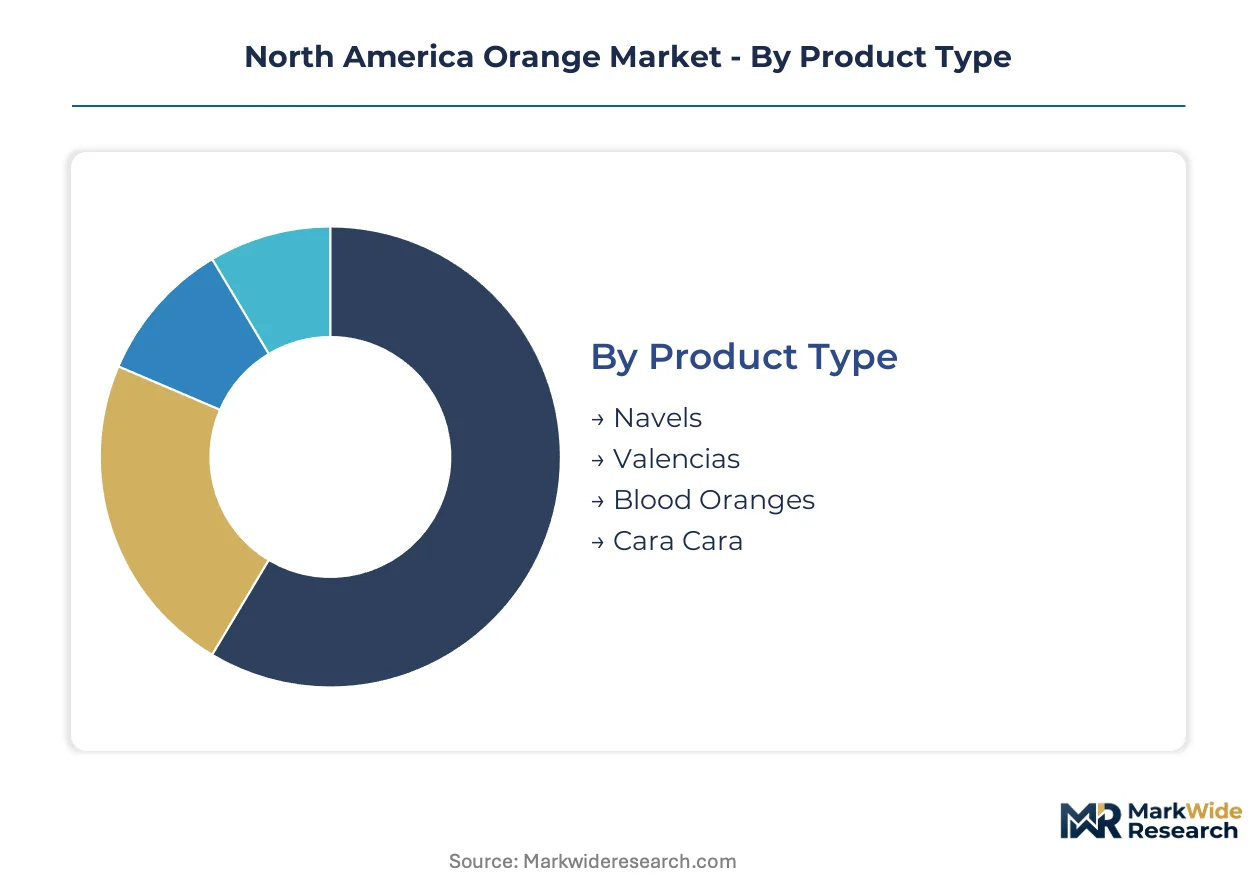
Orange procurement patterns diverge sharply across product types and end-use channels, with extraction-grade specifications commanding premium contracting terms distinct from fresh retail logistics. Quality certification tiers now function as primary margin levers as retailers tighten provenance documentation requirements.
Product Type:
Margin pools concentrate in varietals that sustain year-round shelf presence and command extraction-grade premiums.
- Navels:Seedless morphology and easy-peel rind structure define this fresh-market dominant. California's Central Valley and Arizona's desert microclimates anchor supply for grocery chains requiring consistent winter-spring availability.
- Valencias:Thin rind and high juice content with Brix levels exceeding 12 degrees suit beverage manufacturing specifications. Florida's citrus belt maintains processing dominance despite aquifer pressure on bearing acreage.
- Blood Oranges:Anthocyanin pigmentation creates specialty positioning for premium fresh and juice channels. Limited domestic production concentrates in Texas and California coastal zones.
- Cara Cara:Pink-fleshed navel variant with lower acidity profiles targets differentiated retail placement. California growers have expanded planted area to capture Valentine's Day and Easter promotional windows.
Navels hold installed capacity. Cara Cara is rotating up the share rankings.
End User:
Volume concentration tracks diverging specification requirements between fresh handling and extraction processing.
- Fresh Produce Retailers:Cosmetic grading standards and cold-chain integrity dominate procurement contracts. Mexican Sonora corridor imports extend California's seasonal gaps for Texas and Arizona grocery networks.
- Juice Manufacturers:Soluble solids-to-acid ratios and oil content specifications determine price premiums. Cold-pressed extraction technology is redirecting procurement toward not-from-concentrate grade fruit.
- Food Services:Fresh-cut and zest applications for craft beverage manufacturing are opening volume contracts outside traditional retail procurement channels.
- Exporters:Phytosanitary certification timelines with Mexico's national food safety authority govern seasonal window approvals that delay harvest-to-export velocity.
Juice manufacturers maintain the largest contract volumes. Food services are climbing the fastest.
Distribution Channel:
Logistics infrastructure investment separates channels by temperature control requirements and lot traceability depth.
- Supermarkets:Year-round supply contracts are unbundling into varietal-specific procurement windows that match consumer preference cycles. Chains now schedule separate Navel and Valencia purchase agreements.
- Farmers' Markets:Direct-to-consumer positioning captures organic certification premiums without wholesale margin compression. California and Florida growers leverage regional brand recognition.
- Online Retail:Subscription box models aggregate specialty varieties for home delivery. Cold-chain packaging requirements elevate per-unit logistics costs above traditional retail.
- Wholesale:Foodservice distributors and juice processors source through terminal market auctions and direct grove contracts. Volume aggregation spreads FDA juice safety compliance overhead.
Supermarkets anchor throughput infrastructure. Online retail is expanding most quickly.
Quality Grade:
Certification tiers function as pricing stratification mechanisms with widening premium spreads.
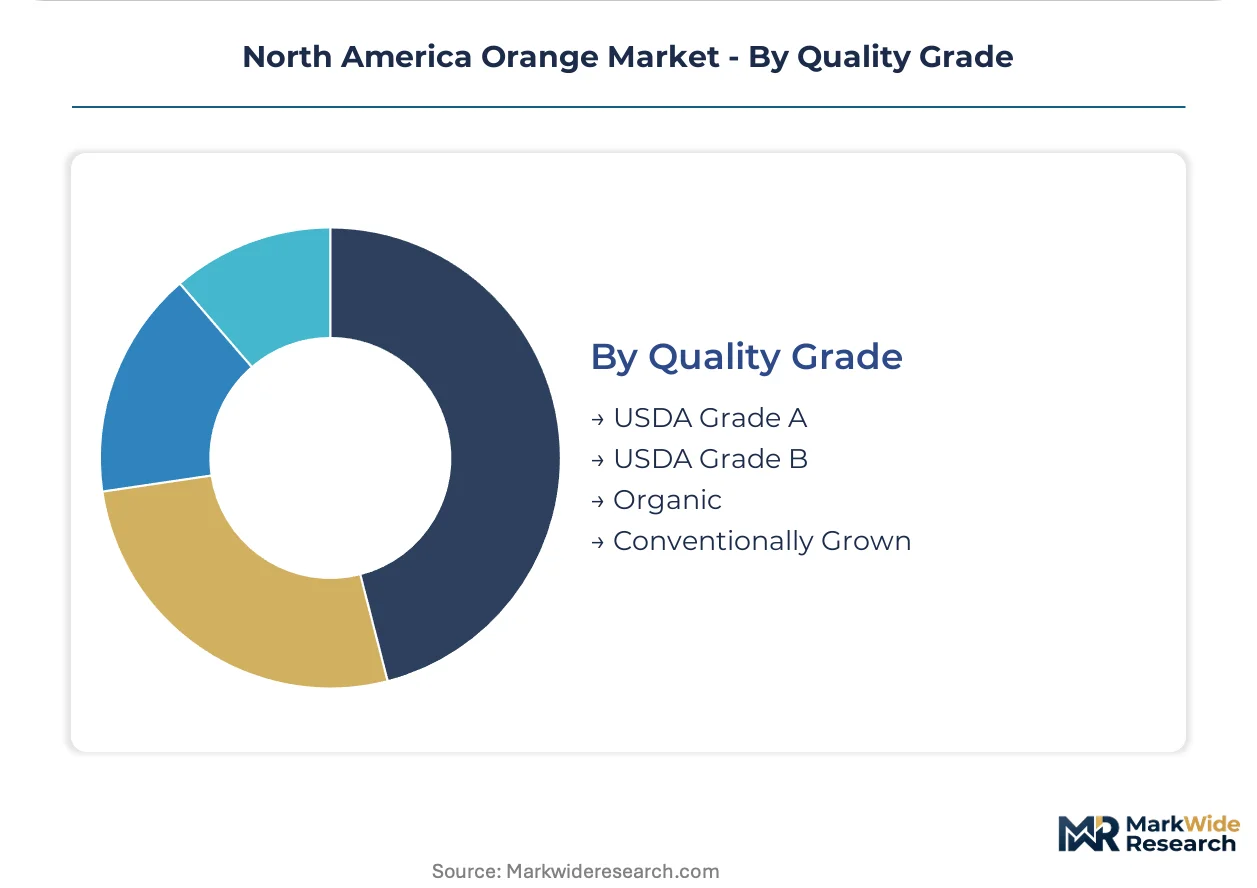
- USDA Grade A:Cosmetic uniformity and minimum size standards determine federal procurement eligibility and export access. Florida and California handlers maintain separate packing lines for Grade A segregation.
- USDA Grade B:Processing-grade fruit with blemish tolerance suits juice extraction where appearance is irrelevant. Lower price points reflect reduced handling care requirements.
- Organic:USDA National Organic Program certification captures margin expansion as retailers tighten provenance requirements. Certified acreage premiums are expanding across extraction-grade channels.
- Conventionally Grown:Standard agricultural input protocols dominate volume production. Huanglongbing vector management elevates input costs for grove management regardless of certification tier.
USDA Grade A holds established premium positioning. Organic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and the Port of Los Angeles together anchor North American citrus import infrastructure, handling the majority of Mexican and South American fruit entering the United States. Interstate 10 and Union Pacific rail corridors link these ports to cold-chain distribution networks spanning the Southwest and Midwest.
United States
California's Central Valley and Florida's citrus belt concentrate domestic production capacity, with Navels dominating winter-spring fresh supply and Valencias sustaining juice processing. The USDA Agricultural Marketing Service enforces Grade A standards that determine federal procurement eligibility and export access. Fresno County handlers operate separate packing lines for organic certification segregation.
Mexico
The Sonora corridor extends seasonal import windows through phytosanitary protocol coordination with the national food safety authority, supplying Texas and Arizona grocery networks during California production gaps. Mexican growers capture expanding shelf space through year-round varietal scheduling. Hermosillo-based exporters leverage proximity to Nogales crossing infrastructure.
Canada
Ontario and Quebec retail chains source through Vancouver and Montreal port terminals, with distribution concentrating in Toronto and Montreal metropolitan cold-chain hubs. Health Canada and the PMRA coordinate phytosanitary import requirements with USDA counterparts. British Columbia's Lower Mainland serves as secondary entry point for Pacific-origin shipments.
North America Orange Market Competitive Landscape
Concentration sits with integrated grower-processors and cooperative marketing organizations that control year-round supply scheduling. Three strategic archetypes define competitive positioning: branded retail specialists owning shelf space through varietal diversification, cooperative handlers aggregating volume across member groves, and multinational processors leveraging cross-border supply arbitrage. Capacity expansion and backward integration into captive grove operations represent the dominant competitive moves.
Among branded retail specialists, Wonderful Citrus and Sunkist Growers exemplify divergent structural approaches to market access. Wonderful Citrus operates as a vertically integrated grower-marketer controlling production through owned acreage. Sunkist Growers represents the cooperative archetype, pooling output across member farms to achieve scale in procurement negotiations. Citrosuco anchors the multinational processor tier, applying Brazilian-origin extraction expertise to North American concentrate supply.
| Leading Market Players |
|---|
| Citrus World |
| Citrosuco |
| Sunkist Growers |
| Tropicana Products |
| Florida's Natural Growers |
| Sun Pacific |
| Wonderful Citrus |
| Dole Food Company |
| Fresh Del Monte Produce |
| Others |
Value Network & Pricing Analysis
Consolidated packing infrastructure across California's Central Valley and Florida's citrus belt generates scale efficiencies that compress unit handling costs while elevating price floors for smaller handlers. Water scarcity rulings across the Colorado River basin and Florida aquifer districts force supply consolidation toward drought-tolerant rootstock operations, concentrating procurement leverage among integrated grower-processors.
Pricing Analysis
Volume-discount tiering structures separate contract-based long-term offtake agreements for juice manufacturers from spot-market transactions for fresh produce retailers. Price differentiation rests on USDA Grade A certification and organic status under the National Organic Program, with certified acreage capturing widening premiums. Cost compression in processing-grade channels is intensifying because Brazilian-origin not-from-concentrate imports displace domestic Valencia margins. Fresh produce retailers exhibit highest price sensitivity due to cosmetic grading standards, while juice manufacturers prioritize soluble solids specifications over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate juice manufacturer procurement, with handlers maintaining cold-storage reserves to bridge seasonal gaps, whereas fresh retailers favor just-in-time delivery to preserve shelf-life margins. Geographic supply concentrates in the United States, Mexico, and Brazil. Raw material dependencies center on phosphate fertilizers, irrigation water allocations, and certified rootstock propagation. Single-source vulnerability runs through Florida's citrus belt concentration for Valencia processing. Distribution runs through terminal market auctions, direct grove contracts, and cooperative pooling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America orange market sits in early-cycle expansion as cold-pressed extraction technology redirects procurement volumes toward premium not-from-concentrate varieties, extending adoption beyond traditional concentrate processors.
For Market Incumbents: Compound year-round varietal scheduling advantages by extending branded shelf space through Arizona and California Imperial Valley microclimate expansion. Deepen backward integration into captive grove operations to secure drought-tolerant rootstock supply ahead of nursery propagation bottlenecks. Defend against Brazilian-origin concentrate substitution by locking long-term offtake contracts with foodservice craft beverage channels. For New Entrants and Emerging Players: Lead with specialty varietal differentiation targeting blood orange and Cara Cara pink-fleshed segments where limited domestic production concentrates premium positioning. Penetrate Texas and Arizona grocery networks through Sonora corridor import timing coordination that exploits California production gaps. Deploy subscription box direct-to-consumer models to capture organic certification premiums without wholesale margin compression. For Investors and Strategic Acquirers: Cooperative marketing organizations with established phytosanitary protocol coordination represent the most defensible acquisition archetype, given their locked access to seasonal import windows and federal procurement channels. Long-term viability over the projection horizon hinges on water rights security and rootstock variety licensing. Watch for Huanglongbing vector spread crossing threshold levels that trigger grove replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Grove Operations | Secures drought-tolerant rootstock supply ahead of USDA Agricultural Marketing Service grading deadlines. |
| Cold-Pressed Extraction Technology Deployment | Captures FDA juice safety compliance premiums through enhanced pasteurization documentation systems. |
| Sonora Corridor Import Window Expansion | Extends year-round varietal scheduling through Mexico's national food safety authority protocol coordination. |
| Organic Certification Investment | Locks USDA National Organic Program premiums as retailers tighten provenance documentation requirements. |
| Foodservice Ingredient Channel Development | Opens volume contracts for fresh-cut and zest applications outside traditional retail procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA Agricultural Marketing Service grading records, FDA juice Hazard Analysis and Critical Control Points enforcement data, and customs import documentation. Primary interviews engaged grove operations managers, juice processor procurement directors, retail category buyers, cooperative marketing executives, and phytosanitary compliance officers. Secondary validation drew from USDA National Agricultural Statistics Service acreage reports, Florida Department of Citrus production data, and California Agricultural Statistics Review publications. Bottom-up acreage and yield modeling triangulates against top-down value-chain aggregation.
Segmentation dimensions modeled include product type, end user, distribution channel, and quality grade across the analysis window. The analytical framework applies elasticity-adjusted volume projections to derive CAGRs, incorporating irrigation water allocation rulings, Huanglongbing vector pressure indices, and cold-pressed technology adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Mexican phytosanitary protocol coordination or accelerated Florida aquifer depletion would require recalibration. Forecasts reflect assumptions regarding rootstock propagation capacity recovery and Brazilian import tariff stability. Revision becomes warranted when Huanglongbing spread crosses threshold levels that trigger federal emergency management protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Brazil Cane Sugar Market
Others
Europe Travel Retail Market
Others
Duckweed Market
Others
Middle East Location-Based Services Market
Others
Nutricosmetics Market
Others
Latin America 3D Printing Construction Market
Others
US Quantum Computing Market
Others
Vegetable Carbon Market
Others
Badminton Apparel Market
Others
Lepidolite Market
Others
Global Injectable Nanomedicine Market
Others
Wearable Brain Devices Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Pin Mills Market
Others
Next Gen Video Codecs Market
Others
Germany 3D Printing Construction Market