
 Egg Market | 2026-2036
Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Market Analysis
Asset-light leasing arrangements for layer housing and equipment is narrowing the capital barrier for mid-scale entrants. Cal-Maine Foods leverages vertical integration across feed mills and processing to sustain margin control across volatile input cycles. Rose Acre Farms anchors its competitiveness through geographic dominance in the Midwest and Southeast production belts.
An egg is a self-contained reproductive structure consisting of albumen, yolk, and shell with specified air-cell depth and Haugh unit measurements that determine interior quality grade; it functions as a complete protein source and emulsifying agent across food manufacturing and direct consumption. Chicken eggs occupy the dominant volume position while organic and cage-free grades command the strongest margin pools as retailers reformulate private-label specifications. Online retail and direct-to-foodservice channels are expanding fastest, though supermarkets still control the bulk of quality-grade segmentation through private-label contracts.
The USDA grades and certifies shell eggs under federal standards that dictate size classification and interior quality, while FDA oversight of shell egg safety rules shapes refrigeration and Salmonella prevention protocols across the supply chain. State-level animal welfare regulations, notably California's Proposition 12 compliance requirements, are fragmenting production standards and raising compliance costs for multi-state suppliers. Stakeholders must monitor how diverging state and federal standards reshape sourcing geography and certification investments.
Market Dynamics
Cage-free mandates across multiple U.S. states are forcing a wholesale reconfiguration of layer housing infrastructure, compressing supply timelines and fragmenting production economics between compliant and conventional operations.
Growth Catalysts
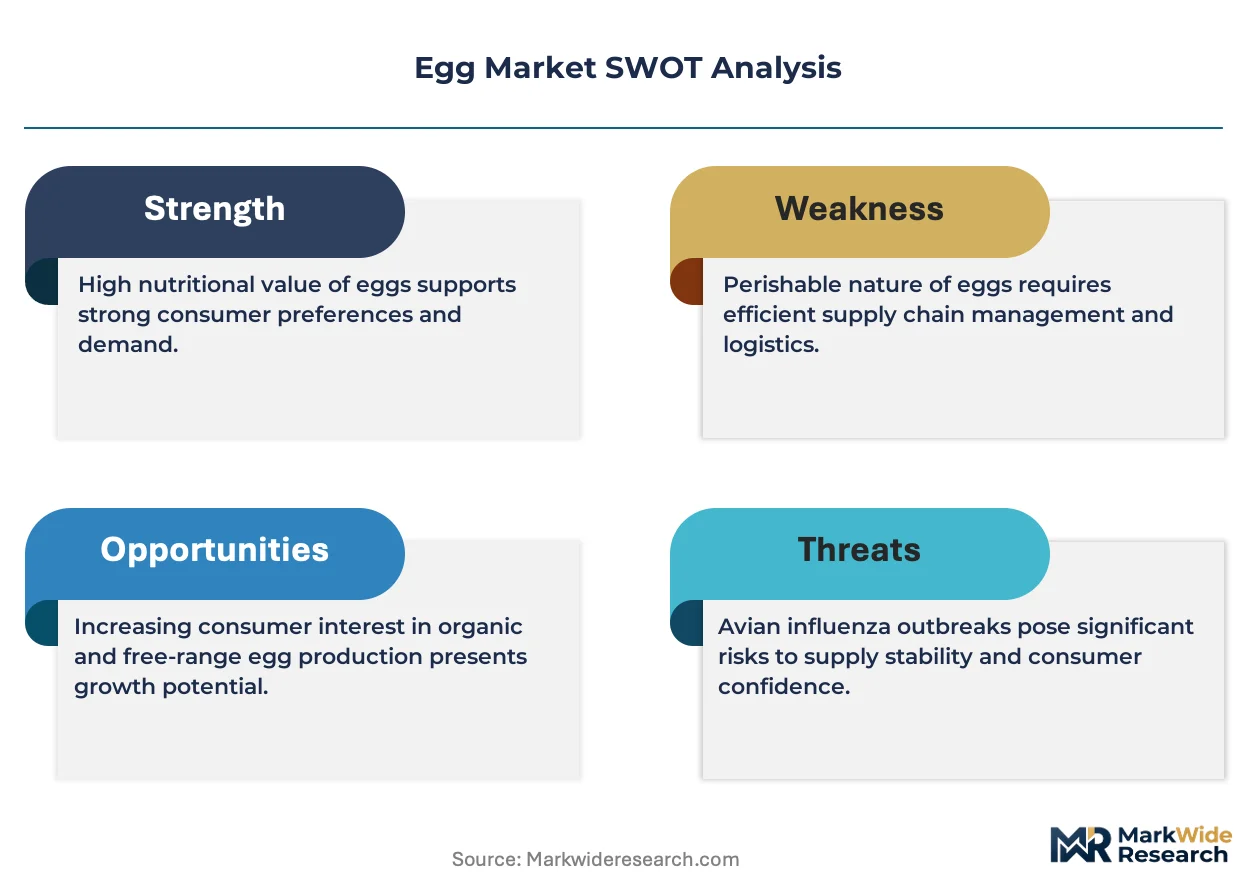
- California Proposition 12:This state-level animal welfare statute mandates minimum space requirements for egg-laying hens, compelling foodservice operators and retailers to accelerate specialty-grade procurement contracts.
- Foodservice channel expansion:Institutional buyers including hotel chains, quick-service restaurants, and contract caterers now specify cage-free and organic grades in procurement tenders, pulling volume away from conventional shell egg supply.
- Precision ventilation systems:Automated climate control in layer barns is reducing mortality rates and improving feed conversion ratios across Midwest production clusters.
Market Restraints
- Feed cost volatility:Corn and soybean meal prices swing with commodity futures, compressing margins for producers lacking backward integration into feed milling operations.
- Midwest supply concentration:Iowa, Indiana, and Ohio together host the majority of U.S. layer capacity, creating regional disease exposure and logistics bottlenecks during extreme weather events.
- Plant-based egg substitutes:Mung bean protein and chickpea-based alternatives are capturing shelf space in retail baking aisles and commercial food manufacturing formulations.
Strategic Opportunities
- Southeast U.S. underpenetration:Georgia, North Carolina, and Alabama offer lower land and labor costs for new cage-free facilities serving Atlantic seaboard population centers.
- Direct-to-foodservice platforms:Digital procurement portals connecting layer farms with restaurant groups and institutional kitchens are bypassing traditional distributor markups.
- USDA Organic certification tailwind:Premium price realization for certified organic grades is attracting capital toward pasture-raised and aviary system investments.
Industry Challenges
- Aviary system design expertise:Engineering firms with proven multi-tier cage-free housing configurations face order backlogs stretching 18-24 months, delaying facility conversions.
- Salmonella Enteritidis monitoring protocols:FDA's egg safety rule requires environmental testing and refrigeration compliance that adds operational complexity for small-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Market |
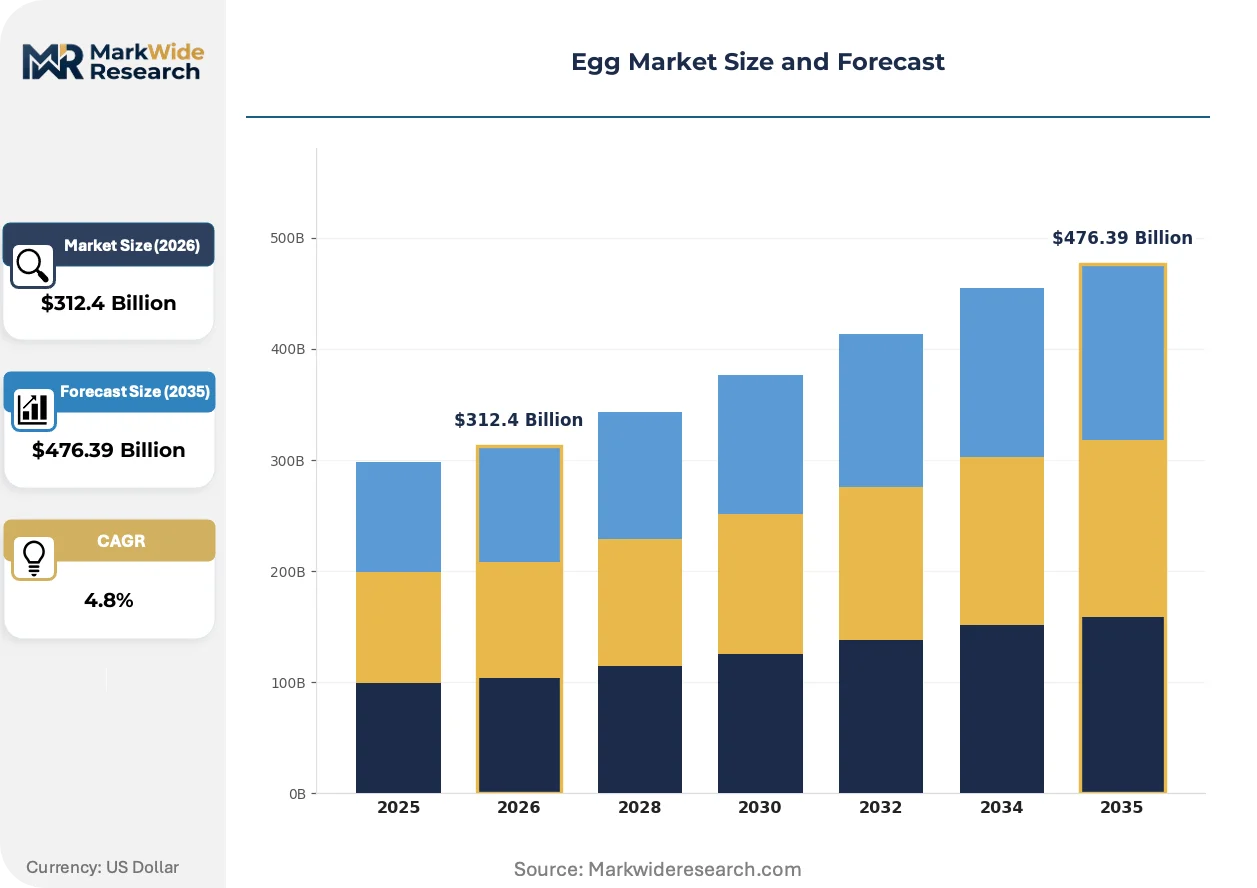
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $476.39 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken Eggs, Duck Eggs, Quail Eggs, Goose Eggs Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Wholesale Packing Type: Cartons, Trays, Bulk, Clamshells Quality Grade: Grade AA, Grade A, Grade B, Organic |
| Companies Covered | Cal-Maine Foods, Rose Acre Farms, SafeLand Farms, Hillandale Farms, Tulare Eggs, Ovobel Foods, SKM Egg, Rembrandt Foods, Interovo Egg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Market Emerging Trajectories
Automation and data analytics are penetrating layer farm operations at accelerating velocity, while regulatory fragmentation and buyer consolidation reshape competitive positioning across the value chain.
Precision livestock monitoring systems deploy computer vision and IoT sensors to track individual hen behavior, feed intake, and health indicators in real time. Large integrated producers are deploying these platforms across multi-site operations to reduce labor dependency and early mortality. This sensor-to-cloud architecture is digitizing flock management decisions that previously relied on manual observation and experience-based judgment.
USDA's organic certification requirements have tightened pasture access and outdoor space mandates, raising the capital threshold for new entrants. Producers must now document continuous outdoor access and prohibit synthetic pesticides in feed crops, adding compliance documentation burdens. The rule change most heavily impacts mid-scale operations in the Midwest and Pacific Northwest that previously operated under looser interpretations.
Retail buyer consolidation is concentrating procurement leverage among supermarket chains and foodservice distributors. These consolidated buyers now demand long-term supply contracts with fixed pricing tiers tied to feed cost indices, transferring input volatility risk backward to producers. This contract restructuring is most visible in California and New York metro markets where retail concentration ratios exceed national averages.
Egg Market Segmentation
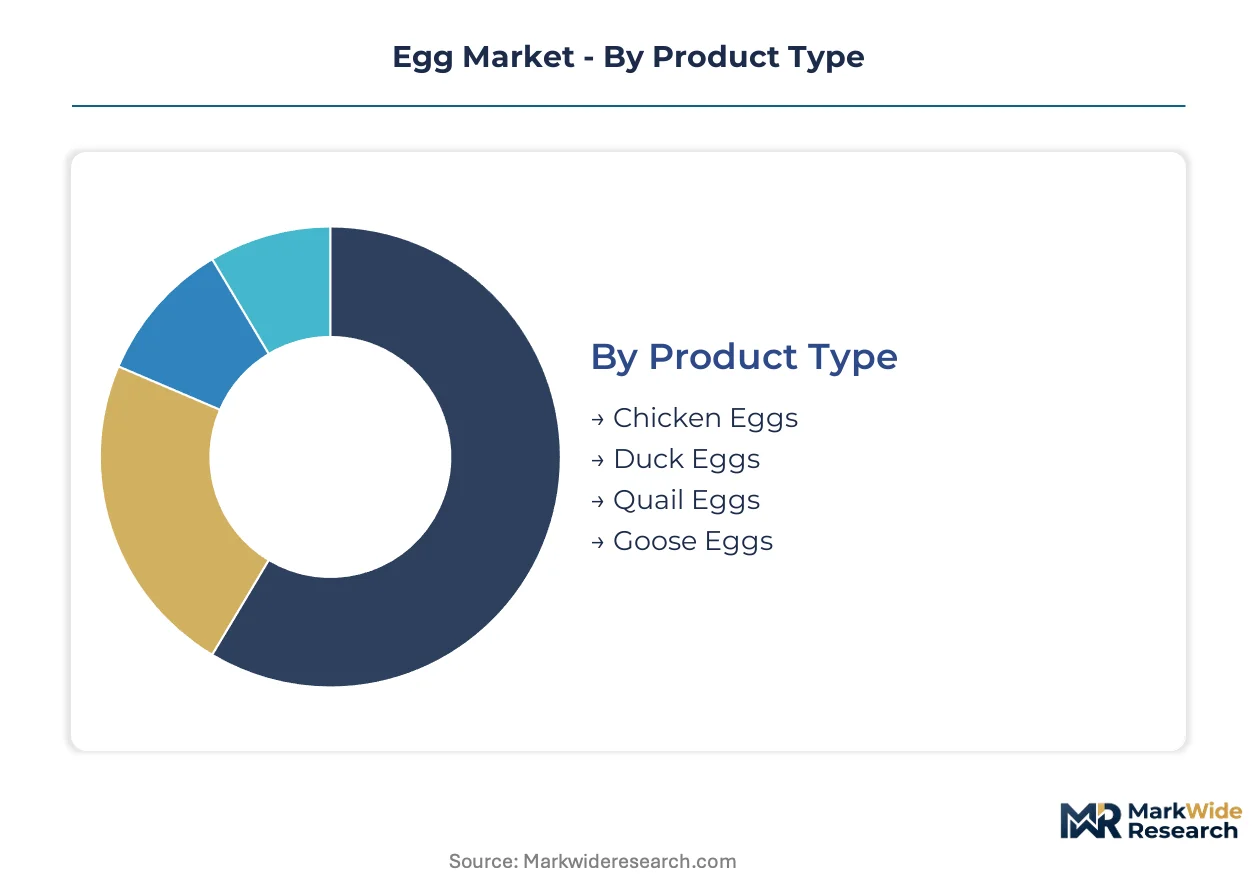
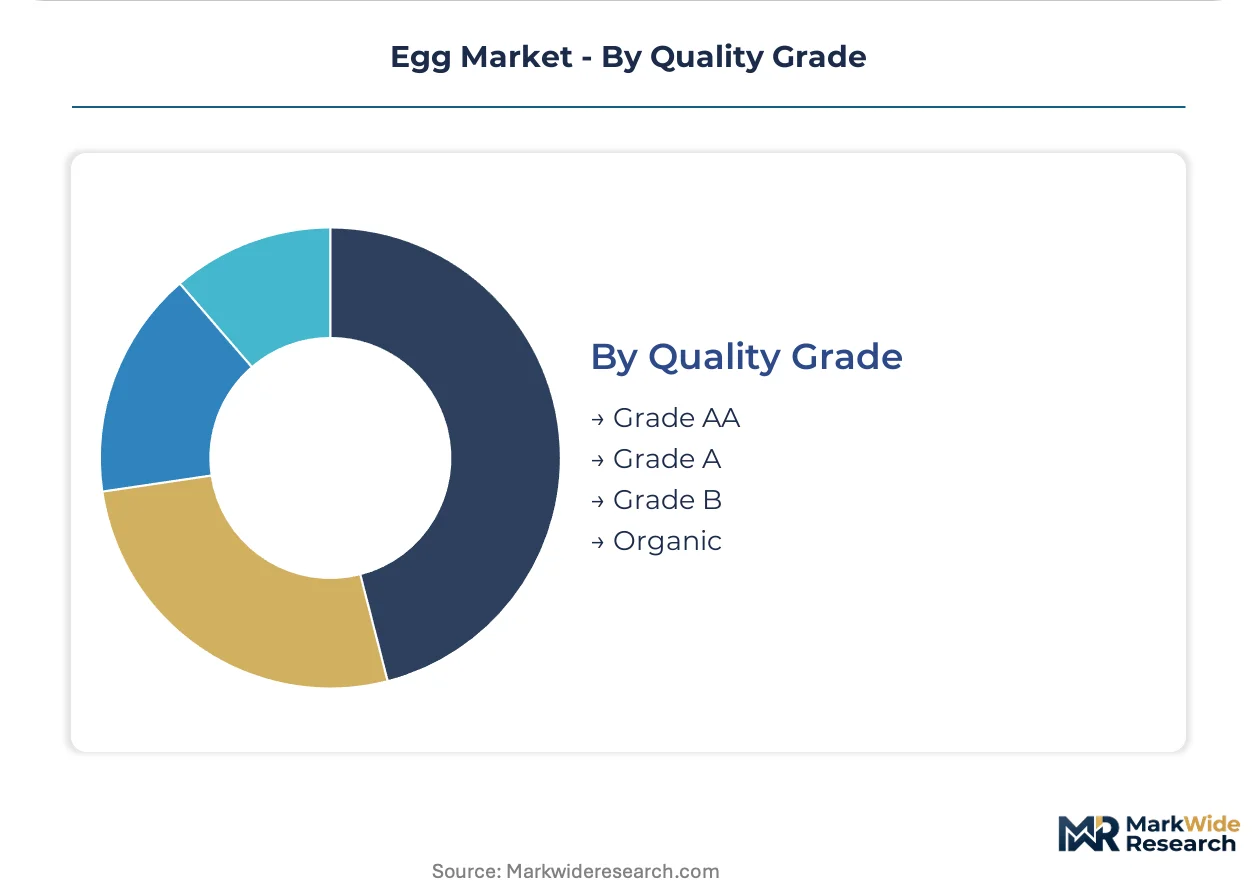
Egg market segmentation reflects divergent supply chain economics across species, channel structures, and certification tiers. Buyers now sort procurement by quality grade and packing format as cage-free mandates reshape distributor specifications.
Product Type:
Species differentiation determines feed conversion efficiency, laying cycle duration, and end-use application suitability across the value chain.
- Chicken Eggs:White and brown shell varieties dominate institutional and retail volume through optimized layer genetics achieving 300+ eggs per hen annually. Quick-service restaurants and bakery manufacturers in the United States specify jumbo and extra-large sizes for formulation consistency.
- Duck Eggs:Higher albumen density and richer yolk composition command premium positioning in Asian cuisine segments and artisanal baking applications. Demand clusters in California and New York metro markets where specialty grocers maintain dedicated shelf placement.
- Quail Eggs:Bite-sized format serves hors d'oeuvre and garnish applications in foodservice channels.
- Goose Eggs:Seasonal availability and substantial unit size restrict penetration to direct farm sales and holiday baking niches.
Chicken eggs hold installed capacity. Duck eggs are rotating up the share rankings.
Distribution Channel:
Channel selection governs price realization, traceability requirements, and inventory velocity for layer operations of varying scale.
- Supermarkets:Private-label contracts dominate volume movement through refrigerated dairy case placement and weekly promotional cycles. Chains in California and Massachusetts now mandate cage-free sourcing for all shell egg SKUs under state compliance timelines.
- Online Retail:Direct-to-consumer subscription models and third-party marketplace fulfillment are capturing urban households seeking specialty grades with delivery convenience. Cold chain packaging investments separate viable entrants from commodity resellers.
- Farmers' Markets:Pasture-raised and small-flock provenance commands price premiums through face-to-face credentialing.
- Wholesale:Institutional buyers including hotel chains and contract foodservice operators procure through broadline distributors with specification compliance documentation.
Supermarkets maintain throughput dominance. Online retail is climbing the fastest.
Packing Type:
Packaging format selection balances shelf life extension, retail display economics, and foodservice handling efficiency.
- Cartons:Molded pulp and expanded polystyrene formats remain standard for dozen-count retail SKUs with printed grade and size labeling. Recycled content mandates in Washington and Oregon are shifting procurement toward fiber-based alternatives.
- Clamshells:Clear PET and rPET construction enables visual quality inspection while protecting against hairline cracks during transport. Retail buyers in the Northeast specify this format for private-label premium tiers.
- Trays:30-egg flats serve commercial bakery and food manufacturing bulk requirements.
- Bulk:Loose fill in foodservice totes minimizes packaging cost for high-volume institutional accounts.
Cartons hold installed capacity. Clamshells are rotating up the share rankings.
Quality Grade:
Grade certification determines permissible distribution channels, price tier placement, and regulatory compliance obligations.
- Grade AA:Haugh unit measurements exceeding 72 and minimal air cell depth qualify eggs for premium retail positioning and export eligibility. USDA graders inspect at packing plants to enforce interior quality standards.
- Organic:USDA certification mandates outdoor access, synthetic pesticide prohibition in feed crops, and third-party audit documentation. Price realization spreads above conventional grades are attracting pasture-raised system investments in the Midwest.
- Grade A:Slightly lower interior quality thresholds accommodate mainstream retail and foodservice volume.
- Grade B:Thin albumen and enlarged air cells restrict usage to liquid egg processing and manufacturing applications.
Grade A holds installed capacity. Organic is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in shell eggs and processed egg products, exporting surplus production to Canada, Mexico, and Asian markets while importing negligible volumes. Export flows concentrate in specialty grades where USDA certification commands premium positioning abroad. Import dependency remains minimal due to domestic overcapacity in conventional grades.
United States
Foodservice operators and retail chains drive cage-free conversion timelines across California, New York, and Massachusetts markets. FDA's egg safety rule mandates refrigeration and Salmonella testing protocols that shape distribution infrastructure investments. The Midwest production belt spanning Iowa, Indiana, and Ohio hosts the majority of layer capacity, with Cal-Maine Foods and Rose Acre Farms operating integrated feed-to-packaging facilities.
China
Urban protein demand and quick-service restaurant expansion sustain volume growth in tier-one and tier-two cities. The country's national agricultural regulator enforces food safety standards for shell egg production and cold chain distribution. Shandong and Henan provinces concentrate industrial-scale layer operations serving Beijing-Tianjin-Hebei and Yangtze River Delta consumption centers.
India
Vegetarian dietary preferences and affordable protein positioning drive per capita consumption growth in southern and western states. FSSAI mandates hygiene and labeling standards for shell eggs sold through organized retail channels. Andhra Pradesh and Telangana host the densest layer farm clusters, with Namakkal in Tamil Nadu serving as a processing and distribution hub for export-oriented liquid egg products.
Brazil
Domestic consumption and Mercosur export opportunities support capacity expansion in grain-adjacent production zones. The country's national agricultural regulator oversees sanitary certification for export eligibility to European and Middle Eastern markets. São Paulo state and the southern region concentrate integrated operations leveraging proximity to corn and soybean feed sources.
Mexico
Border-state demand from US Hispanic populations and domestic retail modernization pull specialty-grade imports and drive local cage-free investments. SENASICA coordinates sanitary protocols aligned with USDA equivalence agreements for cross-border trade. Jalisco and Puebla host the largest layer concentrations, with Baja California and Chihuahua developing export-oriented capacity for California markets.
Egg Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated producers with captive feed milling and multi-state distribution networks. The competitive map separates into three strategic archetypes: large-scale integrated producers controlling procurement leverage, mid-scale specialists targeting organic and pasture-raised niches, and regional cooperatives serving local foodservice accounts. Dominant competitive moves include backward integration into feed production to offset commodity volatility, and geographic expansion into underpenetrated Southeast and Pacific Coast markets to capture cage-free demand premiums.
Within the integrated producer tier, Cal-Maine Foods and Rose Acre Farms exemplify scale-driven positioning through multi-state layer operations and distributor relationships. Among mid-scale specialists, Hillandale Farms occupies a position serving retail private-label and institutional accounts with regional sourcing flexibility. These named entities anchor the competitive structure without exhausting the vendor landscape, as regional cooperatives and emerging pasture-raised operators fill specialty segments below the scale threshold of national distribution.
| Leading Market Players |
|---|
| Cal-Maine Foods |
| Rose Acre Farms |
| SafeLand Farms |
| Hillandale Farms |
| Tulare Eggs |
| Ovobel Foods |
| SKM Egg |
| Rembrandt Foods |
| Interovo Egg Group |
| Others |
Supply Flow & Price Mechanics
Iowa, Indiana, and Ohio together host the majority of U.S. layer capacity, concentrating feed cost leverage and cage-free conversion capital demands among a tight supplier base that transfers margin pressure downstream to foodservice distributors and retail chains negotiating long-term procurement contracts.
Pricing Analysis
Foodservice operators anchor pricing structures through volume commitments and specification compliance requirements that stratify across cage-free, organic, and conventional tiers. Price differentiation hinges on USDA certification grade and state-level animal welfare compliance costs, with California Proposition 12 mandates compressing margins for non-compliant suppliers. Pricing pressure stems from feed commodity volatility and cage-free housing conversion capex, while quick-service restaurant chains exhibit highest price sensitivity and specialty grocers command lowest.
Supply Chain Analysis
Extended payment terms from broadline distributors and supply-chain finance facilities are becoming standard working capital instruments for mid-scale layer operations. Iowa, Indiana, and Ohio draw from corn and soybean meal feed inputs, with supply chain risk anchored in regional disease exposure and Midwest weather logistics chokepoints. Distribution runs through refrigerated broadline networks serving institutional accounts and direct-to-retail cold chains for supermarket private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The egg market functions as a defensive-moat story where regulatory entrenchment through state-level cage-free mandates creates high switching costs for multi-state foodservice buyers locked into compliance-driven procurement contracts.
For Market Incumbents: Pre-empt margin erosion by accelerating backward integration into feed milling operations and securing aviary system engineering capacity before order backlogs extend further. Cal-Maine Foods and Rose Acre Farms demonstrate how captive feed production offsets commodity volatility, while engineering firm scarcity threatens facility conversion timelines for competitors lacking established relationships.
For New Entrants and Emerging Players: Georgia, North Carolina, and Alabama offer lower land and labor costs for cage-free facilities serving Atlantic seaboard population centers with underdeveloped layer infrastructure. Direct-to-foodservice digital procurement platforms bypass traditional distributor markups, while pasture-raised and aviary system investments capture organic certification premiums in Southeast markets lacking incumbent concentration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cage-free and organic production tiers as housing infrastructure and certification compliance demands escalate. Long-term viability favors vertically integrated operations with multi-state distribution networks and feed milling assets. Watch for divergence between state animal welfare enforcement timelines as the signal indicating geographic margin compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captive corn and soybean meal supply insulates margin from commodity futures volatility. |
| Cage-Free Facility Conversion | California Proposition 12 compliance opens foodservice procurement contracts in mandated states. |
| USDA Organic Certification Investment | Pasture-raised system premiums attract retail private-label contracts in Northeast metro markets. |
| Direct-to-Foodservice Platform Launch | Digital procurement portals bypass broadline distributor markups for restaurant group accounts. |
| Southeast Geographic Expansion | Georgia and North Carolina land costs enable competitive positioning for Atlantic seaboard demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USDA production reports, FDA egg safety filings, state agricultural department records, and trade customs data. Conversations with layer farm operators, foodservice procurement directors, supermarket category buyers, and aviary system engineering firms informed supply-side and demand-side dynamics. Secondary validation drew from SEC 10-K disclosures of publicly traded producers, American Egg Board statistics, and state-level animal welfare regulatory filings. Bottom-up facility capacity estimates triangulated against top-down consumption flow models.
Forecast inputs incorporate cage-free mandate implementation timelines, feed commodity price trajectories, and layer housing conversion capex cycles across the projection horizon. Segmentation dimensions span species type, quality grade certification, distribution channel structure, and packing format. CAGRs derive from trend extrapolation of historical production volumes against projected demand shifts in foodservice and retail channels. Industry-specific inputs include state regulatory compliance cost curves and precision livestock technology adoption rates.
Macroeconomic conditions sit as an overlay; deviation in feed grain futures, interest rate environments for agricultural lending, or consumer protein substitution patterns would shift the trajectory. Forecasts reflect documented assumptions regarding mandate enforcement consistency and technology cost decline curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Crystal Growth Equipment Market
Others
Tripod Market
Others
Snus Market
Others
AI in Precision Medicine Market
Others
IT Device Market
Others
Global Hardware Acceleration Market
Others
Post Consumer Recycled Bottles Market
Others
Reef Aquarium Market
Others
Traditional PC Market
Others
Deflectometer Market
Others
Europe Video Encoder Market
Others
South Korea Automotive LED Lighting Market
Others
Boston Round Bottle Market
Others
South America Halal Food and Beverages Market
Others
Food Technology Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market