
 Magnesite Market | 2026-2036
Magnesite Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesite Market Analysis
Aftermarket refractory lining services is reconfiguring margin pools away from raw magnesite sales toward technical application support. RHI Magnesita leverages its global installation network to capture recurring maintenance revenue from steel clients. Grecian Magnesite anchors its position through vertical integration from mining to specialty caustic calcined magnesia. Baymag competes on low-cost dead-burned production for North American refractory customers.
Magnesite denotes magnesium carbonate ore processed through calcination or electrofusion to yield refractory-grade magnesia with MgO content exceeding 90 percent. Dead-burned magnesite dominates volume due to its indispensability in basic oxygen furnace linings, while fused magnesite commands premium pricing for glass tank superstructures where thermal shock resistance proves critical. The steel industry application segment leads absolute consumption, though waste treatment represents the fastest-growing outlet as flue gas desulfurization expands. Distributors still control the majority of channel flow to mid-sized refractory fabricators.
China's SAMR enforces GB standards on boron and heavy metal limits in export-grade magnesia, while REACH registration requirements in Europe restrict unqualified raw material entry. These frameworks push processors toward beneficiation investments and certified supply chains. Stakeholders must monitor how carbon border adjustments and evolving ESG disclosure rules reshape sourcing economics for magnesia-intensive industries.
Market Dynamics
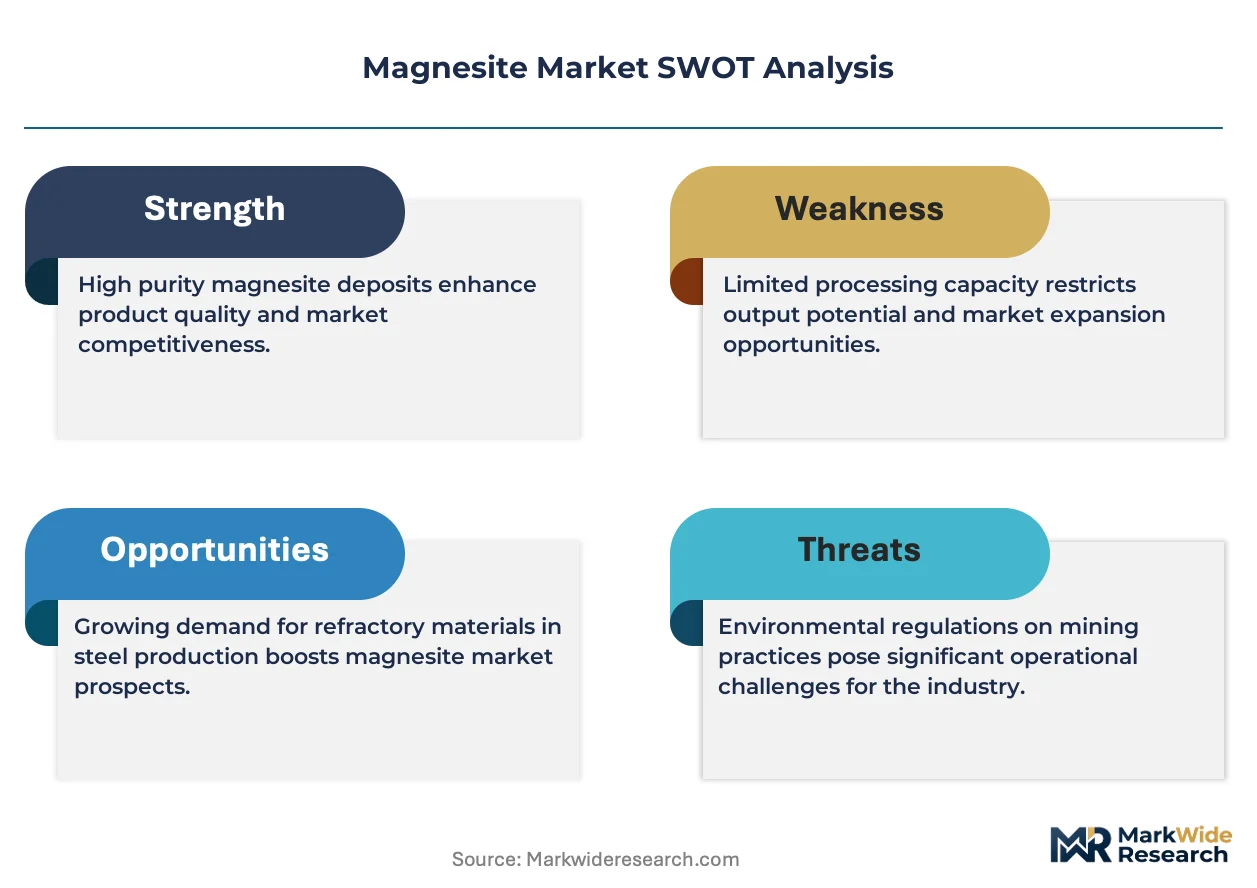
Refractory service bundling is compressing raw material margins while elevating technical support premiums, as steelmakers outsource lining installation and maintenance to specialized providers rather than purchasing standalone magnesia.
Growth Catalysts
- Steel capacity expansion:Basic oxygen furnace retrofits in India and Southeast Asia drive dead-burned magnesia consumption for high-performance refractory linings.
- REACH registration thresholds:EU ECHA requirements for heavy metal documentation push buyers toward certified supply chains, favoring processors with beneficiation capabilities.
- Flue gas desulfurization mandates:Power plant scrubber regulations in multiple jurisdictions expand caustic calcined magnesia demand for sulfur capture applications.
Market Restraints
- Energy cost volatility:Electrofusion and dead-burning require natural gas or electricity inputs vulnerable to price swings, squeezing fused magnesia margins.
- Liaoning supply concentration:Haicheng cluster dominance creates single-point vulnerability for global refractory-grade magnesia availability.
- Dolomite refractory substitution:Lower-cost basic refractories displace magnesia-carbon bricks in certain secondary steelmaking applications.
Strategic Opportunities
- Brazilian market penetration:Underdeveloped domestic magnesia processing creates import substitution potential for dead-burned and caustic calcined grades.
- Carbon capture integration:Magnesium oxide reactivity suits emerging direct air capture and mineral carbonation process streams.
- EU Carbon Border Adjustment Mechanism:CBAM implementation on imported refractories incentivizes local EU magnesia beneficiation investments.
Industry Challenges
- Refractory engineering talent scarcity:Specialized furnace design expertise required for aftermarket service contracts remains concentrated among aging practitioner pools.
- GB standard compliance timelines:China's SAMR certification updates for export-grade magnesia impose documentation burdens on smaller processors lacking laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesite Market |
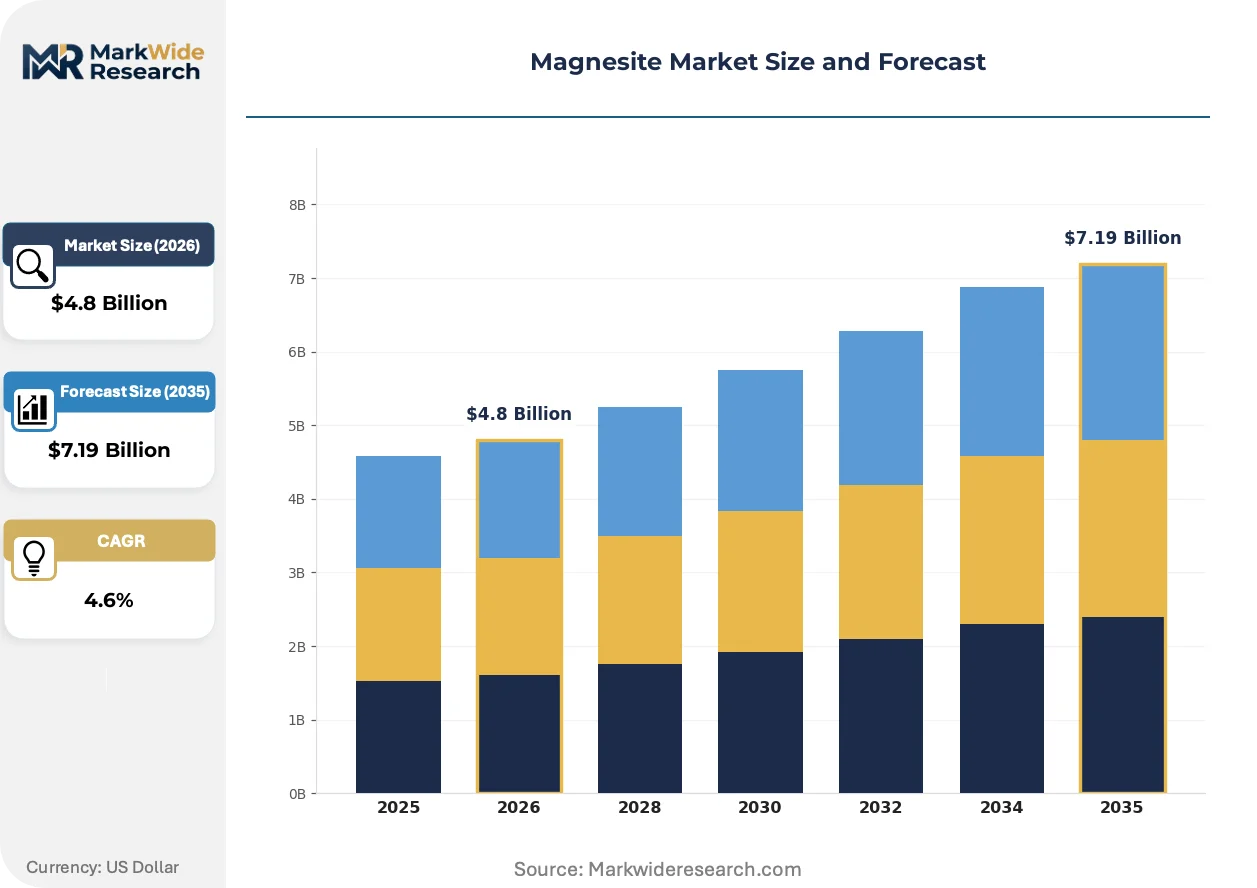
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dead-burned Magnesite, Fused Magnesite, Calcined Magnesite, Magnesia End User: Refractories, Agriculture, Construction, Chemicals Application: Steel Industry, Glass Manufacturing, Waste Treatment, Cement Production Distribution Channel: Direct Sales, Online Retail, Distributors, Brokers |
| Companies Covered | Haicheng Magnesite Group, Martin Marietta Magnesia Specialties, RHI Magnesita, Sibelco Australia Limited, SMZ Jelsava, Magnezit Group, Baymag, Kumas Magnesite, Grecian Magnesite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesite Market Emerging Trajectories
Processing technology convergence and regulatory documentation requirements are elevating capital barriers while opening service-based revenue streams for integrated magnesia suppliers.
Electrofused magnesia production is hybridizing with plasma heating systems to reduce natural gas dependency and improve thermal efficiency in high-purity grade manufacturing. European refractory producers are piloting these installations to hedge against carbon border costs. The technology is compressing energy cost differentials between fused and dead-burned product tiers.
EU REACH annex updates on boron compound classifications are forcing exporters to requalify magnesia shipments for specialty glass and electronics applications. Processors must now submit extended safety data sheets documenting trace element thresholds. Fused magnesia destined for tank furnace superstructures faces the steepest compliance burden.
Steel mill procurement departments are consolidating refractory spend under multi-year performance contracts that bundle material supply with installation and relining services. This disintermediates traditional distributor channels and shifts margin capture toward vertically integrated magnesia-to-application providers. The model is most advanced in German and Japanese steelmaking operations.
Magnesite Market Segmentation
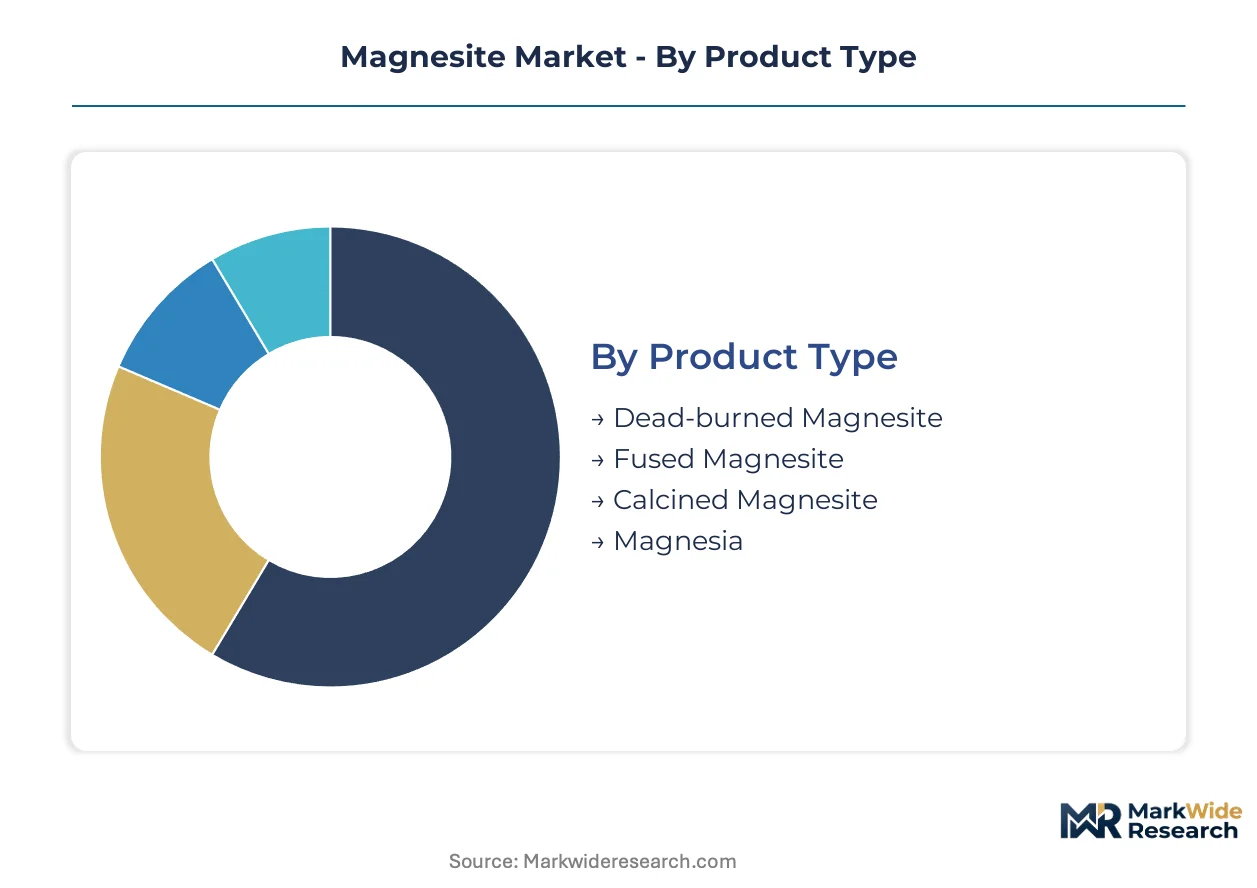
Magnesite market segmentation reveals distinct margin profiles across processing intensities and end-use specifications. Product grade differentiation determines energy input requirements and pricing power, while application-driven demand creates divergent growth trajectories across industrial verticals.
Product Type:
Mature refractory grades dominate volume, while emerging specialty derivatives command premium positioning through purity thresholds.
- Dead-burned Magnesite:Sintered at temperatures exceeding 1500°C to achieve crystalline periclase structure with MgO content above 90 percent. Steelmakers in India's expanding basic oxygen furnace capacity consume this grade for high-wear lining applications where thermal cycling resistance proves critical.
- Fused Magnesite:Electrofused in arc furnaces yielding large-crystal high-density magnesia with superior corrosion resistance. Glass tank superstructure applications in Germany and Japan drive demand where thermal shock tolerance justifies threefold energy input versus dead-burned alternatives.
- Calcined Magnesite:Caustic-calcined variant processed at 700-1000°C retains reactivity for chemical applications and flue gas desulfurization systems.
- Magnesia:Refined magnesium oxide powders serving pharmaceutical and electronics sectors with stringent trace element limits under EU REACH annex requirements.
Dead-burned magnesite retains volume leadership; calcined magnesia holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive industrial consumers from price-sensitive agricultural buyers.
- Refractories:Basic oxygen furnace lining manufacturers represent the dominant value pool, with procurement consolidating under performance-based supply contracts bundling material and installation services.
- Agriculture:Soil amendment applications favor lower-grade caustic calcined material where magnesium deficiency correction drives demand across Brazilian soybean cultivation regions.
- Construction:Magnesium oxychloride cement and flooring compounds utilize caustic calcined grades with moderate reactivity specifications.
- Chemicals:Magnesium salt production and water treatment applications require consistent reactivity profiles for process predictability.
Refractory end users capture the majority of value; agriculture demonstrates the most elastic demand response to price fluctuations.
Application:
Geography of demand concentration shapes supply chain configuration more than technical specification differentiation.
- Steel Industry:Basic oxygen furnace and electric arc furnace lining applications consume dead-burned and fused grades where lining life directly correlates with magnesia purity and density specifications.
- Glass Manufacturing:Tank furnace superstructures and regenerator checkerwork require fused magnesia with low boron content under tightening EU ECHA classification thresholds.
- Waste Treatment:Flue gas desulfurization scrubbers in power generation expand caustic calcined magnesia consumption for sulfur dioxide capture.
- Cement Production:Refractory linings in cement kilns utilize magnesia-chrome and magnesia-spinel compositions where alkali resistance proves essential.
Steel applications anchor absolute consumption volumes; waste treatment is expanding most quickly across regulatory jurisdictions.
Distribution Channel:
Customer type and order scale determine channel selection, with technical buyers bypassing intermediaries.
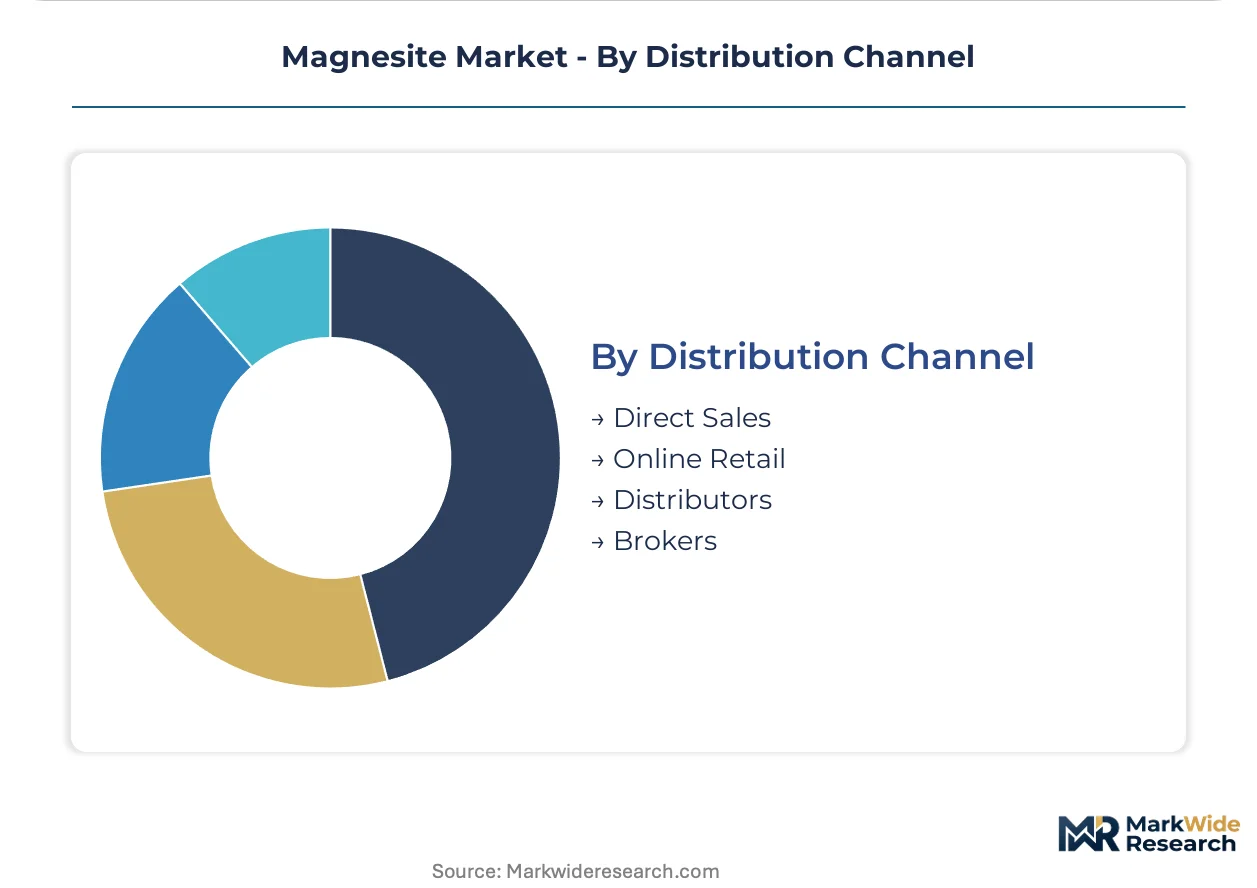
- Direct Sales:Integrated magnesia suppliers contract directly with steel mill procurement departments for multi-year refractory performance agreements.
- Distributors:Regional stockists serve mid-sized refractory fabricators requiring smaller lot sizes and technical support.
- Brokers:Spot market intermediaries facilitate price discovery for uncommitted tonnage from Chinese export processors.
- Online Retail:Agricultural and construction-grade material sees limited digital penetration due to bulk logistics requirements.
Direct sales channels capture margin expansion from service bundling; distributor relationships face compression from procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes magnesite predominantly for steel refractories, while European and North American buyers prioritize specialty grades for glass and environmental applications. This consumption-mix differential shapes divergent supply chain configurations and regulatory compliance burdens across geographies.
China
Liaoning Province's Haicheng cluster supplies both domestic basic oxygen furnace operators and export processors with dead-burned and fused grades. SAMR enforces GB standards on boron and heavy metal content in export-grade magnesia, forcing beneficiation investments among smaller processors. Dalian port facilities handle the majority of seaborne shipments to Japanese and South Korean refractory fabricators.
Germany
Steel mill procurement departments in the Ruhr region consolidate refractory spend under multi-year performance contracts bundling material supply with installation services. ECHA REACH annex updates on boron compound classifications require extended safety data sheets for fused magnesia imports. The Düsseldorf-Cologne corridor hosts specialized engineering firms providing aftermarket lining design expertise.
United States
Electric arc furnace operators in the Great Lakes region drive dead-burned magnesia consumption for high-wear lining applications. EPA flue gas desulfurization mandates expand caustic calcined magnesia demand from power plant scrubber installations. Baymag's Nevada operations anchor North American supply for domestic refractory customers seeking reduced import dependency.
India
Basic oxygen furnace retrofits in Odisha and Jharkhand steel corridors drive dead-burned magnesia imports for high-performance refractory linings. BIS certification requirements for refractory-grade raw materials push buyers toward documented supply chains with beneficiation capabilities. The Visakhapatnam-Kolkata industrial belt concentrates demand from integrated steel producers expanding capacity.
Brazil
Soybean cultivation regions in Mato Grosso and Paraná generate caustic calcined magnesia demand for soil amendment applications. ANVISA oversight of agricultural input registrations creates compliance thresholds for imported magnesium products. Underdeveloped domestic magnesia processing creates import substitution potential for dead-burned and caustic calcined grades serving both agricultural and emerging steel sector needs.
Magnesite Market Vendor Landscape
Capability concentration sits with integrated refractory service providers; scale advantage sits with raw material processors anchored to mineral deposits. The vendor base stratifies across three tiers: global installation networks capturing bundled service margins, regional mining-to-processing operators controlling beneficiation infrastructure, and spot-market exporters competing on uncommitted tonnage. Two dominant competitive moves define current positioning: vertical integration into technical application support, and geographic diversification away from Liaoning supply concentration.
Within the integrated service tier, RHI Magnesita and Grecian Magnesite exemplify divergent strategic positions. RHI Magnesita represents the refractory-service bundling archetype, leveraging global installation networks to capture recurring maintenance revenue. Grecian Magnesite occupies the vertical integration archetype, anchoring position through captive mining-to-specialty-processing control. Haicheng Magnesite Group sits within the scale-driven export processor tier, its geographic naming reflecting concentration in China's dominant production cluster.
| Leading Market Players |
|---|
| Haicheng Magnesite Group |
| Martin Marietta Magnesia Specialties |
| RHI Magnesita |
| Sibelco Australia Limited |
| SMZ Jelsava |
| Magnezit Group |
| Baymag |
| Kumas Magnesite |
| Grecian Magnesite |
| Others |
Supply Flow & Price Mechanics
Liaoning Province's Haicheng cluster controls roughly two-thirds of global refractory-grade magnesia capacity, translating mining-scale leverage into pricing power over steel mill procurement departments. This geographic chokepoint lets integrated processors command premium realizations for certified dead-burned grades while spot-market exporters compete on uncommitted tonnage.
Pricing Analysis
Long-term offtake agreements dominate volume flows between integrated magnesia suppliers and steel mill procurement departments, with multi-year performance contracts bundling material supply and installation services. Price differentiation rests on GB standard certification status and REACH-compliant documentation for EU-bound shipments. Pricing pressure stems from dolomite refractory substitution in secondary steelmaking, compressing margins for uncertified dead-burned grades. Agricultural buyers in Brazilian soybean regions exhibit the highest price elasticity, while glass manufacturers in Germany and Japan accept threefold premiums for low-boron fused magnesia.
Supply Chain Analysis
Extended payment terms from steel mill customers strain working capital for mid-sized processors, pushing some toward supply-chain finance facilities backed by export credit agencies. Raw material extraction concentrates in China, Turkey, and Greece, with electrofusion capacity anchored in Slovakia and Austria. Production draws from magnesite ore, metallurgical coke, and natural gas inputs vulnerable to energy cost volatility. Single-source vulnerability in Liaoning creates systemic risk for global refractory-grade availability. Distribution runs through direct sales channels for integrated service providers and regional distributors for mid-sized refractory fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnesite market sits in early-cycle expansion as flue gas desulfurization mandates across power generation jurisdictions drive caustic calcined magnesia penetration beyond traditional refractory applications.
For Market Incumbents: Harden supply chain resilience through backward integration into captive mining assets outside Liaoning Province, reducing single-point exposure to SAMR export certification disruptions. Invest in plasma-heating electrofusion technology to hedge against carbon border adjustment costs under EU CBAM implementation. Prioritize REACH-compliant beneficiation infrastructure to capture premium pricing from specialty glass and electronics buyers facing ECHA boron compound reclassification. For New Entrants and Emerging Players: Establish a beachhead in Brazilian dead-burned and caustic calcined magnesia processing, where underdeveloped domestic capacity creates import substitution potential for agricultural and emerging steel sector demand. Target soil amendment applications in Mato Grosso soybean cultivation regions as the most penetrable segment, leveraging ANVISA registration pathways to differentiate from commodity traders. Pursue joint venture structures with established distributors to bypass capital-intensive beneficiation investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated refractory service providers with captive installation networks over standalone raw material processors. Long-term viability over a five-to-ten year window rests on carbon capture integration potential and EU regulatory tailwinds for localized beneficiation. Acquisition targets should demonstrate REACH documentation capabilities and geographic diversification beyond China. The signal to watch is CBAM implementation pace on imported refractories, which would accelerate margin compression for unintegrated exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Reduces Liaoning concentration risk and secures ore supply for certified magnesia production. |
| Plasma Heating Technology Deployment | Lowers natural gas dependency in electrofusion while hedging EU carbon border adjustment exposure. |
| REACH-Compliant Beneficiation Investment | Captures premium pricing from German and Japanese glass manufacturers under ECHA boron thresholds. |
| Performance Contract Service Bundling | Shifts margin capture from commodity sales to recurring maintenance revenue at steel mill customers. |
| Brazilian Processing Joint Venture | Addresses ANVISA-registered agricultural demand and emerging steel sector import substitution needs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed refractory producers, and SAMR certification registries. Primary interviews encompassed plant managers at dead-burned magnesia facilities, procurement leads at German and Japanese steel mills, distribution channel partners serving mid-sized refractory fabricators, and technical R&D directors developing plasma heating systems. Secondary validation drew from ECHA REACH annex updates, IEA energy transition reports, and BIS certification documentation. Bottom-up capacity modeling triangulated against top-down steel production forecasts across the analysis window.
Forecast inputs include grade-tier segmentation across dead-burned, fused, and caustic calcined magnesia; end-use industry splits between refractories, agriculture, construction, and chemicals; and regional production hub differentiation. CAGRs were derived from elasticity-adjusted demand projections tied to steel capacity expansion trajectories and flue gas desulfurization regulatory adoption curves. Industry-specific inputs encompassed natural gas price volatility scenarios and EU CBAM implementation timing assumptions.
Stress conditions across energy cost spikes, SAMR certification delays, and dolomite substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about steel production growth and environmental regulation stringency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Massive Machine Type Communication in Healthcare Market
Others
Europe Indoor LBS Market
Others
Asia-Pacific 3D Printing Construction Market
Others
South America Halal Food and Beverages Market
Others
Safety Critical Software Testing Market
Others
Liquid-Cooled Heat Sink Market
Others
Underwater Communication System Market
Others
Dried Fruit Extracts Market
Others
Global Military and Aerospace Sensors Market
Others
5G Devices Market
Others
Fresh Apples Market
Others
Radiation Detection Monitoring and Safety Market
Others
US Tablet Market
Others
Asia-Pacific Adtech Market
Others
Gem Faceting Machine Market
Others
Moveable Water Tap Market