
 Food Technology Market | 2026-2036
Food Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Food Technology Market Analytics
The gap between precision-engineered alternative proteins and conventional commodity food processing is broadening as capital requirements and technical barriers diverge sharply. Apeel Sciences leverages plant-derived shelf-life extension to anchor premium produce supply chains against spoilage losses. Upside Foods sustains its position through cultivated meat bioreactor scale-up, while Eat Just competes on mung bean protein isolate formulations for egg replacement.
Food technology encompasses the application of engineering principles, biological sciences, and data systems to transform raw agricultural inputs into standardized, safe, and shelf-stable consumable products through controlled thermal processing, fermentation, extrusion, or cell cultivation at specified pH, moisture, and temperature parameters. Its primary commercial purpose is to decouple food output from land use intensity while meeting nutritional and sensory specifications at industrial throughput. Biotechnology applications in novel protein fermentation and cell agriculture represent the fastest-expanding segment as margin pools shift toward high-value ingredient platforms, whereas food processing equipment remains the mature revenue base where automation retrofits now dominate capital expenditure cycles.
The FDA governs novel food ingredient approvals and GRAS self-affirmation pathways in the United States, while EFSA mandates pre-market authorization for cell-cultured products across European Union member states, and China's SAMR enforces GB standards for genetically edited organisms in food applications. These frameworks shape demand by determining time-to-market, labeling requirements, and permissible production claims for alternative protein entrants. Stakeholders must monitor how regulatory divergence between jurisdictions affects cross-border product registration strategies and capital allocation for biomanufacturing capacity.
Market Dynamics
Precision fermentation infrastructure is concentrating capital allocation as bioreactor manufacturers face order backlogs stretching eighteen months, forcing food technology firms to secure equipment slots before completing regulatory filings.
Growth Catalysts
- GRAS Self-Affirmation Pathway:The FDA's streamlined notification process for novel proteins accelerates commercial launch timelines for fermentation-derived ingredients in US food applications.
- Cell Agriculture Bioprocessing:Bioreactor scale-up technologies are reducing unit production costs for cultivated meat, attracting contract manufacturing investment from traditional protein processors.
- Germany:The Federal Ministry of Food and Agriculture's funding programs for alternative protein research are anchoring European pilot facility development in Baden-Württemberg.
Market Restraints
- Input Cost Volatility:Pharmaceutical-grade growth media components face supply concentration from Chinese fine chemical manufacturers, exposing cultivated meat producers to price swings.
- EFSA Novel Food Authorization:The eighteen-to-twenty-four month pre-market assessment timeline creates cash flow gaps for European entrants without parallel US revenue streams.
- Technical Limitation:Extrusion texturization of high-moisture plant proteins remains constrained by throughput ceilings below conventional meat grinding equipment.
Strategic Opportunities
- China:SAMR's evolving GB standards for genetically edited crops create first-mover advantage windows for precision-bred ingredient developers willing to navigate localized safety assessment.
- Foodservice Distribution:Direct supply contracts with institutional kitchens and QSR chains bypass retail slotting fee barriers that constrain CPG alternative protein launches.
- Hybrid Formulations:Convergence of plant protein isolates with cultivated fat tissue addresses taste-performance gaps in 100% animal-free products.
Industry Challenges
- Bioprocess Engineering Talent:Scarcity of professionals with simultaneous expertise in mammalian cell culture and food-grade manufacturing standards inflates compensation costs.
- Dual-Use Facility Certification:Converting pharmaceutical biomanufacturing assets to food production requires extensive FDA food safety modernization compliance overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Technology Market |
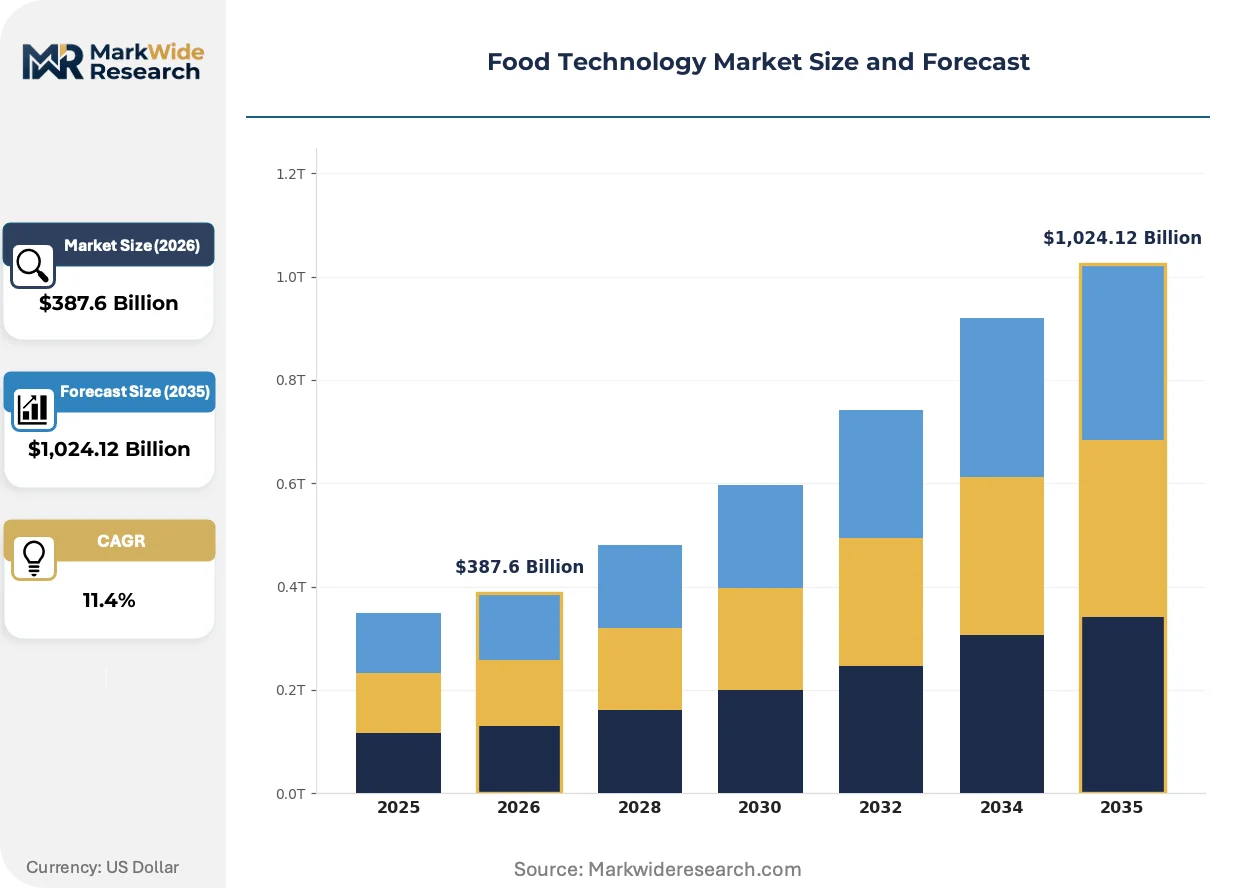
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Processing Equipment, Packaging Machinery, Quality Control Solutions, Automation Systems Technology: IoT Solutions, Artificial Intelligence, Robotics, Biotechnology Application: Food & Beverage, Bakery, Dairy, Meat Processing End User: Food Manufacturers, Retail Chains, Restaurants, Catering Services |
| Companies Covered | Apeel Sciences, True Essence Foods, Eat Just, Biokraft Foods, Hyperion FoodTech, Upside Foods, Revo Foods, DE3PBIO, Aleph Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Technology Market Evolving Landscape
Computational protein design and AI-driven flavor mapping are compressing product development cycles from thirty-six months to under eighteen, forcing legacy R&D organizations to restructure around in-silico screening capabilities.
Precision fermentation-derived dairy proteins are expanding into ice cream and cheese analog applications as Perfect Day's whey protein achieves price parity with commodity dairy isolates in North American foodservice channels. CPG manufacturers in California and Illinois are reformulating legacy brands around these ingredients to secure clean-label positioning without sacrificing functional performance.
EFSA's 2023 updated guidance on cell-cultured meat safety assessments mandates extensive metabolomic profiling that extends authorization timelines. Dutch and Spanish biotech firms are responding by pre-submitting toxicology dossiers to the FDA under GRAS pathways to generate parallel regulatory momentum.
Ingredient procurement is consolidating around long-term offtake agreements with single-source precision fermentation suppliers, displacing spot-market purchasing for high-value proteins. European dairy alternatives manufacturers are locking five-year supply contracts to secure volume allocation amid bioreactor capacity constraints.
Food Technology Market Segmentation
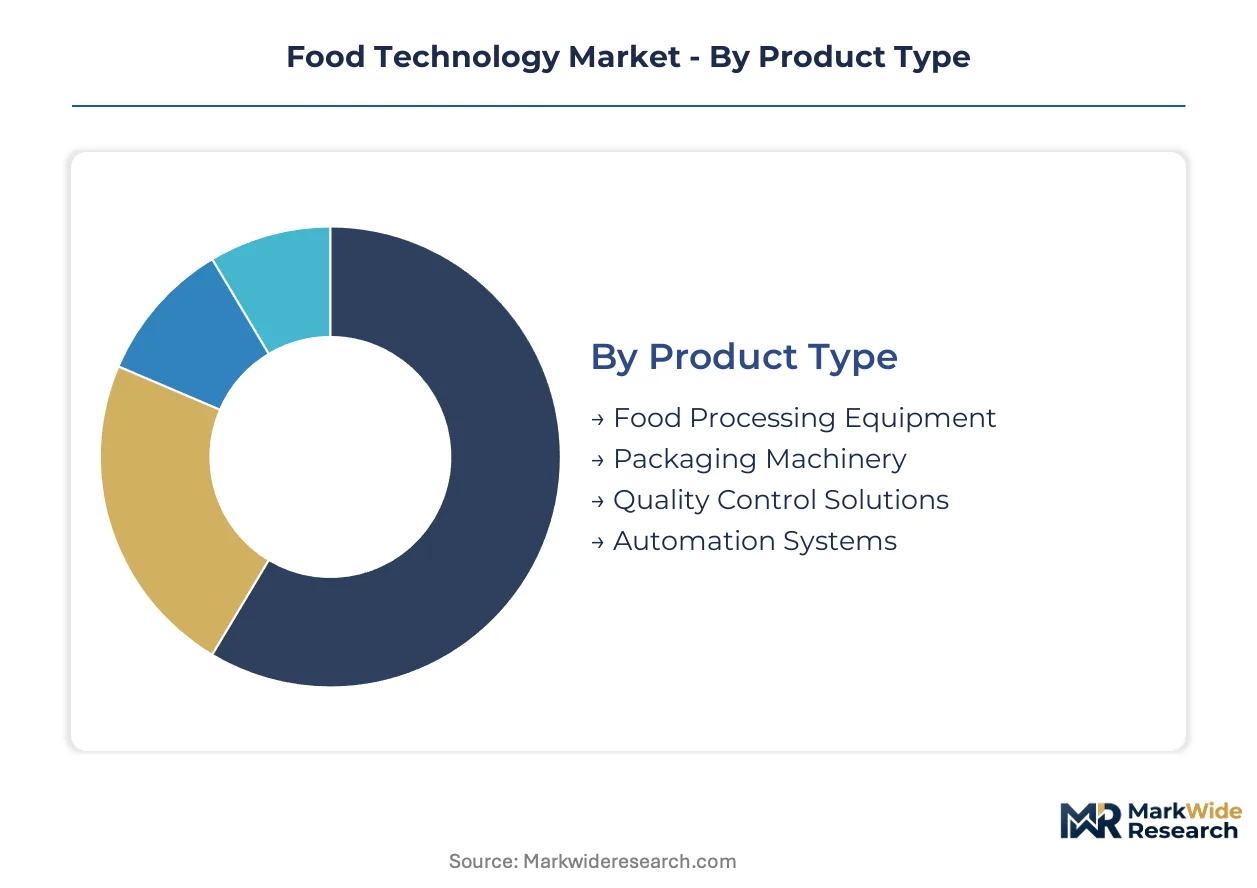
Segmentation in food technology reveals how capital allocation splits between mature equipment categories and emerging bioprocessing platforms. Buyers prioritize either throughput reliability or novel ingredient capabilities depending on their position in the value chain.
Product Type:
Purchase decisions pivot on depreciation schedules and retrofit compatibility with existing plant layouts.
- Food Processing Equipment:Thermal processing, extrusion, and mixing systems form the installed base across commodity food plants. Demand concentrates in Midwestern US meatpacking corridors and German dairy processing clusters where automation retrofits extend asset life cycles.
- Packaging Machinery:Modified atmosphere and vacuum-sealing systems preserve shelf-stable and refrigerated products. European bakery manufacturers in Italy and Spain drive replacement cycles as EFSA packaging material regulations tighten migration limits for recycled content.
- Quality Control Solutions:Spectroscopy and chromatography systems verify contaminant thresholds and nutritional labeling accuracy.
- Automation Systems:Programmable logic controllers and SCADA integration coordinate line-speed optimization across multi-product facilities.
Volume sits with Food Processing Equipment; growth tilts toward Automation Systems.
Technology:
Adoption velocity correlates with technical talent density and regulatory clarity for novel production claims.
- Biotechnology:Precision fermentation and cell cultivation platforms produce alternative proteins and functional ingredients. Investment clusters in California's Bay Area and Netherlands biotech corridors where FDA GRAS and EFSA novel food pathways run in parallel.
- Artificial Intelligence:Machine vision and predictive maintenance algorithms reduce unplanned downtime in high-throughput facilities. Chinese food manufacturers deploy AI-driven sorting systems to meet SAMR food safety traceability mandates.
- IoT Solutions:Sensor networks monitor cold chain integrity and equipment performance across distributed production assets.
- Robotics:Collaborative arms handle variable-weight portions and packaging tasks in labor-constrained processing environments.
Biotechnology commands premium pricing; AI applications are expanding most quickly through retrofit integration.
Application:
End-use selection depends on moisture content tolerance, pH stability requirements, and clean-label positioning pressures.
- Meat Processing:Cultivated meat and plant-based analog production demands bioreactor and extrusion capabilities. Investment flows to Singapore and Israel where regulators have issued commercial approvals for cell-cultured products.
- Dairy:Precision fermentation-derived proteins enable ice cream and cheese analog formulations. North American foodservice channels absorb volume as Perfect Day's whey protein achieves cost parity with commodity isolates.
- Food & Beverage:Beverage sterilization and aseptic filling systems serve high-acid and low-acid product categories.
- Bakery:Enzyme-based dough conditioning and automated portioning equipment address workforce availability constraints.
Meat Processing attracts speculative capital; Dairy shows the steepest expansion trajectory in ingredient substitution.
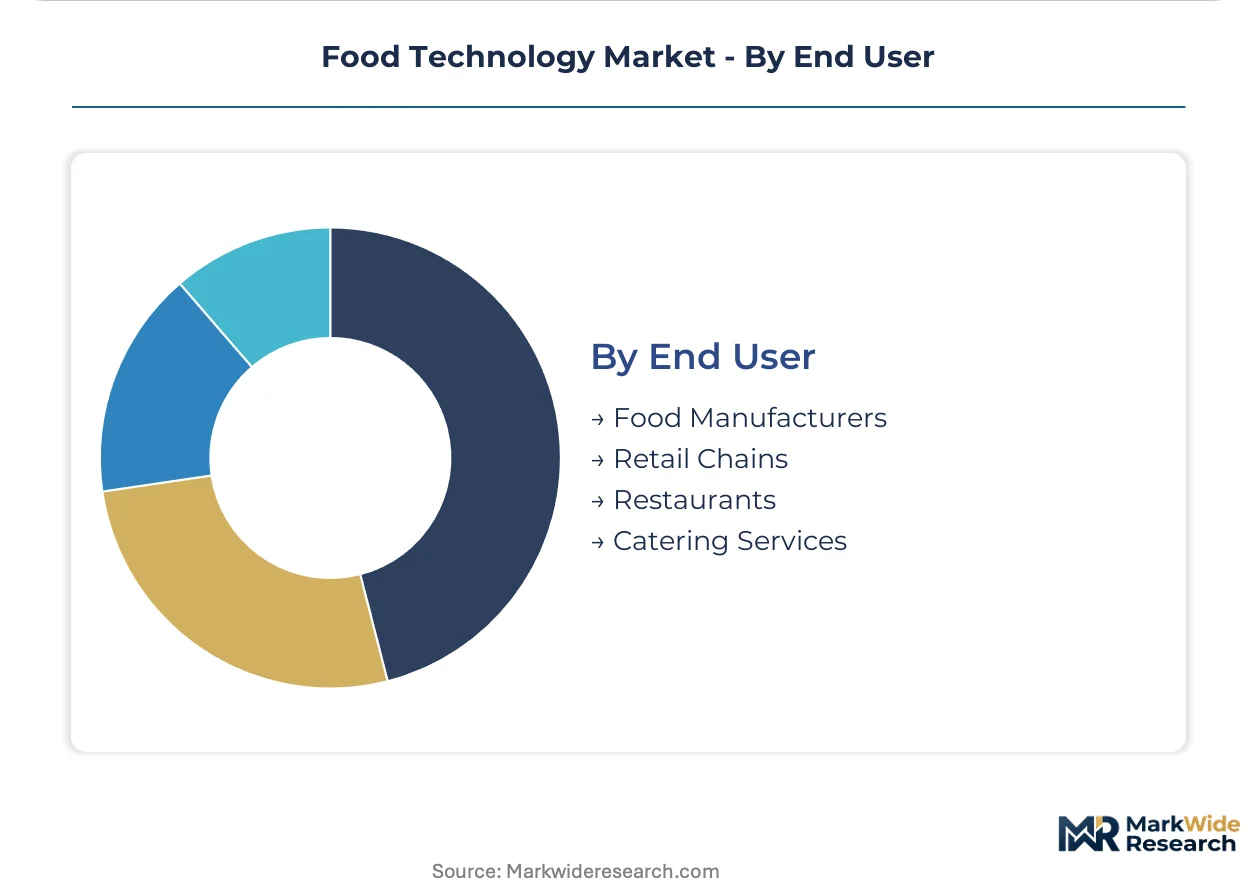
End User:
Procurement authority varies by contract scale, technical specification complexity, and regulatory compliance burden.
- Food Manufacturers:Integrated processors specify custom equipment configurations for proprietary product formats. German mid-cap manufacturers in Baden-Württemberg anchor European pilot facility development through Federal Ministry funding programs.
- Retail Chains:Private-label producers demand flexible packaging and labeling systems for SKU proliferation. US supermarket consolidation drives centralized procurement of quality control infrastructure.
- Restaurants:Ghost kitchen operators and QSR chains source compact processing equipment for limited footprints.
- Catering Services:Institutional kitchens prioritize batch consistency and food safety documentation for contract compliance.
Food Manufacturers dominate capital expenditure; Retail Chains are gaining procurement leverage through consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Bay Area anchors global biotechnology investment in food technology, hosting precision fermentation scale-ups and cultivated meat pilot facilities that attract venture capital from across North America and Asia.
United States
FDA GRAS self-affirmation pathways accelerate novel protein commercialization timelines for domestic fermentation-derived ingredients. The USDA co-regulates cell-cultured meat labeling and safety standards alongside FDA oversight. Chicago and Austin processing corridors drive automation retrofit demand in legacy meatpacking infrastructure.
Germany
Federal Ministry of Food and Agriculture funding programs anchor European alternative protein pilot development in Baden-Württemberg. EFSA novel food authorization timelines shape European market entry strategies for cultivated meat entrants. Munich and Berlin biotech clusters concentrate precision fermentation talent and contract manufacturing capacity.
China
SAMR GB standards for genetically edited organisms in food applications create regulatory clarity for precision-bred ingredient developers. Domestic demand for plant-based protein concentrates accelerates food manufacturer reformulation programs. Shanghai and Shenzhen technology zones host AI-driven food safety traceability system deployments.
Singapore
Singapore Food Agency commercial approvals for cell-cultured meat products attract Asia-Pacific headquarters relocations from Israeli and Dutch biotechnology firms. Government research funding supports bioreactor manufacturing partnerships with German equipment suppliers. Tuas Biomedical Park anchors regional cultivated protein production infrastructure.
Netherlands
Wageningen University research partnerships concentrate alternative protein R&D investment in Gelderland province. EFSA regulatory engagement expertise supports parallel FDA GRAS pathway navigation for domestic biotechnology firms. Eindhoven precision engineering capabilities supply bioreactor automation components to global fermentation infrastructure projects.
Food Technology Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and bioprocessing capability dimensions. The vendor base separates into three distinct tiers: established food processing equipment manufacturers defending installed base relationships, venture-backed biotechnology specialists securing long-term offtake agreements, and hybrid ingredient platforms bridging plant protein isolates with novel production methods. Consolidation pressure concentrates among mid-scale fermentation operators facing eighteen-month bioreactor order backlogs. Dominant competitive moves include strategic partnerships with contract manufacturing organizations and geographic expansion into Singapore and Israel where regulatory clarity supports commercial scale-up.
Within the biotechnology specialist tier, Upside Foods and Eat Just exemplify divergent strategic positioning around cultivated meat bioreactor scale-up versus plant protein isolate formulation approaches. Apeel Sciences occupies a distinct archetype leveraging plant-derived shelf-life extension for premium produce supply chain integration. These three entities collectively represent the capability spectrum spanning cell agriculture, precision fermentation, and botanical extraction methodologies that define competitive differentiation in alternative protein commercialization.
| Leading Market Players |
|---|
| Apeel Sciences |
| True Essence Foods |
| Eat Just |
| Biokraft Foods |
| Hyperion FoodTech |
| Upside Foods |
| Revo Foods |
| DE3PBIO |
| Aleph Farms |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade growth media components from Chinese fine chemical manufacturers cascade through three pricing tiers as they reach cultivated meat producers, contract manufacturers, and retail-ready alternative protein brands.
Pricing Analysis
Yield-per-bioreactor-run anchors value-based pricing for precision fermentation capacity, with contract manufacturers charging premiums tied to output guarantees rather than input volumes. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified facilities from food-grade operations and pilot-scale shared kitchens. Cost compression in standard-tier extrusion equipment is intensifying because Chinese manufacturers are exporting surplus capacity into European and North American markets. Retail chains exhibit the highest price sensitivity due to private-label margin constraints, while venture-backed biotechnology specialists prioritize throughput reliability over unit cost.
Supply Chain Analysis
FDA food safety modernization compliance and EFSA novel food authorization requirements gate supplier qualification, extending vendor onboarding timelines and concentrating procurement authority among established certification holders. Bioreactor manufacturing draws from Germany, China, and the United States, with precision engineering components anchored in Eindhoven and automation controls sourced from Shenzhen. Pharmaceutical-grade growth media, plant protein isolates, and packaging films rest on concentrated input supply. Single-source vulnerability in Chinese fine chemical growth media exposes producers to export restriction risk. Distribution runs through contract manufacturing organizations that consolidate batch production for multiple brand clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
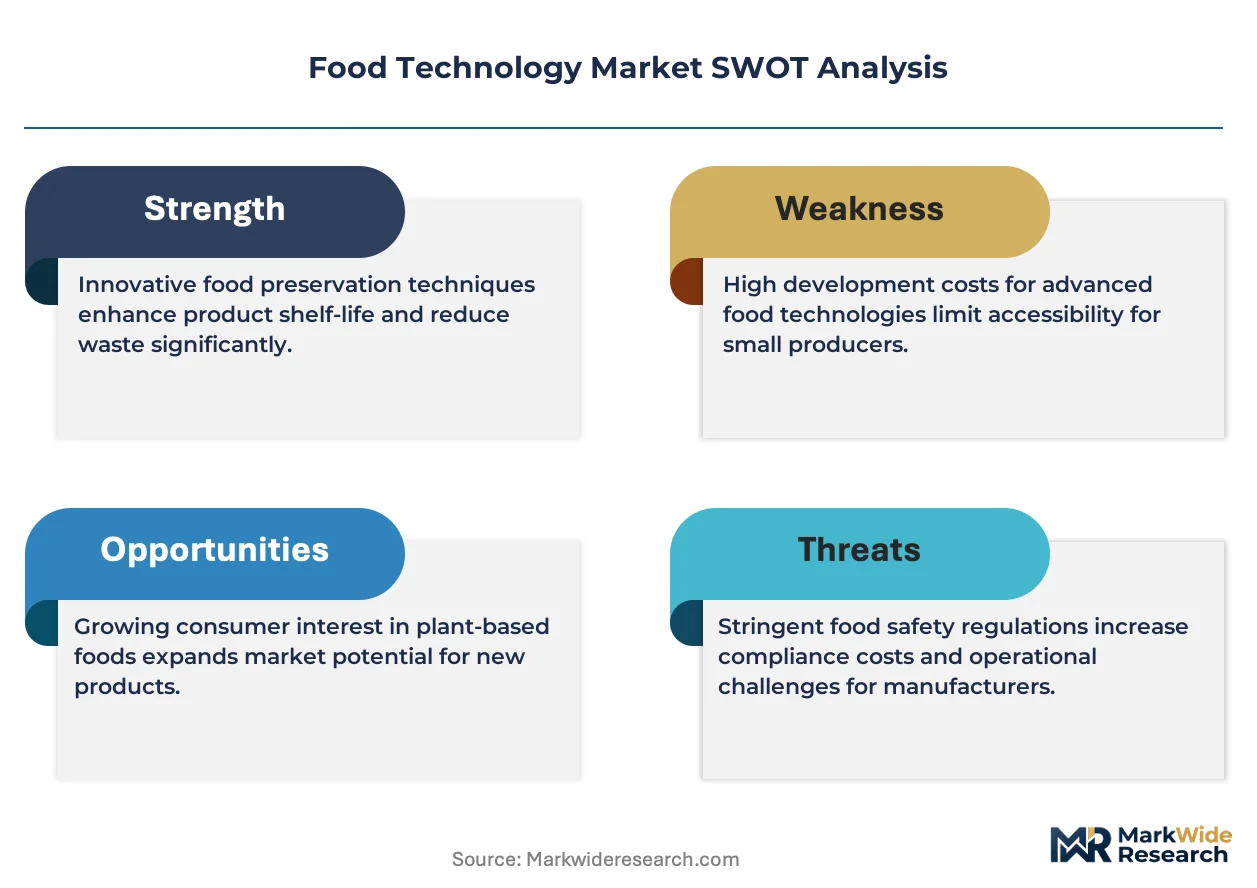
EFSA's eighteen-to-twenty-four month novel food authorization timeline constructs a cost-of-compliance moat that rewards early regulatory investment and disadvantages undercapitalized entrants.
For Market Incumbents: Lock in bioreactor capacity allocation through eighteen-month forward equipment reservations before competitors complete regulatory filings. Secure backward integration into precision fermentation feedstock supply to offset pharmaceutical-grade growth media price volatility from Chinese manufacturers. Cultivated meat specialists and plant protein isolate platforms represent the primary substitution threats requiring defensive patent positioning.
For New Entrants and Emerging Players: Enter via Singapore and Israel where regulatory clarity for cell-cultured products supports commercial scale-up without parallel EFSA authorization delays. Target foodservice distribution contracts with institutional kitchens and QSR chains that bypass retail slotting fee barriers constraining CPG alternative protein launches. A hybrid formulation approach combining plant protein isolates with cultivated fat tissue offers the most penetrable white-space positioning.
For Investors and Strategic Acquirers: FDA GRAS self-affirmation pathway completion is the leading indicator that precision fermentation operators have achieved technical de-risking sufficient for Series C scaling capital. Five-to-ten year viability favors biotechnology specialists with locked offtake agreements and parallel regulatory filings across FDA and EFSA jurisdictions. Contract manufacturing organizations with dual-use pharmaceutical and food-grade certifications represent the priority acquisition archetype as facility scarcity intensifies.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Bioreactor Capacity Reservation | Eighteen-month equipment backlogs force early capital commitment before regulatory clearance. |
| Parallel Regulatory Pathway Navigation | Simultaneous FDA GRAS and EFSA novel food filings compress time-to-market for fermentation-derived ingredients. |
| Hybrid Formulation Development | Convergence of plant isolates with cultivated fat addresses taste-performance gaps in 100% animal-free products. |
| Foodservice Direct Supply Contracting | Institutional kitchen and QSR partnerships bypass retail slotting fees that constrain CPG alternative protein launches. |
| Precision Fermentation Feedstock Integration | Backward integration into growth media production mitigates Chinese fine chemical supply concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-validated through primary interviews with precision fermentation operators, bioprocess engineering directors, contract manufacturing executives, and food manufacturer procurement leads. FDA GRAS notifications, EFSA novel food applications, SAMR GB standard publications, and bioreactor manufacturer order backlogs supplied quantitative anchors. Bottom-up equipment shipment analysis and top-down ingredient demand modeling were triangulated against venture capital deployment patterns.
Segment-level granularity modeled biotechnology platforms, artificial intelligence applications, IoT solutions, and robotics across meat processing, dairy, and bakery end-uses. CAGRs were derived from installed base depreciation cycles and replacement demand elasticity throughout the projection horizon. Precision fermentation capacity expansion timelines, regulatory authorization success rates, and foodservice channel penetration curves served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA authorization delays or Chinese growth media export restrictions. Forecasts reflect assumptions regarding regulatory parallelism, equipment delivery schedules, and alternative protein consumer adoption curves. A model refresh is warranted upon material change in FDA or EFSA novel food guidance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Lepidolite Market
Others
Smart Card Contactless Ticketing Market
Others
Dental Ceramics Market
Others
Industrial Tablet PC Market
Others
China 3D Printing Construction Market
Others
High-End Servers Market
Others
Pollen Allergy Market
Others
Powder Coating Equipment Market
Others
Spend Analytics Market
Others
Storage Dewars Market
Others
Global Military and Aerospace Sensors Market
Others
Aircraft Exterior Lighting Market
Others
Wearable AI Market
Others
Global Digital Caliper Market
Others
Africa Smart Card Market
Others
Brown Ht Market