
 Europe Legal Services Market | 2026-2036
Europe Legal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Legal Services Market Insights
Mid-market enterprises is bifurcating demand away from traditional Fortune 500 retainers across Europe. Clifford Chance leverages its London-Frankfurt corridor to anchor cross-border M&A advisory. DLA Piper competes through technology-sector specialization, while Pinsent Masons dominates infrastructure and energy mandates.
Europe legal services encompass advisory, transactional, and dispute-resolution functions delivered by solicitors, barristers, and multidisciplinary professional networks, typically governed by national bar associations and EU-wide professional conduct codes. These services facilitate contract enforcement, regulatory compliance, risk allocation, and rights protection across commercial and civil domains. Corporate law and intellectual property command premium fee structures given cross-border complexity, while litigation segments face margin compression from alternative fee arrangements. The outsourced delivery model is gaining traction as general counsel seek variable cost structures without sacrificing specialist access.
The EU AI Act, GDPR, and national bar association ethical frameworks collectively elevate compliance spending among European corporates. EMA and national financial regulators in Frankfurt and Paris intensify scrutiny of cross-border advisory conflicts. Stakeholders must monitor how EU Green Deal disclosure rules and CSRD reporting obligations redirect legal procurement toward environmental and governance specialists.
Market Dynamics
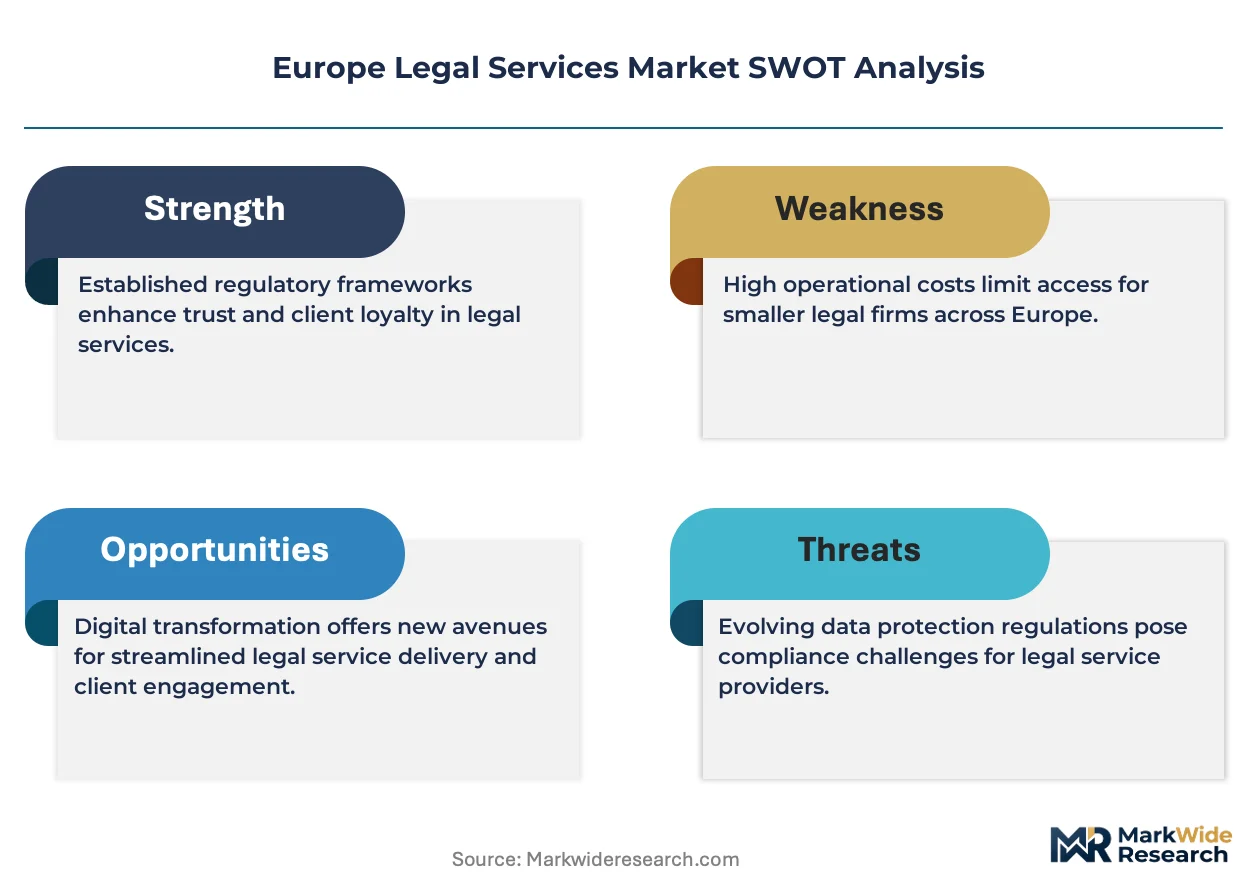
The EU AI Act and CSRD disclosure mandates are forcing European corporates to restructure legal procurement, diverting spend from traditional litigation toward regulatory advisory and compliance architecture.
Growth Catalysts
- EU AI Act compliance architecture:Corporates in Frankfurt and Paris require dedicated AI governance frameworks, creating sustained demand for regulatory specialists versed in algorithmic accountability and risk classification protocols.
- Mid-market enterprise expansion:German and Dutch mid-caps are establishing captive legal functions for cross-border M&A, driving advisory volume outside traditional Fortune 500 retainer pools.
- CSRD reporting obligations:The Corporate Sustainability Reporting Directive mandates granular ESG disclosure, redirecting procurement toward environmental and governance specialists with technical accounting integration.
Market Restraints
- Talent concentration in London-Frankfurt corridor:Elite regulatory and M&A capabilities cluster in two cities, inflating partner-level compensation and constraining service scalability for peripheral mandates.
- Alternative fee arrangement compression:Litigation segments face margin erosion as general counsel mandate fixed-fee structures for discovery and document review, squeezing traditional hourly billing models.
- Technology firm vertical integration:Major technology platforms are building in-house legal operations centers in Dublin and Amsterdam, reducing external counsel dependency for routine contract work.
Strategic Opportunities
- Central and Eastern Europe regulatory advisory:Polish and Czech corporates lack mature compliance infrastructure for GDPR and EU AI Act implementation, creating first-mover advantage for Western firms with local language capability.
- Climate litigation defense specialization:The EU Green Deal is generating shareholder and activist litigation against carbon-intensive industries, opening demand for niche defense practices.
- Legal technology platform integration:Convergence of contract lifecycle management software with AI-powered precedent analysis enables hybrid advisory models combining human expertise with automated document generation.
Industry Challenges
- Multidisciplinary skill synthesis:CSRD and EU AI Act compliance require lawyers to integrate technical accounting, data engineering, and ethics expertise, creating recruitment friction for traditional law firm partnership tracks.
- Cross-border conflicts clearance:EMA and national financial regulators in Frankfurt intensify scrutiny of advisory conflicts, extending engagement timelines and requiring complex organizational separation of teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Legal Services Market |
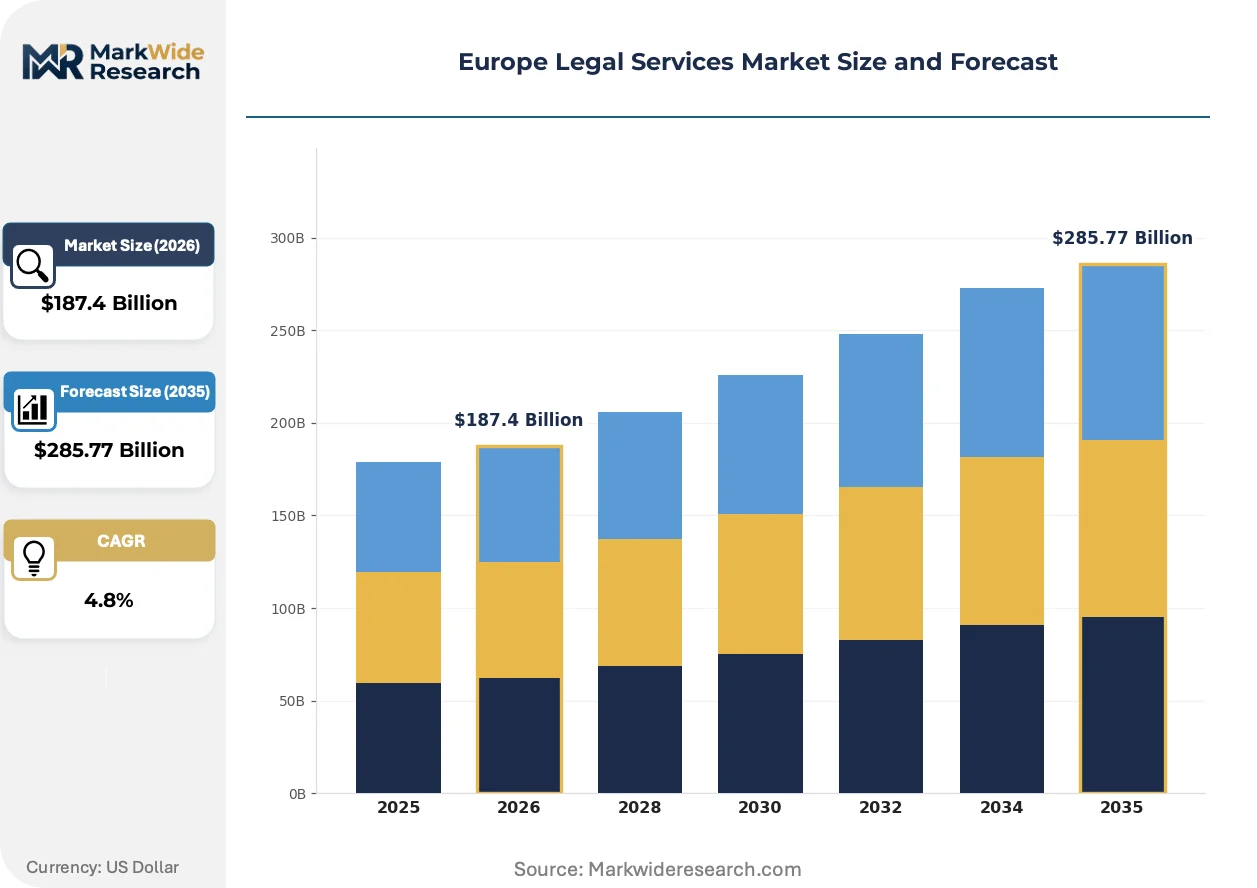
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Law, Intellectual Property, Litigation, Tax Law Client Type: Individuals, Corporations, Government Agencies, NGOs Delivery Model: In-House, Outsourced, Hybrid, Online Practice Area: Family Law, Employment Law, Environmental Law, Criminal Defense |
| Companies Covered | Clifford Chance, DLA Piper, Latham & Watkins, Baker & McKenzie, PwC, Deloitte, Ernst & Young, KPMG, Pinsent Masons, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Legal Services Market Trends and Innovations
Generative AI tools and embedded compliance platforms are restructuring how European corporates consume legal expertise, compressing traditional advisory relationships into technology-augmented service layers.
Generative AI contract analysis is supplanting junior associate document review in due diligence and lease abstraction workflows. German automotive and industrial conglomerates are deploying these tools at scale across procurement and real estate functions. This compression is reallocating advisory spend toward strategic negotiation and regulatory interpretation rather than mechanical drafting.
The EU AI Act's risk-based classification system mandates legal involvement in product development gates for high-risk AI applications. Medical device and financial services manufacturers in France and Germany must embed compliance checkpoints before market release. This integration is elevating in-house legal functions and creating retainer relationships that span product lifecycle rather than episodic transactions.
General counsel in the Netherlands and Scandinavia are unbundling litigation support from strategic advisory, sourcing discovery and document management through alternative legal service providers while retaining elite firms for bet-the-company disputes. This bifurcation is fragmenting traditional full-service relationships and pressuring mid-tier firms to demonstrate specialist depth or operational efficiency advantages.
Europe Legal Services Market Segmentation
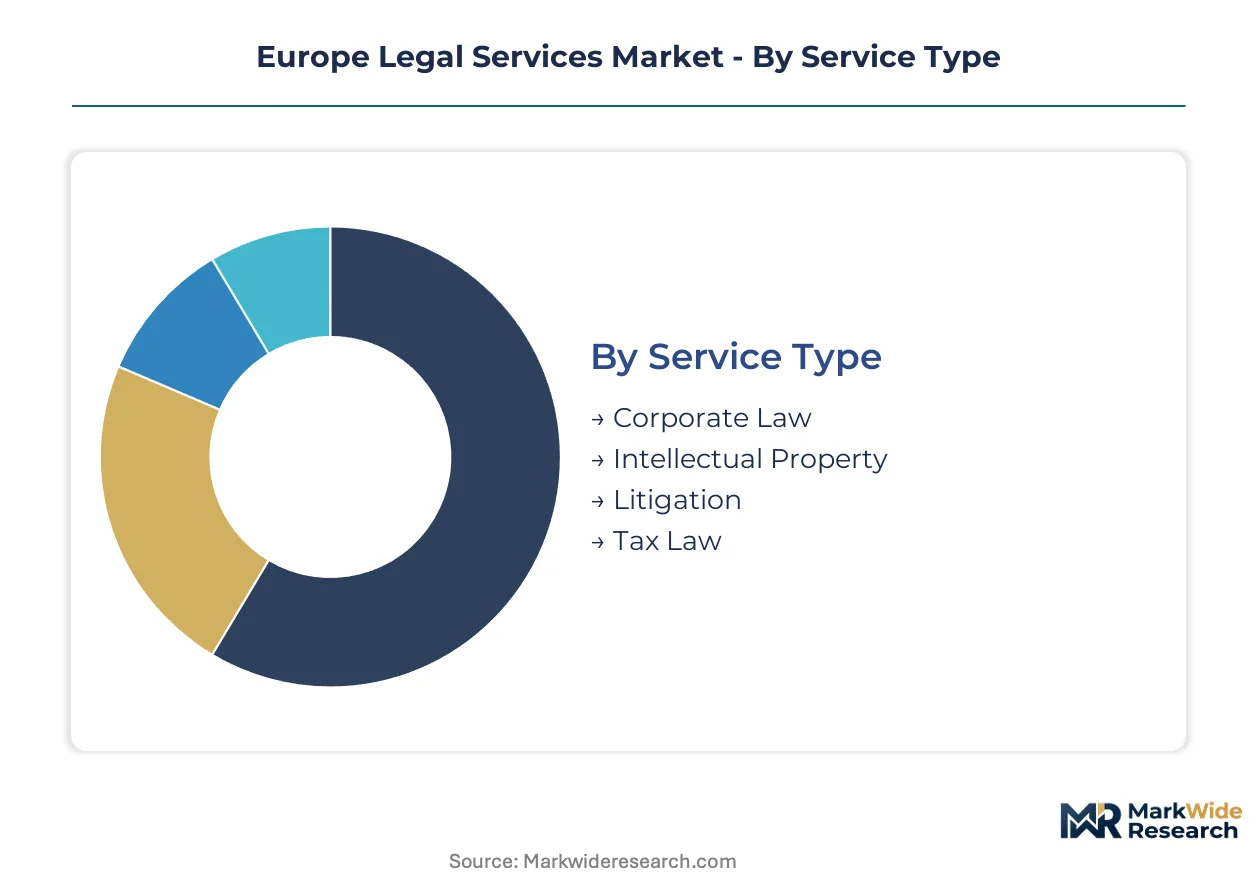
Segmentation reveals how procurement channels fragment across service types and client profiles. Understanding these divisions exposes where margin pools concentrate and which delivery models capture regulatory-driven demand.
Service Type:
Channel mix varies sharply by service complexity, with high-stakes advisory flowing through retained partnerships while commoditized work shifts to alternative providers.
- Corporate Law:Cross-border M&A and governance mandates command premium retainers through elite firm partnerships. German automotive and Dutch industrial conglomerates anchor demand in Frankfurt-Amsterdam corridors, with CSRD compliance now embedded in board advisory.
- Intellectual Property:Patent prosecution and portfolio management blend technical legal expertise with sector-specific engineering knowledge. French medical device manufacturers and German machinery exporters drive filing volume, constrained by EPO examination backlogs and unitary patent system transition costs.
- Litigation:Discovery and document review increasingly route through alternative legal service providers. Fixed-fee compression squeezes traditional hourly models in commercial disputes.
- Tax Law:Transfer pricing and EU state aid defense require coordinated multi-jurisdictional teams. Dublin and Luxembourg serve as coordination hubs for cross-border restructuring.
Corporate Law dominates installed base. Intellectual Property is where expansion concentrates.
Client Type:
Cost tier stratification separates bespoke advisory for complex entities from standardized products for individual consumers.
- Corporations:General counsel functions bifurcate between strategic regulatory advisory and operational contract management. Mid-market German and Dutch enterprises are building captive legal operations for cross-border M&A, diverting spend from traditional Fortune 500 retainer pools.
- Government Agencies:Public procurement frameworks mandate panel appointments with strict fee caps. Infrastructure and state aid mandates in France and Italy flow through pre-qualified consortia.
- Individuals:Consumer legal services concentrate in family law and property transactions, increasingly intermediated through digital platforms. Price transparency pressures traditional high-street solicitors.
- NGOs:Human rights and environmental litigation funding creates contingent fee opportunities. Climate litigation against carbon-intensive industries opens niche defense demand.
Corporations anchor revenue concentration. Government Agencies present the steepest expansion trajectory for regulatory specialist firms.
Delivery Model:
Volume distribution tracks maturity of technology integration and client risk tolerance for automated workflows.
- Hybrid:Combines embedded compliance checkpoints with external specialist escalation. EU AI Act implementation in French medical device and German financial services manufacturing elevates this model across product lifecycles.
- Outsourced:Discovery, document review, and routine contract management flow to alternative legal service providers. Netherlands and Scandinavian general counsel unbundle litigation support from strategic advisory.
- In-House:Technology platforms in Dublin and Amsterdam build captive legal operations centers, reducing external dependency for standardized contract work.
- Online:Consumer-facing platforms automate property transactions and simple dispute resolution. Limited penetration in high-complexity commercial matters.
Hybrid models dominate technology-forward client segments. Outsourced delivery is gaining share fastest in litigation support functions.
Practice Area:
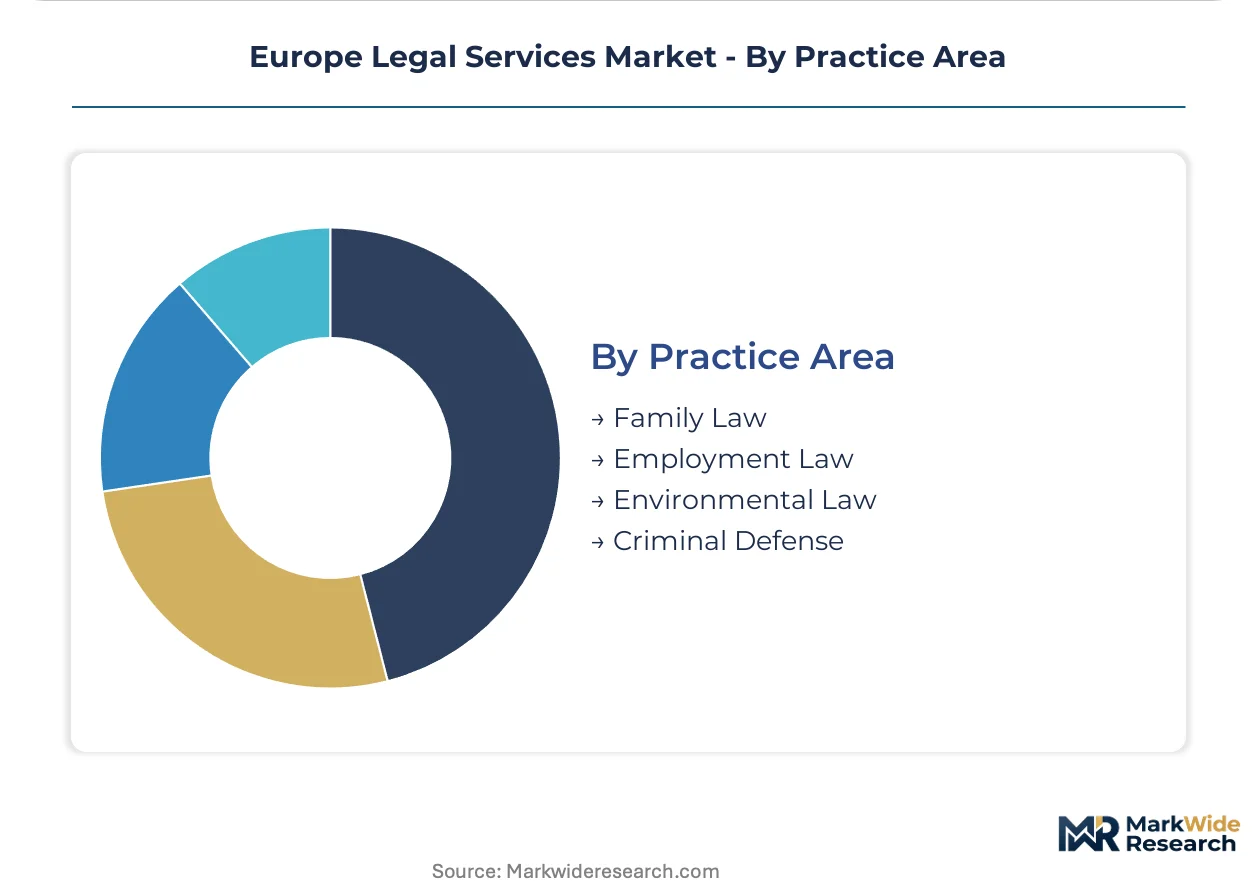
Geographic concentration of specialist expertise creates supply bottlenecks in high-growth regulatory domains.
- Environmental Law:CSRD disclosure mandates and EU Green Deal litigation generate integrated advisory demand spanning technical accounting and governance architecture. Polish and Czech corporates lack mature compliance infrastructure, creating first-mover openings for Western firms with local language capability.
- Employment Law:Cross-border workforce restructuring and whistleblower directive implementation drive advisory volume. German works council consultation requirements add procedural complexity.
- Family Law:High-net-worth matrimonial disputes with cross-border asset structures command specialist arbitration. Limited technology disruption to date.
- Criminal Defense:Corporate criminal liability expansion under national implementations of EU directives elevates white-collar practice. Elite barrister chambers in London retain dominance in complex fraud.
Environmental Law commands premium fee expansion. Employment Law sustains steady volume across economic cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Channel Tunnel and North Sea grid interconnects anchor London-Frankfurt as Europe's dominant legal corridor, with regulatory complexity driving advisory demand across multiple jurisdictions.
Germany
Frankfurt's financial regulator BaFin intensifies scrutiny of cross-border advisory conflicts, while German automotive and industrial conglomerates anchor demand for CSRD compliance architecture. The EU AI Act's risk classification protocols mandate legal involvement in product development gates for medical device manufacturers in Baden-Württemberg.
United Kingdom
London retains dominance in complex fraud defense through elite barrister chambers, though Brexit-related regulatory divergence redirects some EU mandate flow. The Solicitors Regulation Authority enforces professional conduct codes while Clifford Chance leverages its London-Frankfurt corridor for M&A advisory.
France
ANSM and CNIL enforcement actions elevate compliance spending among Paris-based corporates, with medical device manufacturers embedding legal checkpoints before market release. The EU Green Deal generates shareholder litigation against carbon-intensive industries, opening defense demand for environmental specialists.
Netherlands
Amsterdam serves as a coordination hub for transfer pricing and EU state aid defense, while Dutch general counsel unbundle litigation support from strategic advisory. Rotterdam's port infrastructure underwrites maritime and trade finance legal specialization.
Poland
Polish corporates lack mature compliance infrastructure for GDPR and EU AI Act implementation, creating first-mover openings for Western firms with local language capability. Warsaw's emerging fintech cluster drives demand for regulatory specialists versed in algorithmic accountability.
Europe Legal Services Market Competitive Landscape
Listed leaders compete with private specialists across partnership structures and capital access. The market fragments into three tiers: Magic Circle firms commanding premium retainers for cross-border M&A, Big Four accounting networks integrating legal advisory with audit and tax functions, and mid-tier specialists competing on sector depth or operational efficiency. Strategic moves concentrate on lateral partner recruitment for regulatory expertise and technology platform partnerships for contract automation.
Within the full-service partnership tier, Clifford Chance and DLA Piper occupy positions defined by geographic corridor strength and sector specialization respectively. Clifford Chance anchors cross-border M&A advisory through its London-Frankfurt presence. DLA Piper exemplifies technology-sector focus as a competitive differentiator. Among specialist boutiques, Pinsent Masons represents infrastructure and energy mandate dominance. These three exemplify how scale, sector depth, and geographic positioning create defensible market positions.
| Leading Market Players |
|---|
| Clifford Chance |
| DLA Piper |
| Latham & Watkins |
| Baker & McKenzie |
| PwC |
| Deloitte |
| Ernst & Young |
| KPMG |
| Pinsent Masons |
| Others |
Pricing and Supply Chain Analysis
Long-term retainer agreements with embedded rate escalation clauses lock in supply access to elite partner bandwidth while providing fee visibility across multi-year mandates. These structures concentrate pricing power with Magic Circle and Big Four networks in Frankfurt and London, where BaFin scrutiny and EU AI Act compliance complexity sustain premium rate tiers.
Pricing Analysis
Volume-discount tiering structures separate bet-the-company litigation retainers from commoditized discovery and contract management work. Three-tier pricing structure across premium, standard, and economy levels differentiates Clifford Chance partnership rates from mid-tier fixed-fee offerings and alternative legal service provider unit pricing. Pricing pressure stems from general counsel unbundling litigation support and mandating fixed-fee discovery arrangements. Mid-market enterprises exhibit highest price sensitivity, while Fortune 500 general counsel prioritize specialist access over rate competition.
Supply Chain Analysis
Just-in-time talent deployment preferences dominate as firms maintain lean partner benches and activate contract lawyer pools for surge capacity. Elite regulatory and M&A capabilities concentrate in the United Kingdom, Germany, and the Netherlands, drawing from London barrister chambers, Frankfurt BaFin specialists, and Amsterdam tax restructuring expertise. Supply chain risk hinges on single-source vulnerability in the London-Frankfurt corridor, where lateral partner recruitment wars inflate compensation. Distribution runs through retained partnership networks for strategic advisory and alternative legal service providers for operational legal functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe legal services market sits in cyclical recovery as regulatory complexity from the EU AI Act and CSRD mandates drives advisory demand above historical litigation troughs.
For Market Incumbents: Consolidate regulatory specialist capabilities through lateral partner recruitment in AI governance and ESG disclosure architecture. Deepen captive relationships with German automotive and Dutch industrial conglomerates facing CSRD implementation deadlines. Vertical integration into contract lifecycle management software partnerships defends against technology firm in-house legal operations expansion in Dublin and Amsterdam.
For New Entrants and Emerging Players: Lead with Polish and Czech market entry targeting GDPR and EU AI Act compliance gaps among mid-caps lacking mature infrastructure. Local language capability combined with Western regulatory expertise captures first-mover advantage in Central and Eastern Europe. Alternative fee arrangement innovation for discovery and document review unbundles litigation support from incumbent full-service relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist boutiques with demonstrated sector depth in environmental law or algorithmic accountability. Long-term viability rests on regulatory complexity sustaining premium advisory demand beyond automation displacement of mechanical legal work. Watch EMA and national financial regulator enforcement intensity as inflection indicator for compliance spending acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Lateral Partner Recruitment | Captures scarce EU AI Act and CSRD specialist expertise before competitor lock-in. |
| Technology Platform Partnership | Integrates contract lifecycle management with AI-powered precedent analysis for hybrid delivery. |
| Geographic Expansion | Establishes Warsaw and Prague presence to serve Polish and Czech compliance infrastructure gaps. |
| Sector Specialization Deepening | Builds climate litigation defense capabilities as EU Green Deal generates activist shareholder actions. |
| Alternative Delivery Model Launch | Unbundles discovery and document review from strategic advisory to capture mid-market price sensitivity. |
Research Methodology
Desk research of bar association regulatory filings, EU directive implementation guidance, and legal industry compensation surveys preceded structured interviews with managing partners at Magic Circle firms, general counsel at German automotive conglomerates, and procurement leads at Dutch industrial enterprises. Primary fieldwork with alternative legal service provider operations directors and Big Four legal network heads validated secondary findings. Bottom-up mandate volume estimates triangulated against top-down market value reconstructions from partnership revenue disclosures.
Variance decomposition across service type, client segment, and delivery model dimensions shaped the analytical framework. CAGRs derived from regression of historical retainer growth against regulatory event timing, with EU AI Act implementation phases and CSRD reporting deadlines as key forecast inputs across the projection horizon. Segmentation modeling incorporated practice area concentration, geographic corridor strength, and technology adoption intensity as orthogonal dimensions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory complexity or accelerated technology substitution would require recalibration. Forecasts assume continued fragmentation between elite advisory and commoditized legal work. Revision becomes warranted when generative AI capability crosses thresholds displacing strategic negotiation functions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Ultrasonic Flow Meter Market
Others
Czech Republic Market
Others
Global Learning Analytics Market
Others
Free Space Optics (FSO) Market
Others
5G Enabled Healthcare Services Market
Others
Edge Computing in Healthcare Market
Others
Pickup Truck Market
Others
Smart Home and Office Market
Others
Healthcare Bioconvergence Market
Others
Global Phablets and Superphones Market
Others
Bio-Imaging Technologies Market
Others
Global Smartphone ODM Market
Others
Global Microcontroller Embedded Systems Market
Others
Deep Sea Mining Market
Others
Global Molded Plastics Market
Others
North America Flexographic Printing Market