
 Mobile Retina Services Market | 2026-2036
Mobile Retina Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Retina Services Market Analytics
Teleophthalmology distribution is fragmenting as cloud-based platforms, direct-to-clinic hardware vendors, and insurer-backed screening networks compete for channel control. ZEISS International leverages its installed base of diagnostic equipment to bundle mobile imaging modules. Johnson & Johnson anchors its position through R&D intensity in AI-driven disease detection algorithms. Alcon competes by extending its surgical planning software into preoperative mobile consultation workflows.
Mobile retina services encompass remote ophthalmic diagnostics delivered through portable fundus cameras, smartphone-adapted optical coherence tomography peripherals, and cloud-connected imaging platforms that transmit retinal data to specialists for interpretation. These systems typically capture high-resolution posterior pole images at 45-degree fields of view with automated quality assessment, enabling diabetic retinopathy and age-related macular degeneration screening outside traditional clinic settings. Diagnostic imaging leads service type revenue due to recurring image interpretation fees and equipment leasing structures, while optical coherence tomography represents the fastest-expanding technology segment as handheld devices narrow the resolution gap with stationary systems. Patient-facing mobile apps remain the smallest but highest-margin technology category given minimal incremental delivery cost per user.
The FDA regulates mobile retina software under its software-as-medical-device framework, requiring clinical validation for diagnostic claims while the EU MDR mandates notified body review for class IIa imaging peripherals. Japan's PMDA has streamlined approval for AI-assisted grading tools, reshaping competitive access across its prefecture-based screening programs. Stakeholders must monitor evolving reimbursement codes for remote interpretation services and decide whether to build proprietary AI models or license validated algorithms from specialized developers.
Market Dynamics
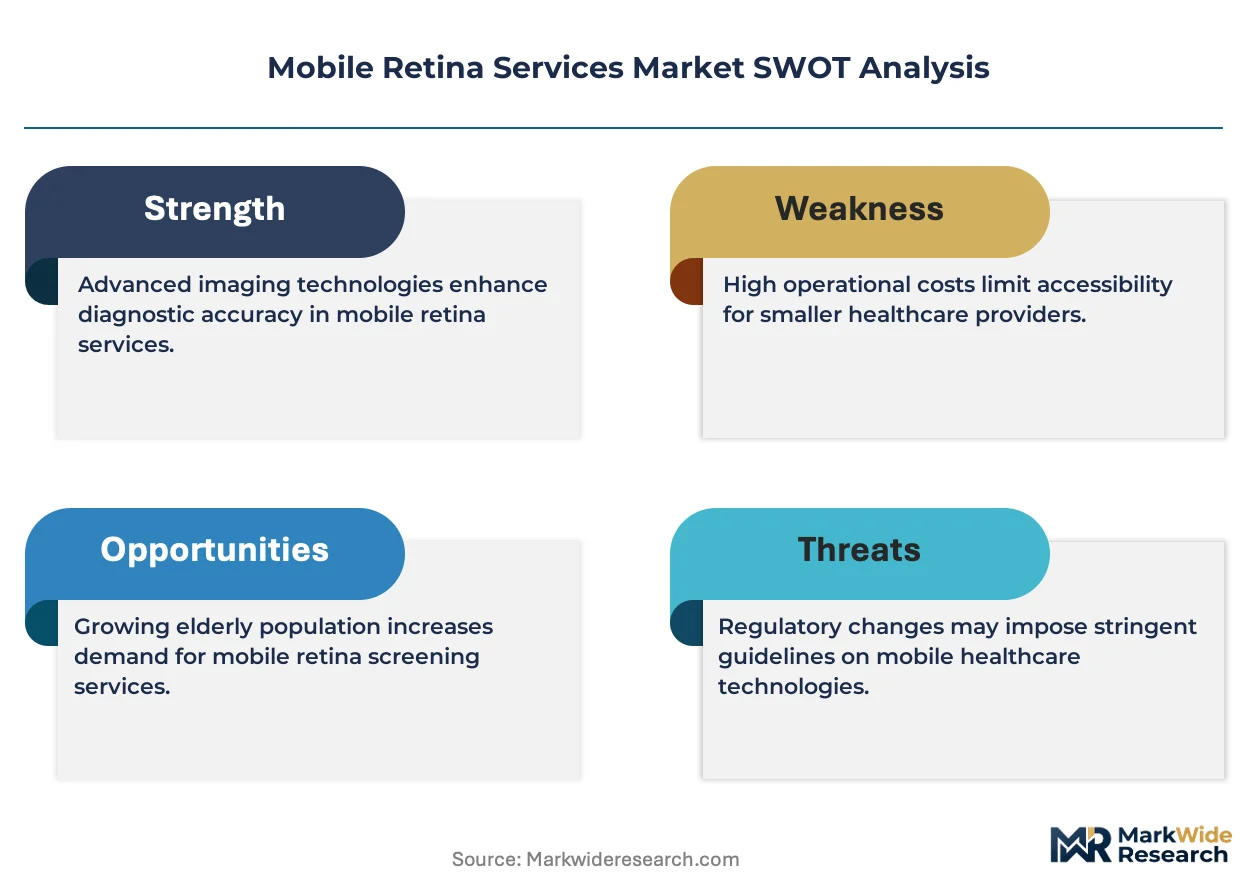
The FDA's software-as-medical-device pathway compresses clearance timelines for AI-enabled fundus tools, while hospital networks consolidate purchasing power around bundled diagnostic platforms. This regulatory acceleration collides with reimbursement uncertainty for remote interpretation services.
Growth Catalysts
- Diabetic retinopathy screening mandates:United States Medicare reimbursement codes for teleophthalmology expand preventive care access in underserved counties.
- Handheld OCT resolution gains:Optical coherence tomography peripherals now match stationary system clarity, enabling point-of-care deployment in primary care clinics.
- Japan's prefecture-based programs:PMDA streamlined approval for AI-assisted grading tools accelerates population-wide screening adoption.
Market Restraints
- Specialist interpreter shortages:Certified retinal specialists concentrate in urban academic medical centers, creating interpretation bottlenecks for rural image transmission.
- EU MDR notified body capacity:Class IIa imaging peripheral reviews face 12-18 month backlogs at designated conformity assessment organizations.
- Smartphone camera substitution:Low-cost adapter systems threaten dedicated fundus camera hardware margins in price-sensitive clinic segments.
Strategic Opportunities
- Germany's ambulatory care networks:Digitale-Versorgung-Gesetz reimbursement for remote diagnostics opens integrated care organization procurement channels.
- AI-ophthalmologist workflow convergence:Automated pre-screening algorithms paired with specialist validation protocols reduce per-case interpretation burden.
- Direct-to-employer screening contracts:Self-insured corporations contract mobile retina services for workforce diabetic complication prevention.
Industry Challenges
- Multi-jurisdiction quality validation:Image acquisition standards vary across FDA, EU MDR, and PMDA frameworks, complicating unified algorithm training datasets.
- Legacy EHR integration friction:Cloud-connected imaging platforms require custom HL7 FHIR interfaces with entrenched hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Retina Services Market |
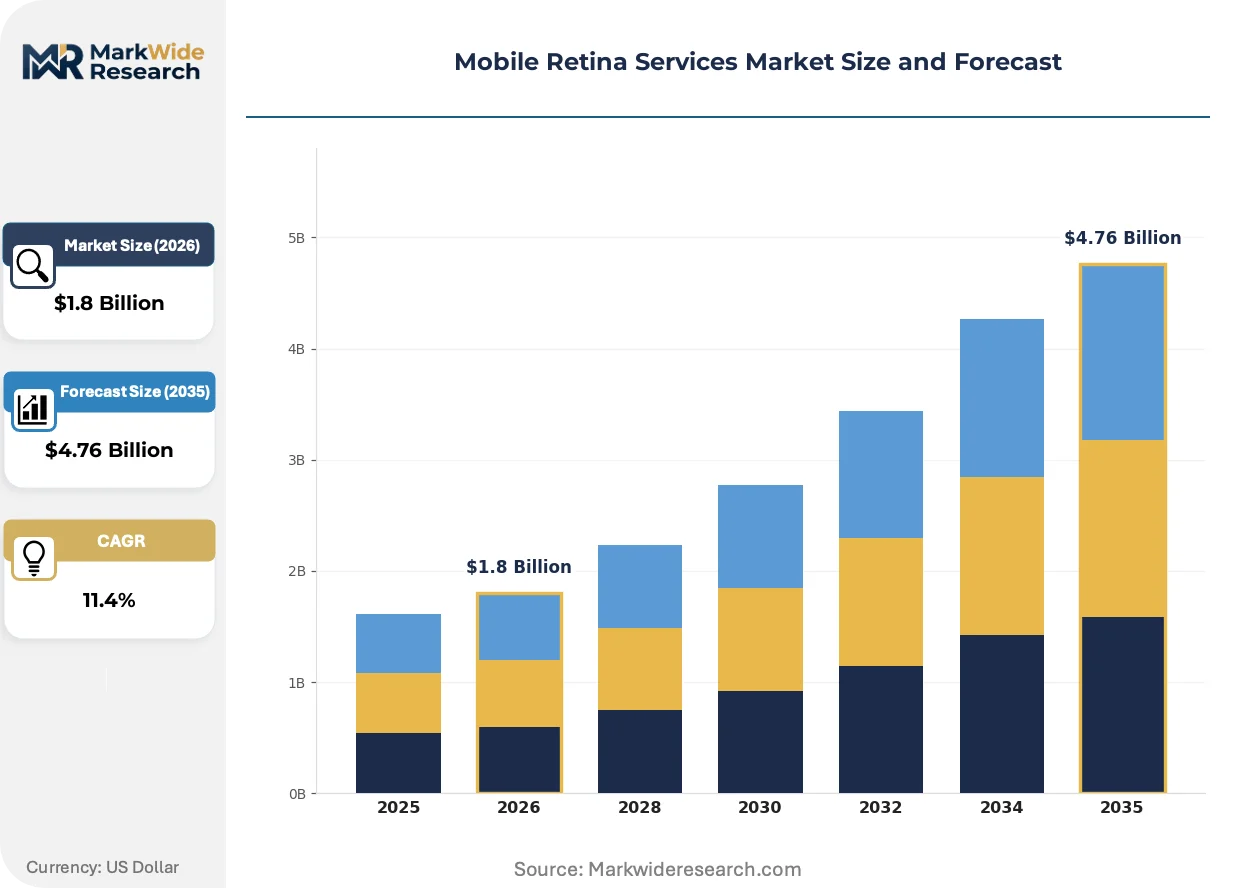
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remote Consultation, Diagnostic Imaging, Treatment Monitoring, Patient Education Technology: Fundus Photography, Optical Coherence Tomography, Ultrasound Imaging, Mobile Apps End User: Ophthalmologists, Optometrists, Healthcare Providers, Patients Application: Screening, Disease Management, Research, Surgical Planning |
| Companies Covered | Johnson & Johnson, Alcon, ZEISS International, Vision Care Associates, Retina Labs, OnSight Vision, Inc., EyeNetra Inc., Visibly, Warby Parker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Retina Services Market Evolving Landscape
Portable diagnostic hardware and automated interpretation algorithms are compressing the distance between image capture and clinical decision. Three forces reshape competitive positioning.
Smartphone-adapted fundus cameras with automated quality assessment is digitizing the screening workflow for primary care physicians. Federally qualified health centers deploy these peripherals during routine diabetes management visits. The technology collapses referral delays that previously stretched 90-180 days.
Japan's PMDA has created a dedicated review track for AI-assisted ophthalmic devices, cutting approval timelines by 40% compared to conventional pathways. Domestic manufacturers file simultaneous 510(k) and Shonin applications to synchronize United States and Japanese market entry. This regulatory arbitrage favors developers with dual-jurisdiction clinical validation capabilities.
Hospital procurement committees now unbundle equipment acquisition from interpretation service contracts, forcing vendors to compete on per-image pricing rather than capital lease structures. Specialty eye care clinics respond by forming regional reading centers that aggregate demand across multiple health systems. Germany's Krankenkassen have piloted capitated payment models for diabetic eye disease prevention.
Mobile Retina Services Market Segmentation
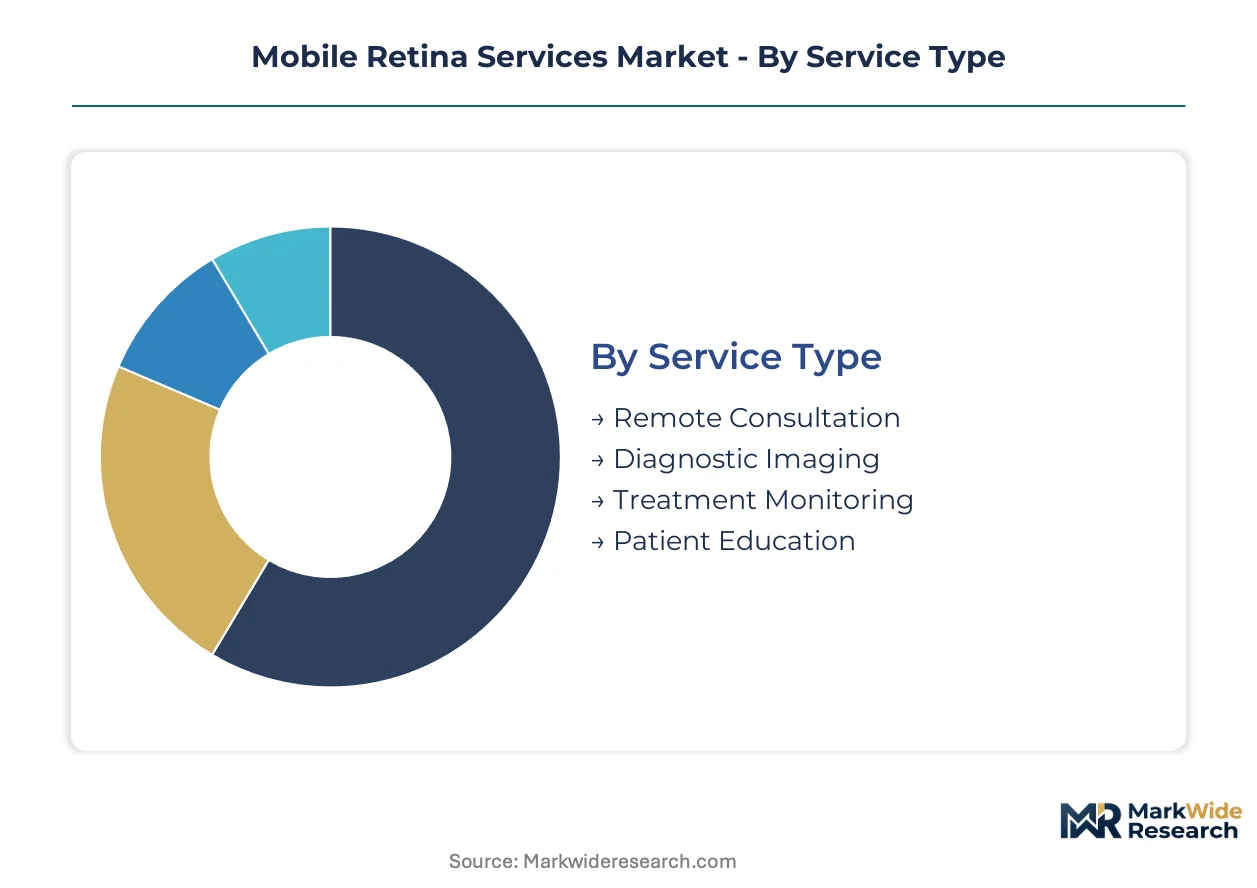
Mobile retina services fragment across four operational dimensions that determine pricing models, regulatory pathways, and customer acquisition costs. Each segmentation axis reveals distinct margin profiles and competitive intensity patterns.
Service Type:
Providers structure offerings around the clinical workflow spectrum from initial patient contact through longitudinal care.
- Diagnostic Imaging:High-resolution fundus capture with automated quality assessment generates recurring revenue through per-image interpretation fees and equipment leasing structures. Hospital networks in the United States consolidate purchasing around bundled platforms that integrate capture hardware with cloud transmission.
- Remote Consultation:Real-time video-linked specialist access enables preoperative planning and urgent case triage without patient travel. Germany's Digitale-Versorgung-Gesetz reimbursement codes accelerate adoption in ambulatory care networks seeking to reduce referral bottlenecks.
- Treatment Monitoring:Serial imaging protocols track disease progression between in-person visits.
- Patient Education:Automated retinal visualization tools explain pathology to drive compliance with screening schedules.
The dominant share belongs to Diagnostic Imaging, while Remote Consultation is closing the gap fastest.
Technology:
Hardware and software categories diverge sharply in capital intensity and margin architecture.
- Optical Coherence Tomography:Handheld peripherals now achieve resolution parity with stationary systems, enabling point-of-care deployment in primary care clinics across Japan's prefecture-based screening programs. PMDA's streamlined AI-assisted device track cuts approval timelines versus conventional pathways.
- Fundus Photography:Smartphone-adapted cameras with automated quality assessment digitize screening workflows for federally qualified health centers, collapsing 90-180 day referral delays into same-visit specialist review.
- Ultrasound Imaging:B-scan capabilities for media opacities where fundus visualization fails.
- Mobile Apps:Patient-facing platforms carry minimal incremental delivery cost per user, producing the highest margin profile despite smallest revenue base.
Optical Coherence Tomography commands premium pricing, though Mobile Apps demonstrate the steepest expansion trajectory.
End User:
Customer types span credentialed specialists through direct-to-consumer channels with diverging liability and reimbursement frameworks.
- Ophthalmologists:Retinal specialists concentrate interpretation demand in urban academic medical centers, creating geographic bottlenecks that AI pre-screening algorithms aim to relieve.
- Optometrists:Primary eye care providers in the United States leverage Medicare teleophthalmology reimbursement to expand diabetic retinopathy screening in underserved counties.
- Healthcare Providers:Integrated delivery networks negotiate unbundled equipment and service contracts.
- Patients:Direct-to-employer screening contracts with self-insured corporations bypass traditional clinical channels.
Healthcare Providers generate the largest contract values, while Patients represent the fastest-climbing adoption curve.
Application:
Use cases range from population-scale prevention through precision surgical intervention.
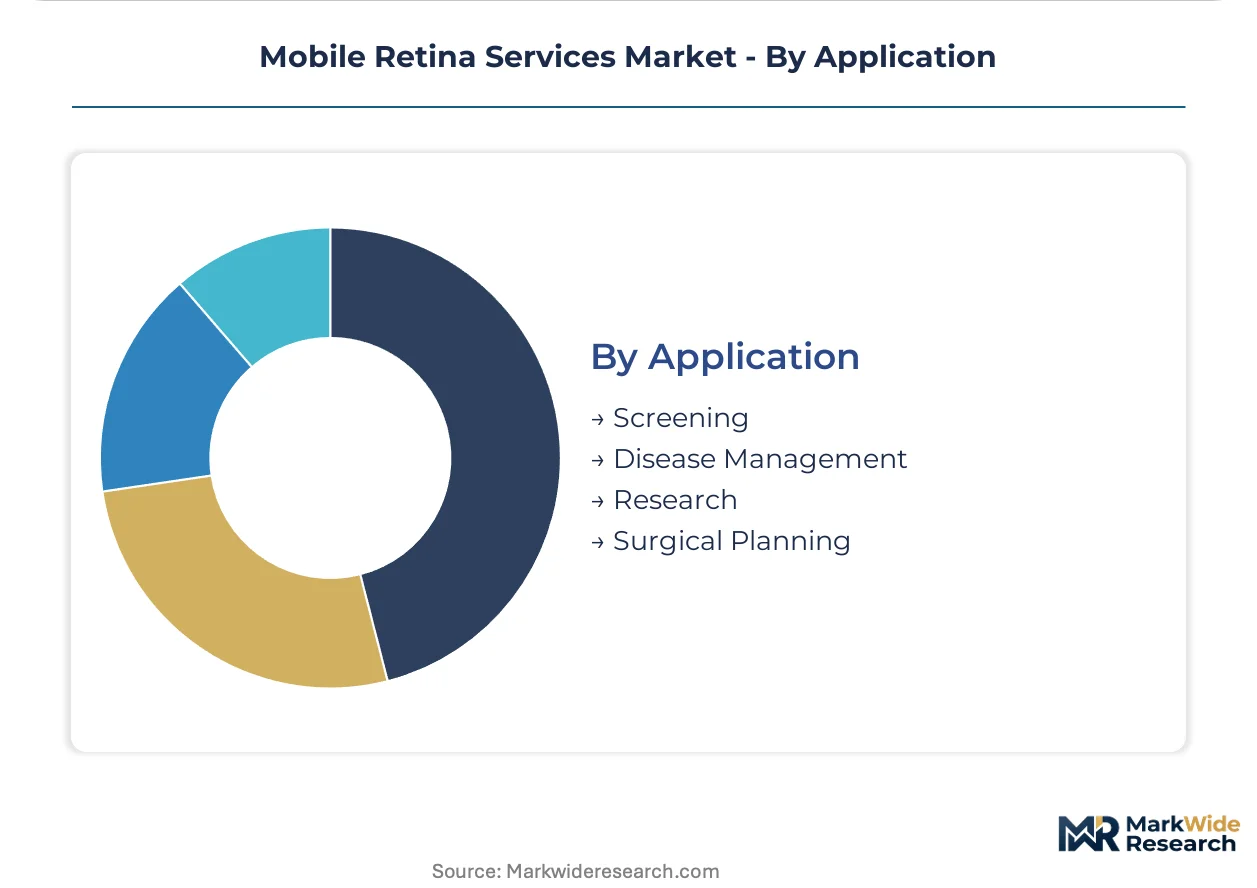
- Screening:Diabetic retinopathy and age-related macular detection programs in Japan and the United States drive volume through mandated prevention protocols and reimbursement support.
- Disease Management:Longitudinal monitoring of chronic retinal conditions requires recurring image interpretation and specialist validation workflows.
- Research:Clinical trial endpoints and algorithm training datasets demand standardized acquisition protocols.
- Surgical Planning:Preoperative mobile consultation workflows extend from diagnostic capture through operative scheduling.
Screening captures the dominant patient volume, while Surgical Planning is gaining share fastest among high-margin niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's prefecture-based screening programs and Germany's Digitale-Versorgung-Gesetz create policy templates that other jurisdictions replicate. Reimbursement frameworks in aging economies now explicitly cover remote retinal interpretation.
United States
Medicare teleophthalmology reimbursement codes expand preventive care access across underserved counties. The FDA's software-as-medical-device pathway compresses clearance timelines for AI-enabled fundus tools. Federally qualified health centers in rural Texas and Mississippi deploy smartphone-adapted cameras during routine diabetes management visits.
Germany
Ambulatory care networks seek to reduce referral bottlenecks through real-time video-linked specialist access. The Digitale-Versorgung-Gesetz reimbursement for remote diagnostics opens integrated care organization procurement channels. Bavaria's Krankenkassen pilot capitated payment models for diabetic eye disease prevention.
Japan
PMDA's streamlined approval track for AI-assisted ophthalmic devices cuts timelines versus conventional pathways. Prefecture-based screening programs accelerate population-wide adoption of handheld OCT peripherals. Domestic manufacturers in the Kanto region file simultaneous 510(k) and Shonin applications to synchronize United States and Japanese market entry.
United Kingdom
NHS England's diabetic eye screening program contracts mobile imaging services for community-based capture. MHRA alignment with EU MDR post-Brexit maintains notified body review requirements for class IIa imaging peripherals. London-based reading centers aggregate interpretation demand across multiple integrated care systems.
India
CDSCO's medical device rules classify AI-enabled fundus cameras as class C devices requiring import license or domestic manufacturing certification. Telemedicine practice guidelines issued by the national medical commission enable cross-state specialist consultation for retinal screening. Maharashtra's tier-two cities host pilot programs linking primary health centers with Mumbai-based ophthalmologists.
Mobile Retina Services Market Competitive Landscape
On the supply side, the industry is consolidating around bundled diagnostic platforms that integrate hardware leasing with cloud-based interpretation services. Hospital procurement committees now unbundle equipment acquisition from service contracts, forcing vendors to compete on per-image pricing. Three archetypes dominate: legacy optical equipment manufacturers extending into mobile modules, AI-native software developers seeking hardware partnerships, and regional reading centers aggregating specialist interpretation capacity. M&A activity concentrates on algorithm developers with dual-jurisdiction FDA-PMDA validation, while strategic partnerships between camera manufacturers and cloud platforms reshape distribution economics.
Within the legacy equipment tier, ZEISS International and Johnson & Johnson occupy positions anchored by installed bases of stationary diagnostic systems. Alcon represents the surgical-to-diagnostic extension archetype, leveraging operative planning software relationships into preoperative mobile consultation workflows. These three entities exemplify how incumbent optical manufacturers defend position through bundled platform strategies rather than standalone hardware sales.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Alcon |
| ZEISS International |
| Vision Care Associates |
| Retina Labs |
| OnSight Vision, Inc. |
| EyeNetra Inc. |
| Visibly |
| Warby Parker |
| Others |
Value Network & Pricing Analysis
Trans-Pacific air freight corridors connecting Shenzhen and Memphis carry high-value CMOS sensors and precision optics, with rate volatility compressing margins for handheld fundus camera manufacturers while amplifying price spreads between FDA-validated and uncertified equipment tiers. This logistics cost dynamic reinforces supply concentration among dual-jurisdiction certified vendors and forces downstream buyers into longer contract lock-ins.
Pricing Analysis
Certification level (FDA 510(k)/CE MDR/PMDA Shonin) creates the primary spread between premium and economy tiers in mobile retina services. Three-tier pricing structure across premium, standard, and economy levels dominates: hospital networks pay per-image interpretation fees bundled with hardware leases, while primary care clinics purchase smartphone-adapted peripherals on transactional spot terms. Cost compression in the economy tier is intensifying because low-cost Asian manufacturers flood price-sensitive segments with uncertified adapter systems. Federally qualified health centers exhibit highest price sensitivity, whereas integrated delivery networks prioritize validation pedigree over unit economics.
Supply Chain Analysis
Export control restrictions on high-resolution CMOS sensors and AI training chipsets limit flows from United States and Taiwan to Chinese equipment manufacturers, fragmenting global supply availability. Component sourcing centers on Japan for precision optics, South Korea for image sensors, and Germany for optical coherence tomography interferometers. Supply chain risk hinges on single-source vulnerability for PMDA-validated algorithm training datasets. Distribution runs through cloud-connected platform vendors who unbundle hardware procurement from interpretation service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile retina services exhibit defensive moat characteristics rooted in regulatory entrenchment: FDA 510(k) and PMDA Shonin clearances create multi-year validation barriers that protect incumbent interpretation platforms from software-only challengers.
For Market Incumbents: Insulate core interpretation revenue by embedding AI pre-screening tools directly into hospital EHR workflows, raising switching costs for health system procurement committees. Deepen backward integration into CMOS sensor supply through exclusive partnerships with Japanese optics houses, neutralizing the threat from smartphone camera substitution. Pursue dual-jurisdiction validation for next-generation handheld OCT peripherals before emerging AI-native developers secure PMDA fast-track approvals.
For New Entrants and Emerging Players: Establish a beachhead in Germany's ambulatory care networks by exploiting Digitale-Versorgung-Gesetz reimbursement gaps that incumbent bundled platforms have not yet saturated. Target direct-to-employer screening contracts with self-insured manufacturers in Japan's Kanto industrial corridor, where workforce diabetic complication prevention budgets remain untapped by traditional clinical channels. Lead with per-image pricing transparency rather than capital lease complexity to dislodge entrenched vendor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy optical equipment manufacturers seeking to divest mobile module divisions that dilute R&D focus on surgical robotics. Long-term viability over the projection horizon favors algorithm developers with simultaneous FDA-PMDA validation datasets and cloud-native architecture. Watch for inflection when Japan's prefecture-based screening programs shift from pilot procurement to multi-year framework contracts, signaling durable revenue visibility for validated platform vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Regulatory Filing | Simultaneous FDA 510(k) and PMDA Shonin submissions compress market entry timelines by 40%. |
| Cloud Platform Integration | Native HL7 FHIR connectivity with Epic and Cerner EHR systems locks in hospital procurement preference. |
| AI Algorithm Licensing | White-label diagnostic grading tools enable camera hardware vendors to compete on interpretation accuracy. |
| Regional Reading Center Acquisition | Aggregating specialist interpretation capacity addresses certified retinalist shortages in rural United States counties. |
| Reimbursement Strategy Investment | CMS teleophthalmology code advocacy expands Medicare-covered preventive screening access. |
Research Methodology
Initial hypotheses were tested against primary input from retinal specialists, hospital purchasing committee chairs, biomedical engineers at camera manufacturers, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, PMDA Shonin approval databases, CMS Medicare reimbursement code updates, and hospital procurement contract disclosures. Bottom-up equipment shipment estimates from Japanese and German optical component suppliers were triangulated against top-down health system IT spending surveys across the analysis window.
Demand-supply balance modeling anchored volume projections on diabetic retinopathy screening mandate penetration rates, handheld OCT resolution improvement curves, and cloud interpretation platform adoption thresholds. Segmentation dimensions included service type, technology modality, end-user credential level, and application intensity. CAGRs were derived from logistic diffusion curves fitted to early-adopter hospital network deployment patterns and late-majority primary care clinic uptake trajectories. Industry-specific inputs incorporated PMDA approval timeline compression effects and EU MDR notified body backlog duration assumptions.
Sensitivities concentrate around reimbursement code expansion velocity, AI diagnostic accuracy validation thresholds, and export control tightening on imaging sensor technologies. Forecasts embed assumptions regarding sustained Medicare teleophthalmology coverage and stable PMDA fast-track pathway availability. Material shifts in FDA software-as-medical-device enforcement posture or major EU MDR notified body capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Video Conferencing Hardware Market
Others
Fenoxanil Market
Others
Hookah Tobacco Market
Others
Nanomedicine for Drug Delivery Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Military Image Intensifier Market
Others
Digital Tattoos Market
Others
Air Separation Module Kit Market
Others
Military Sensors Market
Others
Asia-Pacific Military 4D Printing Market
Others
Legal Services Market
Others
Running Apparel Market
Others
Safety Critical Software Testing Market
Others
Middle East Location-Based Services Market
Others
Global Active Speaker Market
Others
Thiamethoxam Market