
 US 3D Printing Construction Market | 2026-2036
US 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
US 3D Printing Construction Market Insights
Affordable housing developers is rotating toward 3D-printed construction methods as traditional builders face persistent labor shortages and material cost volatility. ICON anchors its position through large-scale robotic deployment across the southwestern United States, while Mighty Buildings specializes in prefabricated panel systems for accessory dwelling units. COBOD International extends its reach through equipment licensing to domestic contractors seeking entry into automated construction.
US 3D printing construction refers to the additive manufacturing of building elements through layer-by-layer deposition of concrete, polymer, or composite materials using gantry-mounted or robotic arm extrusion systems, typically achieving compression strengths of 20-40 MPa for structural walls. The primary purpose centers on reducing construction timelines, material waste, and labor dependency for residential and commercial structures. Concrete dominates material type segments due to its thermal mass properties and compatibility with existing building codes, while fused deposition modeling leads technology adoption for its cost efficiency in field-deployable systems. Infrastructure applications represent the fastest-growing end-use category as state departments of transportation evaluate printed bridge components and culverts.
The US Department of Housing and Urban Development, the International Code Council, and OSHA collectively shape market access through evolving standards for structural performance, fire resistance, and worker safety in automated construction environments. These frameworks currently create a patchwork of state-level adoption timelines that fragment go-to-market strategies for equipment manufacturers and contractors. Stakeholders must monitor municipal zoning amendments and state-level pilot program outcomes to anticipate where code harmonization will unlock scalable project pipelines.
Market Dynamics
Concrete-based gantry systems are compressing residential construction timelines from months to days across the southwestern United States, fundamentally altering the labor-to-output ratio that has governed homebuilding economics for decades. This technological inflection is forcing permitting authorities, material suppliers, and trade unions to recalibrate their operating assumptions simultaneously.
Growth Catalysts
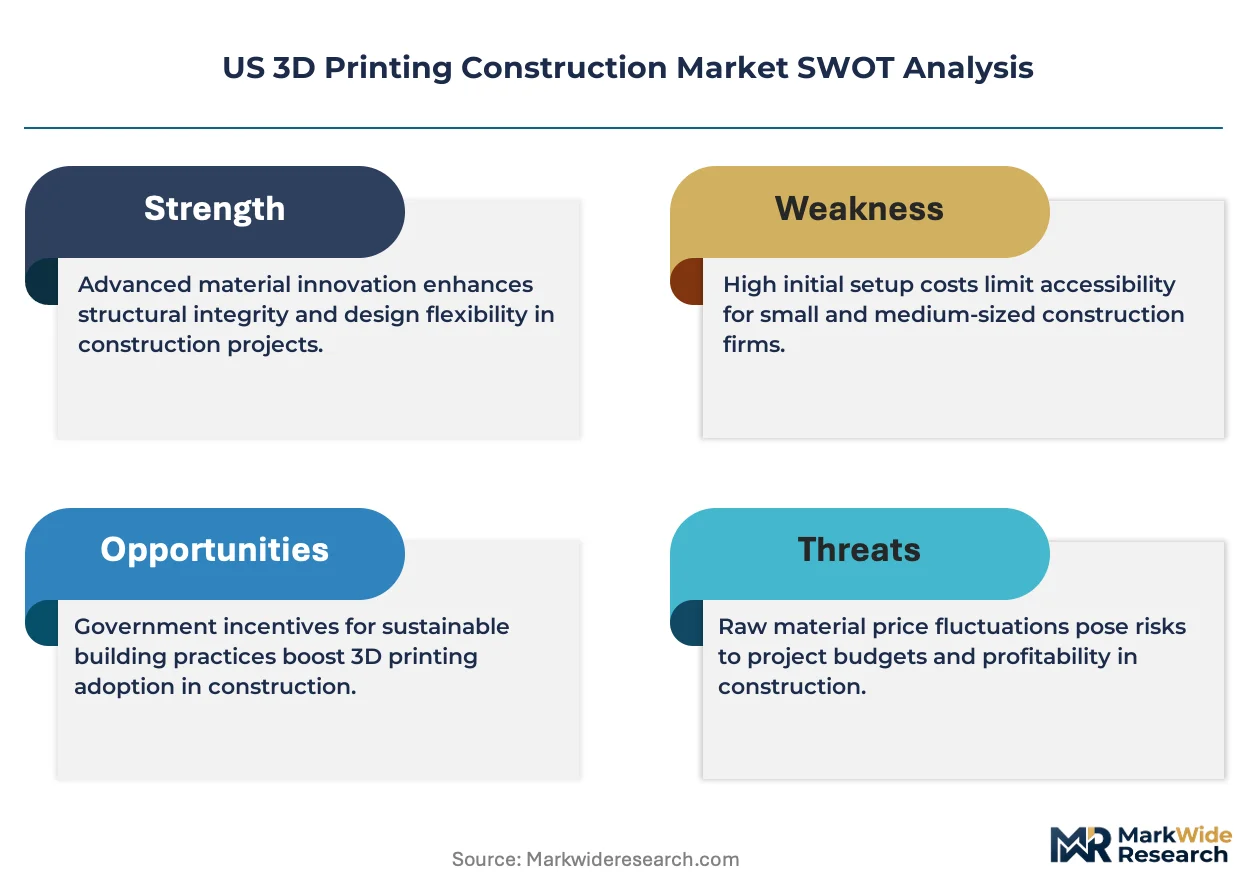
- HUD Building Code Evolution:The Department of Housing and Urban Development's additive construction standards are reducing municipal permitting friction in Texas and Arizona pilot zones, accelerating project approvals for multi-unit developments.
- Labor Scarcity in Sun Belt Construction:Persistent shortages of skilled framers and masons in Florida and Arizona are pushing developers toward robotic extrusion systems that require minimal on-site craft labor.
- Portland Limestone Cement Formulations:Lower-carbon concrete mixes compatible with 3D printing equipment are satisfying California and New York emissions thresholds while maintaining 25-35 MPa structural performance.
Market Restraints
- Specialized Binder Supply Concentration:Domestic production of geopolymer and magnesium phosphate binders concentrates among three mid-Atlantic chemical processors, creating input vulnerability for southwestern print operations.
- OSHA Silica Exposure Standards:Current permissible exposure limits for respirable crystalline silica during concrete extrusion require costly ventilation retrofits that erode field deployment economics.
- Conventional Panelized Construction:Factory-built wall and roof assemblies from established modular builders offer comparable timeline compression without the weather dependency of on-site printing.
Strategic Opportunities
- Rural Texas and New Mexico Counties:Unincorporated jurisdictions with minimal zoning enforcement represent untapped demand for rapid-deploy housing solutions where conventional contractors decline to bid.
- Infrastructure Resilience Mandates:Federal Highway Administration bridge replacement programs are creating entry points for printed culvert and abutment components in flood-prone Gulf Coast corridors.
- Digital Twin Integration:Convergence of BIM workflows with real-time print monitoring software is enabling precision quality control that reduces rework costs below conventional construction variance.
Industry Challenges
- Robotics Technician Pipeline:Field calibration of gantry and robotic arm systems requires mechatronics competencies scarce in existing construction craft training programs, forcing contractors to recruit from industrial automation sectors.
- ICC-ES Evaluation Service Timelines:Structural product reports for novel concrete mixes average 18-24 months, compressing competitive windows for material innovators against incumbent formulations.
- Utility Integration Protocols:Mechanical, electrical, and plumbing rough-in for printed wall cavities lacks standardized chase dimensions, forcing case-by-case coordination with local inspection authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US 3D Printing Construction Market |
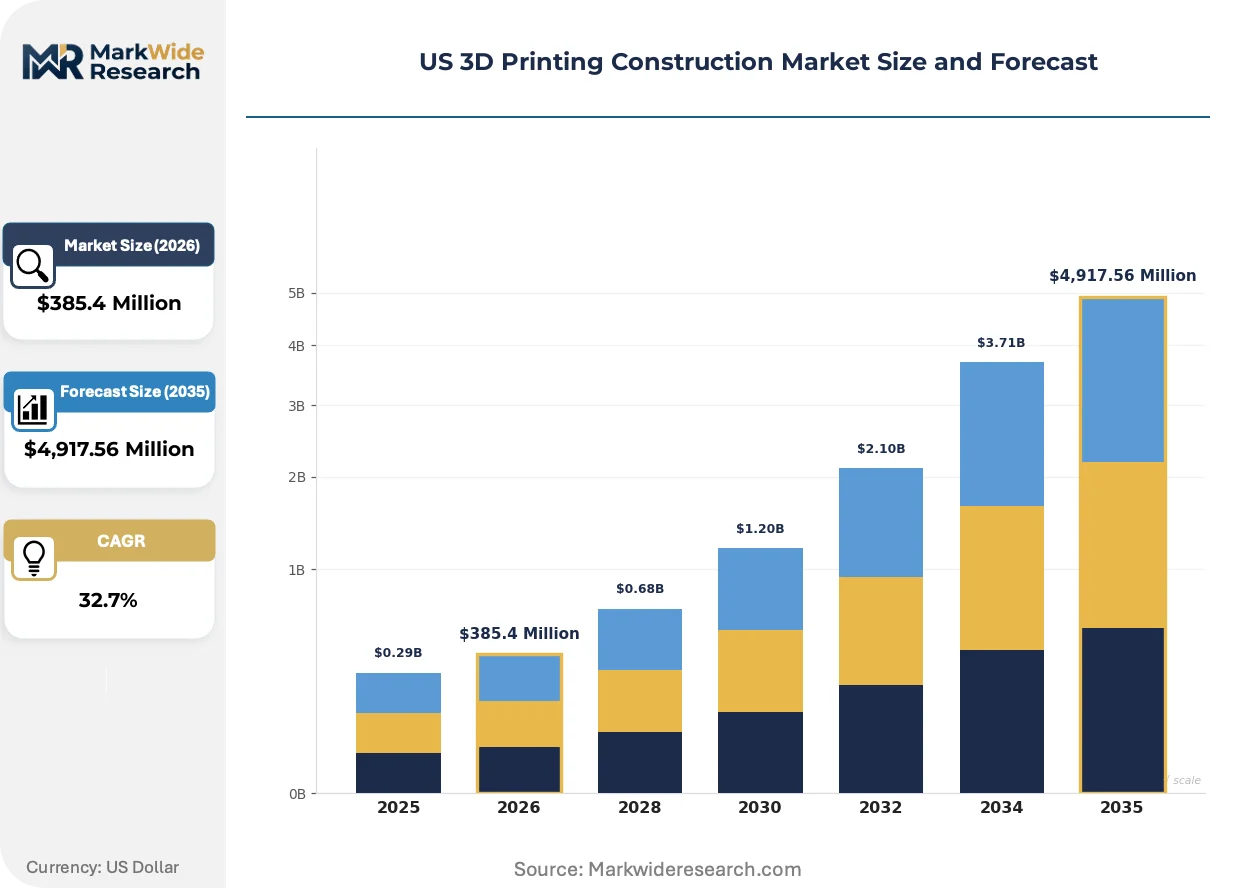
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $4,917.56 Million |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Powder Bonding, Binder Jetting, Stereolithography Material Type: Concrete, Plastic, Metal, Composite End User: Residential, Commercial, Infrastructure, Industrial Application: Building Construction, Road Construction, Structural Components, Prototyping |
| Companies Covered | SQ4D, Constructions-3D, ICON, CyBe Construction, Vertico, Apis Cor, COBOD International, Markforged, Mighty Buildings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US 3D Printing Construction Market Trends and Innovations
Multi-material extrusion capabilities are expanding the architectural vocabulary of automated construction beyond monolithic concrete walls toward integrated insulation, finish surfaces, and embedded structural reinforcement. These advances are compressing the traditional sequence of rough-in, insulation, and finishing into simultaneous deposition operations.
Continuous fiber-reinforced concrete extrusion is displacing conventional rebar placement in shear wall applications across Texas residential projects. Mid-rise developers in Austin and Dallas are adopting carbon fiber and basalt roving integration to achieve seismic performance ratings without the labor hours of tied reinforcement cages. This displacement is compressing structural subcontractor scopes and reallocating budget share toward equipment operators and digital fabrication specialists.
OSHA's pending crystalline silica rulemaking for additive construction environments is forcing equipment manufacturers to engineer enclosed print chambers with negative-pressure dust collection. The industrial consequence is a bifurcation between open-gantry systems suited for rural, low-density deployment and sealed-chamber configurations targeting urban infill sites with stricter air quality enforcement. California and Washington state contractors are pre-emptively specifying enclosed systems to avoid retrofit obligations under anticipated 2025-2026 enforcement timelines.
Design-build procurement consolidation among Texas affordable housing authorities is compressing traditional architect-bid-build cycles into single-source contractor engagements where 3D printing specialists capture both design optimization and construction execution. This consolidation is displacing conventional general contractor bidding pools in HUD-funded projects. The shift is most visible in Houston and San Antonio metropolitan statistical areas, where housing authority technical staff have built direct relationships with automated construction vendors.
US 3D Printing Construction Market Segmentation
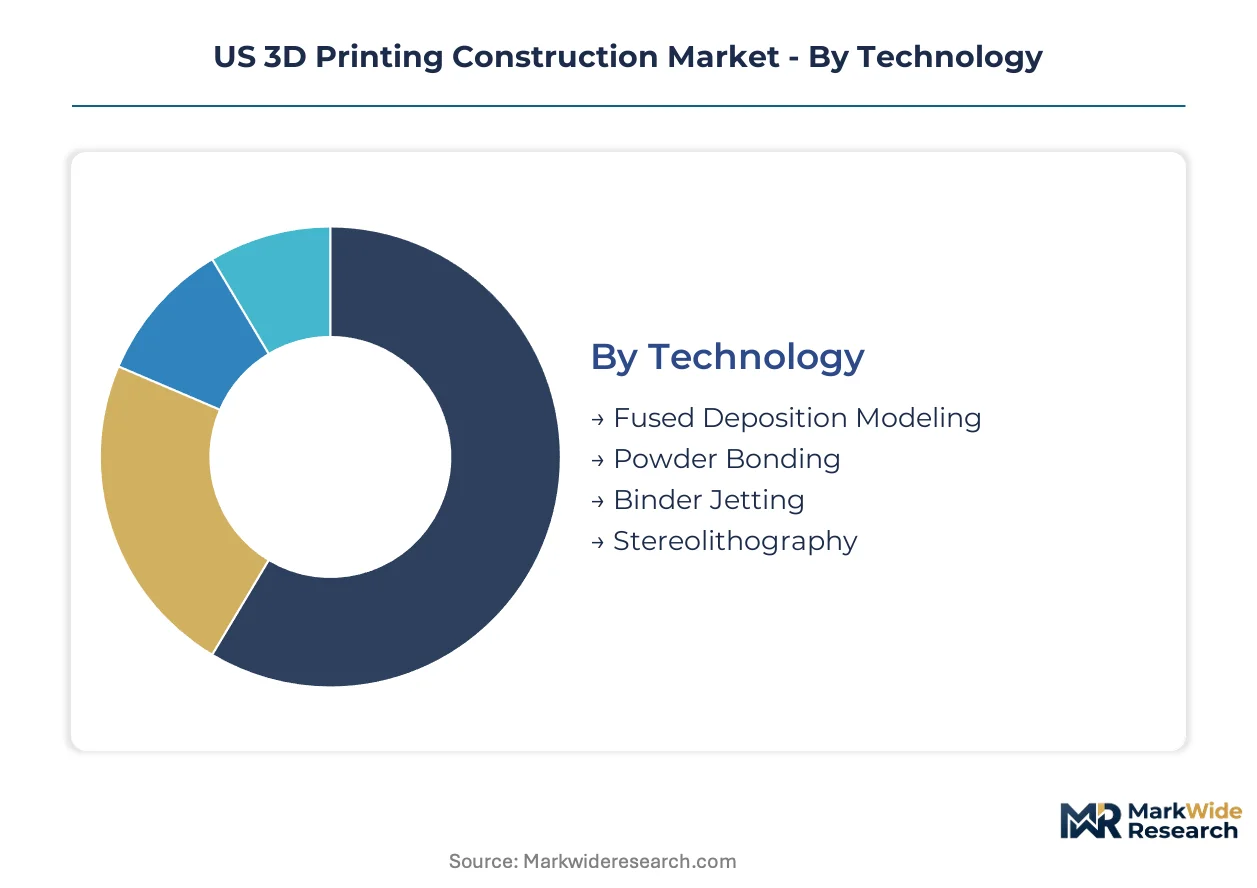
Segmentation in US 3D printing construction reveals how regulatory frameworks, material science advances, and application economics fragment addressable demand across distinct technology-material pairings. Each category carries unique permitting pathways and labor substitution profiles that shape contractor procurement decisions.
Technology:
OSHA silica exposure standards and ICC-ES evaluation timelines create divergent compliance burdens across extrusion methodologies, favoring field-proven systems with existing structural product reports.
- Fused Deposition Modeling:Layer-by-layer thermoplastic or concrete extrusion through heated nozzles mounted on gantry or robotic arm platforms. Texas and Arizona affordable housing developers deploy FDM systems most heavily where HUD pilot programs have streamlined municipal approvals for multi-unit residential structures.
- Powder Bonding:Selective deposition of binding agents onto cementitious or polymer powder beds to form structural elements. Infrastructure applications in Florida and Gulf Coast corridors adopt powder bonding for printed culvert components where FHWA resilience mandates accelerate project timelines.
- Binder Jetting:Liquid binder deposition onto powder layers for sand-based molds and metal-infused construction elements.
- Stereolithography:Photopolymer resin curing through ultraviolet laser projection for architectural prototyping and detailed facade mockups.
Established volume favors Fused Deposition Modeling; emerging adoption favors Powder Bonding.
Material Type:
Cost tiers stratify around carbon intensity thresholds and supply chain proximity to regional concrete batch plants or polymer processors.
- Concrete:Portland limestone cement and geopolymer formulations extruded at 20-40 MPa compression strength for structural walls. Sun Belt residential builders concentrate demand here where thermal mass properties satisfy IECC energy codes and existing trade labor pools understand concrete finishing.
- Plastic:Recycled PET and fiber-reinforced polymer deposition for non-load-bearing partitions and facade elements. California accessory dwelling unit specialists specify plastic composites where weight reduction simplifies foundation requirements in seismic zones.
- Metal:Wire-arc and powder-bed fusion of structural steel connections and reinforcement cages.
- Composite:Continuous fiber-reinforced concrete with carbon or basalt roving integration for seismic shear walls.
Concrete dominates current procurement volumes; composites are climbing the fastest as mid-rise developers in Austin and Dallas pursue seismic performance ratings without conventional rebar labor.
End User:
Customer type determines project scale, financing mechanisms, and tolerance for construction timeline uncertainty.
- Residential:Single-family and multi-unit housing developments seeking labor cost reduction and speed-to-occupancy. Rural Texas and New Mexico counties represent untapped demand where conventional contractors decline to bid on remote sites.
- Infrastructure:State DOT bridge replacement programs and federal flood resilience projects. Gulf Coast corridors are expanding most quickly as FHWA mandates printed culvert and abutment components for hurricane-prone watersheds.
- Commercial:Retail, office, and hospitality structures requiring architectural differentiation.
- Industrial:Warehousing and manufacturing facilities with standardized bay dimensions.
Residential commands current equipment deployment; infrastructure offers the steepest expansion trajectory through federal procurement channels.
Application:
Margin profiles diverge between field-printed vertical structures and prefabricated components factory-produced for assembly.
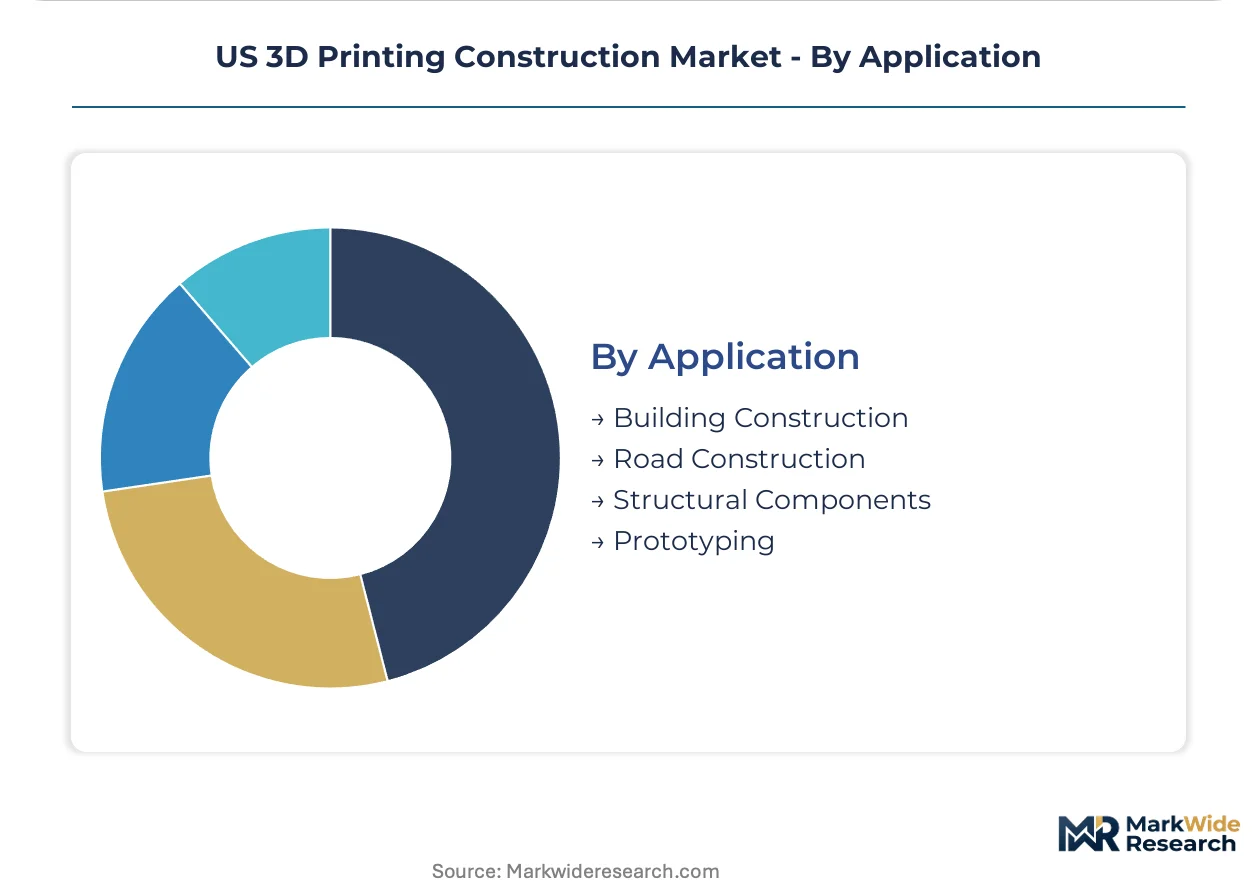
- Building Construction:Complete wall systems, foundations, and roof elements printed on-site or as prefabricated panels. Mighty Buildings and similar specialists target accessory dwelling units in California where factory production escapes weather dependency.
- Structural Components:Beams, columns, and connection nodes produced off-site for conventional assembly. Texas design-build contractors are gaining share fastest here by capturing both BIM optimization and fabrication execution in single-source engagements.
- Road Construction:Printed barriers, sound walls, and drainage structures for highway corridors.
- Prototyping:Architectural models and full-scale mockups for design validation.
Building Construction absorbs the majority of current capital expenditure; Structural Components are gaining share fastest as procurement consolidates around design-build delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 corridor through Texas anchors southwestern deployment capacity for gantry-mounted concrete extrusion systems. HUD pilot zones in Arizona and Florida accelerate permitting velocity where labor scarcity strains conventional building timelines most acutely.
Texas
Rural county housing authorities drive demand for rapid-deploy residential structures where conventional contractors decline remote bids. Texas Department of Housing and Community Affairs streamlines approvals for additive construction in unincorporated jurisdictions. Austin and Dallas metropolitan clusters concentrate mid-rise seismic wall projects using continuous fiber-reinforced concrete extrusion.
Arizona
Phoenix-area affordable housing developers compress multi-unit timelines through robotic extrusion systems requiring minimal on-site craft labor. Arizona Corporation Commission evaluates utility integration standards for printed wall cavities. Maricopa County unincorporated zones represent untapped demand for single-source design-build procurement.
Florida
Gulf Coast flood resilience mandates accelerate state DOT adoption of printed culvert and bridge abutment components. Florida Building Commission harmonizes municipal codes for additive construction in hurricane-prone watersheds. Tampa and Orlando corridors concentrate infrastructure pilot programs evaluating powder bonding for drainage structures.
California
Accessory dwelling unit specialists specify factory-produced prefabricated panels to escape weather dependency and seismic weight restrictions. California Energy Commission emissions thresholds favor lower-carbon concrete formulations compatible with extrusion equipment. Los Angeles and Bay Area metropolitan zones concentrate Mighty Buildings deployment for backyard housing units.
New Mexico
Unincorporated rural jurisdictions with minimal zoning enforcement attract rapid-deploy housing solutions for underserved populations. New Mexico Mortgage Finance Authority explores HUD-aligned pilot programs for tribal and frontier housing. Albuquerque and Santa Fe corridors concentrate early-stage equipment trials for off-grid residential applications.
US 3D Printing Construction Market Competitive Landscape
Concentration sits with integrated equipment-and-service providers rather than pure hardware manufacturers. The vendor base stratifies across three tiers: gantry system operators with field-proven structural product reports, prefabricated panel specialists with factory production models, and international equipment licensors seeking domestic contractor relationships. Competitive moves center on design-build procurement consolidation and regional equipment deployment partnerships with housing authorities.
Among US-based integrated operators, SQ4D and ICON exemplify the equipment-and-execution archetype that captures both technology deployment and construction revenue streams. COBOD International occupies a licensing-focused position, supplying gantry systems to domestic contractors seeking automated construction entry without captive R&D investment. Mighty Buildings represents the factory-production archetype, decoupling manufacturing from field weather exposure through panelized delivery models targeting California accessory dwelling unit demand.
| Leading Market Players |
|---|
| SQ4D |
| Constructions-3D |
| ICON |
| CyBe Construction |
| Vertico |
| Apis Cor |
| COBOD International |
| Markforged |
| Mighty Buildings |
| Others |
Pricing and Supply Chain Analysis
ICC-ES evaluation timelines gate both equipment qualification and price differentiation simultaneously, stretching structural product report acquisition costs across 18-24 month windows that tier pricing power between incumbents with existing certifications and entrants awaiting approval.
Pricing Analysis
Volume-discount tiering separates turnkey project execution from equipment-only sales, with design-build contractors capturing premium positioning through bundled BIM optimization and field deployment. Price differentiation hinges on ICC-ES certification status and regional equipment density, with certified gantry systems commanding substantial markups over uncertified alternatives. Cost compression in entry-level equipment tiers is intensifying because domestic licensing agreements with international manufacturers proliferate. Municipal housing authorities exhibit the highest price sensitivity due to HUD funding constraints, while private mid-rise developers in Austin and Dallas demonstrate lower sensitivity when seismic performance guarantees are bundled.
Supply Chain Analysis
Specialized geopolymer and magnesium phosphate binder production concentrates among three mid-Atlantic chemical processors, creating input vulnerability for southwestern print operations. Domestic equipment manufacturing draws from German and Danish precision engineering for gantry motion systems, Chinese servo motor assemblies, and regional concrete batch plant partnerships. Single-source vulnerability in proprietary nozzle and extrusion head components threatens field deployment continuity. Distribution runs through direct equipment sales to integrated operators and licensing arrangements with regional contractors seeking automated construction entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where software subscriptions for real-time print monitoring and predictive maintenance expand faster than hardware unit sales, creating recurring revenue layers that improve customer lifetime value metrics.
For Market Incumbents: Consolidate design-build procurement relationships with Texas and Arizona housing authorities before modular panel competitors replicate timeline compression without weather dependency. Deepen backward integration into proprietary concrete formulation development to escape mid-Atlantic chemical processor concentration. Capture ICC-ES certification moats for seismic-rated continuous fiber-reinforced systems before evaluation timelines compress competitive windows.
For New Entrants and Emerging Players: Anchor in rural Texas and New Mexico counties where minimal zoning enforcement and conventional contractor abstention create immediate deployment opportunities. Target factory-produced prefabricated panel production for California accessory dwelling unit demand where seismic weight restrictions and weather-independent manufacturing differentiate from field-printed alternatives. Pursue equipment licensing partnerships with established international manufacturers rather than captive R&D investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-as-a-service business models that bundle hardware deployment with software subscriptions and maintenance contracts. Five-to-ten year viability favors integrated operators capturing both technology deployment and construction execution revenue streams. Target acquisition archetypes include regional design-build contractors with established housing authority relationships and proprietary BIM-to-print workflow integration. Monitor ICC-ES evaluation timeline compression as the critical inflection signal for competitive entry barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Procurement Consolidation | Single-source contractor engagements displace conventional bidding pools in HUD-funded projects across Houston and San Antonio. |
| Continuous Fiber-Reinforced Concrete Development | Carbon and basalt roving integration achieves seismic ratings without conventional rebar labor in Austin mid-rise applications. |
| Enclosed Print Chamber Engineering | Negative-pressure dust collection systems preempt OSHA silica rulemaking enforcement in California and Washington urban infill sites. |
| Real-Time Print Monitoring Software | BIM convergence enables precision quality control that reduces rework costs below conventional construction variance thresholds. |
| Rural County Equipment Deployment | Rapid-deploy housing solutions address underserved populations in unincorporated Texas and New Mexico jurisdictions. |
Research Methodology
Initial hypotheses were tested against primary input from equipment operators, housing authority technical staff, concrete formulation chemists, and robotics technicians and refined through secondary validation against ICC-ES evaluation databases, HUD pilot program documentation, OSHA regulatory filings, and state DOT infrastructure procurement records. Bottom-up project pipeline aggregation triangulated against top-down equipment deployment capacity modeling.
Variance-decomposition across technology-material pairings, end-user categories, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs derived from equipment shipment trajectories, permitting velocity in HUD pilot zones, and labor substitution economics across Sun Belt construction markets. Modeled inputs included gantry system deployment rates, ICC-ES certification timelines, and state-level code harmonization progress.
Material uncertainties — OSHA silica rulemaking enforcement timelines, ICC-ES evaluation backlog duration, and geopolymer binder supply concentration — sit outside the modeled envelope. Forecasts reflect assumptions regarding municipal zoning amendment velocity and federal infrastructure resilience funding continuity. Practitioners should keep alternative scenarios live as HUD building code evolution and state DOT procurement standardization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military Lighting Market
Others
Video Paas Market
Others
Electric Pallet Jack Truck Market
Others
Depth Gauge Market
Others
Evidence Management Market
Others
US Quantum Computing Market
Others
Global Healthcare/Medical Simulation Market
Others
Global on-Demand Laundry Service Market
Others
Vacuum Evaporators Market
Others
Underwater Lighting Market
Others
Global Telemetry Market
Others
Czech Republic Market
Others
Digital Transformation of Maritime Freight Market
Others
Animal Feed Alternative Protein Market
Others
Computer on Module Market
Others
Air Separation Module Kit Market