
 Convenience Stores Market | 2026-2036
Convenience Stores Market Size, Share, and Industry Trends Forecast 2026-2036
Convenience Stores Market Intelligence
The skill demarcation between front-of-house customer service and back-of-house inventory management is collapsing due to automation. 7-Eleven leverages its extensive network to pilot new retail technologies and self-checkout systems. Alimentation Couche-Tard, which operates the Circle K brand, focuses on integrating fuel services with its quick-service restaurant offerings. Wawa differentiates through its strong brand loyalty built on a popular range of made-to-order food items.
A convenience store is a small-format retail business stocking a limited range of everyday items. These outlets are characterized by extended operating hours and locations optimized for high foot traffic, offering quick transaction times for consumers. The beverages and snacks product categories continue to generate the highest sales volume for the industry. In terms of store format, the traditional model remains dominant, but drive-thru and non-traditional locations in airports or universities represent the fastest-growing segments.
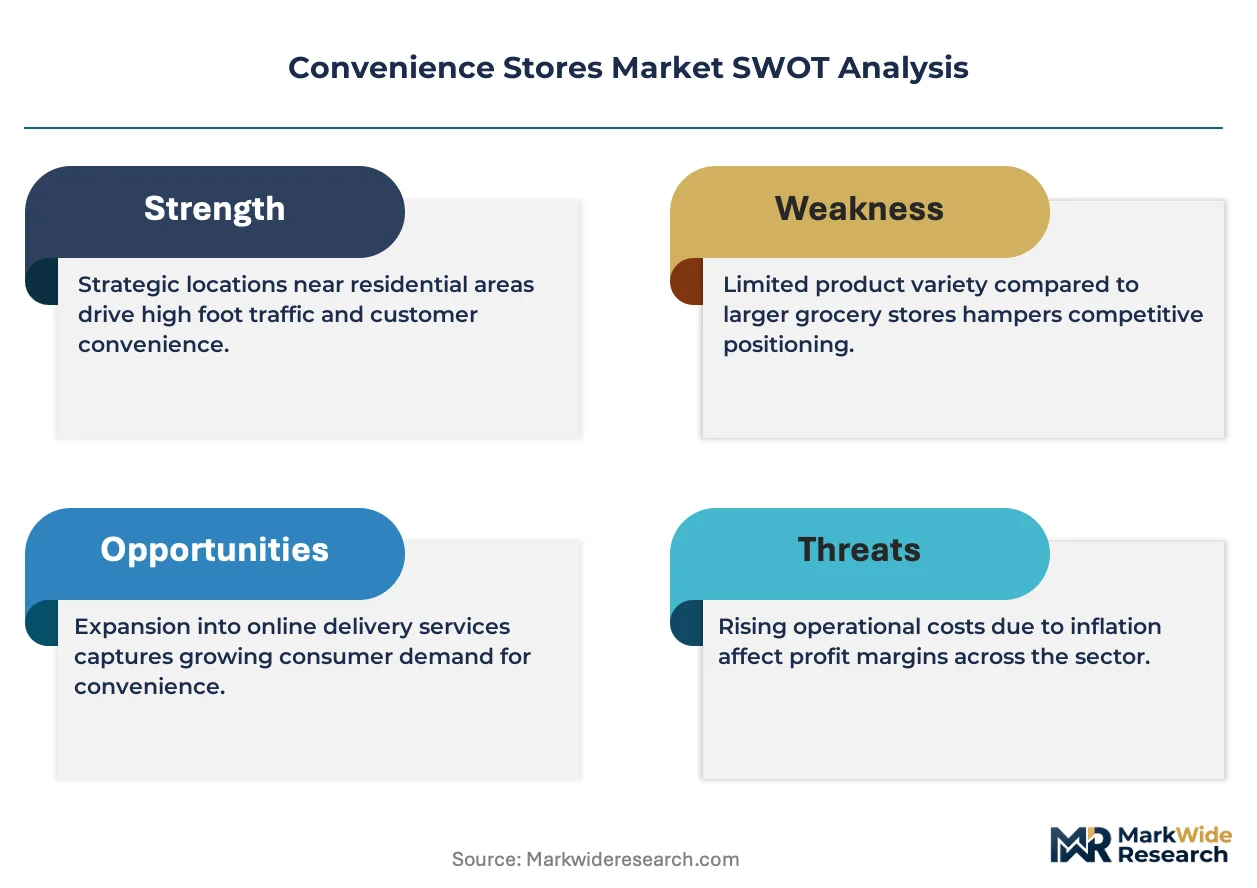
Regulations governing the sale of age-restricted products like tobacco and alcohol, enforced by bodies such as the US FDA and local authorities in Japan, are critical for compliance. Food safety standards from organizations like India's FSSAI and the EU's EFSA dictate handling procedures for prepared foods, impacting operational costs. Stakeholders must decide whether to invest in proprietary digital platforms or partner with third-party delivery services to capture online sales channels.
Market Dynamics
The convergence of quick-service food and traditional retail is the central force shaping the convenience store sector. This shift responds to demand from time-constrained urban consumers for immediate consumption, while navigating stricter food handling regulations from bodies like the US FDA and EFSA.
Growth Catalysts
- Urbanization and Commuter Culture:Rapid urbanization in markets like India and Brazil creates dense commuter corridors, increasing demand for quick-purchase meals and beverages near transit hubs and business districts.
- Retail Automation:The adoption of self-checkout kiosks and mobile payment systems reduces transaction times and minimizes labor costs, improving operational efficiency and customer throughput during peak hours.
- Fresh and Prepared Foods:An expanding offering of made-to-order sandwiches, salads, and hot meals caters to consumer preferences for healthier, convenient food options over traditional packaged snacks.
Market Restraints
- Rising Labor Costs:Increasing minimum wage legislation in parts of the United States and Europe puts significant pressure on the labor-intensive operating model common to most convenience stores.
- Intense QSR Competition:Quick-service restaurants and coffee chains directly compete for the same food-on-the-go customer, often with more extensive menus and established brand recognition in prepared foods.
- Age-Restricted Product Regulations:Strict regulations on tobacco and alcohol sales, enforced by bodies like Japan's local authorities and the US FDA, create significant compliance burdens and operational risks.
Strategic Opportunities
- Last-Mile Delivery Integration:Partnering with third-party delivery platforms or developing proprietary apps allows stores to capture the market for at-home convenience and impulse purchases beyond their physical footprint.
- Financial Services Hubs:Offering services like bill payments, money transfers, and ATM access in underbanked communities can create new revenue streams and consistently drive foot traffic.
- Non-Traditional Store Formats:Drive-thru-only models and micro-stores in locations like airports, hospitals, and university campuses tap into captive consumer bases with highly specific, time-sensitive needs.
Industry Challenges
- Complex Food Supply Chains:Managing fresh food inventory with short shelf lives requires sophisticated logistics and cold chain integrity to comply with FSSAI and EFSA standards, increasing operational complexity.
- Blurring Staff Skillsets:The need for employees to handle both customer service and food preparation tasks requires extensive cross-training and creates challenges in talent recruitment and retention.
- Shrinkage and Security:High foot traffic and extended operating hours make stores vulnerable to theft, necessitating investment in surveillance technology and security personnel, which impacts profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Convenience Stores Market |
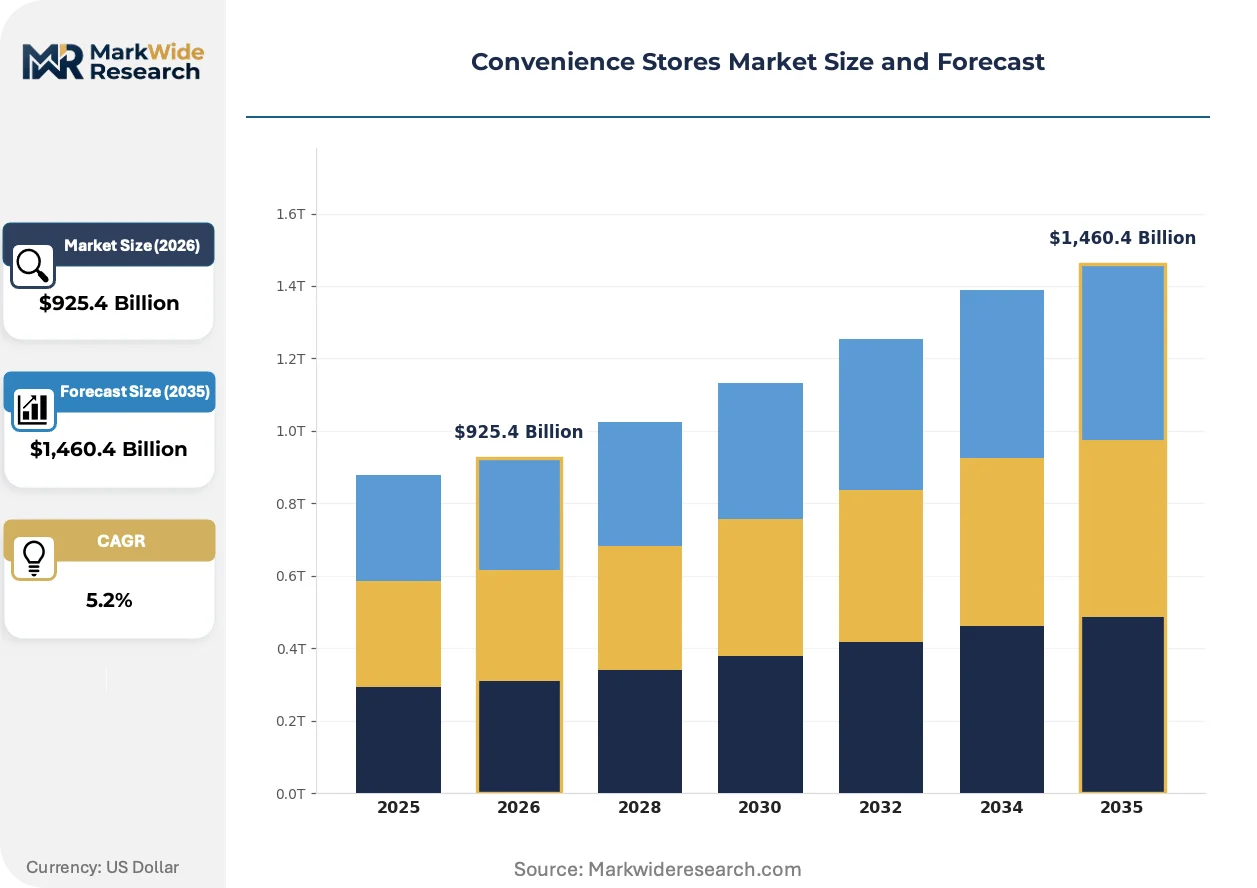
| Market Size in 2026 | $925.4 Billion |
| Market Size in 2035 | $1,460.4 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverages, Snacks, Groceries, Personal Care Store Format: Traditional, Non-Traditional, Vending Machines, Drive-Thru Customer Type: Local Residents, Commuters, Travelers, Businesses Sales Channel: Online, In-Store, Mobile Apps, Delivery Services |
| Companies Covered | FamilyMart, OXXO, 7-Eleven, Wawa, Casey's General Stores, Alimentation Couche-Tard, Lawson, QuikTrip, Circle K, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Convenience Stores Market Strategic Shifts & Innovations
A fundamental shift towards data-driven personalization and frictionless commerce is redefining the convenience retail experience. Innovations focus on leveraging technology to anticipate customer needs and streamline operations from inventory management to final purchase, creating a more responsive business model.
AI-powered inventory management systems use predictive analytics to automate stock ordering and reduce food waste. Major chains and independent operators are adopting these platforms to optimize shelf space for high-turnover items based on sales data and local events. This automated approach is supplanting manual stock-taking and legacy spreadsheet-based forecasting, directly improving product availability and margin.
The European Union's food safety modernization, guided by EFSA principles, imposes stricter traceability and allergen labeling requirements. This regulation compels operators to invest in digital systems for tracking ingredients from the supplier to the point-of-sale. The prepared foods segment is most affected, with operators reformulating products and redesigning in-store processes to ensure compliance.
Consumer purchasing habits are moving towards subscription models for recurring items like coffee and car washes. This model bypasses transactional, single-item purchases, building loyalty through digital apps that offer personalized discounts and rewards. This behavioral shift is most prominent in urban centers in North America and Europe, where chains compete on the value of their loyalty programs.
Convenience Stores Market Segmentation
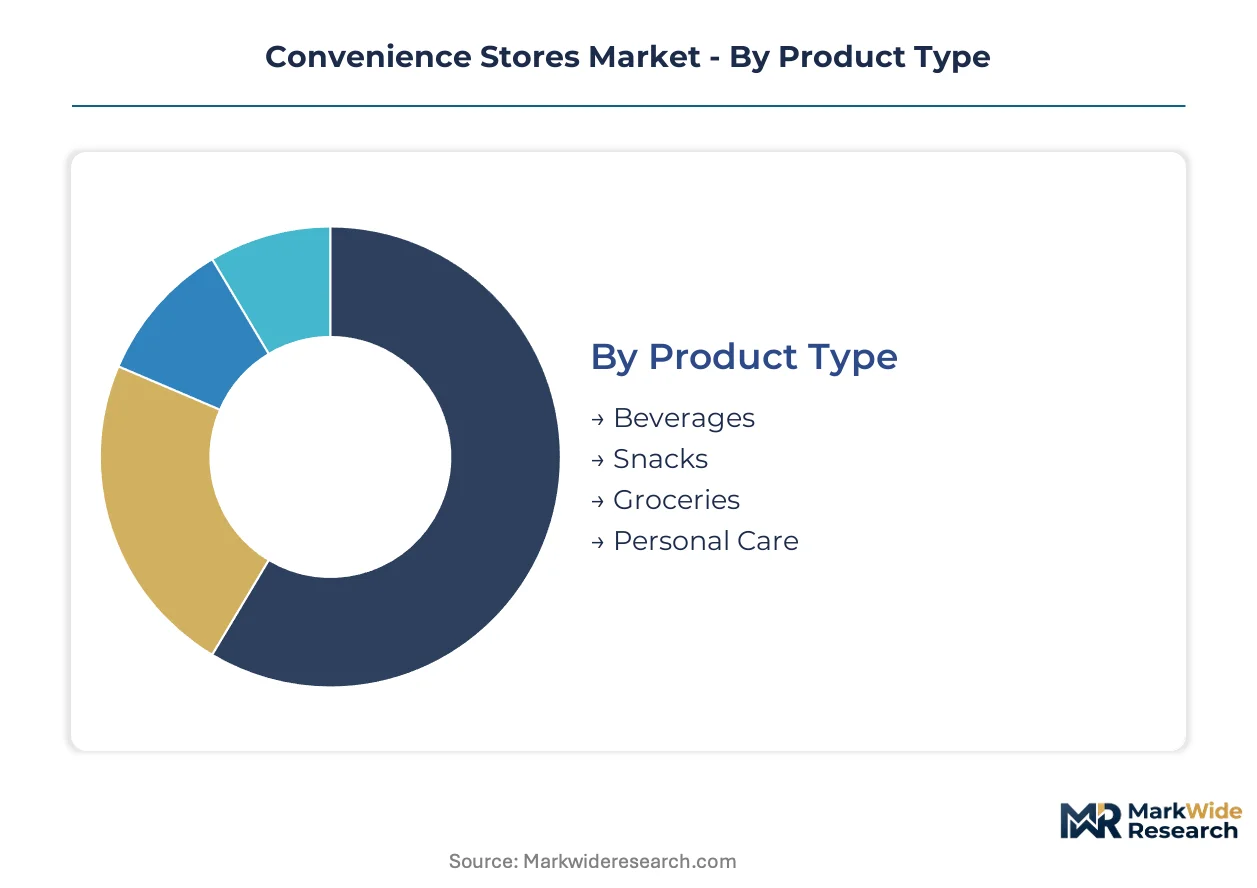
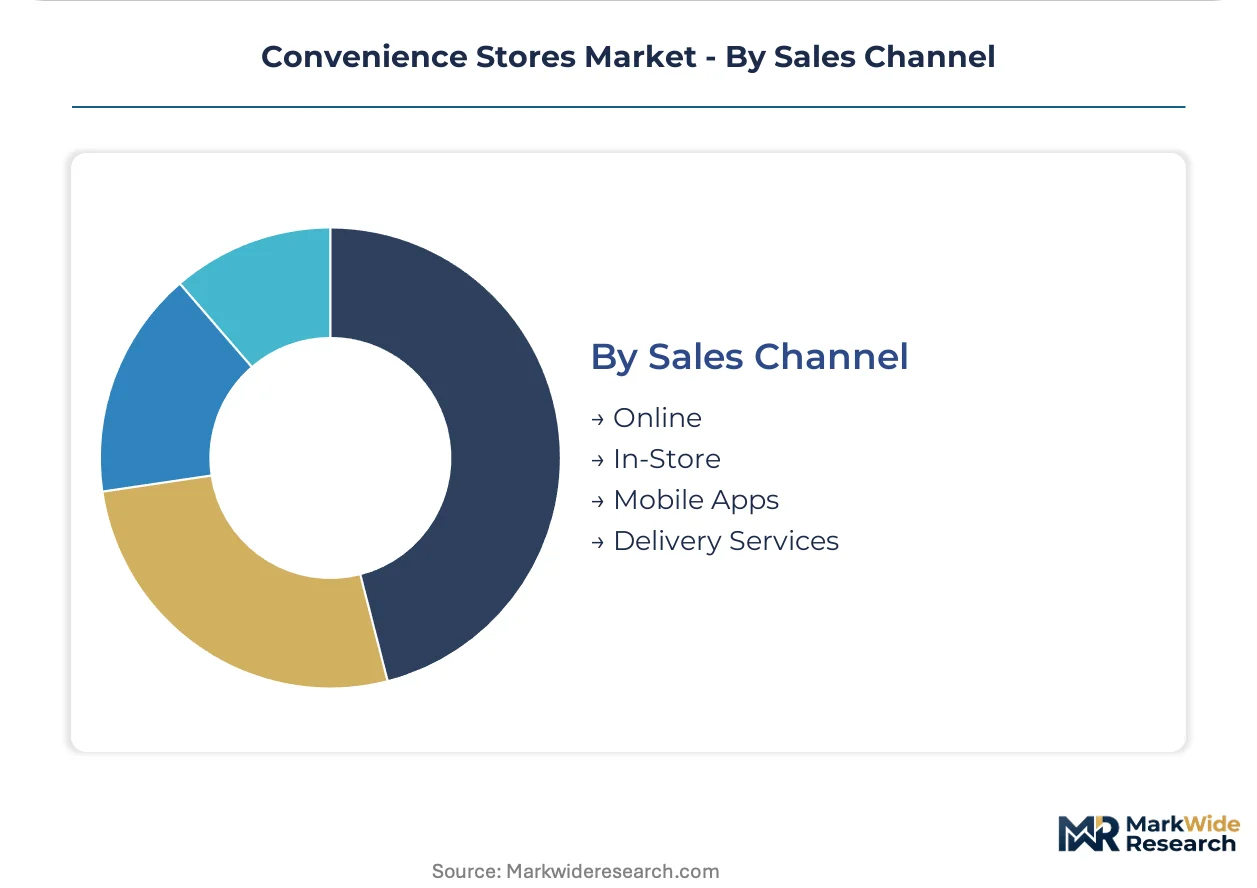
The convenience stores market segments across diverse product offerings, store formats, customer demographics, and sales channels. Understanding these divisions helps stakeholders identify specific growth pockets and tailor operational strategies for maximum impact. This analysis provides a structured view of the market's internal composition.
Product Type:
Margin pools within the product type category are heavily concentrated in high-turnover, impulse-driven purchases.
- Beverages:This segment includes a wide array of non-alcoholic and alcoholic drinks, from bottled water and soft drinks to coffee and energy beverages. Demand concentrates in urban commuter hubs across the US and Japan, driven by immediate consumption needs.
- Snacks:Encompassing packaged chips, confectionery, nuts, and other grab-and-go food items, the snacks category caters to quick hunger solutions. Consumer preference for healthier options in European markets and India influences product innovation.
- Groceries:This category covers essential household items, dairy products, and packaged foods, often purchased for immediate use or emergency needs. Local residents in dense urban areas rely on convenience stores for these quick purchases.
- Personal Care:Products such as toiletries, over-the-counter medicines, and hygiene items fall into this segment. Travelers and commuters frequently purchase these items in airport and train station locations.
The dominant share belongs to Beverages, while Snacks is closing the gap fastest.
Store Format:
Cost tiers vary significantly across store formats, with traditional models often requiring higher initial investment compared to more agile alternatives.
- Traditional:These are standalone, brick-and-mortar stores with a standard layout, forming the foundational model of the convenience retail sector. They continue to dominate sales volumes in most global markets, including the US and India.
- Drive-Thru:This format allows customers to purchase items without leaving their vehicles, emphasizing speed and accessibility. This model experiences rapid expansion in suburban areas of North America, catering to busy motorists.
- Non-Traditional:Locations within airports, hospitals, university campuses, and other captive environments define this format, serving a specific, time-sensitive consumer base. These formats exhibit significant expansion in major transport hubs globally.
- Vending Machines:Automated dispensing units offer a limited selection of products, providing 24/7 access with minimal labor costs. These are prevalent in high-traffic public spaces like train stations in Japan and office buildings.
The Traditional format retains the largest volume, with Drive-Thru models expanding most quickly.
Customer Type:
Volume across customer types is significantly influenced by daily routines and immediate needs, shaping product assortment and service offerings.
- Commuters:Individuals traveling to and from work or school represent a significant customer base, seeking quick meal solutions, coffee, and snacks. Urban centers in countries like India and Brazil generate high demand from this segment.
- Local Residents:Shoppers living within close proximity to a convenience store often purchase daily essentials, impulse items, and last-minute groceries. This customer type forms the stable base for neighborhood stores globally.
- Travelers:This segment includes tourists and business travelers seeking food, beverages, and personal care items while in transit or away from home. Stores located near highways, airports, and train stations cater specifically to these needs.
- Businesses:Small businesses, offices, and construction sites purchase supplies, refreshments, and catering services from convenience stores. This segment often relies on bulk purchases or delivery options.
Commuters constitute the largest customer group, while Travelers are gaining share rapidly.
Sales Channel:
Maturity levels within sales channels range from established physical presence to rapidly evolving digital platforms.
- In-Store:The traditional method where customers physically enter the store to browse and purchase items, representing the dominant sales channel. This channel remains central to the convenience store experience across all geographies.
- Delivery Services:Partnerships with third-party platforms or proprietary apps enable home or office delivery of convenience store products. This channel has seen substantial growth in urban areas of the US and Europe, driven by consumer demand for at-home convenience.
- Online:E-commerce platforms, either store-specific or integrated with larger retail sites, allow customers to order products for pickup or delivery. This channel is expanding as digital literacy and infrastructure improve globally.
- Mobile Apps:Dedicated applications offer features like mobile ordering, loyalty programs, and personalized promotions, streamlining the purchasing process. Consumers in North America and Europe increasingly use these apps for recurring purchases.
The In-Store channel holds the largest portion, with Delivery Services exhibiting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's stringent food safety regulations significantly influence fresh food handling protocols across the convenience store sector. This regulatory environment shapes operational practices, particularly for prepared food offerings. Global expansion of convenience retail is driven by localized consumer needs and evolving regulatory frameworks.
United States
Commuter culture in the United States drives significant demand for quick-purchase beverages and snacks. The US FDA enforces strict age-restricted product regulations for tobacco and alcohol sales. Major metropolitan areas such as Los Angeles experience rapid expansion of drive-thru convenience formats.
India
Rapid urbanization in India creates dense commuter corridors, increasing demand for immediate consumption items. India's FSSAI dictates handling procedures for prepared foods, impacting operational costs. Retail modernization accelerates in cities like Bengaluru, concentrating convenience store development.
Japan
High foot traffic in Japan's urban centers generates consistent demand for convenience store offerings. Local authorities in Japan enforce strict regulations on age-restricted products like tobacco and alcohol. Vending machines are prevalent in high-traffic public spaces, including Tokyo's train stations.
Germany
European consumer preferences for healthier options influence product innovation in Germany's convenience stores. The EU's EFSA guides food safety modernization, imposing stricter traceability requirements for prepared foods. Urban centers such as Munich see demand for convenience stores offering fresh, ready-to-eat meals.
Brazil
Urbanization in Brazil fuels demand for quick-purchase meals and beverages near business districts. ANVISA, Brazil's health surveillance agency, sets food safety standards for prepared items sold in convenience stores. Major cities like São Paulo experience growth in convenience retail catering to time-constrained urban consumers.
Convenience Stores Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the convenience stores market structure. This market exhibits a tiered competitive landscape, with established global chains operating alongside regional and local operators. Strategic archetypes include large-format fuel retailers, urban micro-stores, and specialized food service providers focusing on prepared meals. Companies pursue both geographic expansion into new urban centers and technology integration to enhance their market presence and operational efficiency.
Within the large-format fuel retailer and global network archetype, companies like 7-Eleven and Alimentation Couche-Tard represent significant scale and operational reach. 7-Eleven leverages its extensive network to pilot new retail technologies and self-checkout systems, exemplifying digital innovation. Alimentation Couche-Tard, which operates the Circle K brand, occupies a position focused on integrating fuel services with quick-service restaurant offerings. Wawa anchors the specialized food service provider segment, differentiating through its strong brand loyalty built on a popular range of made-to-order food items. These players collectively demonstrate the diverse strategies employed to capture consumer demand across various convenience store formats.
| Leading Market Players |
|---|
| FamilyMart |
| OXXO |
| 7-Eleven |
| Wawa |
| Casey's General Stores |
| Alimentation Couche-Tard |
| Lawson |
| QuikTrip |
| Circle K |
| Others |
Cost & Logistics Intelligence
Operational scale economies in logistics and procurement shape both supply concentration and price floors across the convenience stores market. This market exhibits a direct relationship where larger networks can negotiate better terms, influencing item costs and consumer pricing. These efficiencies are particularly evident in high-volume product categories like beverages and snacks.
Pricing Analysis
Geographic price spreads reflect varying operational costs and consumer purchasing power across regions. The dominant pricing model is per-unit transactional, driven by immediate consumption needs. Price differentiation stems from brand premium for established chains like Wawa and geographic delivery costs, particularly for fresh food items in urban versus suburban locations. Pricing softness stems from intense QSR competition for prepared foods. Commuters and travelers exhibit lower price sensitivity for quick-purchase items, while local residents are more sensitive to grocery pricing.
Supply Chain Analysis
Inbound logistics costs, particularly for cold chain integrity in fresh food, pose significant challenges for convenience store supply chains. Supply concentration for packaged goods largely centers on global manufacturers, while fresh produce procurement is more localized, drawing from regional suppliers in countries like India and the United States. Raw material dependencies include agricultural products for fresh foods and various ingredients for packaged snacks and beverages. Regulatory restrictions from bodies like India's FSSAI and the EU's EFSA create a structural risk, necessitating complex handling protocols. Distribution runs through a multi-tiered model, combining central warehouse deliveries with direct store delivery for high-turnover items.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The convenience stores market is undergoing a platform-economics inflection, driven by the emergence of integrated digital ecosystems that connect customers, stores, and delivery services.
For Market Incumbents:Shield core market share by investing heavily in proprietary digital platforms and loyalty programs. This strategy counters competitive pressure from third-party delivery services and QSRs. Optimize fresh food supply chains to meet stricter food safety regulations from the US FDA and EFSA, leveraging automation for inventory management. Expand non-traditional store formats in high-foot-traffic locations like airports to capture specific consumer needs.
For New Entrants and Emerging Players:Lead with specialized offerings that target underpenetrated segments, such as healthy prepared meals or gourmet coffee concepts. The most penetrable segment lies in dense urban centers, particularly in rapidly urbanizing markets like India and Brazil. A strong go-to-market angle involves hyper-local partnerships with community-focused suppliers and integrating with existing third-party delivery platforms for immediate reach.
For Investors and Strategic Acquirers:Regional chains with strong local brand loyalty and efficient fresh food operations represent compelling acquisition targets. The long-term viability of the market is anchored in consistent demand from time-constrained urban consumers over a 5-10 year window. A signal to watch is the sustained growth in mobile app adoption and personalized subscription service engagement across North America and Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Investment | Enhances customer loyalty and captures online sales channels. |
| Fresh Food Supply Chain Optimization | Ensures compliance with FSSAI and EFSA standards. |
| Automation Technology Deployment | Reduces labor costs and improves transaction efficiency. |
| Non-Traditional Format Expansion | Taps into captive consumer bases in airports and universities. |
| Fuel and QSR Integration | Attracts motorists seeking combined services at Circle K. |
Research Approach
Initial hypotheses were tested against primary input from store managers, supply chain directors, food safety compliance officers, and retail technology vendors, then refined through iterative analysis. This approach combined in-depth primary interviews with validation from extensive secondary research. Bottom-up and top-down triangulation ensured comprehensive market coverage and data accuracy, drawing insights from US FDA reports, EFSA guidelines, FSSAI publications, and various industry association reports.
Variance decomposition informed the analytical framework, projecting volume and value across the analysis window. Segmentation dimensions modeled include product type, store format, customer type, sales channel, and regional regulatory environment. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Industry-specific forecast inputs included urbanization rates, digital payment adoption, and changes in food safety regulation enforcement.
Underlying assumptions cover consumer spending patterns and regulatory stability, with deviation risk concentrated in unforeseen shifts in food safety standards or major economic downturns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Legal Services Market
Others
Mexico Retail Market
Others
5G Smartphone Market
Others
Europe Astrology Market
Others
Drum Motor Market
Others
North America Healthcare Flexible Packaging Market
Others
South Asia Geosynthetics Market
Others
Level Measuring Instrument Market
Others
Technical Films Market
Others
Fabric Based Computing Market
Others
Radiation Detection Monitoring and Safety Market
Others
North America Enterprise Video Market
Others
Fluorite Market
Others
Digital LUX Meter Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Wearable Solar Devices Market