
 Global Magnesium Carbonate Minerals Market | 2026-2036
Global Magnesium Carbonate Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnesium Carbonate Minerals Market Foresight
Synthetic production methods are tilting cost structures across the magnesium carbonate minerals supply base. Hebei Meishen Technology Co., Ltd. leverages its integrated magnesite reserves to dominate light carbonate output for pharmaceutical and cosmetic buyers. Kyowa Chemical Industry Co., Ltd. sustains a specialized position in high-purity synthetic grades serving Japanese and Southeast Asian personal care markets. Grecian Magnesite anchors European supply through its Kozani mining complex, controlling access to naturally occurring cryptocrystalline deposits prized for flame-retardant applications.
Magnesium carbonate minerals are hydrated or basic magnesium carbonate compounds, typically synthesized through carbonation of magnesium oxide or extracted as natural magnesite, with industrial grades specified by loss-on-ignition values between 50-55% and controlled particle size distributions below 45 microns for filler applications. These minerals function primarily as acid neutralizers, whitening agents, and processing aids across pharmaceutical tablet manufacturing, rubber compounding, and paper coating operations. Light magnesium carbonate dominates pharmaceutical and cosmetic formulations due to its superior oil absorption capacity and compressibility, while heavy magnesium carbonate occupies mature industrial segments where bulk density and cost efficiency determine procurement decisions. Synthetic magnesium carbonate represents the fastest-expanding product category as chemical manufacturers seek consistent specification control unattainable from variable natural ore sources.
EMA pharmaceutical excipient guidelines, FDA's Inactive Ingredient Database standards, and REACH Annex XVII restrictions on heavy metal content collectively elevate purity requirements for market access across Europe and North America. China's GB standards for industrial-grade carbonate and Japan's JIS K 6220 rubber compounding specifications further fragment compliance obligations by end-use geography. Stakeholders must monitor tightening pharmaceutical-grade certification requirements while evaluating backward integration into magnesite mining or synthetic production assets to secure margin visibility.
Market Dynamics
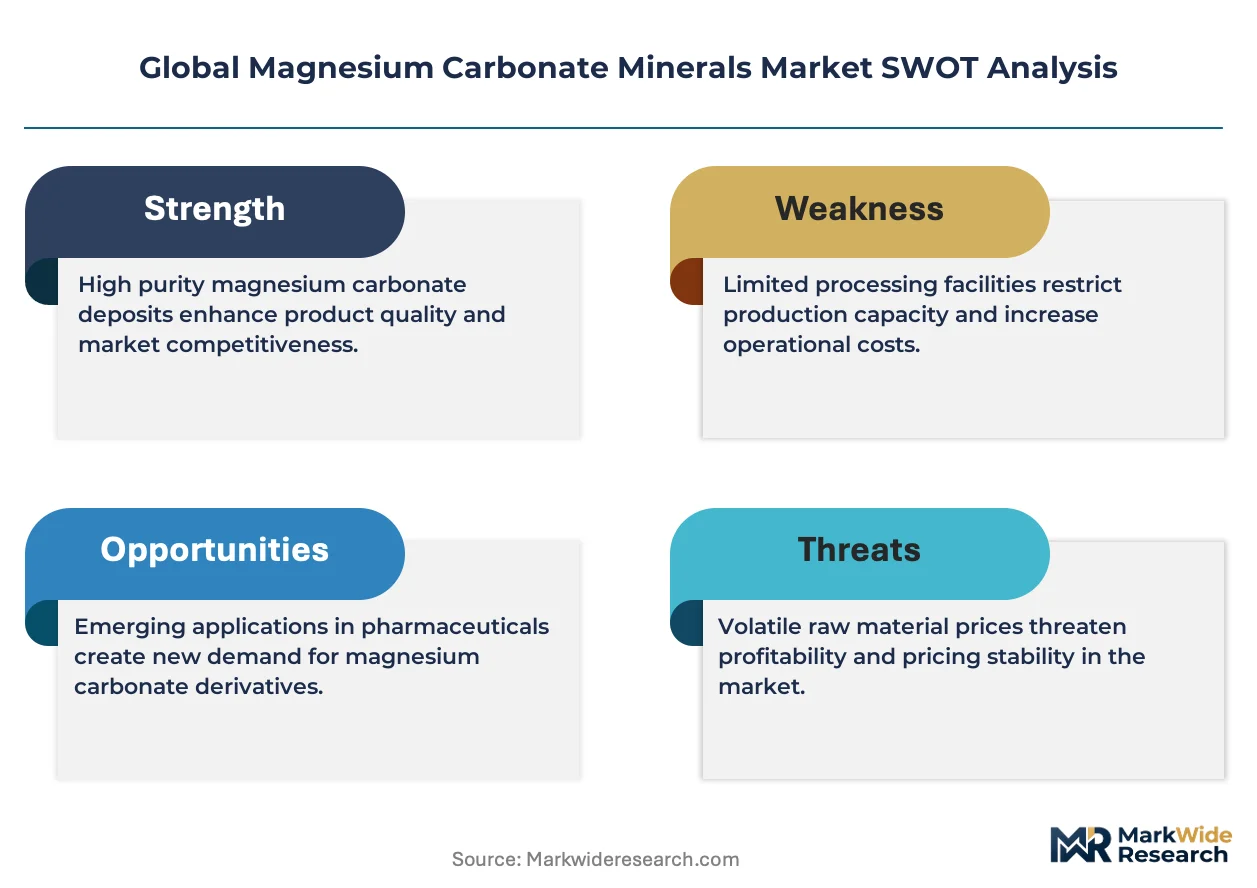
Synthetic production methods are compressing cost structures and specification variability across magnesium carbonate minerals supply chains, forcing natural ore processors to upgrade beneficiation capabilities or retreat to niche pharmaceutical-grade segments.
Growth Catalysts
- REACH Annex XVII heavy metal limits:European pharmaceutical formulators are upgrading to synthetic grades to secure compliance, pulling technical-grade producers toward excipient certification investments.
- Rubber compounding in India:BIS standards alignment with JIS K 6220 is accelerating technical-grade absorption for tire and industrial rubber manufacturing.
- Mineral-based rheology modifiers:Personal care formulation science is displacing petrochemical thickeners with light magnesium carbonate for oil absorption and skin-feel optimization.
Market Restraints
- Magnesite ore concentration:Cryptocrystalline deposit access clusters in Greece and China, creating supply vulnerability for European flame-retardant compounders.
- Energy input volatility:Synthetic carbonate production depends on magnesium oxide calcination, exposing margins to natural gas price swings in key manufacturing clusters.
- Precipitated calcium carbonate substitution:Paper coating and some filler applications are switching to PCC where brightness specifications permit, compressing heavy magnesium carbonate volume.
Strategic Opportunities
- Brazilian rubber manufacturing expansion:ANVISA pharmaceutical-grade recognition remains underdeveloped, creating first-mover advantage for excipient-certified suppliers.
- Direct-to-formulator digital channels:Specialty chemical distributors are launching specification-matching platforms that bypass traditional merchant intermediaries.
- EU Green Deal industrial decarbonization:Carbon capture integration with synthetic carbonate production is attracting green bond financing for facility retrofits.
Industry Challenges
- Pharmaceutical-grade certification timelines:USP-NF and EP compliance documentation requires 18-24 month validation cycles that strain working capital.
- Particle size distribution control:Sub-10 micron specification consistency demands capital-intensive micronization and classification equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnesium Carbonate Minerals Market |
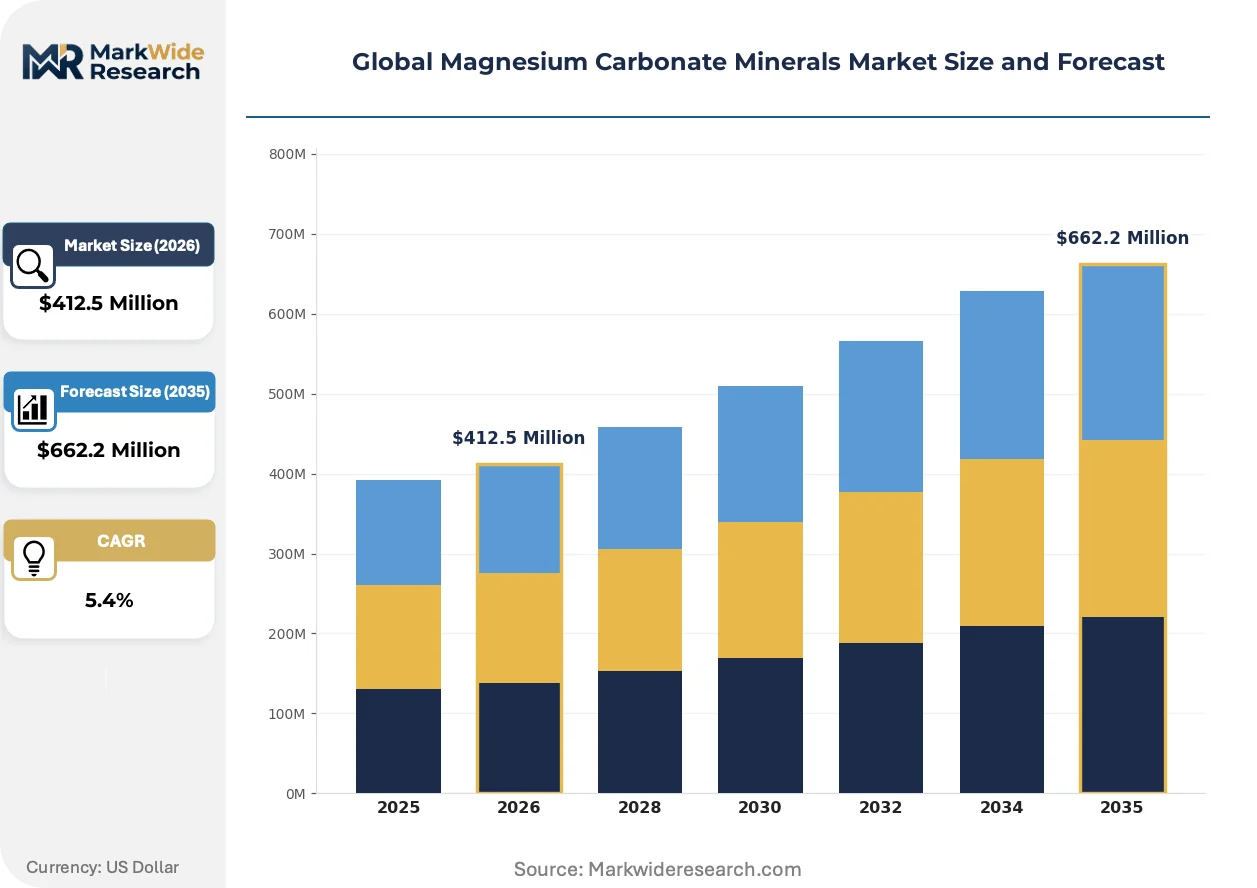
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Magnesium Carbonate, Heavy Magnesium Carbonate, Basic Magnesium Carbonate, Synthetic Magnesium Carbonate Application: Pharmaceuticals, Fireproofing, Rubber Filler, Cosmetics, Paper Coating, Agricultural Additives End User Industry: Chemical Manufacturers, Personal Care Producers, Agriculture Providers, Building Material Firms, Food Processing Plants Form: Powder, Granules, Tablets, Paste |
| Companies Covered | Konoshima Chemical Co., Ltd., Hebei Meishen Technology Co., Ltd., Kyowa Chemical Industry Co., Ltd., Grecian Magnesite, Omya AG, Lhoist Group, Buschle & Lepper S.A., Naikai Salt Industries Co., Ltd., Lehmann & Voss & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnesium Carbonate Minerals Market Shifts & Advancements
Process control technologies and regulatory data systems are converging to reshape how magnesium carbonate minerals are specified, traced, and procured across pharmaceutical and industrial value chains.
Continuous carbonation reactor systems with real-time particle size monitoring are digitizing specification consistency for synthetic magnesium carbonate output. Japanese and South Korean personal care compounders are adopting these systems fastest, replacing batch reactor variability with closed-loop control that compresses rejection rates and certificate-of-analysis turnaround times.
EMA's updated excipient good manufacturing practice guidelines are tightening documentation requirements for residual solvent and elemental impurity testing. Pharmaceutical-grade suppliers must now maintain computerized batch records accessible to qualified persons across the European Economic Area, forcing legacy paper-based quality systems toward expensive validation overhauls.
Specification-driven procurement platforms are fragmenting traditional distributor relationships as formulators demand direct access to COA databases and regulatory file repositories. This channel compression is most visible in North American pharmaceutical and cosmetics verticals, where procurement teams now screen suppliers on FDA Inactive Ingredient Database pre-approval status before engaging technical sales resources.
Global Magnesium Carbonate Minerals Market Segmentation
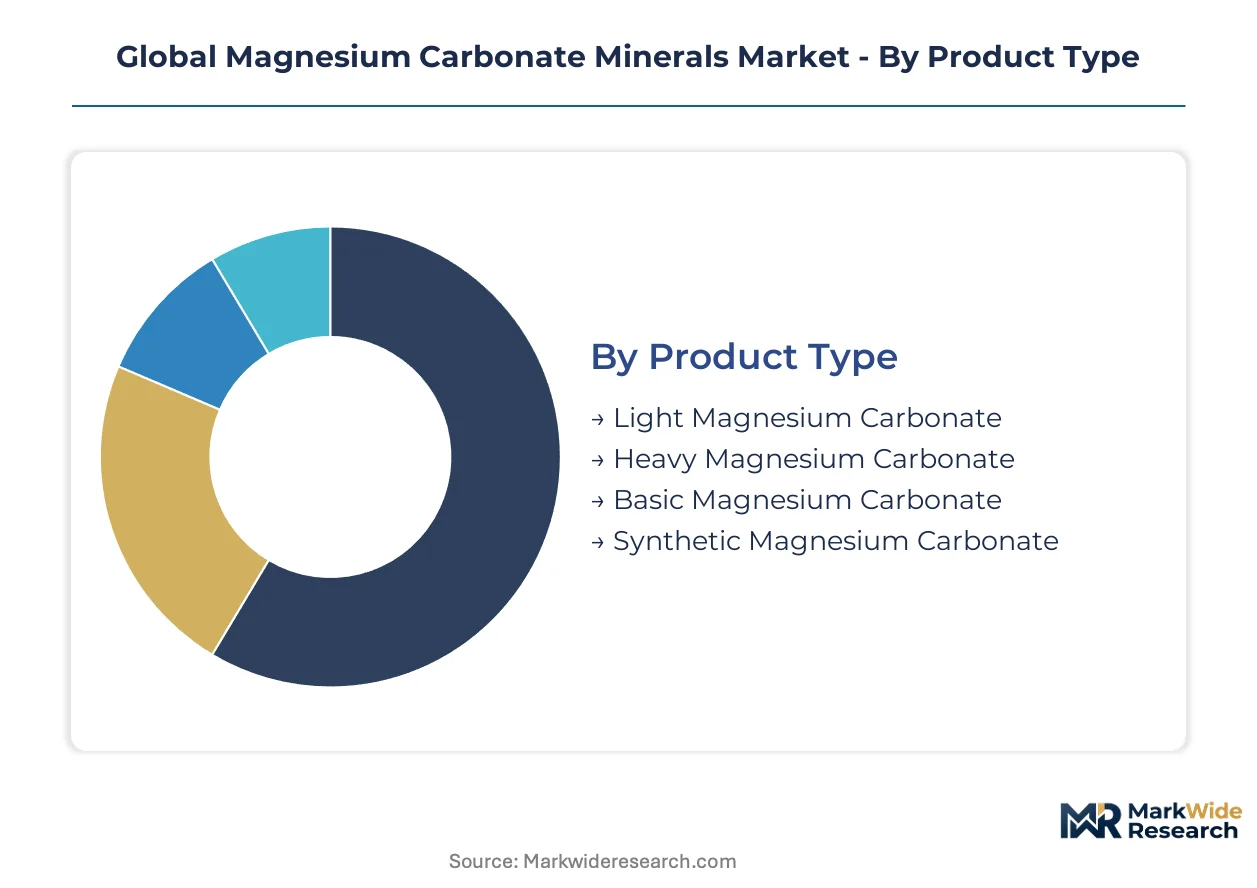
Magnesium carbonate minerals serve divergent specification regimes across pharmaceutical, industrial, and consumer applications. Segmentation reveals how purity grades, particle engineering, and compliance certifications partition procurement decisions and margin structures.
Product Type:
The maturity spectrum stretches from century-old heavy carbonate production to emerging synthetic platforms with closed-loop carbonation control.
- Light Magnesium Carbonate:Low bulk density (0.15-0.25 g/cm³) and exceptional oil absorption capacity define this pharmaceutical and cosmetic grade. Personal care formulators in Japan and South Korea specify sub-10 micron particle distributions for skin-feel optimization, pulling suppliers toward micronization investments. EMA excipient GMP documentation requirements now demand computerized batch records accessible across the European Economic Area.
- Synthetic Magnesium Carbonate:Manufactured through controlled carbonation of magnesium oxide slurry, this grade delivers specification consistency unreachable from natural ore variability. Continuous reactor systems with real-time particle monitoring are displacing batch production in Japanese and South Korean facilities, compressing certificate-of-analysis turnaround times and rejection rates.
- Heavy Magnesium Carbonate:Higher bulk density (0.5-0.8 g/cm³) serves mature industrial segments where cost efficiency outweighs performance premiums. Rubber compounding and construction applications in India absorb rising volumes under BIS standards alignment with JIS K 6220.
- Basic Magnesium Carbonate:Hydrated variants with intermediate properties fill niche applications requiring specific thermal decomposition profiles. Flame-retardant compounders in Greece source cryptocrystalline-derived material for polymer stabilization.
Heavy magnesium carbonate handles the majority of throughput; synthetic grades are expanding most quickly on specification control advantages.
Application:
Application segmentation tracks how regulatory stringency stratifies across end-use sectors, with pharmaceutical and food contact applications commanding premium certification tiers.
- Pharmaceuticals:Tablet manufacturing demands USP-NF and EP compliance with 18-24 month validation cycles for excipient certification. FDA Inactive Ingredient Database pre-approval status now serves as a procurement screen for North American formulators, forcing technical-grade producers toward documentation overhauls.
- Cosmetics:Mineral-based rheology modifiers are displacing petrochemical thickeners as formulation science prioritizes oil absorption and skin-feel optimization. Light magnesium carbonate serves this transition in Japanese and South Korean personal care markets.
- Rubber Filler:Technical-grade absorption is accelerating in India as tire and industrial rubber manufacturing scales under domestic BIS standards.
- Fireproofing:Cryptocrystalline magnesite deposits in Greece supply European flame-retardant compounders with material prized for thermal stability and low smoke emission.
- Paper Coating:Precipitated calcium carbonate substitution is compressing heavy magnesium carbonate volume where brightness specifications permit.
- Agricultural Additives:Soil amendment applications specify lower purity thresholds, sourcing from industrial-grade byproduct streams.
Pharmaceutical and cosmetic applications concentrate margin capture; rubber filler volume is climbing fastest on manufacturing relocation to India.
End User Industry:
Customer type segmentation exposes how backward integration incentives vary across sectors with differing specification volatility and supply security requirements.
- Personal Care Producers:Formulation science shifts toward mineral-based rheology modifiers are strengthening demand for light magnesium carbonate with documented particle size consistency. Japanese and South Korean compounders lead adoption of digitally traced specification control.
- Chemical Manufacturers:Synthetic production investments target captive supply security and margin visibility against natural ore price volatility. Energy input exposure through magnesium oxide calcination shapes facility siting decisions.
- Building Material Firms:Construction applications in China and India absorb technical-grade output for magnesium oxychloride cement and fireproofing board production.
- Agriculture Providers:Fertilizer and soil amendment applications prioritize cost position over certification depth, sourcing from merchant distributors.
- Food Processing Plants:Anticaking and pH buffering applications require food-grade certification with regional regulatory alignment.
Chemical manufacturers and personal care producers anchor premium-grade procurement; agriculture providers represent the highest volume throughput on price-sensitive sourcing.
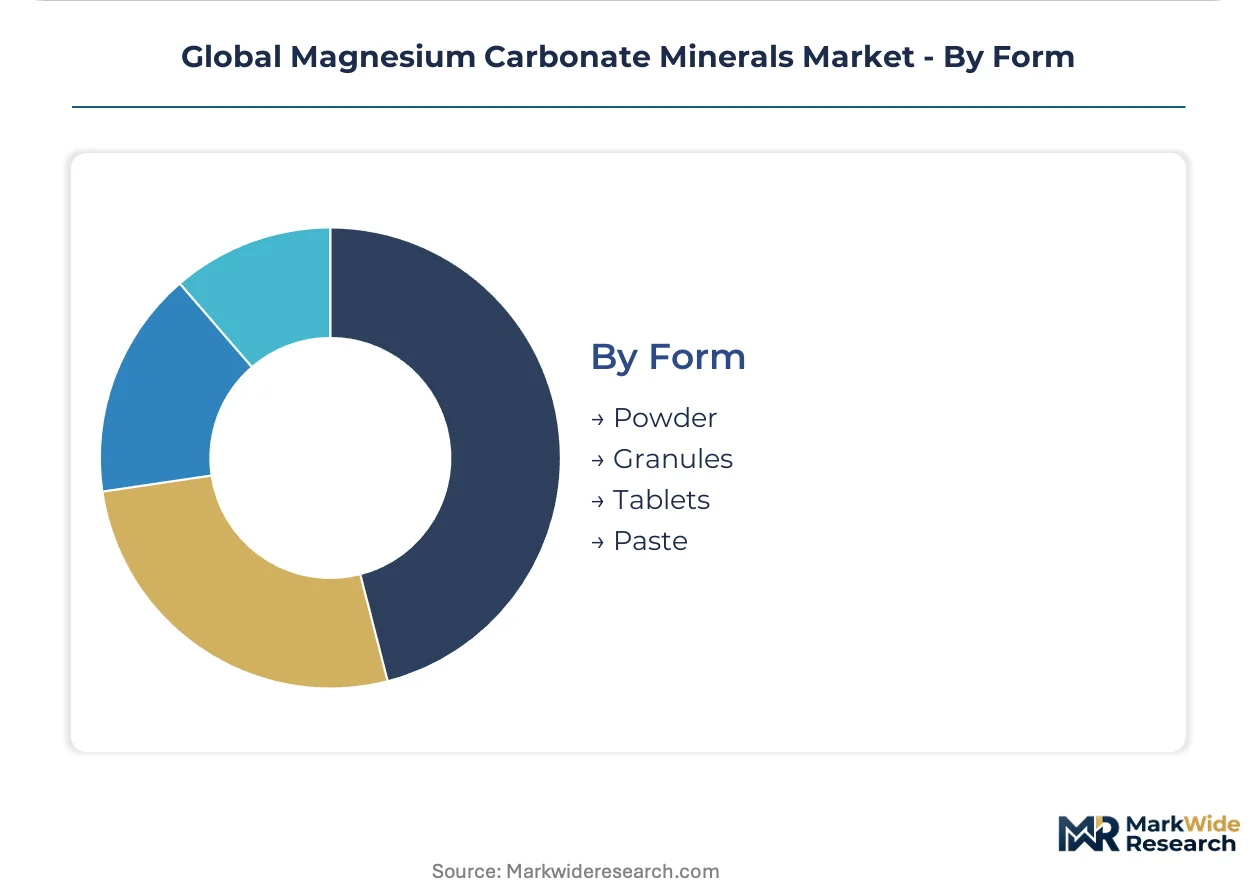
Form:
Physical form selection reflects handling economics, dissolution kinetics, and downstream processing integration requirements across divergent manufacturing environments.
- Powder:Dominant form for pharmaceutical tableting, rubber compounding, and cosmetic formulation. Sub-45 micron specifications for filler applications demand capital-intensive classification equipment.
- Granules:Intermediate processing form for agricultural and construction applications where dust control and flowability determine handling economics.
- Tablets:Pre-compressed units serve specific pharmaceutical manufacturing workflows and effervescent formulation requirements.
- Paste:Slurry and suspension forms support paper coating and specialized chemical processing where direct integration with aqueous systems reduces handling steps.
Powder form commands the dominant share of value and volume; paste formulations are gaining fastest on paper coating line integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese synthetic carbonate producers export rising volumes to Japanese and South Korean personal care compounders, while Greek cryptocrystalline magnesite feeds European flame-retardant manufacturers. India absorbs technical-grade output for rubber manufacturing expansion. Brazil presents underdeveloped pharmaceutical-grade recognition.
China
Hebei Province magnesite reserves support integrated light carbonate production for pharmaceutical and cosmetic export markets. GB standards for industrial-grade material govern domestic construction and rubber applications. Tianjin and Tangshan chemical clusters house synthetic production facilities serving Japanese personal care buyers with sub-10 micron specification control.
Greece
Kozani mining complex controls European access to naturally occurring cryptocrystalline deposits for flame-retardant polymer stabilization. REACH Annex XVII heavy metal limits push pharmaceutical formulators toward imported synthetic grades. Thessaloniki port infrastructure handles bulk export to German and Italian rubber compounders.
Japan
Osaka and Kobe metropolitan areas concentrate personal care formulation science advancing mineral-based rheology modifiers. METI industrial standards align with JIS K 6220 specifications for domestic rubber manufacturing. Continuous carbonation reactor systems with real-time particle monitoring operate in Hyogo Prefecture facilities.
India
Gujarat and Maharashtra industrial corridors scale tire and industrial rubber manufacturing under BIS standards alignment with JIS K 6220. Technical-grade magnesium carbonate absorption accelerates as domestic automotive production expands. Mumbai merchant distributors manage import flows from Chinese synthetic producers.
United States
FDA Inactive Ingredient Database pre-approval status serves as procurement screen for North American pharmaceutical formulators. New Jersey and Pennsylvania chemical processing clusters rely on imported pharmaceutical-grade material for tablet manufacturing. EPA industrial emissions oversight shapes synthetic production facility siting decisions.
Global Magnesium Carbonate Minerals Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated magnesite miners and specialized synthetic carbonate producers. Natural ore processors dominate heavy carbonate output for industrial applications, while chemical manufacturers capture pharmaceutical and cosmetic premiums through specification control. Three archetypes define competitive positioning: reserve-integrated miners, synthetic specialists, and diversified mineral processors. Capacity expansion and backward integration into magnesite mining represent the dominant competitive moves as producers seek margin visibility against raw material volatility.
Among Japanese specialists, Konoshima Chemical Co., Ltd. and Kyowa Chemical Industry Co., Ltd. occupy positions emphasizing high-purity synthetic grades for regulated personal care markets. Hebei Meishen Technology Co., Ltd. exemplifies the reserve-integrated archetype through its captive magnesite access. Grecian Magnesite anchors European natural ore supply from its Kozani mining complex, representing the geographically concentrated cryptocrstalline deposit model.
| Leading Market Players |
|---|
| Konoshima Chemical Co., Ltd. |
| Hebei Meishen Technology Co., Ltd. |
| Kyowa Chemical Industry Co., Ltd. |
| Grecian Magnesite |
| Omya AG |
| Lhoist Group |
| Buschle & Lepper S.A. |
| Naikai Salt Industries Co., Ltd. |
| Lehmann & Voss & Co. |
| Others |
Supply & Pricing Matrix
Tianjin and Tangshan chemical clusters in Hebei Province anchor synthetic magnesium carbonate capacity for Japanese and South Korean personal care buyers, concentrating pricing power among reserve-integrated producers who control magnesite ore access. Pharmaceutical-grade certification costs and energy input volatility for magnesium oxide calcination feed directly into tiered pricing structures that separate excipient-certified synthetic grades from technical-grade heavy carbonate.
Pricing Analysis
Batch-reactor versus continuous-carbonation reactor pricing gaps separate incumbent synthetic producers from next-generation specification control platforms. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels stratifies procurement, with USP-NF and EP certification premiums widening against uncertified technical material. Cost compression in heavy carbonate is intensifying because precipitated calcium carbonate substitution in paper coating erodes volume leverage. Rubber compounders in India exhibit highest price sensitivity, while Japanese personal care formulators prioritize particle size consistency over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for pharmaceutical-grade distributors. Production gravity centers on China, Greece, and India, with cryptocrystalline magnesite deposits in Kozani feeding European flame-retardant compounders. Synthetic output draws from magnesium oxide calcination, natural gas inputs, and carbonation reagent supply. Single-source vulnerability concentrates in Hebei Province magnesite reserves controlled by integrated miners. Distribution runs through Mumbai and Thessaloniki merchant distributors for technical-grade material, while pharmaceutical grades bypass intermediaries via direct-to-formulator digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnesium carbonate minerals sit in early-cycle expansion as mineral-based rheology modifiers displace petrochemical thickeners in personal care formulation science, with synthetic grade penetration still below saturation across pharmaceutical excipient applications.
For Market Incumbents: Harden excipient certification moats through USP-NF and EP validation investments that extend 18-24 month timelines, blocking technical-grade producers from pharmaceutical tier migration. Deepen backward integration into magnesite mining or captive synthetic production assets to secure margin visibility against natural ore price volatility and energy input swings. For New Entrants and Emerging Players: Brazilian pharmaceutical-grade recognition gaps offer first-mover positioning before ANVISA excipient guidelines mature, targeting rubber manufacturing expansion in São Paulo industrial corridors with technical-grade supply. Pursue direct-to-formulator digital channel entry, bypassing legacy merchant distributors who currently control specification-matching platforms in North American cosmetics verticals. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic specialists with continuous carbonation reactor systems and locked personal care supply agreements in Japan and South Korea. Long-term viability over the next decade favors reserve-integrated miners with Kozani or Hebei deposit access, or synthetic platforms with carbon capture integration attracting green bond financing. Watch EMA excipient GMP guideline enforcement tightening as the inflection signal for certification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesite Mining | Hebei Meishen Technology's captive reserve access demonstrates margin protection against ore price volatility. |
| Continuous Carbonation Reactor Upgrade | Hyogo Prefecture facilities deploy real-time particle monitoring to compress certificate-of-analysis turnaround times. |
| Pharmaceutical-Grade Certification Investment | EMA's updated excipient GMP guidelines force legacy quality systems toward computerized batch record validation. |
| Carbon Capture Integration | EU Green Deal industrial decarbonization incentives attract green bond financing for synthetic production retrofits. |
| Direct-to-Formulator Digital Channel Launch | Specialty chemical distributors bypass traditional merchant intermediaries with specification-matching platforms. |
Research Methodology
A spread of perspectives from synthetic production plant managers, pharmaceutical procurement leads at tablet manufacturers, personal care formulation scientists, and magnesite mining operations directors converged on the working assumptions. Primary interviews combined with secondary validation from FDA Inactive Ingredient Database filings, EMA excipient guidance documents, REACH Annex XVII regulatory texts, and BIS standards publications. Bottom-up capacity and consumption estimates triangulated against top-down trade flow analysis across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling grade tier, end-use industry, particle size specification, and regional production hub segmentation throughout the forecast period. CAGRs derived from production capacity expansion schedules, regulatory compliance cost trajectories, and substitution elasticity estimates for precipitated calcium carbonate in paper coating. Energy input price scenarios and pharmaceutical-grade certification timeline assumptions shaped synthetic versus natural ore growth differentials.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed synthetic producers or Greek mining consortiums would shift outcomes beyond modeled ranges. Regulatory enforcement intensity at EMA, FDA, and REACH, plus carbon capture technology cost curves, represent primary revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Flake Graphite Market