
 Saudi Arabia and GCC Ferrosilicon Market | 2026-2036
Saudi Arabia and GCC Ferrosilicon Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia and GCC Ferrosilicon Market Foresight
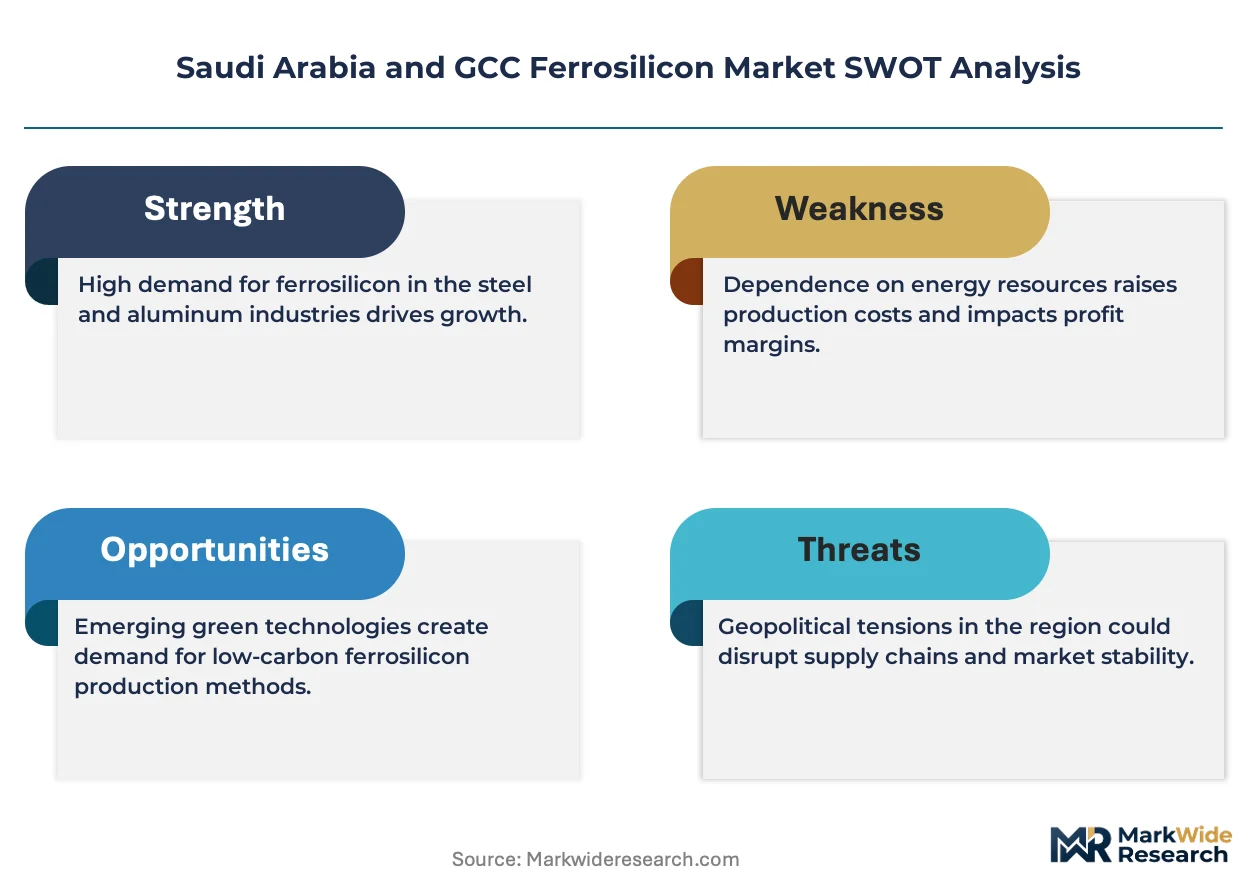
The capability gap between integrated smelters and merchant traders is reorganizing competitive dynamics across the GCC ferrosilicon landscape. Elkem ASA leverages its captive Norwegian silicon metal supply to sustain cost discipline in Gulf deliveries. Ferroglobe PLC anchors its regional position through Spanish and French furnace assets that feed Middle East distributors. Gulf Ferro Alloys Company (SABAYEK) competes on proximity, operating submerged arc capacity within Saudi Arabia's industrial corridor.
Ferrosilicon denotes an iron-silicon alloy typically containing 70-90% silicon by weight, produced via carbothermic reduction of quartz and iron oxide in submerged arc furnaces at temperatures exceeding 1,800°C; it functions primarily as a deoxidizer and inoculant in liquid steel processing. The product type dimension shows Ferrosilicon 75 occupying the dominant volume share due to its balanced silicon content for general steelmaking, while Ferrosilicon 90 commands premium positioning in specialty alloy production where ultra-high silicon purity justifies elevated pricing. Within applications, steelmaking absorbs the majority of regional offtake, though casting demand is gaining traction from Saudi automotive supplier investments in lightweight engine component manufacturing.
SASO metallurgical standards, the Gulf Standardization Organization (GSO) technical regulations, and Saudi Vision 2030 domestic content requirements collectively shape product specifications and import substitution incentives for ferrosilicon suppliers. The SFDA and Saudi Customs Authority enforce material traceability protocols that filter non-compliant imports from Asian merchant traders. Stakeholders must monitor how Jubail and Ras Al-Khair industrial zone expansion timelines reshape regional smelter capacity decisions against freight-advantaged imports.
Market Dynamics
Saudi Vision 2030 construction megaprojects are compressing ferrosilicon procurement cycles as integrated steelmakers in Jubail Industrial City accelerate deoxidizer offtake ahead of smelter commissioning timelines.
Growth Catalysts
- Jubail Industrial City expansion:Integrated steel complexes in Saudi Arabia's Eastern Province are locking in multi-year ferrosilicon supply contracts to feed capacity ramps at direct-reduced iron and electric arc furnace facilities.
- SASO metallurgical standards tightening:Higher-grade import specifications are filtering low-purity Asian merchant supply and creating pull-through for regional producers capable of 75% silicon minimum content certification.
- Automotive casting investments:Saudi supplier parks for lightweight engine component manufacturing are diversifying ferrosilicon demand beyond traditional steelmaking into inoculant applications for ductile iron foundries.
Market Restraints
- Quartz feedstock cost volatility:Carbothermic reduction economics hinge on high-purity silica sourcing, with Norwegian and Brazilian quartz concentrate pricing subject to mining royalty adjustments and ocean freight rate swings.
- Merchant trader supply concentration:Non-integrated distributors without captive submerged arc furnace assets face margin compression when Elkem ASA and Ferroglobe PLC leverage backward integration into silicon metal production.
- Substitute deoxidizer threat:Calcium-silicon alloys and aluminum-based alternatives are gaining specification trials in certain low-carbon steel grades where silicon content flexibility exists.
Strategic Opportunities
- Ras Al-Khair industrial zone:Saudi Arabia's second integrated metals cluster offers greenfield smelter siting advantages with captive power and proximity to Red Sea shipping lanes for African quartz import.
- GSO technical regulation harmonization:Unified Gulf Standardization Organization metallurgical standards across GCC states are reducing compliance fragmentation for regional producers seeking multi-country certification.
- Solar-grade silicon convergence:Polysilicon purification technology spillover from Saudi photovoltaic manufacturing investments is creating technical pathways for ultra-high-purity ferrosilicon 90 production.
Industry Challenges
- Submerged arc furnace operator scarcity:The specialized electrochemistry expertise required for 1,800°C carbothermic reduction process control is concentrated among retiring European technical workforces with limited GCC knowledge transfer.
- SASO certification timeline compression:Material traceability protocols enforced by Saudi Customs Authority require batch-level documentation that extends import clearance cycles and strains distributor working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia and GCC Ferrosilicon Market |
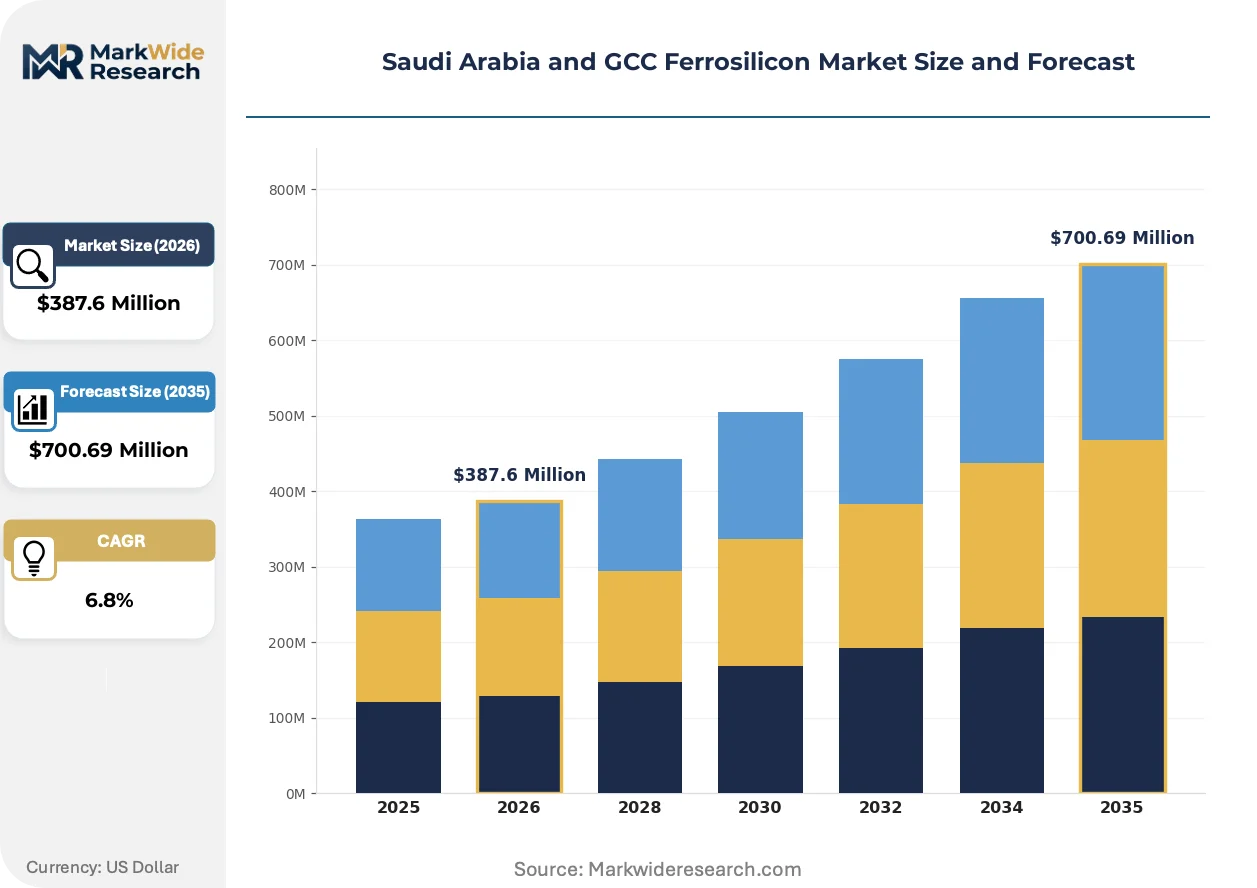
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrosilicon 70, Ferrosilicon 75, Ferrosilicon 80, Ferrosilicon 90 Application: Casting, Steelmaking, Alloy Production, Welding End User: Construction, Automotive Suppliers, Aerospace, Shipbuilding Production Process: Submerged Arc Furnace, Electric Arc Furnace, Induction Furnace, Others |
| Companies Covered | Elkem ASA, Ferroglobe PLC, Eurasian Resources Group, Gulf Ferro Alloys Company (SABAYEK), Saudi Ferroalloys Company, Oman Ferroalloy Company (OFAC), Emirates Steel, Kuwait Ferro Alloys, OM Holdings Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia and GCC Ferrosilicon Market Shifts & Advancements
Electrode technology advances and digital furnace control systems are restructuring production economics for GCC ferrosilicon suppliers competing against freight-advantaged European integrated producers.
Graphite electrode consumption optimization through AI-driven arc stability management is supplanting traditional operator-dependent furnace control in Saudi smelter operations. SABAYEK and regional producers are deploying sensor arrays for real-time bath temperature monitoring to reduce specific electrode consumption per ton of ferrosilicon 75 output. This technology compression is narrowing the cost gap between GCC merchant supply and Norwegian integrated production.
SFDA material traceability protocols are mandating blockchain-anchored documentation for ferrosilicon imports into Saudi Arabia. The industrial consequence is a filtering mechanism that advantages established suppliers with integrated ERP-to-customs data pipelines over Asian merchant traders with paper-based certification. High-grade ferrosilicon 90 for specialty alloy applications faces the most stringent documentation requirements, pushing distributors toward direct mill relationships.
Steelmaker buying committees in Jubail are consolidating ferrosilicon procurement under annual framework agreements with volume-scale pricing mechanisms. Long-term contracting is displacing quarterly spot purchasing as megaproject construction schedules demand supply security over price optimization. This behavioral shift is most visible in Saudi Arabia's Eastern Province, where integrated steel complexes are internalizing procurement functions previously delegated to trading houses.
Saudi Arabia and GCC Ferrosilicon Market Segmentation
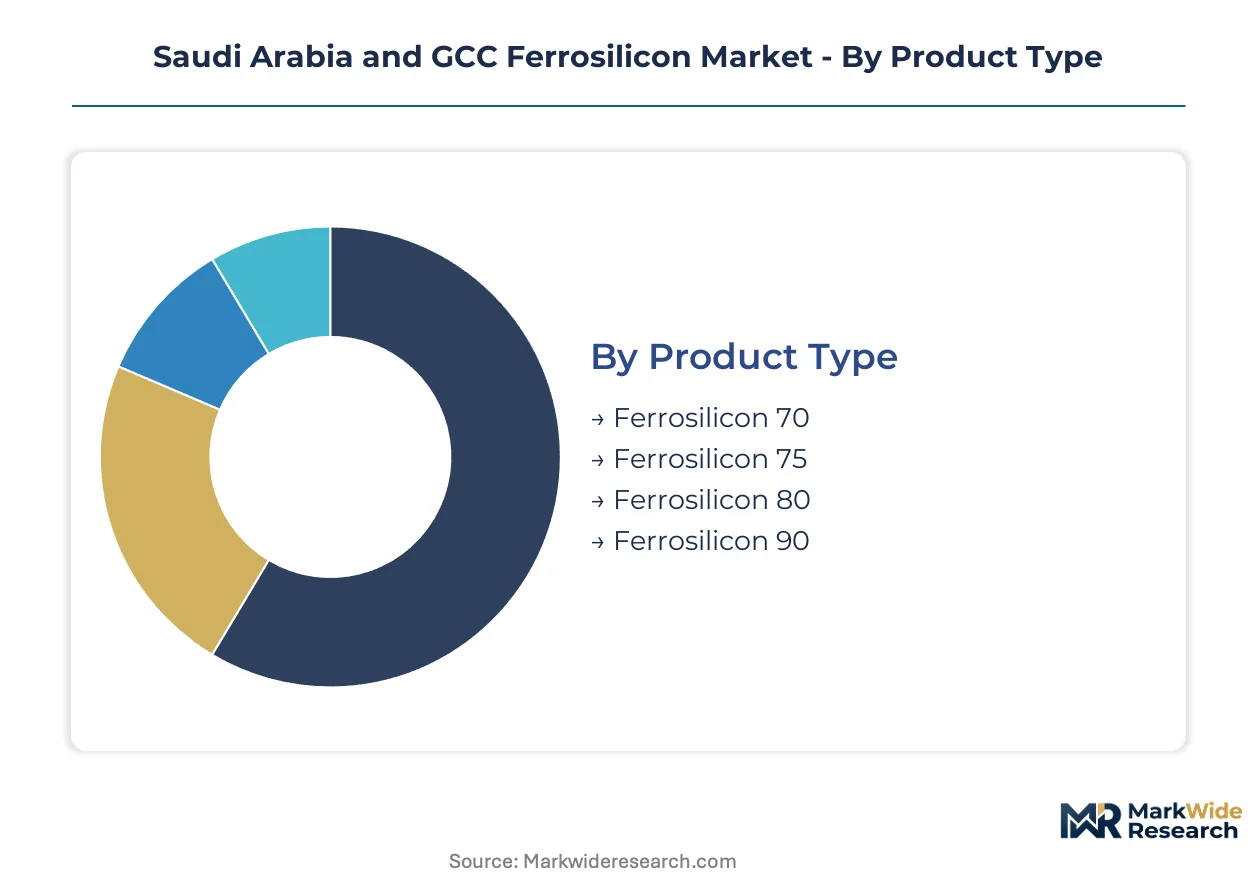
Ferrosilicon procurement patterns across Saudi Arabia and GCC states diverge sharply by product grade and end-use sophistication. SASO certification requirements and Vision 2030 project timelines are compressing specification tolerances, forcing buyers to segment suppliers by metallurgical compliance rather than price alone.
Product Type:
Domestic Saudi production concentrates in mid-grade ferrosilicon for regional steelmakers, while ultra-high-purity grades remain import-dependent from European integrated smelters.
- Ferrosilicon 75:The alloy contains 74-76% silicon by weight with balanced aluminum and calcium trace elements optimized for general steel deoxidation. Demand concentrates in Jubail Industrial City's direct-reduced iron facilities where procurement committees prioritize supply security over spot price minimization.
- Ferrosilicon 90:This ultra-high-silicon grade demands 88-92% silicon content with stringent phosphorus and sulfur limits below 0.04%. Specialty alloy producers in Ras Al-Khair industrial zone absorb regional offtake for aerospace-grade stainless steel where SASO import documentation requirements filter merchant traders.
- Ferrosilicon 70:Lower silicon content suits cost-sensitive foundry applications in Saudi Arabia's Central Province.
- Ferrosilicon 80:Intermediate positioning serves ductile iron inoculation where automotive supplier parks demand consistent nodularity control.
Ferrosilicon 75 commands the established base. The steepest expansion runs through Ferrosilicon 90.
Application:
Steelmaking absorbs volume leadership, yet casting applications are diversifying procurement specifications as Saudi automotive investments mature.
- Steelmaking:Deoxidation and alloying in liquid steel processing consumes submerged arc furnace output at temperatures exceeding 1,600°C. Jubail's integrated steel complexes anchor regional offtake through multi-year framework agreements that displace quarterly spot purchasing.
- Casting:Inoculation of molten iron to control graphite morphology requires precise silicon dissolution kinetics. Dammam's emerging automotive supplier parks for lightweight engine components are qualifying ferrosilicon grades previously reserved for European foundries.
- Alloy Production:Master alloy feedstock for specialty steel mills demands trace element documentation under SFDA protocols.
- Welding:Electrode coating applications represent niche consumption concentrated in Saudi Arabia's Eastern Province fabrication clusters.
Steelmaking retains volume dominance. Casting gains share fastest as supplier park investments commission.
End User:
Construction sector procurement cycles compress around megaproject milestones, while automotive suppliers extend qualification timelines for metallurgical certification.
- Construction:Reinforcing bar and structural steel production at Jubail and Yanbu integrated mills drives baseline ferrosilicon 75 consumption. NEOM and Red Sea Project timelines are accelerating deoxidizer procurement ahead of concrete pour schedules.
- Automotive Suppliers:Ductile iron foundries serving engine block and transmission housing manufacturing require inoculant-grade ferrosilicon with controlled size distribution. SASO material traceability mandates are extending supplier qualification periods to 18-24 months.
- Aerospace:Premium alloy specifications for turbine components demand Ferrosilicon 90 with full batch documentation.
- Shipbuilding:Ras Al-Khair maritime cluster absorption remains nascent as yard commissioning progresses.
Construction anchors current procurement volumes. Automotive suppliers are climbing the fastest as localization targets harden.
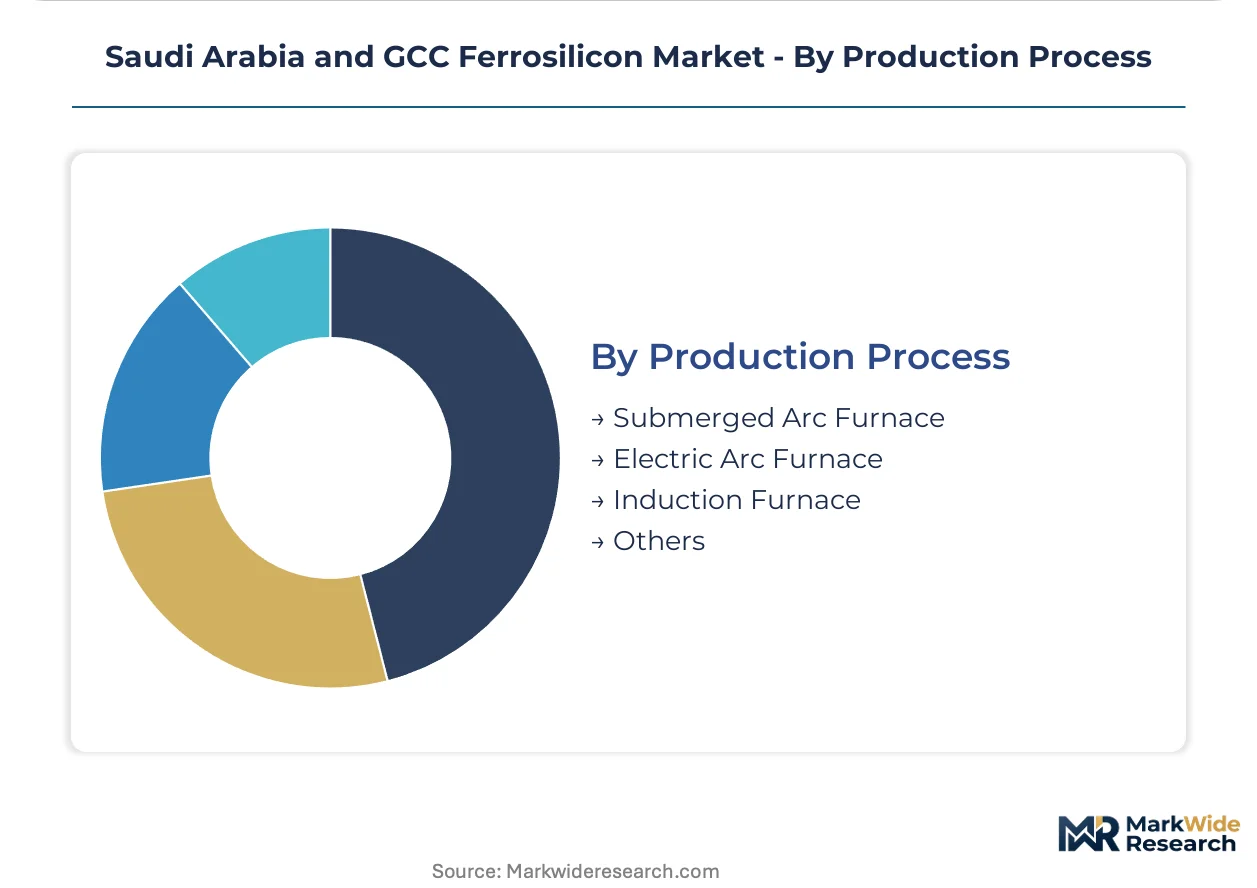
Production Process:
Process selection determines cost position and metallurgical control, with submerged arc furnace output commanding premium positioning against electric arc alternatives.
- Submerged Arc Furnace:Carbothermic reduction at 1,800-2,000°C using graphite electrodes delivers consistent silicon recovery above 90% from quartz and iron oxide feedstock. SABAYEK's Saudi-based capacity leverages this process for domestic supply security.
- Electric Arc Furnace:Scrap-based remelting suits lower-grade ferrosilicon production where silicon content flexibility accommodates construction steel specifications.
- Induction Furnace:Precision temperature control serves small-batch specialty alloy production with rapid chemistry adjustment.
- Others:Emerging plasma and solar-thermal reduction technologies remain pre-commercial for GCC deployment.
Submerged arc furnace output commands the established base. The steepest expansion trajectory runs through electric arc furnace processing as scrap availability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia absorbs the dominant ferrosilicon volume share through Jubail's steel corridor, while smaller GCC states concentrate demand in discrete industrial zones with distinct procurement patterns shaped by local content mandates and import dependency.
Saudi Arabia
Jubail Industrial City and Ras Al-Khair anchor ferrosilicon consumption through integrated steel complexes and emerging metals clusters. SASO metallurgical standards tightening filters low-grade imports and elevates domestic smelter competitiveness. Eastern Province steelmakers are locking multi-year supply contracts ahead of NEOM construction milestones.
United Arab Emirates
Emirates Steel in Abu Dhabi drives baseline deoxidizer demand for construction-grade rebar production. MOHAP material traceability protocols extend import clearance cycles for merchant traders lacking integrated documentation systems. Jebel Ali industrial zone distributors are consolidating procurement under annual framework agreements with volume-scale pricing.
Oman
SOHAR Port and Freezone ferroalloy investments target Red Sea shipping advantages for African quartz feedstock import. Oman Ferroalloy Company capacity ramps are compressing regional supply timelines for specialty steelmakers. Duqm Special Economic Zone greenfield smelter siting offers captive power integration for cost-competitive Ferrosilicon 75 output.
Kuwait
Shuaiba industrial area steel fabrication clusters sustain modest ferrosilicon offtake for reinforcing bar production. Kuwait Ferro Alloys maintains merchant trading presence without captive submerged arc furnace assets. Domestic procurement depends on Saudi and UAE transshipment given limited local smelter infrastructure.
Qatar
Mesaieed industrial city steel investments absorb ferrosilicon for construction material supply tied to FIFA legacy infrastructure completion. QatarEnergy downstream metals diversification is evaluating ferroalloy integration within existing petrochemical corridors. Ras Laffan industrial zone expansion timelines remain contingent on LNG revenue allocation priorities.
Saudi Arabia and GCC Ferrosilicon Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in GCC ferrosilicon supply, with Norwegian and Spanish furnace operators leveraging backward integration into silicon metal production against regional proximity-based competitors. The market structure stratifies across three archetypes: integrated smelters with captive quartz sourcing, regional furnace operators dependent on imported feedstock, and merchant distributors without production assets. Competitive moves center on long-term procurement contracting with Jubail steelmakers and SASO certification pre-qualification to filter Asian spot supply.
Among integrated European suppliers, Elkem ASA and Ferroglobe PLC exemplify the backward-integrated archetype controlling silicon metal supply chains that feed Gulf deliveries. Gulf Ferro Alloys Company (SABAYEK) occupies the regional producer position with Saudi-based submerged arc capacity serving Eastern Province steel complexes. Eurasian Resources Group represents the diversified mining conglomerate archetype with ferroalloy exposure across multiple metallurgical product lines.
| Leading Market Players |
|---|
| Elkem ASA |
| Ferroglobe PLC |
| Eurasian Resources Group |
| Gulf Ferro Alloys Company (SABAYEK) |
| Saudi Ferroalloys Company |
| Oman Ferroalloy Company (OFAC) |
| Emirates Steel |
| Kuwait Ferro Alloys |
| OM Holdings Ltd. |
| Others |
Supply & Pricing Matrix
SASO metallurgical certification protocols gate both supplier qualification and price differentiation simultaneously, compressing procurement timelines for documented ferrosilicon 75 while elevating premiums for traceable Ferrosilicon 90. Buyers in Jubail Industrial City now segment vendors by compliance tier rather than spot price alone, restructuring how cost pressure transmits through GCC steelmaker supply chains.
Pricing Analysis
Long-term offtake contracts dominate ferrosilicon procurement in Saudi Arabia's Eastern Province, displacing quarterly spot purchasing as NEOM construction milestones accelerate. Price differentiation rests on silicon purity certification and volume scale, with SASO-compliant Ferrosilicon 90 commanding substantial premiums over undocumented Asian merchant supply. Cost compression intensifies in mid-grade Ferrosilicon 75 as SABAYEK's domestic submerged arc capacity expands, while specialty alloy producers show least price sensitivity due to aerospace qualification requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites GCC ferrosilicon supply security, with Norwegian, Spanish, and Brazilian furnace output feeding Gulf distributor networks. Raw material dependencies center on high-purity quartz concentrate from Norwegian and Brazilian mining operations, graphite electrodes sourced from Chinese and Japanese manufacturers, and metallurgical coke from Australian coking coal. Single-source vulnerability concentrates in European integrated smelters controlling silicon metal feedstock. Distribution runs through Jebel Ali and SOHAR Port bonded warehouses serving Saudi transshipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Vision 2030 construction acceleration and SASO traceability mandates are disrupting traditional merchant trading economics, creating structural openings for integrated producers with documented supply chains.
For Market Incumbents: Shield market position by deepening backward integration into silicon metal production and securing multi-year framework agreements with Jubail steelmakers before Ras Al-Khair capacity ramps. Invest in blockchain-anchored ERP systems to satisfy SFDA batch-level documentation requirements that filter paper-based Asian competitors.
For New Entrants and Emerging Players: Anchor in Ras Al-Khair industrial zone greenfield development, where captive power integration and Red Sea shipping access offset European freight advantages. Target automotive supplier park inoculant qualification as the most penetrable segment, leveraging 18-24 month SASO certification timelines to build technical credibility before steelmaker procurement committees consolidate vendor lists.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across submerged arc furnace capacity expansions as electrode technology and digital control systems raise technical barriers. Five-to-ten year viability favors integrated producers with captive quartz sourcing or regional furnace operators with Saudi industrial zone proximity. Monitor Oman Ferroalloy Company capacity ramp timelines as the signal to watch for regional supply-demand rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Elkem ASA and Ferroglobe PLC leverage captive Norwegian supply to defend Gulf margin position against merchant traders. |
| SASO Certification Pre-Qualification | Documentation compliance filters low-purity Asian imports and creates pull-through for 75% silicon minimum regional output. |
| Long-Term Supply Agreement | Jubail steelmakers lock multi-year ferrosilicon contracts to secure deoxidizer offtake ahead of smelter commissioning timelines. |
| Greenfield Smelter Siting in Ras Al-Khair | Captive power integration and Red Sea proximity offer cost-competitive positioning against freight-advantaged European imports. |
| Blockchain-Anchored Traceability System | SFDA protocols mandate ERP-to-customs data pipelines that advantage established suppliers over paper-based certification traders. |
Research Methodology
A standing panel of submerged arc furnace operators, Jubail steelmaker procurement directors, and SFDA compliance officers provided ongoing calibration across the analysis window. Primary interviews with SABAYEK technical staff, Emirates Steel buying committees, and Oman Ferroalloy project developers combined with secondary validation from SASO technical regulations, GSO harmonization directives, customs trade data, and SEC filings from Elkem ASA and Ferroglobe PLC. Bottom-up capacity assessments and top-down steel production forecasts underwent iterative triangulation.
Consistency checks validated volume and value outputs against external benchmarks including regional steel output projections and ferroalloy trade flow databases. Segmentation modeling incorporated product grade tier, end-use application, production process technology, and industrial zone geography across the projection horizon. CAGRs derived from production capacity ramp schedules, megaproject construction timelines, and import substitution elasticity assumptions. Forecast inputs included quartz feedstock pricing volatility and electrode technology cost curves.
Material uncertainties — quartz royalty adjustments, ocean freight rate swings, and SASO certification timeline compression — sit outside the modeled envelope. Forecasts reflect documented assumptions about Vision 2030 project execution and GSO regulatory harmonization. Practitioners should keep alternative scenarios live as NEOM construction milestones and Ras Al-Khair smelter commissioning dates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Diamond Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Dolomite Market