
 Wegscheiderite Market | 2026-2036
Wegscheiderite Market Size, Share, and Industry Trends Forecast 2026-2036
Wegscheiderite Market Analysis
Single-source reliance on Chinese mineral feedstock is recalibrating toward multi-source agreements with synthetic producers. Ashland Global Holdings leverages its polymer science infrastructure to secure modified wegscheiderite supply chains. Kemin Industries anchors natural extraction partnerships in Southeast Asian botanical zones. Indena competes through specialized purification protocols that differentiate pharmaceutical-grade output from industrial grades.
Wegscheiderite is a rare sodium carbonate mineral with orthorhombic crystal structure, typically synthesized for industrial use when natural deposits prove insufficient for specialized applications. Synthetic variants dominate volume due to controlled stoichiometry essential for optical coatings and battery electrolyte matrices. The application split shows optical coatings leading value contribution while nanocomposites represent the fastest-growing structural category driven by aerospace thermal management demand. End-user concentration in electronics manufacturing supports premium pricing for high-purity synthetic grades, whereas industrial manufacturing absorbs composite formulations at standard specifications.
Japan's METI mineral security framework and China's GB standards for rare mineral processing collectively shape import substitution incentives across North American and European supply chains. The EPA and REACH both enforce disclosure thresholds for sodium carbonate derivatives in coatings applications, tightening market access for uncharacterized feedstock sources. Stakeholders must monitor synthesis patent filings and national mineral stockpile policies as signals for near-term supply reconfiguration.
Market Dynamics
China's tightened export controls on rare mineral processing feedstocks are forcing European and Japanese buyers to accelerate domestic synthetic wegscheiderite capacity, reshaping procurement from extraction-dependent to chemistry-controlled supply chains.
Growth Catalysts
- Japan's METI mineral security framework:Incentivizes strategic stockpiling and domestic synthesis investment, pulling procurement away from Chinese mineral dependency toward captive production.
- Thermal barrier coatings in aerospace:Precision ceramics manufacturers in Germany and Japan are expanding synthetic wegscheiderite procurement for high-temperature engine components.
- Battery electrolyte matrices:Controlled stoichiometry requirements in solid-state battery development favor synthetic variants with exact sodium carbonate ratios.
Market Restraints
- Feedstock concentration risk:Natural sodium carbonate deposits cluster in specific geological formations, leaving synthetic production dependent on purified industrial soda ash with volatile energy-linked pricing.
- REACH disclosure thresholds:ECHA enforcement of sodium carbonate derivative reporting in coatings applications restricts market access for uncharacterized feedstock sources.
- Technical purity ceilings:Pharmaceutical-grade wegscheiderite requires sub-ppm contamination control that exceeds standard ceramic synthesis protocols, limiting supplier qualification.
Strategic Opportunities
- India's PLI scheme for advanced materials:Production-linked incentives for specialty chemicals create tariff-advantaged synthesis capacity for export to European coatings markets.
- Optical coatings convergence:AR/VR waveguide manufacturing demands orthorhombic crystal structures with precise refractive index matching, opening premium synthetic grades.
- Direct procurement platforms:Specialty ceramics buyers in Nagoya's precision corridor are bypassing distributors for long-term offtake agreements with synthesis specialists.
Industry Challenges
- Crystallization process engineering talent:Synthetic wegscheiderite production requires rare expertise in orthorhombic phase control, constraining capacity expansion timelines.
- ISO certification complexity:Multi-jurisdictional quality standards for battery electrolyte grades create 18-24 month qualification cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wegscheiderite Market |
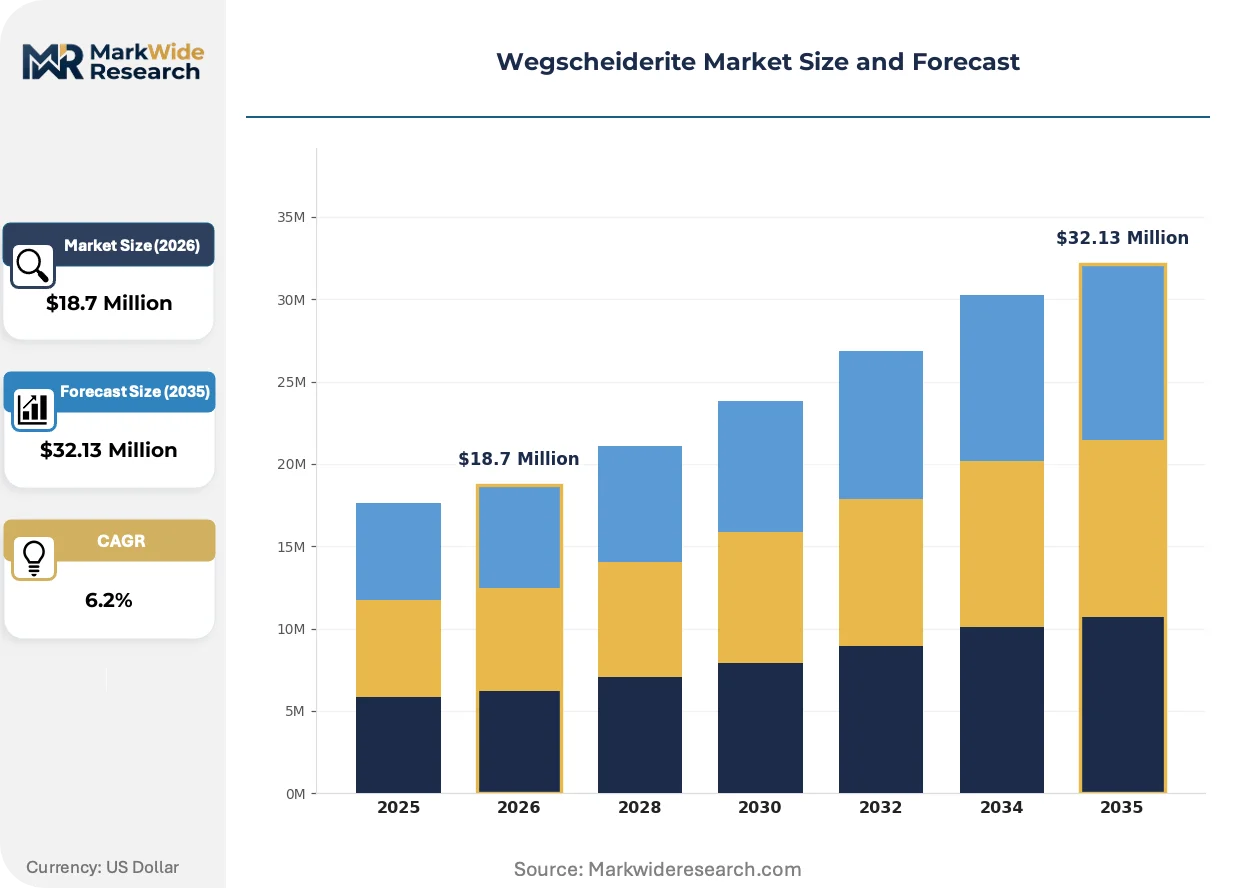
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.13 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Wegscheiderite, Synthetic Wegscheiderite, Modified Wegscheiderite, Composite Wegscheiderite Application: Optical Coatings, Nanocomposites, Ceramics, Batteries End User: Aerospace, Electronics, Automotive Components, Industrial Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | 6Wresearch, Alchem International, Ashland Global Holdings, Botanical Extracts, E. I. du Pont de Nemours, Ginkgo BioWorks, Herbalife Nutrition, Indena, Kemin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wegscheiderite Market Emerging Trajectories
Synthesis technology maturation is compressing the cost gap between natural extraction and laboratory-controlled production, while regulatory mineral security frameworks redirect capital toward domestic chemistry infrastructure.
Sol-gel synthesis routes for sub-micron wegscheiderite powders are converging with atomic layer deposition equipment capabilities, enabling conformal optical coatings on complex waveguide geometries. AR/VR headset manufacturers in Japan and South Korea are qualifying these materials for 2026 product generations. The structural consequence is a compression in acceptable particle size distributions from ceramic-grade to thin-film-grade specifications.
EU F-Gas Regulation phase-down schedules are accelerating thermal management material substitution in aerospace and electronics cooling systems. Wegscheiderite-containing ceramic composites qualify as fluorocarbon alternatives for high-temperature insulation. German specialty ceramics producers are reformulating product lines to meet 2027 compliance deadlines, pulling synthetic feedstock demand ahead of prior forecasts.
Consolidated procurement by Japan's precision ceramics corridor around Nagoya is disintermediating traditional mineral traders. Tier-one coating houses now negotiate directly with synthesis specialists for multi-year offtake agreements with fixed purity bands. This behavior shift is most visible in thermal barrier coating supply chains, where Nagoya-based manufacturers account for disproportionate synthetic grade absorption.
Wegscheiderite Market Segmentation
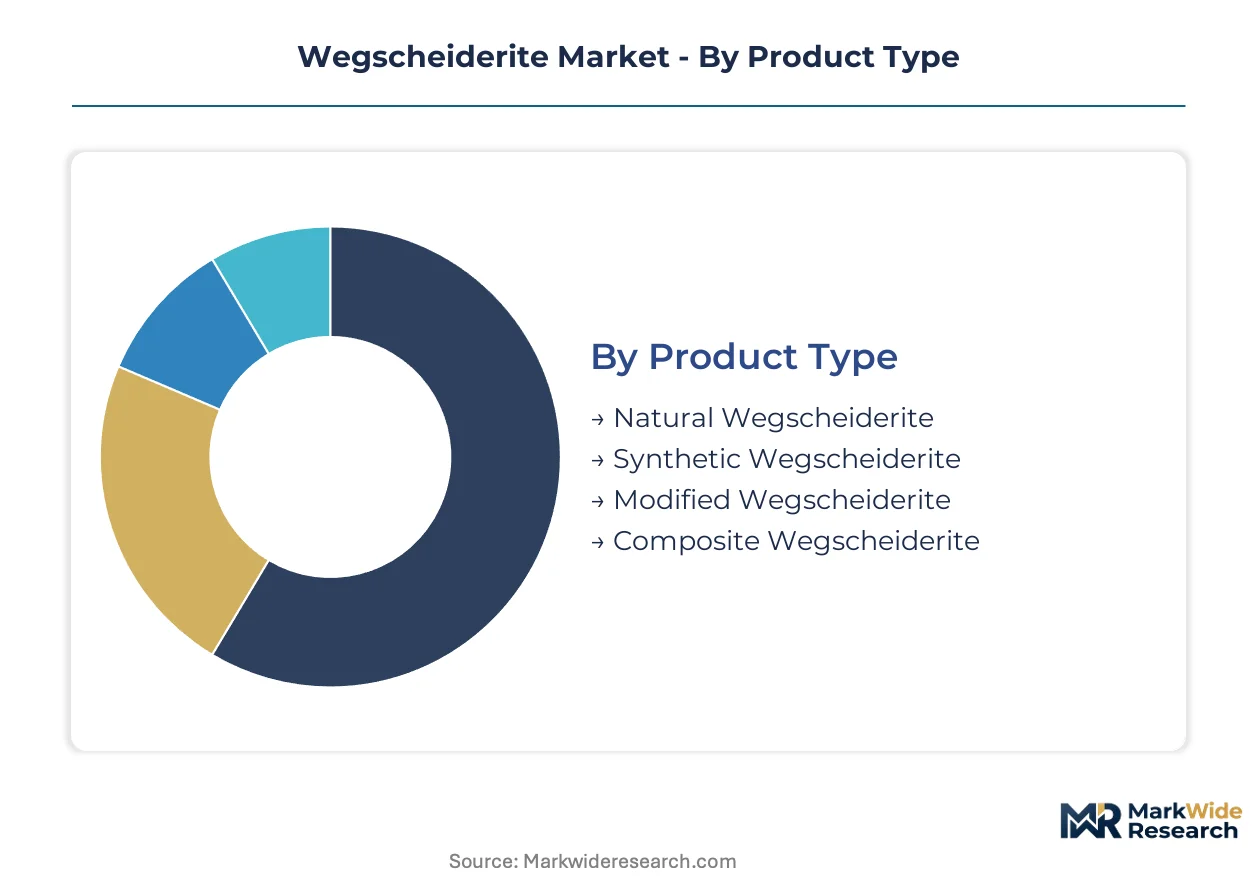
Wegscheiderite procurement splits sharply between extraction-dependent natural grades and chemistry-controlled synthetic variants. Buyers weigh stoichiometric precision against unit economics across optical, structural, and electrochemical applications.
Product Type:
Cost tier determines qualification pathways, with premium synthetic grades commanding multi-year offtake agreements while natural variants serve price-sensitive industrial formulations.
- Natural Wegscheiderite:Mined sodium carbonate mineral with inherent orthorhombic structure and trace elemental variability. German specialty ceramics manufacturers limit natural grade procurement to non-critical thermal barrier layers where stoichiometric tolerance permits geological inconsistency.
- Synthetic Wegscheiderite:Laboratory-controlled precipitation yielding exact Na₂CO₃ ratios essential for solid-state battery electrolytes. Japan's precision ceramics corridor around Nagoya absorbs the majority of high-purity synthetic output for AR/VR waveguide manufacturing.
- Modified Wegscheiderite:Polymer-composite surface treatments enhancing dispersion in ceramic matrices. Ashland Global Holdings anchors supply chains through proprietary modification protocols.
- Composite Wegscheiderite:Blended formulations with alumina or zirconia for aerospace thermal management. Kemin Industries supplies composite grades to Southeast Asian industrial manufacturers.
Synthetic Wegscheiderite leads on scale; Modified Wegscheiderite leads on momentum.
Application:
Volume concentration tracks end-use certification requirements, with optical coatings demanding sub-micron particle distributions that exclude lower-grade feedstock.
- Optical Coatings:Conformal thin-film deposition on waveguide geometries requiring atomic layer deposition compatibility. South Korean AR/VR headset manufacturers qualify sol-gel synthesized sub-micron powders for 2026 product generations.
- Nanocomposites:Structural ceramic matrices for aerospace thermal insulation displacing fluorocarbon alternatives under EU F-Gas Regulation phase-down schedules. German producers reformulate product lines to meet 2027 compliance deadlines.
- Ceramics:Traditional refractory applications absorbing standard-grade natural and composite variants. Industrial manufacturing in India leverages PLI scheme tariff advantages for export to European coatings markets.
- Batteries:Solid-state electrolyte matrices requiring pharmaceutical-grade purity with sub-ppm contamination control. ISO certification complexity creates 18-24 month qualification cycles.
Optical Coatings leads on scale; Nanocomposites expands most quickly.
End User:
Customer type dictates purity thresholds, with aerospace and electronics mandating synthetic grades while automotive and industrial sectors absorb composite formulations.
- Aerospace:Thermal barrier coating applications for high-temperature engine components. Germany and Japan dominate procurement through direct long-term agreements with synthesis specialists.
- Electronics:Precision ceramics for semiconductor thermal management and display technologies. Nagoya-based manufacturers account for disproportionate synthetic grade absorption.
- Automotive Components:Emerging demand for battery electrolyte matrices in electric vehicle platforms. Solid-state battery development favors controlled stoichiometry synthetic variants.
- Industrial Manufacturing:Broad absorption of standard ceramic and composite grades at price-sensitive specifications. China's tightened export controls redirect European buyers toward domestic synthesis capacity.
Electronics leads on scale; Aerospace climbs the fastest.
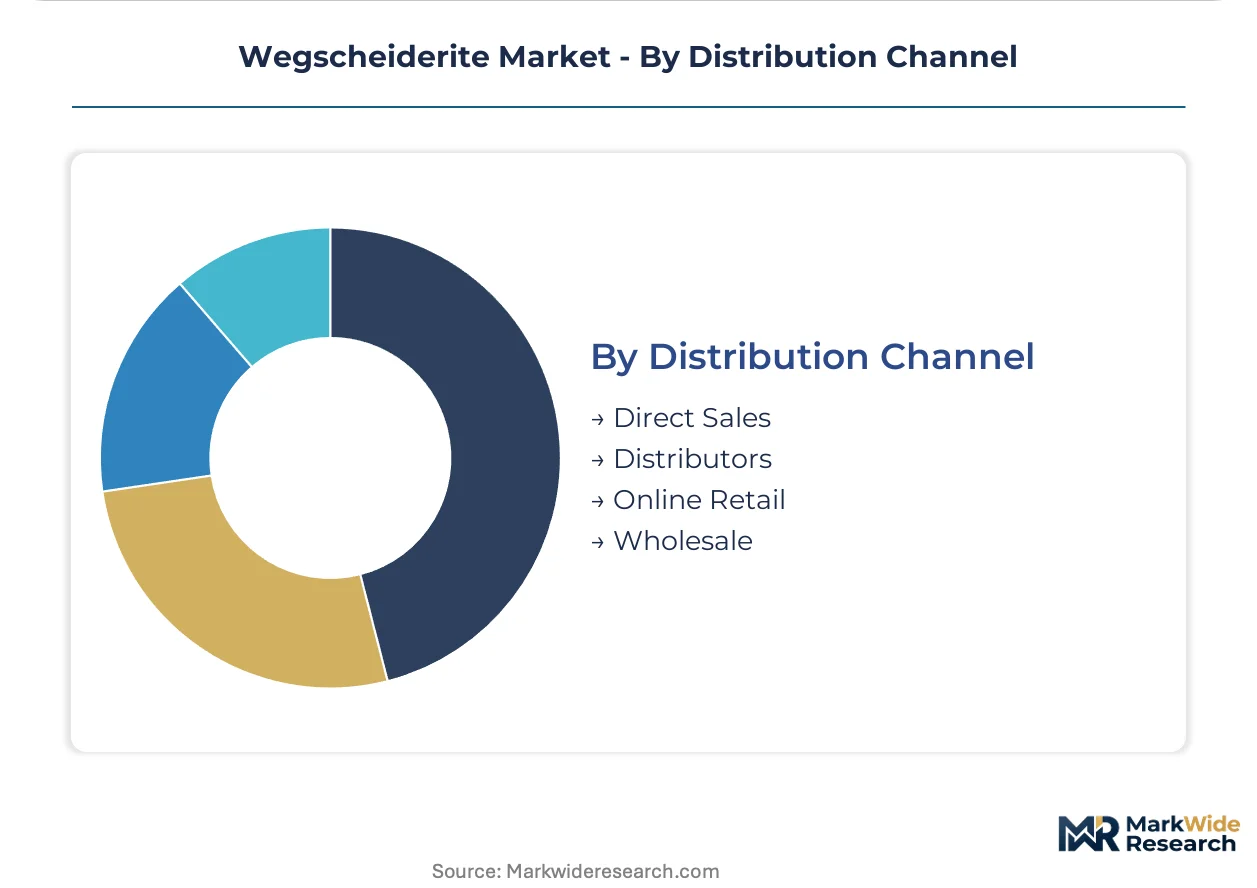
Distribution Channel:
Supply concentration reshapes channel economics, with precision ceramics buyers bypassing intermediaries for captive synthesis relationships.
- Direct Sales:Multi-year offtake agreements with fixed purity bands dominating thermal barrier coating supply chains. Tier-one coating houses negotiate directly with synthesis specialists.
- Distributors:Traditional mineral traders losing share in synthetic grade procurement as consolidated procurement disintermediates legacy channels.
- Online Retail:Limited to small-volume research-grade and pilot-scale quantities for academic and startup battery developers.
- Wholesale:Bulk natural and composite grades for industrial manufacturing in price-sensitive applications with lower certification requirements.
Direct Sales leads on scale; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagoya's precision ceramics corridor anchors global synthetic wegscheiderite procurement, pulling supply chain investment toward Japanese domestic synthesis capacity and away from Chinese mineral dependency.
Japan
METI's mineral security framework incentivizes strategic stockpiling of high-purity synthetic grades for AR/VR waveguide manufacturing. JIS standards for specialty ceramics tighten qualification protocols for battery electrolyte applications. Nagoya-based coating houses negotiate multi-year offtake agreements directly with synthesis specialists, bypassing traditional mineral traders.
Germany
EU F-Gas Regulation phase-down schedules accelerate thermal barrier coating reformulation for aerospace engine components. ECHA enforcement of REACH disclosure thresholds restricts market access for uncharacterized sodium carbonate feedstock sources. Bavarian specialty ceramics producers expand procurement of synthetic variants to meet 2027 compliance deadlines for fluorocarbon alternatives.
China
Tightened GB standards for rare mineral processing feedstocks redirect European buyers toward domestic synthesis capacity outside Chinese supply chains. MIIT dual carbon goals constrain energy-intensive soda ash purification operations. Yangtze River Delta mineral processors face export quota pressure as national stockpile policies prioritize domestic industrial manufacturing.
United States
EPA disclosure thresholds for sodium carbonate derivatives in coatings applications tighten procurement standards for aerospace thermal management materials. FAA certification requirements for high-temperature engine components favor synthetic grades with documented stoichiometric precision. California-based AR/VR hardware developers qualify sub-micron sol-gel powders for 2026 product generations.
India
PLI scheme production-linked incentives for advanced materials create tariff-advantaged synthesis capacity targeting European coatings markets. BIS quality standards for specialty chemicals align with ISO certification complexity that delays battery electrolyte grade qualification. Gujarat industrial manufacturers absorb composite formulations for price-sensitive ceramic applications.
Wegscheiderite Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue chemistry-controlled synthesis and polymer modification protocols. The vendor base stratifies across three tiers: extraction-dependent natural grade suppliers, laboratory-scale synthesis specialists, and polymer science integrators with proprietary modification capabilities. Two strategic archetypes dominate: mineral security-focused domestic synthesizers and backward-integrated specialty chemicals conglomerates. Competitive moves concentrate on multi-year offtake agreements with fixed purity bands and captive synthesis relationships that disintermediate legacy distribution channels.
Within the polymer modification tier, Ashland Global Holdings anchors supply chains through its infrastructure in specialty chemicals. Kemin Industries exemplifies the natural extraction partnership model with Southeast Asian sourcing networks. Indena occupies a position among purification protocol specialists differentiating pharmaceutical-grade output from industrial specifications.
| Leading Market Players |
|---|
| 6Wresearch |
| Alchem International |
| Ashland Global Holdings |
| Botanical Extracts |
| E. I. du Pont de Nemours |
| Ginkgo BioWorks |
| Herbalife Nutrition |
| Indena |
| Kemin Industries |
| Others |
Supply Flow & Price Mechanics
Purified industrial soda ash costs cascade through synthetic wegscheiderite production tiers, with energy-linked volatility in European and Japanese manufacturing compressing margins on standard grades while premium specifications absorb input spikes through fixed multi-year offtake structures.
Pricing Analysis
Input-cost pass-through from energy-intensive soda ash purification creates a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade synthetic variants command fixed-band contracts with Nagoya precision ceramics houses, while composite formulations for Indian industrial manufacturers track spot soda ash indices. Price differentiation hinges on ISO certification tier and volume scale, with battery electrolyte grades requiring 18-24 month qualification cycles supporting premium retention. Pricing pressure stems from Chinese export quota constraints redirecting European buyers toward higher-cost domestic synthesis, though AR/VR waveguide demand in Japan and South Korea sustains least price-sensitive absorption at the top tier.
Supply Chain Analysis
Workforce availability constraints in orthorhombic phase control engineering limit capacity expansion across German Bavarian and Japanese Nagoya manufacturing clusters. Geographic supply concentration centers on Japan, Germany, and India, with synthesis specialists drawing from purified soda ash feedstocks and rare mineral processing equipment. Raw material dependencies rest on industrial sodium carbonate, atomic layer deposition precursors, and polymer modification agents. Single-source vulnerability in Chinese rare mineral processing feedstocks is accelerating. Distribution runs through direct long-term offtake agreements disintermediating traditional mineral traders, particularly for thermal barrier coating supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as AR/VR waveguide manufacturing pulls procurement toward sub-micron synthetic grades with exacting refractive index specifications.
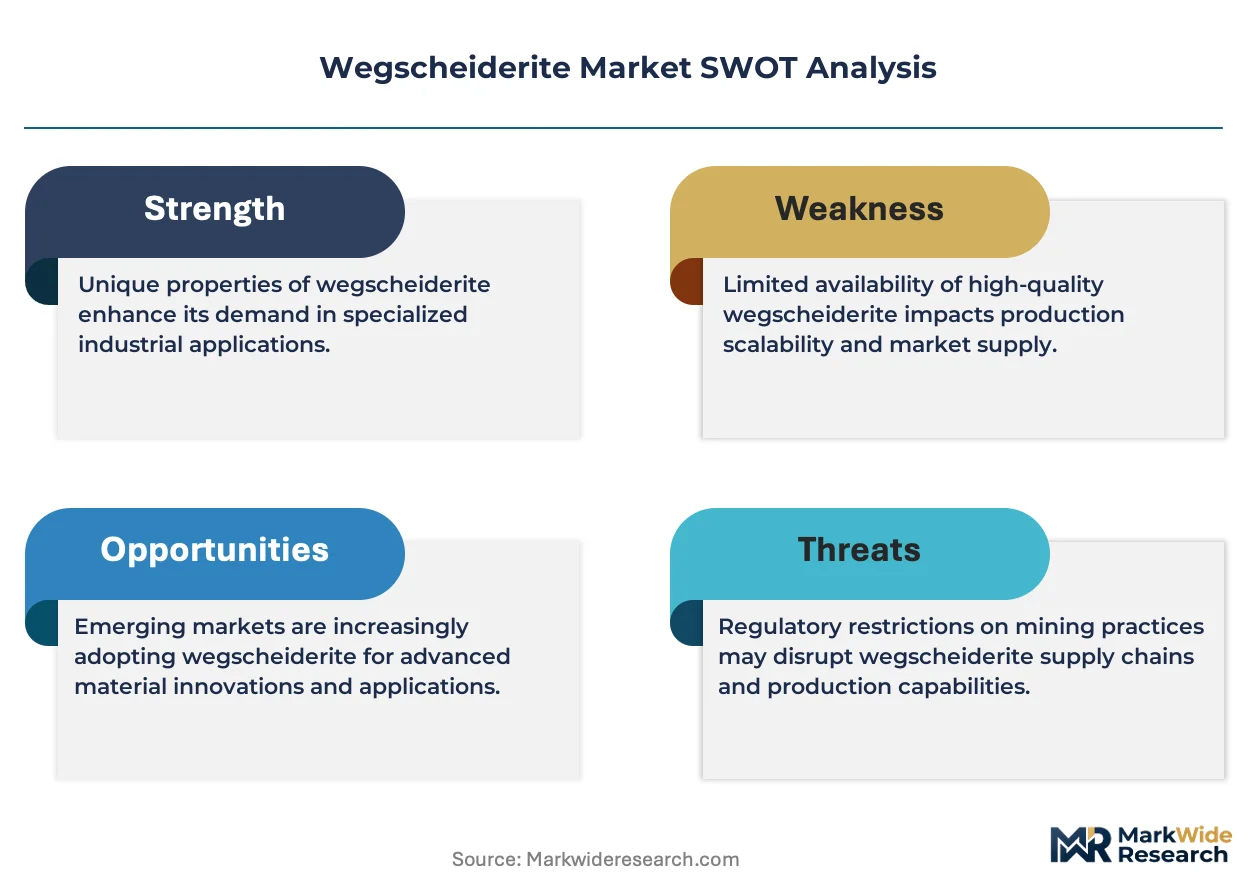
For Market Incumbents: Anticipate margin compression in standard ceramic grades as Indian PLI-subsidized synthesis capacity floods European industrial markets. Defensive consolidation through captive synthesis relationships with Nagoya coating houses locks in volume commitment. Certification investment in ISO battery electrolyte tiers creates 18-24 month switching costs against emerging entrants. Backward integration into soda ash purification secures input cost control against energy volatility. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade synthetic and natural extraction grades offers white-space targeting for modified composite formulations. Southeast Asian industrial ceramics manufacturers present the most penetrable geography, with tariff-advantaged Indian synthesis capacity enabling competitive export positioning. Sol-gel synthesis specialization for sub-micron powders serves as the primary go-to-market angle, qualifying for 2026 AR/VR product generations in South Korea. For Investors and Strategic Acquirers: Consolidation pressure builds where synthesis patent portfolios overlap with mineral security stockpile mandates. Long-term viability favors laboratory-scale specialists with orthorhombic phase control expertise over extraction-dependent natural grade suppliers. Acquisition target archetypes include polymer modification protocol holders and atomic layer deposition equipment-integrated synthesis shops. Practitioners should monitor JIS and GB standard harmonization progress as inflection signals for cross-border qualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash Purification | Ashland Global Holdings secures energy-cost insulation against volatile European gas pricing. |
| Long-term Supply Agreement with Nagoya Coating Houses | Direct offtake structures disintermediate legacy mineral traders and fix purity bands. |
| Capacity Expansion in Gujarat Under PLI Scheme | Tariff-advantaged synthesis targets European thermal barrier coating reformulation demand. |
| Joint Venture for Sol-gel Synthesis Equipment | AR/VR waveguide manufacturers in South Korea qualify sub-micron powders for conformal deposition. |
| Green Manufacturing Transition for F-Gas Compliance | German aerospace suppliers meet 2027 EU deadlines with fluorocarbon-alternative ceramic composites. |
Methodological Framework
Coverage spans Japan, Germany, China, India, and the United States, with primary inputs from each regional cluster combining interviews with synthesis plant managers, precision ceramics procurement leads at Nagoya coating houses, specialty chemicals distribution channel partners, and technical R&D directors in battery electrolyte development. Secondary validation draws from customs and trade data, METI mineral security policy filings, ECHA REACH disclosure registries, and SEC 10-K specialty chemicals segment disclosures. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic and regulatory scenario analysis.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions include product grade tier, application category, end-use industry concentration, and regional regulatory framework cluster. CAGRs derive from weighted capacity expansion timelines, qualification cycle duration assumptions, and substitution elasticity estimates for fluorocarbon alternatives in thermal management. Industry-specific forecast inputs incorporate METI stockpile policy implementation pace and EU F-Gas Regulation enforcement schedules.
Caveats apply where Chinese export quota expansion or relaxation could materially shift the outlook for European and Japanese synthesis investment. Forecasts reflect assumptions regarding orthorhombic phase control engineering talent availability and sol-gel equipment utilization rates. Practitioners should monitor GB standards harmonization with REACH disclosure thresholds and patent filing velocity in atomic layer deposition compatibility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Bauxite Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Global Ferrous Scrap Recycling Market