
 Tantalum Pentoxide Market | 2026-2036
Tantalum Pentoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Tantalum Pentoxide Market Analytics
Modular supply contracts for tantalum pentoxide are realigning how capacitor manufacturers source material across purity tiers. Global Advanced Metals leverages captive mine-to-oxide refining to sustain long-term supply security for aerospace clients. Jiujiang Tanbre anchors Chinese domestic demand through integrated tantalum concentrate processing. Materion differentiates via specialty optical-grade production for defense and semiconductor lithography applications.
Tantalum pentoxide is a high-refractory oxide of tantalum with a melting point near 1872°C, produced primarily through chlorination of tantalum-containing ores followed by hydrolysis or direct oxidation of tantalum metal; it functions as a critical dielectric material in electrolytic capacitors and as a coating precursor for corrosion-resistant and optical thin-film applications. Semiconductor-grade material commands premium positioning due to stringent trace-metal specifications required for sub-7nm node manufacturing, while industrial-grade supply competes primarily on volume scale and logistics reliability. Capacitor applications retain the largest demand share, though thin-film deposition for optical components represents the fastest-expanding consumption segment as extreme ultraviolet lithography systems proliferate.
FDA medical-device material standards, EU REACH conflict-mineral disclosure rules, and China's GB environmental compliance protocols collectively elevate documentation and purity requirements for market participation. These frameworks compel producers to maintain dual-certified production streams and blockchain-traceable supply chains. Stakeholders must monitor evolving semiconductor export controls and rare-element national stockpiling policies that could abruptly reroute qualified supply.
Market Dynamics
Semiconductor-grade purity specifications are compressing qualified supplier pools as sub-7nm node manufacturing spreads through East Asian wafer fabrication facilities. This technical escalation is forcing capacitor manufacturers to requalify material streams against tightening trace-metal thresholds.
Growth Catalysts
- Extreme ultraviolet lithography expansion:EUV system deployment for sub-5nm chip production is consuming specialty optical-grade tantalum pentoxide for mirror coatings at accelerating rates.
- China's dual carbon goals:Domestic environmental compliance protocols under MEE are consolidating refining capacity toward integrated producers with captive hydrometallurgical circuits.
- REACH Article 33:EU conflict-mineral disclosure mandates are redirecting procurement toward blockchain-traceable supply chains, advantaging qualified oxide refiners with verified mine-to-smelter documentation.
Market Restraints
- Tantalite concentrate oligopoly:Primary ore sourcing concentrates in African artisanal and small-scale mining corridors, exposing processors to supply interruption and price volatility.
- Niobium substitution in high-voltage capacitors:Polymer niobium oxide capacitors are capturing niche applications previously served by tantalum-based components in automotive power electronics.
- Chlorination route energy intensity:Conventional tantalum pentoxide production via TaCl5 hydrolysis requires sustained high-temperature processing, elevating carbon exposure under tightening EU ETS benchmarks.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic semiconductor packaging incentives under MeitY are seeding captive tantalum capacitor demand as fabrication clusters emerge near Gujarat and Tamil Nadu.
- Thin-film battery solid electrolytes:Lithium-tantalum oxide formulations for next-generation solid-state cells represent unpenetrated consumption vectors outside traditional dielectric applications.
- Direct shipping ore-to-oxide models:Bypassing intermediate concentrate trading through integrated mine-refinery logistics is compressing working capital cycles for qualified suppliers.
Industry Challenges
- Semiconductor-grade certification timelines:Qualification protocols for sub-7nm node material require 18-24 month validation cycles against JEDEC standards, freezing supplier switching.
- Hydrometallurgical talent scarcity:Specialized expertise in tantalum-niobium separation chemistry is concentrating among retiring cohorts at legacy European and Japanese refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tantalum Pentoxide Market |
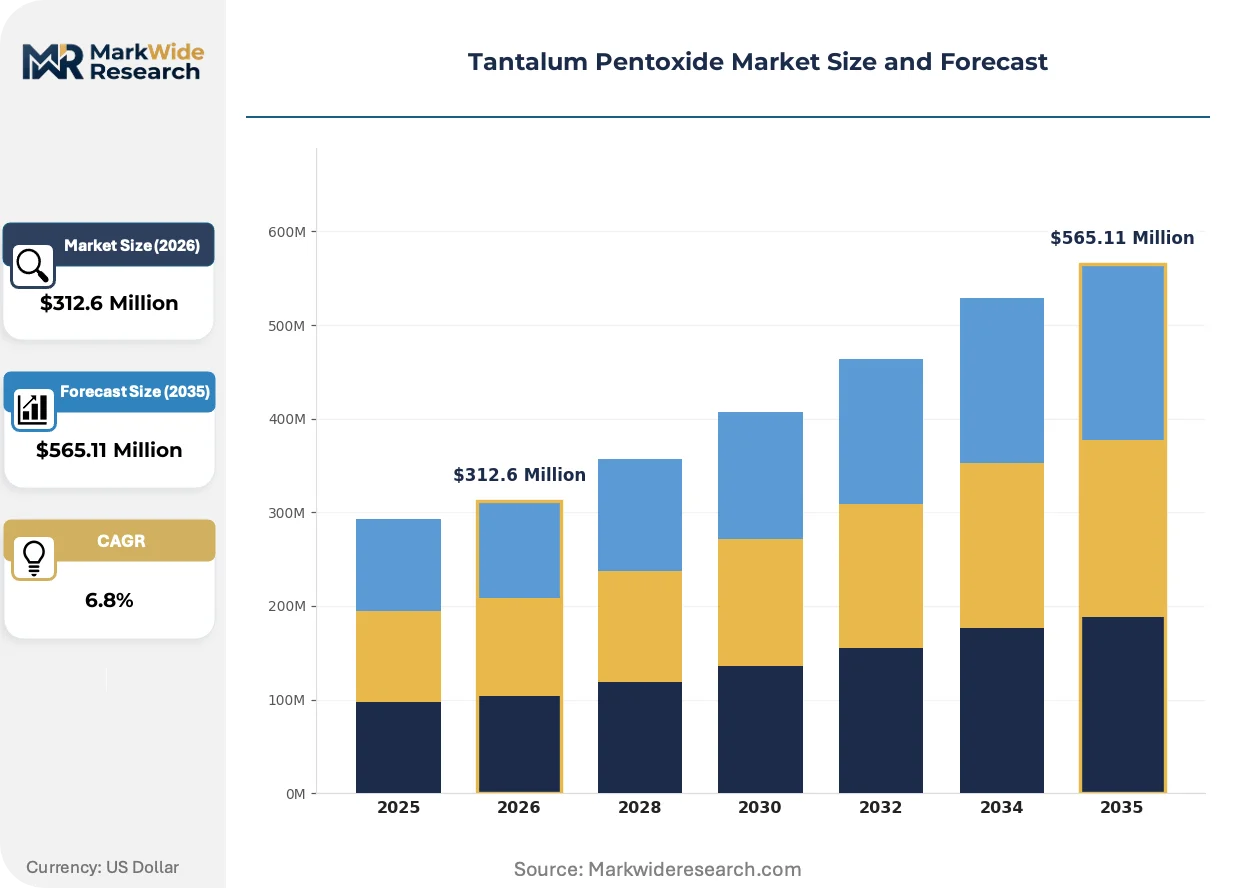
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Industrial Grade, Semiconductor Grade, Optical Grade Application: Capacitors, Coatings, Optical Components, Thin Films End User: Electronics, Aerospace, Defense, Manufacturing Form: Powder, Pellets, Wafers, Films |
| Companies Covered | Mitsui Kinzoku, KING-TAN Tantalum, Global Advanced Metals, Admat Inc, F&X Electro-Materials, AMG, Jiujiang Tanbre, MPIL, Materion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tantalum Pentoxide Market Evolving Landscape
Process intensification and digital traceability are converging to redefine how tantalum pentoxide moves from ore body to dielectric layer. These shifts are compressing traditional value chain configurations while elevating documentation burdens.
Advanced chlorination-cum-hydrolysis circuits with real-time impurity monitoring are modularizing how refiners toggle between semiconductor-grade and optical-grade output streams. Japanese capacitor manufacturers are adopting these flexible configurations to reduce inventory carrying costs across purity tiers. This process architecture is modularizing the traditional separation between specialty and industrial oxide production, enabling single-site supply of multiple certification grades.
EU REACH Annex XVII restrictions on persistent organic pollutants are extending reporting obligations to tantalum supply chains with secondary organic contamination risk. Refiners must now document solvent recovery rates and waste-stream treatment protocols to maintain market access. Aerospace coating applications in France and Germany are experiencing the steepest compliance cost escalation as ECHA enforcement tightens.
Long-term offtake contracting is displacing spot-market purchasing among tier-one capacitor manufacturers seeking supply security amid concentrate volatility. Korean electronics conglomerates are pioneering five-year fixed-volume agreements with price reopener clauses indexed to tantalite concentrate benchmarks. This behavioral shift is most pronounced in procurement departments serving smartphone and automotive module production lines.
Tantalum Pentoxide Market Segmentation
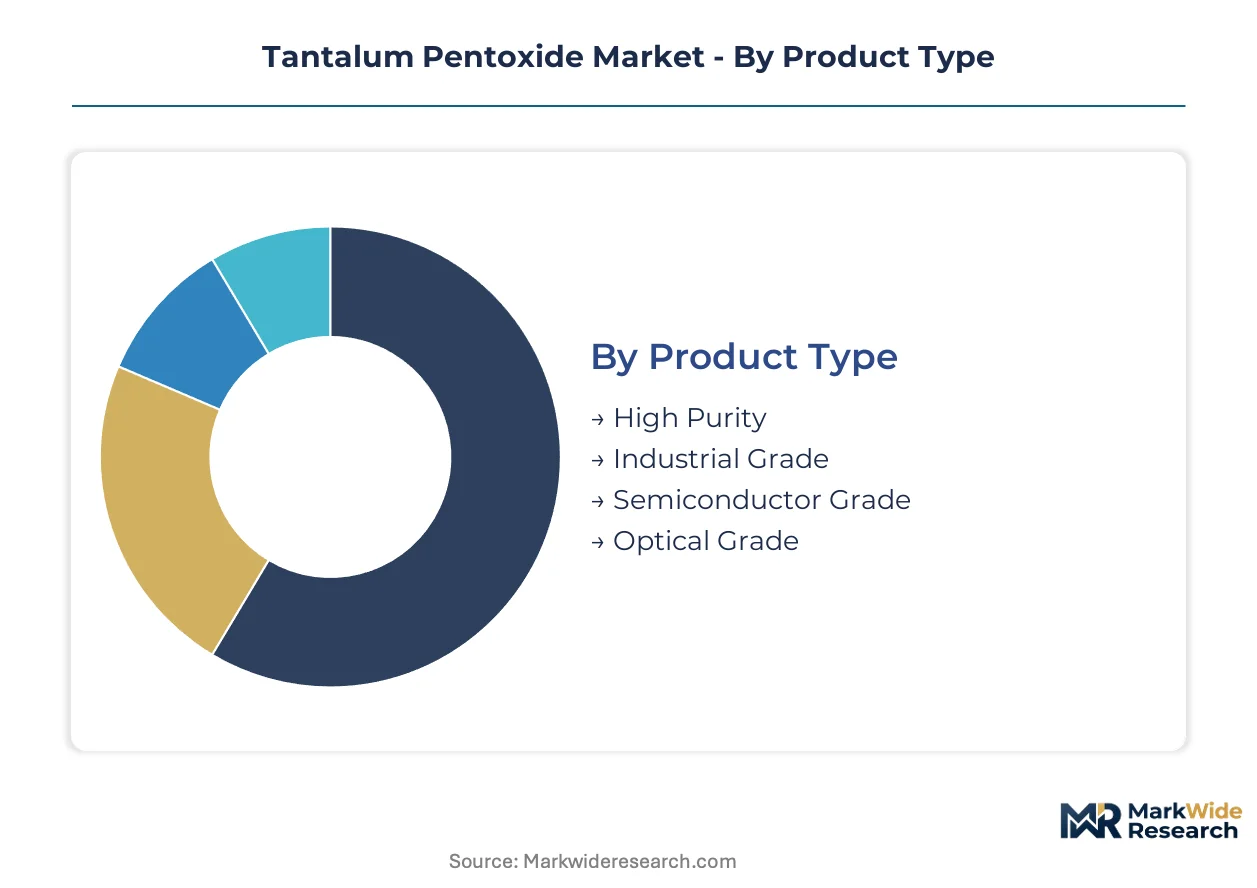
Purity thresholds and form-factor specifications determine pricing power and customer lock-in across tantalum pentoxide supply tiers. Buyers requalify material streams against application-specific trace-metal limits, creating segmented procurement protocols that resist cross-tier substitution.
Product Type:
Certification grade dictates contract duration, with semiconductor and optical tiers commanding multi-year offtake agreements against JEDEC and MIL-STD validation.
- Semiconductor Grade:Material meeting sub-7nm node specifications with total metallic impurities below 10 ppm. Wafer fabrication facilities in Taiwan and South Korea anchor procurement volume as EUV lithography deployment accelerates.
- Optical Grade:Oxide engineered for extreme ultraviolet mirror coatings with controlled oxygen stoichiometry and surface roughness below 0.5 nm RMS. Lithography system manufacturers in Japan and the Netherlands drive qualification cycles for this tier.
- High Purity:General electronic-grade material for premium capacitor applications requiring controlled niobium and tungsten levels.
- Industrial Grade:Volume oxide for corrosion-resistant coatings and conventional ceramic applications where trace-metal specifications are less stringent.
Semiconductor Grade leads on scale; Optical Grade leads on momentum.
Application:
End-use technology maturity separates established dielectric demand from emerging thin-film consumption vectors.
- Capacitors:Electrolytic and polymer tantalum capacitors consume the largest purity-tiered volume, with smartphone and automotive module manufacturers specifying JEDEC-compliant material for surface-mount components.
- Thin Films:Physical vapor deposition and atomic layer deposition processes for semiconductor tooling and solid-state battery research represent the steepest expansion trajectory as solid electrolyte formulations advance.
- Coatings:Corrosion-resistant layers for chemical processing equipment and aerospace turbine blades, qualified against AMS specifications.
- Optical Components:EUV mirror substrates and infrared optical elements requiring nanoscale thickness control.
Capacitors retains volume leadership; Thin Films gains share fastest.
End User:
Defense and aerospace procurement protocols impose documentation burdens that filter supplier pools differently than commercial electronics purchasing.
- Electronics:Capacitor manufacturers and semiconductor fabricators in Japan, South Korea, and China concentrate demand through consolidated procurement functions.
- Defense:National security applications in the United States and European NATO members require DFARS-compliant conflict-mineral tracing and ITAR-controlled distribution.
- Aerospace:Turbine coating and thermal protection system suppliers qualify material against SAE AMS specifications with extended batch retention requirements.
- Manufacturing:Industrial ceramic and chemical equipment producers purchasing on spot-market terms with shorter qualification cycles.
Electronics dominates absolute consumption; Defense tightens sourcing standards most aggressively.
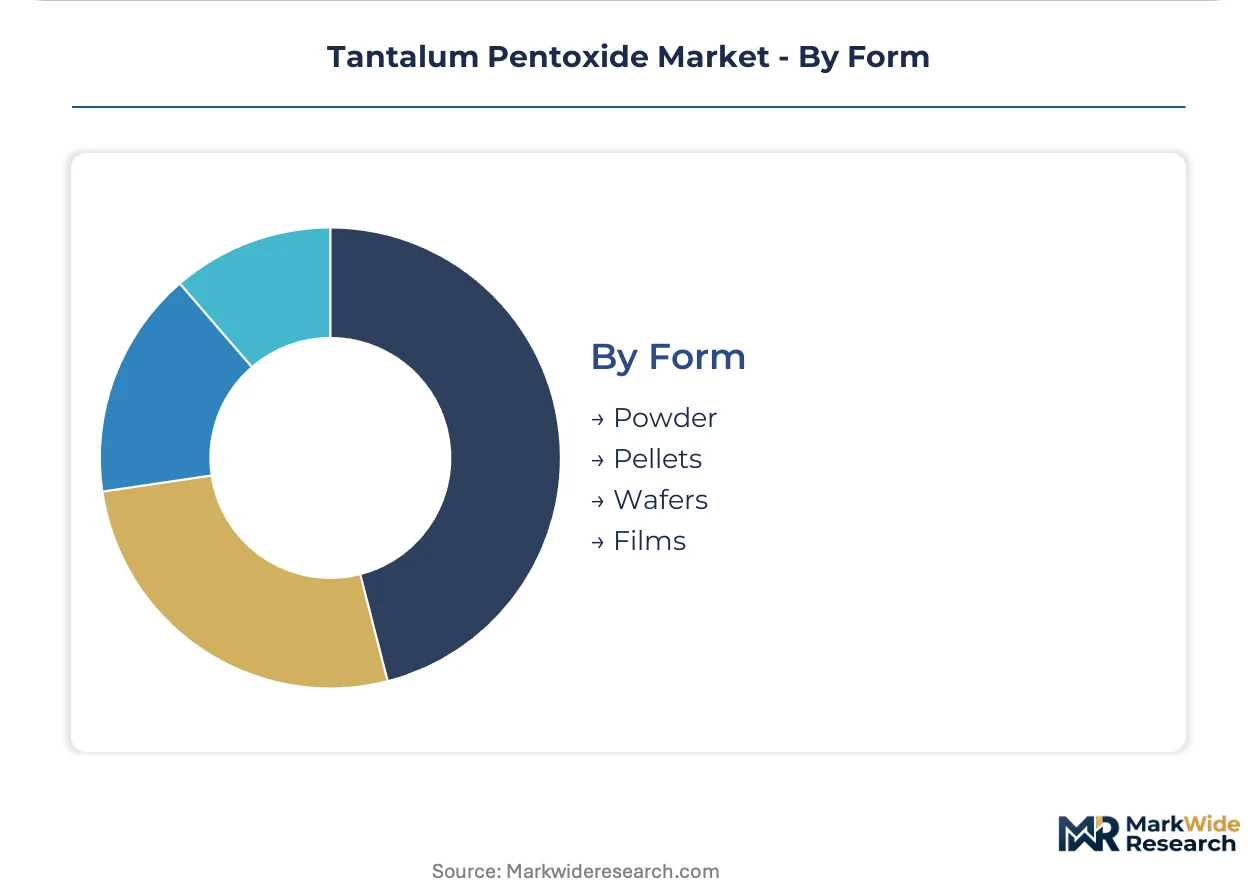
Form:
Processing stage determines logistics economics and customer in-house conversion capabilities.
- Powder:Primary refined oxide for capacitor sintering and ceramic pressing, shipped in controlled-atmosphere containers to prevent moisture uptake.
- Pellets:Pre-pressed feedstock for electron-beam evaporation and sputtering targets, reducing customer handling and contamination risk.
- Wafers:Monocrystalline or polycrystalline substrates for semiconductor research and specialty optical applications.
- Films:Pre-deposited layers on carrier substrates for transfer processes in MEMS and micro-optics fabrication.
Powder leads on shipment volume; Pellets tightest supply concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tantalum pentoxide refining originated in German and Japanese industrial laboratories during the mid-20th century, establishing quality benchmarks that persist in today's semiconductor-grade specifications. Production now clusters near electronics manufacturing corridors and captive ore processing facilities.
China
Domestic wafer fabrication expansion in Shanghai and Hefei is absorbing record volumes of semiconductor-grade oxide. MEE environmental compliance protocols are consolidating refining capacity toward integrated producers with captive hydrometallurgical circuits. Jiujiang anchors concentrate processing in Jiangxi province, feeding oxide to capacitor manufacturers in the Yangtze River Delta.
Japan
EUV lithography system deployment by Nikon and Canon is driving qualification cycles for optical-grade material with sub-nanometer surface roughness. METI semiconductor subsidies are reinforcing domestic supply chain security for critical dielectric materials. Osaka-Kobe industrial corridor hosts the densest concentration of qualified capacitor manufacturers specifying JEDEC-compliant feedstock.
United States
Defense and aerospace coating applications in California and Texas require DFARS-compliant conflict-mineral tracing with extended batch retention. FDA medical-device material standards elevate documentation burdens for implantable capacitor components. Boston-area semiconductor research clusters are piloting thin-film deposition for solid-state battery electrolytes.
Germany
ECHA REACH Annex XVII enforcement is extending reporting obligations to solvent recovery rates in oxide refining. Aerospace turbine coating suppliers in Bavaria and Baden-Württemberg qualify material against AMS specifications with ITAR-controlled distribution protocols. Frankfurt-Rhine-Main logistics corridor handles EU import consolidation for qualified oxide streams.
South Korea
Samsung and SK Hynix wafer fabrication in Pyeongtaek and Icheon is compressing qualified supplier pools for sub-7nm node material. Korean electronics conglomerates are pioneering five-year fixed-volume offtake agreements with price reopener clauses. Seoul Capital Area procurement departments are displacing spot-market purchasing for smartphone module production lines.
Tantalum Pentoxide Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade tiers, with semiconductor and optical specifications commanding multi-year contract premiums. The supplier base concentrates around integrated mine-to-oxide refiners, captive processors serving domestic electronics clusters, and specialty optical-grade specialists. Three archetypes dominate: African ore-integrated refiners with blockchain traceability, Asia-Pacific electronics-captive processors, and defense-aerospace qualification holders. Competitive moves center on backward integration into concentrate sourcing and modular process intensification enabling grade-switching flexibility.
Among Asia-Pacific fabricators, Mitsui Kinzoku and Jiujiang Tanbre exemplify the electronics-captive processor archetype, while Global Advanced Metals occupies a position representing African ore-integrated refining with verified mine-to-smelter documentation. Materion sits within the specialty optical-grade tier serving lithography and defense applications. These named entities anchor industry-level commentary without implying specific strategic actions or market positions beyond their evident geographic and structural positioning.
| Leading Market Players |
|---|
| Mitsui Kinzoku |
| KING-TAN Tantalum |
| Global Advanced Metals |
| Admat Inc |
| F&X Electro-Materials |
| AMG |
| Jiujiang Tanbre |
| MPIL |
| Materion |
| Others |
Value Network & Pricing Analysis
Semiconductor-optical grade bifurcation creates divergent value capture mechanisms across tantalum pentoxide supply tiers, with JEDEC-certified material commanding multi-year contract premiums while industrial-grade supply competes on spot-market logistics efficiency. This tier divergence manifests in procurement protocols: capacitor manufacturers in South Korea and Japan lock in five-year offtake agreements for sub-7nm node material, while coating applicators in Germany purchase industrial oxide on quarterly volume schedules indexed to tantalite concentrate benchmarks.
Pricing Analysis
Long-term fixed-volume contracting with price reopener clauses anchors pricing architecture across purity tiers, separating semiconductor-grade premiums from industrial-grade commodity exposure. Price differentiation rests on certification grade against JEDEC and MIL-STD specifications, plus volume scale commitments from tier-one capacitor manufacturers. Cost compression in industrial-grade supply is intensifying because MEE environmental compliance in China is consolidating refining capacity toward integrated producers with captive hydrometallurgical circuits. Electronics procurement departments serving smartphone module production lines exhibit lowest price sensitivity due to dielectric material's small share of bill-of-materials cost.
Supply Chain Analysis
Scrap tantalum capacitor recovery and spent sputtering target refurbishment create secondary material flows that supplement primary ore-derived supply in Japan and Germany. Geographic concentration centers on China, Japan, and South Korea for oxide refining capacity, with raw material dependencies drawing from tantalite concentrate corridors in Rwanda and the Democratic Republic of Congo. Single-source vulnerability runs through African artisanal and small-scale mining exposure, where supply interruption risks propagate through concentrate trading networks. Distribution runs through controlled-atmosphere container logistics for powder shipments and direct mill-to-fab agreements for pellet and wafer form factors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
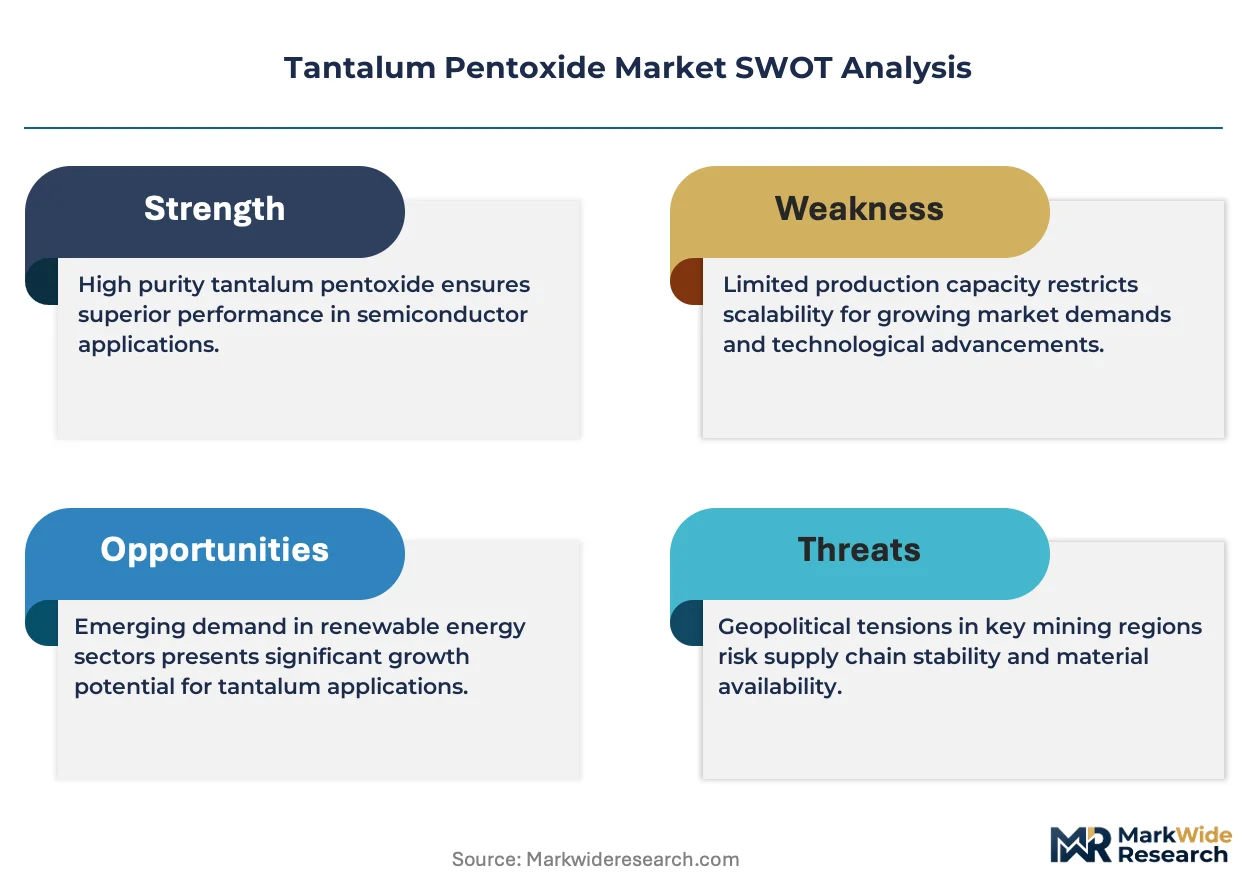
Tantalum pentoxide functions as a stable compounder anchored by irreplaceable dielectric performance in sub-7nm semiconductor nodes and EUV lithography mirror coatings. Long-term demand visibility stems from wafer fabrication capacity expansion in East Asia that outpaces niobium substitution in all but niche high-voltage automotive applications.
For Market Incumbents: Deepen backward integration into blockchain-traceable tantalite concentrate sourcing to defend against REACH Article 33 compliance disruption and African supply corridor volatility. Prioritize modular chlorination-cum-hydrolysis circuit investments that enable rapid grade-switching between semiconductor and optical output streams, reducing inventory carrying costs across purity tiers while maintaining JEDEC certification continuity.
For New Entrants and Emerging Players: Capture thin-film battery solid electrolyte applications for lithium-tantalum oxide formulations, an unpenetrated consumption vector outside traditional dielectric demand. India's PLI scheme for electronics under MeitY seeds captive capacitor demand near Gujarat fabrication clusters, offering qualification entry points before Korean and Japanese procurement departments consolidate supplier pools. Pursue direct shipping ore-to-oxide models that bypass intermediate concentrate trading to compress working capital cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where hydrometallurgical talent scarcity concentrates among retiring cohorts at legacy European and Japanese refiners. Long-term viability favors integrated mine-to-oxide operators with verified conflict-mineral documentation and dual-certified production streams serving both commercial electronics and DFARS-compliant defense applications. Monitor EU ETS carbon pricing escalation and semiconductor export control expansion as inflection indicators for qualified supply rerouting.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Sourcing | Blockchain-traceable mine-to-smelter documentation satisfies REACH Article 33 and DFARS conflict-mineral mandates. |
| Modular Grade-Switching Circuit Deployment | Real-time impurity monitoring enables single-site supply of JEDEC semiconductor and optical-grade output streams. |
| Long-term Offtake Agreement Structuring | Five-year fixed-volume contracts with Korean electronics conglomerates displace spot-market purchasing volatility. |
| Thin-film Battery Electrolyte R&D Partnership | Lithium-tantalum oxide formulations for solid-state cells open consumption vectors beyond capacitor dielectrics. |
| India PLI Scheme Localization | Domestic semiconductor packaging incentives under MeitY seed captive demand near Gujarat fabrication clusters. |
Research Methodology
Bottom-up capacitor and thin-film deposition modeling reconciled against top-down tantalite concentrate trade flow tracking forms the analytical core of this study. Primary interviews with capacitor procurement directors, hydrometallurgical plant managers, semiconductor fabrication material engineers, and EUV lithography system coating specialists combined with secondary validation from SEC filings, customs and trade databases, JEDEC certification registries, and ECHA REACH submission records. Triangulation across these sources calibrated purity-tier demand splits and regional refining capacity utilization.
Historical trendline analysis of semiconductor-grade oxide pricing against tantalite concentrate benchmarks established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated certification grade, application end-use, form factor, and regional electronics manufacturing cluster dimensions. CAGRs derived from fitted trend extrapolation adjusted for MEE environmental compliance consolidation effects and EUV lithography deployment rates. Forecast inputs included wafer fabrication capacity buildout schedules and solid-state battery research funding flows.
Underlying measurement precision varies by segment; semiconductor and optical-grade volumes carry tighter precision than industrial-grade spot-market flows due to longer contract visibility and qualification documentation. Forecasts incorporate assumptions regarding tantalite concentrate supply continuity and REACH enforcement intensity that could revise trajectory if African mining corridor disruption escalates or ECHA extends Annex XVII reporting obligations. Practitioners should monitor EU ETS carbon pricing thresholds and rare-element national stockpiling policy announcements for early signals of qualified supply rerouting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Diamond Market
Metals & Minerals
Selenium Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Global Boron Market
Metals & Minerals
Laminated Steel Market