
 Global Carbonate Minerals Market | 2026-2036
Global Carbonate Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbonate Minerals Market Foresight
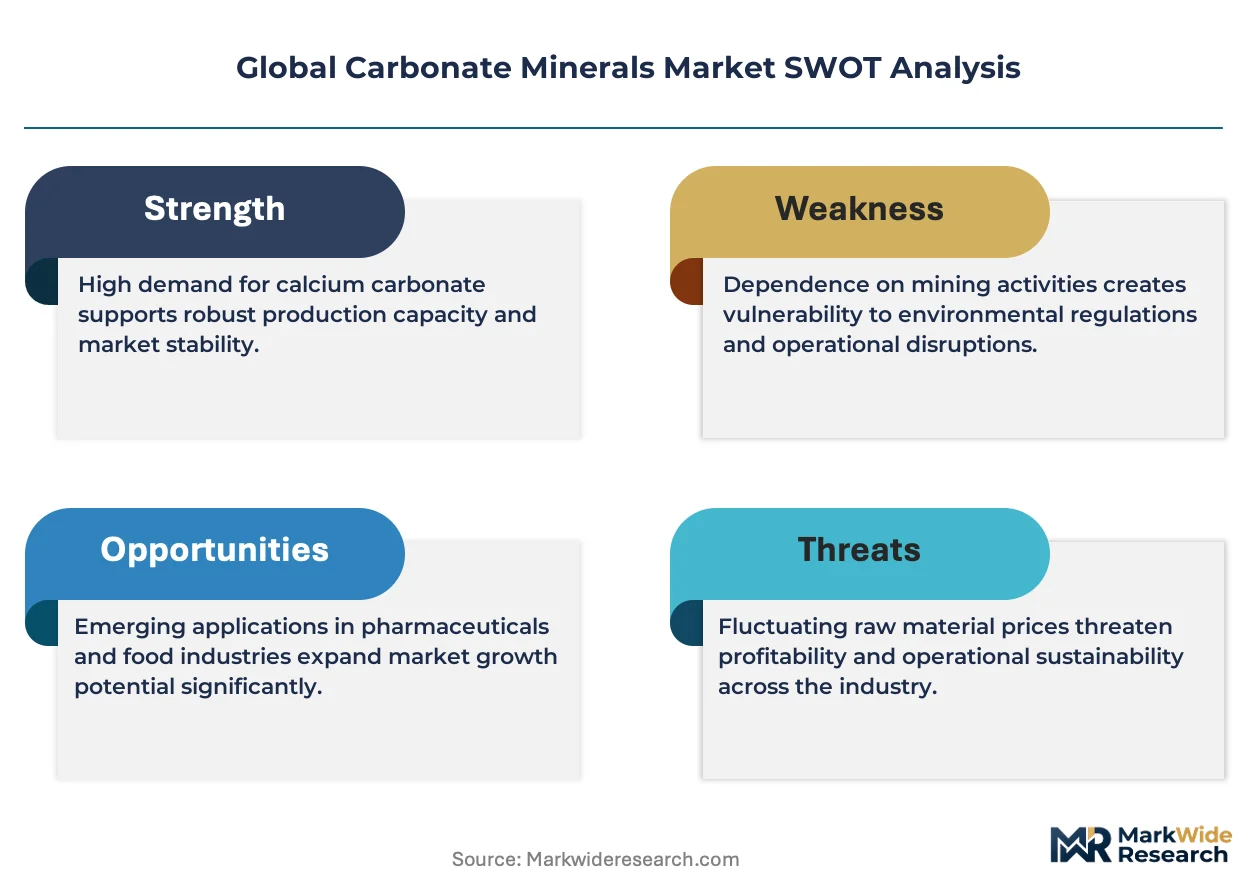
China is reconfiguring supply dynamics through expanded high-purity calcium carbonate capacity serving paper and plastics manufacturers. Omya leverages its global micronization network to sustain premium positioning in coated grades for paints and coatings. Imerys anchors European supply through vertically integrated quarry-to-delivery operations in France and Belgium. Carmeuse competes on scale in steel-flux dolomite while extending its carbon capture integration roadmap.
Carbonate minerals comprise naturally occurring or synthetically processed compounds containing the carbonate anion, with calcium carbonate typically exceeding 98% purity in food-grade and pharmaceutical specifications through controlled precipitation or beneficiation of limestone and marble deposits. These minerals function primarily as functional fillers, pH modifiers, fluxing agents, and dietary supplements across industrial and consumer applications. Calcium carbonate dominates volume flows into paper industry applications where precipitated variants deliver opacity and brightness control, while magnesium carbonate captures expanding share in pharmaceuticals and food processing units where low-heavy-metal specifications command margin premiums. Dolomite maintains steady demand from construction firms and steel producers, though growth rates trail micronized and coated specialty forms.
EPA effluent guidelines in the United States limit quarry runoff and processing discharge, compelling investment in closed-loop water systems at extraction sites. REACH registration requirements in Europe mandate full toxicological dossiers for imported carbonate feedstocks, raising compliance costs for non-EU suppliers. China's MEE enforces stricter particulate emissions standards at calcination facilities, accelerating kiln technology replacement cycles. Stakeholders must monitor how tightening carbon border adjustments and evolving product carbon footprint protocols reshape competitive access across major demand centers.
Market Dynamics
China's state-directed infrastructure investment is absorbing unprecedented volumes of calcium carbonate, compressing export availability and forcing European and North American buyers to secure alternative supply chains through longer-term offtake agreements.
Growth Catalysts
- EU Green Deal decarbonization mandates:Manufacturers are retrofitting calcination kilns with carbon capture integration to meet emission reduction targets, creating demand for processed dolomite in steel flux applications.
- Food-grade precipitated calcium carbonate:Pharmaceutical and nutraceutical formulators are expanding specification requirements for low-heavy-metal variants, pulling volume into higher-margin purification processes.
- Micronization technology diffusion:Paper mills in Indonesia and Vietnam are installing on-site grinding capacity to reduce coating raw material costs, accelerating regional beneficiation infrastructure buildout.
Market Restraints
- Energy cost volatility:Natural gas and electricity account for 35-45% of calcination operating expenses, exposing margins to European and Asian spot price spikes.
- Quarry permitting delays:EPA effluent guidelines in the United States and MEE particulate standards in China are extending greenfield extraction approval timelines by 18-36 months.
- Ground calcium carbonate substitution:Precipitated variants and engineered silicates are capturing brightness-critical paper applications, eroding commodity limestone market share.
Strategic Opportunities
- Brazilian pharmaceutical excipient market:ANVISA registration pathways for imported mineral feedstocks remain underdeveloped, creating first-mover advantage for compliant suppliers.
- Carbon capture utilization in construction:Mineral carbonation processes are enabling synthetic calcium carbonate production from industrial CO2 streams, qualifying for EU carbon border adjustment credits.
- Direct-to-mill distribution platforms:Digital procurement networks are bypassing traditional mineral traders in Southeast Asia, compressing working capital cycles for integrated producers.
Industry Challenges
- Process engineer scarcity:Wet grinding and surface coating expertise is concentrated among retiring specialists in Belgium and northern Italy, constraining capacity expansion timelines.
- REACH dossier compilation:Full toxicological registration for novel carbonate grades requires 24-36 month timelines and seven-figure documentation investments, freezing product pipeline velocity.
- Kiln technology integration:Retrofitting vertical shaft furnaces with oxy-fuel combustion systems demands simultaneous control system overhaul, disrupting production continuity during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbonate Minerals Market |
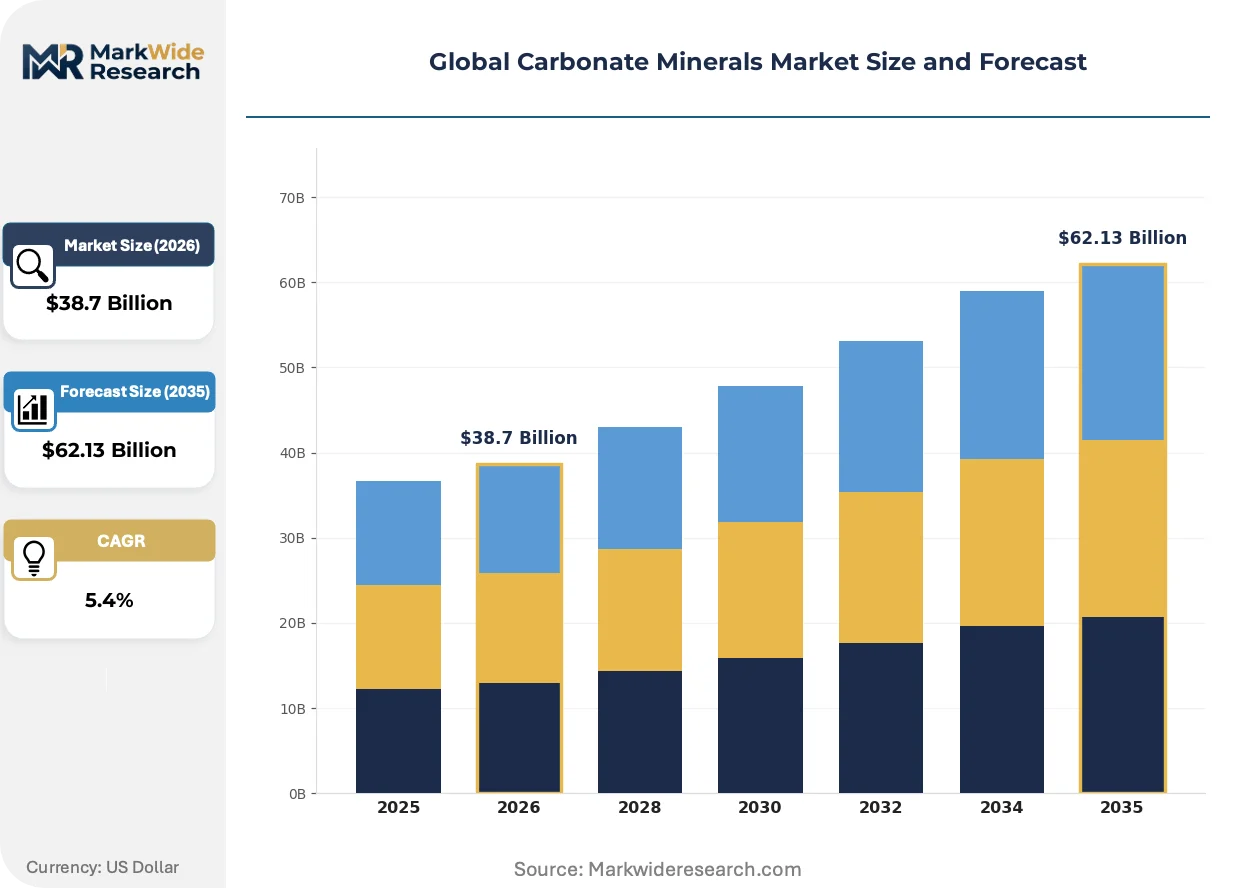
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Magnesium Carbonate, Sodium Bicarbonate, Potassium Carbonate, Dolomite Application: Paper Industry, Paints & Coatings, Plastics Manufacturing, Agriculture, Pharmaceuticals End User Industry: Construction Firms, Chemical Manufacturers, Food Processing Units, Water Treatment Plants, Electronics Producers Form: Powder, Granular, Micronized, Coated, Pelletized |
| Companies Covered | Mineral Technologies, Lhoist North America, Omya, Great Lakes Calcium Corporation, Mississippi Lime Company, Imerys, Huber Engineered Materials, Calcinor, Carmeuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbonate Minerals Market Shifts & Advancements
Processing technology convergence and regulatory carbon accounting are compressing traditional distinctions between commodity extraction and specialty chemical manufacturing, rewiring competitive advantage toward emission-verified supply chains.
Surface modification chemistry using stearic acid and silane coupling agents is collapsing the performance gap between untreated ground calcium carbonate and precipitated variants in polypropylene compounding. Automotive interior suppliers in Germany and Mexico are qualifying these coated grades for dashboard and trim applications previously reserved for higher-cost precipitated materials. The substitution is collapsing premium pricing tiers in filler markets where brightness specifications have historically dictated grade selection.
REACH registration requirements for imported carbonate feedstocks are mandating full substance identity and impurity profiling, raising compliance costs for non-EU quarry operators. ECHA's enforcement of updated dossier standards is diverting Chinese and Turkish export volumes toward Middle Eastern and African markets with less stringent chemical safety frameworks. European paper and plastics manufacturers are responding by deepening captive supply relationships with domestic micronization facilities in France and Spain.
Buyers in the paints and coatings sector are consolidating annual carbonate mineral tenders into multi-year framework agreements with fixed-volume, indexed-price structures. The shift from spot procurement is compressing trader margins and favoring vertically integrated producers with documented carbon footprint data. This concentration is most visible in the Netherlands and Italy, where architectural coatings formulators are reducing qualified supplier panels from 8-12 to 3-4 core partners.
Global Carbonate Minerals Market Segmentation
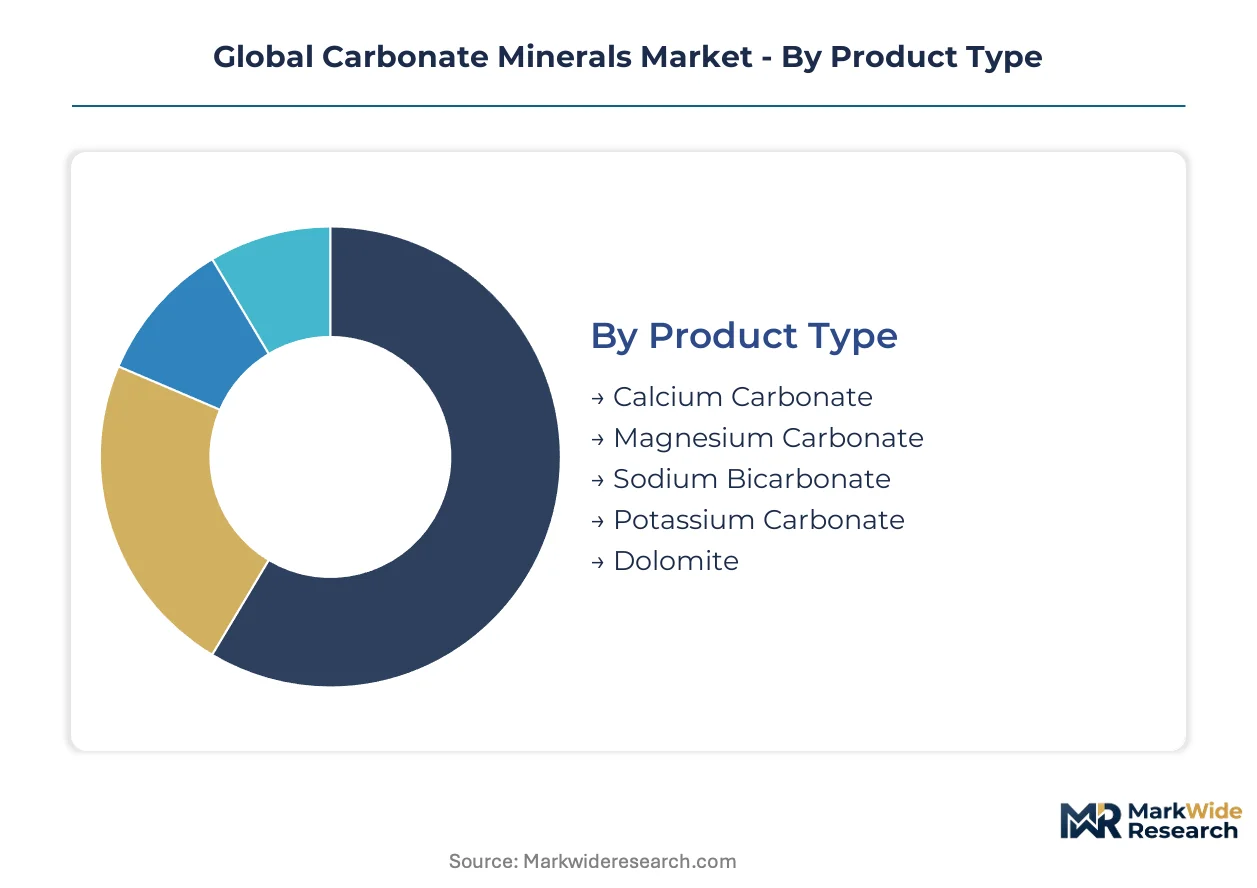
Carbonate mineral value chains fragment sharply across specification tiers, with purity thresholds and particle size distributions determining access to premium applications. Procurement patterns diverge between commodity bulk buyers and specialty formulators requiring certified low-heavy-metal grades.
Product Type:
Industrial applications span from construction-grade fluxing agents to pharmaceutical excipients with purity exceeding 99.5%.
- Calcium Carbonate:Precipitated variants deliver controlled particle size distributions for paper opacity and brightness, while ground limestone serves cement and concrete applications. Chinese state infrastructure programs are absorbing unprecedented volumes, compressing export availability and forcing European buyers toward longer-term offtake agreements.
- Magnesium Carbonate:Synthetic and natural forms function as antacid actives and rubber reinforcing agents, with low-heavy-metal specifications commanding substantial margin premiums in nutraceutical applications. Pharmaceutical formulators in Germany and Switzerland are tightening impurity thresholds, pulling volume into dedicated purification infrastructure.
- Sodium Bicarbonate:Food-grade and technical grades serve pH buffering across water treatment, animal feed, and fire suppression systems.
- Potassium Carbonate:Glass manufacturing and specialty fertilizers absorb volume, with hygroscopic properties limiting storage and handling options.
- Dolomite:Steel flux applications and construction aggregates maintain steady demand, though growth rates trail micronized specialty forms.
The dominant share belongs to Calcium Carbonate, while Magnesium Carbonate is closing the gap fastest.
Application:
Customer requirements stratify between commodity volume buyers and performance-critical formulators.
- Paper Industry:Precipitated calcium carbonate provides opacity and brightness control in coated paper grades. Indonesian and Vietnamese mills are installing on-site grinding capacity to reduce coating raw material costs, accelerating regional beneficiation infrastructure buildout.
- Paints & Coatings:Micronized and surface-coated grades deliver rheology control and TiO2 extension in architectural and industrial formulations. Dutch and Italian formulators are consolidating supplier panels from 8-12 to 3-4 core partners with documented carbon footprint data.
- Plastics Manufacturing:Stearic acid and silane surface modifications enable ground calcium carbonate substitution for precipitated variants in polypropylene compounding.
- Agriculture:Soil pH amendment and fertilizer conditioning absorb commodity limestone and dolomite volumes.
- Pharmaceuticals:Low-heavy-metal precipitated grades serve tablet excipients and antacid actives, with REACH dossier requirements raising compliance barriers for non-EU suppliers.
Paper Industry retains the largest volume position, though Paints & Coatings is gaining share fastest through sustainability-linked procurement consolidation.
End User Industry:
Demand concentration varies between project-driven construction cycles and continuous-process manufacturing.
- Construction Firms:Cement and concrete applications absorb ground calcium carbonate and dolomite at specification thresholds far below specialty grades. China's state-directed infrastructure investment continues absorbing unprecedented mineral volumes.
- Chemical Manufacturers:Synthetic carbonate production and downstream derivative manufacturing require consistent feedstock quality.
- Food Processing Units:Sodium bicarbonate and precipitated calcium carbonate serve leavening and fortification applications under FDA and EFSA purity mandates.
- Water Treatment Plants:pH correction and remineralization processes consume bulk limestone and quicklime derivatives.
- Electronics Producers:High-purity magnesium carbonate functions in component packaging and specialty glass manufacturing.
Construction Firms command the dominant volume share, while Food Processing Units are expanding fastest through clean-label fortification trends.
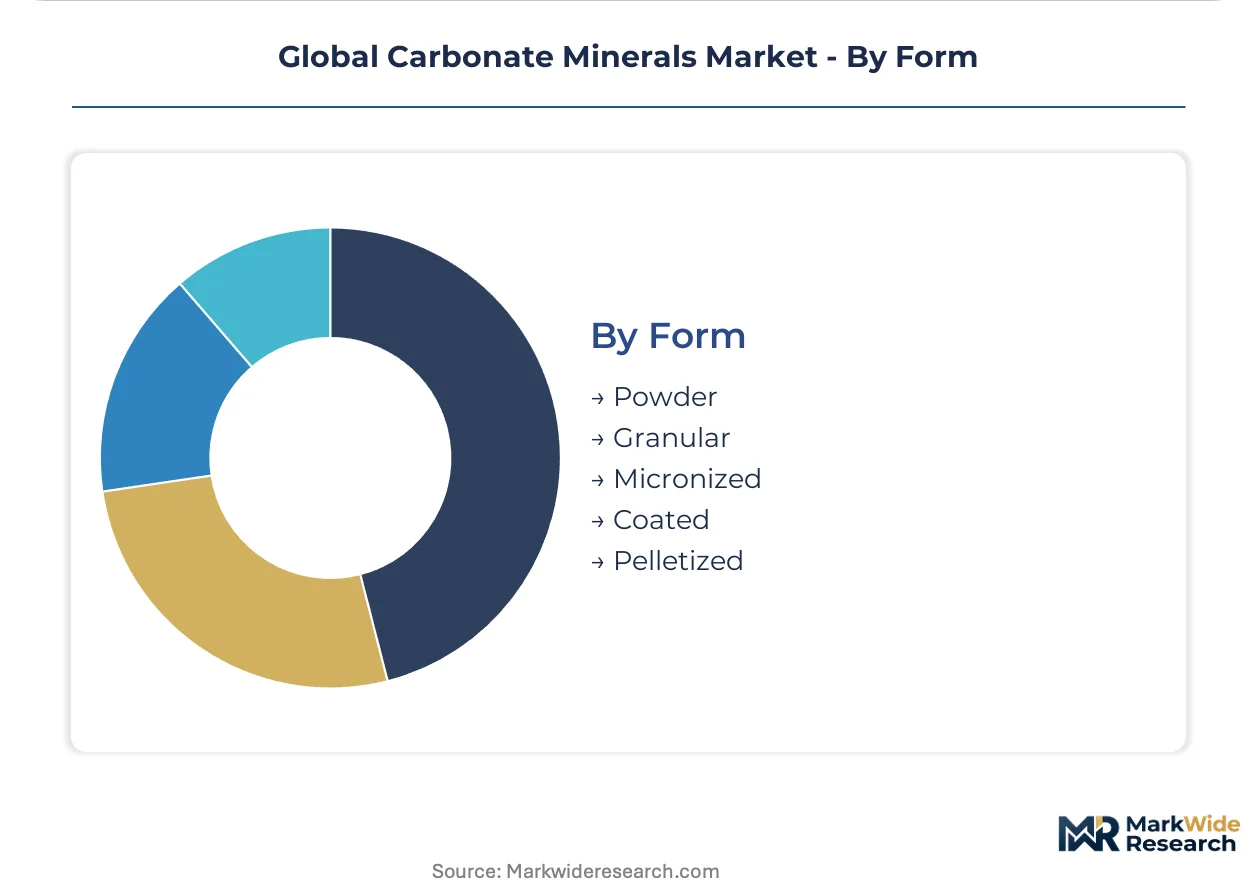
Form:
Physical processing intensity determines margin capture and application access.
- Micronized:Sub-10 micron particle sizes enable high-loading filler applications in automotive plastics and premium paper coatings. Surface modification chemistry using stearic acid and silane coupling agents is collapsing the performance gap with precipitated variants.
- Coated:Surface-treated grades deliver dispersion stability and polymer compatibility in masterbatch compounding. Automotive interior suppliers in Germany and Mexico are qualifying these grades for dashboard applications previously reserved for higher-cost materials.
- Powder:Standard ground material serves commodity construction and agricultural applications with minimal beneficiation.
- Granular:Controlled particle size distributions improve handling and dust suppression in bulk chemical processing.
- Pelletized:Compacted forms reduce dust generation and improve flow characteristics in automated feeding systems.
Powder forms retain volume leadership, while Coated grades are climbing the fastest through substitution of precipitated materials in performance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction and primary processing capacity clusters in China, Belgium, and the United States, with secondary beneficiation networks extending into Vietnam, Mexico, and Poland. Regulatory divergence across EPA, REACH, and MEE jurisdictions is fragmenting supply chain access and forcing regional qualification strategies.
China
State infrastructure programs absorb unprecedented calcium carbonate volumes for cement and concrete applications. MEE particulate emissions standards at calcination facilities are accelerating kiln technology replacement cycles. The Yangtze River Delta hosts expanding precipitated calcium carbonate capacity serving paper and plastics manufacturers.
United States
Construction-grade limestone demand tracks federal infrastructure spending and residential housing cycles. EPA effluent guidelines limit quarry runoff and processing discharge, compelling investment in closed-loop water systems. The Great Lakes region maintains integrated quarry-to-delivery operations for steel flux and chemical manufacturing feedstocks.
Germany
Automotive interior suppliers qualify coated calcium carbonate grades for polypropylene compounding applications. REACH registration requirements mandate full toxicological dossiers for imported feedstocks, raising compliance barriers for non-EU suppliers. The North Rhine-Westphalia chemical corridor anchors European micronization and surface modification infrastructure.
Vietnam
Paper mills install on-site grinding capacity to reduce coating raw material costs and bypass import dependencies. The country's national environmental regulator enforces stricter particulate standards at mineral processing facilities. The Red River Delta concentrates regional beneficiation infrastructure buildout for Southeast Asian export markets.
Mexico
Automotive manufacturing clusters in Nuevo León and the Bajío Region pull coated filler grades for interior component production. The federal environmental authority extends quarry permitting timelines through enhanced water and air quality reviews. Northern border states develop cross-border supply relationships with Texas and California processing facilities.
Global Carbonate Minerals Market Competitive Landscape
Vertically integrated multinationals and regional specialists split the market between scale-driven commodity supply and specification-controlled specialty grades. The vendor base organizes around three archetypes: quarry-owning integrated producers with captive micronization networks, toll-processing specialists serving paper and plastics formulators, and carbon capture-integrated operators monetizing emission reduction credits. Dominant competitive moves include backward integration into high-purity limestone deposits and strategic partnerships with coatings formulators seeking documented carbon footprint data.
Within the integrated multinational tier, Omya and Imerys exemplify archetypal positioning through global micronization networks and European quarry-to-delivery operations respectively. Carmeuse occupies a position at the scale-driven end of steel flux and carbon capture integration. These three entities anchor competitive dynamics across premium coated grades, regional supply security, and emission-verified supply chain development.
| Leading Market Players |
|---|
| Mineral Technologies |
| Lhoist North America |
| Omya |
| Great Lakes Calcium Corporation |
| Mississippi Lime Company |
| Imerys |
| Huber Engineered Materials |
| Calcinor |
| Carmeuse |
| Others |
Supply & Pricing Matrix
Yangtze River Delta freight corridors transmit calcination cost volatility into downstream price spreads between coated specialty grades and commodity ground limestone, compressing margins for non-integrated processors while amplifying pricing power for quarry-owning multinationals with captive micronization networks.
Pricing Analysis
EU Green Deal carbon accounting dictates the pricing tier structure across the carbonate minerals market. Three-tier pricing structure across premium, standard, and economy levels separates emission-verified coated grades from unverified ground materials and bulk construction flux. Cost compression in standard grades is intensifying because energy expenses constitute the dominant operating cost component. Construction firms exhibit the highest price sensitivity due to specification tolerance for lower-purity inputs, while pharmaceutical formulators accept substantial premiums for REACH-registered low-heavy-metal certifications.
Supply Chain Analysis
Toll-processing specialists in Vietnam and Poland hold expanding beneficiation capacity for paper and plastics manufacturers seeking regional grinding services. Extraction concentrates in China, Belgium, and the United States, with raw material supply draws from high-calcium limestone deposits, dolomite formations, and precipitated carbonate chemical feedstocks. Single-source vulnerability runs through Yangtze River Delta calcination clusters where MEE emissions enforcement is accelerating kiln replacement timelines. Distribution runs through direct-to-mill digital procurement platforms that bypass traditional mineral traders in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon capture integration in calcination facilities represents a technological inflection that will bifurcate competitive viability between emission-verified suppliers and stranded commodity processors. This disruption accelerates as EU carbon border adjustments phase in compliance requirements.
For Market Incumbents: Insulate premium positioning by deepening backward integration into high-purity limestone deposits in France and Belgium while accelerating oxy-fuel kiln retrofit programs to capture carbon border adjustment credits. Threat of substitution by engineered silicates in brightness-critical paper applications demands defensive investment in surface modification R&D to collapse performance gaps with precipitated variants. For New Entrants and Emerging Players: Establish a beachhead in Brazilian pharmaceutical excipients where ANVISA registration pathways remain underdeveloped for imported mineral feedstocks. White-space opportunity concentrates in carbon capture utilization construction materials qualifying for EU emission credits, with go-to-market leverage through direct partnerships with coatings formulators seeking documented supply chain footprints. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate mineral divisions lacking integrated micronization infrastructure or carbon capture development roadmaps. Long-term viability across the projection horizon favors operators with quarry-to-delivery vertical control and REACH dossier completion for premium grade access. Signal to monitor: tightening MEE enforcement timelines in China that compress export availability and force European buyer consolidation toward qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Kiln Retrofit | Oxy-fuel combustion integration at calcination facilities secures EU Green Deal compliance credits and carbon border adjustment eligibility. |
| Backward Integration into High-Purity Deposits | Captive limestone and marble quarry access in France and Belgium locks in feedstock security for pharmaceutical-grade production. |
| Surface Modification Technology Licensing | Stearic acid and silane coating chemistry enables ground calcium carbonate substitution in automotive polypropylene compounding applications. |
| Direct-to-Mill Digital Platform Launch | Bypassing traditional mineral traders in Indonesia and Vietnam compresses working capital cycles and captures procurement margin. |
| REACH Dossier Completion Partnership | Joint toxicological registration investments with European formulators accelerate market access for low-heavy-metal precipitated grades. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EU ECHA registration databases, Chinese MEE emissions disclosures, and trade flow customs records. Interviews with calcination plant managers, paper mill procurement directors, coatings formulator R&D leads, and mineral trading channel partners informed supply chain and pricing dynamics. Bottom-up volume modeling across quarry extraction, beneficiation capacity, and end-use consumption triangulates against top-down market value reconstruction.
Forecast inputs include grade tier stratification, end-use industry absorption rates, regional regulatory enforcement intensity, and carbon accounting protocol adoption curves across the analysis window. Segmentation dimensions encompass product purity specifications, particle size distribution categories, surface treatment chemistry types, and geographic production hub clusters. CAGRs derive from regression analysis of historical volume trajectories adjusted for policy inflection points and technology substitution elasticities.
Stress conditions across natural gas price volatility, quarry permitting timeline extensions, and precipitated carbonate substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU carbon border adjustment implementation pace and Chinese state infrastructure spending continuity. Quarterly review of MEE enforcement actions, REACH dossier submission volumes, and coatings sector supplier consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Talc Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Perlite Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Kyanite Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market