
 Zinc Sulphate Market | 2026-2036
Zinc Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Sulphate Market Outlook
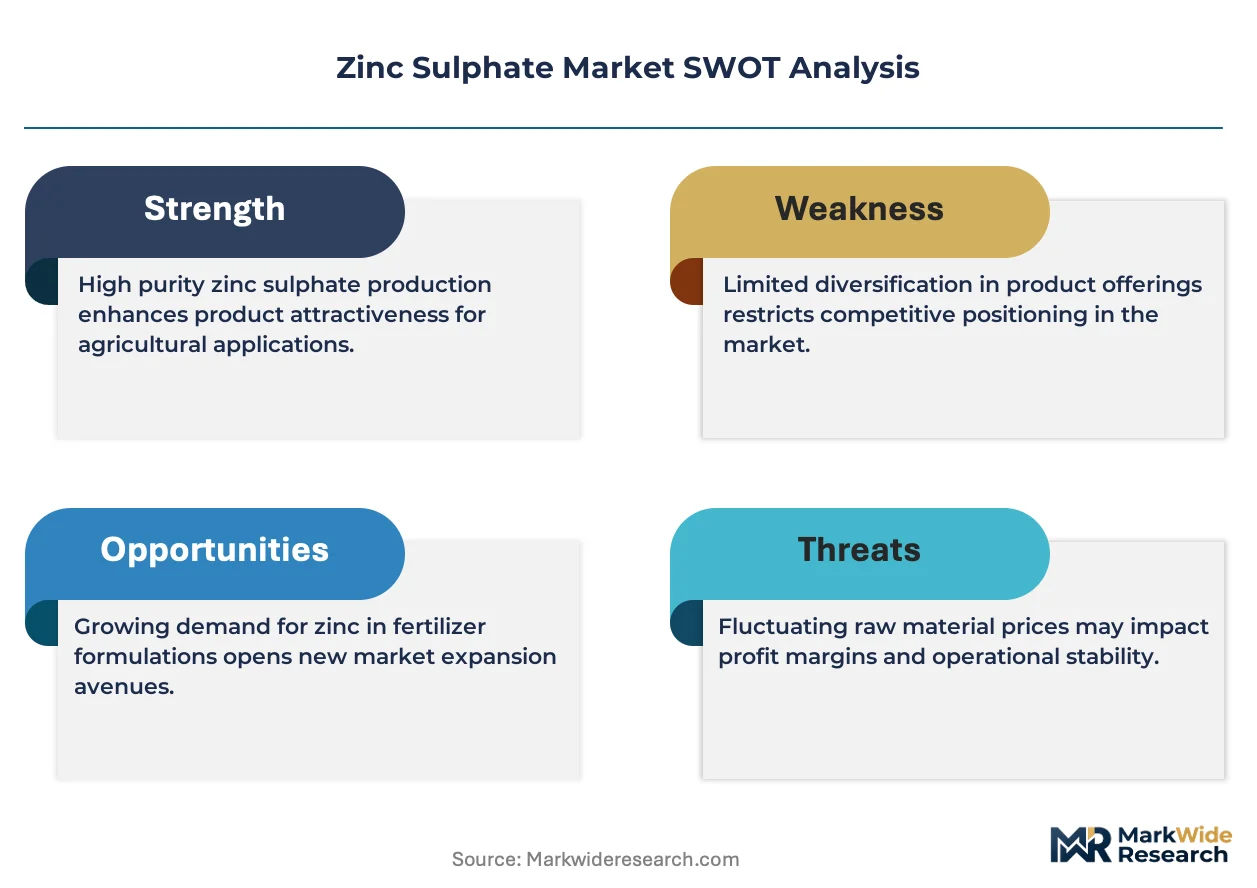
REACH is restructuring the cost-of-entry calculus for pharmaceutical-grade zinc sulphate across European value chains. Merck KGaA leverages its analytical-grade certification infrastructure to command premium positioning in life-science applications. Balaji Industries anchors South Asian supply through backward integration into zinc smelting operations. China Bohigh competes on crystalline purity grades tailored to precision agriculture protocols.
Zinc sulphate is a divalent zinc salt with the formula ZnSO₄, typically produced through the reaction of zinc-bearing ores or secondary zinc with sulfuric acid, yielding heptahydrate, monohydrate, or anhydrous forms with zinc content ranging from 22% to 36% by weight. Its primary industrial purpose centers on correcting zinc deficiency in soils and animal nutrition, while also serving as a precursor in electroplating, rayon production, and pharmaceutical synthesis. Powder formulations dominate volume flows into bulk fertilizer blending operations, whereas crystalline grades capture margin pools in pharmaceutical and laboratory end uses. The agriculture application segment sustains the broadest demand base, with livestock farmer end users driving incremental offtake through precision trace-mineral supplementation programs.
EPA standards govern effluent discharge from zinc sulphate manufacturing facilities in the United States, while ECHA enforces REACH registration and hazard communication across European production and import channels. India's BIS certification mandates specific heavy-metal limits for fertilizer-grade material, directly shaping product formulation decisions by domestic manufacturers. Stakeholders must monitor evolving soil-health program budgets and fertilizer subsidy allocations as these policy levers determine regional demand elasticity more precisely than raw zinc price movements alone.
Market Dynamics
Soil zinc deficiency mapping programs are redirecting agricultural procurement toward certified crystalline grades, compressing margins for unverified powder suppliers while elevating analytical-grade producers into long-term offtake contracts with national fertilizer distributors.
Growth Catalysts
- India's Soil Health Card Scheme:Government-mandated micronutrient testing protocols are institutionalizing zinc sulphate application rates across wheat and rice cultivation belts, creating predictable demand visibility for domestic blenders.
- REACH registration completion:Full dossier acceptance for pharmaceutical-grade material has unlocked formaldehyde-free synthesis pathways, enabling EU manufacturers to supply GMP-certified precursor chemicals for parenteral nutrition formulations.
- Precision livestock farming:Automated mineral dosing systems in dairy operations are specifying monohydrate grades with verified particle-size distribution, upgrading specification requirements across North American feed compounders.
Market Restraints
- Sulfuric acid price volatility:Smelter-derived acid supply interruptions in China are transmitting cost shocks directly into zinc sulphate production economics, squeezing merchant producers without captive acid sources.
- Heptahydrate substitution pressure:Chelated zinc alternatives in premium fertilizer applications are capturing margin pools in high-value horticulture, constraining volume expansion for crystalline sulphate in specialty crop segments.
- BIS heavy-metal certification delays:Extended testing timelines for arsenic and cadmium limits are throttling new entrant qualification into India's government tender system, consolidating procurement around incumbent domestic suppliers.
Strategic Opportunities
- Brazilian Cerrado expansion:Underpenetrated soybean cultivation zones with documented zinc deficiency present first-mover positioning for crystalline-grade suppliers establishing local blending partnerships.
- Pharmaceutical precursor verticalization:Integration into sterile injectable zinc formulations for total parenteral nutrition creates margin capture opportunities distinct from commodity agriculture pricing cycles.
- Direct-to-farm digital channels:E-procurement platforms connecting micronutrient manufacturers with cooperatives are disintermediating traditional distributor markups in Southeast Asian rice production regions.
Industry Challenges
- ISO 17025 laboratory accreditation timelines:Extended certification periods for heavy-metal testing capabilities are delaying product launch schedules for new grade introductions.
- Legacy ERP integration with traceability systems:Batch-level serialization requirements for pharmaceutical-grade material are forcing capital-intensive system overhauls at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Sulphate Market |
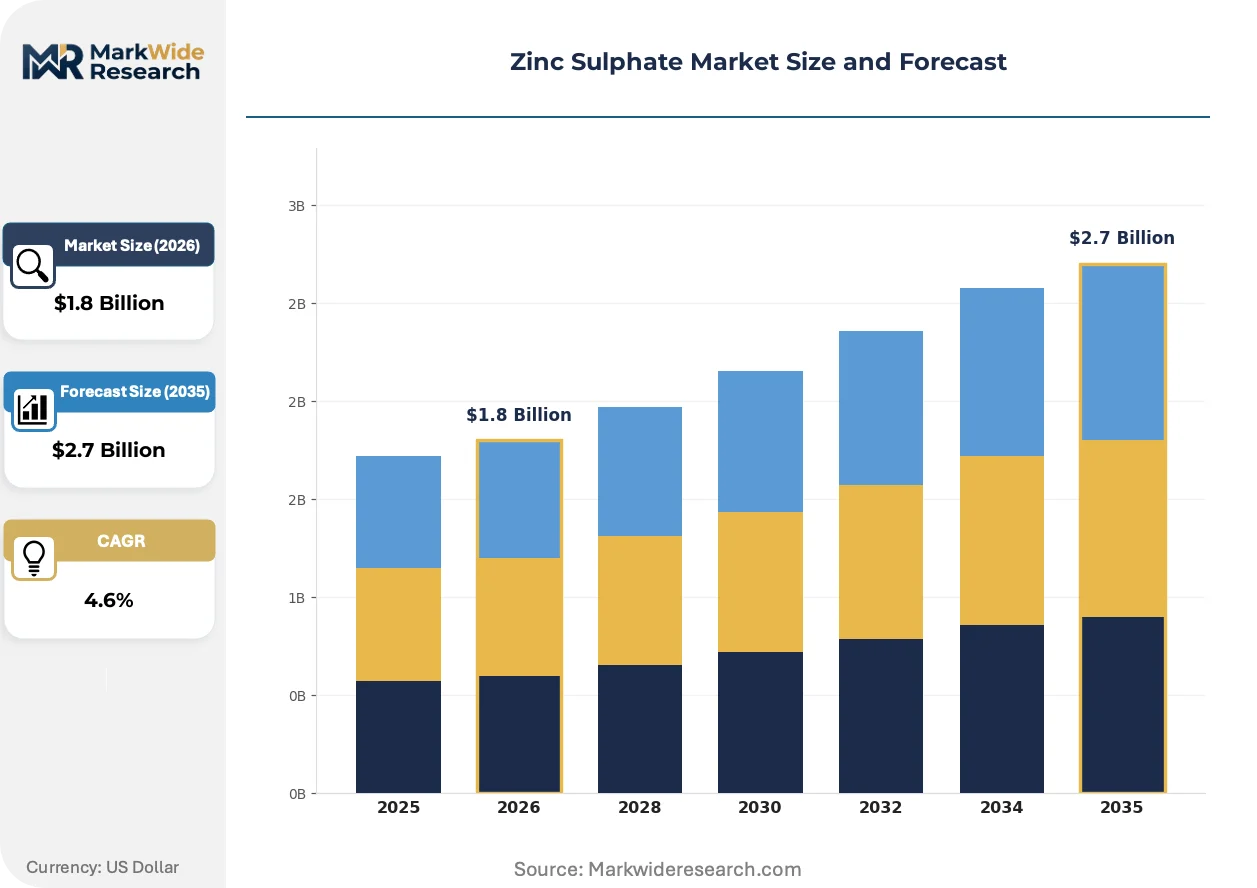
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
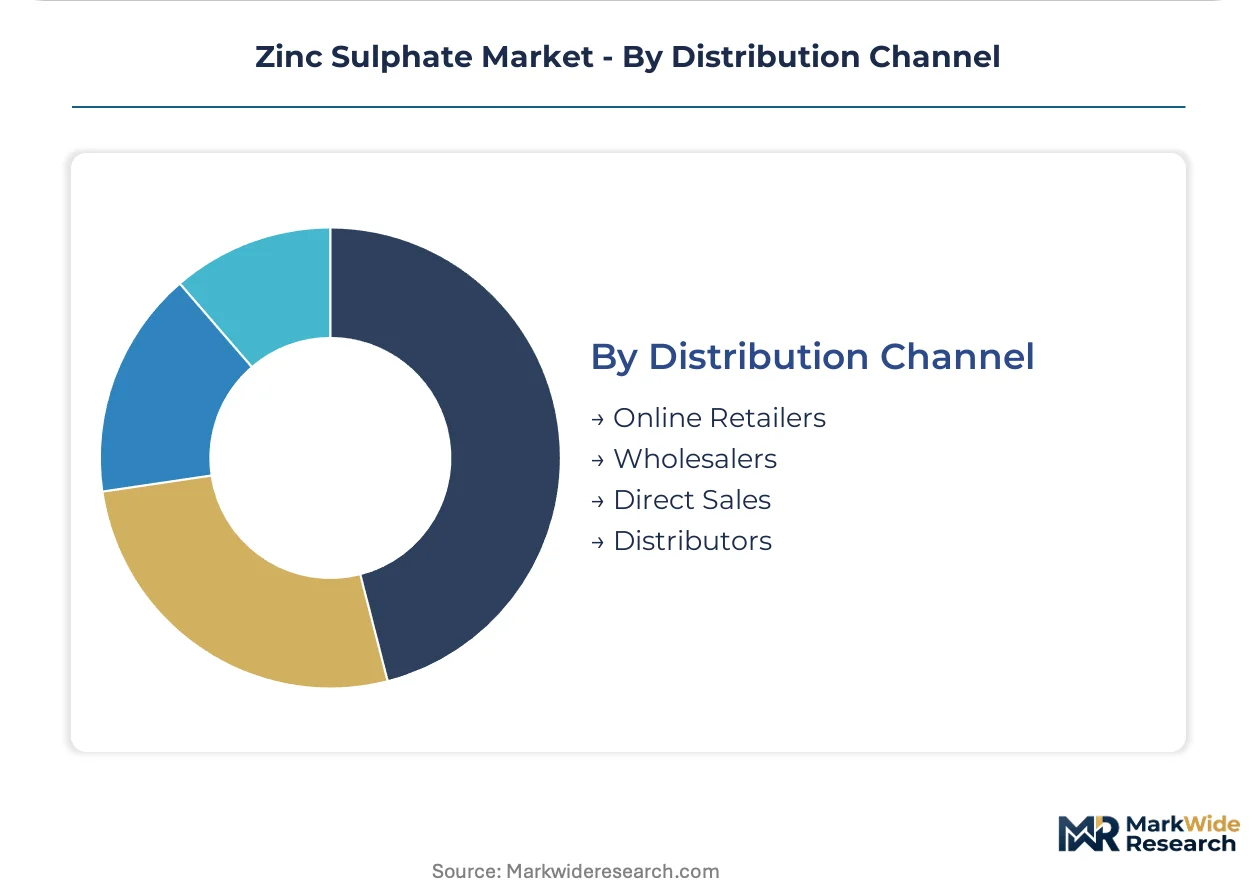
| Segmentation | Product Type: Granular, Powder, Liquid, Crystalline Application: Agriculture, Pharmaceuticals, Animal Feed, Industrial End User: Crop Producers, Healthcare Providers, Livestock Farmers, Manufacturers Distribution Channel: Online Retailers, Wholesalers, Direct Sales, Distributors |
| Companies Covered | Zinc Nacional, Old Bridge Chemicals, China Bohigh, Rech Chemical Co. Ltd, Changsha Haolin Chemicals Co. Ltd, Balaji Industries, Sulfozyme Agro India Pvt. Ltd, Alpha Chemicals, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Sulphate Market Strategic Shifts
Production technology shifts and regulatory data requirements are compressing the viable supplier base while opening specification premiums for certified-grade producers with verified supply chain documentation.
Continuous crystallization systems with inline particle-size monitoring are decentralizing quality control from centralized laboratories to production-line sensors, enabling real-time grade segregation. Large-scale fertilizer blenders in the US Corn Belt are adopting these systems to reduce batch rejection rates. The technology is decentralizing procurement authority toward plant-floor operators who can certify on-spec material without laboratory confirmation delays.
REACH extended safety data sheet obligations now mandate granular exposure scenario documentation for zinc sulphate dust handling across all downstream uses. Chemical distributors in Germany are restructuring warehouse operations to segregate pharmaceutical-grade inventory from agricultural material. Pharmaceutical compounders are responding by qualifying single-source suppliers with pre-validated exposure assessments, narrowing the approved vendor list.
Cooperative procurement consortia are aggregating micronutrient demand across multiple farm operations to negotiate volume-tiered pricing directly with manufacturers. Rice cultivation cooperatives in Vietnam are displacing traditional agricultural input distributors through collective tendering. This consolidation is most visible in regions with strong farmer organization density, where shared storage infrastructure reduces per-unit logistics costs.
Zinc Sulphate Market Segmentation
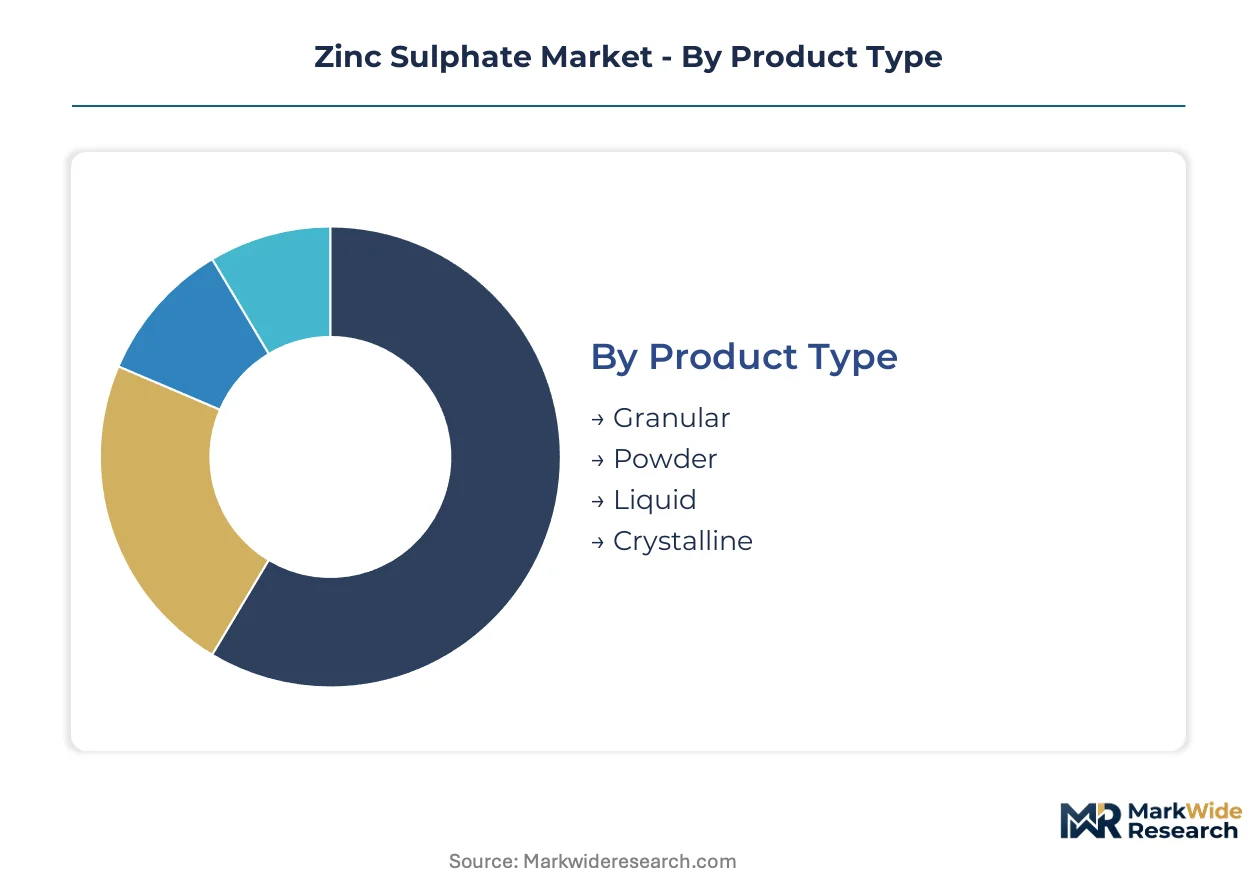
Zinc sulphate procurement patterns diverge sharply across buyer types, with agricultural blenders prioritizing volume throughput while pharmaceutical compounders demand batch-level certification documentation. Specification requirements and price elasticity vary by an order of magnitude between commodity fertilizer applications and GMP-certified precursor uses.
Product Type:
Buyers in this category separate by handling infrastructure and dissolution rate requirements rather than zinc content alone.
- Granular:Slow-release formulations with controlled particle sizing between 2-4 millimeters suit mechanized fertilizer spreading equipment. Brazilian soybean operations in Mato Grosso specify this grade for aerial application compatibility, with procurement volumes tied to planting season windows.
- Powder:Fine-ground material with 95% passing through 150-micron sieves dominates bulk blending operations where rapid dissolution in irrigation systems is required. Indian state fertilizer corporations specify powder grades for their Soil Health Card distribution programs, locking in annual tender volumes.
- Liquid:Pre-dissolved concentrates eliminate dust exposure during handling and enable precision injection into drip irrigation lines. California specialty crop producers favor liquid formulations for vineyard micronutrient programs where foliar application timing is critical.
- Crystalline:High-purity heptahydrate crystals with verified heavy-metal limits serve laboratory reagent and pharmaceutical precursor markets. Merck KGaA and similar analytical-grade suppliers command specification premiums through ISO 17025-certified batch documentation.
Powder leads volumes today; crystalline is gaining share fastest.
Application:
End-use differentiation tracks regulatory intensity and formulation complexity rather than zinc concentration.
- Agriculture:Soil amendment and foliar feeding applications consume the majority of commodity-grade production, with demand concentrated in wheat belts where zinc deficiency correlates with yield penalties. Government micronutrient subsidy programs in India and China institutionalize application rates and procurement timing.
- Pharmaceuticals:Injectable-grade zinc sulphate for total parenteral nutrition requires formaldehyde-free synthesis pathways and endotoxin testing per pharmacopeial standards. REACH dossier completion has unlocked GMP-certified supply chains for EU hospital pharmacies.
- Animal Feed:Monohydrate grades with specified particle-size distribution integrate into automated mineral dosing systems at North American dairy operations. Precision livestock farming protocols are upgrading specification requirements beyond traditional feed-grade standards.
- Industrial:Electroplating bath maintenance and rayon production utilize technical-grade material where metal purity requirements are less stringent than pharmaceutical applications. Textile manufacturers in Bangladesh and Vietnam drive regional demand for industrial-grade crystalline forms.
Agriculture commands absolute volume; pharmaceuticals show the steepest expansion trajectory.
End User:
Procurement sophistication and contract structures vary dramatically by buyer scale and regulatory exposure.
- Crop Producers:Smallholder cooperatives in Southeast Asia aggregate demand through collective tendering platforms, displacing traditional distributor markups. Large-scale corn belt operators in the United States negotiate direct manufacturer relationships with volume-tiered pricing.
- Healthcare Providers:Hospital pharmacy procurement committees specify single-source suppliers with pre-validated exposure assessments under REACH extended safety data sheet obligations. German distributors now segregate pharmaceutical-grade inventory in dedicated warehouse zones.
- Livestock Farmers:Automated mineral dosing systems at commercial dairy operations are specifying monohydrate grades with verified particle-size distribution, upgrading requirements across North American feed compounders.
- Manufacturers:Electroplating shops and chemical synthesis facilities purchase technical-grade material through industrial chemical distributors with less stringent documentation requirements than pharmaceutical channels.
Crop producers dominate transaction counts; healthcare providers are consolidating procurement fastest.
Distribution Channel:
Channel selection reflects buyer scale, geographic concentration, and specification verification needs.
- Online Retailers:E-procurement platforms connecting micronutrient manufacturers with agricultural cooperatives are disintermediating traditional distributor markups in Vietnamese rice production regions. Digital channels suit standardized grades with established specifications.
- Wholesalers:Regional agricultural input distributors maintain inventory positions for planting season surges, extending credit terms to smallholder farmers. Indian state fertilizer corporations route subsidized material through authorized wholesale networks.
- Direct Sales:Large-scale fertilizer blenders and pharmaceutical compounders negotiate long-term offtake contracts directly with manufacturers, securing batch-level traceability and custom formulation services.
- Distributors:Industrial chemical distributors serve fragmented electroplating and manufacturing customers with technical-grade material, leveraging multi-product logistics networks.
Wholesalers still handle the greatest tonnage; direct sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemists and agricultural extension specialists cluster around zinc smelting corridors and grain belt research stations. Their technical capacity shapes regional formulation standards and certification pathways.
India
Soil Health Card Scheme extension drives crystalline-grade procurement through state fertilizer corporations. BIS heavy-metal certification mandates filter supplier qualification, consolidating tender awards around domestic manufacturers with captive testing laboratories. Gujarat and Maharashtra host backward-integrated zinc sulphate operations feeding government distribution networks.
China
Precision agriculture protocols in Shandong and Hebei provinces upgrade specification requirements for crystalline grades used in high-value horticulture. MIIT environmental compliance deadlines force acid-plant integration decisions among merchant producers. Yangtze River Delta fertilizer blenders source heptahydrate crystals for automated spreading equipment calibration.
United States
Corn Belt cooperatives negotiate direct manufacturer contracts bypassing wholesale markups through volume-tiered procurement platforms. EPA effluent standards shape production economics at Ohio and Illinois manufacturing facilities. Midwest dairy operations specify monohydrate grades with verified particle-size distribution for automated mineral dosing systems.
Brazil
Cerrado soybean expansion creates first-mover positioning for crystalline-grade suppliers establishing local blending partnerships in Mato Grosso. ANVISA pharmaceutical precursor regulations remain less stringent than REACH, enabling technical-grade material diversion into emerging parenteral nutrition markets. São Paulo chemical distributors aggregate demand across fragmented farm operations.
Germany
REACH extended safety data sheet obligations mandate granular exposure scenario documentation for zinc sulphate dust handling across pharmaceutical and agricultural channels. ECHA dossier acceptance unlocks formaldehyde-free synthesis pathways for GMP-certified precursor supply. Merck KGaA leverages analytical-grade certification infrastructure to command premium positioning in life-science applications.
Zinc Sulphate Market Competitive Environment
The competitive structure tilts toward vertically integrated smelter-chemical complexes with captive acid supply and laboratory accreditation infrastructure. Tiered supplier bases separate crystalline-grade specialists from commodity powder blenders. Three archetypes dominate: backward-integrated zinc producers, analytical-grade certification holders, and regional agricultural formulators. Capacity expansion and REACH dossier completion represent the dominant competitive moves, with pharmaceutical-grade registration unlocking premium pricing tiers.
Among Indian manufacturers, Balaji Industries anchors South Asian supply through smelter integration. China Bohigh occupies a position within the crystalline purity segment serving precision agriculture protocols. Merck KGaA exemplifies the analytical-grade archetype with ISO 17025-certified batch documentation for European pharmaceutical channels. These three represent distinct capability clusters rather than direct substitutes.
| Leading Market Players |
|---|
| Zinc Nacional |
| Old Bridge Chemicals |
| China Bohigh |
| Rech Chemical Co. Ltd |
| Changsha Haolin Chemicals Co. Ltd |
| Balaji Industries |
| Sulfozyme Agro India Pvt. Ltd |
| Alpha Chemicals |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Continuous crystallization systems with inline particle-size monitoring are compressing quality-control timelines while concentrating procurement authority among plant-floor operators who can certify on-spec material without laboratory confirmation delays, simultaneously reducing batch rejection costs and elevating specification premiums for certified-grade producers with verified supply chain documentation.
Pricing Analysis
Certification-bundled versus unbundled service splits define transaction economics across agricultural and pharmaceutical channels. Three-tier pricing structure across pharmaceutical-grade, analytical-grade, and fertilizer-grade levels tracks ISO 17025 accreditation status and REACH dossier completion. Cost compression in commodity powder grades is intensifying because sulfuric acid supply interruptions transmit directly into production economics. State fertilizer corporations in India exhibit highest price sensitivity; hospital pharmacy procurement committees show lowest elasticity due to single-source qualification requirements.
Supply Chain Analysis
Regional distribution centers in Gujarat, Maharashtra, and Shandong province anchor hub-and-spoke patterns for crystalline-grade material serving government tender systems and precision agriculture protocols. Merchant producers draw from zinc smelting corridors in India and China, with captive sulfuric acid supply determining cost competitiveness. Single-source vulnerability concentrates in BIS-certified testing laboratory access, where extended arsenic and cadmium certification timelines throttle new entrant qualification. Distribution runs through state fertilizer corporation networks for subsidized agricultural grades and direct manufacturer contracts for pharmaceutical precursors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH dossier completion for pharmaceutical-grade material has unlocked formaldehyde-free synthesis pathways and GMP-certified supply chains, permanently elevating entry barriers and specification premiums.
For Market Incumbents: Deepen backward integration into zinc smelting operations to secure captive acid supply and insulate margins from sulfuric acid price volatility. Accelerate ISO 17025 laboratory accreditation investments to capture crystalline-grade specification premiums before BIS certification delays consolidate procurement around domestic incumbents with captive testing infrastructure.
For New Entrants and Emerging Players: Agricultural cooperatives in Vietnam and rice cultivation collectives in Southeast Asia represent the most penetrable channel partner type for disintermediating traditional distributor markups through e-procurement platform partnerships. Target Brazilian Cerrado soybean expansion zones with documented zinc deficiency for first-mover crystalline-grade positioning through local blending partnerships.
For Investors and Strategic Acquirers: Valuations sit cheapest among merchant producers without captive acid supply or laboratory accreditation infrastructure, presenting consolidation targets for vertically integrated specialists. Long-term viability favors smelter-chemical complexes with REACH dossier completion and GMP-certified pharmaceutical pathways. Monitor BIS heavy-metal certification timeline extensions as the inflection signal for domestic incumbent consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Smelting | Captive acid supply insulates margins from sulfuric acid volatility at China Bohigh and Balaji Industries. |
| ISO 17025 Laboratory Accreditation | Certified batch documentation unlocks pharmaceutical-grade specification premiums for Merck KGaA life-science channels. |
| REACH Dossier Completion | Formaldehyde-free synthesis pathways enable GMP-certified parenteral nutrition precursor supply across European hospital pharmacies. |
| Direct-to-Farm Digital Channel Development | E-procurement platforms disintermediate distributor markups for Vietnamese rice cooperative procurement consortia. |
| Continuous Crystallization System Deployment | Inline particle-size monitoring reduces batch rejection rates for US Corn Belt fertilizer blender operations. |
Study Parameters
Coverage spans India, China, the United States, Brazil, and Germany, with primary inputs from each market cluster obtained through structured interviews with plant managers at zinc smelting operations, procurement leads at state fertilizer corporations, regulatory affairs specialists navigating REACH and BIS compliance, distribution channel partners managing warehouse segregation protocols, and technical R&D directors overseeing crystallization system deployments. Secondary validation draws from customs and trade data, SEC 10-K filings, ECHA registration databases, and Indian government tender records. Bottom-up volume estimates triangulate against top-down value projections across grade tiers and application segments.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. The analytical framework models zinc sulphate demand by product type (granular, powder, liquid, crystalline), application (agriculture, pharmaceuticals, animal feed, industrial), end user (crop producers, healthcare providers, livestock farmers, manufacturers), and regional production hub. CAGRs derive from segmented growth rate analysis applied to base-year estimates. Key forecast inputs include government micronutrient subsidy allocation trajectories and soil zinc deficiency mapping program expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sulfuric acid supply disruptions, chelated zinc substitution rates in premium horticulture, and BIS certification timeline volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Chromite Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Global Nickel Hydroxide Market