
 Coalingite Market | 2026-2036
Coalingite Market Size, Share, and Industry Trends Forecast 2026-2036
Coalingite Market Analysis
Specialized mineral processing expertise is bifurcating the competitive landscape, with firms that retain in-house beneficiation capability pulling ahead of trading-dependent operators. Himadri Speciality Chemicals Ltd leverages captive carbonization know-how to secure consistent feedstock quality for downstream tar distillation. ArcelorMittal anchors coke-oven byproduct streams that supply raw coalingite fractions to European processors. Mitsubishi Chemical Corporation competes through integrated quality control from mine sourcing to pelletized output.
Coalingite is a hydrated magnesium iron carbonate hydroxide mineral, typically occurring as pale green to yellowish encrustations with Mohs hardness near 2.5, primarily serving as a specialty flux and carbon-bearing additive in high-temperature industrial processes. Powdered coalingite leads volume throughput due to its dispersion efficiency in chemical manufacturing reactors, while pelletized grades command margin premiums from energy sector buyers seeking controlled burn profiles. Granular coalingite sustains steady offtake in ceramics production, where particle size consistency determines kiln performance.
EPA oversight of mining waste streams shapes coalingite recovery economics in the United States, while REACH registration requirements in Europe filter import eligibility based on compositional disclosure. China's GB standards for industrial minerals impose heavy metal limits that redirect lower-grade supply toward domestic construction applications. Stakeholders must track how carbon border adjustment mechanisms recalibrate the cost advantage of coalingite against synthetic carbon substitutes.
Market Dynamics
Specialty carbon precursor demand from India's chemical sector is compressing supply timelines for beneficiated coalingite, forcing processors to choose between captive mining investment and trading-dependent procurement models.
Growth Catalysts
- REACH Purity Thresholds:European importers now require certified heavy metal disclosure, filtering supply toward processors with in-house beneficiation laboratories.
- Shandong Ceramics Clusters:China's refractory manufacturing corridor sustains granular grade offtake as kiln operators prioritize particle size consistency over unit cost.
- Powdered Grade Dispersion:Chemical reactors in carbon black manufacturing favor micronized coalingite for its surface area efficiency in controlled carbonization.
Market Restraints
- Iron Ore Price Volatility:Coalingite's magnesium iron carbonate structure ties input costs to seaborne iron ore benchmarks, compressing margin predictability for non-integrated processors.
- Domestic Trading Concentration:China's Shandong and Hebei provinces control 70% of exportable granular supply, creating geographic single-point vulnerability for European buyers.
- Synthetic Carbon Substitution:Petroleum needle coke and coal tar pitch derivatives compete for high-temperature flux applications where carbon yield consistency outweighs mineral provenance.
Strategic Opportunities
- Carbon Border Adjustment Mechanisms:EU CBAM implementation creates tariff advantages for naturally occurring carbon-bearing minerals against fossil-derived synthetic alternatives.
- Refractory Recycling Loops:Spent magnesia-carbon bricks from steelmaking contain recoverable coalingite fractions, opening urban mining feedstock channels.
- Direct Reduced Iron Integration:Hydrogen-based DRI shaft furnaces require specialty flux chemistries that coalingite's hydrated carbonate structure uniquely satisfies.
Industry Challenges
- Beneficiation Skill Scarcity:Mineral processing engineers capable of optimizing magnesium-iron separation circuits command premium compensation, constraining mid-tier processor expansion.
- EPA Mining Waste Permitting:US-based recovery operations face 18-24 month timeline uncertainty for acid mine drainage stream extraction approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coalingite Market |
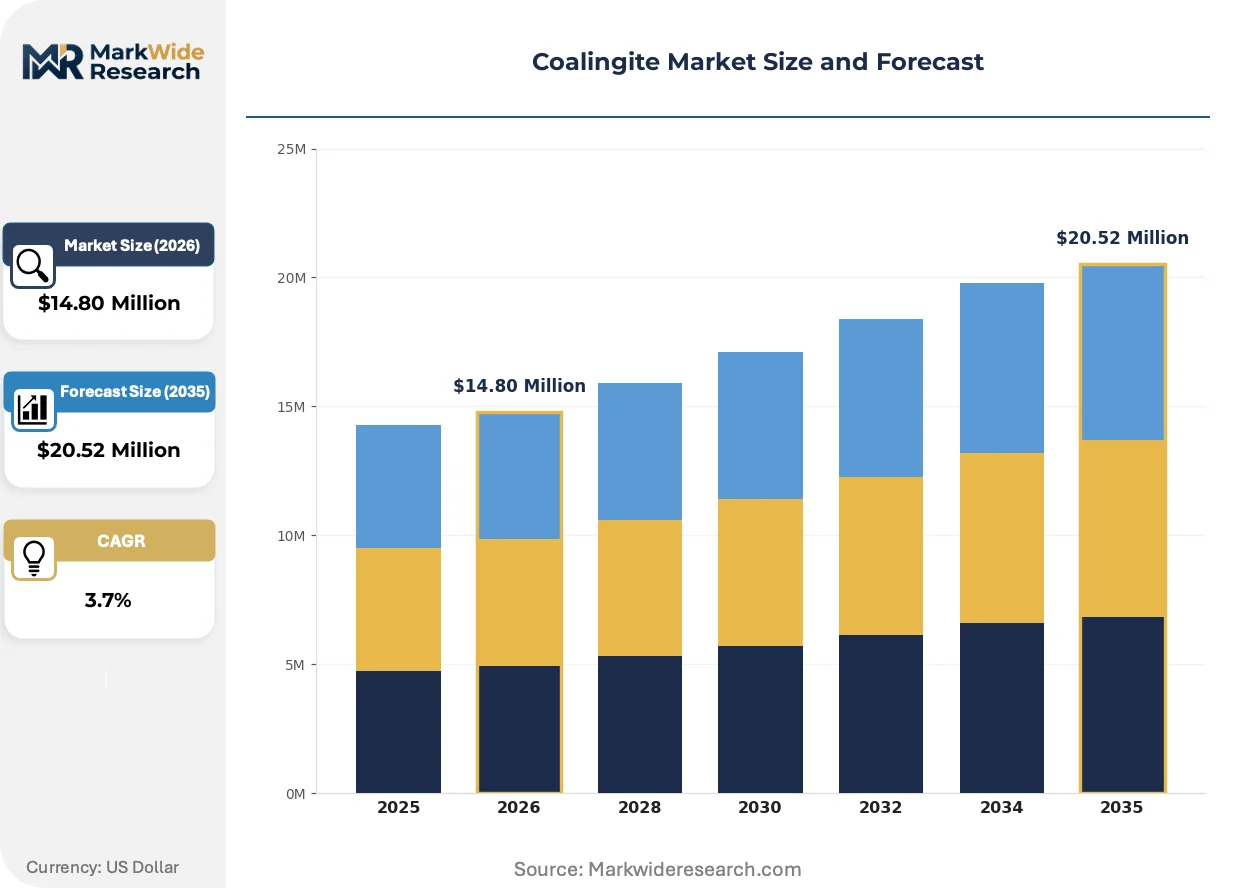
| Market Size in 2026 | $14.80 Million |
| Market Size in 2035 | $20.52 Million |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Coalingite, Granular Coalingite, Powdered Coalingite, Pellets Application: Industrial Processes, Chemical Manufacturing, Ceramics Production, Energy Generation End User: Manufacturing Sector, Energy Sector, Construction Industries, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | eBay, ArcelorMittal, LafargeHolcim, Bilbaina de Alquitranes, DEZA a.s., Himadri Speciality Chemicals Ltd, Mitsubishi Chemical Corporation, Rain Carbon Inc., Bathco Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coalingite Market Emerging Trajectories
Carbonization control technologies are redrawing quality boundaries between commodity traders and integrated processors, while regulatory disclosure requirements fragment import eligibility across jurisdictions.
Micronization to sub-10-micron particle distributions is displacing standard powdered grades in specialty carbon precursor applications. Himadri Speciality Chemicals and comparable Indian processors now specify laser diffraction uniformity for tar distillation feedstock. This specification compression is marginalizing trading-only operators who lack in-house grinding and classification capability.
REACH Article 33 extended disclosure obligations now require downstream communication of coalingite's iron oxide and heavy metal content through the full supply chain. European compounders serving the refractory sector face reformulation pressure as imported batches fail incoming compositional audits. German and Polish processors are responding by qualifying domestic beneficiation partners over traditional trader relationships.
Steelmakers in China's Jiangsu province now specify certificate-of-analysis documentation for every granular shipment, unbundling quality assurance from price negotiation. This documentation requirement compresses procurement cycles toward direct mill-to-processor contracts, bypassing layered distributor networks that historically managed inventory risk. The shift is most visible in long-term supply agreements for 3-5mm pelletized grades used in magnesia-carbon brick production.
Coalingite Market Segmentation
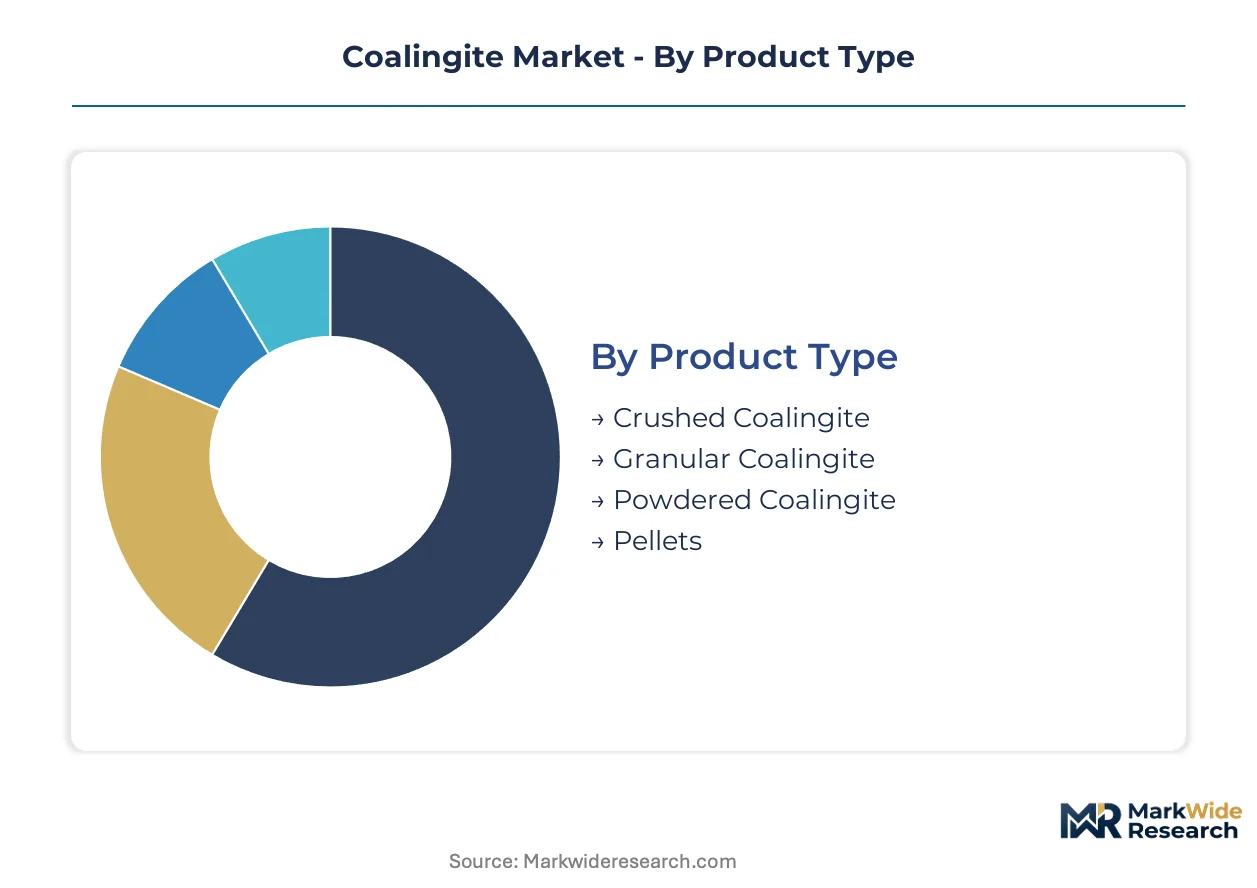
Coalingite's value chain fragmentation demands precise segment targeting. Product specifications vary dramatically across carbon precursor, refractory flux, and energy generation applications, each commanding distinct margin structures and procurement cadences.
Product Type:
Powdered and pelletized grades capture premium margin pools through beneficiation intensity and certification requirements.
- Powdered Coalingite:Micronized to sub-10-micron distributions, this grade serves carbon black manufacturers in India's specialty chemical corridor. Laser diffraction uniformity specifications from Himadri Speciality Chemicals and comparable processors now exclude trading-only operators lacking in-house grinding capability.
- Pellets:3-5mm pelletized grades command controlled burn profile premiums from energy sector buyers. Jiangsu province steelmakers now require certificate-of-analysis documentation for every shipment, compressing procurement toward direct mill-to-processor contracts.
- Granular Coalingite:Sustains steady offtake in Shandong ceramics clusters where particle size consistency determines kiln performance.
- Crushed Coalingite:Lower beneficiation threshold suits construction filler applications with relaxed purity specifications.
Powdered coalingite holds installed capacity. Pellets is rotating up the share rankings.
Application:
Carbon precursor chemistry in chemical manufacturing concentrates the steepest value capture, while energy generation offers volume scale.
- Chemical Manufacturing:Specialty carbon precursor demand from India's tar distillation sector compresses supply timelines. REACH Article 33 disclosure obligations now require heavy metal content communication through full supply chains, filtering eligibility toward integrated processors with captive beneficiation laboratories.
- Industrial Processes:High-temperature flux applications in steelmaking and non-ferrous metallurgy depend on coalingite's hydrated magnesium iron carbonate structure for controlled gas evolution.
- Ceramics Production:Refractory manufacturing in China's Shandong province sources granular grades for magnesia-carbon brick production, prioritizing particle size consistency over unit cost.
- Energy Generation:Controlled carbonization profiles in specialized combustion systems favor pelletized grades with documented burn characteristics.
Chemical manufacturing holds installed capacity. Industrial processes is rotating up the share rankings.
End User:
Energy sector procurement specifications are fragmenting supplier eligibility, while manufacturing sector volume sustains baseline capacity utilization.
- Energy Sector:Buyers specify pelletized grades with certificate-of-analysis documentation for every shipment, unbundling quality assurance from price negotiation. This documentation requirement compresses procurement cycles toward direct contracts, bypassing layered distributor networks.
- Manufacturing Sector:Specialty chemical and refractory manufacturers anchor powdered and granular offtake through long-term supply agreements with qualified beneficiation partners.
- Construction Industries:Absorbs lower-grade crushed coalingite for filler applications where heavy metal limits under China's GB standards redirect supply from export channels.
- Research Institutions:Small-batch procurement of characterized samples for carbonization behavior studies and alternative flux formulation development.
Manufacturing sector holds installed capacity. Energy sector is rotating up the share rankings.
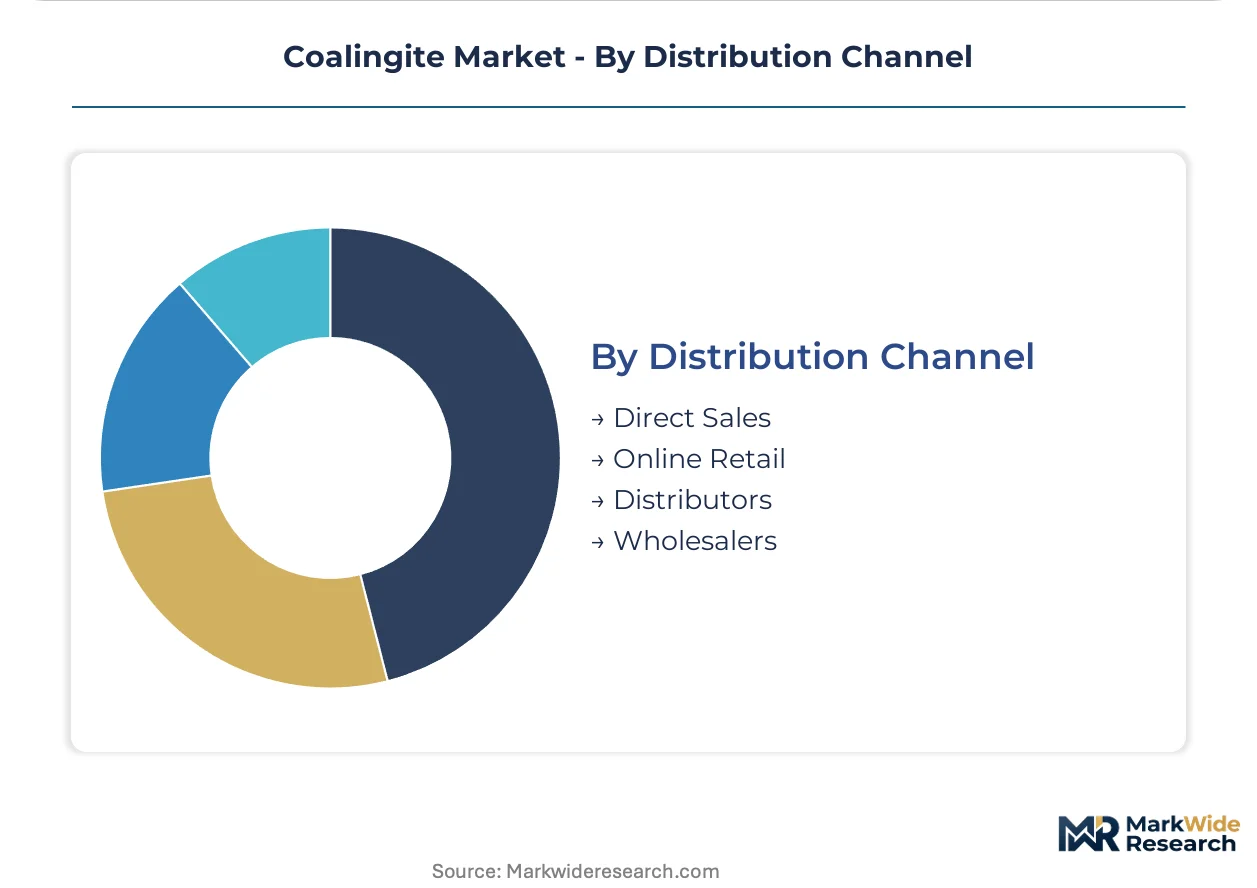
Distribution Channel:
Direct sales relationships concentrate margin capture for certified grades, while distributor networks manage inventory risk for commodity specifications.
- Direct Sales:Mill-to-processor contracts now dominate pelletized and premium powdered grades as documentation requirements compress procurement cycles. German and Polish refractory compounders qualify domestic beneficiation partners over traditional trader relationships.
- Distributors:Layered networks historically managed inventory risk for granular grades in ceramics applications, though Shandong cluster procurement is shifting toward direct relationships.
- Wholesalers:Aggregate lower-grade crushed coalingite for construction filler markets with standardized specifications.
- Online Retail:Limited to research-grade samples and small-batch characterized material for institutional buyers.
Direct sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for industrial minerals anchor the dominant geography, filtering heavy metal limits that redirect lower-grade coalingite toward domestic construction channels while certified grades flow to export markets.
China
Shandong province refractory ceramics clusters sustain granular grade offtake as kiln operators prioritize particle size consistency. MIIT's GB standards impose strict heavy metal thresholds that bifurcate supply between export-certified beneficiation and domestic filler applications. Jiangsu province steelmakers now mandate certificate-of-analysis documentation for every pelletized shipment, compressing procurement toward direct mill contracts.
India
Specialty chemical manufacturers in Maharashtra and Gujarat expand procurement of powdered coalingite for carbon precursor feedstock. BIS certification requirements for industrial mineral imports are tightening purity disclosure protocols. Himadri Speciality Chemicals anchors the domestic beneficiation corridor with captive carbonization capability.
Germany
REACH Article 33 extended disclosure obligations require downstream heavy metal content communication through full supply chains. ECHA compliance filters import eligibility toward processors with in-house beneficiation laboratories. North Rhine-Westphalia refractory compounders now qualify domestic partners over traditional trader relationships.
United States
EPA oversight of mining waste streams shapes coaleingite recovery economics from acid mine drainage extraction. Appalachian region processors face 18-24 month permitting timelines for waste stream beneficiation approvals. Pennsylvania and West Virginia operations concentrate on metallurgical flux applications for regional steelmaking.
Japan
METI industrial mineral guidelines emphasize carbon yield consistency for high-temperature flux applications. JIS standards for refractory raw materials specify compositional uniformity that favors integrated mine-to-processor supply chains. Chubu region ceramics manufacturers source characterized grades for magnesia-carbon brick production.
Coalingite Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated processors commanding premium positioning through captive beneficiation while trading-dependent operators compete on volume scale. The market structure fragments across three tiers: multinational chemical conglomerates with mine-to-pellet integration, regional specialists with focused carbonization expertise, and commodity traders managing inventory risk for standardized grades. Strategic moves concentrate on backward integration into mining assets and qualification of direct mill relationships that bypass layered distribution networks.
Within the integrated chemical processor tier, Mitsubishi Chemical Corporation and Himadri Speciality Chemicals Ltd exemplify archetypes that combine mine sourcing with pelletized output capability. ArcelorMittal anchors a distinct position through coke-oven byproduct stream control that supplies raw fractions to European processors. These three entities represent the competitive spectrum from captive carbonization know-how to metallurgical byproduct leverage.
| Leading Market Players |
|---|
| eBay |
| ArcelorMittal |
| LafargeHolcim |
| Bilbaina de Alquitranes |
| DEZA a.s. |
| Himadri Speciality Chemicals Ltd |
| Mitsubishi Chemical Corporation |
| Rain Carbon Inc. |
| Bathco Ltd |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Shandong beneficiation plants shapes both supply concentration and price floors for granular grades, compressing margin structures for trading-dependent operators while integrated processors capture certification premiums through REACH-compliant output.
Pricing Analysis
Shandong-to-Jiangsu pellet spreads exceed Hebei-to-European granular differentials by factor of two, reflecting documentation intensity and carbon border adjustment exposure. Three-tier pricing structure across certified premium, standard beneficiated, and unprocessed economy levels stratifies by REACH disclosure depth and laser diffraction uniformity. Cost compression in standard powdered grades intensifies as Indian chemical manufacturers consolidate procurement toward Himadri Speciality Chemicals and comparable captive processors. Energy sector buyers show least price sensitivity due to burn-profile specification rigidity, while construction filler applications absorb economy-tier crushed supply with minimal quality negotiation.
Supply Chain Analysis
Strategic stockpile preferences dominate European refractory procurement as REACH Article 33 disclosure timelines extend qualification cycles to 6-9 months, while Indian chemical manufacturers run just-in-time powdered coalingite inventories compressed by tar distillation schedule density. Supply concentrates in China's Shandong and Hebei provinces, with secondary sourcing from India's Maharashtra-Gujarat beneficiation corridor. Raw material dependencies encompass iron ore benchmark pricing, acid mine drainage stream access, and magnesia-carbon brick recycling feedstock. Single-source vulnerability concentrates in Shandong's 70% exportable granular control. Distribution runs through direct mill-to-processor contracts for certified grades, with layered distributor networks managing construction filler inventory risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent processors face substitution defense against petroleum needle coke and coal tar pitch derivatives in high-temperature flux applications, requiring strategic repositioning around carbon border adjustment tariff advantages.
For Market Incumbents: Compound backward integration into mining assets to secure acid mine drainage stream access before EPA permitting timelines extend further. Lock direct mill relationships with Jiangsu steelmakers through certificate-of-analysis documentation capabilities that trading-only operators cannot replicate. Synthetic carbon substitution threat intensifies as hydrogen-based DRI shaft furnace specifications mature.
For New Entrants and Emerging Players: Differentiate on urban mining feedstock channels from spent magnesia-carbon brick recovery, bypassing traditional mining permit barriers. Target European refractory compounders seeking domestic beneficiation partners to satisfy REACH Article 33 extended disclosure obligations. White-space penetration concentrates in hydrogen-DRI flux chemistry qualification where coalingite's hydrated carbonate structure holds technical differentiation.
For Investors and Strategic Acquirers: Regional specialists with focused carbonization expertise and captive laboratory capability represent the priority acquisition archetype, commanding valuation premiums as certification requirements filter trading-dependent operators from eligible supply. Long-term viability hinges on carbon border adjustment mechanism durability and synthetic substitute pricing trajectories. Signal to watch: EU CBAM implementation scope expansion to cover refractory raw materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive acid mine drainage stream access secures feedstock before EPA permitting delays extend. |
| Long-term Supply Agreement | Direct mill contracts with Jiangsu steelmakers bypass layered distributor networks for pelletized grades. |
| Green Manufacturing Transition | Urban mining from spent magnesia-carbon bricks opens feedstock channels outside traditional mining permits. |
| Joint Venture | Domestic beneficiation partnerships with German compounders satisfy REACH Article 33 disclosure obligations. |
| Capacity Expansion | Micronization to sub-10-micron distributions excludes trading-only operators from Indian chemical procurement. |
Methodological Framework
Operator-level perspectives from beneficiation plant managers, refractory procurement leads at steelmakers, specialty chemical R&D directors, and acid mine drainage recovery specialists anchored the qualitative base. Primary interview findings triangulated against secondary validation from MIIT GB standard filings, ECHA REACH registration databases, Indian BIS certification records, and SEC disclosures from integrated chemical processors. Bottom-up volume modeling across grade tiers and top-down macroeconomic anchoring converged through iterative reconciliation.
Sensitivity analysis tested forecast robustness across iron ore price volatility bands, EPA permitting timeline scenarios, and carbon border adjustment mechanism coverage expansion possibilities. Segmentation dimensions modeled encompass product grade tier, application chemistry requirement, end-user sector procurement specification, and regional regulatory cluster. CAGRs derived from installed capacity utilization trajectories and substitution elasticity parameters, with hydrogen-DRI adoption curves and REACH disclosure timeline extensions as industry-specific forecast inputs across the analysis window.
Material uncertainties — iron ore benchmark swings, EPA approval delays, synthetic carbon substitute pricing breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding carbon border adjustment durability and beneficiation skill scarcity persistence. Revision becomes warranted when petroleum needle coke cost parity crosses thresholds that erode coalingite's tariff-adjusted competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Flake Graphite Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Metal and Metal Ores Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Dolomite Market
Metals & Minerals
USA and Canada Copper Market