
 Gregoryite Market | 2026-2036
Gregoryite Market Size, Share, and Industry Trends Forecast 2026-2036
Gregoryite Market Outlook
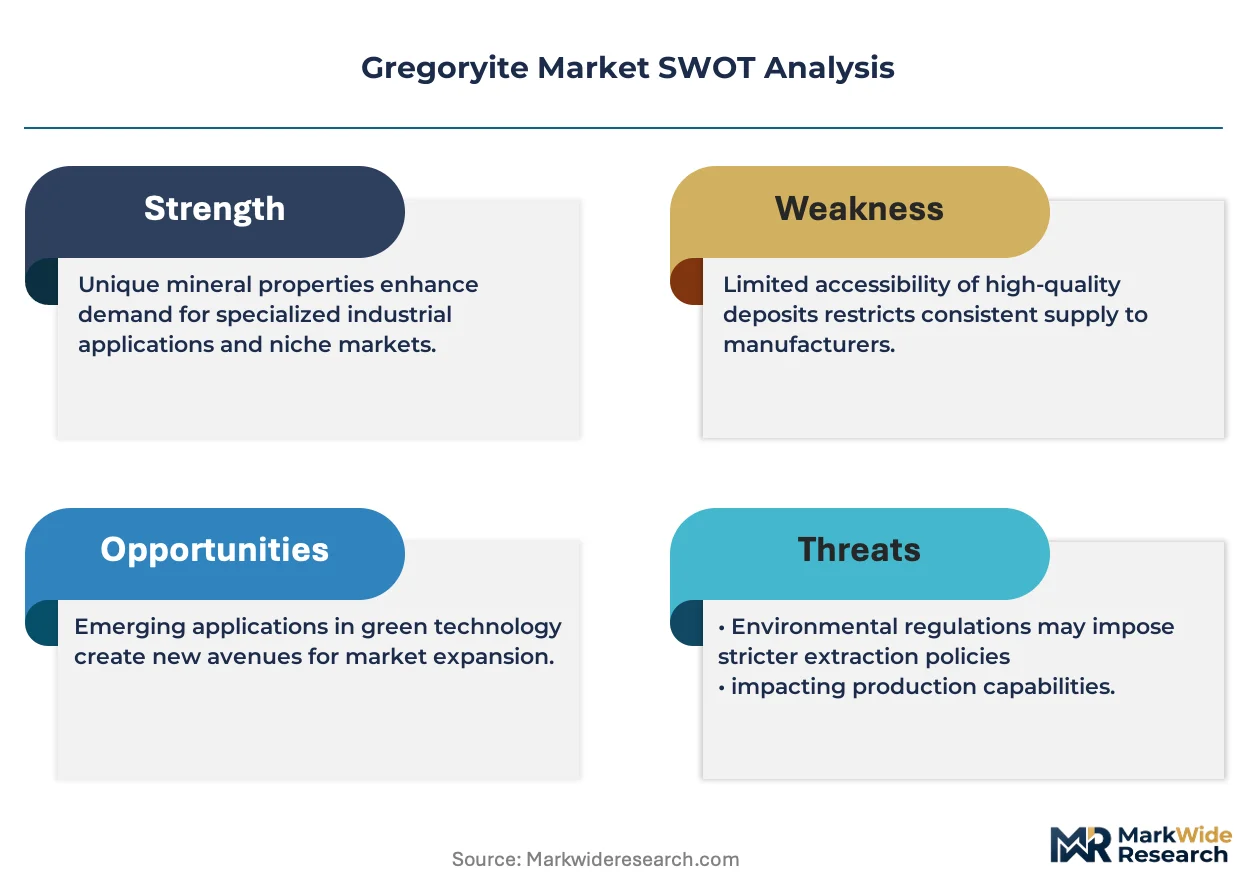
East African carbonate mineral extraction is reconfiguring upstream supply dynamics for Gregoryite feedstock. Weinrich Minerals Company leverages direct mine-to-lab relationships to sustain premium raw material flows into European research institutions. R&M Minerals anchors North American distribution through specialized geological specimen networks. Brazil Mineral Suppliers competes on volume scale across Latin American industrial carbonate channels.
Gregoryite is a rare sodium-calcium carbonate mineral with the chemical formula Na2Ca(CO3)2, typically occurring in alkaline igneous complexes and requiring controlled thermal processing to achieve battery-grade purity above 99.5 percent. Its primary commercial purpose centers on serving as a specialized precursor in high-temperature ceramic electrolytes and advanced thermal barrier coatings. Refined Gregoryite captures the dominant margin pool among product type categories due to energy-intensive purification requirements and limited qualified processor capacity. Energy Storage represents the fastest-expanding application segment as solid-state battery developers seek alternative carbonate electrolyte chemistries, while Industrial Use retains volume leadership through established refractory and glass manufacturing offtake.
China's SAMR enforces revised GB standards on carbonate mineral trace-element thresholds, directly constraining which raw Gregoryite lots qualify for electronics-grade refinement. The EPA in the United States monitors extraction site runoff under Clean Water Act provisions, adding compliance layers for domestic processors. ISO 14001 environmental management certification has become a de facto market access requirement for European defense contractor supply chains. Stakeholders must monitor which purification technologies achieve qualification under China's evolving dual carbon policy framework before committing capital to capacity expansion.
Market Dynamics
Specialty mineral processors face mounting pressure from China's MIIT purity mandates while solid-state battery developers race to qualify alternative carbonate electrolyte chemistries before incumbent suppliers lock in long-term offtake agreements.
Growth Catalysts
- Solid-state battery electrolyte qualification:Next-generation energy storage developers are actively testing refined Gregoryite as a sodium-calcium carbonate precursor, creating fresh pull from German precision ceramics corridors.
- Dual carbon policy framework:China's evolving environmental compliance standards are accelerating processor investment in low-carbon purification technologies that qualify for preferential market access.
- East African feedstock expansion:Upstream carbonate mineral extraction capacity is scaling in Kenya and Tanzania, diversifying raw material origins beyond traditional alkaline igneous complex sources.
Market Restraints
- Energy-intensive purification costs:Achieving battery-grade purity above 99.5 percent requires controlled thermal processing that consumes substantial electricity, compressing margins for non-integrated processors.
- Qualified processor concentration:Refined Gregoryite capacity clusters among a handful of specialty mineral processors with direct mine-to-lab relationships, creating supply vulnerability.
- Trace-element threshold compliance:China's SAMR revised GB standards on carbonate mineral impurities are disqualifying substantial raw feedstock lots from electronics-grade refinement pipelines.
Strategic Opportunities
- Brazilian industrial carbonate channels:Latin American refractory and glass manufacturing offtake remains underpenetrated by premium refined Gregoryite suppliers focused on European battery markets.
- Defense contractor supply chain certification:ISO 14001 environmental management qualification is becoming a de facto entry requirement for European thermal barrier coating procurement.
- Direct specimen network distribution:Specialized geological specimen channels offer bypass routes around consolidated industrial mineral traders for high-purity research-grade volumes.
Industry Challenges
- Purification technology qualification timelines:Processors must demonstrate compliance with China's dual carbon policy framework before capital deployment, stretching decision cycles.
- Clean Water Act extraction compliance:US-based processors face EPA monitoring of extraction site runoff, adding operational layers that delay site permitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gregoryite Market |
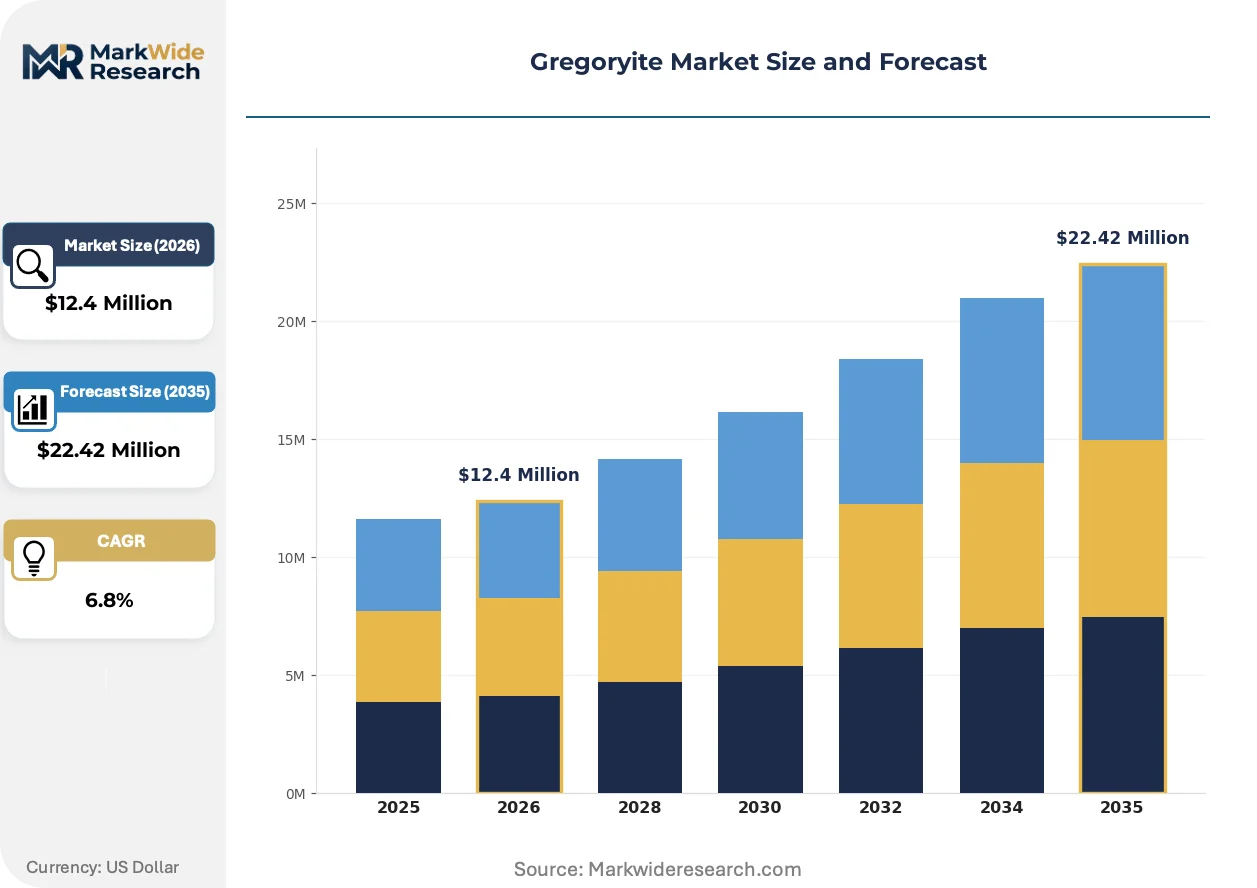
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $22.42 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Gregoryite, Refined Gregoryite, Synthetic Gregoryite, Composite Gregoryite Application: Industrial Use, Electronics, Energy Storage, Aerospace Components End User: Manufacturers, Research Institutions, Technology Firms, Defense Contractors Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Weinrich Minerals Company, R&M Minerals, John Betts Fine Minerals, Allminerals LLC, Brazil Mineral Suppliers, Mexico Mineral Suppliers, Global Mineral Distributors, Regional Carbonate Mineral Producers, Specialty Mineral Processors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gregoryite Market Strategic Shifts
Solid-state battery developers are forcing rapid adaptation across carbonate mineral supply chains as electrolyte chemistry specifications crystallize ahead of commercial scale-up.
Flash calcination coupled with selective ion exchange is hybridizing conventional thermal purification workflows. Solid-state battery developers in Germany's Dresden corridor are piloting these hybrid systems to compress qualification timelines for next-generation ceramic electrolytes. The technology is hybridizing what were historically separate roasting and leaching stages, enabling modular capacity expansion that avoids large integrated plant commitments.
REACH substance registration requirements are tightening traceability documentation for imported carbonate minerals entering European industrial channels. The regulation forces processors to maintain chain-of-custody records from extraction through refinement, elevating compliance costs for non-integrated traders. Battery-grade Gregoryite shipments are most affected, with German precision ceramics manufacturers now demanding full REACH dossier packages as standard procurement terms.
Research institutions are consolidating purchasing through direct mine-to-lab relationships that bypass traditional mineral trading houses. Weinrich Minerals Company has structured dedicated supply lines serving European university and national laboratory networks, displacing spot-market procurement for high-purity specimen volumes. This channel compression is most visible in Germany, where defense and energy research funding concentrates demand among a handful of large institutional buyers.
Gregoryite Market Segmentation
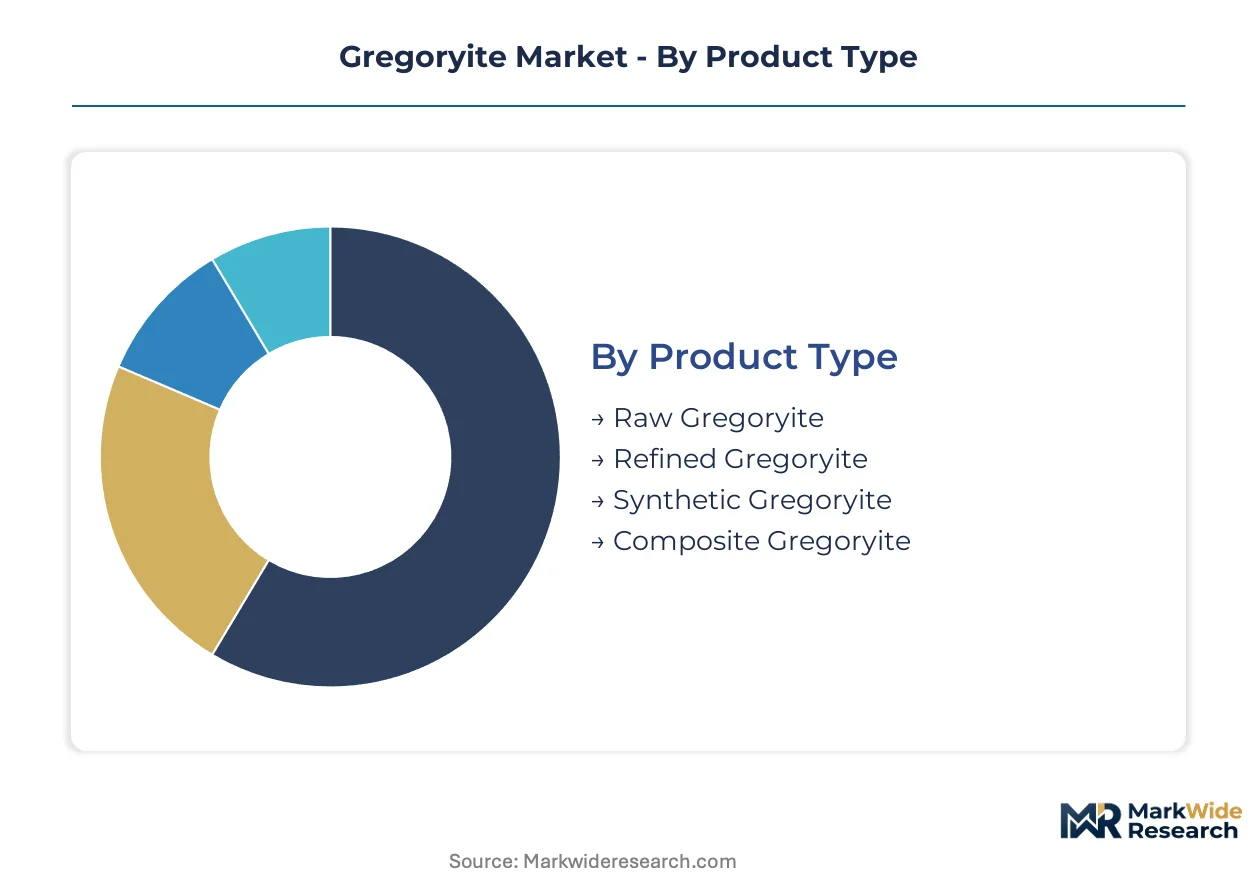
Gregoryite's specialized role in battery-grade electrolytes and thermal coatings forces precise segmentation around purity thresholds and procurement relationships. Each category reveals distinct margin structures and qualification barriers that shape competitive positioning across the value chain.
Product Type:
After-sales service intensity varies dramatically across purity grades, with battery-grade refinement demanding continuous technical support and certification maintenance.
- Raw Gregoryite:Extracted directly from alkaline igneous complexes, this feedstock requires minimal processing but faces disqualification under China's SAMR revised GB trace-element thresholds. East African extraction operations in Kenya and Tanzania are diversifying supply origins for industrial consumers tolerant of lower purity.
- Refined Gregoryite:Controlled thermal processing achieves battery-grade purity above 99.5 percent through energy-intensive calcination workflows. German precision ceramics corridors around Dresden concentrate demand for this grade as solid-state battery developers qualify alternative carbonate electrolyte chemistries.
- Synthetic Gregoryite:Laboratory-controlled precipitation enables precise stoichiometry for research applications requiring consistent Na2Ca(CO3)2 ratios.
- Composite Gregoryite:Blended formulations with other carbonate minerals target specialized refractory applications in glass manufacturing.
Refined Gregoryite holds the largest share; momentum sits with Raw Gregoryite as East African feedstock expansion diversifies upstream supply.
Application:
Cost tier differentiation separates commodity industrial consumption from premium electronics-grade qualification pipelines.
- Industrial Use:Established refractory and glass manufacturing offtake dominates volume consumption with tolerance for moderate purity. Brazilian industrial carbonate channels remain underpenetrated by premium suppliers focused on European battery markets.
- Energy Storage:Solid-state battery developers are actively testing refined Gregoryite as a sodium-calcium carbonate precursor. This segment is expanding most quickly as electrolyte chemistry specifications crystallize ahead of commercial scale-up.
- Electronics:REACH substance registration requirements force full chain-of-custody documentation for battery-grade shipments entering European channels.
- Aerospace Components:Thermal barrier coating procurement demands ISO 14001 environmental management certification as a de facto entry requirement for European defense contractor supply chains.
Industrial Use retains volume leadership; Energy Storage demonstrates the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with institutional buyers consolidating purchasing through direct mine-to-lab relationships.
- Research Institutions:European university and national laboratory networks are displacing spot-market procurement for high-purity specimen volumes through dedicated supply lines.
- Defense Contractors:European thermal barrier coating procurement elevates ISO 14001 certification to mandatory status, filtering qualified suppliers.
- Technology Firms:Solid-state battery developers in Germany's Dresden corridor pilot hybrid purification systems to compress qualification timelines.
- Manufacturers:Refractory and glass producers across Latin America purchase through established industrial mineral trading channels.
Manufacturers represent the broadest installed base; Research Institutions are gaining share fastest through channel compression.
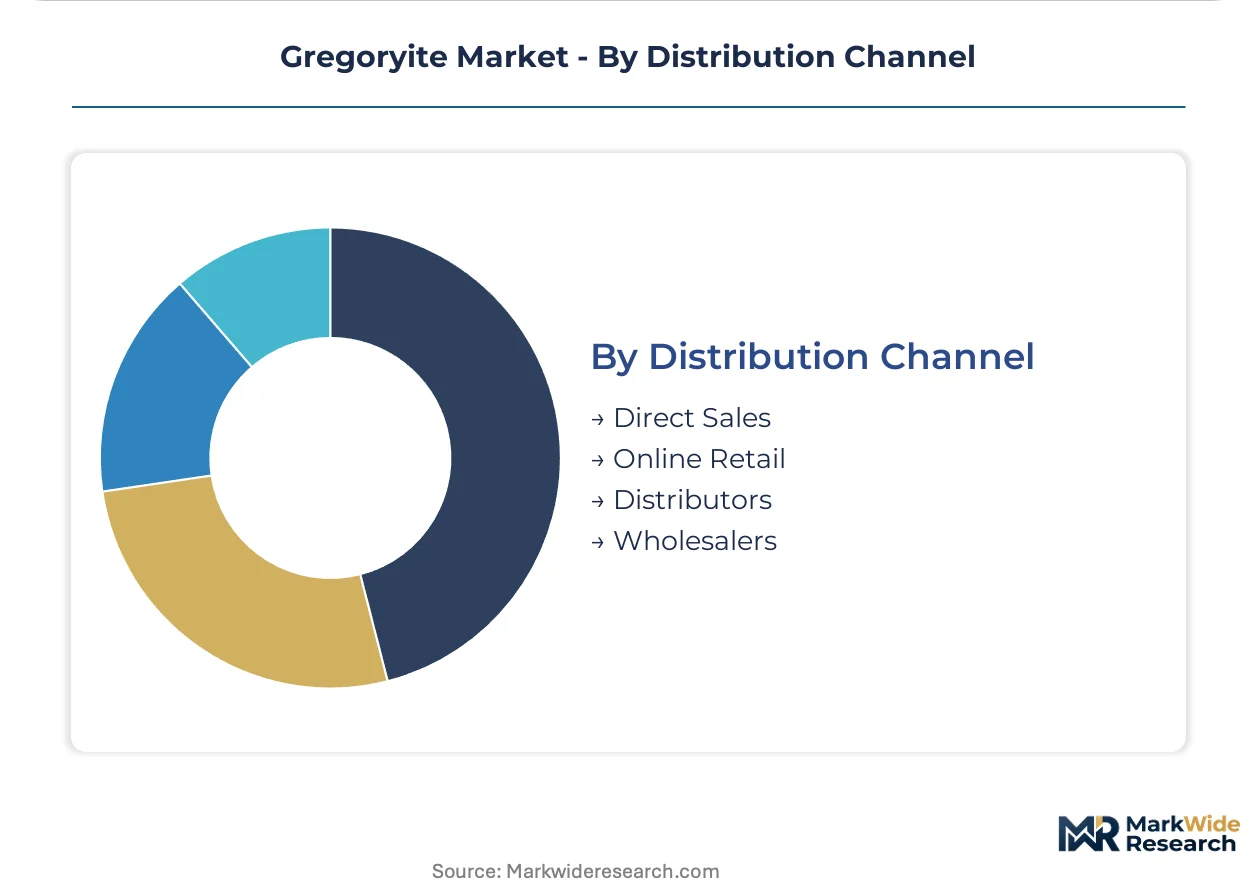
Distribution Channel:
Supply concentration among qualified processors shapes how material flows reach end users, with direct relationships displacing traditional trading intermediaries.
- Direct Sales:Weinrich Minerals Company leverages mine-to-lab relationships to sustain premium raw material flows into European research institutions, bypassing consolidated mineral traders.
- Distributors:R&M Minerals anchors North American distribution through specialized geological specimen networks serving qualified processor demand.
- Wholesalers:Volume-scale Latin American industrial carbonate channels move lower-purity feedstock to refractory manufacturers.
- Online Retail:Limited to small-lot specimen sales and educational material procurement.
Direct Sales commands the highest value flows; Distributors retain structural importance in fragmented North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Germany's precision ceramics corridor demands battery-grade refinement, while Brazilian industrial channels absorb lower-purity feedstock for refractory applications. This split between premium electronics-grade and commodity industrial consumption shapes regional competitive positioning.
Germany
Dresden's precision ceramics corridor anchors European demand for refined Gregoryite as solid-state battery developers qualify alternative carbonate electrolyte chemistries. REACH substance registration requirements force full chain-of-custody documentation for battery-grade shipments entering German industrial channels. Research institutions in Baden-Württemberg consolidate purchasing through direct mine-to-lab relationships that bypass traditional mineral trading houses.
China
SAMR's revised GB standards on carbonate mineral trace-element thresholds disqualify substantial raw feedstock lots from electronics-grade refinement pipelines. The dual carbon policy framework accelerates processor investment in low-carbon purification technologies that qualify for preferential market access. Yangtze River Delta processors face tightening MIIT purity mandates while scaling capacity for next-generation solid-state battery electrolytes.
United States
EPA monitoring of extraction site runoff under Clean Water Act provisions adds compliance layers for domestic Gregoryite processors. Specialized geological specimen networks anchor North American distribution through qualified processor relationships. The Mountain West region hosts alkaline igneous complex extraction operations subject to federal environmental oversight.
Brazil
Industrial carbonate channels across Latin America remain underpenetrated by premium refined Gregoryite suppliers focused on European battery markets. Refractory and glass manufacturing offtake dominates volume consumption with tolerance for moderate purity. São Paulo-based industrial mineral traders move lower-purity feedstock to regional manufacturers through established wholesale networks.
Kenya
East African carbonate mineral extraction is reconfiguring upstream supply dynamics for Gregoryite feedstock destined for European research institutions. Alkaline igneous complex deposits in the Rift Valley diversify raw material origins beyond traditional sources. Direct mine-to-lab relationships with European university networks are displacing spot-market procurement for high-purity specimen volumes.
Gregoryite Market Competitive Environment
Capability concentration sits with specialty mineral processors possessing direct mine-to-lab relationships; scale advantage sits with volume-oriented suppliers across Latin American industrial channels. The vendor base organizes around three strategic archetypes: premium refinement specialists, research-grade specimen distributors, and commodity industrial carbonate traders. Dominant competitive moves include capacity expansion for battery-grade purification and backward integration into East African feedstock extraction.
Among research-grade specimen distributors, Weinrich Minerals Company and R&M Minerals exemplify archetypes built on specialized channel relationships. Weinrich Minerals occupies a position within the direct mine-to-lab tier serving European institutional networks. R&M Minerals anchors North American distribution through geological specimen channels. Brazil Mineral Suppliers represents the scale-driven industrial carbonate archetype competing on volume across Latin American refractory markets.
| Leading Market Players |
|---|
| Weinrich Minerals Company |
| R&M Minerals |
| John Betts Fine Minerals |
| Allminerals LLC |
| Brazil Mineral Suppliers |
| Mexico Mineral Suppliers |
| Global Mineral Distributors |
| Regional Carbonate Mineral Producers |
| Specialty Mineral Processors |
| Others |
Value Chain & Pricing Dynamics
East African alkaline igneous complex deposits in Kenya and Tanzania concentrate upstream Gregoryite feedstock ownership among a handful of specialty mineral processors with direct mine-to-lab relationships, anchoring margin capture in the refined battery-grade purification tier where energy-intensive thermal processing creates natural barriers to entry.
Pricing Analysis
Long-term offtake contracts dominate refined Gregoryite procurement as solid-state battery developers lock in qualified supply ahead of commercial scale-up, while spot-market transactions persist for raw feedstock lots disqualified under China's SAMR revised GB trace-element thresholds. Price differentiation separates battery-grade volumes above 99.5 percent purity from industrial-grade material through ISO 14001 certification bundling and continuous technical support obligations. Cost compression in the raw feedstock tier is intensifying because East African extraction expansion outpaces qualified processor capacity, squeezing margins for non-integrated traders. Research institutions demonstrate the lowest price sensitivity due to dedicated supply line premiums, while Latin American refractory manufacturers remain highly sensitive to volume-scale discounts.
Supply Chain Analysis
Extended payment terms from German precision ceramics manufacturers are forcing working capital strain upstream as REACH substance registration compliance elevates documentation costs for non-integrated traders. Supply concentrates in Kenya, Tanzania, and Germany, with raw material flows drawing from alkaline igneous complex extraction and controlled thermal processing inputs. Single-source vulnerability sits with the handful of specialty mineral processors qualified for battery-grade refinement. Distribution runs through direct mine-to-lab relationships for premium research-grade volumes, while consolidated industrial mineral traders handle Latin American refractory channel offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gregoryite procurement is evolving into a service-attach business as continuous certification maintenance and technical support for battery-grade refinement expand faster than hardware margins on raw material extraction.
For Market Incumbents: Insulate qualified processor positions by deepening backward integration into East African alkaline igneous complex extraction and accelerating ISO 14001 certification renewal cycles before China's dual carbon policy framework disqualifies additional feedstock lots. Flash calcination hybridization represents the priority R&D lever for compressing qualification timelines against substitute carbonate electrolyte chemistries. For New Entrants and Emerging Players: Pursue Brazilian industrial carbonate channels where refractory and glass manufacturing offtake remains underpenetrated by premium refined Gregoryite suppliers fixated on European battery markets. Direct specimen network distribution offers a defensible go-to-market angle around high-purity research-grade volumes serving university and national laboratory procurement consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward specialty mineral processors with captive East African feedstock positions and established direct mine-to-lab relationships serving German precision ceramics corridors. The signal to watch is qualification velocity under China's evolving dual carbon policy framework as an inflection indicator for which purification technologies secure preferential market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into East African Extraction | Captive supply from Kenya and Tanzania insulates against SAMR disqualification risk. |
| Flash Calcination Technology Deployment | Hybrid purification compresses qualification timelines for Dresden corridor developers. |
| ISO 14001 Certification Acceleration | Mandatory status in European defense contractor supply chains filters qualified suppliers. |
| Direct Mine-to-Lab Relationship Expansion | Bypasses consolidated mineral traders for research-grade specimen volume capture. |
| Long-term Offtake Agreement Structuring | Locks in solid-state battery developer demand before incumbent supply commitments harden. |
Study Parameters
Initial hypotheses were tested against primary input from specialty mineral processor technical directors, solid-state battery developer procurement leads, East African extraction site operators, and German precision ceramics manufacturing engineers, then refined through secondary validation against customs trade data, MIIT GB standard revision filings, SEC 10-K disclosures from listed mineral processors, and REACH substance registration dossiers. Bottom-up volume triangulation across purity grades and applications was cross-checked against top-down market sizing from identified processor capacity.
Demand-supply balance modeling across the analysis window segmented by product type, application, end user, and distribution channel, with CAGRs derived from regression analysis of historical volume trajectories and forward-looking qualification pipeline visibility. Forecast inputs incorporated solid-state battery electrolyte chemistry specification crystallization timelines and China's dual carbon policy framework implementation velocity.
Sensitivities concentrate around SAMR trace-element threshold enforcement intensity and flash calcination technology qualification rates. Forecasts reflect documented assumptions on processor capacity expansion and battery-grade purity achievement timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Bauxite Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Zellerite Market