
 Global Artificial Rutile Market | 2026-2036
Global Artificial Rutile Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Rutile Market Foresight
A shift from single-source ilmenite dependency toward multi-source titanium feedstock strategies is rebalancing procurement patterns across the value chain. Iluka Resources leverages its integrated mineral sands operations to secure upstream supply control. Tronox sustains competitive positioning through chloride-process expertise spanning Western Australia and the United States. Rio Tinto anchors long-term offtake relationships with Asian pigment manufacturers through its QIT Madagascar Minerals operation.
Artificial rutile is a titanium dioxide-rich material produced by upgrading ilmenite through reduction and leaching processes, typically containing 90-97 percent TiO2, serving primarily as a chloride-process feedstock for titanium pigment and titanium metal production. Synthetic rutile dominates value capture due to its superior TiO2 content and compatibility with premium chloride-route pigment manufacturing, while metallurgical grade occupies a narrower niche serving welding electrode and specialty alloy applications. The ilmenite upgrading segment leads volume throughput, though chloride-process output commands the widest margin pool as paint producers and chemical manufacturers prioritize high-purity feedstock consistency.
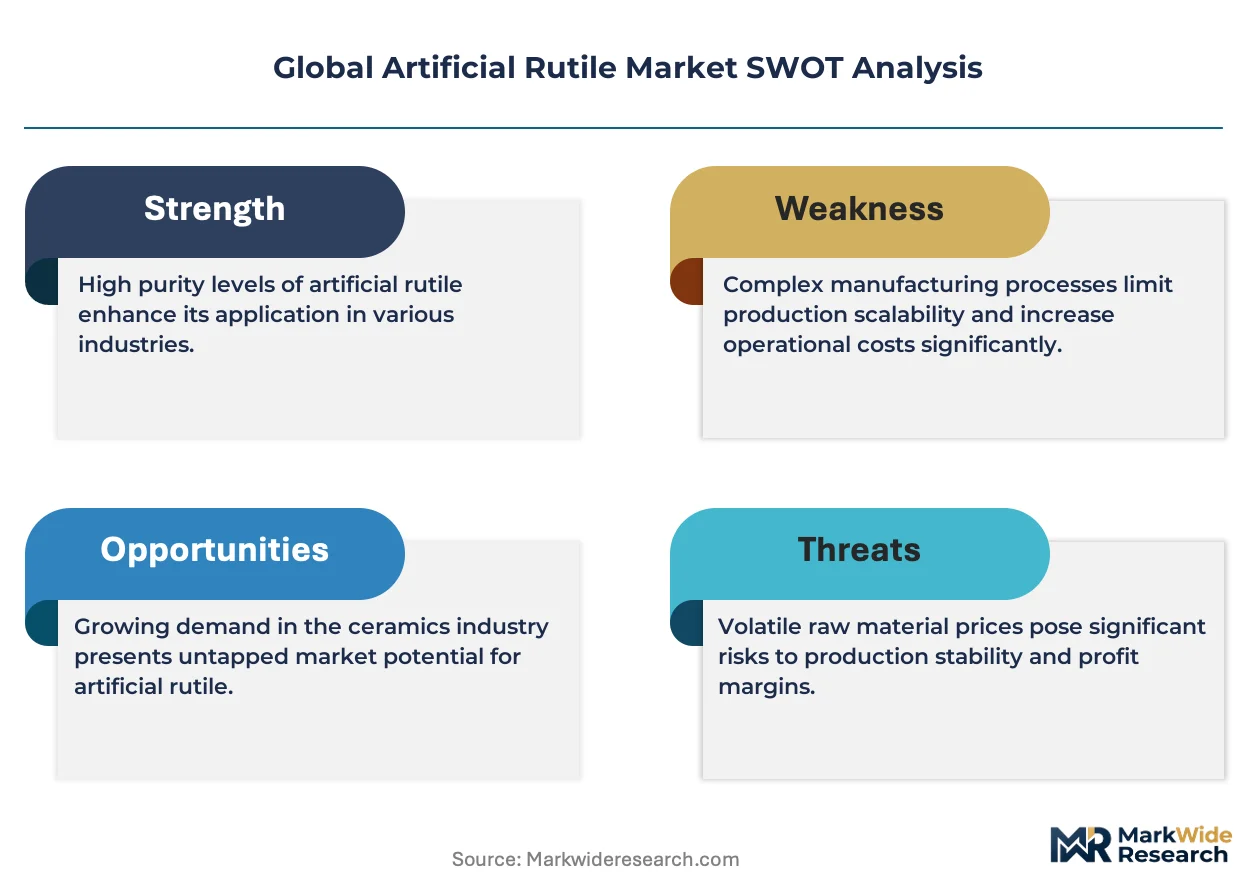
The US EPA enforces stringent tailings and emissions standards at synthetic rutile facilities, pushing operators toward closed-loop acid regeneration systems. Australia's environmental regulators impose rehabilitation bonds on mineral sands miners, embedding restoration costs into project economics. REACH compliance in Europe restricts certain processing chemicals, redirecting trade flows toward certified producers. Stakeholders must monitor feedstock cost spreads between sulfate and chloride routes, as this differential determines artificial rutile's competitiveness against natural rutile and titanium slag alternatives.
Market Dynamics
Paint manufacturers are accelerating feedstock diversification away from sulfate-route titanium dioxide toward chloride-process compatible materials, compressing procurement cycles and rewiring long-term supply agreements across the titanium value chain.
Growth Catalysts
- Chloride-process pigment demand:Paint producers in North America and Europe prioritize synthetic rutile for its superior TiO2 consistency and lower waste generation compared to ilmenite alternatives.
- China's MEE environmental standards:Tightening emissions controls on ilmenite smelting operations are redirecting domestic capacity toward cleaner upgrading technologies with higher synthetic rutile yields.
- Becher process improvements:Advanced reduction-leaching systems are lowering energy intensity per ton of artificial rutile produced, improving project economics for new capacity investments.
Market Restraints
- Natural rutile price volatility:Fluctuations in Sierra Leone and South African natural rutile spot markets create feedstock cost uncertainty that compresses synthetic rutile margin premiums.
- Australian supply concentration:Western Australia's mineral sands corridor hosts over 70 percent of synthetic rutile nameplate capacity, exposing buyers to single-geography disruption risk.
- High-purity ilmenite scarcity:Depletion of easily upgradable feedstock deposits in India and Sri Lanka is forcing operators toward lower-grade sources with higher processing costs.
Strategic Opportunities
- Saudi Arabia industrialization:The Kingdom's minerals downstream strategy under Vision 2030 is creating greenfield synthetic rutile demand from planned titanium sponge and pigment complexes.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases used in certain titanium processing routes are creating competitive openings for chloride-process feedstock suppliers.
- Digital trading platforms:Spot market liquidity for titanium feedstocks is improving through specialized commodity exchanges, enabling price discovery for mid-tier consumers.
Industry Challenges
- Acid regeneration expertise:Closed-loop hydrochloric acid recovery systems require specialized chemical engineering talent that concentrates among a handful of technology licensors.
- Rehabilitation bonding requirements:Australian state regulators mandate upfront financial assurances for tailings facility closure, tying up capital across multi-decade project horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Rutile Market |
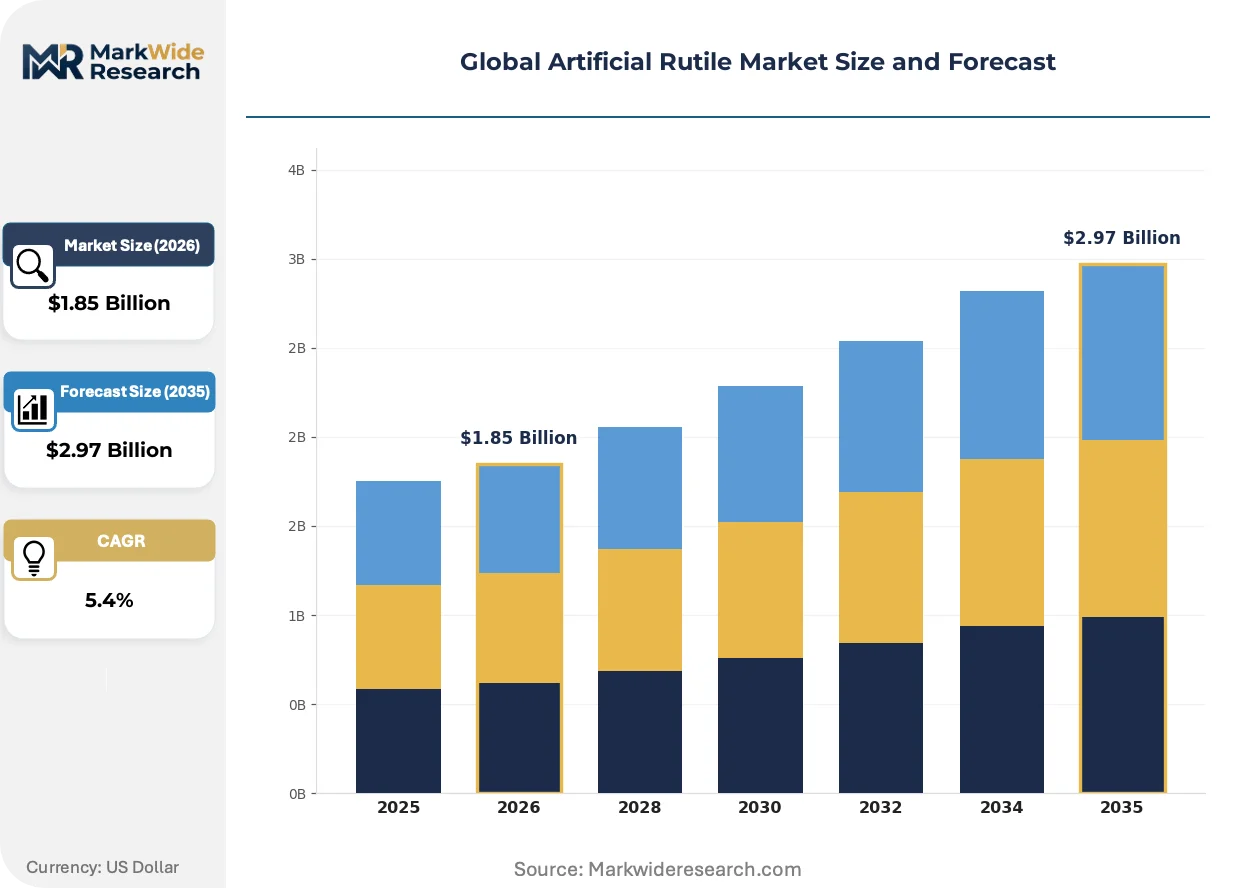
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Rutile, Metallurgical Grade, Pigment Grade, Specialty Grade Application: Welding Electrodes, Ceramic Coatings, Foundry Sands, Refractory Materials, Paper Coatings End User Industry: Metal Fabricators, Ceramic Manufacturers, Foundries, Paint Producers, Paper Mills Manufacturing Process: Ilmenite Upgrading, Titanium Slag Production, Sulfate Process, Chloride Process |
| Companies Covered | Iluka Resources Limited, Tronox Holdings plc, Rio Tinto Group, The Chemours Company, Base Resources Limited, Cristal Global, TiZir Titanium and Iron, Kerala Minerals and Metals Ltd, Lomon Billions Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Rutile Market Shifts & Advancements
Process intensification and environmental compliance automation are redefining competitive advantage in synthetic rutile production, separating capital-efficient operators from legacy asset owners.
Electrothermal reduction technology is converging with advanced leaching controls to enable direct processing of lower-grade ilmenite without intermediate beneficiation steps. Mid-scale pigment producers in Southeast Asia are piloting these integrated systems to bypass traditional upgrade bottlenecks. The technology is converging with digital process optimization platforms that compress energy consumption per ton while maintaining 94-plus percent TiO2 purity specifications.
The US EPA's tailings integrity standards are forcing facility redesigns toward dry-stack deposition and zero-discharge water circuits. Operators face capital outlays for secondary containment and real-time monitoring infrastructure that add 12-18 months to permitting timelines. Synthetic rutile producers in Florida and coastal Georgia are most exposed, with some redirecting expansion capital toward Australian jurisdictions with established regulatory frameworks.
Long-term offtake contracting is giving way to indexed pricing with shorter renewal cycles as buyers seek flexibility amid feedstock route uncertainty. Titanium sponge manufacturers in Japan and aerospace alloy producers are leading this shift, replacing 5-7 year fixed-price agreements with 18-24 month contracts tied to chloride-sulfate spread differentials. The pattern is most pronounced in spot market activity through Singapore and Rotterdam trading hubs.
Global Artificial Rutile Market Segmentation
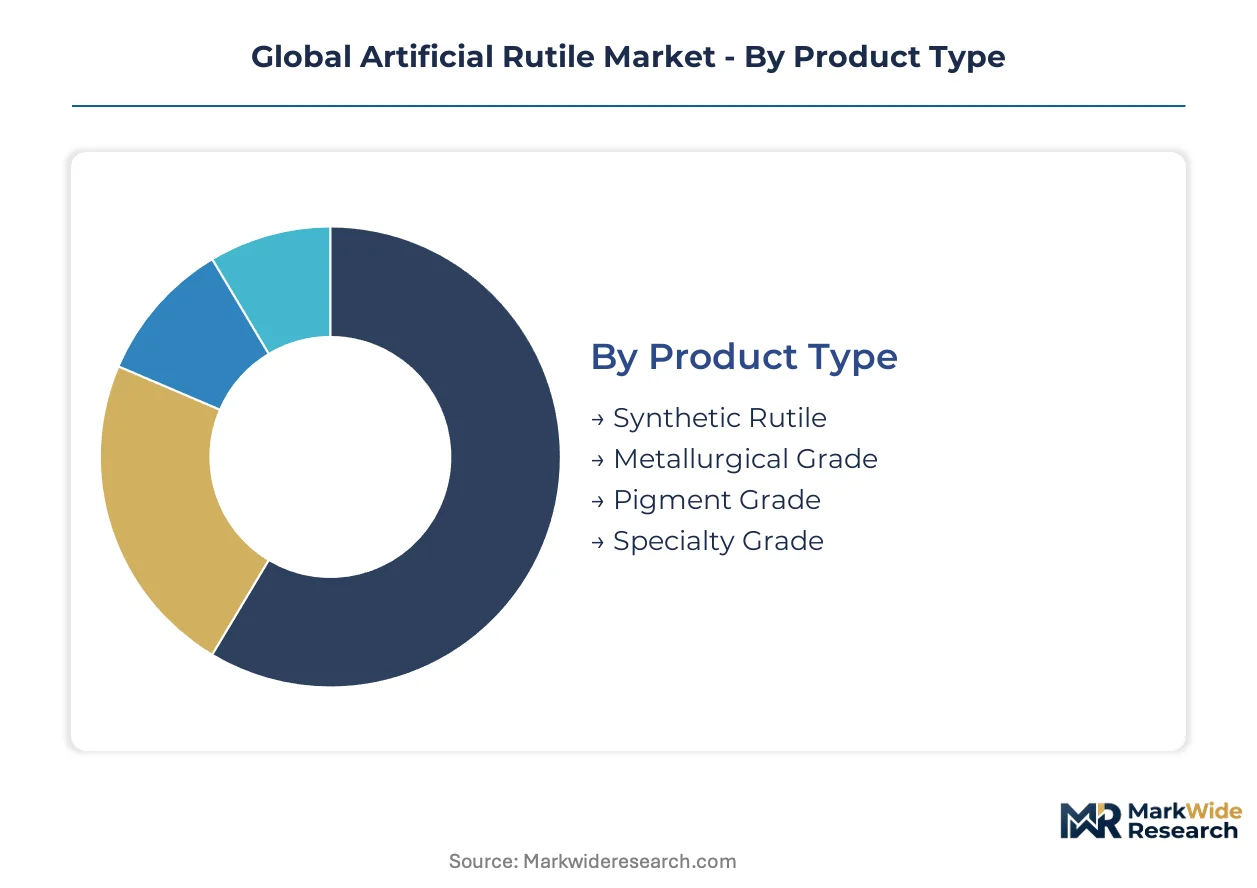
Feedstock chemistry and process route compatibility determine artificial rutile value capture across the titanium value chain. Segmentation reveals how TiO2 purity thresholds and chloride-process economics concentrate procurement decisions among pigment producers and specialty metal fabricators.
Product Type:
Capital intensity escalates with TiO2 purity requirements, as higher-grade segments demand sophisticated reduction-leaching infrastructure and acid regeneration systems.
- Synthetic Rutile:Contains 90-97 percent TiO2 through ilmenite reduction and acid leaching, serving as the primary chloride-process feedstock. Demand concentrates among paint producers in North America and Europe seeking consistent high-purity input for premium titanium dioxide pigment manufacturing.
- Pigment Grade:Engineered to exacting TiO2 specifications for chloride-route compatibility, commanding the widest margin pool across artificial rutile categories. Procurement from Tronox and Iluka Resources anchors long-term supply relationships with Asian pigment manufacturers.
- Metallurgical Grade:Serves welding electrode and specialty alloy applications with moderate purity requirements.
- Specialty Grade:Targets niche aerospace and medical titanium sponge production with ultra-low impurity thresholds.
Synthetic rutile absorbs the bulk of installed capacity; pigment grade is expanding most quickly.
Application:
End-use diversification spreads across industrial manufacturing sectors with varying technical specifications and volume profiles.
- Welding Electrodes:Metallurgical-grade artificial rutile provides arc-stabilizing coatings for consumable electrodes. Foundries in Germany and Japan source this material for high-performance structural welding applications.
- Ceramic Coatings:Specialty grades enable thermal barrier protection in turbine components and industrial kilns.
- Foundry Sands:Synthetic rutile's refractory properties support precision casting molds for aerospace and automotive components.
- Refractory Materials:High-temperature stability makes artificial rutile suitable for furnace linings and crucible manufacturing.
- Paper Coatings:Pigment-grade material provides opacity and brightness in premium printing and packaging substrates.
Welding electrodes command steady baseline volumes; ceramic coatings are climbing the fastest as aerospace thermal management requirements intensify.
End User Industry:
Customer concentration patterns reflect downstream integration strategies and captive supply arrangements across the titanium value chain.
- Paint Producers:Chloride-process pigment manufacturers in the United States and Germany represent the dominant demand sink for high-TiO2 synthetic rutile, with procurement cycles compressing toward 18-24 month indexed contracts.
- Metal Fabricators:Welding electrode and specialty alloy producers source metallurgical grades through direct mill relationships.
- Ceramic Manufacturers:Thermal barrier coating specialists in Japan and France drive specialty grade specifications.
- Foundries:Investment casting operations consume foundry sand grades for precision component production.
- Paper Mills:Coated paper producers in Finland and Canada integrate pigment-grade material for brightness enhancement.
Paint producers anchor the largest procurement volumes; ceramic manufacturers are gaining share fastest on aerospace demand expansion.
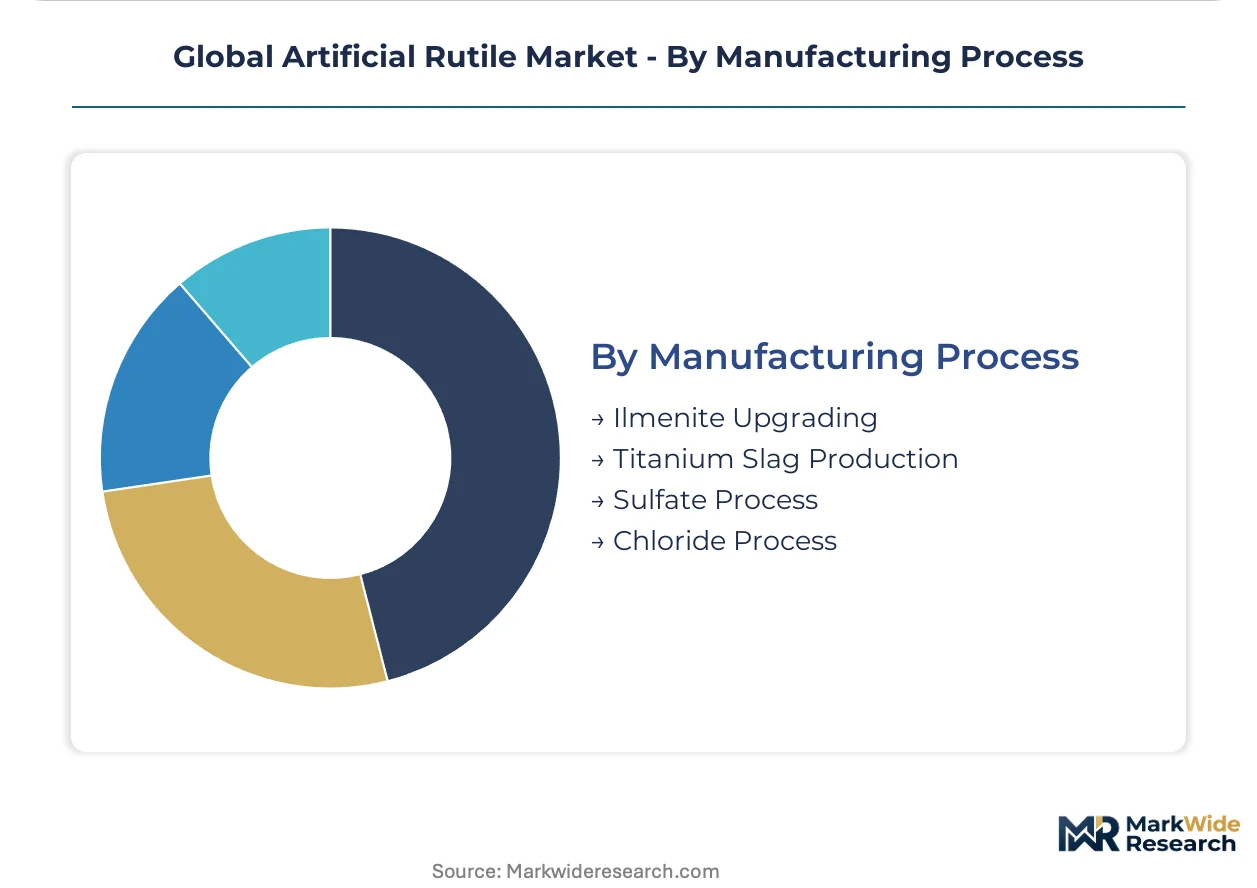
Manufacturing Process:
Process selection locks in feedstock flexibility, energy intensity, and regulatory compliance burdens for multi-decade asset lifecycles.
- Chloride Process:Synthetic rutile serves as the preferred feedstock for this premium pigment route, with US EPA tailings standards and EU F-Gas Regulation phase-downs reinforcing competitive positioning against sulfate alternatives.
- Ilmenite Upgrading:Becher process and reduction-leaching systems dominate volume throughput, with Australia's Western Australia corridor hosting the majority of nameplate capacity.
- Titanium Slag Production:Electric furnace smelting of ilmenite yields intermediate TiO2 content for blended feedstock strategies.
- Sulfate Process:Lower-purity ilmenite compatibility persists in legacy European and Chinese capacity, though environmental pressures are redirecting investment toward chloride-compatible upgrading.
Ilmenite upgrading holds the deepest installed base; chloride process output carries the steepest expansion trajectory as pigment producers prioritize waste minimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paint producers in Germany and the United States absorb the largest synthetic rutile procurement volumes, while mineral sands upgrading clusters in Australia and India concentrate upstream supply capacity. Regulatory pressures on chloride-process emissions and tailings management are fragmenting investment across multiple jurisdictions rather than consolidating it.
Australia
Western Australia's mineral sands corridor hosts the majority of synthetic rutile nameplate capacity, with Iluka Resources and Tronox operating integrated reduction-leaching facilities. The country's environmental regulators impose rehabilitation bonds on tailings facilities, embedding restoration costs into multi-decade project economics. Perth-based engineering clusters supply acid regeneration expertise to operators throughout the Pilbara and Southwest regions.
China
Domestic pigment manufacturers are redirecting capacity toward cleaner ilmenite upgrading methods as the MEE tightens emissions controls on legacy smelting operations. The dual carbon goals accelerate substitution of sulfate-route feedstock with chloride-compatible synthetic rutile. Shandong and Jiangsu provinces concentrate new upgrading investments near coastal titanium dioxide complexes.
United States
Chloride-process pigment producers in the Southeast source synthetic rutile through long-term offtake arrangements with Australian suppliers. The EPA enforces stringent tailings integrity standards that extend permitting timelines by 12-18 months for facility expansions. Florida and coastal Georgia host the remaining domestic synthetic rutile processing infrastructure.
Saudi Arabia
The Kingdom's minerals downstream strategy under Vision 2030 is creating greenfield demand from planned titanium sponge and pigment complexes. The national industrial development program offers preferential financing for chloride-process feedstock integration. Yanbu and Jubail industrial cities anchor projected synthetic rutile consumption growth.
India
Depletion of easily upgradable ilmenite deposits in Kerala and Tamil Nadu is forcing operators toward lower-grade feedstock with higher processing costs. State mineral development corporations face acid regeneration expertise gaps that limit capacity expansion. Odisha and Andhra Pradesh host emerging upgrading projects targeting domestic chloride-process demand.
Global Artificial Rutile Market Competitive Landscape
Capacity expansion dominates the current landscape as operators position for chloride-process pigment demand growth. The vendor base concentrates among integrated mineral sands majors and specialized titanium feedstock refiners, with limited mid-tier participation. Three archetypes define competitive positioning: upstream-integrated miners with captive ilmenite supply, chloride-process specialists with acid regeneration expertise, and diversified pigment producers securing backward feedstock control. Geographic expansion into Saudi Arabia and strategic partnerships with Asian offtakers represent the dominant competitive moves.
Among Australia-based integrated miners, Iluka Resources Limited and Tronox Holdings plc exemplify upstream-controlled competitive positioning, while Rio Tinto Group represents the diversified resources major archetype with titanium feedstock exposure through its Madagascar operation.
| Leading Market Players |
|---|
| Iluka Resources Limited |
| Tronox Holdings plc |
| Rio Tinto Group |
| The Chemours Company |
| Base Resources Limited |
| Cristal Global |
| TiZir Titanium and Iron |
| Kerala Minerals and Metals Ltd |
| Lomon Billions Group |
| Others |
Supply & Pricing Matrix
Becher process improvements and electrothermal reduction advances are compressing unit production costs while simultaneously concentrating supply among operators with capital to deploy closed-loop acid regeneration systems. This technology-driven cost restructuring reinforces pricing power for Australian integrated miners with captive ilmenite supply, while marginal producers in India and Florida face margin compression from higher compliance outlays.
Pricing Analysis
Long-term offtake contracts with acid regeneration service guarantees anchor premium pricing tiers, while spot-indexed agreements with minimal technical support occupy lower value bands. Price differentiation hinges on TiO2 consistency grades and chloride-process certification status, with pigment-grade synthetic rutile commanding substantial premiums over metallurgical alternatives. Pricing pressure stems from natural rutile spot volatility in Sierra Leone and South African markets, which compresses synthetic rutile margin premiums during feedstock cost spikes. Mid-tier pigment producers in Southeast Asia exhibit highest price sensitivity, while Japanese titanium sponge manufacturers prioritize supply security over unit cost optimization.
Supply Chain Analysis
Australia's domestic-content requirements for mineral sands beneficiation are reshaping procurement patterns among Asian pigment manufacturers seeking supply chain resilience. Production concentrates in Western Australia, China, and India, with ilmenite upgrading capacity anchored in the Pilbara and Southwest corridors. Feedstock supply draws from high-grade mineral sands deposits, hydrochloric acid regeneration infrastructure, and specialized reduction-leaching equipment. Single-geography concentration in Western Australia exposes buyers to disruption risk from cyclone activity or regulatory tightening. Distribution runs through long-term offtake agreements with Singapore and Rotterdam trading hubs providing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial rutile sector is navigating a chloride-process transition as paint producers abandon sulfate-route legacy capacity. Electrothermal reduction technology is displacing conventional Becher process investments, rewarding operators with integrated digital process optimization platforms.
For Market Incumbents: Cement supply security through backward integration into captive ilmenite deposits in Western Australia or Madagascar, insulating against high-purity feedstock scarcity. Invest in closed-loop acid regeneration certification to meet EPA tailings standards and EU F-Gas compliance requirements. Prioritize capacity modernization over geographic expansion to defend margin position against emerging electrothermal reduction specialists.
For New Entrants and Emerging Players: Engineering procurement contractors in Saudi Arabia's Vision 2030 industrial cities offer partnership pathways for greenfield synthetic rutile supply to planned titanium sponge complexes. Target underdeveloped chloride-process feedstock demand in Yanbu and Jubail, where domestic upgrading capacity remains nascent. Pursue technology licensing arrangements with Australian acid regeneration specialists rather than building proprietary chemical engineering capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated mineral sands majors with demonstrated chloride-process offtake relationships and rehabilitation bond compliance track records. Five-to-ten year viability favors operators with dual feedstock flexibility across synthetic rutile and titanium slag production. Monitor chloride-sulfate spread differentials at Singapore trading hubs as the inflection signal for feedstock route competitiveness shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ilmenite Supply | Iluka Resources and Tronox secure captive feedstock control against Indian deposit depletion. |
| Closed-Loop Acid Regeneration Deployment | EPA tailings compliance in Florida and Georgia demands capital outlays for secondary containment infrastructure. |
| Electrothermal Reduction Technology Licensing | Southeast Asian mid-scale producers bypass traditional upgrade bottlenecks through direct lower-grade ilmenite processing. |
| Long-Term Offtake Restructuring | Japanese titanium sponge manufacturers shift from fixed-price agreements to 18-24 month indexed contracts. |
| Saudi Arabia Greenfield Partnership | Vision 2030 minerals downstream strategy creates demand anchor for chloride-process feedstock suppliers. |
Research Methodology
Trade flow databases, mineral sands production reports, and SEC filings from publicly listed titanium feedstock operators formed the secondary backbone of this analysis. Primary interviews with plant managers at Western Australian reduction-leaching facilities, procurement leads at North American pigment manufacturers, and technical R&D directors specializing in electrothermal reduction systems validated demand assumptions and process economics. Bottom-up capacity modeling across ilmenite upgrading installations was cross-referenced with top-down titanium dioxide consumption estimates from paint producer associations.
Bottom-up modeling of installed reduction-leaching capacity and utilization rates was triangulated against top-down titanium pigment consumption forecasts across the projection horizon. Segmentation dimensions encompassed TiO2 purity grade tiers, end-use industry concentration patterns, manufacturing process route economics, and regional regulatory framework clusters. CAGRs were derived from supply-demand balance analysis incorporating feedstock cost spread dynamics and chloride-process capacity expansion pipelines. Forecast inputs included MEE emissions standard implementation timelines and Australian rehabilitation bond requirement trajectories.
Caveats apply where natural rutile spot price volatility, Chinese dual carbon policy acceleration, or unexpected ilmenite deposit depletion rates could materially shift the outlook. Forecasts reflect assumptions regarding Becher process energy intensity improvements and electrothermal reduction technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Garnet Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Mexico Mining Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Precious Metals E-Waste Recovery Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Sodium Tungstate Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market