
 Global Nickel Hydroxide Market | 2026-2036
Global Nickel Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nickel Hydroxide Market Foresight
Specialty chemical distribution channels serving battery precursor supply chains is reconfiguring as cathode manufacturers seek direct offtake agreements with nickel hydroxide refiners. Umicore leverages its integrated battery materials platform to control precursor qualification workflows across European and Asian cell plants. Sumitomo Metal Mining Co., Ltd. anchors high-purity nickel hydroxide output through captive laterite-to-cathode pipelines in Southeast Asia. Jinchuan Group International Resources Co. Ltd. dominates Chinese domestic supply through integrated nickel sulfide refining and hydroxide precipitation capacity.
Nickel hydroxide is an inorganic compound with the formula Ni(OH)₂, typically produced as a green crystalline solid through co-precipitation of nickel salts with alkali hydroxides at controlled pH and temperature; it serves as the primary active material in nickel-metal hydride and nickel-cadmium battery cathodes, as well as a precursor for nickel-cobalt-manganese hydroxide used in lithium-ion cells. Battery grade material commands the dominant value share given stringent purity requirements for electric vehicle cathode precursors, while industrial grade applications in catalysts and pigments represent mature volume segments with compressed margin structures. Co-precipitation remains the prevailing production method for battery-grade output, though hydrothermal synthesis routes are gaining traction for specialized high-nickel cathode formulations requiring controlled particle morphology.
The EU Green Deal and associated battery passport regulations mandate full supply chain traceability for nickel hydroxide entering European cell manufacturing, while China's MEE enforces wastewater discharge limits on nickel salt refineries that elevate environmental compliance costs. EPA hazardous waste classifications in the United States affect spent nickel hydroxide catalyst disposal protocols across chemical processing industries. Stakeholders must monitor evolving cathode chemistry shifts toward higher nickel content versus solid-state alternatives that could alter precursor demand specifications.
Market Dynamics
Cathode chemistry evolution toward high-nickel NCM formulations is compressing qualification timelines for nickel hydroxide precursors, forcing refiners to synchronize particle morphology controls with cell manufacturer specifications.
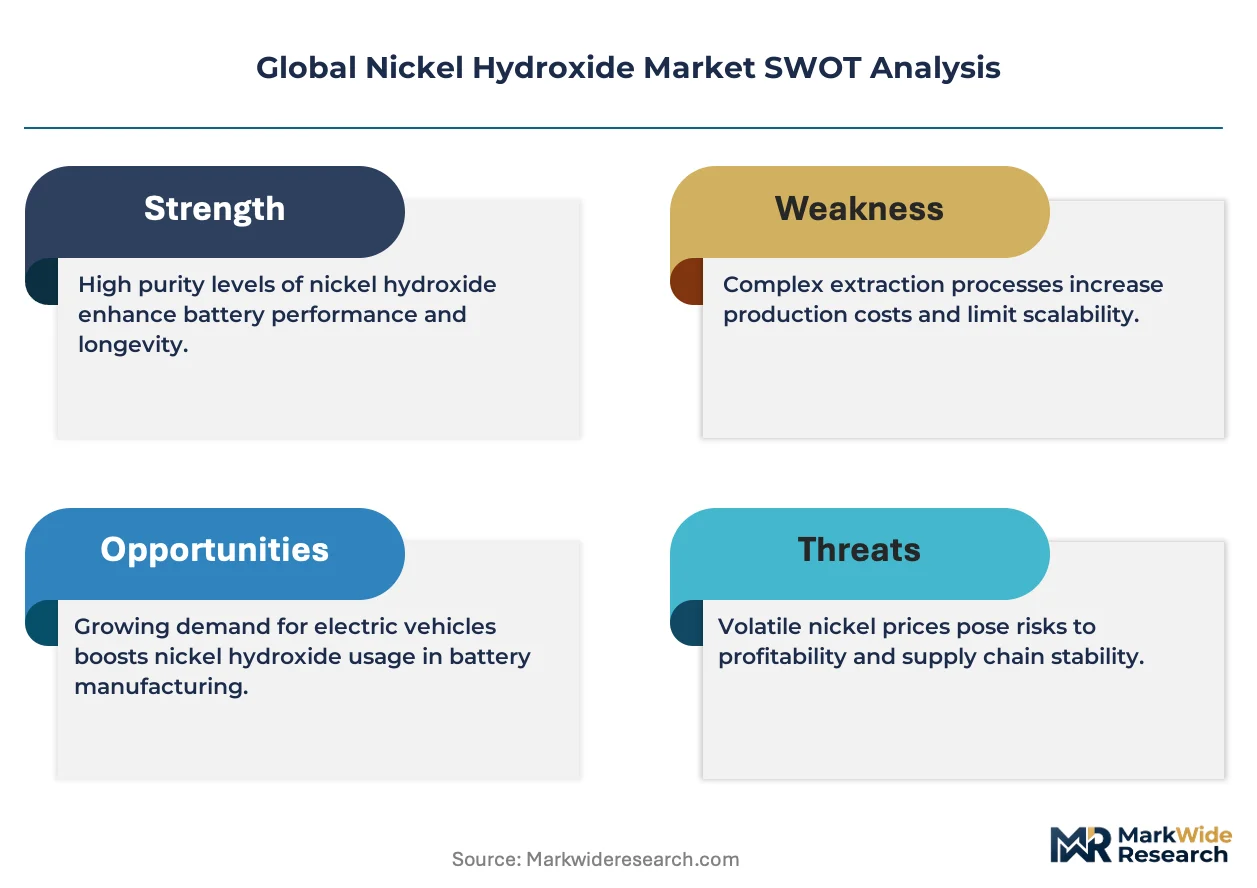
Growth Catalysts
- EU battery passport mandates:Full supply chain traceability requirements under the EU Green Deal are pulling certified nickel hydroxide volumes into European cell plants ahead of 2027 enforcement deadlines.
- Electric vehicle OEM cathode strategies:Battery manufacturers are locking multi-year offtake agreements directly with nickel refiners to secure precursor supply for high-nickel cathode formulations.
- China's dual carbon framework:MEE wastewater discharge limits on nickel salt production are accelerating consolidation toward integrated refiners with captive environmental compliance systems.
Market Restraints
- Laterite ore processing cost volatility:High-pressure acid leach capital intensity and sulfur input price swings constrain margin expansion for nickel hydroxide refiners serving battery-grade specifications.
- Indonesian supply concentration:Over 40% of global nickel laterite feedstock originates from Indonesian mining concessions, creating geopolitical and logistics vulnerability for hydroxide precipitation capacity elsewhere.
- Solid-state battery chemistry uncertainty:Lithium-metal and sulfide-based solid-state designs threaten to bypass nickel-rich cathode precursors entirely if commercialization timelines accelerate.
Strategic Opportunities
- North American battery supply chain localization:US Inflation Reduction Act critical mineral sourcing incentives are creating qualification pathways for nickel hydroxide refiners establishing precipitation capacity in Canada and the United States.
- Recycling-derived nickel hydroxide:Black mass hydrometallurgical recovery flows are enabling secondary nickel hydroxide production with lower carbon intensity credentials for ESG-sensitive cathode buyers.
- Stationary storage cathode diversification:Grid-scale battery manufacturers are specifying nickel-manganese-cobalt hydroxide precursors with modified stoichiometry, opening formulation customization services as a value-add segment.
Industry Challenges
- Particle size distribution engineering talent:Co-precipitation reactor optimization for specific D50 and span targets requires specialized chemical engineers in short supply across battery materials sectors.
- Multi-customer qualification backlog:Each cathode manufacturer demands bespoke impurity threshold validation, stretching analytical laboratory capacity and extending sales cycle timelines.
- Legacy nickel-cadmium demand erosion:Industrial battery OEMs are phasing out nickel hydroxide purchases for reserve power applications, forcing refiners to reconfigure customer mix toward lithium-ion precursor buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nickel Hydroxide Market |
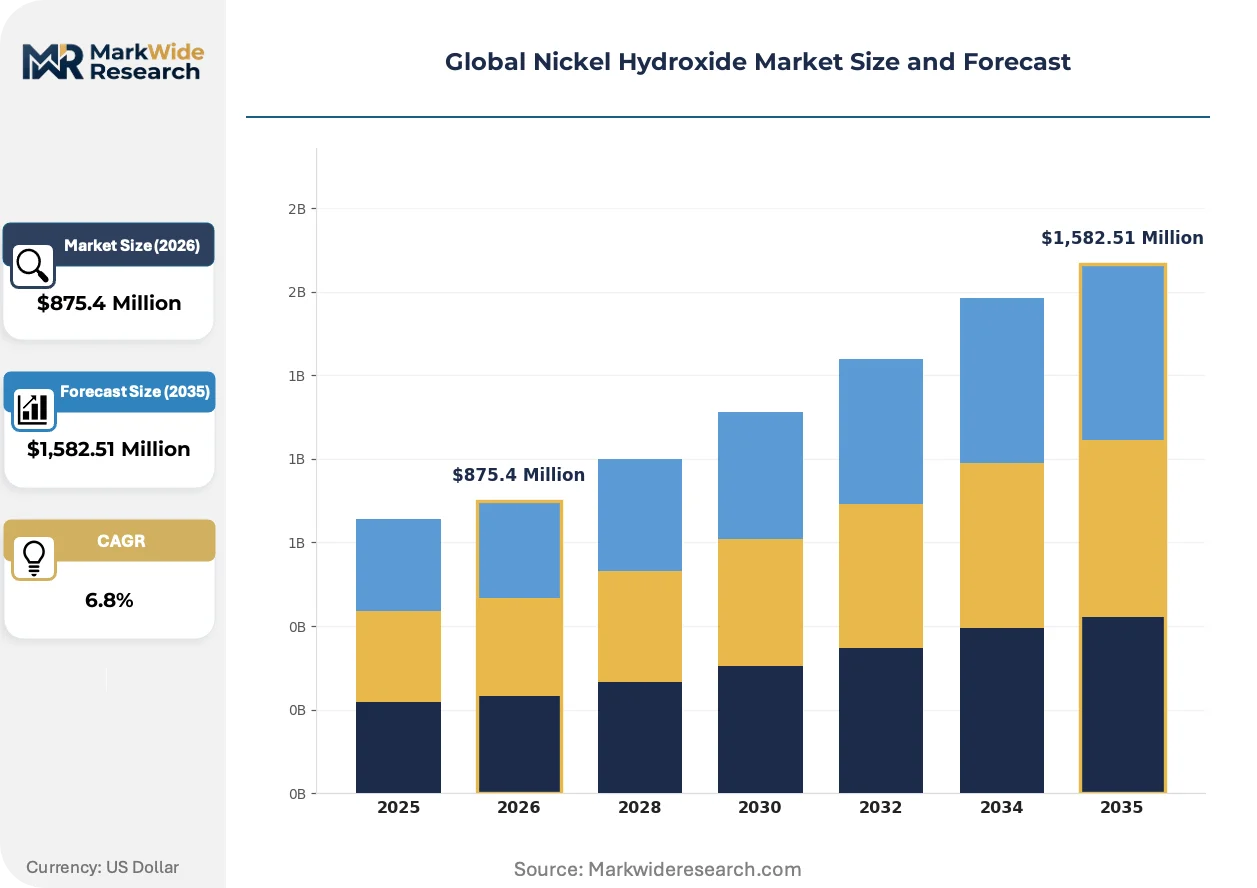
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,582.51 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Industrial Grade, Chemical Grade, Pharmaceutical Grade, Research Grade Application: Rechargeable Batteries, Catalysts, Pigments, Electroplating, Chemical Intermediates End User Industry: Consumer Electronics, Electric Vehicles, Aerospace Manufacturing, Chemical Manufacturing, Renewable Energy Production Method: Co-precipitation, Thermal Decomposition, Hydrothermal Synthesis, Sol-Gel Process, Electrodeposition |
| Companies Covered | Umicore, Tanaka Chemical Corporation, Sumitomo Metal Mining Co., Ltd., Kansai Catalyst Co., Ltd., Jilin Jien Nickel Industry, American Elements, Jinchuan Group International Resources Co. Ltd., Stanford Advanced Materials, Kishida Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nickel Hydroxide Market Shifts & Advancements
Continuous co-precipitation reactor designs and hydrothermal synthesis routes are rewriting process economics for battery-grade nickel hydroxide, while regulatory traceability mandates and direct refiner-to-cathode procurement models reshape commercial relationships.
Hydrothermal synthesis is collapsing the particle morphology control gap between laboratory specifications and volume production. Cell manufacturers in South Korea and Japan are qualifying hydrothermal nickel hydroxide for next-generation NCM 9-0.5-0.5 cathodes requiring tight primary particle size distribution. This technology is collapsing the traditional 18-month qualification timeline for new precursor suppliers by enabling precise control of tap density and specific surface area in single-reactor configurations.
REACH authorization requirements for nickel compounds are tightening purity documentation burdens on European importers. The regulation forces refiners to establish batch-level ICP-MS trace analysis for cobalt, copper, and zinc impurities below 50 ppm thresholds. Battery precursor buyers in Germany and Poland are responding by auditing Southeast Asian refiners for in-house analytical capabilities before contract execution.
Direct offtake contracting is displacing merchant market spot purchases across major cathode manufacturers. Tier-one cell producers in China's Jiangsu province are negotiating five-year supply agreements with fixed volume tiers and indexed pricing. This pattern is most visible in precursor procurement for cylindrical battery formats where cathode active material costs dominate cell bill-of-materials calculations.
Global Nickel Hydroxide Market Segmentation
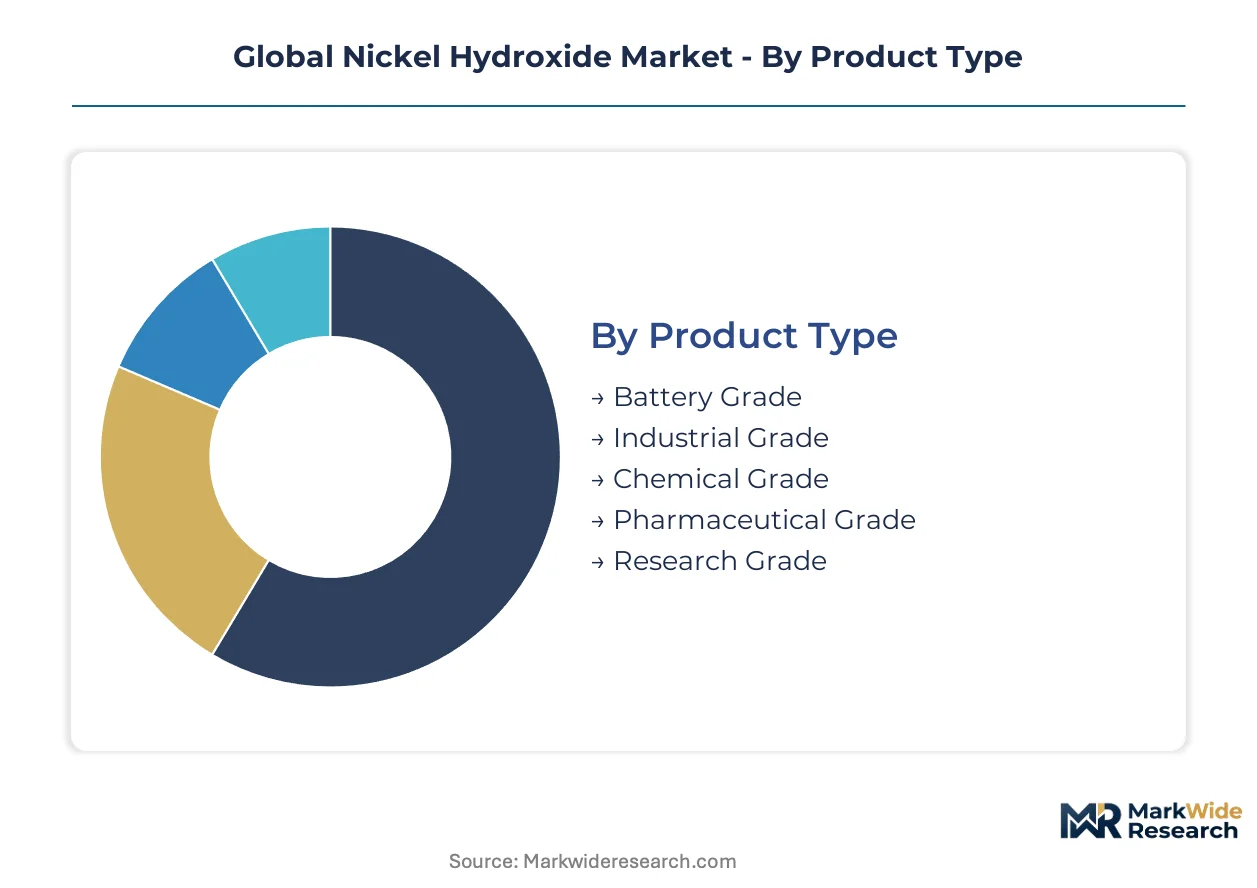
Nickel hydroxide procurement patterns diverge sharply across purity tiers and end-use specifications, forcing suppliers to maintain parallel qualification workflows. Cathode manufacturers impose distinct particle morphology requirements that reshape production method selection and pricing structures.
Product Type:
After-sales service intensity escalates with purity grade, as battery-grade customers demand batch-level analytical support and failure analysis capabilities throughout contract life.
- Battery Grade:Material meeting cathode precursor specifications requires sub-50 ppm impurity thresholds for cobalt, copper, and zinc. Demand concentrates in China's Jiangsu province, where integrated precursor-to-cell supply chains dominate regional cathode active material production.
- Industrial Grade:Lower-purity output serves catalyst and pigment applications with standardized quality documentation. Procurement concentrates among chemical processors in Germany's Ruhr industrial cluster, where REACH compliance documentation adds service overhead.
- Chemical Grade:Intermediate purity tier supplies nickel salt derivatives for electroplating baths and specialty chemical synthesis.
- Pharmaceutical Grade:Ultra-high purity material for drug formulation applications requires GMP-compliant manufacturing and extensive batch certification.
- Research Grade:Small-volume, high-variability specifications for academic and R&D laboratories carry premium pricing and minimal service obligations.
By volume, Industrial Grade leads. By growth pace, Battery Grade is ahead.
Application:
Application selection directly determines margin structure, with rechargeable battery precursors commanding triple the unit economics of pigment or catalyst applications.
- Rechargeable Batteries:Primary active material in nickel-metal hydride cells and precursor for NCM hydroxide in lithium-ion cathodes. Demand concentrates with South Korean cell manufacturers in Gyeonggi province, where cathode producers specify tight particle size distribution for high-energy-density formulations.
- Catalysts:Hydrogenation and methanation catalyst substrates require controlled surface area and porosity specifications. Procurement clusters among petrochemical refiners in Texas and Louisiana, where EPA hazardous waste classifications affect spent catalyst disposal protocols.
- Pigments:Nickel hydroxide-derived colorants for ceramics and glass applications represent mature volume with compressed margins.
- Electroplating:Decorative and functional nickel coating applications use lower-purity material with standardized bath chemistry requirements.
- Chemical Intermediates:Feedstock for nickel oxide, nickel sulfate, and other derivative compounds serves diversified industrial demand.
Rechargeable Batteries generates the dominant revenue share. Catalysts offer the most stable contract tenures.
End User Industry:
Customer concentration varies dramatically by sector, with electric vehicle OEMs consolidating procurement through direct refiner relationships while chemical manufacturing remains fragmented.
- Consumer Electronics:Cylindrical and prismatic battery demand from laptop and power tool manufacturers. Procurement concentrates with Japanese electronics OEMs in Osaka and Tokyo prefectures, where cell specifications prioritize cycle life over energy density.
- Electric Vehicles:High-nickel cathode precursor demand from automotive cell suppliers. Sourcing concentrates with CATL and BYD supply chains in China's Fujian and Guangdong provinces, where dual carbon goals reshape material qualification requirements.
- Aerospace Manufacturing:Specialized nickel-cadmium battery applications for aircraft emergency power systems require extensive certification documentation.
- Chemical Manufacturing:Diversified demand across catalyst, pigment, and intermediate applications with fragmented procurement patterns.
- Renewable Energy:Grid-scale storage systems specify modified NCM hydroxide stoichiometry for extended calendar life.
Electric Vehicles drives the steepest expansion trajectory. Consumer Electronics provides the most established qualification pathways.
Production Method:
Process selection locks in capital intensity and particle engineering capabilities, with co-precipitation dominating volume output while hydrothermal synthesis captures premium segments.
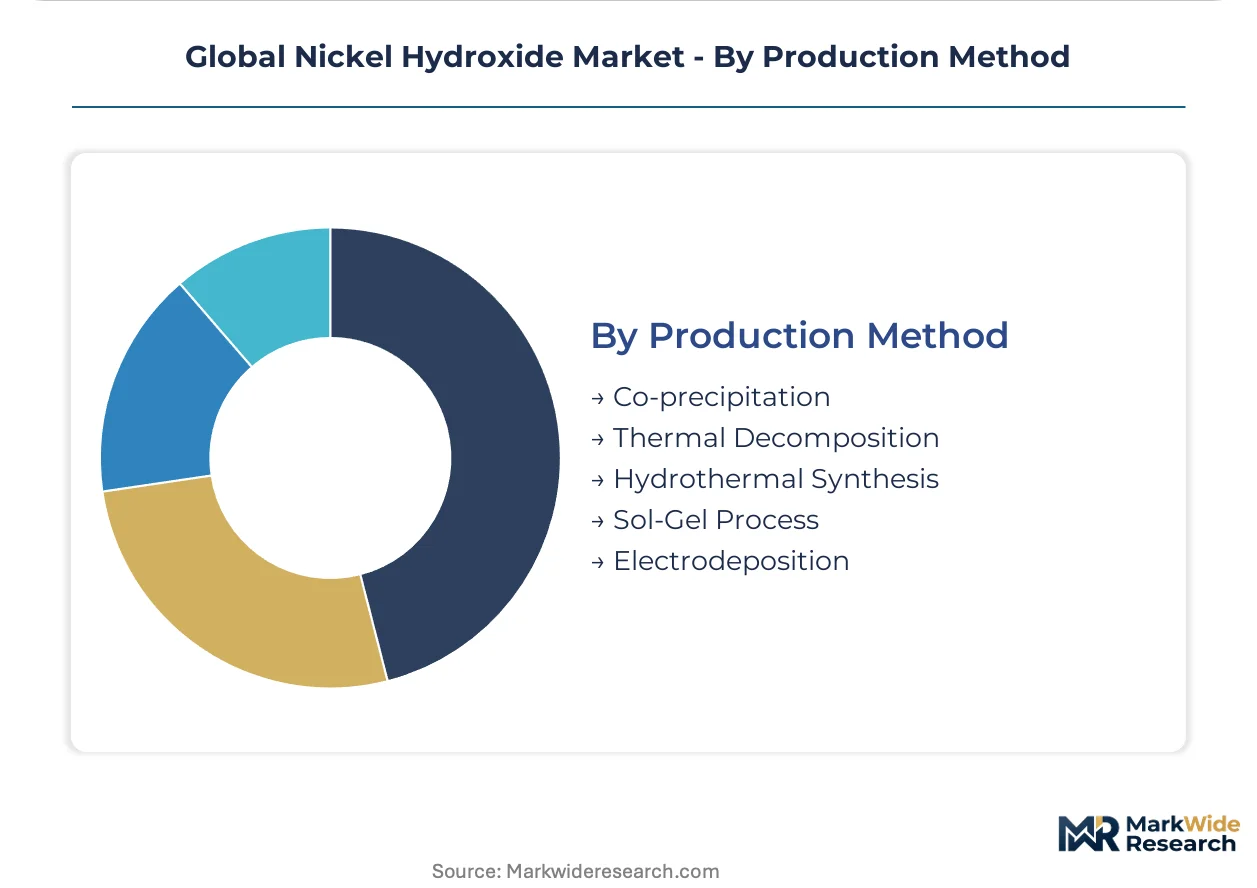
- Co-precipitation:Prevailing industrial method combining nickel sulfate with sodium hydroxide at controlled pH and temperature. Capacity concentrates among Chinese integrated refiners in Gansu and Xinjiang provinces, where captive nickel sulfide feedstock secures cost position.
- Hydrothermal Synthesis:High-pressure aqueous processing enables precise primary particle size control for next-generation cathode formulations. Adoption concentrates with South Korean and Japanese cell manufacturers qualifying material for NCM 9-0.5-0.5 cathodes requiring tight tap density specifications.
- Thermal Decomposition:Solid-state conversion of nickel salts for oxide precursor applications with limited battery-grade relevance.
- Sol-Gel Process:Specialized route for ultra-uniform particle distribution in research and pharmaceutical applications.
- Electrodeposition:Electrochemical synthesis for thin-film and coating applications with minimal battery material penetration.
Co-precipitation dominates current output volumes. Hydrothermal Synthesis is climbing the fastest as high-nickel cathode adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Inflation Reduction Act critical mineral sourcing incentives are redirecting nickel hydroxide procurement toward North American precipitation capacity. China's dual carbon framework and Indonesia's export policy shifts are reshaping Asian supply geography. European battery passport mandates are pulling certified volumes into regional cell plants ahead of 2027 enforcement.
China
Dual carbon goals from Beijing are accelerating consolidation toward integrated refiners with captive environmental compliance systems. MEE wastewater discharge limits on nickel salt production in Gansu and Xinjiang provinces are elevating costs for non-integrated operators. Cathode active material production clusters in Jiangsu and Zhejiang provinces dominate regional precursor demand.
United States
IRA critical mineral sourcing incentives are creating qualification pathways for nickel hydroxide refiners establishing precipitation capacity in Texas and Louisiana. EPA hazardous waste classifications affect spent catalyst disposal protocols across Gulf Coast petrochemical processors. Battery precursor demand concentrates with cell manufacturers scaling cylindrical format production in Nevada and Michigan.
Germany
REACH authorization requirements for nickel compounds are tightening purity documentation burdens on importers serving Ruhr industrial cluster catalyst consumers. ECHA batch-level ICP-MS trace analysis mandates for cobalt, copper, and zinc impurities below 50 ppm thresholds are stretching analytical laboratory capacity. Cathode precursor buyers in Poland are auditing Southeast Asian refiners before contract execution.
South Korea
Gyeonggi province cell manufacturers are specifying tight particle size distribution for high-energy-density cathode formulations. MFDS chemical safety regulations intersect with battery material import documentation requirements. Hydrothermal synthesis qualification for NCM 9-0.5-0.5 cathodes is collapsing traditional supplier onboarding timelines.
Indonesia
Mining concession policies concentrate over 40% of global nickel laterite feedstock, creating geopolitical vulnerability for hydroxide precipitation capacity elsewhere. Domestic downstream processing incentives are pulling refining investment toward Sulawesi and Halmahera industrial zones. Export restriction rhetoric periodically disrupts contract pricing for integrated Southeast Asian cathode supply chains.
Global Nickel Hydroxide Market Competitive Landscape
On the supply side, the industry is consolidating around integrated refiners with captive feedstock and environmental compliance systems. Merchant market spot purchases are contracting as direct offtake agreements displace traditional distribution channels. Three archetypes dominate: diversified mining conglomerates with downstream battery materials platforms, specialty chemical refiners focused on high-purity precipitation, and integrated precursor-to-cathode operators. Capacity expansion and backward integration into laterite processing represent the dominant competitive moves.
Within the diversified materials tier, Umicore and Sumitomo Metal Mining Co., Ltd. exemplify integrated battery materials platforms controlling precursor qualification workflows across European and Asian cell plants. Jinchuan Group International Resources Co. Ltd. anchors Chinese domestic supply through integrated nickel sulfide refining and hydroxide precipitation capacity.
| Leading Market Players |
|---|
| Umicore |
| Tanaka Chemical Corporation |
| Sumitomo Metal Mining Co., Ltd. |
| Kansai Catalyst Co., Ltd. |
| Jilin Jien Nickel Industry |
| American Elements |
| Jinchuan Group International Resources Co. Ltd. |
| Stanford Advanced Materials |
| Kishida Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Jiangsu province's integrated precursor-to-cell manufacturing clusters concentrate cathode active material output, translating supply-side tightness into asymmetric pricing power for qualified nickel hydroxide refiners serving battery-grade specifications. Direct offtake contracting is displacing spot market liquidity as tier-one cell producers negotiate multi-year agreements with indexed pricing tiers.
Pricing Analysis
Certification level creates the primary spread between battery-grade and industrial-grade nickel hydroxide, with REACH-compliant documentation and batch-level ICP-MS trace analysis commanding substantial premia from European cathode buyers. Contract-based long-term offtake agreements dominate procurement for high-nickel NCM formulations, while merchant spot purchases persist in pigment and catalyst applications. Pricing pressure stems from laterite ore processing cost volatility and sulfur input price swings compressing refiner margins. Industrial-grade buyers exhibit highest price sensitivity due to standardized quality requirements and fragmented procurement patterns, whereas electric vehicle OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming standard in cathode precursor procurement as cell manufacturers stretch working capital cycles. Nickel hydroxide supply concentrates in China, Indonesia, and South Korea, with Indonesian mining concessions anchoring over 40% of global laterite feedstock. Production draws from nickel sulfide refining capacity in Gansu and Xinjiang provinces, high-pressure acid leach operations in Sulawesi, and hydrothermal synthesis qualification lines in Gyeonggi province. Single-source vulnerability around Indonesian export policy shifts represents the dominant structural risk. Distribution runs through direct refiner-to-cathode relationships, bypassing traditional specialty chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through EU battery passport mandates and MEE wastewater compliance creates substantial switching costs for qualified suppliers.
For Market Incumbents: Pre-empt qualification backlogs by expanding in-house analytical laboratory capacity to compress multi-customer validation timelines. Secure backward integration into Indonesian laterite processing through joint venture structures to defend feedstock cost position against sulfur price volatility and HPAL capital intensity. Solid-state battery chemistry uncertainty represents the primary substitution threat requiring R&D hedging in lithium-metal anode adjacent materials. For New Entrants and Emerging Players: Establish a beachhead in North American precipitation capacity development, where IRA critical mineral sourcing incentives create qualification pathways absent entrenched competitor relationships. Recycling-derived nickel hydroxide from black mass hydrometallurgical recovery offers the most penetrable white-space segment, with ESG-sensitive cathode buyers prioritizing carbon intensity credentials. Lead with closed-loop material passports and batch-level traceability documentation as the go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated refiners with captive environmental compliance systems and established cathode manufacturer qualification relationships. Long-term viability hinges on five-to-ten year windows for high-nickel cathode chemistry dominance before solid-state alternatives mature. Target acquisition archetypes include Southeast Asian hydrothermal synthesis specialists and North American recycling-to-hydroxide operators. Watch solid-state battery commercialization timelines as the critical inflection signal for precursor demand specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laterite Processing | Captive Indonesian feedstock secures cost position against HPAL sulfur price volatility. |
| Hydrothermal Synthesis Capacity Expansion | South Korean and Japanese cell manufacturers qualify material for NCM 9-0.5-0.5 cathodes. |
| Black Mass Recycling-to-Hydroxide Infrastructure | Secondary production with lower carbon intensity credentials attracts ESG-sensitive cathode buyers. |
| In-House Analytical Laboratory Investment | Batch-level ICP-MS trace analysis compresses multi-customer qualification timelines. |
| Direct Offtake Agreement Structuring | Five-year supply contracts with indexed pricing displace merchant spot purchases. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through primary interviews with cathode active material procurement managers, nickel refinery plant managers, battery cell platform engineers, and specialty chemical distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K filings of diversified materials conglomerates, MEE wastewater discharge compliance records, and EU battery passport regulatory documentation. Bottom-up capacity and demand modeling was triangulated against top-down market sizing from production cluster analysis.
Calibration across the projection horizon employed multi-dimensional segmentation by purity grade, end-use application, production method, and regional production hub. CAGRs were derived from volume-weighted growth rate aggregation across segment-level forecasts. Industry-specific inputs included cathode chemistry evolution timelines for high-nickel NCM adoption, solid-state battery commercialization trajectory assessments, and Indonesian mining concession policy scenario modeling.
Stress conditions across laterite ore price volatility, sulfur input cost spikes, and solid-state battery substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and cathode manufacturer qualification workflows. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Recycled Steel Market
Metals & Minerals
Flake Graphite Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Garnet Market