
 Global Lubricants Market | 2026-2036
Global Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lubricants Market Outlook
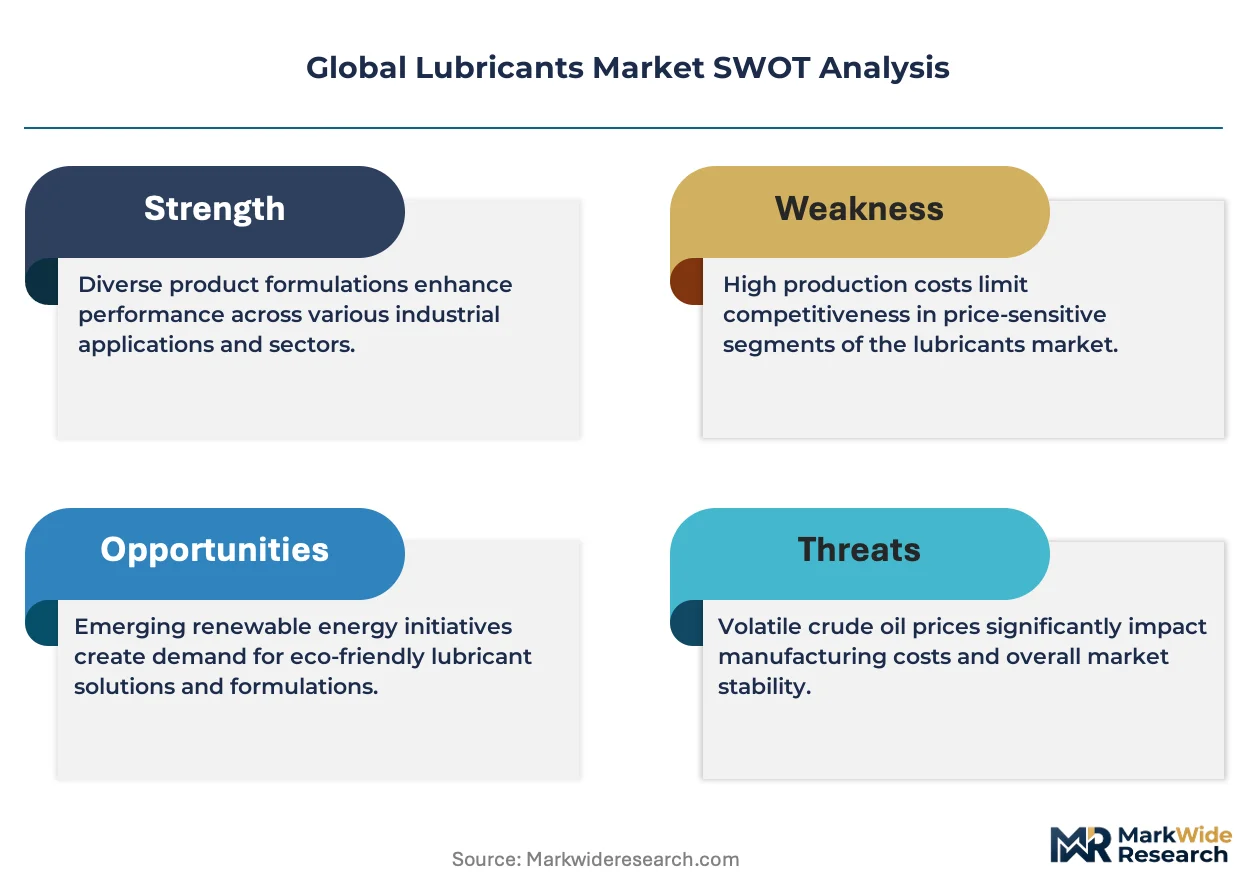
Synthetic base stocks are displacing Group I mineral oils in high-performance formulations, a material-substitution event that is realigning product economics across the value chain. Shell plc leverages backward integration into gas-to-liquids base oil production to sustain margin capture. ExxonMobil Corporation anchors its position through proprietary metallocene polyalphaolefin technology leadership. FUCHS Group specializes in application-specific industrial lubricants, competing on engineering service density rather than commodity volume.
Lubricants are formulated fluids comprising base oils—mineral, synthetic, or bio-derived—combined with functional additive packages to reduce friction, dissipate heat, and prevent wear in mechanical systems; their performance grades are defined by viscosity indices, oxidation stability, and pour-point specifications per ASTM and SAE protocols. The automotive application segment dominates value generation due to OEM fill requirements and aftermarket service intervals, while biodegradable lubricants represent the fastest-growing product type as environmental compliance tightens across marine and energy end users. Mineral oil formulations remain the largest volume category but face structural compression from synthetic alternatives in manufacturing and transportation sectors where equipment uptime costs dominate lubricant procurement decisions.
EPA fuel economy standards in the United States, REACH chemical registration requirements in Europe, and China's GB national standards administered by SAMR collectively shape formulation chemistry, product labeling, and market access conditions for lubricant suppliers. The EU F-Gas Regulation and emerging MEE emissions controls in China are further restricting certain additive chemistries, redirecting R&D investment toward low-sulfur, low-ash, and bio-based alternatives. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to pursue platform formulations or region-specific product architectures.
Market Dynamics
Synthetic base stocks are compressing mineral oil economics while REACH and China's GB standards force simultaneous reformulation across multiple jurisdictions, creating a dual squeeze on legacy product architectures.
Growth Catalysts
- EV powertrain lubrication:Electric vehicle OEMs require specialized thermal management fluids for e-axles and battery cooling systems, opening formulation development pipelines previously dormant in conventional drivetrain portfolios.
- EU Green Deal acceleration:REACH registration requirements and F-Gas restrictions are mandating biodegradable marine lubricants and low-sulfur industrial formulations across European ports and manufacturing clusters.
- Industrial machinery density in China:SAMR-administered GB standards and MEE emissions protocols are synchronizing with automotive production volumes to anchor regional consumption growth in precision manufacturing lubrication.
Market Restraints
- Group I base oil supply concentration:Refinery closures in North America and Europe have tightened feedstock availability for mineral formulations, elevating input cost volatility for mid-tier blenders without captive supply.
- Metallocene PAO technical barriers:Proprietary catalyst technologies limit synthetic base oil production to vertically integrated majors, constraining independent formulator access to high-viscosity-index stocks.
- Biodegradable performance gaps:Vegetable-derived esters exhibit hydrolytic instability and oxidative weakness versus synthetic alternatives, restricting deployment in high-temperature turbine and hydraulic applications.
Strategic Opportunities
- India industrial penetration:BIS certification alignment with ISO viscosity grades and PLI scheme incentives for domestic manufacturing are creating formulation partnerships for foreign suppliers in Mumbai-Pune and Chennai industrial corridors.
- Wind turbine gearbox fluids:Offshore wind installation growth in the North Sea and Baltic is demanding synthetic PAO and polyalkylene glycol lubricants with 10-year service intervals and corrosion resistance specifications.
- Digital fluid monitoring convergence:Integration of IoT sensors with lubricant analysis services enables predictive maintenance contracts, shifting revenue from product volume to uptime-guarantee subscriptions in fleet and plant operations.
Industry Challenges
- Additive chemistry registration timelines:ECHA REACH dossier preparation and SAMR new chemical notification procedures extend product launch cycles by 18-36 months, compressing patent-protected revenue windows.
- Cross-jurisdictional formulation divergence:EPA low-ash requirements for gasoline direct injection engines, EU ACEA sequences, and China 6 emission standards are fragmenting product architectures and multiplying SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lubricants Market |
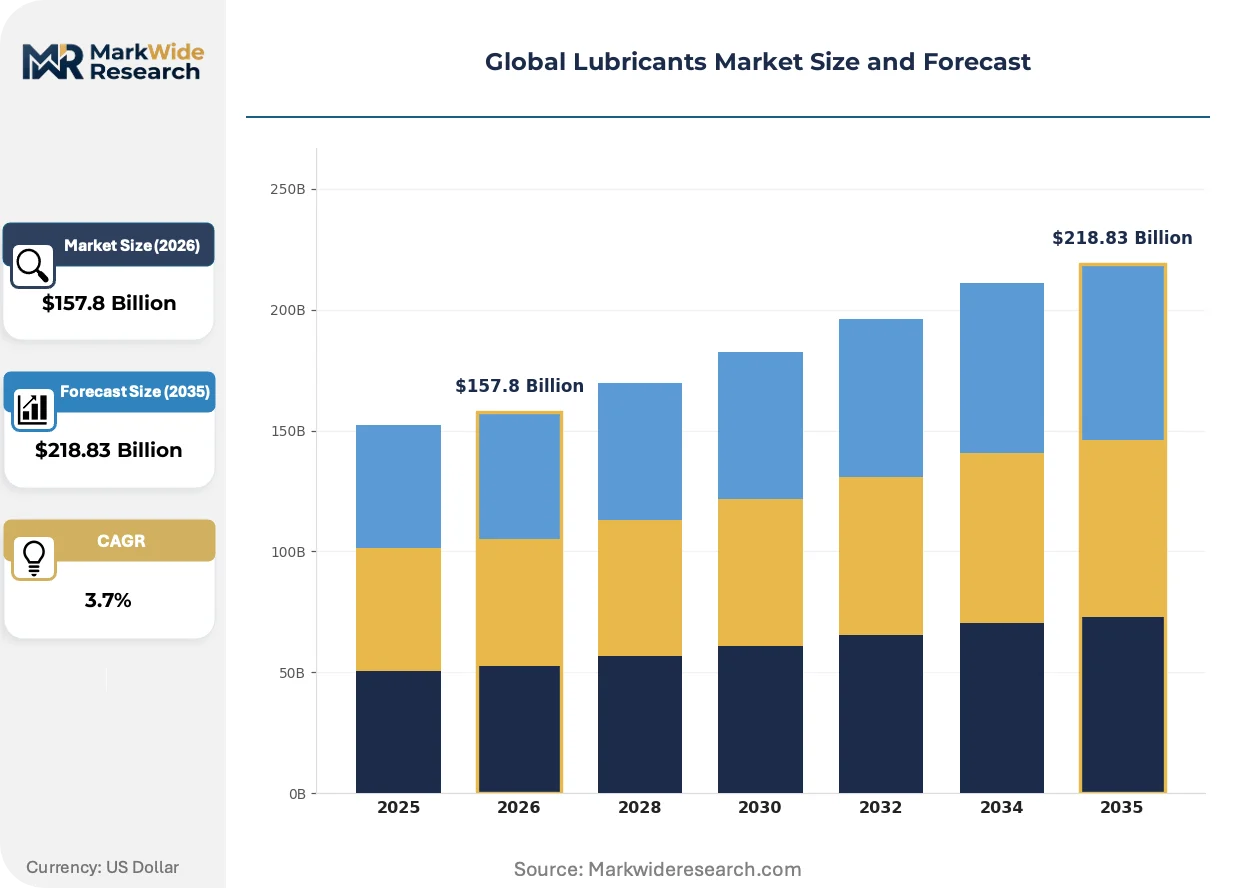
| Market Size in 2026 | $157.8 Billion |
| Market Size in 2035 | $218.83 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Biodegradable Lubricants, Additives Application: Automotive, Industrial Machinery, Marine, Aerospace End User: Manufacturing, Transportation, Construction, Energy Packaging Type: Drums, Pails, Bulk Containers, Aerosols |
| Companies Covered | Shell plc, ExxonMobil Corporation, TotalEnergies SE, BP plc, Chevron Corporation, FUCHS Group, PetroChina Company Limited, Sinopec Lubricant Company, Valvoline Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lubricants Market Strategic Shifts
Formulation chemistry and service delivery models are diverging simultaneously as environmental compliance tightens and equipment OEMs consolidate fluid specifications around proprietary performance standards.
Gas-to-liquids base oils produced via Fischer-Tropsch synthesis deliver near-zero sulfur content and exceptional oxidation stability for extended drain intervals. Heavy-duty fleet operators in Germany and long-haul logistics networks across the US are specifying these stocks for 100,000-mile service cycles. This technology is overtaking Group II-plus mineral oils in premium commercial vehicle segments where total cost of ownership calculations dominate procurement decisions.
REACH authorization procedures and the EU F-Gas Regulation are restricting chlorinated paraffin and certain sulfur-phosphorus extreme-pressure additives in metalworking and gear applications. Industrial lubricant suppliers are redirecting R&D toward boron-nitride and ionic liquid alternatives that maintain film strength without persistent organic pollutant classification. Marine stern tube and hydraulic systems in European-flagged vessels face the most immediate substitution pressure.
Fluid analysis laboratories are unbundling from product sales, with independent service providers capturing used oil diagnostics and recommendation authority previously held by lubricant manufacturers. Fleet maintenance departments and power generation utilities in Japan and South Korea are outsourcing condition monitoring to third-party specialists. This restructuring concentrates specification influence with engineering service firms rather than branded product marketers.
Global Lubricants Market Segmentation
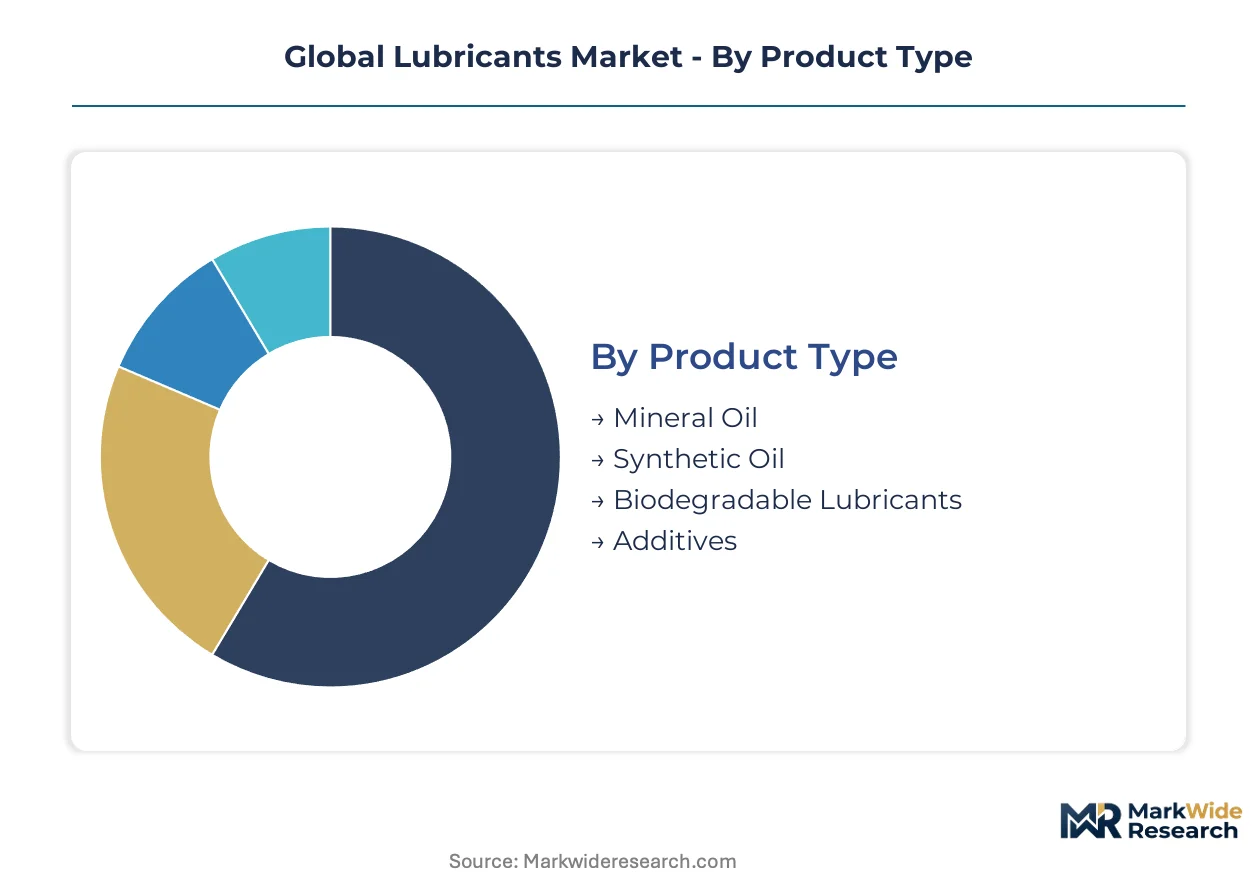
Segmentation in lubricants reveals how capital allocation, regulatory exposure, and technical performance requirements fragment demand across incompatible product architectures. Understanding these divisions exposes where formulation R&D investments concentrate and which customer relationships command premium pricing power.
Product Type:
Capital intensity escalates sharply from mineral refining through synthetic base stock production to biodegradable ester synthesis, with Fischer-Tropsch gas-to-liquids facilities requiring the heaviest upfront commitment.
- Mineral Oil:Derived from vacuum distillation and hydrotreating of crude petroleum fractions, these Group I-III base stocks dominate volume but face margin compression from refinery closures in the US and EU. Demand concentrates in emerging market fleet maintenance where drain interval extension remains secondary to unit cost.
- Synthetic Oil:Polyalphaolefins and polyalkylene glycols manufactured via metallocene catalysis or oligomerization deliver viscosity indices exceeding 140 and oxidation stability for 100,000-mile service cycles. German heavy-duty logistics operators and North American long-haul fleets specify these formulations where equipment downtime costs dwarf lubricant expenditure.
- Biodegradable Lubricants:Vegetable-derived esters and synthetic esters formulated for marine stern tube and hydraulic systems in EU-flagged vessels facing REACH and F-Gas restrictions.
- Additives:Detergent, dispersant, anti-wear, and viscosity modifier packages blended at 5-25% treat rates to meet ACEA, API, and OEM proprietary specifications.
Most installed capacity flows through Mineral Oil. Expansion is steepest in Biodegradable Lubricants.
Application:
Application segmentation tracks divergent equipment lifecycle economics, with aerospace and marine demanding certified supply continuity while automotive and industrial machinery reward formulation flexibility.
- Automotive:Engine oils, transmission fluids, and driveline lubricants specified by OEM fill requirements and service interval protocols. China's automotive production corridors in Shanghai and Guangzhou anchor regional consumption as domestic OEMs electrify powertrains and demand specialized thermal management fluids for e-axles.
- Industrial Machinery:Hydraulic fluids, compressor oils, and gear lubricants for metalworking, plastics processing, and precision manufacturing. German automotive component suppliers and Japanese machine tool builders specify premium synthetics where uptime guarantees dominate procurement.
- Marine:Cylinder oils, stern tube lubricants, and deck machinery fluids subject to IMO 2020 sulfur caps and EU port state biodegradable mandates.
- Aerospace:Gas turbine oils and hydraulic fluids certified to SAE AS5780 and MIL-PRF-23699 specifications with multi-year qualification timelines.
Automotive captures the largest revenue pool. Industrial Machinery is gaining share fastest in precision manufacturing clusters.
End User:
End user segmentation separates procurement behaviors: manufacturing and energy prioritize technical service density, while transportation and construction emphasize logistics reliability and field availability.
- Manufacturing:Automotive stamping plants, semiconductor fabrication facilities, and food processing operations requiring H1 food-grade or cleanroom-compatible formulations with contamination monitoring protocols.
- Transportation:Fleet operators, railroads, and aviation MRO facilities specifying lubricants through total cost of ownership models that weight fuel economy gains against fluid changeout labor.
- Construction:Earthmoving equipment and mobile cranes operating in ambient temperature extremes with irregular maintenance access, favoring high-viscosity-index mineral formulations with extended drain claims.
- Energy:Wind turbine operators in the North Sea and Baltic specifying 10-year service interval synthetic gear oils, plus combined cycle power plants requiring turbine oils with demulsibility and air release specifications.
Manufacturing commands the deepest technical engagement. Energy is expanding most quickly behind offshore wind installation growth.
Packaging Type:
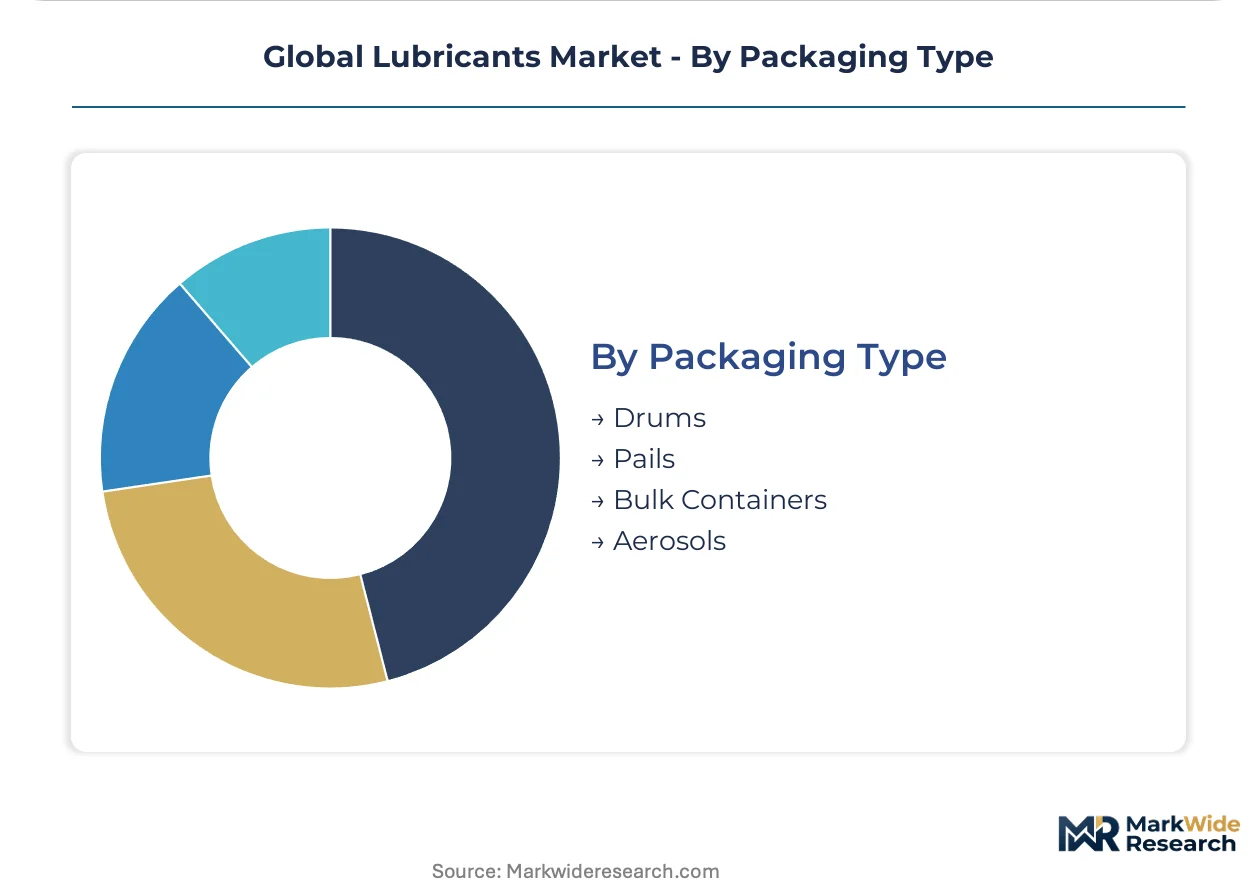
Packaging segmentation reflects supply chain economics: bulk delivery minimizes unit cost for high-volume consumers, while drums and pails preserve formulation integrity for specialized applications requiring contamination control.
- Drums:55-gallon steel containers dominating industrial and fleet distribution, with reconditioned drum programs reducing environmental compliance costs for EU and US customers.
- Pails:5-gallon plastic containers for maintenance shops and smaller manufacturing facilities requiring multiple product grades without bulk storage infrastructure.
- Bulk Containers:Tank trucks and flexitanks for direct-to-silo delivery at automotive assembly plants, refineries, and power generation stations where annual offtake exceeds 100,000 liters.
- Aerosols:Penetrating oils, chain lubricants, and release agents for maintenance technicians requiring precise application control in confined equipment spaces.
Bulk Containers move the greatest volume. Aerosols are climbing the fastest on maintenance outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive production corridors in Shanghai and Guangzhou anchor global lubricant consumption, with industrial machinery density and powertrain electrification driving formulation demand across precision manufacturing clusters.
China
Automotive OEMs in Shanghai and Guangzhou electrify powertrains, demanding specialized thermal management fluids for e-axles and battery cooling systems. SAMR-administered GB standards and MEE emissions protocols synchronize with production volumes. The Yangtze River Delta precision manufacturing belt anchors regional consumption in metalworking and industrial hydraulic applications.
United States
Heavy-duty fleet operators specify synthetic formulations for extended drain intervals where equipment downtime costs dominate procurement decisions. EPA fuel economy standards and low-ash requirements for gasoline direct injection engines redirect formulation chemistry. The Gulf Coast petrochemical corridor sustains base oil production infrastructure serving North American blenders.
Germany
Automotive component suppliers and machine tool builders demand premium synthetics with uptime guarantees. REACH authorization procedures and the EU F-Gas Regulation restrict chlorinated paraffin additives in metalworking applications. The Stuttgart automotive cluster and Ruhr industrial belt concentrate formulation R&D and precision manufacturing lubrication demand.
India
BIS certification alignment with ISO viscosity grades and PLI scheme incentives for domestic manufacturing attract foreign formulation partnerships. Industrial corridors in Mumbai-Pune and Chennai drive hydraulic and compressor oil consumption in automotive stamping and plastics processing. The country's national standards body tightens chemical registration timelines for new additive packages.
Japan
Fleet maintenance departments and power generation utilities outsource condition monitoring to third-party fluid analysis specialists. METI industrial standards and JIS specifications govern turbine oil and hydraulic fluid performance grades. The Nagoya automotive manufacturing cluster and Osaka industrial zone sustain demand for high-viscosity-index synthetic formulations.
Global Lubricants Market Competitive Environment
Global majors compete with regional champions across base oil supply and formulation technology, creating a tiered structure where vertically integrated energy conglomerates hold feedstock advantages and independent specialists compete on engineering service density. The vendor base separates into three archetypes: integrated majors with captive base oil production, regional champions with distribution depth in industrial corridors, and application-specific specialists competing on technical service rather than commodity volume. Dominant competitive moves include backward integration into gas-to-liquids base oil production and strategic partnerships with automotive OEMs for EV powertrain fluid co-development.
Among the integrated majors, Shell plc exemplifies the captive supply archetype through upstream control over Fischer-Tropsch synthesis routes, while ExxonMobil Corporation anchors the metallocene technology tier. FUCHS Group occupies a position representing the specialist model, competing on formulation engineering density rather than volume scale in industrial machinery applications.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| TotalEnergies SE |
| BP plc |
| Chevron Corporation |
| FUCHS Group |
| PetroChina Company Limited |
| Sinopec Lubricant Company |
| Valvoline Inc |
| Others |
Value Chain & Pricing Dynamics
Extended drain interval specifications from German heavy-duty fleet operators and North American long-haul logistics networks force blenders toward synthetic base stocks, compressing margins on mineral formulations and elevating procurement costs for mid-tier players without captive supply.
Pricing Analysis
Input-cost pass-through from Group I base oil refinery closures in North America and Europe elevates mineral formulation pricing, while synthetic premiums widen due to metallocene catalyst scarcity. Three-tier pricing structure across premium synthetics, standard Group II-plus mineral oils, and economy-grade Group I formulations separates procurement pools by equipment uptime sensitivity. Cost compression in mid-tier mineral blends intensifies because independent blenders lack backward integration into base oil production. Fleet operators and manufacturing plants with continuous production lines exhibit lowest price sensitivity, while emerging market maintenance shops show highest elasticity.
Supply Chain Analysis
Certification to ACEA, API, and OEM proprietary specifications gates blender access to automotive fill contracts, extending qualification timelines and concentrating supply relationships. Base oil production concentrates in the United States, Germany, and China, with Fischer-Tropsch gas-to-liquids facilities anchoring premium synthetic supply. Formulation draws from polyalphaolefin base stocks, detergent-dispersant additive packages, and viscosity modifier polymers. Single-source vulnerability runs through metallocene catalyst technology controlled by vertically integrated majors. Distribution runs through bulk tank trucks for high-volume automotive plants, steel drums for industrial fleet maintenance, and flexitanks for marine port delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement shifting toward synthetic and biodegradable specifications that reward formulation engineering depth over commodity volume scale.
For Market Incumbents: Extend qualification timelines for OEM fill contracts to lock out independent competitors, and deepen captive supply of gas-to-liquids base stocks to defend margin position against feedstock volatility. The closure of Group I refineries threatens mineral formulation economics, while REACH authorization procedures for new additive chemistries demand sustained R&D investment. For New Entrants and Emerging Players: REACH and EU F-Gas Regulation in Europe opens a window for biodegradable marine lubricant specialists to capture port-state compliance mandates ahead of incumbent reformulation cycles. White-space targets include India industrial corridors seeking BIS-certified hydraulic fluids and offshore wind gearbox fluid specifications demanding 10-year service interval synthetics. A technical service partnership model with precision manufacturing clusters bypasses capital barriers to base oil production. For Investors and Strategic Acquirers: Asymmetric upside sits with application-specific formulation specialists possessing OEM co-development relationships and digital fluid monitoring capabilities. The five-to-ten year viability window favors targets with proven synthetic ester synthesis and corrosion-resistant additive portfolios. Watch for inflection in EV thermal management fluid specification consolidation around proprietary OEM standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gas-to-Liquids Base Oil Production | Shell plc's Fischer-Tropsch synthesis routes secure near-zero sulfur feedstock for extended drain interval formulations. |
| EV Powertrain Fluid Co-Development Partnership | Automotive OEMs in Shanghai and Guangzhou demand specialized thermal management fluids for e-axle and battery cooling systems. |
| Biodegradable Marine Lubricant Certification | EU port state mandates under REACH and F-Gas Regulation redirect R&D toward vegetable-derived ester formulations. |
| Digital Fluid Monitoring Service Launch | IoT sensor integration enables predictive maintenance subscriptions, shifting revenue from product volume to uptime guarantees. |
| India Industrial Corridor Formulation Partnership | BIS certification alignment with PLI scheme incentives attracts foreign suppliers to Mumbai-Pune and Chennai manufacturing clusters. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each market through interviews with lubricant plant managers, automotive OEM procurement teams, industrial fleet maintenance directors, and aftermarket distribution channel partners. Secondary validation draws from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up demand modeling triangulates against top-down market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across base oil grade tier, end-use application, packaging format, and regional production hub segmentation. CAGRs derive from equipment fleet expansion rates, drain interval extension trends, and synthetic penetration curves in precision manufacturing clusters. Forecast inputs include automotive production volumes in Shanghai and Guangzhou, offshore wind installation pipelines in the North Sea and Baltic, and regulatory implementation timelines for REACH authorization and China's GB standards.
Revisions become necessary when refinery closure announcements, additive chemistry registration delays, or EV powertrain specification shifts materially alter supply-demand balances. Forecasts reflect assumptions about synthetic base stock capacity expansion, biodegradable performance gap closure, and OEM consolidation around proprietary fluid standards. A model refresh is warranted upon material change in regulatory divergence between EPA, REACH, and SAMR jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Global Grease Cartridges Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Lubricated Tracks Market
Lubricants
Graphite Lubricant Market
Lubricants
Contact Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Global Lubrication Systems Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Turkey Marine Lubricants Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Iraq Lubricants Market