
 ASEAN Lubricants Market | 2026-2036
ASEAN Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Lubricants Market Outlook
API SP and ILSAC GF-6 certification cycles is redrawing competitive access across the ASEAN Lubricants Market, forcing smaller blenders toward costly formulation upgrades or private-label dependence. Shell PLC leverages its integrated supply chain from Singapore refining hubs to secure volume contracts with Indonesian fleet operators. Petronas (Petroliam Nasional Berhad) anchors its position through captive feedstock access at the Pengerang complex, while PT Pertamina Lubricants dominates domestic distribution via state-affiliated fuel retail networks.
Lubricants are formulated mixtures of base oils and additive packages engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from SAE 0W-16 to SAE 60 for automotive applications and ISO VG 32 to 680 for industrial machinery. Their primary commercial purpose centers on extending equipment life and optimizing energy efficiency across powertrain and manufacturing operations. Synthetic formulations command expanding share as OEM drain interval specifications lengthen, while mineral oil retains volume leadership in price-sensitive workshop channels. Engine oils generate the deepest margin pools due to branded specification complexity, whereas hydraulic fluids compete primarily on bulk pricing to industrial procurement teams.
Thailand's Department of Industrial Works enforces lubricant waste handling protocols under hazardous substance controls, while Indonesia's Ministry of Environment and Forestry implements extended producer responsibility frameworks for used oil collection. Malaysia's Department of Standards Malaysia (DSM) aligns SIRIM certification with ASEAN harmonized technical requirements, creating cross-border product registration efficiencies. Stakeholders must monitor evolving national fuel economy regulations, as tighter CO2 targets in Vietnam and the Philippines will cascade into OEM factory-fill specifications that reshape aftermarket demand profiles.
Market Dynamics
Fleet operators across Thailand, Indonesia, and Vietnam are compressing maintenance cycles while extending drain intervals through synthetic reformulation, forcing blenders to recalibrate additive chemistry and base oil sourcing strategies simultaneously.
Growth Catalysts
- Thailand's emissions tightening:The national automotive regulator is accelerating factory-fill specifications toward lower-viscosity grades, pulling aftermarket demand toward API SP-certified products.
- Industrial logistics scaling:Indonesian manufacturing clusters in Bekasi and Karawang are consolidating lubricant procurement through direct volume contracts with integrated suppliers.
- Group III base oil availability:Singapore refining hub expansions are improving regional access to synthetic feedstocks, reducing import dependency for Malaysian and Thai blenders.
Market Restraints
- Additive package cost volatility:PPD and detergent component prices fluctuate with specialty chemical feedstock markets, compressing blender margins on fixed-price fleet contracts.
- Feedstock concentration risk:Group II/III base oil supply concentrates in Singapore and South Korean export terminals, exposing ASEAN formulators to shipping disruption and currency exposure.
- Reformulation lag:Smaller blenders face 18-24 month certification cycles for ILSAC GF-6 and API SP compliance, locking them out of OEM factory-fill opportunities.
Strategic Opportunities
- Vietnam industrial corridor penetration:Northern manufacturing zones around Hai Phong and Bac Ninh remain underserved by premium synthetic distribution, creating first-mover positioning for compliant suppliers.
- Extended producer responsibility frameworks:Indonesia's Ministry of Environment and Forestry is mandating used oil collection infrastructure, opening service-contract revenue streams for integrated lubricant-waste operators.
- E-mobility fluid diversification:Thermal management fluids for battery electric vehicle powertrains represent adjacent formulation expertise applications for existing automotive lubricant R&D teams.
Industry Challenges
- Formulation chemist scarcity:ASEAN universities produce limited graduates with tribology and additive chemistry specializations, forcing blenders to recruit from European and North American talent pools.
- Cross-border certification fragmentation:Divergent national implementation timelines for SIRIM, TISI, and SNI standards create product registration duplication costs for multi-country suppliers.
- Legacy distribution integration:State-affiliated fuel retail networks dominate last-mile access in Indonesia and Vietnam, requiring foreign suppliers to navigate complex joint-venture structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Lubricants Market |
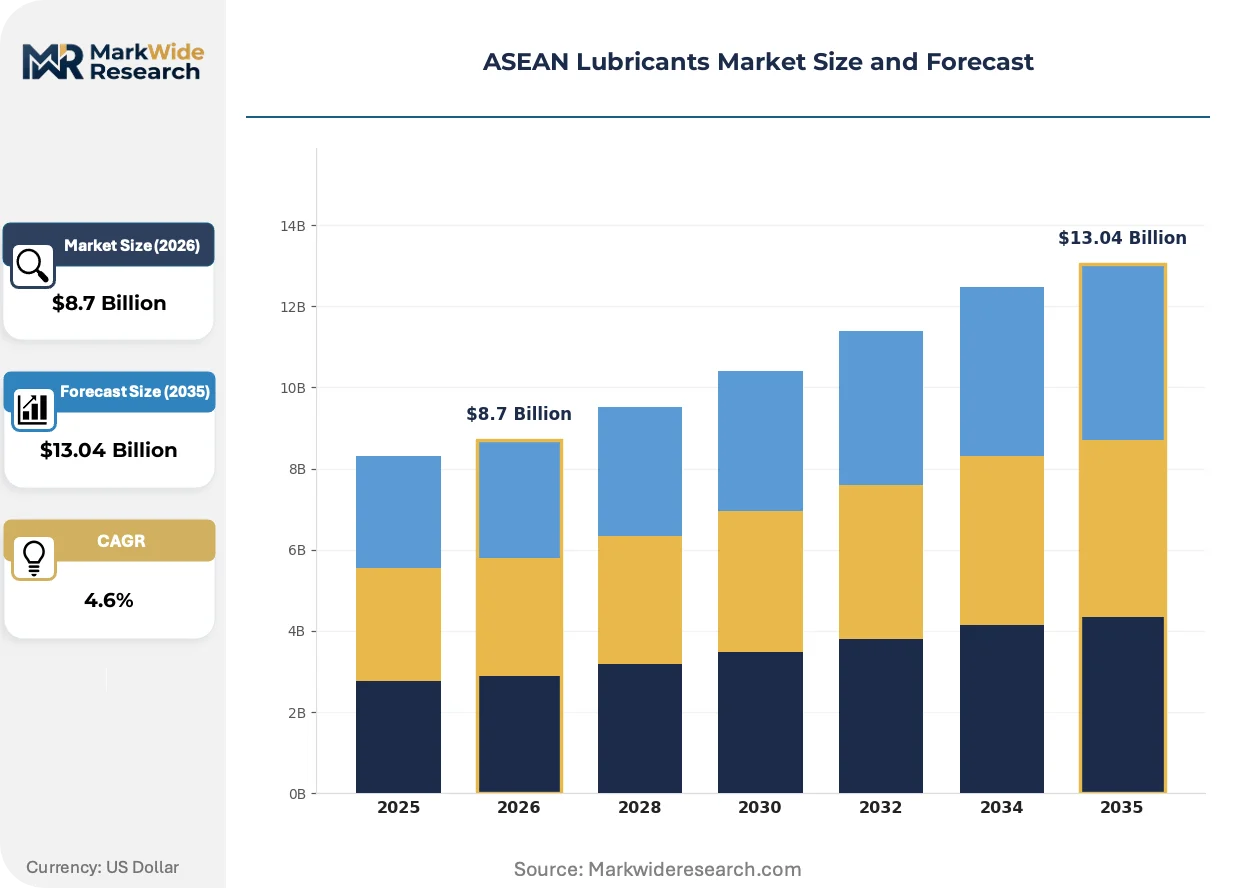
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral Oil, Bio-Lubricants, Semi-Synthetic End User: Automotive Industry, Industrial Machinery, Marine Sector, Aerospace Sector Application: Engine Oils, Gear Oils, Hydraulic Fluids, Metal Working Fluids Distribution Channel: Retail Stores, Online Sales, Distributors, Workshops |
| Companies Covered | Exxon Mobil Corporation, Petronas (Petroliam Nasional Berhad), Shell PLC, PTT Lubricants, Idemitsu Kosan Co., Ltd, Castrol Limited (BP p.l.c.), PT Pertamina Lubricants, TotalEnergies, Caltex (Chevron Corporation), Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Lubricants Market Strategic Shifts
Synthetic base oil technology is compressing traditional mineral oil volume positions while regulatory certification cycles accelerate product obsolescence, reshaping how blenders allocate R&D and how buyers evaluate total cost of ownership.
Polyalphaolefin and Group III+ formulations are displacing Group I mineral oils in heavy-duty diesel applications across Thai and Indonesian fleet operations. Logistics operators running Scania and Volvo powertrains are specifying 15W-40 synthetic blends to achieve 100,000-kilometer drain intervals. This chemistry shift is displacing workshop-grade mineral products from high-mileage commercial segments, redirecting volume toward integrated supply contracts.
Thailand's Department of Industrial Works is enforcing hazardous substance controls on lubricant waste handling, requiring blenders to fund collection infrastructure or partner with licensed waste operators. The regulation compresses operating margins for small independent workshops while favoring suppliers with integrated reverse-logistics capabilities. Malaysian blenders are responding by aligning SIRIM certification with ASEAN harmonized technical requirements to streamline cross-border registration.
Fleet procurement teams are consolidating lubricant sourcing through direct manufacturer contracts, bypassing traditional distributor markups in Indonesian and Vietnamese commercial vehicle segments. Workshop owners lose margin capture on bulk engine oil sales as transport operators negotiate annual volume agreements with Shell, Petronas, and PT Pertamina Lubricants directly. This channel compression is most visible in Jakarta and Surabaya, where logistics consolidation has concentrated buying power among fewer fleet operators.
ASEAN Lubricants Market Segmentation
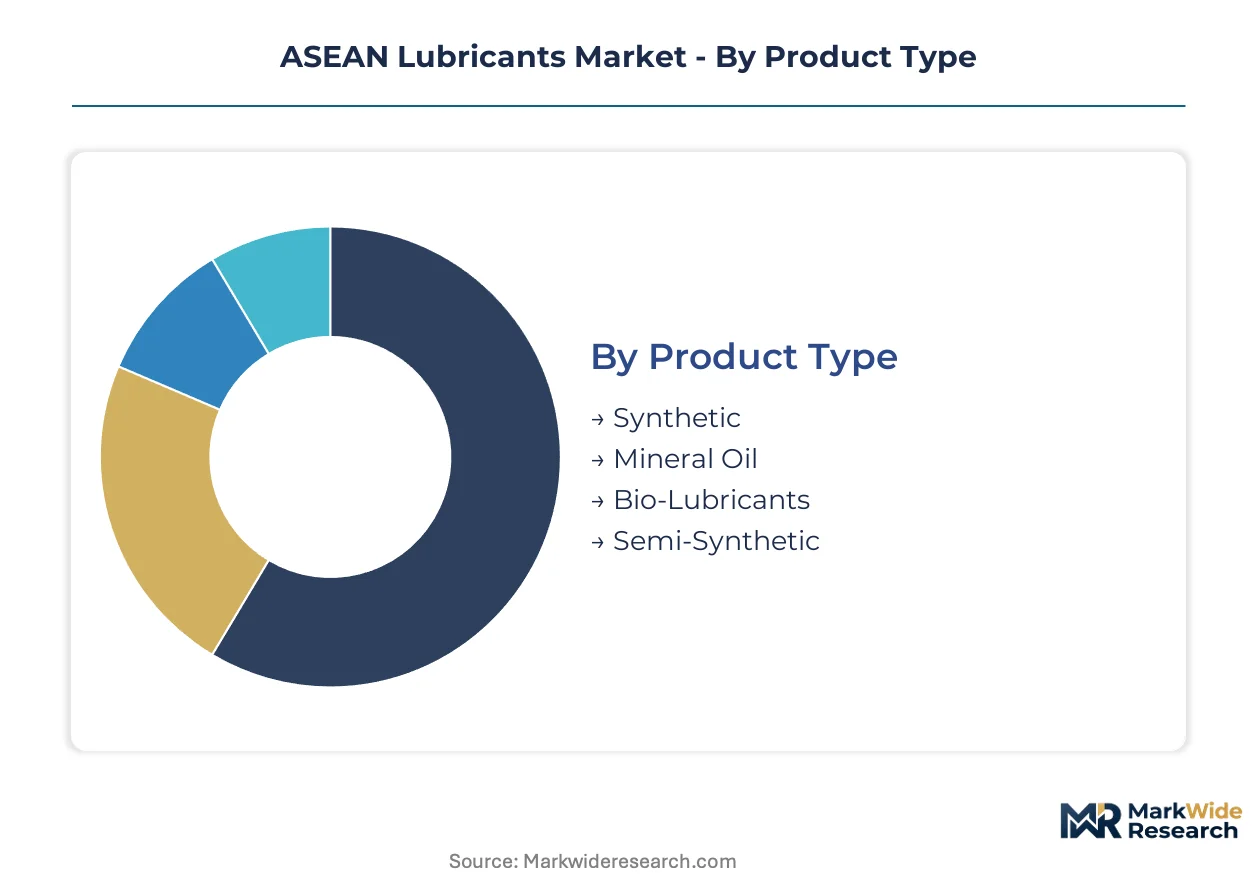
Lubricant segmentation in ASEAN reflects divergent channel economics and specification complexity. Synthetic formulations flow through direct fleet contracts, while mineral oils dominate workshop retail. Understanding these pathway distinctions clarifies where margin pools concentrate versus where volume accumulates.
Product Type:
Synthetic formulations command premium pricing through integrated supply chains, while mineral oils move through fragmented workshop networks. Bio-lubricants and semi-synthetics occupy intermediate positions with distinct certification requirements.
- Synthetic:Group III and PAO base stocks formulated for extended drain intervals. Thai and Indonesian fleet operators specify these for Scania and Volvo powertrains to achieve 100,000-kilometer service cycles under tightening emissions protocols.
- Mineral Oil:Group I and II base stocks refined from crude petroleum fractions. Price-sensitive independent workshops across Vietnam and the Philippines rely on these for passenger vehicle servicing where OEM warranty compliance is less critical.
- Bio-Lubricants:Estolide and vegetable oil derivatives targeting biodegradable applications in sensitive ecosystems. Malaysian palm oil feedstock integration supports regional production for agricultural and marine use.
- Semi-Synthetic:Blended formulations combining mineral and synthetic base stocks. Indonesian commercial vehicle segments adopt these as compromise solutions between performance requirements and procurement budgets.
Mineral oil dominates installed base. Synthetic is where expansion concentrates.
End User:
End-use segmentation tracks equipment complexity and procurement centralization. Automotive and industrial machinery represent scale opportunities, while marine and aerospace command specification premiums.
- Automotive Industry:Factory-fill and aftermarket demand from passenger and commercial vehicle operations. Thailand's Board of Investment incentives for EV manufacturing are reshaping fluid specifications toward thermal management chemistries.
- Industrial Machinery:Manufacturing equipment lubrication across Indonesian Bekasi-Karawang industrial corridors. Procurement teams negotiate direct volume contracts with integrated suppliers, bypassing traditional distributor markups.
- Marine Sector:Two-stroke and four-stroke engine oils for shipping and fishing fleets. Singapore's port authority regulations on bunker fuel quality cascade into lubricant selection criteria for vessels calling at regional terminals.
- Aerospace Sector:Aviation turbine oils and hydraulic fluids meeting SAE AS5780 and MIL-PRF-23699 specifications. Limited regional MRO capacity concentrates demand at Singapore Changi and Kuala Lumpur maintenance hubs.
Automotive absorbs the deepest volume. Industrial machinery is climbing the fastest.
Application:
Application segmentation separates formulation complexity from bulk commodity positioning. Engine oils carry specification premiums, while hydraulic fluids compete on price-per-liter.
- Engine Oils:Crankcase lubricants spanning SAE 0W-16 to 60 viscosity grades. API SP and ILSAC GF-6 certification requirements are forcing reformulation investments among Thai blenders.
- Hydraulic Fluids:Power transmission media for construction and manufacturing equipment. Indonesian infrastructure projects drive ISO VG 46 and 68 demand through equipment import channels.
- Gear Oils:Axle and transmission lubricants for commercial vehicle drivetrains. Extended drain interval specifications are pulling demand toward synthetic GL-5 formulations.
- Metal Working Fluids:Coolants and lubricants for machining operations. Vietnamese manufacturing zones around Hai Phong show rising demand as precision engineering clusters expand.
Engine oils capture the widest margin spread. Hydraulic fluids represent the steepest volume trajectory.
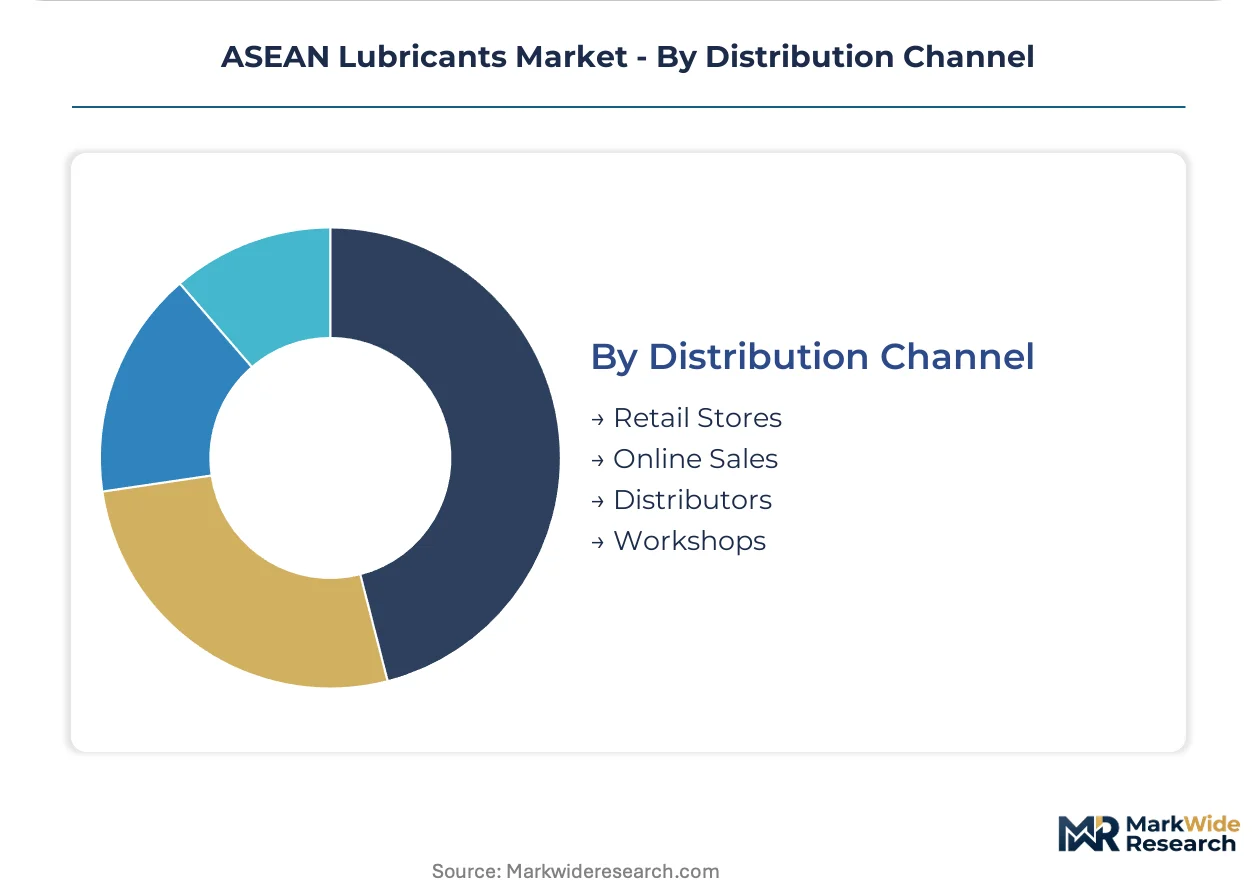
Distribution Channel:
Channel segmentation reveals control points in last-mile access. State-affiliated networks dominate in Indonesia, while independent workshops retain influence in Thailand.
- Distributors:Regional warehousing and logistics operators managing multi-brand portfolios. Malaysian blenders leverage these for cross-border penetration into secondary Vietnamese cities.
- Workshops:Independent service bays and quick-lube operations. Thai Department of Industrial Works waste handling regulations are compressing margins for non-compliant operators.
- Retail Stores:Consumer-facing outlets including hypermarkets and auto parts specialists. Do-it-yourself maintenance culture remains limited across ASEAN compared to developed markets.
- Online Sales:E-commerce platforms and direct-to-consumer fulfillment. Logistics complexity for hazardous materials restricts this channel to packaged consumer formats.
Workshops anchor current volume. Distributors are where structural consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Board of Investment incentives for EV manufacturing are accelerating factory-fill specification shifts across ASEAN. Indonesia's domestic manufacturing expansion and Vietnam's northern industrial corridor development concentrate procurement volume growth. Malaysia's SIRIM certification alignment with ASEAN harmonized standards reduces cross-border registration friction.
Indonesia
Domestic manufacturing clusters in Bekasi and Karawang are consolidating lubricant procurement through direct volume contracts with integrated suppliers. The Ministry of Environment and Forestry mandates extended producer responsibility frameworks for used oil collection infrastructure. Jakarta and Surabaya logistics operators negotiate annual agreements with state-affiliated fuel retail networks, compressing traditional distributor channels.
Thailand
The Department of Industrial Works enforces hazardous substance controls on lubricant waste handling protocols. National automotive regulator emissions tightening pulls aftermarket demand toward API SP-certified lower-viscosity products. Eastern Economic Corridor manufacturing zones specify extended drain interval formulations for heavy-duty commercial fleets.
Vietnam
Northern manufacturing zones around Hai Phong and Bac Ninh remain underserved by premium synthetic distribution networks. Tightening CO2 targets cascade into OEM factory-fill specifications that reshape aftermarket demand profiles. Construction equipment imports through Ho Chi Minh City drive ISO VG 46 and 68 hydraulic fluid procurement.
Singapore
Refining hub expansions improve regional access to Group III synthetic feedstocks for Malaysian and Thai blenders. Port authority regulations on bunker fuel quality cascade into lubricant selection criteria for vessels calling at regional terminals. Integrated supply chain infrastructure secures volume contracts with Indonesian fleet operators.
Malaysia
Department of Standards Malaysia aligns SIRIM certification with ASEAN harmonized technical requirements. Pengerang complex captive feedstock access anchors Petronas positioning. Palm oil feedstock integration supports regional bio-lubricant production for agricultural and marine biodegradable applications.
ASEAN Lubricants Market Competitive Environment
Player mix skews toward integrated petroleum majors with captive refining and national oil companies with state-affiliated distribution networks. Market structure concentrates volume leadership among five entities controlling Singapore supply chain access and Indonesian retail infrastructure. Two strategic archetypes dominate: integrated majors leveraging hub-and-spoke refining economics, and national champions securing volume through fuel retail network integration. Competitive moves center on additive package certification acceleration and reverse-logistics infrastructure buildout for used oil collection compliance.
Within the integrated petroleum major tier, Shell PLC and Exxon Mobil Corporation exemplify supply chain control through Singapore refining hub positioning. Petronas (Petroliam Nasional Berhad) anchors the national champion archetype through captive feedstock access at Malaysian complexes. PT Pertamina Lubricants occupies the state-affiliated distribution position, dominating Indonesian last-mile access via fuel retail network integration. These three entities represent distinct competitive vectors: hub economics, upstream integration, and channel control.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Petronas (Petroliam Nasional Berhad) |
| Shell PLC |
| PTT Lubricants |
| Idemitsu Kosan Co., Ltd |
| Castrol Limited (BP p.l.c.) |
| PT Pertamina Lubricants |
| TotalEnergies |
| Caltex (Chevron Corporation) |
| Others |
Value Chain & Pricing Dynamics
API SP and ILSAC GF-6 certification cycles gate both supply qualification and price differentiation across the ASEAN Lubricants Market, forcing blenders to absorb reformulation costs while fleet operators capture extended drain interval savings. This regulatory threshold simultaneously filters out smaller formulators and creates tiered pricing spreads between certified synthetic formulations and workshop-grade mineral products.
Pricing Analysis
Certification level creates the primary spread between premium synthetic formulations and standard mineral products. Three-tier pricing structure across premium, standard, and economy levels reflects API SP compliance status, base oil Group classification, and volume contract scale. Cost compression in the economy tier is intensifying because Indonesian fleet procurement teams are consolidating annual agreements with integrated suppliers, squeezing independent workshop margins. Price-sensitive independent operators across Vietnam and the Philippines represent the most elastic demand segment, while Thai commercial fleet managers prioritize total cost of ownership over per-liter pricing.
Supply Chain Analysis
Singapore port congestion and container availability on the Middle East-Southeast Asia trade lane elevate inbound logistics costs for Malaysian and Thai blenders sourcing additive packages. Group II and Group III base oil supply concentrates in Singapore and South Korean export terminals, drawing from specialty chemical feedstocks and hydrocracked refinery streams. Single-source vulnerability around Singapore refining hub capacity exposes ASEAN formulators to shipping disruption and currency exposure. Distribution runs through state-affiliated fuel retail networks in Indonesia and Vietnam, while independent distributors manage cross-border penetration into secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery electric vehicle thermal management fluids represent a substitution threat that incumbent lubricant blenders must navigate through formulation diversification. Incumbents face pressure to defend synthetic engine oil positions while building adjacent capabilities in e-mobility fluid chemistries.
For Market Incumbents: Secure captive feedstock access through Singapore refining hub partnerships or Pengerang-complex-style integrated positions. Accelerate additive package certification timelines to lock in OEM factory-fill contracts before smaller blenders complete ILSAC GF-6 compliance cycles. Defend against e-mobility substitution by redirecting automotive R&D teams toward battery thermal management fluid formulations.
For New Entrants and Emerging Players: Differentiate on reverse-logistics integration by building used oil collection infrastructure aligned with Indonesia's extended producer responsibility mandates. Target Vietnam's northern industrial corridor around Hai Phong and Bac Ninh, where premium synthetic distribution remains underserved by incumbent networks. Penetrate through direct volume contracts with logistics operators running Scania and Volvo powertrains, bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Thailand's Department of Industrial Works emissions tightening reshapes the acquisition landscape by devaluing non-compliant independent blenders and premiuming integrated operators with certification acceleration capabilities. Long-term viability hinges on exposure to synthetic formulation R&D capabilities and state-affiliated distribution network access. Watch for Indonesia's Ministry of Environment and Forestry enforcement intensity on used oil collection mandates as the signal for regulatory-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Captive feedstock from Singapore refining expansions secures margin control against import volatility. |
| API SP Certification Acceleration | Early compliance locks OEM factory-fill contracts ahead of 18-24 month competitor lag cycles. |
| Used Oil Collection Infrastructure Buildout | Indonesia's extended producer responsibility frameworks create service-contract revenue streams. |
| E-Mobility Thermal Fluid Diversification | Battery electric vehicle powertrain chemistries repurpose existing automotive lubricant R&D expertise. |
| Direct Fleet Contract Consolidation | Bypassing distributor markups in Jakarta and Surabaya captures margin from logistics operator procurement centralization. |
Study Parameters
Cross-validation between primary interviews with lubricant blenders and fleet procurement managers anchors the qualitative findings against secondary trade data and national regulatory filings. The research incorporated discussions with plant managers at Indonesian Bekasi-Karawang manufacturing clusters, technical R&D directors at integrated petroleum majors, distribution channel partners managing cross-border logistics, and aftermarket service heads at commercial vehicle workshops. Secondary sources included customs and trade data tracking base oil and additive package flows, ASEAN harmonized technical requirement documentation, SEC filings from listed petroleum majors, and national environmental regulator enforcement records. Bottom-up volume modeling triangulated against top-down market sizing from refining capacity and vehicle fleet data.
Sensitivity analysis around feedstock price volatility and certification timeline acceleration tested forecast robustness across the projection horizon. The analytical framework segmented by product type, end user, application, and distribution channel, with additional modeling of regulatory compliance tier as a cross-cutting dimension. CAGRs were derived from trend extrapolation of synthetic penetration rates and fleet procurement consolidation patterns, incorporating input variables including Singapore refining hub capacity expansion schedules and OEM drain interval specification changes.
Material uncertainties — feedstock supply disruption, regulatory enforcement intensity variation, and e-mobility penetration acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification cycle completion rates and fleet operator procurement centralization trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Europe Grease Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Hydropower Lubricants Market